
 Healthcare CMO Market | 2026-2036
Healthcare CMO Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare CMO Market Outlook
Buyer concentration among large pharmaceutical sponsors is pivoting toward a broader base of emerging biotechnology firms and virtual drug developers seeking flexible manufacturing partnerships. Lonza Group AG leverages its integrated biologics network across Switzerland and Singapore to capture complex protein production. Samsung Biologics Co., Ltd. anchors massive mammalian cell culture capacity in South Korea. Catalent Inc. competes through differentiated oral and injectable formulation technologies.
A healthcare contract manufacturing organization provides outsourced pharmaceutical production services encompassing active ingredient synthesis, drug product formulation, fill-finish operations, and analytical testing under validated quality systems. These entities operate multi-product facilities with isolator-based aseptic processing lines, single-use bioreactor trains, and automated packaging suites to supply commercial and clinical-stage therapies. Biologics services command premium margins due to cell-line development complexity and cold-chain infrastructure requirements, while small molecule segments remain volume-driven with established chemistry platforms. Formulations and analytical services represent faster-expanding pockets as sponsors outsource later-stage characterization and stability programs.
FDA enforces current Good Manufacturing Practice through facility inspections and process validation guidance, while EMA coordinates centralized marketing authorization assessments that determine CMO eligibility for European supply. ICH Q7 and Q10 guidelines harmonize quality risk management expectations across US, European, and Japanese regulatory jurisdictions. Stakeholders must monitor evolving cell and gene therapy manufacturing standards that lack mature CMO inspection precedents.
Market Dynamics
FDA's quality-by-design mandates and EMA's GMP Annex 1 revisions are forcing facility reinvestment across the contract manufacturing base, while mid-sized biotechnology sponsors accelerate outsourcing of complex biologics production.
Growth Catalysts
- Biologics capacity expansion:Mid-sized biotechnology firms are accelerating adoption of outsourced mammalian cell culture manufacturing for monoclonal antibodies and recombinant proteins.
- EMA GMP Annex 1 revisions:Updated aseptic processing requirements are driving replacement of open isolator systems with closed barrier technologies in European fill-finish operations.
- Switzerland-Ireland-South Korea clusters:Specialized biologics manufacturing hubs in these jurisdictions attract sponsor investment through integrated cold-chain infrastructure and regulatory alignment.
Market Restraints
- Platinum-group metal catalyst costs:Small molecule API synthesis faces input price volatility for hydrogenation and cross-coupling catalysts essential to high-potency compound manufacturing.
- Single-use consumables concentration:Supply of bioprocessing bags and tubing assemblies concentrates among a limited supplier base, creating vulnerability to resin and polymer feedstock disruptions.
- Cell-line development timelines:Complex protein expression system optimization extends early-phase program initiation by 12-18 months versus established platform technologies.
Strategic Opportunities
- Cell and gene therapy manufacturing:Viral vector production and CAR-T cell processing lack mature CMO inspection precedents, creating first-mover advantage for facilities achieving regulatory clarity.
- Continuous manufacturing adoption:FDA's quality-by-design framework incentivizes transition from batch to continuous processing for oral solid dosage forms, reducing facility footprint requirements.
- Analytical services outsourcing:Later-stage characterization, stability programs, and comparability studies represent faster-expanding service pockets as sponsors divest in-house capabilities.
Industry Challenges
- Aseptic processing technician scarcity:Isolator-based fill-finish operations require specialized operator certification that outpaces vocational training program output in key manufacturing regions.
- Multi-product facility validation:Campaign changeover procedures for biologics manufacturing demand extensive cleaning validation and cross-contamination risk assessment, compressing facility utilization rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare CMO Market |
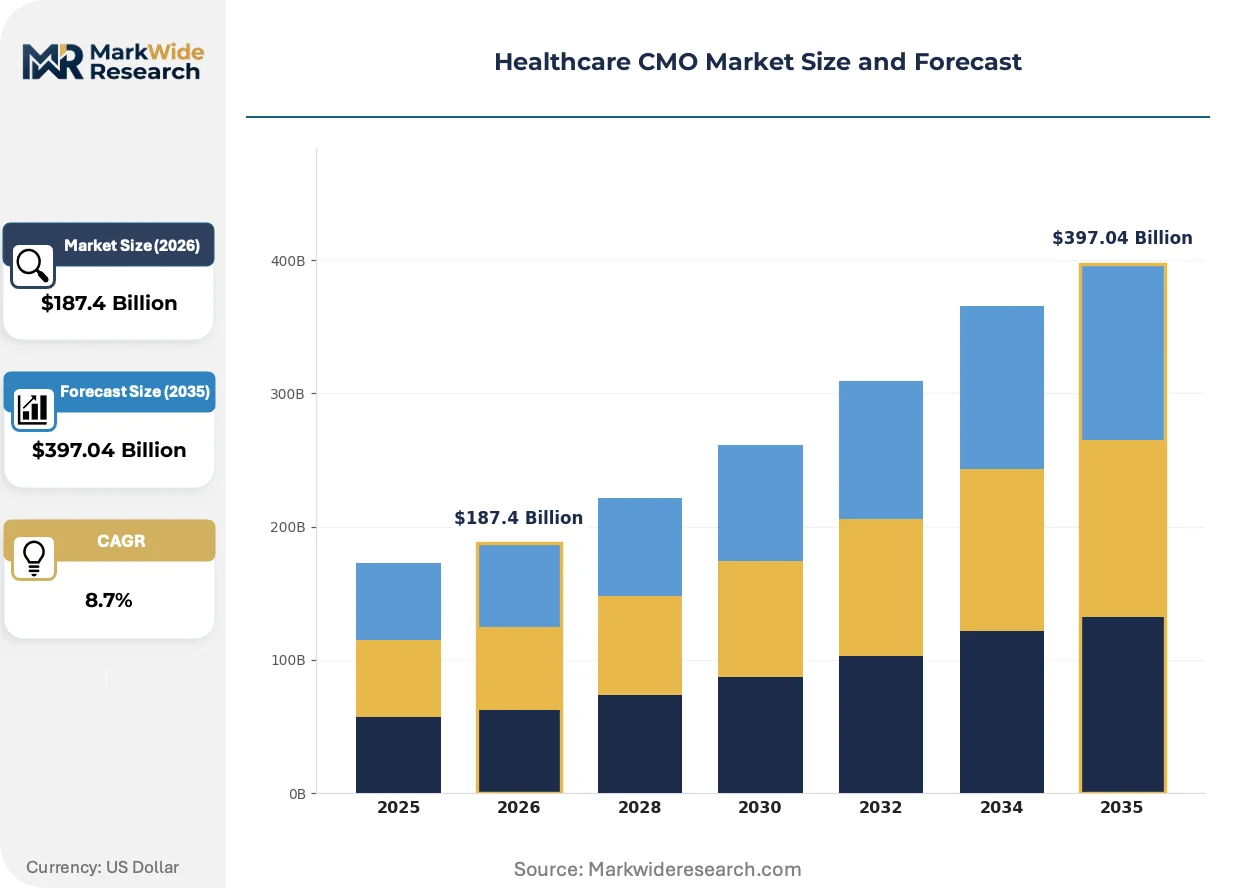
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $397.04 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Biologics, Small Molecules, Formulations, Analytical Services End User: Pharmaceutical Companies, Biotechnology Firms, Medical Device Manufacturers, Academic Institutions Delivery Mode: Injection, Infusion, Oral, Transdermal Regulatory Compliance: GMP, GLP, ICH, FDA |
| Companies Covered | Samsung Biologics Co., Ltd., AGC Biologics Inc., Lonza Group AG, Fareva Holding SAS, Boehringer Ingelheim International GmbH, Thermo Fisher Scientific Inc., Recipharm AB, WuXi AppTec Co., Ltd., Catalent Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare CMO Market Strategic Shifts
Single-use bioprocessing technologies are converging with automated control systems to reshape facility economics, while regulatory harmonization efforts and sponsor outsourcing preferences accelerate structural change across the contract manufacturing landscape.
Continuous bioprocessing technology is converging with perfusion cell culture platforms to enable higher cell density maintenance over extended production runs. Emerging biotechnology sponsors are adopting these integrated systems for clinical-phase material supply, reducing stainless steel infrastructure requirements. This convergence is compressing capital intensity thresholds for entry into complex biologics manufacturing.
EMA's revised GMP Annex 1 guidance on sterile medicinal products mandates barrier isolation technology and environmental monitoring enhancements for aseptic operations. Contract manufacturers serving European markets must retrofit open cleanroom suites with restricted access barrier systems or isolators. Fill-finish service providers in Ireland and Switzerland are prioritizing these capital programs to maintain marketing authorization eligibility.
Sponsor quality agreements now specify real-time release testing and extended characterization data packages prior to lot disposition. Virtual drug developers and emerging biotechnology firms are displacing traditional milestone-based contracts with integrated partnership models that embed CMO personnel within sponsor quality units. This pattern is most visible among South Korea-based sponsors sourcing mammalian cell culture capacity for biosimilar development programs.
Healthcare CMO Market Segmentation
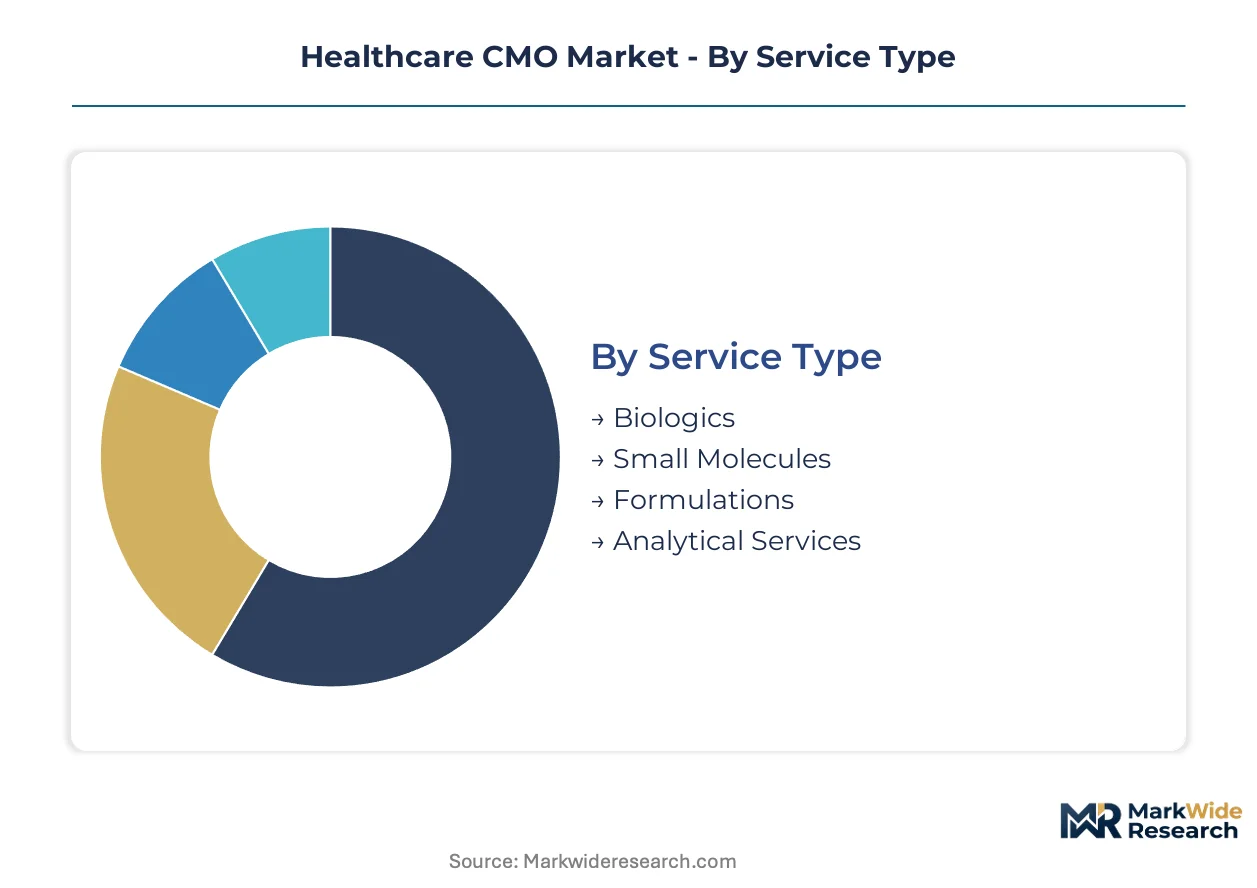
Healthcare CMO segmentation reveals divergent margin profiles and capital intensity requirements across service types, while end-user composition shifts toward emerging biotechnology sponsors seeking flexible manufacturing partnerships. Understanding these dimensional splits enables targeted capacity investment and partnership structuring.
Service Type:
Buyer procurement decisions pivot on therapeutic modality complexity and regulatory pathway maturity, with biologics commanding premium pricing for cell-line development expertise.
- Biologics:Mammalian cell culture and microbial fermentation platforms produce monoclonal antibodies, recombinant proteins, and vaccines under cold-chain infrastructure. Demand concentrates among mid-sized biotechnology firms in Switzerland and South Korea outsourcing complex protein production due to FDA quality-by-design mandates.
- Small Molecules:Chemical synthesis and high-potency API manufacturing leverage catalytic hydrogenation and cross-coupling chemistry. Volume remains concentrated with established pharmaceutical sponsors in Ireland seeking cost-optimized oral solid dosage capacity.
- Formulations:Drug product development spans immediate-release tablets, controlled-release matrices, and sterile injectable preparations.
- Analytical Services:Characterization, stability testing, and comparability studies support regulatory submissions.
Volume sits with Small Molecules; growth tilts toward Analytical Services.
End User:
Customer type determines contract structure flexibility and quality agreement intensity, with virtual developers requiring embedded CMO personnel.
- Pharmaceutical Companies:Large sponsors leverage multi-year capacity reservations and dedicated manufacturing suites for commercial supply security. Procurement patterns favor Switzerland-based facilities with integrated regulatory compliance infrastructure.
- Biotechnology Firms:Emerging and mid-sized developers outsource entire manufacturing workflows under milestone-based partnerships. Sponsors in South Korea increasingly embed CMO quality personnel within sponsor organizations for biosimilar programs.
- Medical Device Manufacturers:Combination product developers require sterile fill-finish capabilities for drug-device integration.
- Academic Institutions:Research-scale production supports investigator-initiated trials and early-phase material supply.
Revenue concentration favors Pharmaceutical Companies; Biotechnology Firms are expanding most quickly.
Delivery Mode:
Route of administration dictates facility infrastructure requirements, with parenteral formats driving aseptic processing investments.
- Injection:Prefilled syringes and vial presentations demand isolator-based aseptic processing under EMA GMP Annex 1 barrier requirements. EMA's revised sterile product guidance is forcing retrofit investments in Ireland and Switzerland fill-finish networks.
- Infusion:Large-volume parenteral bags and pump-compatible presentations require specialized blow-fill-seal technology.
- Oral:Tablets, capsules, and multiparticulate systems leverage established continuous manufacturing platforms.
- Transdermal:Patches and topical formulations require adhesive matrix expertise and specialized stability programs.
Utilization rates peak for Injection; capacity expansion focuses on Infusion.
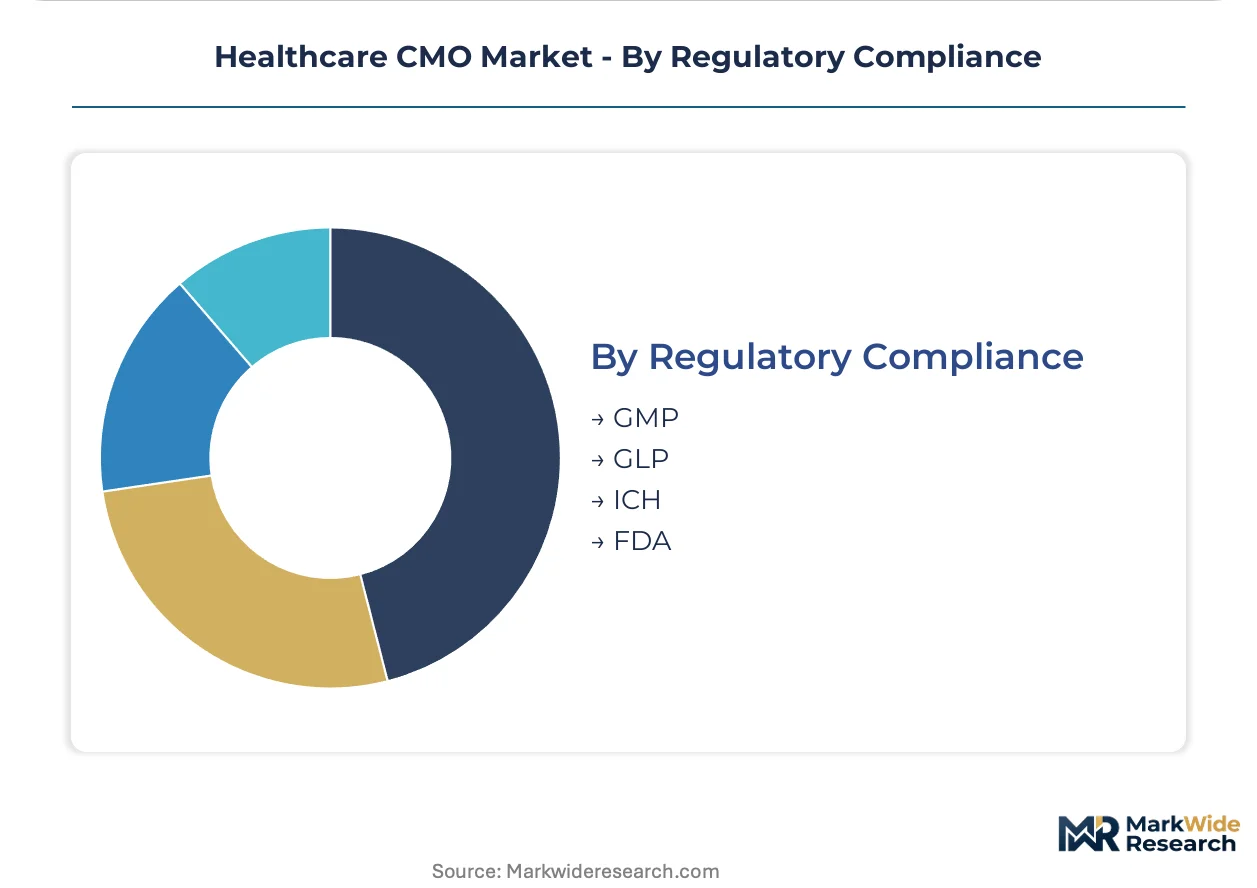
Regulatory Compliance:
Certification tier determines geographic market access eligibility and inspection frequency exposure.
- GMP:Current Good Manufacturing Practice compliance enables commercial supply across FDA and EMA jurisdictions. Facilities in South Korea and Ireland prioritize simultaneous FDA-EMA inspection readiness for multi-territory supply.
- GLP:Good Laboratory Practice governs analytical method validation and stability study execution.
- ICH:Q7 and Q10 guideline harmonization streamlines quality risk management across US, European, and Japanese regulatory submissions.
- FDA:Facility registration and drug master file maintenance support US market authorization.
Baseline requirements center on GMP; differentiation is climbing fastest through ICH alignment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platinum-group metal catalysts sourced from South African mining operations underpin small molecule API synthesis economics across European and Asian manufacturing networks. Cold-chain infrastructure investments cluster where biologics capacity expansion meets regulatory harmonization.
Switzerland
Basel and Zurich host dense networks of monoclonal antibody manufacturing facilities serving biosimilar developers. Swissmedic enforces stringent GMP standards that align with FDA quality-by-design frameworks. Lonza Group AG anchors integrated biologics production across Visp and Basel, capturing complex protein programs from mid-sized biotechnology sponsors.
South Korea
Songdo and Incheon concentrate mammalian cell culture capacity for global biosimilar supply. MFDS inspection protocols increasingly synchronize with FDA facility assessment schedules. Samsung Biologics Co., Ltd. operates massive single-use bioreactor trains, embedding quality personnel directly within sponsor organizations for integrated partnership models.
Ireland
Dublin and Cork harbor fill-finish operations targeting European and North American parenteral drug markets. EMA GMP Annex 1 revisions mandate barrier isolation retrofits across legacy cleanroom suites. Catalent Inc. and Recipharm AB facilities prioritize closed aseptic processing technology upgrades to maintain marketing authorization eligibility.
United States
Boston-Cambridge and San Diego biotechnology clusters outsource clinical-phase manufacturing to specialized CMO networks. FDA process validation guidance and quality-by-design mandates reshape facility investment priorities. Thermo Fisher Scientific Inc. maintains multi-product facilities across Massachusetts and California with integrated analytical services for real-time release testing.
Germany
Bavaria and North Rhine-Westphalia concentrate high-potency API synthesis and sterile injectable formulation capacity. EMA centralized marketing authorization assessments determine CMO eligibility for European supply. Boehringer Ingelheim International GmbH leverages integrated chemical and biologics platforms across Ingelheim and Biberach for contract manufacturing partnerships.
Healthcare CMO Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue cell and gene therapy manufacturing where regulatory precedents remain unsettled. The vendor base stratifies across three tiers: integrated biologics networks, specialized formulation technologists, and regional API synthesis specialists. Two dominant competitive moves define current positioning: multi-year capacity reservations locking sponsor relationships, and isolator-based aseptic processing retrofits securing EMA compliance.
Within the integrated biologics tier, Lonza Group AG and Samsung Biologics Co., Ltd. represent contrasting geographic anchoring strategies—Swiss precision manufacturing against Korean scale economics. Catalent Inc. occupies a differentiated position through oral and injectable formulation specialization. Thermo Fisher Scientific Inc. exemplifies the diversified life sciences conglomerate model, while WuXi AppTec Co., Ltd. anchors Chinese-origin capacity expansion for global sponsor access.
| Leading Market Players |
|---|
| Samsung Biologics Co., Ltd. |
| AGC Biologics Inc. |
| Lonza Group AG |
| Fareva Holding SAS |
| Boehringer Ingelheim International GmbH |
| Thermo Fisher Scientific Inc. |
| Recipharm AB |
| WuXi AppTec Co., Ltd. |
| Catalent Inc. |
| Others |
Value Chain & Pricing Dynamics
Platinum-group metal spot indices cascade through small molecule API synthesis economics, compressing margins on catalytic hydrogenation steps while biologics manufacturers absorb single-use consumables premiums through tiered service bundling. Contract manufacturers pass resin and polymer feedstock volatility into customer pricing through material surcharge mechanisms tied to quarterly commodity resets.
Pricing Analysis
Warranty-backed regulatory compliance packages anchor premium pricing tiers, with FDA drug master file maintenance and EMA inspection readiness bundled into multi-year partnership rates versus transactional per-batch arrangements. Three-tier pricing structure across premium, standard, and economy levels separates dedicated suite reservations from multi-product campaign slots and spot-fill capacity. Cost compression in small molecule segments is intensifying because platinum catalyst input volatility outpaces formulation efficiency gains. Virtual drug developers and emerging biotechnology sponsors exhibit highest price sensitivity, while large pharmaceutical companies prioritize supply security over unit cost optimization.
Supply Chain Analysis
Single-use bioprocessing assembly supply rests on German and US specialty polymer converters, with bioreactor bag films and aseptic tubing drawing from a concentrated resin formulation base. Stainless steel equipment fabrication sources from Swiss and German precision engineering clusters, while platinum-group metal catalysts for API synthesis hinge on South African mining output. Tariff exposure on Chinese-origin stainless steel components creates margin vulnerability for facility expansion programs. Distribution runs through sponsor-integrated logistics networks with cold-chain custody validation from manufacturing suite to clinical site.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aseptic processing technician scarcity props pricing power across fill-finish networks, with isolator certification bottlenecks limiting capacity expansion regardless of capital availability. Qualified operator supply constraints sustain premium rates for barrier technology manufacturing.
For Market Incumbents: Acquire closed isolator system manufacturers to secure equipment lead times and lock out competitor retrofit programs. Catalent and Lonza should prioritize backward integration into single-use assembly production to neutralize resin supply concentration risk. Samsung Biologics must defend mammalian cell culture margin position against emerging Chinese capacity by embedding quality personnel deeper into sponsor organizations.
For New Entrants and Emerging Players: FDA's quality-by-design framework in the United States opens a window for continuous manufacturing specialists to capture oral solid dosage share from batch-oriented incumbents. Cell and gene therapy viral vector production in Switzerland presents the most penetrable white-space target, lacking mature CMO inspection precedents. A go-to-market angle emphasizing real-time release testing capabilities distinguishes entrants from legacy validation-dependent competitors.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-sized European fill-finish specialists in Ireland and Germany facing EMA Annex 1 retrofit capital demands. Long-term viability over a multi-year horizon centers on facilities with simultaneous FDA-EMA inspection readiness and isolator-based aseptic processing already deployed. The signal to watch is sponsor quality agreement migration toward integrated partnership models with embedded personnel.
| Strategic Initiative | Industry Significance |
|---|---|
| Isolator Retrofit Program | EMA GMP Annex 1 compliance secures European marketing authorization eligibility for fill-finish networks. |
| Single-Use Capacity Expansion | Samsung Biologics leverages single-use bioreactor trains to compress capital intensity for biosimilar sponsors. |
| Continuous Manufacturing Transition | FDA quality-by-design incentives reward oral solid dosage facilities adopting continuous processing platforms. |
| Cell and Gene Therapy Qualification | Viral vector production capabilities capture first-mover advantage where CMO inspection precedents remain unsettled. |
| Analytical Services Integration | Thermo Fisher embeds real-time release testing to displace sponsor in-house characterization capabilities. |
Study Parameters
Multi-period observation of FDA warning letter trends and EMA inspection deficiency rates anchored the trend analysis, supplemented by interviews with contract manufacturing executives, regulatory affairs directors at biotechnology sponsors, aseptic processing technicians, and GMP compliance consultants. Secondary validation drew from FDA Form 483 observations, EMA GMP inspection reports, ICH guideline revision drafts, and facility expansion announcements. Bottom-up capacity utilization modeling triangulated against top-down sponsor outsourcing spend estimates.
Segment-weighting across service type, end user archetype, delivery mode, and regulatory compliance tier structured the analytical framework. Growth projections over the projection horizon incorporated biologics capacity expansion trajectories, continuous manufacturing adoption curves, and cell therapy manufacturing maturation timelines. CAGRs were derived from sponsor pipeline analysis and facility investment announcement tracking.
The model assumes a particular technology adoption path; alternative pathways for continuous bioprocessing would alter the outlook if perfusion platform reliability fails to meet commercial-scale expectations. Forecasts reflect assumptions about regulatory harmonization progress and sponsor outsourcing preference stability. A small set of named triggers warrants ongoing watch: EMA GMP Annex 1 enforcement intensity, platinum-group metal price volatility, and single-use consumables supply disruption events.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
US Care Services Market
Healthcare Services
US Registered Nurses Market
Healthcare Services
Funeral Products and Services Market
Healthcare Services
Professional Spa Services Market
Healthcare Services
Life Science Trade Lane Design and Qualification Services Market
Healthcare Services
Medically Supervised Weight Loss Services Market
Healthcare Services
Global Infusion Pharmacy Management Market
Healthcare Services
Vaccine Transport Carrier Market
Healthcare Services
In-Home Senior Care Franchises Market
Healthcare Services
Contract Research Organization (CRO) Services Market
Healthcare Services
Medical Devices and Equipment Logistics Market
Healthcare Services
Eastern Europe Online Pharmacy Market
Healthcare Services
Escort Bed Sharing Market
Healthcare Services
Nutraceutical Contract Manufacturing Services Market
Healthcare Services
Immunoassay CDMO Market
Healthcare Services
Spa Services Market