
 Aged Care Market | 2026-2036
Aged Care Market Size, Share, and Industry Trends Forecast 2026-2036
Aged Care Market Intelligence
A growing consolidation of service procurement by large insurance networks and government payers is realigning provider business models. Extendicare Inc. specializes in a full continuum of care, from home support to long-term facilities. Chartwell Retirement Residences leverages its significant portfolio scale within Canada for operational efficiency. Atria Senior Living differentiates through high-end amenities and personalized service programs in its communities.
Aged care encompasses a range of services designed to support the health and daily living needs of older adults. Providers utilize standardized assessment tools to create individualized care plans addressing specific functional or cognitive limitations. The Home Care service type is expanding rapidly, often outpacing growth in traditional Residential Care. Within care settings, Assisted Living Facilities attract residents with less severe needs, capturing share from more intensive nursing homes.
Regulatory frameworks set minimum standards for quality and safety, such as staff-to-resident ratios in Germany and care plan requirements in the United States. Data management is governed by privacy laws like Europe's GDPR, impacting the adoption of digital health records. Service providers now face a strategic choice between scaling through technology-driven efficiency or focusing on high-touch, premium care models.
Market Dynamics
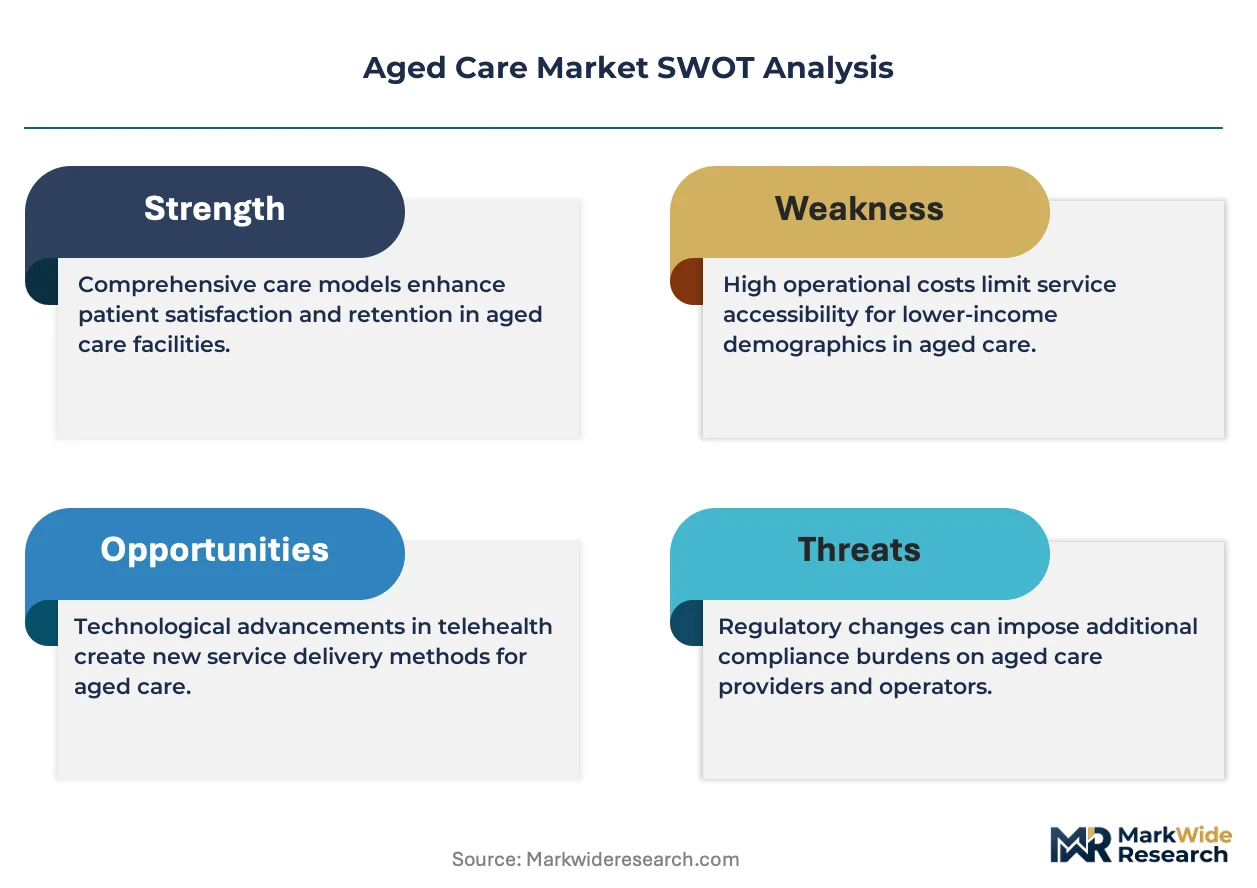
The central dynamic in the aged care market is the strategic tension between scaling through technology-driven efficiency and differentiating through high-touch, premium service models. This choice is forced by rising operational costs and new expectations from consumers for personalized care pathways.
Growth Catalysts
- Telehealth Integration:The adoption of remote monitoring platforms to manage chronic conditions like diabetes and hypertension is expanding the scope of home care, allowing for continuous oversight and fewer hospital visits.
- Demographic Shifts:Countries with rapidly aging populations, particularly Japan, are experiencing intense demand for all types of aged care services, driving public and private investment into facility construction and service innovation.
- Regulatory Mandates:Requirements for standardized assessment tools and individualized care plans, such as those enforced in the United States, create a consistent demand for comprehensive care planning and management services.
Market Restraints
- Workforce Shortages:A structural deficit of qualified nurses, therapists, and certified caregivers creates upward pressure on labor costs and limits the capacity of providers to expand services.
- Data Privacy Compliance:Regulations like Europe's GDPR impose significant compliance costs and operational constraints on the use of digital health records and cross-border data sharing, slowing technology adoption.
- System Interoperability:The lack of standardized communication protocols between different electronic health record systems, pharmacy software, and medical devices creates data silos, hindering the delivery of integrated care.
Strategic Opportunities
- Specialized Care Niches:Developing facilities and programs dedicated to specific, high-acuity needs, such as memory care for Alzheimer's and dementia patients, addresses a critical gap in the market.
- Predictive Analytics:The convergence of AI algorithms with data from wearable sensors and smart home devices enables providers to predict health events like falls or infections, shifting from reactive to proactive care models.
- Wellness-Oriented Communities:There is an opportunity to develop retirement communities focused on preventative health, active lifestyles, and social engagement, attracting a younger, more affluent demographic of seniors.
Industry Challenges
- Staff Training and Retention:Providers face the ongoing operational challenge of recruiting, training, and retaining skilled care staff in a highly competitive labor market, impacting service quality and consistency.
- Regulatory Navigation:Adhering to a complex and divergent patchwork of state, national, and international regulations, including staff-to-resident ratios in Germany, consumes significant administrative resources.
- Legacy System Integration:Many established providers struggle with the technical and financial challenge of integrating modern digital tools with outdated, on-premise IT infrastructure, limiting efficiency gains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aged Care Market |
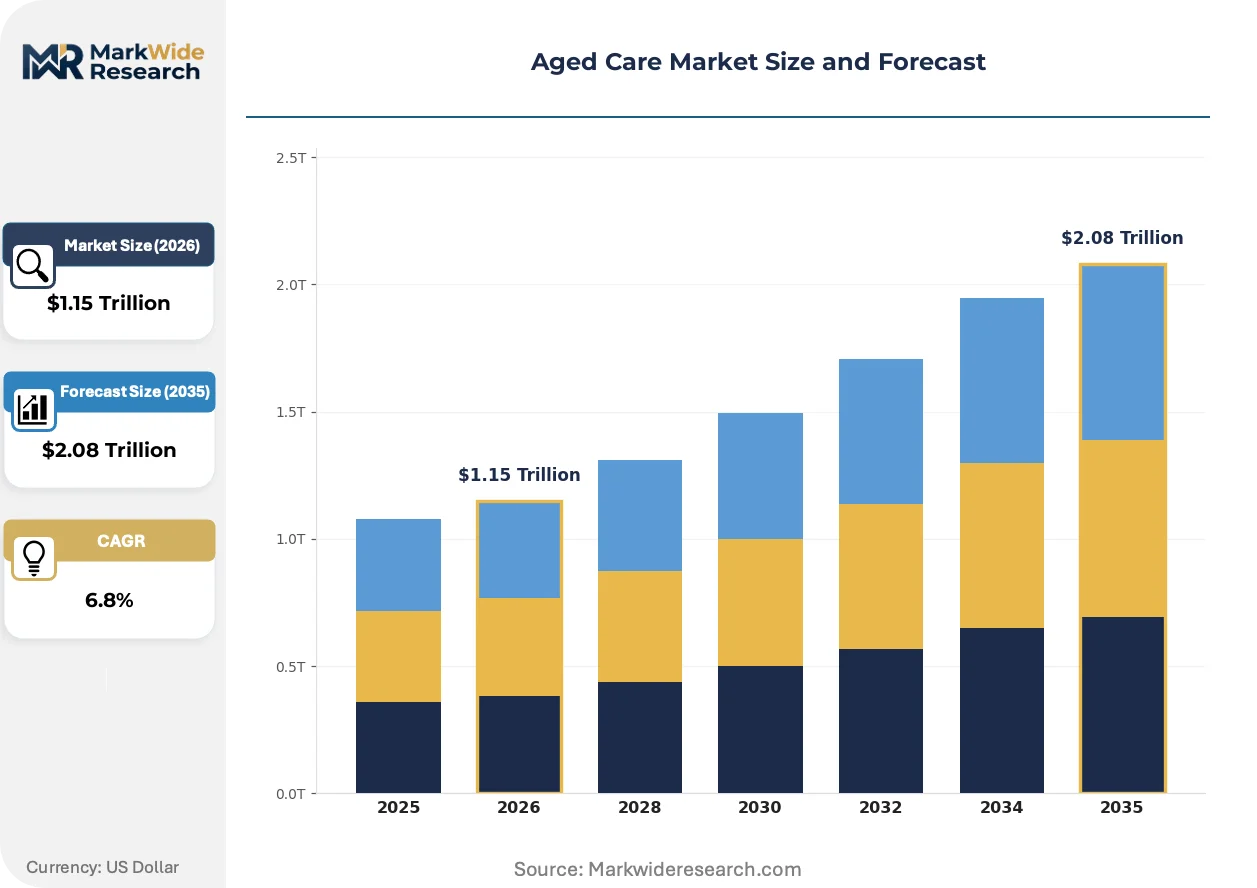
| Market Size in 2026 | $1.15 Trillion |
| Market Size in 2035 | $2.08 Trillion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Residential Care, Home Care, Respite Care, Day Care, Palliative Care Care Setting: Nursing Homes, Assisted Living Facilities, Community Centers, Memory Care Units, Rehabilitation Centers Funding Source: Private Pay, Government Funded, Insurance Supported, Charitable Contributions, Employer Sponsored End User: Seniors with Chronic Conditions, Physically Disabled Elders, Dementia Patients, Post-Surgery Seniors, Mental Health Clients |
| Companies Covered | Extendicare Inc., Atria Senior Living, Chartwell Retirement Residences, SE Health, ParaMed, Sienna Senior Living, Amica Senior Lifestyles, WELL Health Technologies, Revera Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aged Care Market Strategic Shifts & Innovations
A dual pursuit of hyper-personalization and operational efficiency is reshaping service delivery. Providers are adopting new technologies and service models to meet consumer demands for customized care while managing the economic pressures of a consolidating payer landscape.
Ambient sensing technology uses passive, non-intrusive sensors to monitor activities of daily living, gait, and sleep patterns. Assisted Living operators are the primary adopters, using the data for early fall detection and identifying subtle behavioral changes that may indicate a health decline. This technology is integrating with electronic health records and nurse call systems, providing a holistic, real-time view of resident well-being and enabling more proactive clinical interventions.
Europe's General Data Protection Regulation (GDPR) establishes a stringent framework for handling sensitive health information. Its enforcement compels providers and their technology partners to engineer privacy into their systems, investing heavily in secure data architecture and transparent consent management. Digital health firms targeting the European Union are most affected, often redesigning data governance and storage protocols to meet these strict compliance standards.
Consumer preference is shifting decisively toward aging in place rather than entering institutional settings. This behavioral change directly supports the expansion of the Home Care service segment, which is outpacing growth in traditional residential care. The trend is especially visible in North America and parts of Europe, where government reimbursement policies increasingly favor community-based services that delay or prevent more costly nursing home admissions.
Aged Care Market Segmentation
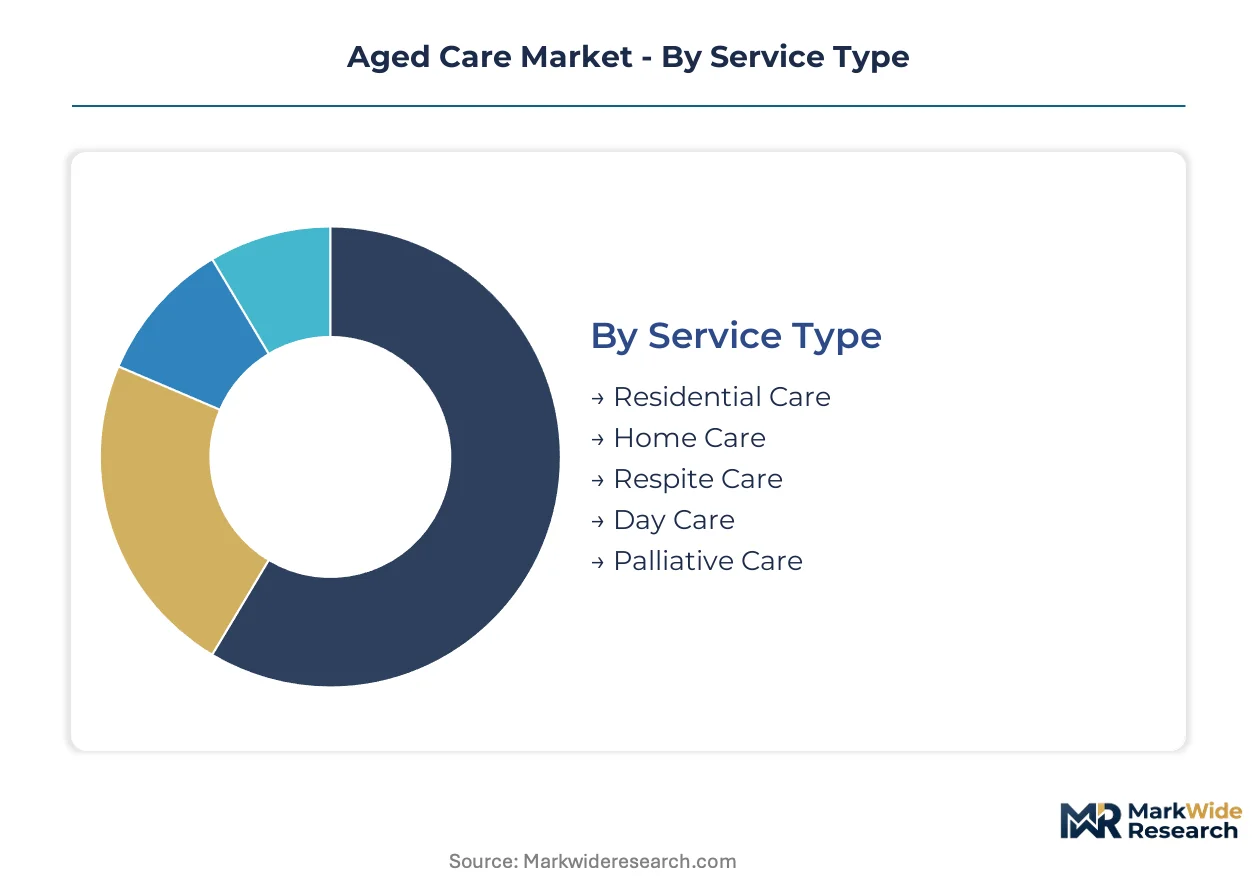
The aged care market's diverse service offerings and support models necessitate detailed segmentation. Understanding these distinct categories helps providers tailor services and allocate resources effectively. This segmentation analysis delineates the market across key dimensions, revealing varied operational requirements and consumer preferences.
Service Type:
Regulatory bodies like Germany's MDK (Medical Review Board) and the US Centers for Medicare & Medicaid Services (CMS) impose distinct certification requirements across various service types, impacting operational complexity and reimbursement eligibility.
- Home Care:This segment provides non-medical and skilled healthcare services directly in the client's residence. Demand concentrates in North America, driven by consumer preference for aging in place and government reimbursement shifts.
- Residential Care:Residential care encompasses long-term living arrangements where older adults receive daily support, meals, and supervision within a communal facility. Japan's aging population drives significant investment into new facilities.
- Respite Care:Respite care offers temporary relief for primary caregivers, providing short-term care for elders.
- Day Care:Day care centers offer supervised activities and social engagement for seniors during daytime hours.
- Palliative Care:Palliative care focuses on comfort and improving quality of life for individuals facing serious illnesses.
Home Care sits at the top of the volume ranking, with Palliative Care climbing the fastest.
Care Setting:
Each care setting serves distinct functional needs and acuity levels, dictating the intensity of medical support and daily assistance provided to residents.
- Assisted Living Facilities:These facilities offer housing, personal care services, and supervision for individuals needing assistance with daily activities. Demand expands rapidly in the United States, driven by preference for less restrictive environments.
- Nursing Homes:Nursing homes provide 24-hour skilled nursing care, rehabilitation services, and long-term medical supervision for individuals with complex health conditions. Germany's strict staff-to-resident ratios influence operational models.
- Community Centers:Community centers provide social activities, educational programs, and wellness services for seniors.
- Memory Care Units:Memory care units specialize in supporting individuals with Alzheimer's and other dementias.
- Rehabilitation Centers:Rehabilitation centers offer physical, occupational, and speech therapies for seniors recovering from illness or injury.
Assisted Living Facilities are gaining market share, while Nursing Homes maintain a significant operational footprint.
Funding Source:
Funding sources often dictate the cost tier of services accessible to seniors, influencing the scope and quality of care received.
- Government Funded:This segment includes financial support from national or regional government programs, such as Medicare and Medicaid in the US. Regulatory frameworks like the EU's F-Gas Regulation indirectly impact facility costs.
- Private Pay:Private pay involves individuals or families directly covering aged care service costs from personal savings or family contributions. This mechanism often enables access to high-touch, premium care models with enhanced amenities.
- Insurance Supported:Insurance-supported care relies on long-term care insurance policies or private health insurance plans.
- Charitable Contributions:Charitable contributions involve funding from non-profit organizations, foundations, or individual donations.
- Employer Sponsored:Employer-sponsored programs offer benefits or subsidies for aged care services as part of employee welfare.
Government Funded initiatives drive broad service accessibility, while Private Pay models enable specialized, premium offerings.
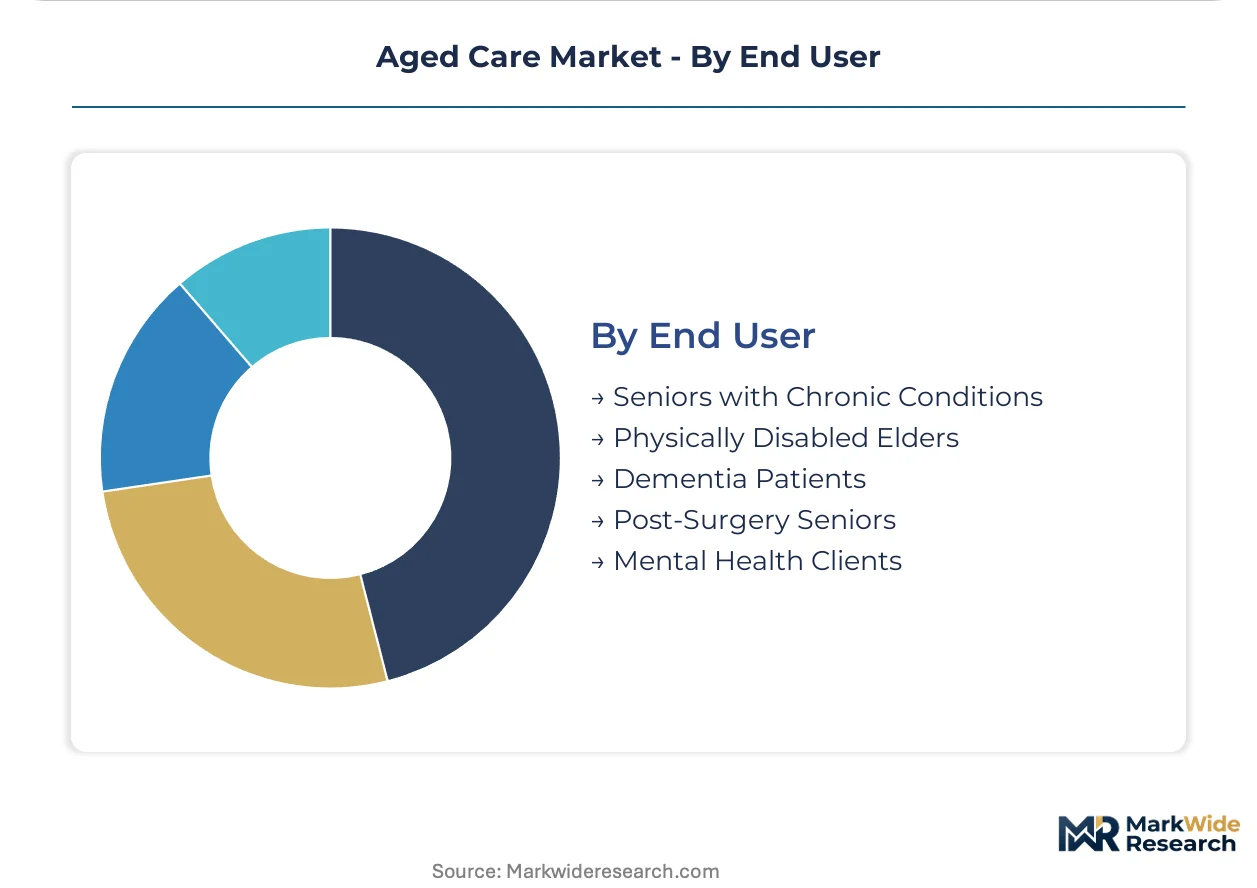
End User:
The specific needs of each end-user group necessitate highly specialized care plans and facility adaptations.
- Seniors with Chronic Conditions:This group manages long-term health issues like diabetes, requiring ongoing medical supervision and support. Telehealth platforms expand home care for these seniors, enabling continuous remote monitoring.
- Dementia Patients:This segment comprises individuals experiencing cognitive decline due to Alzheimer's disease, requiring specialized memory care and structured environments. Dedicated memory care units address a critical market gap for this high-acuity population.
- Physically Disabled Elders:Physically disabled elders require assistance with mobility, daily tasks, and adaptive equipment.
- Post-Surgery Seniors:Post-surgery seniors need temporary rehabilitative care, wound management, and recovery support.
- Mental Health Clients:Mental health clients require specialized support for conditions such as depression or anxiety in later life.
Seniors with Chronic Conditions generate consistent demand, and Dementia Patients require increasingly specialized interventions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan faces intense demand for aged care services due to its rapidly aging population. In contrast, the United States experiences significant demand driven by preference for less restrictive environments. Both nations grapple with balancing high-quality care with escalating operational costs.
Japan
Japan experiences intense demand for all types of aged care services from its rapidly aging population. METI initiatives support significant investment into new facility construction and service innovation. Tokyo and Osaka are seeing substantial development of residential care facilities and advanced home care technologies.
United States
Consumer preference for aging in place fuels the expansion of the Home Care service segment. The US Centers for Medicare & Medicaid Services (CMS) mandate standardized assessment tools and individualized care plans. Major metropolitan areas like New York and Los Angeles witness robust growth in Assisted Living Facilities.
Germany
Strict regulatory frameworks, including staff-to-resident ratios, influence operational models for nursing homes. The MDK (Medical Review Board) sets distinct certification requirements across various service types. Berlin and Munich are hubs for specialized palliative care and advanced rehabilitation centers.
Canada
Canada's aging demographic generates consistent demand for a full continuum of care services. Health Canada oversees quality and safety standards across the continuum of care services. Toronto and Vancouver observe substantial expansion in retirement residences and home support programs.
Australia
A strong consumer preference for community-based services supports the expansion of home care. The TGA (Therapeutic Goods Administration) regulates medical devices and digital health solutions used in aged care. Sydney and Melbourne are seeing increased adoption of ambient sensing technology in assisted living.
Aged Care Market Key Industry Players
North American providers anchor one tier, specializing in comprehensive care continua, while European specialists often hold positions in high-touch, premium service models. The market exhibits a tiered structure, with large insurance networks consolidating procurement and smaller entities focusing on niche services. Key strategic archetypes include integrated care networks, luxury senior living operators, and technology-enabled home care providers. Providers frequently engage in geographic expansion and strategic partnerships, alongside technology integration, to broaden their service reach and enhance operational efficiency.
Within the integrated care network tier, Extendicare Inc. exemplifies a provider offering a full continuum of care, from home support to long-term facilities. Atria Senior Living represents a high-end operator, differentiating through luxurious amenities and personalized service programs in its communities. Chartwell Retirement Residences, a Canadian corporation, occupies a position leveraging significant portfolio scale within Canada for operational efficiency. These entities collectively underscore the market's strategic choice between scaling through technology-driven efficiency and differentiating through premium care models, driven by rising operational costs and consumer expectations for personalized care pathways.
| Leading Market Players |
|---|
| Extendicare Inc. |
| Atria Senior Living |
| Chartwell Retirement Residences |
| SE Health |
| ParaMed |
| Sienna Senior Living |
| Amica Senior Lifestyles |
| WELL Health Technologies |
| Revera Inc. |
| Others |
Cost & Logistics Intelligence
Government reimbursement shifts towards home care are forcing aged care providers to optimize service delivery, which impacts pricing models for residential facilities. This demand-side pressure necessitates supply chain adaptation for diverse care settings.
Pricing Analysis
Capacity additions in Japan are reshaping price floors for residential care services, particularly within its rapidly aging population. The dominant pricing model remains a hybrid of value-based contracts for premium services and government-funded rates for essential care. Price differentiation stems from service customization levels and facility amenities offered. Pricing pressure stems from persistent workforce shortages in Germany, increasing labor costs for nursing homes. Government-funded initiatives exhibit the highest price sensitivity, while private pay models access premium, less sensitive offerings.
Supply Chain Analysis
The reverse logistics of medical equipment and assistive devices presents unique challenges for aged care providers, requiring specialized handling. Geographic supply concentration for essential medical devices often centers in China and the United States. The aged care supply chain depends on critical inputs such as specialized sensors for ambient monitoring and digital health platforms for data management. A structural supply chain risk involves single-source vulnerability for key technology components. Distribution runs through a dual model: direct-to-consumer for home care technologies and institutional procurement for large residential facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Significant wage differentials for care staff between Western Europe and Southeast Asia create a geographic arbitrage opportunity within the aged care market. This cost disparity influences strategic investment decisions for service expansion.
For Market Incumbents:Anticipate increased regulatory scrutiny on staff-to-resident ratios in Germany by investing in advanced training programs for caregivers. Consolidate service offerings across residential and home care segments to counter technology-enabled home care providers. Leverage existing infrastructure for new specialized care niches, like memory care, to mitigate margin pressure from rising operational costs. Invest in digital health platforms to enhance operational efficiency and personalize care delivery.
For New Entrants and Emerging Players:Home health agencies represent a primary channel partner for new entrants targeting the rapidly expanding home care segment in North America. Focus on specialized memory care units in underserved US suburban areas, leveraging predictive analytics for proactive care. Develop wellness-oriented communities that attract a younger, more affluent demographic seeking preventative health services. Offer technology-driven solutions for remote monitoring to penetrate the chronic conditions segment.
For Investors and Strategic Acquirers:Asymmetric upside sits with technology-enabled home care platforms that can scale efficiently across diverse regulatory environments. Long-term viability depends on integrating AI-driven insights for personalized care pathways over the next decade. Acquisition targets should prioritize providers with strong data governance frameworks compliant with Europe's GDPR. Watch for increased government funding for community-based services as a key inflection indicator for market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Telehealth Monitoring Capabilities | Telehealth platforms allow continuous oversight for seniors with chronic conditions, reducing hospital visits. |
| Acquire Regional Memory Care Specialists | Acquiring specialized memory care units addresses a critical gap for dementia patients in specific markets. |
| Invest in Staff Training and Retention Programs | Addressing workforce shortages through training ensures consistent service quality and compliance with staff ratios. |
| Develop Wellness-Oriented Retirement Communities | These communities attract affluent seniors seeking preventative health and active lifestyles in North America. |
| Implement GDPR-Compliant Data Architecture | Secure data architecture ensures compliance with Europe's GDPR, facilitating digital health record adoption. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region. This analysis combined extensive primary interviews with aged care facility administrators, home care managers, and government health officials. Secondary validation utilized reports from the US Centers for Medicare & Medicaid Services, Germany's MDK, and Japan's METI. Bottom-up aggregation and top-down market sizing ensured robust data triangulation.
Granular modeling detailed service type, care setting, and funding source across key geographies. CAGRs were derived through a comprehensive review of historical growth trends and future demand projections over the analysis window. Population aging rates and chronic disease prevalence served as critical industry-specific forecast inputs for the modeling period.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory changes and technological disruption. The projections reflect current market assumptions, but unforeseen global health crises or economic downturns could revise these outlooks. Practitioners should monitor shifts in government reimbursement policies for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
US Value-Based Healthcare Service Market
Healthcare Services
Funeral Products and Services Market
Healthcare Services
Healthcare Physician Staffing Market
Healthcare Services
Tissue Banking Market
Healthcare Services
Per Diem Nurse Staffing Market
Healthcare Services
Global Mobile Clinics Market
Healthcare Services
Global Cath Lab Services Market
Healthcare Services
Pharmaceutical Contract Sales Organizations Market
Healthcare Services
Eastern Europe Online Pharmacy Market
Healthcare Services
Global Healthcare Provider Network Management Market
Healthcare Services
Global Sperm Bank Market
Healthcare Services
Hospice and Palliative Care Centers Market
Healthcare Services
Global Infusion Pharmacy Management Market
Healthcare Services
Canada Senior Living Market
Healthcare Services
US Hospice Market
Healthcare Services
Packaging and Labeling (Healthcare) Services Market