
 EMEA Home Infusion Services Market | 2026-2036
EMEA Home Infusion Services Market Size, Share, and Industry Trends Forecast 2026-2036
EMEA Home Infusion Services Market Intelligence
Oncology is repositioning the demand profile of EMEA home infusion services as more chemotherapy and biologic regimens move from hospital wards to living-room settings. Baxter International Inc. leverages its broad portfolio of ambulatory pumps and sterile compounding infrastructure across European markets. Fresenius Kabi anchors its position through hospital partnerships that extend into discharge planning and home-based continuation of IV therapies. B. Braun Melsungen AG differentiates via integrated safety-engineered devices that reduce medication error risk in unsupervised environments.
Home infusion services encompass the preparation, delivery, administration, and monitoring of intravenous therapies outside acute-care facilities, requiring cold-chain logistics, aseptic compounding, and remote patient surveillance to maintain therapeutic efficacy and safety. Electronic pump systems command the technology segment due to programmable flow rates and alarm functions that support unsupervised administration, while gravity infusion retains cost-sensitive share in hydration therapy across price-constrained markets. Antibiotic infusion leads product type demand as outpatient parenteral antimicrobial therapy protocols expand, though pain management solutions generate higher per-patient margins through specialized nursing and controlled-substance compliance.
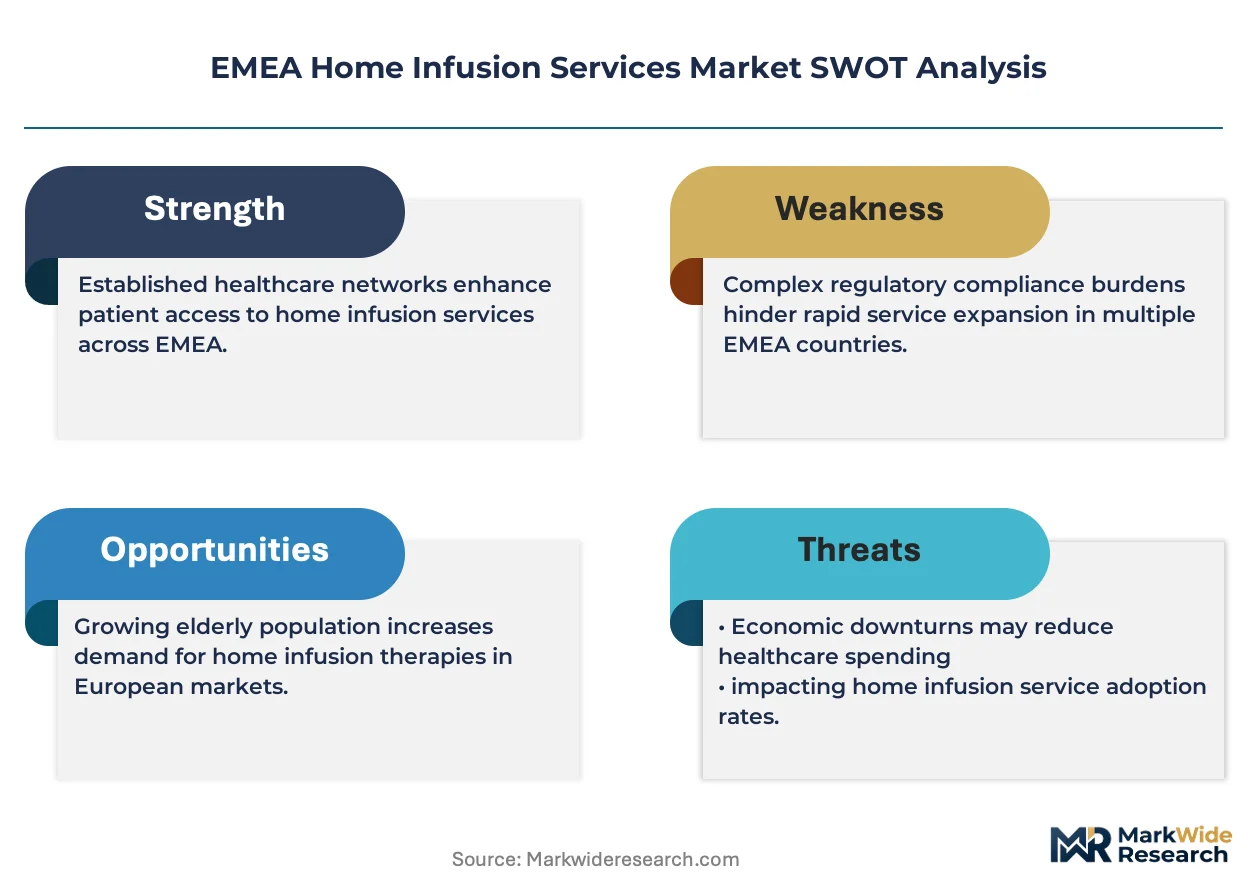
The EU Medical Device Regulation and national health technology assessment bodies in France and Germany shape device approval timelines and reimbursement thresholds for home-based infusion. EMA pharmacovigilance requirements and GDPR-compliant remote monitoring standards add compliance layers that favor scaled service providers over fragmented regional operators. Stakeholders must weigh technology upgrade cycles against reimbursement lag to preserve margin structures as clinical evidence requirements intensify for at-home administration.
Market Dynamics
The EMEA home infusion services sector faces structural pressure from the EU Medical Device Regulation's phased enforcement, which mandates upgraded pump certification and post-market surveillance systems that smaller operators cannot absorb.
Growth Catalysts
- OPAT Protocol Expansion:Outpatient parenteral antimicrobial therapy programs in France and Germany now reimburse home-based antibiotic administration, diverting inpatient days to residential settings.
- GDPR-Compliant Remote Monitoring:Telehealth platforms with encrypted patient data transmission satisfy EMA pharmacovigilance requirements while enabling real-time dose adjustment by hospital-based clinicians.
- Oncology Shift to Subcutaneous Biologics:Patient preference for avoiding hospital-acquired infections during neutropenic periods accelerates demand for home-administered immunotherapy regimens.
Market Restraints
- Cold-Chain Logistics Concentration:Temperature-controlled distribution networks remain concentrated among three pan-European pharmaceutical logistics providers, creating single-point vulnerability for biologic therapies.
- Reimbursement Lag in Southern Europe:Italy and Spain maintain hospital-centric reimbursement codes that fail to cover nursing visits and pump rental for home-based infusion.
- Substitute Pressure from Oral Antivirals:Direct-acting oral hepatitis C regimens eliminate indication for interferon infusion in previously captive patient cohorts.
Strategic Opportunities
- Middle East Greenfield Markets:Saudi Arabia's MOHAP licensing framework for home healthcare operators creates first-mover advantage for European service providers with MDR-compliant device portfolios.
- Convergence of Wearable Sensors and Ambulatory Pumps:Integration of continuous glucose monitors with insulin infusion systems opens diabetes management to home infusion protocols previously limited to hospital endocrinology units.
- France's Territorial Hospital Group Mandate:GHT consolidation requires standardized discharge planning across regional hospital networks, favoring contracted home infusion partners with multi-site service capability.
Industry Challenges
- Specialized Nursing Shortage:Chemotherapy administration certification requirements exceed supply of oncology-certified nurses in the UK and Netherlands, constraining service expansion.
- MDR Transition Timeline Compression:Legacy pump fleets require technical documentation remediation and notified body recertification before May deadlines, straining quality assurance bandwidth.
- Legacy IT Integration Friction:Hospital electronic health record systems lack API standardization with home infusion scheduling platforms, forcing manual data reconciliation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EMEA Home Infusion Services Market |
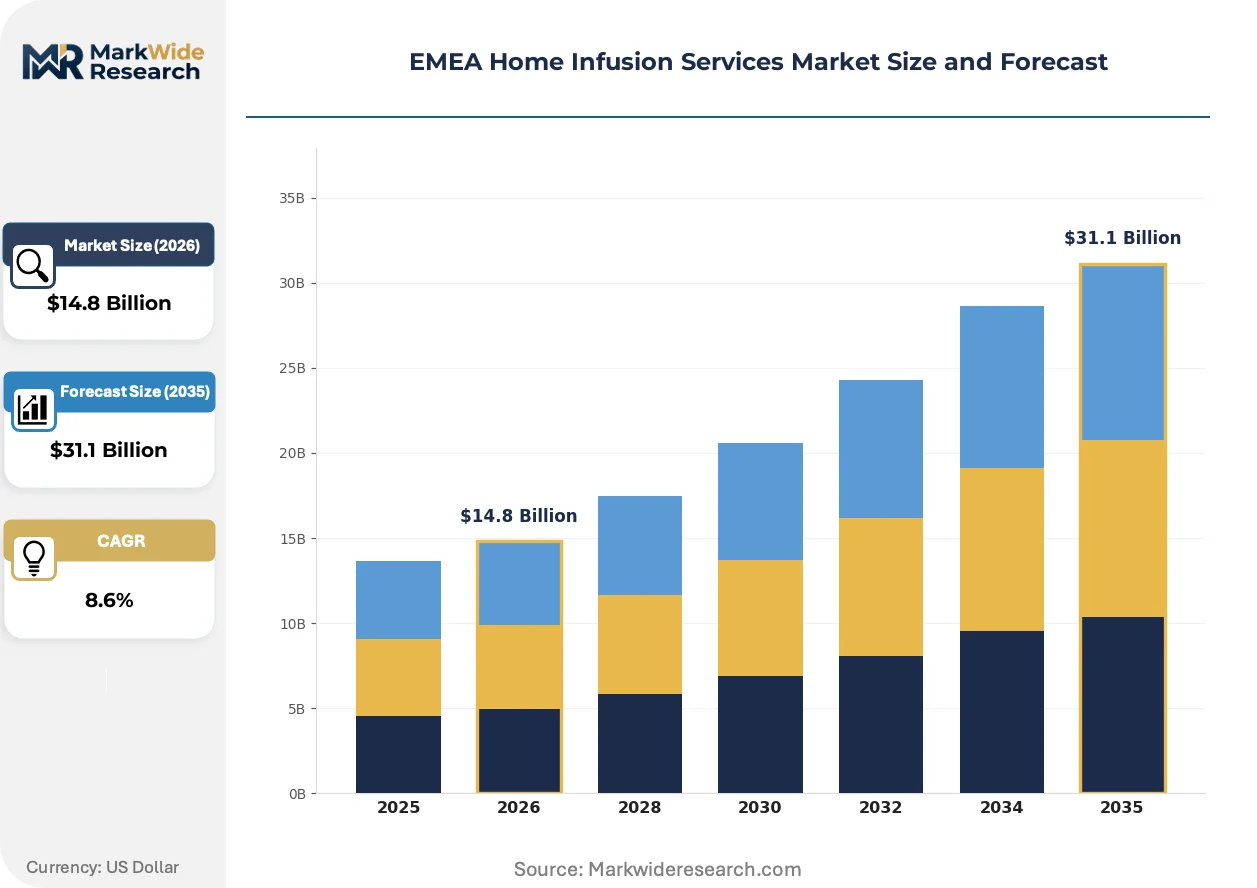
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.1 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: IV Nutrients, Antibiotic Infusion, Pain Management Solutions, Hydration Therapy End User: Hospitals, Home Healthcare Agencies, Pharmacies, Long-term Care Facilities Technology: Electronic Pump Systems, Gravity Infusion, Manual Infusion, Safety Devices Service Type: Patient Education, Supply Management, 24-hour Support, Therapy Monitoring |
| Companies Covered | Baxter International Inc., B. Braun Melsungen AG, Fresenius Kabi, ICU Medical, Becton Dickinson and Company, Terumo Corporation, Johnson & Johnson Services, Inc., Smith & Nephew plc, Pfizer Inc., Others |
| Regions Covered | EMEA: Germany, UK, France, Saudi Arabia, UAE, South Africa, Russia, Italy, Rest of EMEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EMEA Home Infusion Services Market Strategic Shifts & Innovations
Smart pump connectivity and predictive analytics are compressing the window between dose deviation and clinical intervention, transforming home infusion from reactive nursing visits to continuous remote management.
Closed-loop infusion systems with embedded dose-error reduction software are electrifying safety protocols in unsupervised environments. Oncology clinics in Germany and Switzerland deploy these devices for high-risk chemotherapy regimens previously restricted to inpatient wards. The technology is electrifying competitive positioning by converting liability-sensitive hospital pharmacy directors into home infusion advocates.
The EU Medical Device Regulation's post-market clinical follow-up requirements extend surveillance obligations from manufacturers to service providers operating infusion equipment. German notified bodies now demand real-world performance data submission for pump models exceeding ten years in field deployment. Oncology and immunology service lines bear the heaviest documentation burden, with French operators consolidating device fleets to reduce variant complexity.
Hospital procurement departments unbundle infusion nursing from device rental and pharmacy compounding, treating each as separately sourced cost centers. This fragmentation favors specialized home healthcare agencies with standalone nursing credentials over integrated service providers. The Netherlands and Belgium exhibit the most advanced unbundling, with university hospitals operating competitive tender processes for each service layer.
EMEA Home Infusion Services Market Segmentation
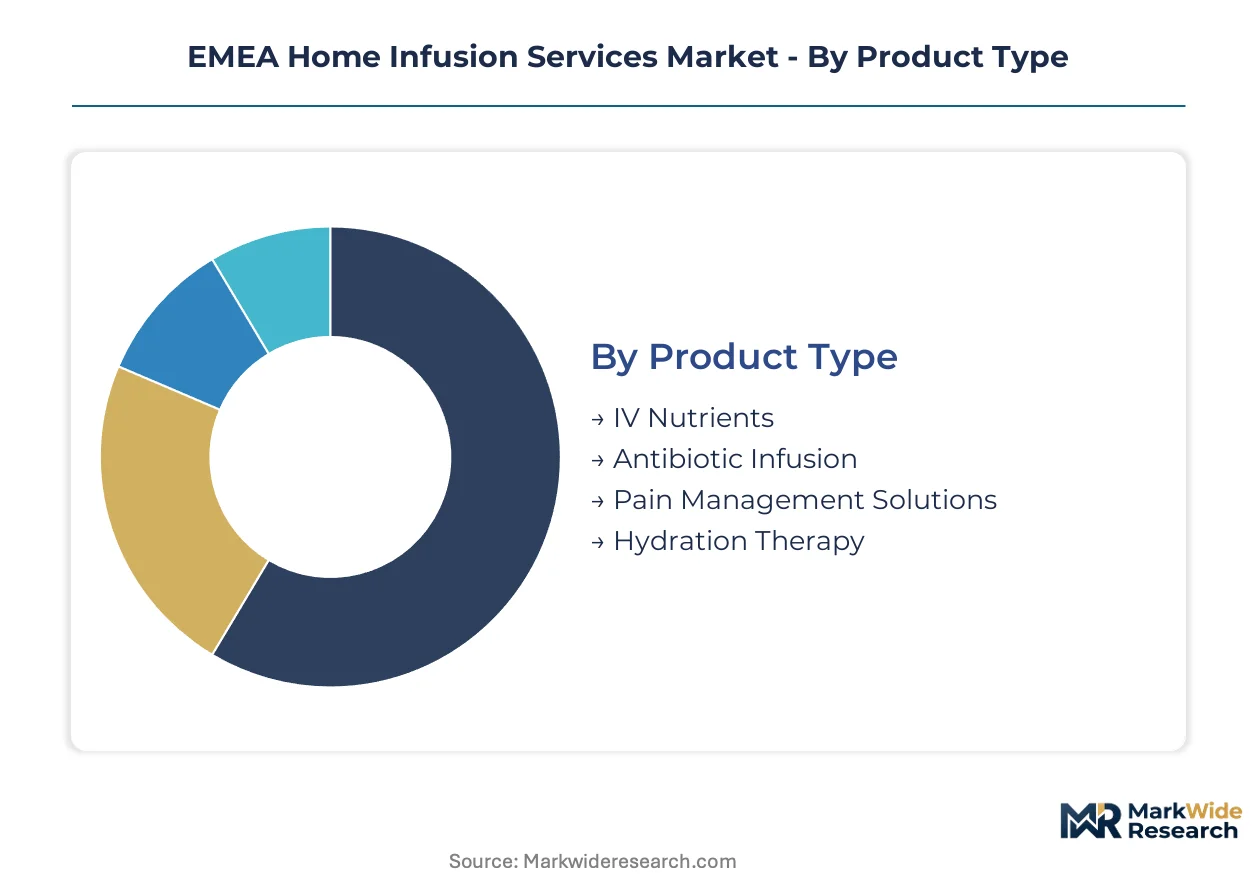
Home infusion services fragment across four intersecting dimensions that determine reimbursement codes, regulatory pathways, and margin structures. Each category reflects a distinct trade-off between clinical risk, operational complexity, and patient autonomy.
Product Type:
Standardized infusion protocols dominate high-volume categories, while customized compounding commands premium pricing in specialized therapeutic areas.
- IV Nutrients:Parenteral nutrition formulations combine amino acids, lipids, and micronutrients for patients with non-functional gastrointestinal tracts. Demand concentrates in Germany and France among oncology and Crohn's disease cohorts, constrained by the EU Medical Device Regulation's sterile compounding documentation requirements.
- Antibiotic Infusion:Outpatient parenteral antimicrobial therapy protocols deliver cephalosporins and glycopeptides through peripherally inserted central catheters. France and Germany now reimburse home-based OPAT administration, diverting inpatient days to residential settings while reducing hospital-acquired infection exposure.
- Pain Management Solutions:Patient-controlled analgesia and continuous opioid infusions for palliative care and post-surgical recovery.
- Hydration Therapy:Electrolyte replacement and fluid resuscitation for dehydration and chemotherapy-induced nausea.
Most installed capacity flows through Antibiotic Infusion. Expansion is steepest in Pain Management Solutions.
End User:
Procurement authority shifts from centralized hospital pharmacy directors to distributed home healthcare agency managers as patients transition through discharge.
- Hospitals:Inpatient units initiate infusion therapies and coordinate discharge planning to external providers. German territorial hospital groups now mandate standardized home infusion contracting across regional networks, consolidating vendor relationships.
- Home Healthcare Agencies:Licensed nursing services deliver supervised administration and device management in residential settings. French GHT consolidation favors multi-site agencies with MDR-compliant pump fleets and oncology-certified nursing staff.
- Pharmacies:Compounding facilities prepare sterile admixtures and coordinate cold-chain logistics to patient homes.
- Long-term Care Facilities:Skilled nursing environments manage chronic infusion regimens for elderly populations with limited mobility.
Service volume concentrates in Home Healthcare Agencies. Margin expansion is most pronounced in Long-term Care Facilities.
Technology:
Programmability and alarm sophistication separate premium device tiers from basic gravity-dependent systems.
- Electronic Pump Systems:Programmable volumetric and syringe pumps with dose-error reduction software and remote connectivity. German oncology clinics deploy these for high-risk chemotherapy regimens previously restricted to inpatient wards.
- Gravity Infusion:Simple drip-rate systems without electronic control retain cost-sensitive share in hydration therapy across price-constrained Southern European markets.
- Manual Infusion:Push-syringe and bolus administration for intermittent dosing protocols.
- Safety Devices:Needle-free connectors, anti-siphon valves, and air-in-line detectors integrated into infusion sets.
Electronic Pump Systems carry the heaviest installed base. Safety Devices are climbing the fastest as MDR post-market surveillance requirements intensify.
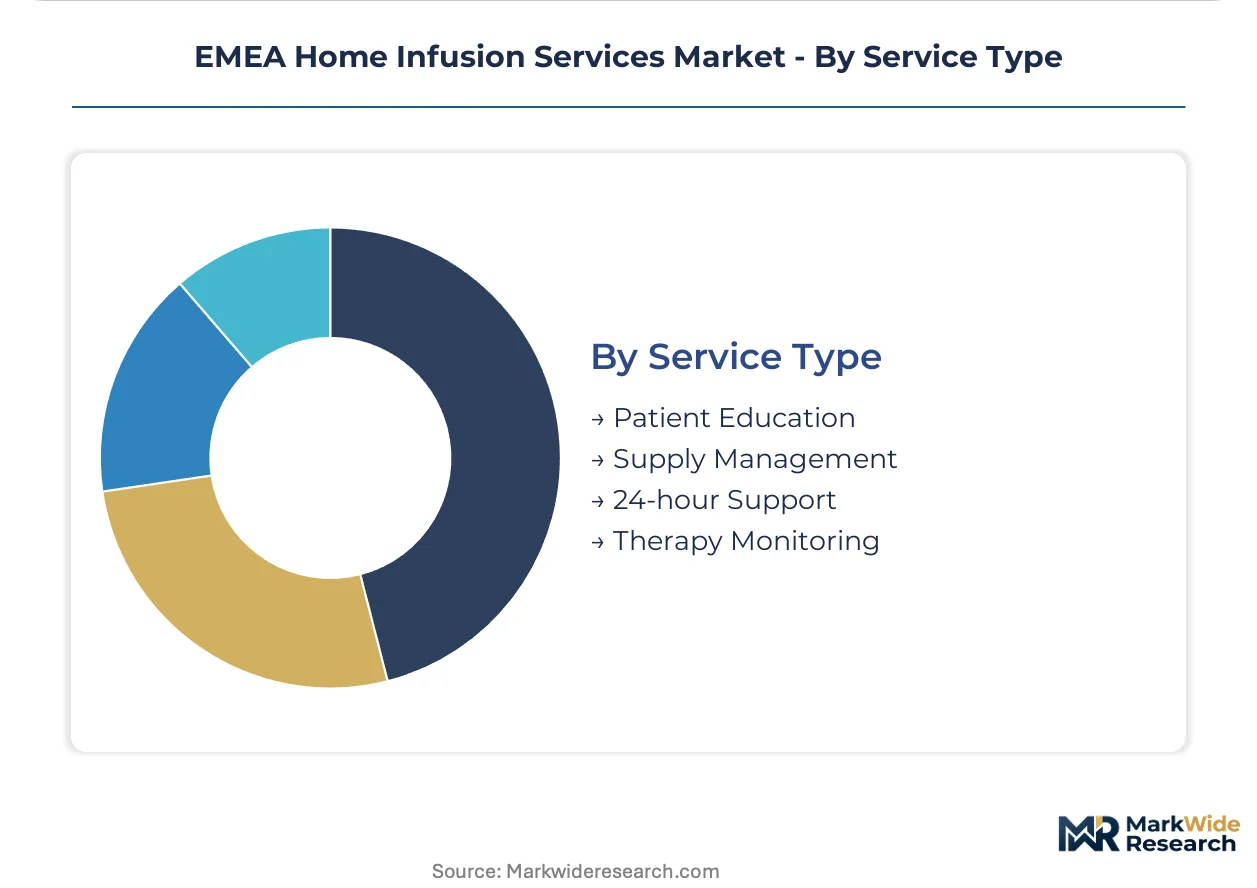
Service Type:
Reactive nursing visits are compressing into continuous remote management through predictive analytics platforms.
- Patient Education:Training protocols for self-administration, device troubleshooting, and infection recognition. UK operators face constraints from chemotherapy certification requirements that exceed nurse supply.
- Supply Management:Cold-chain logistics, inventory replenishment, and waste disposal coordination. Temperature-controlled distribution networks remain concentrated among pan-European pharmaceutical logistics providers.
- 24-hour Support:On-call nursing and technical assistance for device malfunction or adverse events.
- Therapy Monitoring:Remote surveillance of infusion parameters and patient-reported outcomes through GDPR-compliant telehealth platforms.
Therapy Monitoring commands the highest growth trajectory. Supply Management absorbs the largest operational cost base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping service provider footprints across EMEA, with operators migrating toward jurisdictions offering faster MDR certification pathways and more favorable reimbursement coding. Germany and France absorb disproportionate compliance investment due to stringent notified body requirements, while Middle Eastern markets attract European players seeking greenfield licensing advantages.
Germany
Oncology discharge planning and territorial hospital group consolidation drive demand for standardized home infusion contracting. The EU Medical Device Regulation mandates upgraded pump certification through German notified bodies like TÜV SÜD, extending surveillance obligations to decade-old device fleets. The Rhine-Ruhr corridor concentrates multi-site service providers with MDR-compliant infrastructure and oncology-certified nursing networks.
France
Groupements Hospitaliers de Territoire integration requires uniform discharge protocols across regional hospital networks, favoring contracted partners with pan-regional coverage. ANSM pharmacovigilance standards and CNIL data governance rules impose layered compliance on remote monitoring platforms. The Île-de-France region hosts the densest cluster of integrated home healthcare agencies serving Parisian hospital discharge flows.
United Kingdom
OPAT program expansion and NHS long-term plan targets for hospital-at-home services accelerate antibiotic and hydration therapy migration. Chemotherapy administration certification requirements exceed available oncology nurse supply, constraining service scalability. Greater Manchester and London metropolitan areas concentrate specialized nursing agencies with hospital partnership frameworks.
Saudi Arabia
MOHAP licensing framework for home healthcare operators creates first-mover terrain for European service providers with established MDR device portfolios. Vision 2030 healthcare privatization mandates expand private insurance coverage for residential infusion therapies. Riyadh and Jeddah medical cities anchor initial market development, with European-trained clinical staff transferring operational protocols.
Netherlands
Hospital procurement unbundling treats infusion nursing, device rental, and pharmacy compounding as separately tendered cost centers, fragmenting vendor relationships. GDPR-compliant telehealth infrastructure supports remote therapy monitoring for dispersed rural populations. The Randstad conurbation concentrates university hospital networks operating competitive multi-layer sourcing processes.
EMEA Home Infusion Services Market Key Industry Players
Strategic partnerships dominate the current landscape as device manufacturers align with home healthcare agencies to secure discharge planning pathways. The vendor base stratifies across three tiers: multinational medtech conglomerates with full-stack infusion portfolios, regional service specialists with nursing-intensive operations, and emerging digital health platforms with remote monitoring capabilities. Consolidation pressure intensifies as MDR compliance costs eliminate sub-scale operators. Geographic expansion into Middle Eastern greenfield markets and backward integration into sterile compounding represent the primary competitive vectors.
Within the multinational medtech tier, Baxter International Inc., B. Braun Melsungen AG, and Fresenius Kabi occupy anchor positions shaped by their European manufacturing heritage and hospital system embeddedness. These Germany-based and US-headquartered entities exemplify the integrated device-and-service archetype, leveraging sterile compounding infrastructure and ambulatory pump portfolios to secure territorial hospital group contracts. Their scale positions them to absorb MDR transition costs that fragment smaller competitors, while their geographic footprint enables knowledge transfer into Saudi Arabian and UAE licensing frameworks.
| Leading Market Players |
|---|
| Baxter International Inc. |
| B. Braun Melsungen AG |
| Fresenius Kabi |
| ICU Medical |
| Becton Dickinson and Company |
| Terumo Corporation |
| Johnson & Johnson Services, Inc. |
| Smith & Nephew plc |
| Pfizer Inc. |
| Others |
Cost & Logistics Intelligence
Medical-grade polymer price indices cascade through sterile compounding infrastructure into three distinct pricing tiers across EMEA home infusion services. Hospital procurement unbundling in the Netherlands and Belgium fragments vendor relationships, compressing margins on device rental while elevating premiums for integrated pharmacy-nursing bundles.
Pricing Analysis
Distributor margins on ambulatory pump fleets absorb the steepest compression as German territorial hospital groups consolidate procurement. Pricing stratifies across MDR-certified premium systems, transitional standard devices, and economy gravity-infusion alternatives. Cost compression in the economy tier intensifies because Italian and Spanish reimbursement codes exclude home nursing coverage. Home healthcare agencies exhibit highest price sensitivity, while oncology clinics with neutropenic infection protocols remain least sensitive to pump rental premiums.
Supply Chain Analysis
Single-source vulnerability sits with pan-European pharmaceutical logistics providers controlling temperature-controlled distribution for biologic therapies. Manufacturing concentration clusters in Germany, Switzerland, and the Netherlands for precision pump components and sterile admixture preparation. Raw material dependencies include medical-grade polymers, lithium-ion power cells, and cold-chain refrigerants. Tariff exposure on Chinese-sourced electronic components threatens cost stability. Distribution runs through hospital pharmacy directors, home healthcare agency managers, and direct-to-patient pharmacy compounding networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EMEA home infusion services function as a stable compounder anchored by irreversible clinical migration from inpatient wards to residential settings. The structural shift of oncology and immunology administration outside hospital walls generates recurring revenue streams resistant to cyclical pressure.
For Market Incumbents: Hedge against MDR compliance cost inflation by consolidating device fleets to reduce variant complexity. Acquire oncology-certified nursing agencies in the UK and Netherlands where chemotherapy administration certification constraints exceed supply. Channel control through territorial hospital group partnerships defends against unbundling pressure from procurement departments.
For New Entrants and Emerging Players: The mid-tier price gap between premium electronic pump systems and basic gravity infusion creates entry terrain for connected safety devices with remote monitoring capabilities. Target Saudi Arabia's MOHAP licensing framework as the most penetrable geography, where European MDR-compliant device portfolios transfer operational protocols into greenfield markets. A hospital system partnership go-to-market angle secures discharge planning pathways.
For Investors and Strategic Acquirers: Asymmetric upside sits with regional service specialists with MDR-compliant infrastructure and multi-site nursing networks. The five-to-ten-year viability window favors scaled operators capable of absorbing post-market surveillance documentation burdens. Acquisition targets should display integrated pharmacy compounding and device rental capabilities. Watch France's GHT consolidation pace as the inflection signal for regional vendor consolidation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| MDR Certification Pathway | German notified body engagement secures pump recertification before enforcement deadlines. |
| Hospital System Partnership | GHT integration in France mandates standardized discharge planning across regional networks. |
| Software Companion Development | GDPR-compliant telehealth platforms enable real-time dose adjustment by hospital clinicians. |
| Backward Integration into Compounding | Captive sterile admixture production insulates margin from pharmaceutical logistics concentration. |
| Geographic Expansion | Saudi MOHAP licensing transfers European operational protocols into privatizing healthcare markets. |
Research Approach
Coverage spans Western Europe, the Middle East, and North Africa, with primary inputs from each region combined with secondary validation. Interviews with hospital pharmacy directors, home healthcare agency operators, biomedical engineers, and GPO contracts managers informed operational dynamics. Secondary sources included EMA pharmacovigilance databases, EU Medical Device Regulation guidance documents, hospital procurement databases, and national health technology assessment body reimbursement filings. Bottom-up service volume estimates triangulated against top-down market sizing from device manufacturer disclosures.
Granularity-level modeling captured product type, end user, technology tier, and service type dimensions across the projection horizon. Country-level CAGRs derived from regulatory timeline phasing, reimbursement code expansion trajectories, and nursing supply elasticity estimates. Forecast inputs incorporated MDR transition cost absorption curves, territorial hospital group consolidation schedules, and cold-chain logistics capacity expansion plans.
Caveats apply where MDR enforcement delays, reimbursement code revisions, or oral therapeutic substitutions could materially shift the outlook. Forecasts reflect assumptions about nursing certification pipeline expansion and biologic therapy approval velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Surgical Fluid Disposal Market
Healthcare Services
Pharmaceutical Contract Sales Organizations Market
Healthcare Services
Global Cord Blood Banking Services Market
Healthcare Services
Canada Senior Living Market
Healthcare Services
Patient Throughput and Capacity Management Market
Healthcare Services
Health Care Supply Chain Management Market
Healthcare Services
Assisted Living Market
Healthcare Services
Prescription Delivery Services Market
Healthcare Services
Ambulatory Healthcare Service Market
Healthcare Services
European Union Cross Border Healthcare Market
Healthcare Services
Escort Bed Sharing Market
Healthcare Services
Spa Services Market
Healthcare Services
Biopharmaceutical Third Party Logistics (3PL) Market
Healthcare Services
Care Services Market
Healthcare Services
Inhaled and Intranasal Products Contract Service Providers Market
Healthcare Services
Healthcare Logistics Market