
 Global Operating Room Management Market | 2026-2036
Global Operating Room Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global Operating Room Management Market Foresight
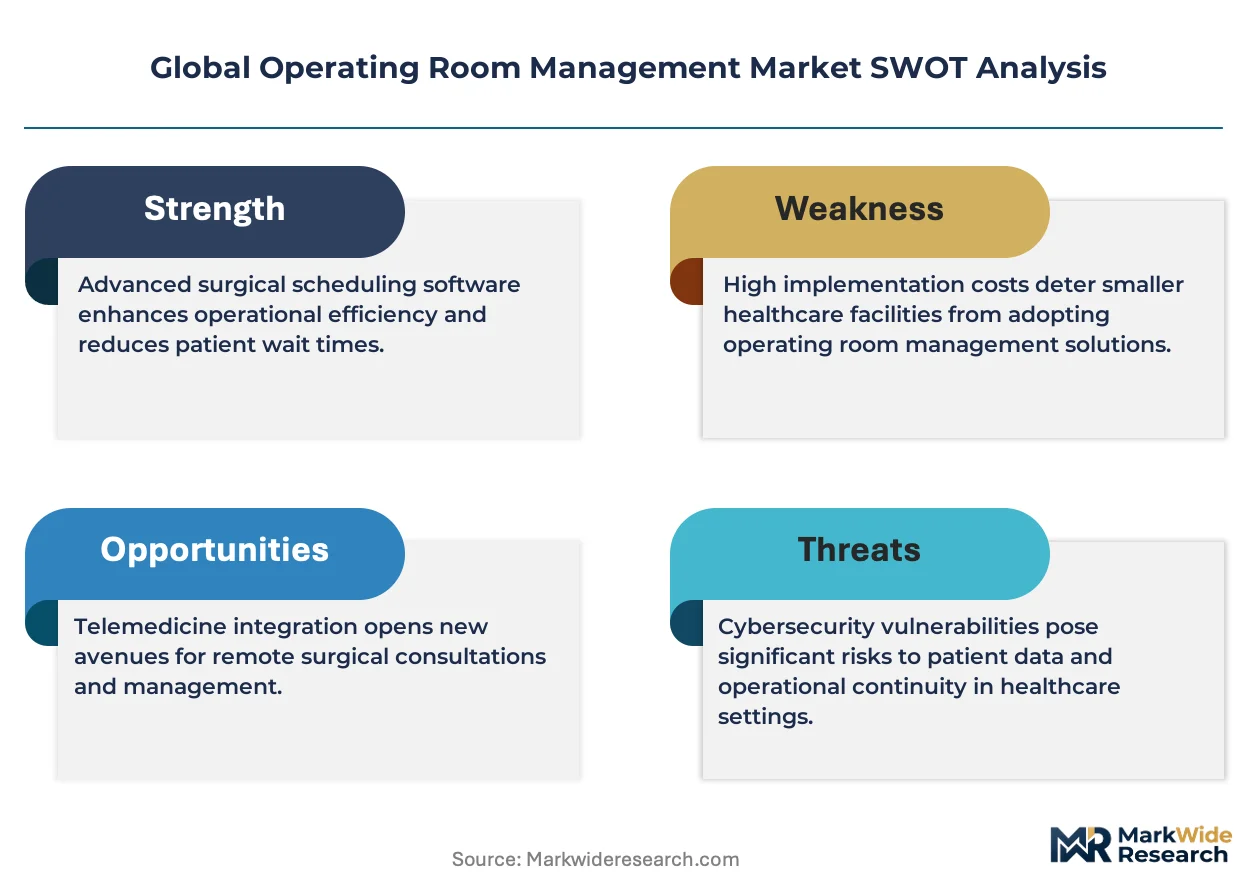
The EU Medical Device Regulation is realigning the cost-of-entry calculus for software vendors seeking European hospital contracts. Epic Systems Corporation leverages deep EHR integration to anchor its perioperative suite in large academic medical centers. Cerner, now under Oracle, competes through cloud-native architecture that extends across scheduling, inventory, and analytics modules. GE HealthCare differentiates by combining surgical asset tracking with real-time location systems in hybrid operating rooms.
Operating room management encompasses software and hardware systems that coordinate surgical scheduling, staff allocation, equipment tracking, and postoperative documentation to maximize throughput and patient safety. Cloud computing deployments now dominate new installations, offering elastic capacity for peak surgical volumes while reducing on-premise infrastructure burdens. AI integration represents the fastest-expanding technology segment, with machine learning models predicting case duration and optimizing block scheduling for hospitals. Scheduling software remains the most mature product category, though margin pools increasingly shift toward analytics platforms that aggregate utilization data across multiple surgical sites.
FDA software-as-a-medical-device guidance, EU MDR conformity requirements, and HIPAA security frameworks collectively shape product roadmaps and market access conditions for vendors. The EU AI Act introduces additional risk classification layers for automated scheduling algorithms that influence patient prioritization. Stakeholders must monitor how regulatory divergence between Washington and Brussels affects interoperability standards and deployment timelines for cross-border health system rollouts.
Market Dynamics
Cloud-native perioperative platforms are compressing deployment timelines while forcing incumbents to abandon legacy on-premise architectures. The EU Medical Device Regulation and FDA software-as-a-medical-device guidance are creating divergent compliance pathways that reshape vendor R&D allocation.
Growth Catalysts
- AI-driven predictive scheduling:Machine learning models that forecast case duration are reducing block underutilization in high-volume surgical centers. Academic medical centers in the United States are deploying these tools fastest.
- EU MDR conformity pathways:Streamlined software validation frameworks for clinical decision support tools are accelerating vendor market access across German university hospitals.
- Hybrid operating room construction:Real-time location systems integrated with surgical asset tracking are becoming mandatory infrastructure in new hospital builds across Japan.
Market Restraints
- HIPAA security compliance costs:Encryption and audit requirements for cloud-based patient data are elevating total cost of ownership for US hospital deployments.
- Legacy system integration friction:Proprietary data formats from incumbent EHR vendors create technical lock-in that slows multi-site standardization.
- Anesthesia workforce shortages:Staffing gaps in perioperative nursing and anesthesiology are capping throughput gains from scheduling optimization software.
Strategic Opportunities
- Ambulatory surgery center penetration:Freestanding ASCs in India represent an underpenetrated channel for cloud scheduling platforms as surgical volume migrates from inpatient settings.
- EU AI Act risk classification:Automated patient prioritization algorithms face new transparency requirements that create first-mover advantage for vendors with explainable AI architectures.
- Blockchain-integrated supply tracking:Convergence of distributed ledger technology with surgical inventory management is opening new margin pools in implant traceability.
Industry Challenges
- Interoperability standard fragmentation:HL7 FHIR implementation varies across health systems, forcing vendors to maintain multiple integration codebases.
- Cybersecurity certification timelines:ISO 27001 and SOC 2 Type II attestations for cloud platforms are extending sales cycles by six to twelve months in risk-averse hospital procurement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Operating Room Management Market |
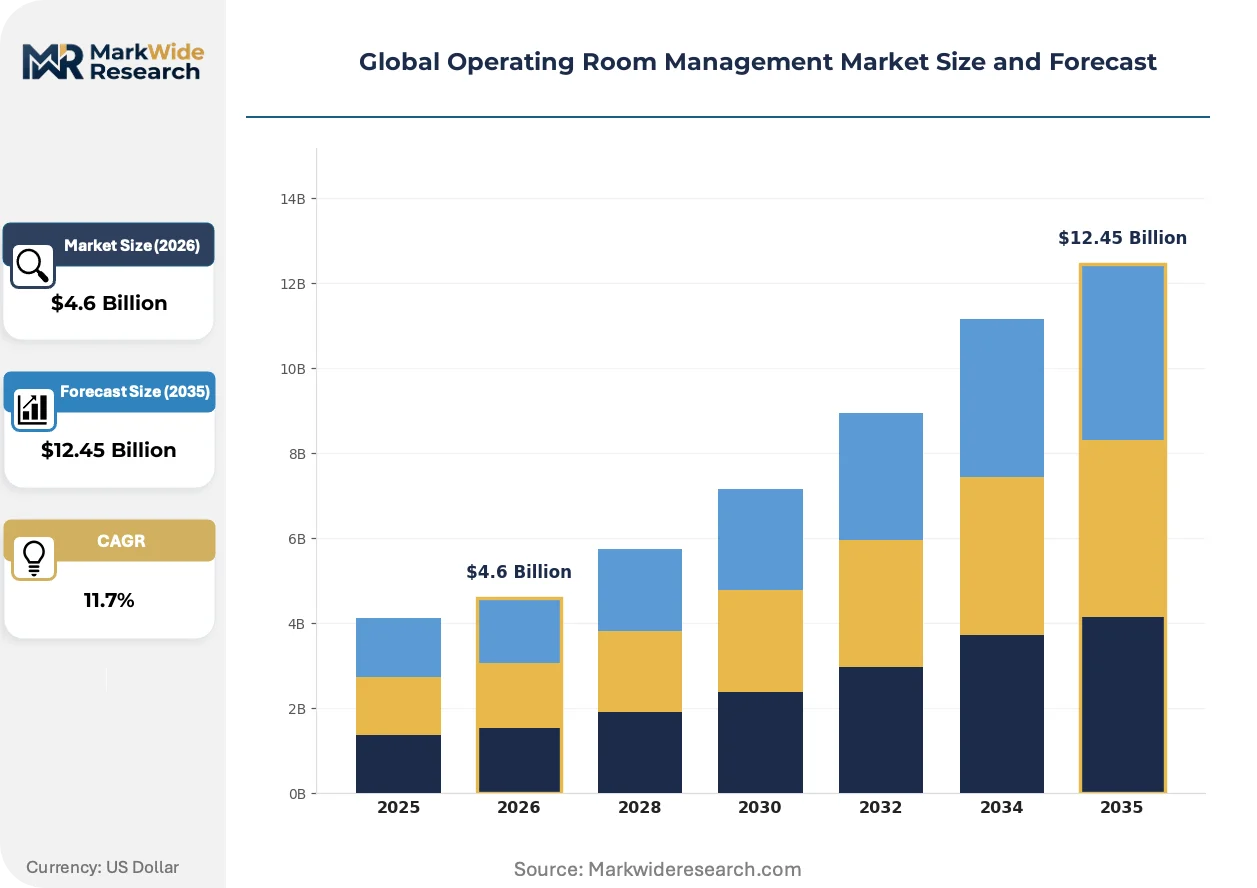
| Market Size in 2026 | $4.6 Billion |
| Market Size in 2035 | $12.45 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
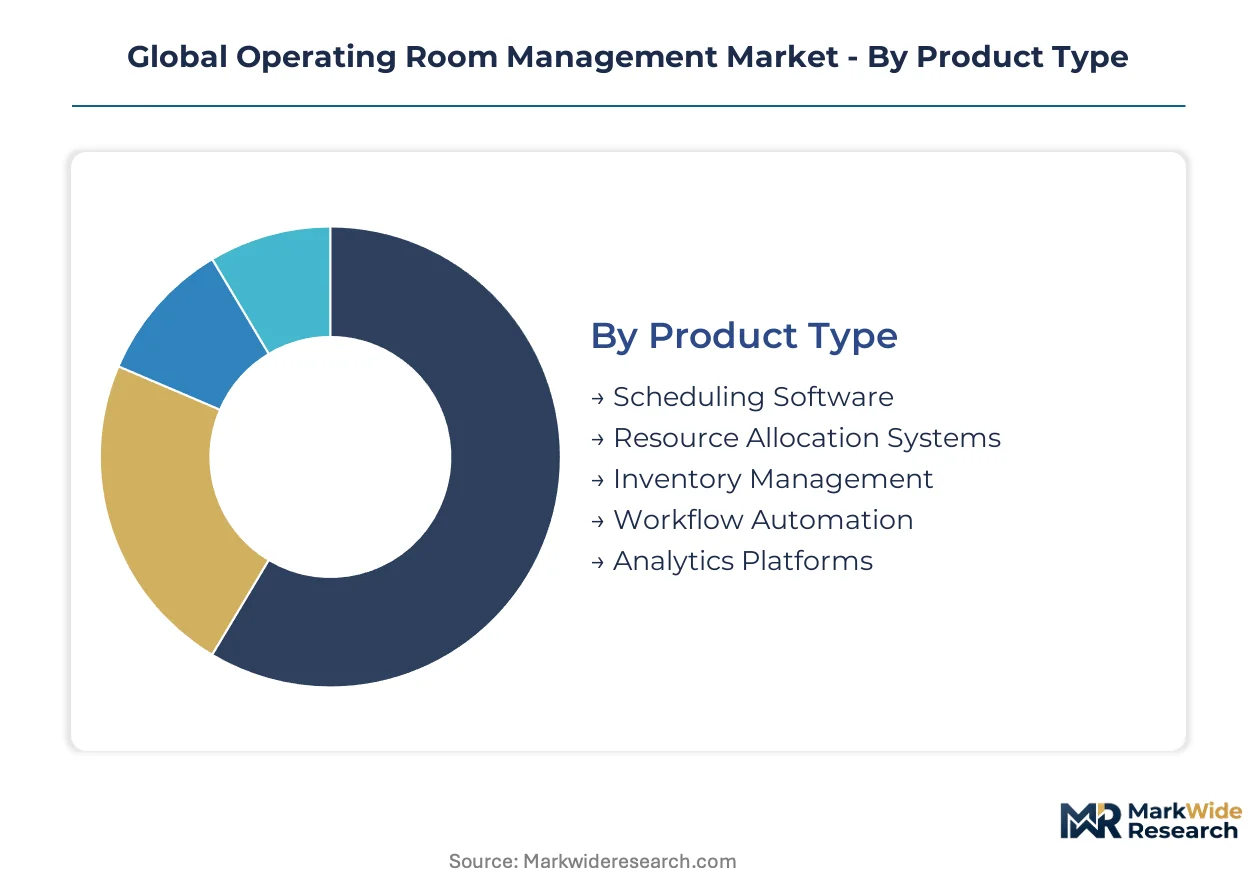
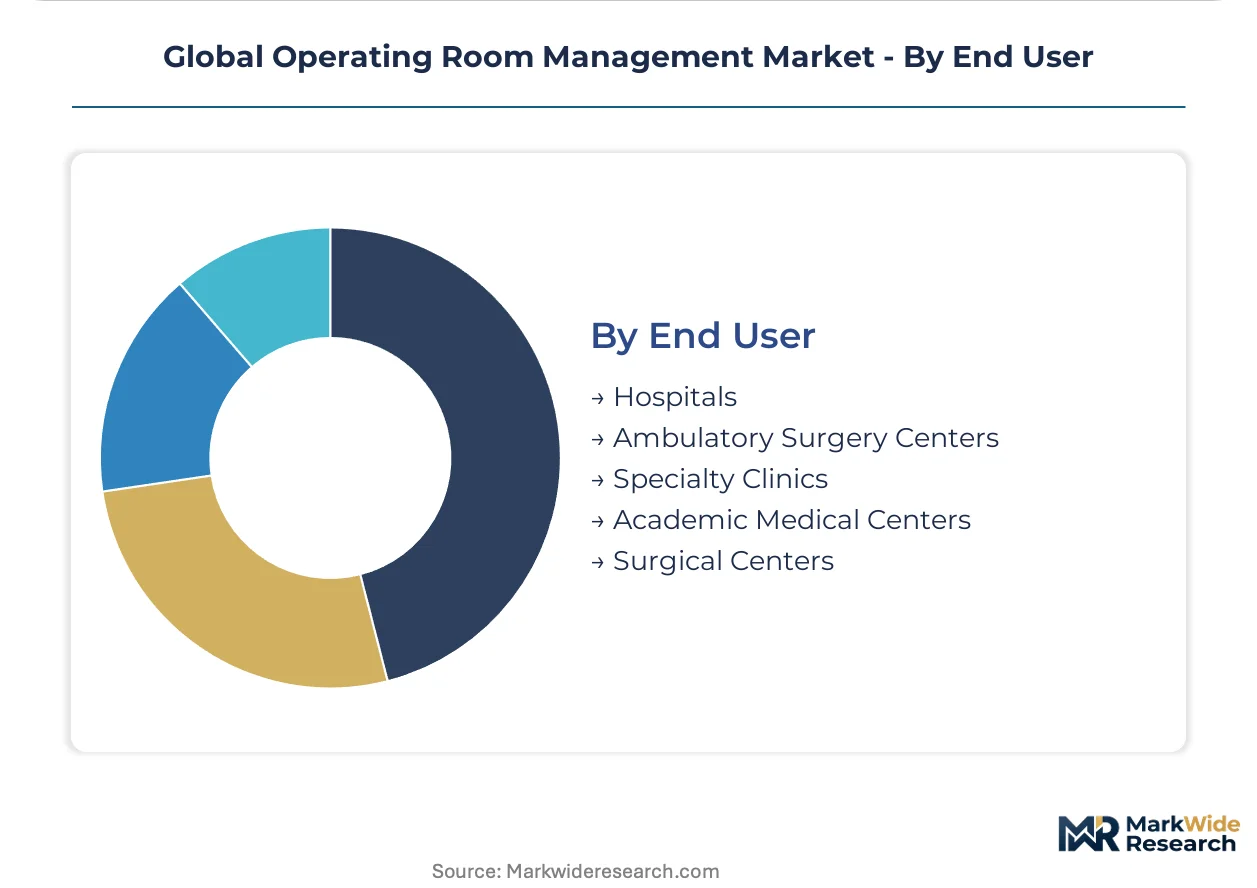
| Segmentation | Product Type: Scheduling Software, Resource Allocation Systems, Inventory Management, Workflow Automation, Analytics Platforms Technology: Cloud Computing, On-Premise Solutions, AI Integration, Mobile Access, IoT Connectivity Application: Preoperative Planning, Intraoperative Coordination, Postoperative Assessment, Staff Management, Compliance Tracking End User: Hospitals, Ambulatory Surgery Centers, Specialty Clinics, Academic Medical Centers, Surgical Centers |
| Companies Covered | Oracle (Cerner Corporation), Epic Systems Corporation, Medical Information Technology (Meditech), GE HealthCare, Surgical Information Systems, Getinge AB, Picis Clinical Solutions, Veradigm, Steris Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Operating Room Management Market Shifts & Advancements
Perioperative software is pivoting from reactive scheduling tools toward predictive systems that anticipate surgical delays before they cascade. Edge computing architectures and ambient intelligence sensors are enabling this shift while compressing the latency between data capture and decision support.
Edge-deployed inference engines are decentralizing AI workloads from centralized cloud servers to on-premise surgical clusters. Large academic medical centers in Germany are piloting these architectures to maintain sub-100-millisecond response times for intraoperative decision alerts. This topology is decentralizing vendor business models away from pure SaaS subscriptions toward hybrid licensing that captures hardware margin.
The EU AI Act's risk-based classification system is forcing algorithmic transparency for patient prioritization tools. Vendors must now document training data provenance and model drift monitoring protocols to maintain CE marking. High-risk automated scheduling systems face the strictest conformity assessment pathways, with German notified bodies establishing the precedent review standards.
Hospital procurement teams are unbundling after-sales implementation services from software licenses. Large US health systems now separately contract specialized perioperative workflow consultants rather than accepting vendor professional services bundles. This pattern is most visible in multi-hospital networks consolidating anesthesia coverage across formerly independent surgical sites.
Global Operating Room Management Market Segmentation
Perioperative software vendors structure product portfolios around distinct operational workflows, technology maturity levels, and facility scale requirements. Segmentation clarity enables procurement teams to match deployment complexity against infrastructure readiness and regulatory exposure.
Product Type:
Supply concentration among scheduling platforms has consolidated vendor R&D budgets toward predictive modules, leaving adjacent categories dependent on partnership strategies.
- Scheduling Software:Core modules coordinate block time allocation, staff rotations, and equipment reservations through rule-based engines. Demand concentrates in United States academic medical centers seeking AI-augmented case duration forecasting to reduce turnover delays.
- Resource Allocation Systems:These platforms optimize nursing assignments, anesthesia coverage, and room turnover sequences in real time. German university hospitals deploy these most aggressively under EU MDR conformity pressure to document perioperative staffing decisions.
- Inventory Management:Surgical supply tracking with barcode and RFID integration.
- Workflow Automation:Robotic process automation for documentation and billing handoffs.
- Analytics Platforms:Utilization dashboards aggregating multi-site surgical performance.
Today's leader: Scheduling Software. Tomorrow's challenger: Analytics Platforms.
Technology:
Cost tier stratification separates enterprise cloud deployments from budget-constrained on-premise installations in emerging markets.
- Cloud Computing:Elastic infrastructure scales with seasonal surgical volume fluctuations while offloading HIPAA security compliance to vendor SOC 2 attestations. United States health systems with distributed surgical networks favor this architecture for centralized governance.
- AI Integration:Machine learning models for case duration prediction and block optimization. Academic medical centers in Germany pilot these under EU AI Act risk classification requirements for algorithmic transparency.
- On-Premise Solutions:Legacy architectures retained by risk-averse institutions with captive IT security teams.
- Mobile Access:Tablet and smartphone interfaces for circulating nurses and surgeons.
- IoT Connectivity:Sensor networks linking surgical equipment to location systems.
Cloud Computing captures current procurement volume. AI Integration is climbing the fastest as regulatory frameworks mature.
Application:
Volume concentration in intraoperative coordination reflects vendor investment in real-time decision support during active procedures.
- Intraoperative Coordination:Real-time dashboards track procedure progress, equipment status, and staff availability to prevent cascade delays. Japanese hospital construction mandates integrate these with real-time location systems in hybrid operating rooms.
- Preoperative Planning:Patient risk stratification, consent documentation, and surgical checklist completion. Demand clusters in United States ambulatory surgery centers facing CMS quality reporting requirements.
- Postoperative Assessment:Recovery tracking and handoff documentation to post-anesthesia care units.
- Staff Management:Credentialing, scheduling, and competency tracking for perioperative personnel.
- Compliance Tracking:Automated audit trails for regulatory inspection readiness.
Intraoperative Coordination dominates current deployments. Preoperative Planning shows steepest expansion trajectory as same-day surgery protocols spread.
End User:
Customer type differentiation separates enterprise health systems with dedicated perioperative informatics teams from lean ambulatory operators seeking turnkey solutions.
- Hospitals:Integrated delivery networks with multiple surgical suites require modular platforms spanning scheduling, inventory, and analytics. United States systems with 500+ beds drive the majority of new cloud-native deployments.
- Ambulatory Surgery Centers:Freestanding facilities performing outpatient procedures demand lightweight, rapidly deployable scheduling tools. Indian ASCs represent an underpenetrated channel as surgical volume migrates from inpatient settings.
- Specialty Clinics:Ophthalmology, orthopedics, and gastroenterology focused practices.
- Academic Medical Centers:Teaching hospitals with research mandates and complex case mixes.
- Surgical Centers:Hospital-owned or joint-venture outpatient facilities.
Hospitals anchor present revenue. Ambulatory Surgery Centers are gaining share fastest as site-of-care shifts accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Operating room management systems trace their commercial origins to United States academic medical centers during the 1990s EHR expansion, with subsequent technology transfer establishing beachheads in Germany and Japan through the 2000s.
United States
Academic medical centers with 500+ beds drive cloud-native perioperative platform procurement, seeking AI-augmented case duration forecasting to reduce turnover delays. FDA software-as-a-medical-device guidance shapes vendor product roadmaps and compliance investments. The Greater Boston cluster anchors health system informatics innovation, with Massachusetts General and Brigham and Women's Hospital piloting edge-computing inference engines for intraoperative alerts.
Germany
University hospitals modernize perioperative infrastructure fastest among European markets, deploying resource allocation systems under EU MDR conformity pressure to document staffing decisions. The EU AI Act introduces risk classification layers for automated patient prioritization algorithms. The Munich-Berlin corridor concentrates vendor pilot programs, with Charité Berlin establishing precedent review standards for high-risk scheduling system CE marking.
Japan
Hybrid operating room construction mandates integrate real-time location systems with surgical asset tracking as mandatory infrastructure in new hospital builds. METI industrial standards guide IoT connectivity specifications for perioperative sensor networks. The Tokyo-Osaka axis dominates deployment, with National Cancer Center Hospital and Osaka University Hospital serving as reference sites for edge-computing architectures.
India
Freestanding ambulatory surgery centers represent an underpenetrated channel as surgical volume migrates from inpatient settings, creating demand for lightweight cloud scheduling platforms. CDSCO medical device regulations govern software validation requirements for imported perioperative systems. The Mumbai-Pune corridor concentrates private hospital chain expansion, with Apollo Hospitals and Max Healthcare driving multi-site standardization initiatives.
United Kingdom
NHS England procurement frameworks consolidate demand for modular perioperative platforms spanning scheduling, inventory, and analytics across integrated care systems. MHRA conformity assessment aligns with EU MDR technical standards post-Brexit transition. The London-Southeast cluster anchors deployment, with Guy's and St Thomas' NHS Foundation Trust and Imperial College Healthcare piloting predictive scheduling modules.
Global Operating Room Management Market Competitive Landscape
The competitive structure tilts toward EHR-anchored incumbents with deep hospital workflow integration. Three archetypes dominate: electronic health record platform extenders, standalone perioperative specialists, and diversified medical technology conglomerates with surgical asset tracking capabilities. Consolidation pressure intensifies as cloud-native entrants force legacy architecture abandonment, while strategic partnerships between scheduling vendors and real-time location system providers reshape alliance networks.
Within the EHR-platform tier, Epic Systems Corporation and Oracle (Cerner Corporation) exemplify divergent technical architectures—deep integration versus cloud-native modularity. GE HealthCare occupies a position bridging medical device and software domains. Among standalone specialists, Surgical Information Systems and Picis Clinical Solutions represent pure-play perioperative workflow vendors competing through vertical depth rather than horizontal platform breadth.
| Leading Market Players |
|---|
| Oracle (Cerner Corporation) |
| Epic Systems Corporation |
| Medical Information Technology (Meditech) |
| GE HealthCare |
| Surgical Information Systems |
| Getinge AB |
| Picis Clinical Solutions |
| Veradigm |
| Steris Corporation |
| Others |
Supply & Pricing Matrix
Perioperative software engineering talent concentration in the Greater Boston corridor and Bangalore tech hubs creates labor-cost differentials that widen pricing-tier spreads between premium AI-augmented suites and economy cloud scheduling tools. HIPAA compliance infrastructure and EU MDR conformity investments anchor the premium tier, while lightweight ASC deployments in emerging markets compress margins at the entry level.
Pricing Analysis
Subscription-based SaaS licensing with modular tiering anchors vendor revenue models across deployment scales. Price differentiation rests on AI integration depth and FDA SaMD validation tier, with academic medical centers absorbing premium positioning for predictive scheduling modules. Cost compression in the mid-market tier is intensifying because cloud-native entrants force legacy architecture abandonment. Ambulatory surgery centers in India exhibit highest price sensitivity, while United States integrated delivery networks with 500+ beds demonstrate lowest elasticity for enterprise bundles.
Supply Chain Analysis
India's PLI scheme for electronics manufacturing and local-content mandates in Saudi Arabia's Vision 2030 healthcare infrastructure are reshaping sourcing patterns for edge-computing hardware components. Software development concentrates in the United States, Germany, and India, with cloud infrastructure provision anchored in hyperscaler data centers across these jurisdictions. Raw material dependencies span semiconductor chips for IoT sensors, rare earth elements for surgical equipment magnets, and lithium-ion cells for mobile device fleets. Single-source vulnerability in Taiwan-based chip fabrication poses structural risk. Distribution runs through direct enterprise sales teams for hospital systems and channel partners for ASC penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Operating Room Management Market functions as a geographic-arbitrage play where EU AI Act compliance costs in Germany create margin headroom for vendors with pre-validated explainable AI architectures versus late entrants facing extended CE marking timelines.
For Market Incumbents: Hedge cloud-native displacement risk by accelerating backward integration into edge-computing hardware partnerships that capture hybrid licensing revenue. Fortify position against standalone perioperative specialists through deeper EHR workflow embedding and preemptive EU MDR conformity investments that extend procurement lock-in. For New Entrants and Emerging Players: The premium-to-economy pricing gap in AI-augmented scheduling modules creates entry space for mid-tier challengers with transparent algorithmic architectures. White-space targets include Indian ASCs migrating from inpatient settings and German university hospitals modernizing under EU MDR pressure. A channel partnership with real-time location system providers accelerates hybrid OR penetration without captive hardware development. For Investors and Strategic Acquirers: EHR platform extenders are the most active acquirer in this space, consolidating standalone perioperative specialists to deepen workflow integration. Long-term viability centers on vendors with dual FDA-EU regulatory pathways and explainable AI architectures that satisfy emerging transparency mandates. The signal to watch is EU notified body precedent review standards for high-risk scheduling system CE marking, which will clarify competitive moat durability.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Conformity Pathway | Charité Berlin precedent reviews establish CE marking standards for algorithmic transparency in patient prioritization tools. |
| Hospital System Partnership | Massachusetts General pilot programs validate edge-computing inference engines for intraoperative alert sub-100-millisecond response. |
| Software Companion Development | FDA SaMD guidance compliance for predictive scheduling modules opens United States academic medical center procurement channels. |
| Platform Integration | Epic Systems deep EHR embedding creates technical lock-in that slows multi-site standardization for cloud-native challengers. |
| Geographic Expansion | Apollo Hospitals multi-site initiatives in the Mumbai-Pune corridor drive Indian ASC cloud scheduling platform adoption. |
Research Methodology
Bottom-up hospital and ambulatory surgery center deployment modeling reconciled against top-down vendor revenue and cloud infrastructure capacity tracking forms the analytical core. Primary interviews with perioperative informatics officers, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers combined with secondary validation from FDA 510(k) filings, EU MDR notified body documentation, CMS Medicare cost report data, and hospital procurement database aggregations. Triangulation across these sources ensures segmentation integrity.
Input-output matrices map surgical volume forecasts through technology adoption curves, regulatory compliance cost structures, and workforce availability constraints across the projection horizon. Segmentation dimensions span product type, deployment architecture, application workflow, and facility scale. CAGRs derive from weighted scenario analysis incorporating AI integration penetration rates and EU AI Act implementation timelines. Industry-specific forecast inputs include anesthesia workforce shortage projections and hybrid OR construction mandates.
Caveats apply where EU AI Act risk classification enforcement intensity or FDA SaMD guidance interpretation shifts could materially shift the outlook. Forecasts reflect assumptions about cloud migration velocity and interoperability standard convergence that remain sensitive to health system consolidation patterns and cybersecurity incident frequency. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Blood Bank Market
Healthcare Services
Hair Transplant Services Market
Healthcare Services
Chronic Disease Management Service Market
Healthcare Services
US Concierge Medicine Market
Healthcare Services
Global Mobile Clinics Market
Healthcare Services
Global Corporate Wellness Solutions Market
Healthcare Services
Audiology Services Market
Healthcare Services
Europe Medical Affairs Outsourcing Market
Healthcare Services
India Senior Living Market
Healthcare Services
Patient Throughput and Capacity Management Market
Healthcare Services
Vaccine Transport Carrier Market
Healthcare Services
Global Umbilical Cord Blood Banking Market
Healthcare Services
Escort Bed Sharing Market
Healthcare Services
UK Ambulatory Services Market
Healthcare Services
Healthcare Transportation Services Market
Healthcare Services
Funeral Products and Services Market