
 Global Geriatric Care Services Market | 2026-2036
Global Geriatric Care Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Geriatric Care Services Market Foresight
Post-surgery patient demand is recalibrating the end-use vertical mix within geriatric care services. Home Instead leverages its franchise network to dominate community-based personal care across North American markets. Amedisys anchors its position through in-house hospice and home health capabilities that reduce hospital readmission exposure.
Geriatric care services encompass medical, personal, and social support delivered to individuals aged sixty-five and older, typically involving licensed nursing, physical therapy, medication management, and activities of daily living assistance in institutional or community-based settings. The primary purpose is to preserve functional independence, manage chronic conditions, and delay acute care utilization. Home Care commands the largest service type share due to persistent consumer preference for aging in place, while Memory Care Units within the Care Setting dimension capture disproportionate margin pools as specialized staffing ratios justify premium pricing. Assisted Living competes intensely on occupancy rates and amenity differentiation across suburban residential clusters.
The FDA oversees pharmaceutical and medical device standards affecting in-facility medication administration, while CMS reimbursement rules directly shape provider revenue stability and capital allocation for bed expansion. Japan's METI coordinates community-based integrated care systems that blend medical and long-term care under unified municipal budgets. Stakeholders must monitor how CMS star-rating methodologies and value-based purchasing thresholds redefine acceptable quality benchmarks without explicit timeline commitments.
Market Dynamics
Japan's METI-backed community care integration is forcing providers to restructure around municipal budgets rather than facility-based reimbursement, compressing traditional nursing home economics while expanding home health capacity.
Growth Catalysts
- CMS Value-Based Purchasing:Medicare reimbursement now ties 25% of skilled nursing facility payments to readmission metrics, accelerating capital flows toward home-based post-acute alternatives.
- Remote Patient Monitoring:Wearable biosensors and AI-enabled fall detection are extending clinical oversight into residential settings without licensed staff presence.
- Japan's 2025 Dementia Policy:METI mandates integrated community care systems that merge medical and long-term care budgets, creating unified procurement for home health vendors.
Market Restraints
- Direct Care Labor Scarcity:Certified nursing assistant wages in the United States lag adjacent healthcare sectors by 18-22%, constraining facility expansion regardless of capital availability.
- Medicaid Rate Compression:State-level reimbursement stagnation in Texas, Florida, and Ohio forces margin erosion that private-pay cross-subsidies cannot fully offset.
- Real Estate Cost Escalation:Memory care construction costs in suburban California and New York corridors have outpaced rent growth, freezing greenfield development.
Strategic Opportunities
- Germany's Pflegeversicherung Expansion:Long-term care insurance benefit increases in 2025 create addressable demand for international home care operators with compliance expertise.
- Hospital-at-Home Convergence:CMS waiver programs enabling acute-level care in residential settings merge skilled nursing and home health service lines.
- Vietnam's Aging Transition:Southeast Asia's fastest-aging population lacks institutional infrastructure, opening first-mover positioning for community-based care models.
Industry Challenges
- Interoperability Fragmentation:Electronic health record systems across home health, skilled nursing, and hospital platforms lack standardized data exchange, forcing manual care coordination.
- Regulatory Licensing Variability:State-level home care agency licensure requirements in the United States create operational complexity for multi-state operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Geriatric Care Services Market |
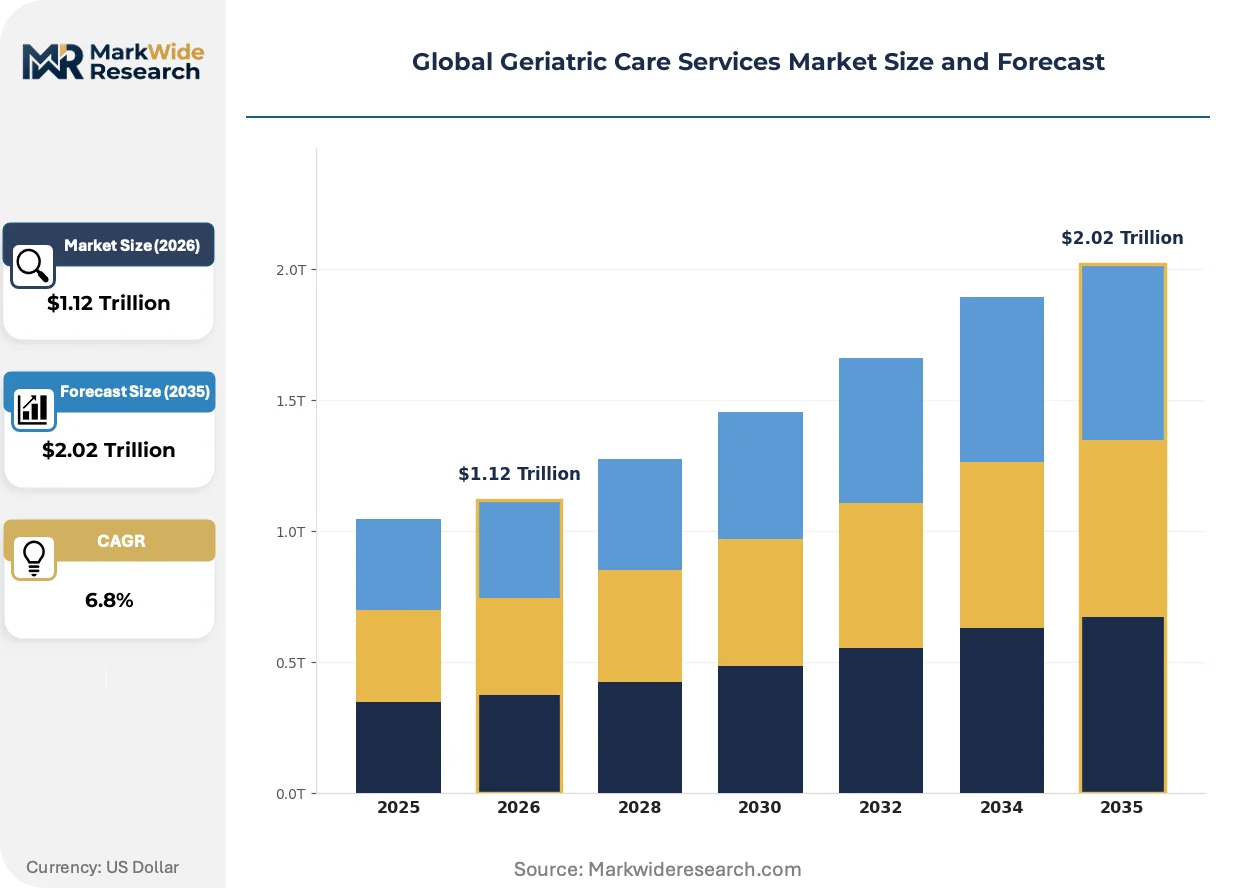
| Market Size in 2026 | $1.12 Trillion |
| Market Size in 2035 | $2.02 Trillion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Home Care, Assisted Living, Day Care, Hospice Care, Rehabilitation Services Care Setting: Nursing Homes, Community Centers, Residential Facilities, Outpatient Clinics, Memory Care Units End User: Seniors with Mobility Issues, Individuals with Cognitive Impairment, Post-Surgery Patients, Chronic Disease Patients, Socially Isolated Elders Payment Model: Private Pay, Insurance Coverage, Government Funding, Long-term Care Policies, Out-of-Pocket |
| Companies Covered | Brookdale Senior Living, Extendicare, Gentiva, Sunrise Senior Living, Genesis HealthCare, Home Instead, Amedisys, Atria Senior Living, Kindred Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Geriatric Care Services Market Shifts & Advancements
Telehealth infrastructure and predictive analytics are redrawing where clinical oversight happens, shifting investment from beds to bandwidth and algorithmic risk stratification.
Remote physiological monitoring is decentralizing geriatric care delivery by transmitting vital signs, medication adherence, and mobility data from patient residences to centralized nursing stations. Medicare Advantage plans in Arizona and Pennsylvania are deploying these systems to 40% of their high-risk enrollees within eighteen months of contract signing. The technology is decentralizing emergency department utilization by enabling early intervention before acute decompensation.
Europe's Medical Device Regulation (MDR) is tightening software-as-a-medical-device classifications for AI-driven fall prediction and medication management tools. Compliance costs for algorithm validation and post-market surveillance are diverting R&D budgets from feature development to regulatory documentation. German and Dutch home care technology vendors are responding by pursuing notified body partnerships earlier in product lifecycles.
Family caregiver procurement patterns are fragmenting as adult children coordinate services through digital platforms rather than single-provider relationships. Platform-mediated care coordination in Australia and Canada is displacing traditional agency-based engagement for non-medical personal care. This channel shift concentrates most visibly in metropolitan Toronto and Sydney, where platform penetration exceeds 30% of private-pay home care hours.
Global Geriatric Care Services Market Segmentation
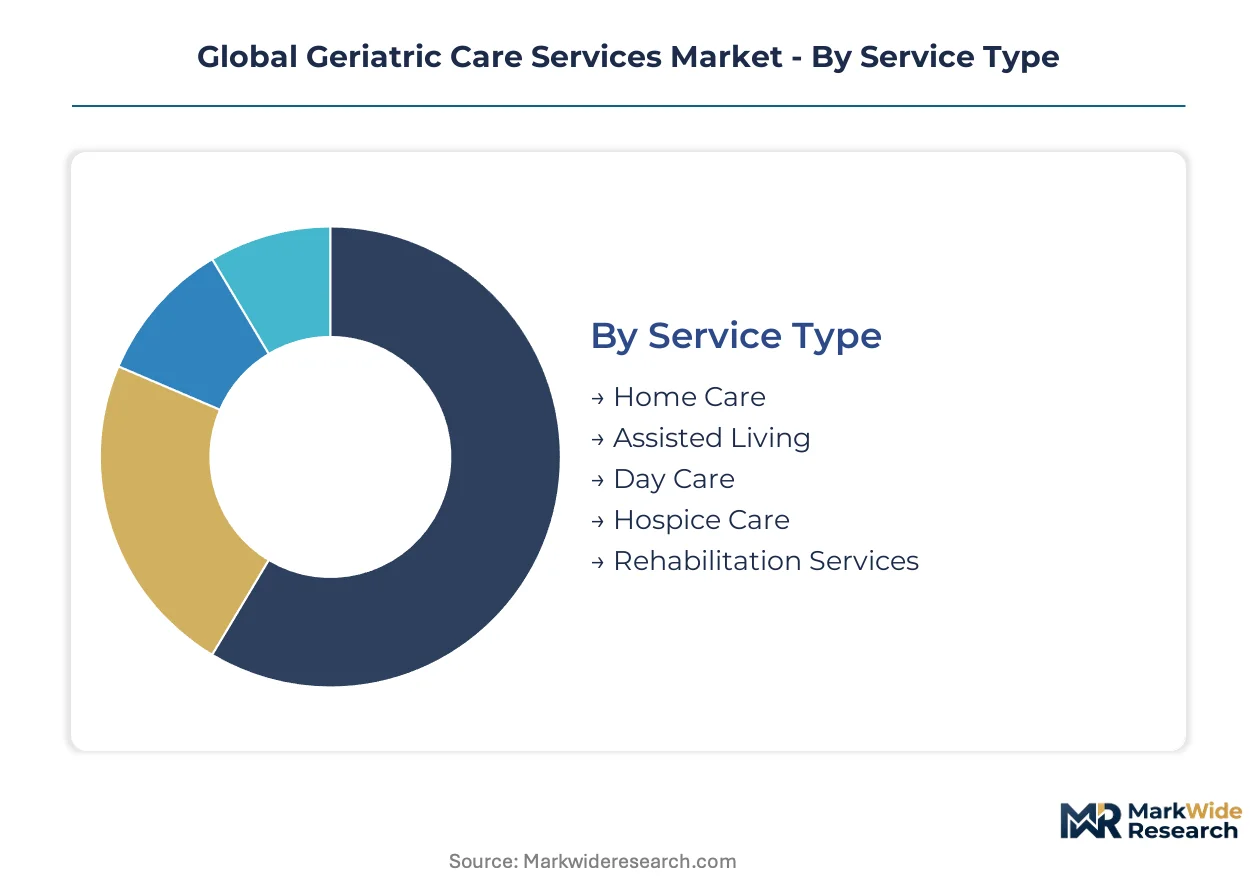
Segmentation in geriatric care services reveals how reimbursement mechanics and clinical acuity reshape provider economics. Service type and care setting dimensions expose divergent margin structures, while end-user acuity and payment models determine capital deployment priorities.
Service Type:
Volume concentration sits in home-based delivery, while premium capture clusters around specialized institutional settings with regulated staffing ratios.
- Home Care:Non-medical assistance with activities of daily living, medication reminders, and companionship delivered in patient residences. Demand concentrates among post-surgery patients in Arizona and Pennsylvania where Medicare Advantage plans deploy remote monitoring to 40% of high-risk enrollees within eighteen months.
- Assisted Living:Housing with supportive services including meals, housekeeping, and personal care for seniors needing help with daily tasks but not continuous nursing. Suburban California and New York corridors see frozen greenfield development as construction costs outpace rent growth, compressing new supply.
- Day Care:Supervised daytime programs offering social activities, meals, and limited health monitoring for seniors living with family caregivers.
- Hospice Care:End-of-life medical, emotional, and spiritual support emphasizing pain management and quality of life rather than curative treatment.
- Rehabilitation Services:Post-acute physical, occupational, and speech therapy to restore function after hospitalization or injury.
Today's leader: Home Care. Tomorrow's challenger: Hospice Care.
Care Setting:
Institutional capacity faces margin compression from municipal budget integration, while outpatient and residential alternatives capture diverted capital flows.
- Nursing Homes:24-hour skilled nursing care for medically complex seniors requiring continuous clinical oversight. Texas, Florida, and Ohio operators endure margin erosion from state-level Medicaid rate stagnation that private-pay cross-subsidies cannot fully offset.
- Memory Care Units:Secured environments with specialized staffing for dementia patients, featuring structured routines and safety protocols. Japan's METI-backed community care integration is forcing providers to restructure around municipal budgets rather than facility-based reimbursement, compressing traditional nursing home economics.
- Community Centers:Municipal or nonprofit facilities delivering social services, wellness programs, and care coordination.
- Residential Facilities:Group homes or board-and-care settings offering housing with personal care assistance.
- Outpatient Clinics:Scheduled medical visits, therapy sessions, and specialist consultations without overnight stays.
Memory Care Units command pricing power through regulatory staffing mandates. Outpatient Clinics are expanding most quickly via CMS waiver programs enabling acute-level care in residential settings.
End User:
Clinical acuity tiers separate high-touch institutional demand from technology-enabled community alternatives.
- Chronic Disease Patients:Seniors managing diabetes, heart failure, COPD, or other persistent conditions requiring ongoing monitoring and medication adjustment. Medicare reimbursement now ties 25% of skilled nursing facility payments to readmission metrics, accelerating capital flows toward home-based post-acute alternatives for this cohort.
- Individuals with Cognitive Impairment:Those with Alzheimer's disease, vascular dementia, or other conditions affecting memory, judgment, and daily function. Japan's 2025 Dementia Policy mandates integrated community care systems that merge medical and long-term care budgets, creating unified procurement for specialized vendors.
- Seniors with Mobility Issues:Those with limited physical function requiring assistance with transfers, ambulation, and fall prevention.
- Post-Surgery Patients:Individuals recovering from orthopedic, cardiac, or other procedures needing short-term rehabilitation and wound care.
- Socially Isolated Elders:Seniors lacking regular social contact who need companionship, transportation, and community engagement.
Chronic Disease Patients dominate current bed demand. Post-Surgery Patients are climbing the fastest as value-based reimbursement shifts site of care.
Payment Model:
Revenue stability separates public program dependence from private premium capture.
- Private Pay:Direct out-of-pocket payment by seniors or families without third-party reimbursement, common in assisted living and memory care.
- Government Funding:Federal and state programs including Medicare, Medicaid, and veterans' benefits covering skilled nursing and home health.
- Insurance Coverage:Medicare Advantage and commercial health plans managing capitated or fee-for-service arrangements.
- Long-term Care Policies:Private insurance products reimbursing home care, assisted living, or nursing facility costs after elimination periods.
- Out-of-Pocket:Direct consumer expenditure for non-covered services, copayments, and private-room upgrades.
Government Funding anchors volume. Private Pay secures margin.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping where geriatric care providers deploy capital, as reimbursement rate differentials and compliance cost gaps between jurisdictions accelerate cross-border service model replication.
United States
Post-surgery patient demand and Medicare Advantage expansion are redirecting investment toward home-based alternatives. CMS star-rating methodologies and value-based purchasing thresholds now tie 25% of skilled nursing facility payments to readmission metrics. The Arizona and Pennsylvania metropolitan corridors host concentrated remote patient monitoring deployments covering 40% of high-risk enrollees within eighteen months of contract activation.
Japan
Demographic aging and dementia prevalence are restructuring municipal procurement frameworks. METI mandates integrated community care systems that merge medical and long-term care budgets under unified municipal control. The Kanto region around Tokyo anchors facility restructuring as providers abandon traditional nursing home economics for home health capacity expansion.
Germany
Pflegeversicherung benefit increases in 2025 are creating addressable demand for compliant international operators. Europe's Medical Device Regulation tightens software-as-a-medical-device classifications for AI-driven care tools. The North Rhine-Westphalia cluster hosts notified body partnerships where home care technology vendors pursue earlier compliance certification.
Australia
Platform-mediated care coordination is displacing traditional agency-based engagement for non-medical personal care. The country's national aged care regulator enforces quality standards across community and residential settings. Metropolitan Sydney exceeds 30% platform penetration of private-pay home care hours, fragmenting family caregiver procurement patterns.
Vietnam
Southeast Asia's fastest-aging population lacks institutional infrastructure, opening positioning for community-based care models. The country's national health ministry coordinates pilot programs blending family caregiver support with professional service integration. The Red River Delta around Hanoi anchors first-mover facility development as international operators test scalable entry templates.
Global Geriatric Care Services Market Competitive Landscape
Franchise network expansion dominates the current landscape as operators seek capital-light geographic coverage without facility ownership burdens. The vendor base stratifies across three tiers: integrated health systems with hospital affiliations, specialized home health and hospice platforms, and community-based personal care franchise networks. Two strategic archetypes define positioning: those capturing margin through specialized staffing ratios in memory care settings, and those reducing hospital readmission exposure through post-acute home health capabilities. M&A activity concentrates on hospice and home health asset accumulation, while technology licensing partnerships extend remote monitoring infrastructure without proprietary R&D commitment.
Among North American operators, Brookdale Senior Living and Home Instead occupy distinct archetype positions. Brookdale represents the integrated facility-based model with multi-state assisted living and memory care portfolios. Home Instead exemplifies the franchise-network approach to community-based personal care, leveraging capital-light expansion across suburban residential clusters. Amedisys anchors the specialized post-acute tier, with in-house hospice and home health capabilities that align with CMS reimbursement shifts toward site-of-care migration.
| Leading Market Players |
|---|
| Brookdale Senior Living |
| Extendicare |
| Gentiva |
| Sunrise Senior Living |
| Genesis HealthCare |
| Home Instead |
| Amedisys |
| Atria Senior Living |
| Kindred Healthcare |
| Others |
Supply & Pricing Matrix
Medicare Advantage plan procurement concentration in Arizona and Pennsylvania anchors pricing power toward value-based reimbursement models. CMS star-rating methodologies tie facility payments to readmission metrics, forcing providers to absorb clinical outcome risk into contract structures.
Pricing Analysis
Direct-to-payer contracting discounts dominate the channel-margin layer as Medicare Advantage plans consolidate purchasing leverage. Three-tier pricing structure across premium, standard, and economy levels separates memory care units with specialized staffing ratios from basic assisted living and non-medical home care. Price differentiation hinges on CMS certification tier and geographic delivery cost, with suburban California and New York corridors showing pricing softness due to construction cost escalation. Private-pay assisted living residents exhibit lowest price sensitivity, while Medicaid-dependent nursing home operators face acute margin compression.
Supply Chain Analysis
Japan's METI-mandated local-content rules for community care integration are reshaping sourcing toward municipal-approved vendor networks. Labor supply concentrates in the Philippines, India, and Mexico as certified nursing assistant recruitment pools. Raw material dependencies include wearable biosensors, AI-enabled fall detection hardware, and pharmaceutical distribution infrastructure. Single-source vulnerability runs through concentrated remote monitoring technology vendors. Distribution runs through franchise networks for personal care and integrated health systems for skilled nursing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as post-surgery patient demand shifts toward premium home-based alternatives with embedded remote monitoring capabilities.
For Market Incumbents: Acquire hospice and home health assets to reduce hospital readmission exposure under CMS value-based purchasing. Defensive consolidation should prioritize Medicare Advantage contract concentration in Arizona and Pennsylvania corridors. Direct care labor scarcity threatens facility expansion regardless of capital availability. For New Entrants and Emerging Players: Platform-mediated care coordination partnerships offer lowest barrier to entry in metropolitan Sydney and Toronto where digital penetration exceeds thirty percent of private-pay hours. Vietnam's Red River Delta presents the most penetrable geography for community-based care model testing. Go-to-market positioning should emphasize family caregiver procurement fragmentation through mobile-first service orchestration. For Investors and Strategic Acquirers: Integrated health systems with hospital affiliations are the most active acquirer in this space, consolidating post-acute capabilities to capture site-of-care migration value. Five-to-ten year viability favors operators with in-house remote patient monitoring infrastructure and value-based contract portfolios. The signal to watch is CMS waiver program expansion enabling acute-level care in residential settings.| Strategic Initiative | Industry Significance |
|---|---|
| Hospice Asset Acquisition | Captures margin pools from end-of-life care specialization and reduces readmission penalty exposure under CMS metrics. |
| Remote Monitoring Platform Integration | Extends clinical oversight into residential settings without licensed staff presence, aligning with Medicare Advantage deployment patterns. |
| Municipal Procurement Partnership | Secures position within Japan's METI-backed integrated community care systems merging medical and long-term care budgets. |
| Franchise Network Expansion | Enables capital-light geographic coverage across suburban residential clusters without facility ownership burdens. |
| Reimbursement Strategy Development | Structures value-based contracts that absorb clinical outcome risk while capturing premium from reduced acute utilization. |
Research Methodology
Coverage spans North America, Asia-Pacific, and Western Europe, with primary inputs from each region combined through structured stakeholder engagement and secondary validation. Interviews incorporated geriatric care facility operators, Medicare Advantage plan executives, municipal procurement officers in Japan, and certified nursing assistant workforce specialists. Secondary sources included CMS Medicare data, METI policy documentation, hospital procurement databases, and GPO contracts. Bottom-up facility capacity modeling and top-down reimbursement flow analysis were triangulated against primary intelligence.
Granularity-level framing applied service type, care setting, end-user acuity tier, and payment model dimensions at the country-regulator cluster level. CAGRs were derived through regression analysis of historical reimbursement rate trajectories and demographic aging curves across the projection horizon. Forecast inputs incorporated Japan's 2025 Dementia Policy implementation timelines and CMS value-based purchasing threshold adjustments.
Revisions become necessary when regulatory reimbursement frameworks shift materially or when labor supply constraints accelerate beyond modeled assumptions. Forecasts reflect documented assumptions regarding municipal budget integration pace and remote monitoring technology adoption curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Western Europe Medical Recruitment Market
Healthcare Services
Nutraceutical Contract Manufacturing Services Market
Healthcare Services
Contract Manufacturing Organization (CMO) Market
Healthcare Services
US Hospice Care Market
Healthcare Services
Global Ambulatory Services Market
Healthcare Services
Healthcare CRO Services Market
Healthcare Services
In-Home Senior Care Franchises Market
Healthcare Services
Health Care Supply Chain Management Market
Healthcare Services
Hospital Workforce Management Market
Healthcare Services
Europe Pharmaceutical Logistics Market
Healthcare Services
Kids Sports Injury Treatment Market
Healthcare Services
Spa Services Market
Healthcare Services
Europe Medical Affairs Outsourcing Market
Healthcare Services
Australia and New Zealand Healthcare Logistics Market
Healthcare Services
Asia-Pacific Healthcare Staffing Market
Healthcare Services
UK Ambulatory Services Market