
 Global Hospital Services Market | 2026-2036
Global Hospital Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hospital Services Market Foresight
Specialized nursing and surgical technician labor is bifurcating the competitive landscape between academic medical centers and community hospitals. Massachusetts General Hospital leverages its research workforce to sustain complex procedure volumes. Mayo Clinic anchors its premium positioning through deep specialization in multi-organ transplant programs.
Hospital services encompass the organized delivery of acute, sub-acute, and preventive medical care through licensed inpatient and outpatient facilities, typically operating under accreditation standards such as Joint Commission International protocols for patient safety and clinical quality. These institutions generate revenue through procedure-based billing, diagnostic testing, and longitudinal care management for chronic conditions. Inpatient care dominates revenue pools due to higher reimbursement intensity, while outpatient care captures the fastest structural expansion as same-day surgery and ambulatory diagnostics displace traditional bed-based treatment. Diagnostic services concentrate margin pools through imaging and laboratory consolidation.
FDA oversight of medical device safety and EMA clinical trial standards shape service line expansion and capital equipment procurement across major hospital systems. HIPAA privacy requirements and GDPR health data rules constrain telemedicine platform architecture and cross-border patient data flows. Stakeholders must monitor how reimbursement parity laws for virtual care reshape capital allocation between physical infrastructure and digital delivery platforms.
Market Dynamics
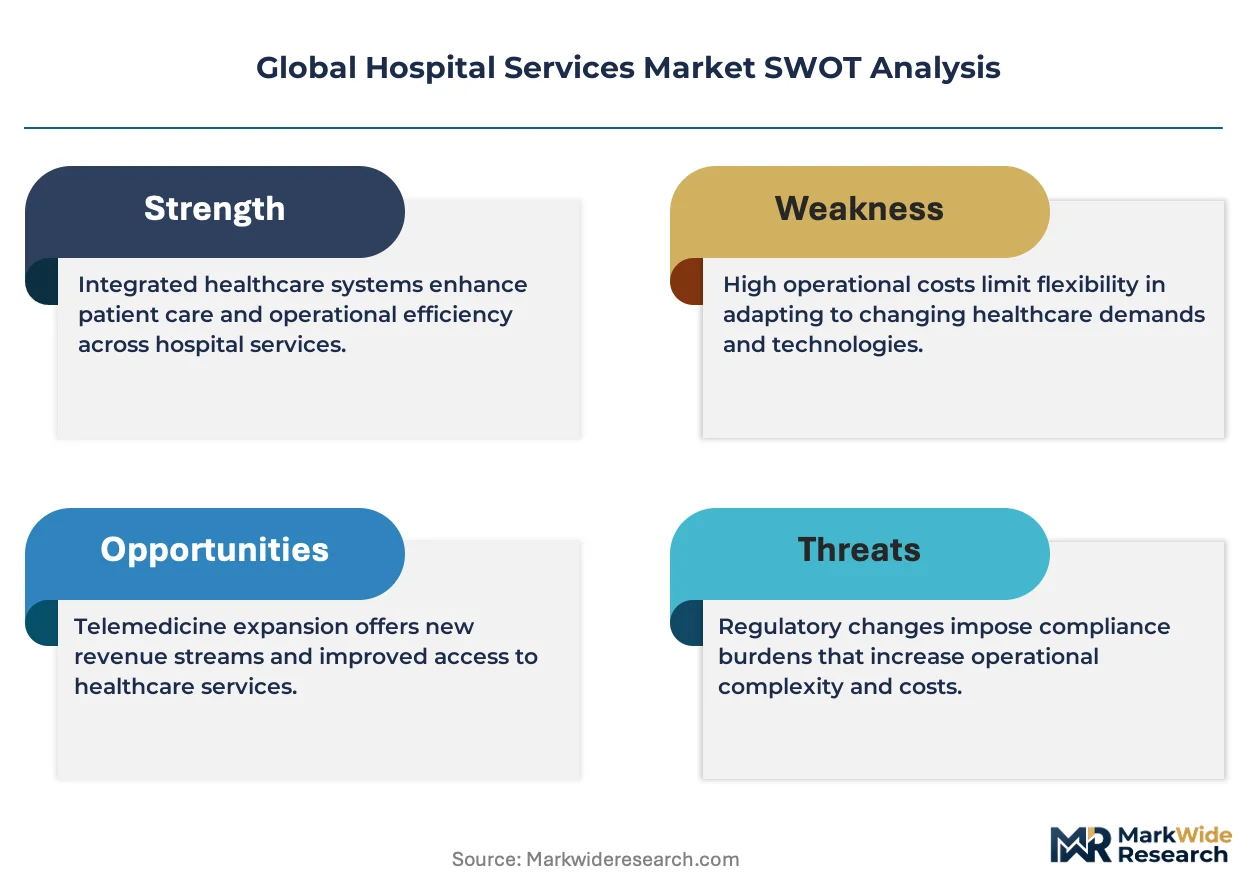
Hospital infrastructure investment is concentrating capital allocation toward digital platforms and ambulatory capacity, compressing traditional inpatient bed expansion. The FDA's digital health pre-certification pathway and EMA's medical device regulation are accelerating procurement timelines for AI-enabled diagnostic systems.
Growth Catalysts
- HIPAA-aligned telemedicine reimbursement parity:US federal and state-level mandates now compensate virtual visits at rates matching in-person encounters, expanding ambulatory service lines and same-day surgical volumes.
- Germany's Hospital Future Act infrastructure funding:Federal capital injections for IT modernization and emergency capacity are upgrading acute care networks in Bavaria and North Rhine-Westphalia.
- Remote patient monitoring sensor integration:Continuous glucose monitors and cardiac telemetry devices are extending hospital-level monitoring into home settings, reducing readmission penalties.
Market Restraints
- Specialized nursing labor scarcity:Critical care and operating room nurse vacancy rates exceed 15% in multiple OECD markets, forcing premium wage structures and contract staffing dependency.
- Medical device supply concentration:Imaging equipment and implantable device manufacturing clusters in Germany, Japan, and the United States create procurement vulnerability during trade disruptions.
- EMA MDR transition compliance burden:Extended clinical evidence requirements for Class III devices are delaying service line launches and freezing capital equipment replacement cycles.
Strategic Opportunities
- India's Ayushman Bharat insurance expansion:The national health protection scheme is creating tier-two and tier-three city demand for standardized secondary care facilities and diagnostic networks.
- AI-enabled radiology workflow convergence:Machine learning triage tools combined with cloud PACS architecture are enabling teleradiology networks to capture outsourced imaging demand from rural systems.
- China's NMPA digital therapeutics pathway:Regulatory clarity for software-as-medical-device approvals is opening reimbursement channels for chronic disease management platforms.
Industry Challenges
- EHR interoperability fragmentation:Proprietary data architectures from Cerner and Epic implementations are blocking seamless patient record exchange between competing hospital systems.
- Joint Commission International accreditation timelines:Developing-market hospitals face 18-24 month certification cycles that delay international patient revenue capture and medical tourism positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hospital Services Market |
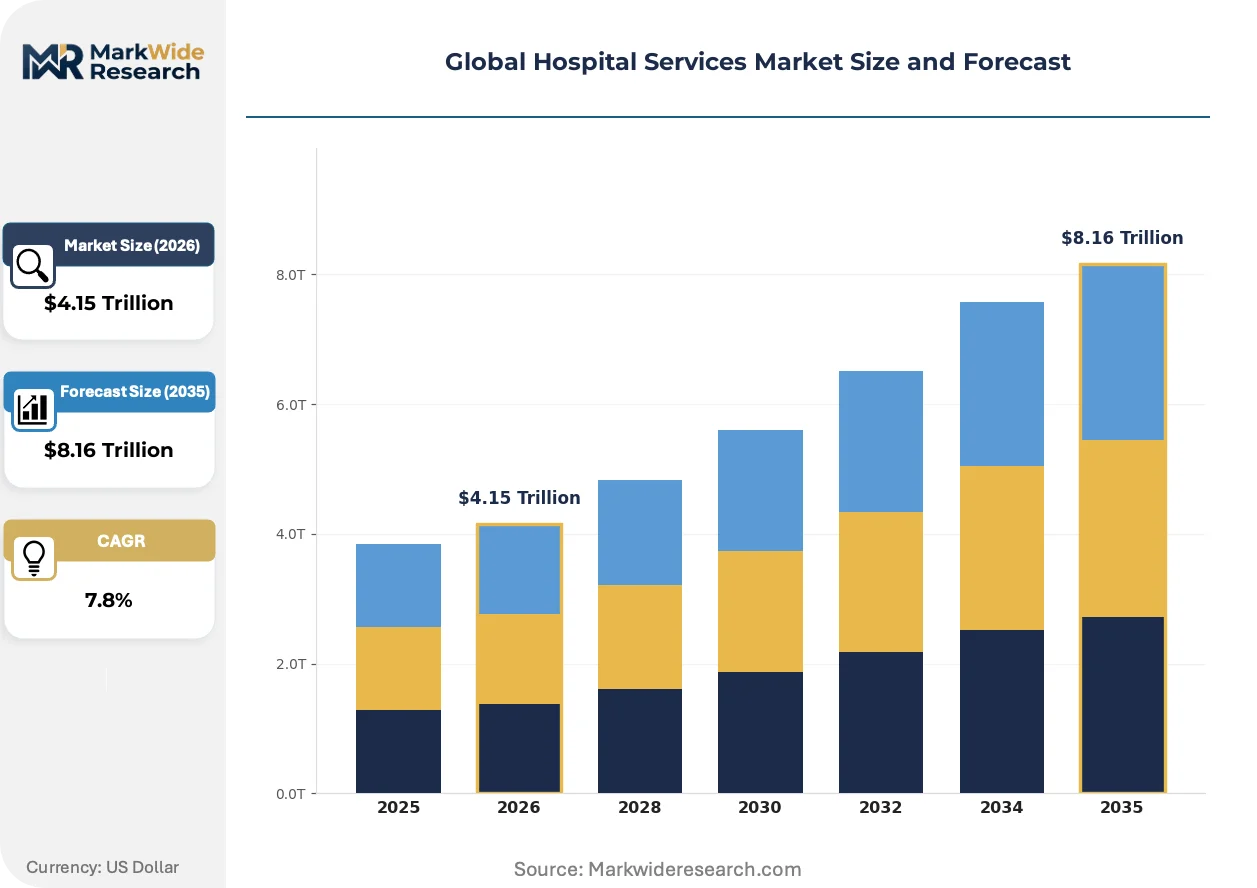
| Market Size in 2026 | $4.15 Trillion |
| Market Size in 2035 | $8.16 Trillion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Inpatient Care, Outpatient Care, Emergency Care, Surgical Services, Diagnostic Services Application: Cardiology Treatments, Oncology Procedures, Orthopedic Therapy, Neurology Services, Maternity Care End User: Public Hospitals, Private Clinics, Specialty Centers, Rehabilitation Facilities, Ambulatory Surgical Centers Technology: Electronic Health Records, Telemedicine, Robotic Surgery, Imaging Systems, Patient Monitoring |
| Companies Covered | Massachusetts General Hospital, Charité, Johns Hopkins Hospital, Houston Methodist, Cedars-Sinai Health System, Mayo Clinic, University Health Network, NewYork-Presbyterian Hospital, Cleveland Clinic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hospital Services Market Shifts & Advancements
Digital infrastructure is compressing care delivery into distributed, technology-mediated encounters that displace traditional bed-based treatment models. Regulatory frameworks are simultaneously enabling and constraining this transition.
Point-of-care ultrasound devices are miniaturizing from cart-based systems to handheld probes with smartphone connectivity. Emergency departments and rural clinics in Brazil and Indonesia are adopting these units for rapid triage. The technology is miniaturizing diagnostic capacity into ambulatory settings previously dependent on centralized radiology departments.
EMA's Medical Device Regulation (MDR) is tightening clinical evidence standards for implantable cardiovascular and orthopedic devices. Manufacturers must now submit post-market surveillance data extending across multi-year patient cohorts. High-acuity cardiac centers in France and the Netherlands are extending procurement cycles to accommodate supplier recertification timelines.
Employer-sponsored health plans are contracting directly with hospital systems for bundled surgical episodes, bypassing traditional payer intermediaries. Self-insured corporations in Texas and California are negotiating fixed-price arrangements for joint replacement and bariatric procedures. This channel compression is most visible in markets where large employer concentration creates sufficient volume leverage.
Global Hospital Services Market Segmentation
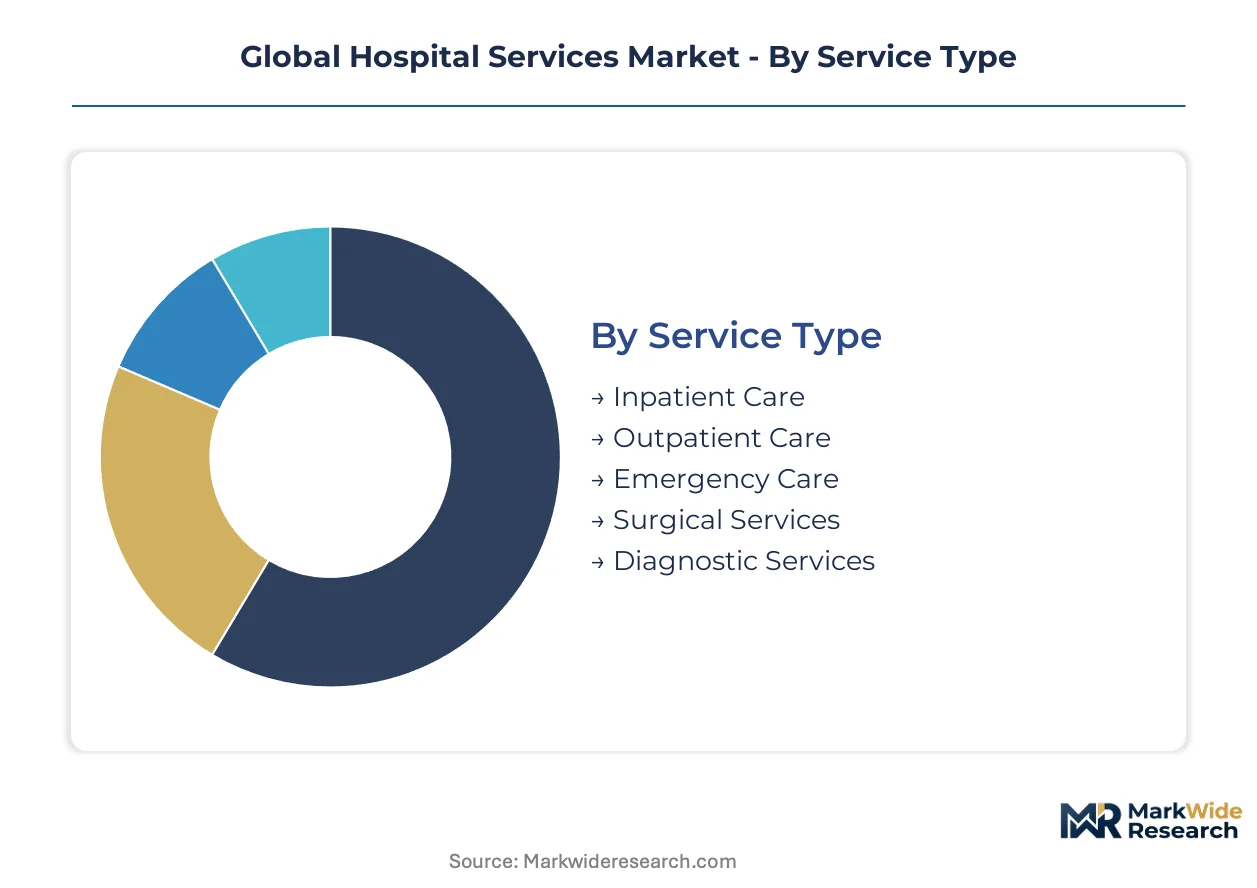
Hospital services fragment across service delivery modes, clinical applications, and technology platforms that concentrate revenue differently. Understanding these fault lines clarifies where capital deployment and margin defense priorities sit for operators and investors.
Service Type:
Margin pools concentrate in high-acuity encounters requiring extended resource commitment and specialized labor.
- Inpatient Care:Bed-based acute treatment spanning multi-day admissions for complex conditions. Massachusetts General and Mayo Clinic sustain premium positioning through high-complexity procedure volumes that command elevated reimbursement intensity from Medicare Advantage and commercial payers.
- Outpatient Care:Same-day clinical encounters including ambulatory surgery, diagnostic testing, and routine procedures. Demand is concentrating in the United States and Germany as HIPAA-aligned reimbursement parity and Germany's Hospital Future Act accelerate same-day surgical capacity expansion.
- Emergency Care:Unscheduled acute intervention for trauma and critical conditions requiring immediate stabilization.
- Surgical Services:Operating room-based invasive procedures spanning elective and emergency interventions.
- Diagnostic Services:Imaging and laboratory testing generating concentrated margin pools through equipment utilization and consolidation.
The dominant share belongs to Inpatient Care, while Outpatient Care is closing the gap fastest.
Application:
Volume distribution tracks disease burden demographics and reimbursement attractiveness across clinical specialties.
- Cardiology Treatments:Interventional and medical management of cardiovascular disease spanning catheterization labs and electrophysiology. High-acuity cardiac centers in France and the Netherlands are extending procurement cycles to accommodate EMA MDR recertification timelines for implantable devices.
- Oncology Procedures:Surgical, medical, and radiation therapy for cancer treatment requiring coordinated multidisciplinary care.
- Orthopedic Therapy:Joint replacement, spine surgery, and musculoskeletal intervention. Self-insured corporations in Texas and California are negotiating fixed-price bundled episodes directly with hospital systems, bypassing traditional payer intermediaries.
- Neurology Services:Surgical and medical management of central nervous system disorders including stroke and neurodegenerative conditions.
- Maternity Care:Obstetric and neonatal services spanning prenatal through postpartum management.
Cardiology Treatments command the deepest revenue per encounter, though Orthopedic Therapy is gaining share fastest through employer-direct contracting channels.
End User:
Customer type determines reimbursement mechanics, capital intensity requirements, and regulatory compliance scope.
- Public Hospitals:Government-funded acute care facilities serving universal coverage populations. India's Ayushman Bharat insurance expansion is creating tier-two and tier-three city demand for standardized secondary care facilities in this channel.
- Private Clinics:Investor-owned outpatient facilities emphasizing elective procedures and concierge access models.
- Specialty Centers:Focused facilities concentrating single-disease expertise such as orthopedics or ophthalmology.
- Rehabilitation Facilities:Post-acute care settings managing recovery from surgery, injury, or chronic disease decompensation.
- Ambulatory Surgical Centers:Licensed same-day surgery facilities displacing hospital-based operating rooms for appropriate procedures. Remote patient monitoring sensor integration is extending hospital-level oversight into home settings, reducing readmission penalties for this channel.
Public Hospitals absorb the highest patient volume, yet Ambulatory Surgical Centers are expanding most quickly through technology-enabled site-of-care migration.
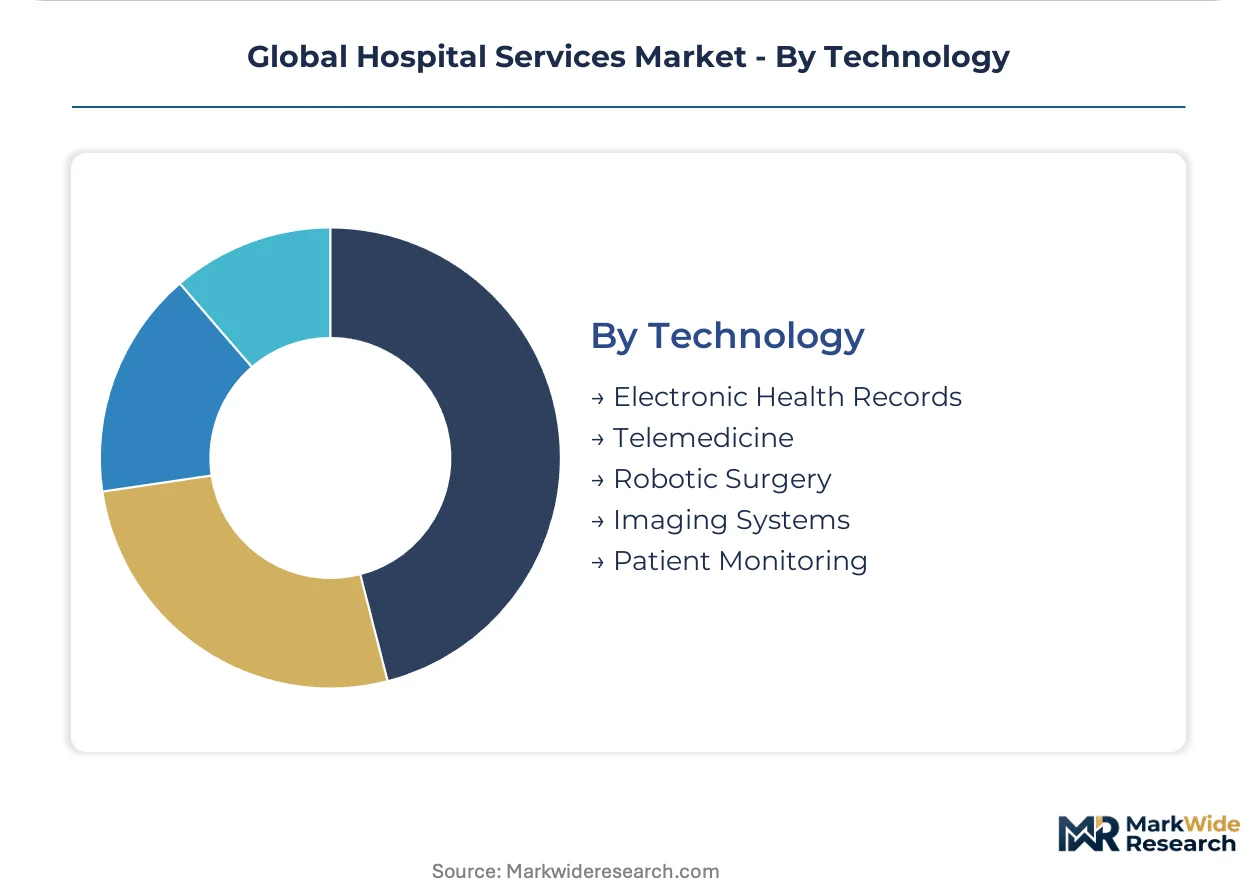
Technology:
Capital allocation and vendor selection in this category are compressing procurement timelines while extending interoperability constraints.
- Electronic Health Records:Digital patient data platforms governing clinical documentation, order entry, and billing workflows. Proprietary architectures from Cerner and Epic implementations are blocking seamless record exchange between competing hospital systems in the United States.
- Telemedicine:Virtual care delivery platforms enabling remote consultation and follow-up. US federal and state-level mandates now compensate virtual visits at rates matching in-person encounters, expanding service line reach.
- Robotic Surgery:Computer-assisted surgical systems enabling minimally invasive precision procedures.
- Imaging Systems:Radiological equipment spanning MRI, CT, and ultrasound modalities. AI-enabled radiology workflow convergence is enabling teleradiology networks to capture outsourced demand from rural systems.
- Patient Monitoring:Continuous physiological surveillance devices spanning intensive care and ambulatory settings.
Electronic Health Records represent the largest installed base, while Telemedicine is climbing the fastest on reimbursement parity tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA digital health mandates and HIPAA-aligned reimbursement parity anchor United States demand, while EMA medical device regulations and Germany's Hospital Future Act reshape European capital allocation patterns across acute care networks.
United States
Employer-direct bundled surgical contracting and Medicare Advantage penetration concentrate volume in Texas and California hospital systems. HIPAA-aligned telemedicine reimbursement parity at federal and state levels expands ambulatory service lines. The Cleveland Clinic anchors complex procedure volumes through research workforce integration in Ohio.
Germany
Federal capital injections under the Hospital Future Act upgrade IT modernization and emergency capacity in Bavaria and North Rhine-Westphalia. EMA MDR transition compliance extends procurement cycles for implantable cardiovascular devices. High-acuity cardiac centers in France and the Netherlands coordinate with German suppliers on recertification timelines.
China
NMPA digital therapeutics pathway clarity opens reimbursement channels for chronic disease management platforms in tier-two and tier-three cities. Dual carbon goals constrain hospital infrastructure energy intensity. The Yangtze River Delta concentrates AI-enabled diagnostic procurement through cloud PACS architecture deployment.
India
Ayushman Bharat national health protection scheme generates standardized secondary care demand beyond metropolitan centers. CDSCO regulatory alignment with international standards accelerates medical device import substitution. Maharashtra and Karnataka anchor diagnostic network expansion through public-private partnership models.
United Kingdom
NHS long-term plan targets shift elective procedures into ambulatory settings, compressing traditional inpatient bed allocation. GDPR health data rules constrain cross-border telemedicine platform architecture. London and Southeast England concentrate private hospital capacity for international patient revenue capture.
Global Hospital Services Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with academic medical centers commanding premium positioning through research workforce depth while community hospitals compete on access and cost efficiency. The structure bifurcates between high-complexity procedure volume aggregators and distributed ambulatory networks. Three archetypes dominate: multi-organ transplant specialists, employer-direct contracting hubs, and technology-integrated regional systems. Competitive moves concentrate on strategic clinical affiliations and same-day surgical capacity expansion.
Within the academic medical center tier, Massachusetts General Hospital and Mayo Clinic exemplify research-anchored premium positioning through complex procedure concentration. Johns Hopkins Hospital occupies a position bridging clinical innovation with international patient referral networks. These institutions represent the integrated leader archetype that capital allocation patterns increasingly favor as reimbursement intensity concentrates in high-acuity encounters.
| Leading Market Players |
|---|
| Massachusetts General Hospital |
| Charité |
| Johns Hopkins Hospital |
| Houston Methodist |
| Cedars-Sinai Health System |
| Mayo Clinic |
| University Health Network |
| NewYork-Presbyterian Hospital |
| Cleveland Clinic |
| Others |
Supply & Pricing Matrix
Bed utilization rates above 85% in academic medical centers create scale economies that compress per-procedure costs while elevating price floors for complex interventions. This capacity concentration in the United States, Germany, and China simultaneously shapes supply procurement power and reimbursement negotiation leverage across hospital networks.
Pricing Analysis
Geographic price spreads between Boston and Mumbai exceed 400% for comparable cardiac procedures, reflecting labor cost differentials and reimbursement intensity gaps. Three-tier pricing structure across academic medical centers, community hospitals, and ambulatory surgical centers stratifies access based on procedure complexity and brand premium. Pricing pressure stems from Medicare Advantage rate compression and employer-direct bundled contracting in Texas and California. Self-insured corporations demonstrate highest price sensitivity, while international medical tourism patients show lowest elasticity.
Supply Chain Analysis
Just-in-time inventory strategies dominate implantable device procurement, though pandemic disruptions have pushed cardiac centers toward strategic stockpiles of pacemakers and stents. Manufacturing concentrates in Germany, Japan, and the United States for imaging equipment and orthopedic implants. Supply chains draw from rare earth elements for MRI magnets, specialized polymers for catheters, and precision electronics for monitoring devices. Single-source vulnerability persists for contrast agents and radioisotopes. Distribution runs through group purchasing organizations and manufacturer-direct contracts with IDNs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital services increasingly attach recurring revenue through remote patient monitoring subscriptions and chronic care management platforms, with software-enabled service layers expanding faster than bed-based capacity hardware.
For Market Incumbents: Fortify complex procedure volume through research workforce depth and transplant program accreditation. Defend margin position by deepening vertical integration into ambulatory surgical center networks. Counter the threat of employer-direct contracting bypassing traditional payer channels through exclusive narrow-network arrangements with self-insured corporations. For New Entrants and Emerging Players: Differentiate on AI-enabled diagnostic workflow convergence rather than capital-intensive bed expansion. Target tier-two and tier-three cities in India through Ayushman Bharat-aligned standardized secondary care facilities. Pursue teleradiology network partnerships as the go-to-market angle for rural system outsourcing demand. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platforms with software companion development capabilities and reimbursement strategy expertise over pure hardware operators. Long-term viability hinges on digital therapeutics pathway clarity and HIPAA-aligned data architecture. Acquisition targets should demonstrate hospital system partnership density. Watch FDA digital health pre-certification adoption rates as the inflection signal for platform scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Cleveland Clinic's research integration anchors complex procedure volumes and premium reimbursement rates. |
| Software Companion Development | Remote patient monitoring platforms extend hospital-level oversight into home settings under HIPAA-aligned reimbursement. |
| Reimbursement Strategy | Medicare Advantage penetration and employer-direct contracting reshape capital allocation between inpatient and ambulatory capacity. |
| CE Marking Pathway | EMA MDR compliance timelines delay implantable device procurement and freeze service line launches. |
| AI-Enabled Workflow Integration | Cloud PACS architecture deployment enables teleradiology networks to capture outsourced imaging from rural systems. |
Research Methodology
Desk research of hospital procurement databases, CMS Medicare cost reports, and GPO contract filings preceded structured interviews with hospital purchasing committee chairs, biomedical engineering directors, and regulatory affairs specialists. Primary fieldwork with clinicians and health system strategy executives combined with secondary validation against FDA 510(k) filings, EMA MDR transition notices, and Joint Commission International accreditation records. Bottom-up service line volume estimates triangulated against top-down national health expenditure data.
Variance decomposition across service type, application, end user, and technology platform dimensions shaped the analytical framework over the projection horizon. Segmentation modeling incorporated inpatient versus outpatient migration patterns, public versus private reimbursement mechanics, and AI-enabled versus conventional technology adoption curves. CAGRs derived from procedure volume intensity, reimbursement rate trajectories, and capital equipment replacement cycles.
Material uncertainties — nursing labor scarcity escalation, EMA MDR compliance timeline extensions, and telemedicine reimbursement parity reversals — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory stability and capital market access for hospital infrastructure investment. Revision becomes warranted when critical care nurse vacancy rates cross 20% thresholds in multiple OECD markets simultaneously.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Aged Care Market
Healthcare Services
Global Pharmaceutical Contract Sales Outsourcing (CSO) Market
Healthcare Services
Blood Bank Market
Healthcare Services
Australia and New Zealand Healthcare Logistics Market
Healthcare Services
Tissue Banking Market
Healthcare Services
Canada Senior Living Market
Healthcare Services
Global Retirement Home Services Market
Healthcare Services
US Care Services Market
Healthcare Services
European Union Cross Border Healthcare Market
Healthcare Services
Medical Transcription Services Market
Healthcare Services
Healthcare Physician Staffing Market
Healthcare Services
Sterilization Services Market
Healthcare Services
South Korea Healthcare Cold Chain Logistics Market
Healthcare Services
Western Europe Medical Recruitment Market
Healthcare Services
Global Cord Blood Banking Services Market
Healthcare Services
Healthcare Third-Party Logistics Market