
 Idiopathic Intracranial Hypertension Therapeutics Market | 2026-2036
Idiopathic Intracranial Hypertension Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Idiopathic Intracranial Hypertension Therapeutics Market Foresight
Market Context
Targeted drug delivery systems are rewriting therapeutic paradigms for idiopathic intracranial hypertension, shifting care from chronic systemic medication toward precision-intervention models. Medtronic plc leverages its neurosurgical portfolio to anchor minimally invasive shunt and pressure-monitoring platforms across tertiary care networks. Sun Pharmaceutical Industries Ltd sustains cost-competitive generic carbonic anhydrase inhibitor supply, while Novartis AG differentiates through sustained-release formulation R&D and specialty neurology channel control.
Technical Definition and Segment Structure
Idiopathic intracranial hypertension therapeutics encompass pharmacologic agents and procedural interventions that reduce cerebrospinal fluid production or divert fluid to normalize intracranial pressure, with carbonic anhydrase inhibitors such as acetazolamide functioning at proximal renal tubule and choroid plexus sites to decrease CSF secretion rates by altering bicarbonate transport kinetics. The primary commercial purpose centers on preventing irreversible optic nerve damage and preserving visual function in patients with elevated pressure of unknown etiology. Carbonic anhydrase inhibitors command the largest current revenue pool due to established oral bioavailability and decades of clinical familiarity, while surgical interventions represent the fastest-expanding segment as neurointerventional techniques reduce perioperative morbidity. Delivery mode stratification shows oral formulations dominating volume, though intravenous routes capture premium pricing in acute exacerbation management within emergency care settings.
Regulatory Framework and Outlook
The FDA's orphan drug designation and breakthrough therapy pathways accelerate development timelines for novel IIH compounds, while the EMA's centralized pediatric investigation plans mandate age-appropriate formulation studies that shape European market access conditions. Health Canada and Australia's TGA align with ICH E11 guidelines for pediatric extrapolation, creating a harmonized but stringent evidentiary threshold for new entrants. Stakeholders must monitor how real-world evidence requirements evolve across FDA, EMA, and national health technology assessment bodies to anticipate reimbursement and access differentiation.
Market Dynamics
Minimally invasive neurointerventional techniques are compressing the traditional surgical pipeline for intracranial pressure management, forcing carbonic anhydrase inhibitor manufacturers to defend oral therapy positioning through real-world evidence generation while hospital systems recalibrate capital allocation toward integrated monitoring platforms.
Growth Catalysts
- FDA Breakthrough Therapy Designation:Accelerated review timelines for novel IIH compounds compress development cycles and reduce capital-at-risk for sponsors targeting orphan neurological indications.
- Academic Medical Center Consolidation:Tertiary referral networks in the United States concentrate patient volume into standardized protocol environments that favor device-integrated therapeutic approaches.
- Optic Nerve Sheath Fenestration Advancement:Microsurgical refinements reduce perioperative morbidity and expand addressable patient pools beyond pharmacologic-intolerant populations.
Market Restraints
- Acetazolamide Supply Concentration:Generic API manufacturing clusters in India create single-source vulnerability for carbonic anhydrase inhibitor availability across North American and European markets.
- Reimbursement Compression:Medicare severity-adjusted diagnosis-related group classifications undervalue complex IIH surgical interventions relative to actual resource utilization.
- Diagnostic Delay Latency:Mean time from symptom onset to definitive diagnosis exceeds 18 months in non-specialized care settings, truncating addressable treatment windows.
Strategic Opportunities
- Pediatric Formulation Gap:EMA-mandated pediatric investigation plans create first-mover advantage for sponsors developing age-appropriate acetazolamide dosing vehicles.
- Remote Intracranial Pressure Monitoring:Telemedicine-integrated implantable sensors enable home-based pressure trending that reduces emergency department utilization.
- Biomarker-Guided Titration:CSF neurofilament light chain quantification supports personalized acetazolamide dosing that optimizes therapeutic index.
Industry Challenges
- Neurointerventionalist Workforce Scarcity:Fellowship-trained specialists capable of ventriculoperitoneal shunt revision and endovascular pressure management remain concentrated in urban academic centers.
- Real-World Evidence Infrastructure:Fragmented electronic health record systems impede longitudinal outcome tracking required for FDA post-market commitments and HTA submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Idiopathic Intracranial Hypertension Therapeutics Market |
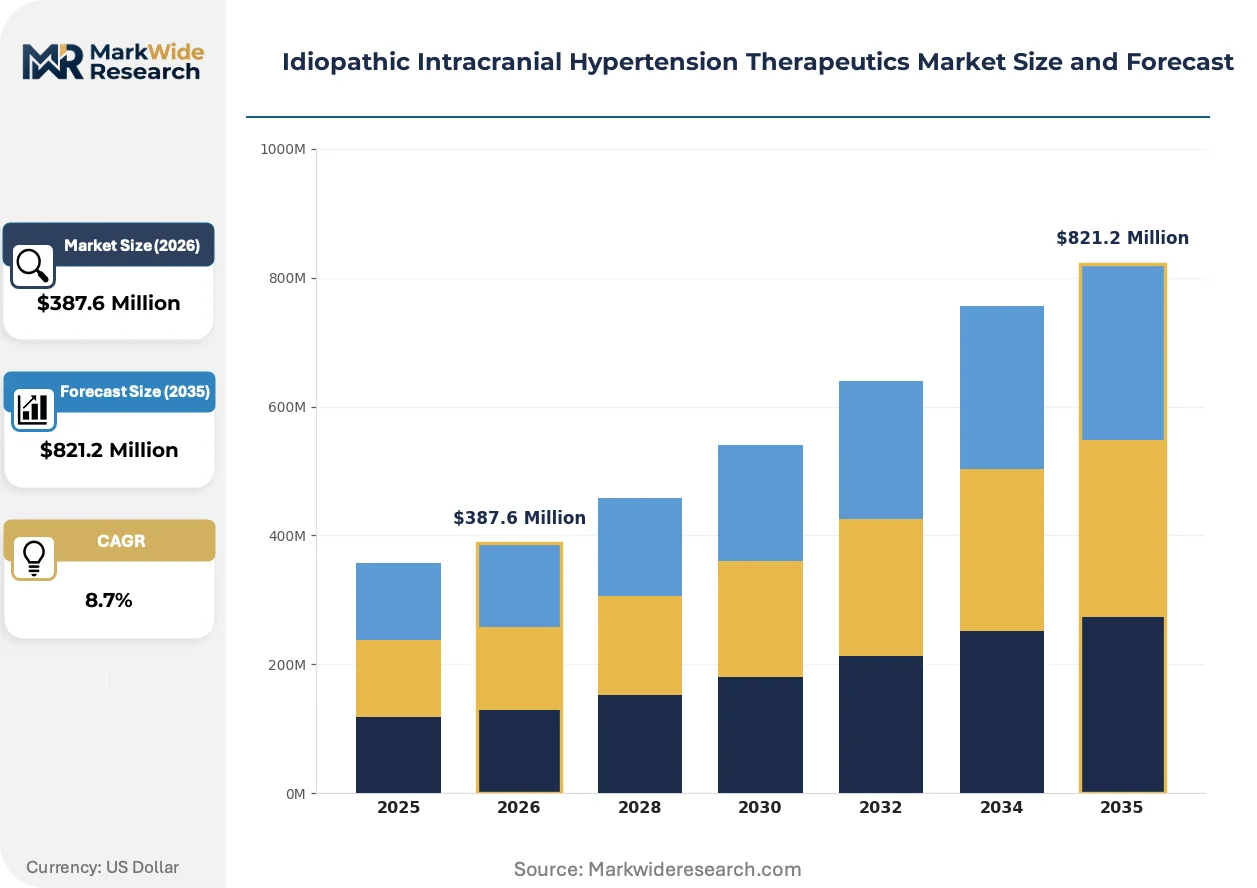
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diuretics, Corticosteroids, Carbonic Anhydrase Inhibitors, Surgical Interventions Delivery Mode: Oral, Intravenous, Intramuscular, Ophthalmic End User: Hospitals, Specialty Clinics, Homecare Settings, Research Institutions Application: Pediatric, Adult, Clinical Trials, Emergency Care |
| Companies Covered | Medtronic plc, Becton Dickinson and Company, Sanofi, Abbott Laboratories, Philips, Sun Pharmaceutical Industries Ltd, Siemens AG, Novartis AG, Teva Pharmaceutical Industries Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Idiopathic Intracranial Hypertension Therapeutics Market Shifts & Advancements
Digital health integration and precision-monitoring platforms are reconfiguring how intracranial pressure data flows through clinical decision pathways, compressing the latency between physiological change and therapeutic adjustment.
Implantable wireless pressure sensors is digitizing continuous intracranial pressure monitoring by eliminating transcutaneous catheter maintenance. Tertiary neurosurgical units in the United States and Germany are piloting these devices in refractory IIH populations. The technology is digitizing patient management workflows by enabling ambulatory pressure trending that reduces hospital readmission frequency.
EMA's Medical Device Regulation recalibration is elevating clinical evidence requirements for cerebrospinal fluid diversion shunts. Manufacturers must now submit prospective registry data demonstrating sustained pressure normalization. European notified bodies are extending review timelines for novel valve mechanisms, compressing product launch windows relative to prior regulatory epochs.
Specialized headache center procurement collectives are consolidating acetazolamide purchasing through group purchasing organizations that extract volume-based concessions. Independent neurology practices face margin compression as these networks capture preferred formulary positioning. The United States exhibits the most pronounced buyer concentration, with academic medical center alliances controlling substantial IIH patient referral volume.
Idiopathic Intracranial Hypertension Therapeutics Market Segmentation
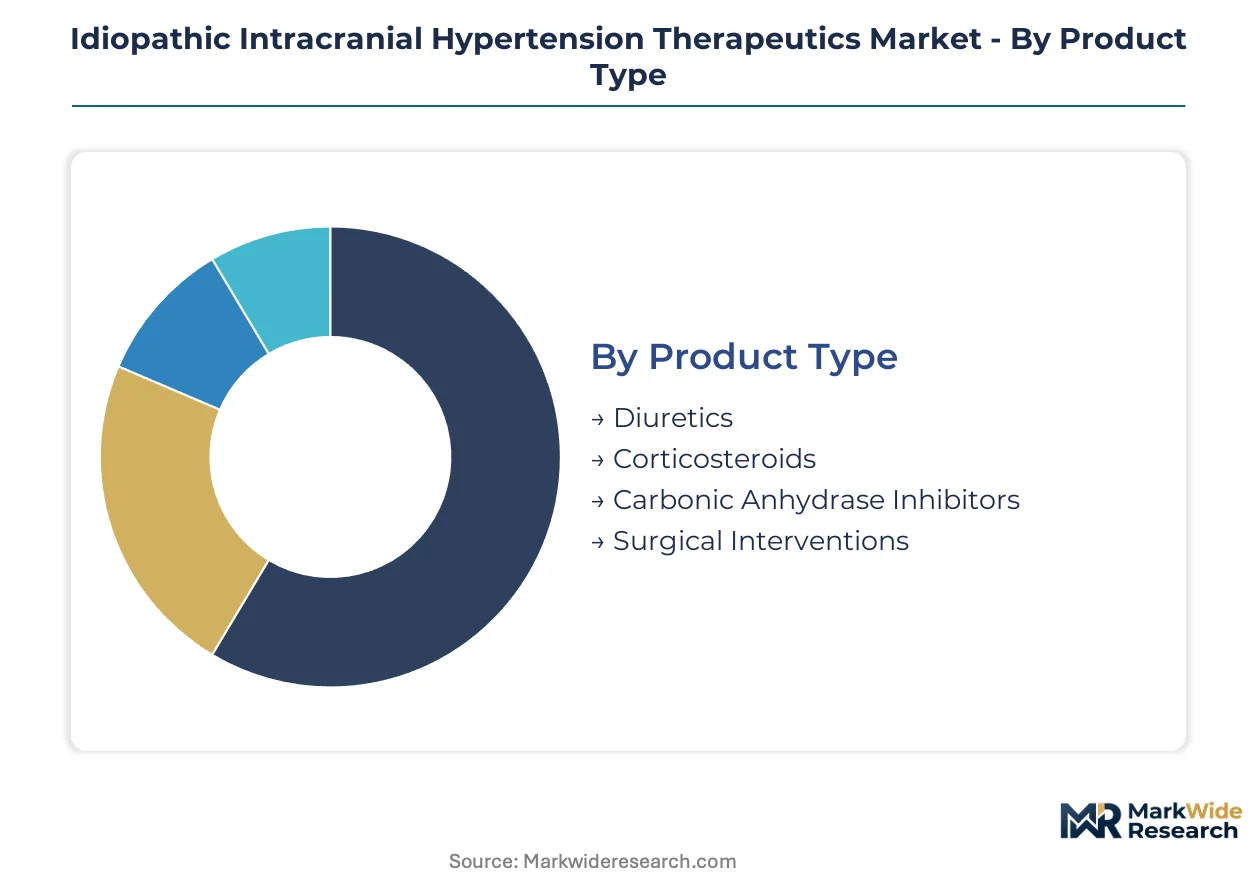
Segmentation in IIH therapeutics reveals how pressure management protocols bifurcate between pharmacologic maintenance and procedural intervention. Carbonic anhydrase inhibitors anchor outpatient management, while surgical modalities capture refractory cases. Delivery mode and end-user configuration determine reimbursement pathways and capital allocation across care settings.
Product Type:
Mature oral agents dominate prescription volume, yet emerging neurointerventional platforms are redrawing the surgical threshold for refractory patients.
- Carbonic Anhydrase Inhibitors:Acetazolamide and methazolamide function at choroid plexus and proximal renal tubule sites to suppress cerebrospinal fluid secretion through bicarbonate transport inhibition. United States headache centers prescribe these agents as first-line maintenance therapy, though generic API concentration in Indian manufacturing clusters creates supply vulnerability.
- Surgical Interventions:Ventriculoperitoneal shunt placement and optic nerve sheath fenestration divert CSF or decompress the optic nerve respectively. Academic medical centers in the United States and Germany are expanding minimally invasive approaches that reduce perioperative morbidity and shorten recovery intervals.
- Diuretics:Furosemide and chlorthalidone provide adjunctive volume management in patients with concurrent metabolic syndrome or renal comorbidities.
- Corticosteroids:Prednisone and dexamethasone serve acute exacerbation protocols and bridge therapy during surgical candidacy evaluation.
Carbonic anhydrase inhibitors handle the majority of throughput; surgical interventions are gaining share fastest as microsurgical techniques expand the addressable pool.
Delivery Mode:
Cost tier stratification separates chronic outpatient management from premium-priced acute intervention, with route selection driven by clinical urgency and reimbursement classification.
- Oral:Tablet and capsule formulations of acetazolamide sustain chronic pressure suppression with established bioavailability profiles. Homecare settings and specialty clinics in the United States rely on oral regimens for stable patients, with generic competition compressing per-dose costs.
- Intravenous:Parenteral acetazolamide and mannitol achieve rapid pressure reduction in emergency departments and intensive care units. United States academic medical centers capture premium reimbursement for IV administration during acute vision-threatening exacerbations.
- Intramuscular:Depot corticosteroid formulations provide sustained anti-inflammatory effect in patients with unreliable oral adherence.
- Ophthalmic:Topical carbonic anhydrase inhibitors address ocular surface pressure modulation as adjunctive therapy.
Oral delivery handles the majority of throughput; intravenous administration commands the steepest expansion trajectory as emergency protocol standardization advances.
End User:
Customer type concentration reflects how IIH diagnosis complexity funnels patients toward specialized referral networks with integrated pressure monitoring capability.
- Hospitals:Tertiary neurosurgical units perform shunt placement, fenestration, and implantable sensor deployment. United States hospital systems are consolidating IIH service lines into designated centers of excellence that capture severity-adjusted diagnosis-related group reimbursement.
- Specialty Clinics:Dedicated headache centers manage stable patients through protocolized acetazolamide titration and remote monitoring integration.
- Homecare Settings:Post-surgical recovery and chronic oral therapy management shift to home health nurses and telemedicine platforms.
- Research Institutions:Academic sites conduct pediatric investigation plan-mandated studies and biomarker-guided dosing trials under FDA and EMA oversight.
Hospitals handle the majority of throughput; specialty clinics are expanding most quickly as remote monitoring reduces hospital dependency.
Application:
Volume distribution across age cohorts and care settings reveals how diagnostic delay truncates pediatric addressable windows while adult populations sustain chronic management demand.
- Adult:Women of childbearing age represent the predominant diagnosed demographic, with oral carbonic anhydrase inhibitors forming the maintenance backbone. United States academic centers are refining withdrawal protocols for patients pursuing pregnancy.
- Pediatric:EMA-mandated pediatric investigation plans require age-appropriate formulation development, creating regulatory-driven R&D concentration. United States children's hospitals and European pediatric neurology networks are establishing standardized diagnostic pathways to compress the current 18-month mean delay.
- Emergency Care:Acute vision loss protocols demand rapid pressure reduction through IV mannitol or surgical decompression.
- Clinical Trials:Sponsors leverage FDA breakthrough therapy designation and orphan drug pathways to accelerate novel compound evaluation.
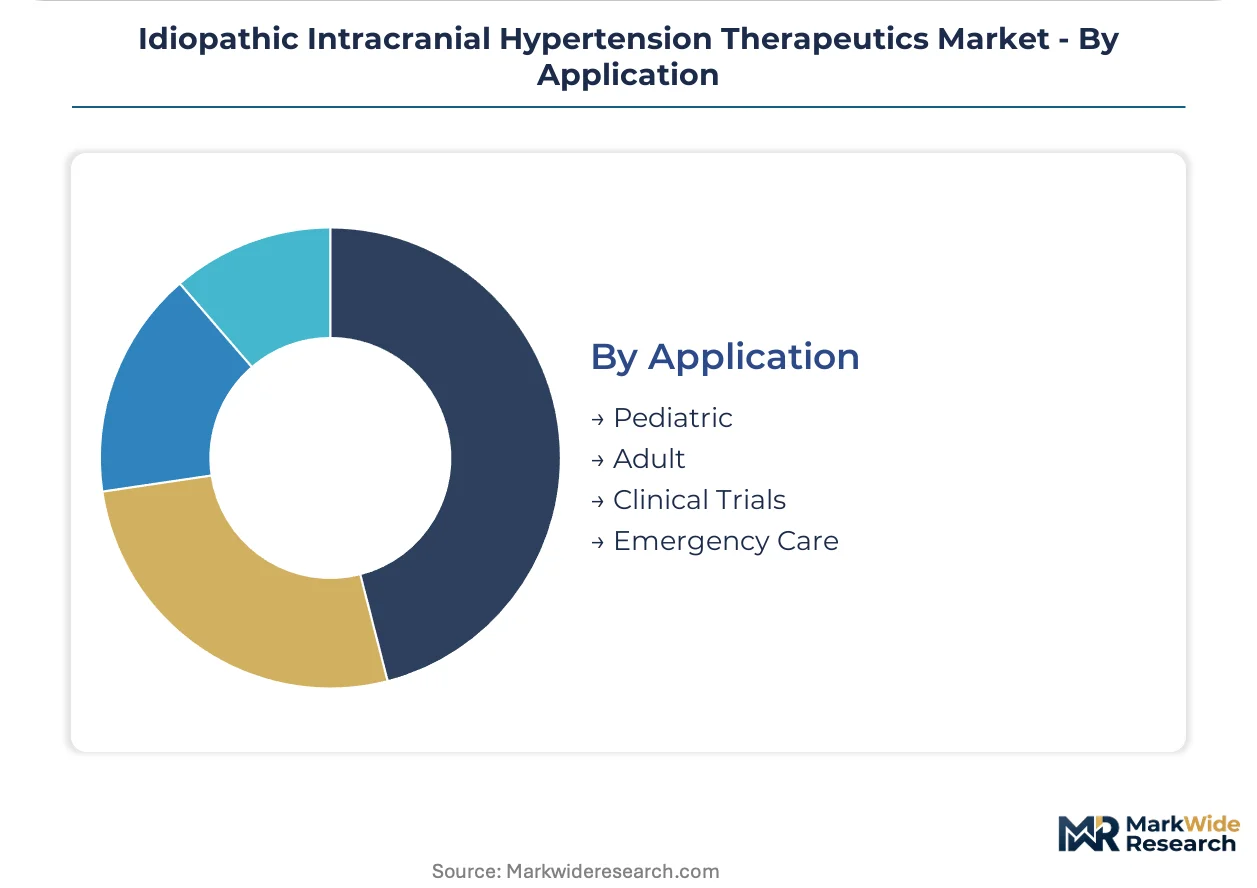
Adult applications handle the majority of throughput; pediatric applications are climbing the fastest as regulatory mandates and diagnostic awareness expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Academic medical centers and specialized headache clinics concentrate IIH therapeutics procurement in the United States, while European networks emphasize EMA-mandated pediatric formulation development. Reimbursement frameworks and regulatory pathways diverge sharply across major markets, shaping how carbonic anhydrase inhibitors and neurointerventional platforms penetrate care systems.
United States
Tertiary referral networks in Boston, Baltimore, and Houston standardize IIH protocols through designated centers of excellence. FDA breakthrough therapy designation accelerates novel compound timelines for sponsors targeting orphan neurological indications. The Mayo Clinic and Johns Hopkins anchor multicenter trials for implantable pressure sensors that enable home-based monitoring.
Germany
University hospitals in Munich and Heidelberg pioneer minimally invasive fenestration techniques that reduce perioperative morbidity. EMA Medical Device Regulation recalibration demands prospective registry data for CSF diversion shunts, extending notified body review timelines. The German Neurosurgical Society coordinates standardized diagnostic pathways to compress diagnostic delay.
United Kingdom
NHS England's specialized commissioning frameworks concentrate IIH surgical volume into neurosurgical units at Queen Square and Oxford. NICE technology appraisals evaluate remote intracranial pressure monitoring for cost-effectiveness against standard care. London headache centers pilot biomarker-guided acetazolamide titration protocols.
India
Generic API manufacturing clusters in Hyderabad and Ahmedabad supply acetazolamide active pharmaceutical ingredient to North American and European markets. CDSCO orphan drug pathways remain underdeveloped, limiting indigenous novel compound development. Apollo Hospitals and Max Healthcare establish dedicated IIH clinics in Delhi and Mumbai.
Australia
TGA alignment with ICH E11 guidelines creates harmonized evidentiary thresholds for pediatric extrapolation studies. Royal Melbourne Hospital and Royal North Shore Hospital anchor multicenter pressure management trials. Telemedicine-integrated care models extend specialist reach into regional Queensland and Western Australia.
Idiopathic Intracranial Hypertension Therapeutics Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a bifurcated structure where neurointerventional device portfolios and generic pharmaceutical supply chains operate on divergent margin profiles. The vendor base stratifies into three tiers: integrated medtech conglomerates with neurosurgical platform breadth, mid-scale generic manufacturers with API-to-finished-dose verticality, and precision-delivery specialists advancing implantable sensor technology. Consolidation pressure intensifies as hospital procurement collectives extract volume concessions and EMA evidence requirements elevate development costs.
Among integrated medtech conglomerates, Medtronic plc anchors minimally invasive pressure management platforms across tertiary care networks. Sun Pharmaceutical Industries Ltd exemplifies the generic manufacturing archetype with cost-competitive carbonic anhydrase inhibitor supply. Novartis AG occupies the specialty pharmaceutical tier through sustained-release formulation development and neurology channel control.
| Leading Market Players |
|---|
| Medtronic plc |
| Becton Dickinson and Company |
| Sanofi |
| Abbott Laboratories |
| Philips |
| Sun Pharmaceutical Industries Ltd |
| Siemens AG |
| Novartis AG |
| Teva Pharmaceutical Industries Ltd |
| Others |
Supply & Pricing Matrix
Hyderabad and Ahmedabad manufacturing clusters anchor global acetazolamide API capacity, with their output fluctuations transmitting directly into North American and European finished-dose pricing power. Carbonic anhydrase inhibitor procurement teams at academic medical centers face margin compression when Indian API supply tightens, forcing emergency spot-market sourcing at elevated cost tiers.
Pricing Analysis
Cost-plus contracts with Indian API manufacturers typically index to active pharmaceutical ingredient commodity benchmarks, creating transparency in raw material pass-through. Three-tier pricing structure across premium sustained-release formulations, standard immediate-release tablets, and economy generic capsules separates Novartis AG's specialty neurology positioning from Sun Pharmaceutical Industries Ltd's volume-driven supply. Pricing pressure stems from Medicare severity-adjusted diagnosis-related group undervaluation of complex IIH surgical interventions. Hospital procurement collectives exhibit highest price sensitivity through group purchasing organization leverage, while emergency departments capture premium reimbursement tolerance for intravenous acetazolamide during acute vision-threatening episodes.
Supply Chain Analysis
Supplier-financing facilities extended by Indian API manufacturers to North American generic finished-dose producers compress working capital cycles and lock in offtake commitments. Active pharmaceutical ingredient production concentrates in India and China, with secondary formulation capacity in the United States and Germany. The supply chain draws from sulfonamide precursor chemicals, acetazolamide API, and specialized excipients for sustained-release matrices. Single-source vulnerability runs through concentrated Indian API manufacturing clusters exposed to environmental compliance shutdowns. Distribution runs through hospital system prime vendor agreements, specialty pharmacy networks, and direct-to-clinic channels serving headache centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA breakthrough therapy designation for orphan neurological indications is compressing development timelines and attracting capital deployment into IIH-targeted platforms. This regulatory inflection positions the market for sustained expansion as precision-intervention models displace chronic systemic medication paradigms.
For Market Incumbents: Build regulatory data moats through prospective registry submissions satisfying EMA Medical Device Regulation recalibration for cerebrospinal fluid diversion shunts. Incumbents should deepen backward integration into acetazolamide API supply through captive Indian manufacturing partnerships, defending against generic supply concentration vulnerability while securing volume-based concessions from hospital procurement collectives. For New Entrants and Emerging Players: Establish a beachhead in pediatric formulation development, where EMA-mandated pediatric investigation plans create first-mover advantage for age-appropriate acetazolamide dosing vehicles. Remote intracranial pressure monitoring hardware represents the most penetrable white-space segment, with telemedicine-integrated implantable sensors enabling home-based pressure trending that reduces emergency department utilization. Go-to-market positioning should anchor on hospital system risk-sharing agreements that align sensor deployment with readmission reduction metrics. For Investors and Strategic Acquirers: Long-term, this sits as a precision-neurology platform play because implantable wireless pressure sensors are digitizing continuous intracranial pressure monitoring and creating recurring revenue streams beyond device placement. Acquisition targets should profile as mid-scale neurointerventional device specialists with FDA breakthrough therapy designation progress and established academic medical center pilot sites. The signal to watch is CMS reimbursement determination for remote monitoring codes, which would validate home-based pressure trending economics and accelerate hospital capital allocation toward integrated monitoring platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Pediatric Formulation Development | EMA-mandated pediatric investigation plans create regulatory-driven R&D concentration for age-appropriate dosing vehicles. |
| Implantable Sensor Deployment | Mayo Clinic and Johns Hopkins anchor multicenter trials validating home-based pressure monitoring against standard care. |
| API Supply Security Investment | Indian manufacturing cluster partnerships reduce single-source vulnerability for carbonic anhydrase inhibitor availability. |
| Reimbursement Strategy Advancement | NICE technology appraisals evaluate remote intracranial pressure monitoring for cost-effectiveness in NHS England. |
| Specialty Clinic Network Expansion | Apollo Hospitals and Max Healthcare establish dedicated IIH clinics in Delhi and Mumbai capturing regional patient volume. |
Research Methodology
Cross-validation between primary interviews with neurosurgeons, headache specialists, hospital procurement managers, and regulatory affairs directors anchors the qualitative findings against secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and hospital procurement databases. Bottom-up patient volume modeling and top-down pharmaceutical and device revenue triangulation reconcile segment-level estimates across carbonic anhydrase inhibitors, surgical interventions, and emerging monitoring platforms.
Calibration against historical FDA approval timelines for orphan neurological indications and EMA Medical Device Regulation review patterns shapes the projection framework across the analysis window. Segmentation dimensions include product type, delivery mode, end-user configuration, and regional regulatory cluster. CAGRs derive from patient epidemiology trends, protocol adoption curves at academic medical centers, and reimbursement pathway evolution. Forecast inputs incorporate diagnostic delay compression initiatives and pediatric investigation plan completion rates.
Stress conditions across API supply disruption, Medicare reimbursement reclassification, and neurointerventionalist workforce scarcity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory pathway timelines and hospital capital allocation priorities. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Mild Cognitive Impairment Market
Neurology
Brain Aneurysm Treatment Market
Neurology
Cerebral Spinal Fluid (CSF) Management Market
Neurology
North America Neurology Devices Market
Neurology
Hydrocephalus Market
Neurology
Cerebral Aneurysm Management Market
Neurology
CNS Therapeutics Market
Neurology
Hepatic Encephalopathy Market
Neurology
UAE Neurology Devices Market
Neurology
Narcolepsy Treatment Market
Neurology
Europe Pediatric Neurology Device Market
Neurology
Brain Ischemia Market
Neurology
Parkinsons Disease Therapeutics Market
Neurology
Mild Traumatic Brain Injury Treatment Market
Neurology
Spasticity Treatment Market
Neurology
Germany Neurology Devices Market