
 Bruxism Management Market | 2026-2036
Bruxism Management Market Size, Share, and Industry Trends Forecast 2026-2036
Bruxism Management Market Outlook
Specialist dental clinics is bifurcating demand away from general practitioners as patients seek targeted occlusal therapy. Henry Schein controls distribution networks across North American dental practices, leveraging scale to secure preferred vendor status. Ivoclar Vivadent dominates high-precision splint manufacturing with proprietary CAD/CAM workflows. Dentsply Sirona anchors digital dentistry integration, extending its software ecosystem into bruxism diagnostic protocols.
Bruxism management encompasses the clinical assessment, mechanical intervention, pharmacological adjunct, and behavioral modification of involuntary jaw clenching and grinding. Dental splints fabricated from ethylene-vinyl acetate copolymers or hard acrylic resins function as the primary mechanical intervention, distributing occlusal forces to prevent enamel degradation and temporomandibular joint pathology. Sleep monitoring technology is gaining fastest as home-based polysomnography and wearable electromyography systems reduce reliance on clinical sleep studies. Cognitive behavioral therapy remains margin-constrained due to reimbursement gaps, while muscle relaxants occupy a mature position with generic competition compressing pricing power.
FDA 510(k) clearance governs biofeedback and electrical stimulation devices entering the US market, while the EU MDR requires clinical evidence for dental splints reclassified as Class IIa medical devices. Japan's PMDA enforces stringent biocompatibility testing for intraoral materials, adding validation timelines for foreign manufacturers. Stakeholders must monitor evolving reimbursement codes for home-use sleep monitoring devices across Medicare, NHS England, and Japan's MHLW as these determine patient out-of-pocket exposure and adoption velocity.
Market Dynamics
Digital dentistry workflows are compressing fabrication timelines for occlusal splints while EU MDR reclassification forces clinical evidence investment for previously exempt dental devices.
Growth Catalysts
- Home-based polysomnography:Wearable electromyography systems reduce patient reliance on clinical sleep studies, expanding addressable screening populations.
- EU MDR Class IIa reclassification:Dental splints now require clinical evidence, creating competitive moats for manufacturers with established validation capabilities.
- Specialist dental clinic expansion:Patients seeking targeted occlusal therapy migrate from general practitioners to dedicated bruxism protocols.
Market Restraints
- Ethylene-vinyl acetate copolymer price volatility:Petrochemical feedstock fluctuations compress margins on soft splint fabrication.
- Japan PMDA biocompatibility requirements:Stringent intraoral material testing extends validation timelines for foreign manufacturers by 12-18 months.
- Generic muscle relaxant saturation:Off-label prescribing of mature pharmaceuticals limits pricing power for novel pharmacological entrants.
Strategic Opportunities
- Medicare reimbursement expansion:Home-use sleep monitoring devices await coding decisions that would reduce patient out-of-pocket exposure.
- CAD/CAM-EMG convergence:Integration of digital splint design with real-time jaw muscle monitoring enables personalized therapy adjustment.
- Germany statutory insurance recognition:Oral appliance therapy reimbursement maturity creates template for adjacent European markets.
Industry Challenges
- FDA 510(k) predicate device scarcity:Novel biofeedback mechanisms struggle to identify acceptable equivalence pathways, extending clearance timelines.
- Cognitive behavioral therapy reimbursement gaps:Behavioral modification protocols lack procedure codes across NHS England and US commercial payers.
- Legacy practice management integration:Sleep diagnostic data formats conflict with established dental software ecosystems, requiring middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bruxism Management Market |
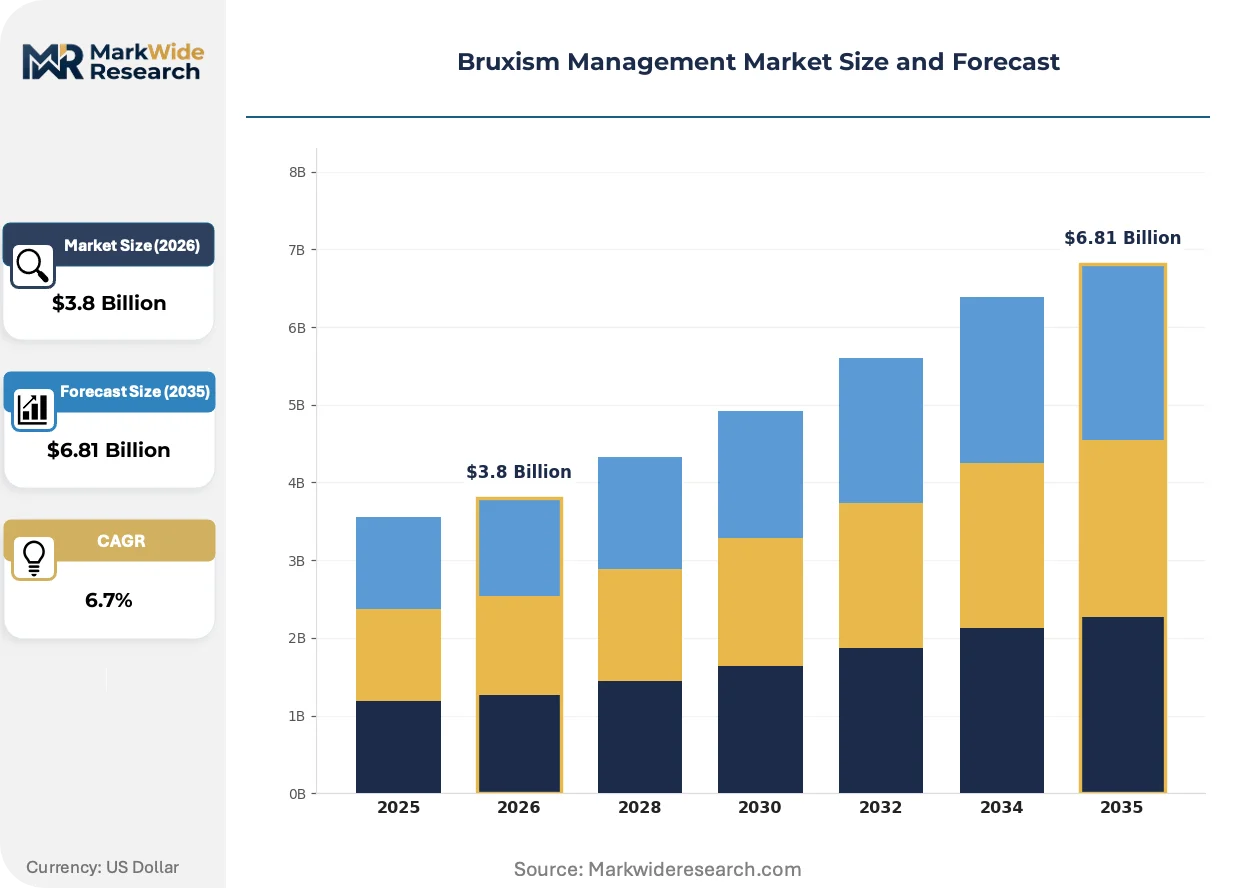
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dental Splints, Chewing Devices, Muscle Relaxants, Biofeedback Devices Technology: Electrical Stimulation, Cognitive Behavioral Therapy, Sleep Monitoring, Behavioral Training End User: Dental Clinics, Hospitals, Home Care Settings, Rehabilitation Centers Distribution Channel: Online Stores, Retail Pharmacies, Specialty Dental Clinics, Others |
| Companies Covered | Ivoclar Vivadent AG, Akervall Technologies, Inc., GlaxoSmithKline plc, Pfizer Inc., Carestream Dental, Henry Schein, Inc., Procter & Gamble, Dentsply Sirona, Teva Pharmaceutical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bruxism Management Market Strategic Shifts
Bruxism management is transitioning from episodic intervention to continuous monitoring paradigms, with hardware miniaturization and algorithmic sleep staging enabling patient-owned diagnostic workflows.
Wearable electromyography systems is bifurcating the diagnostic pathway. These devices capture masseter muscle activity during sleep without clinical supervision. Specialist sleep clinics adopt them for patient triage, while direct-to-consumer channels bypass traditional referral networks entirely. The technology is bifurcating market access between reimbursed clinical pathways and out-of-pocket wellness segments.
EU MDR technical documentation requirements for dental splints now mandate clinical performance data where bench testing previously sufficed. Manufacturers must demonstrate biocompatibility and mechanical durability through prospective studies. German notified bodies report 40% application backlogs for Class IIa dental devices, compressing first-mover advantages for prepared filers.
Patient acquisition through dental practices is fragmenting as tele-dentistry platforms enable remote splint fitting and adjustment. Direct-to-consumer oral appliance brands bypass traditional professional channels with boil-and-bite alternatives. The United States exhibits the most pronounced channel shift, where employer-sponsored dental plans increasingly exclude non-network providers.
Bruxism Management Market Segmentation
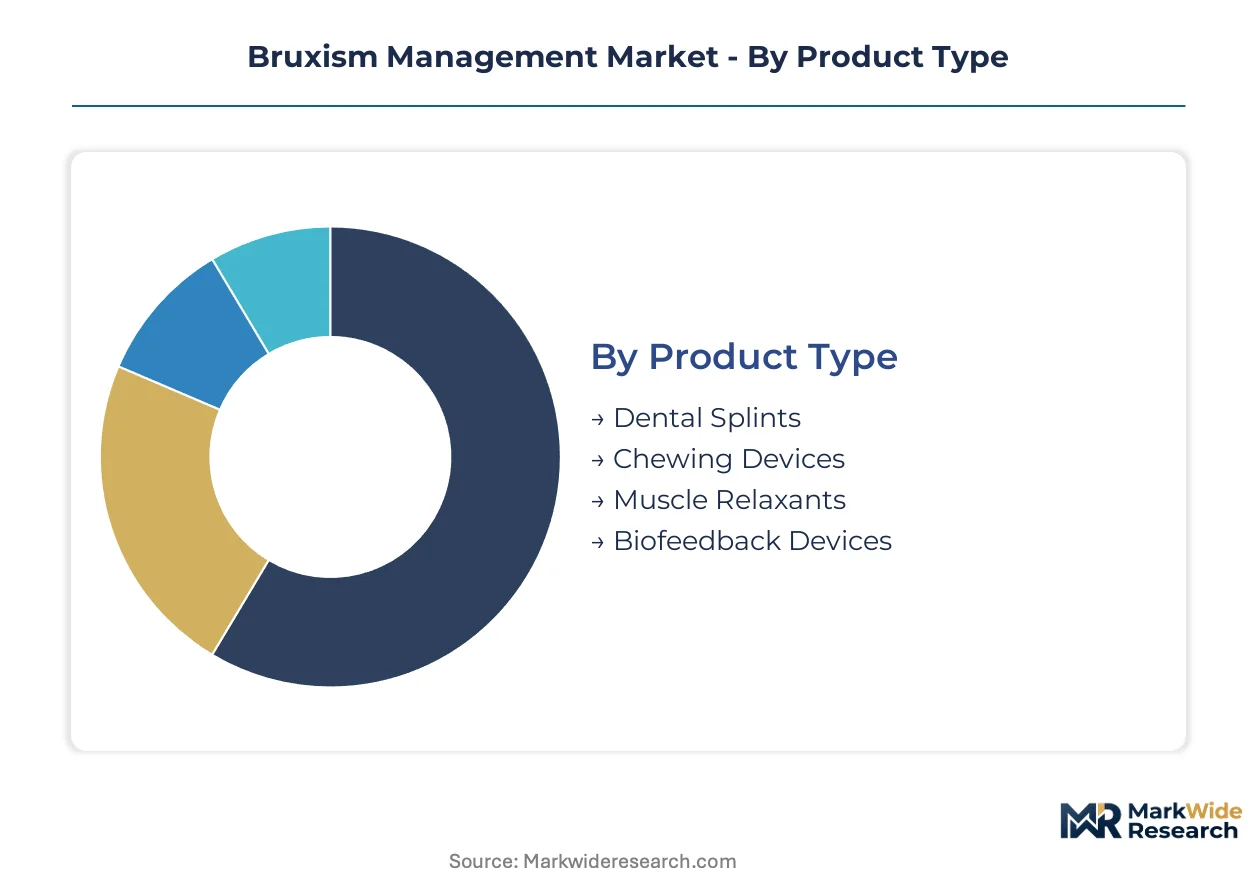
Bruxism management segments reflect distinct procurement pathways, with professional channels commanding premium positioning while direct-to-consumer routes expand access. Channel selection determines reimbursement eligibility, clinical oversight requirements, and patient compliance monitoring capabilities.
Product Type:
Dental splints flow predominantly through specialty clinics with professional fitting protocols, while biofeedback devices bifurcate between reimbursed clinical pathways and wellness-oriented direct sales.
- Dental Splints:Fabricated from ethylene-vinyl acetate copolymers or hard acrylic resins, these mechanical interventions distribute occlusal forces to prevent enamel degradation. Demand concentrates in Germany and the United States where statutory insurance recognition reduces patient out-of-pocket exposure.
- Biofeedback Devices:Wearable electromyography systems capture masseter muscle activity during sleep, enabling patient-owned diagnostic workflows. Home-use channels in the United States bypass traditional referral networks entirely, though Medicare reimbursement decisions remain pending.
- Chewing Devices:Therapeutic silicone implements designed for daytime jaw muscle relaxation and proprioceptive training.
- Muscle Relaxants:Off-label prescribing of generic pharmaceuticals limits pricing power for novel pharmacological entrants.
Dental splints dominate installed base. Biofeedback devices are where expansion concentrates.
Technology:
Cost stratification separates reimbursed clinical technologies from out-of-pocket behavioral interventions, with sleep monitoring systems commanding premium positioning due to hardware complexity.
- Sleep Monitoring:Home-based polysomnography and wearable electromyography systems reduce reliance on clinical sleep studies. Specialist sleep clinics in Japan adopt them for patient triage, though PMDA biocompatibility requirements extend validation timelines for foreign manufacturers.
- Electrical Stimulation:Transcutaneous devices deliver targeted neuromuscular modulation to reduce nocturnal muscle hyperactivity. FDA 510(k) clearance governs US market entry, with predicate device scarcity extending timelines for novel mechanisms.
- Cognitive Behavioral Therapy:Structured protocols addressing stress-mediated bruxism lack procedure codes across NHS England and US commercial payers.
- Behavioral Training:Habit-reversal techniques and jaw positioning exercises delivered through mobile applications or clinician guidance.
Sleep monitoring commands highest average revenue per patient. Electrical stimulation is climbing the fastest as miniaturization enables consumer-grade form factors.
End User:
Patient acuity and reimbursement maturity determine facility selection, with dental clinics capturing routine cases while hospitals manage complex temporomandibular joint comorbidities.
- Dental Clinics:Specialist practices with dedicated occlusal therapy protocols capture patients migrating from general practitioners. Henry Schein distribution networks secure preferred vendor status across North American practices.
- Home Care Settings:Direct-to-consumer oral appliances and wearable diagnostics enable remote management. Tele-dentistry platforms in the United States facilitate remote splint fitting and adjustment.
- Hospitals:Academic medical centers manage refractory cases requiring multidisciplinary coordination between sleep medicine and orofacial pain specialists.
- Rehabilitation Centers:Post-traumatic bruxism management following neurological injury or maxillofacial surgery.
Dental clinics capture plurality of volume. Home care settings are gaining share fastest as employer-sponsored dental plans narrow network coverage.
Distribution Channel:
Channel selection determines margin structure, with specialty clinics preserving premium pricing while online stores compete on convenience and cost transparency.
- Specialty Dental Clinics:Professional fitting and adjustment services justify premium positioning. Ivoclar Vivadent leverages proprietary CAD/CAM workflows to dominate high-precision splint manufacturing.
- Online Stores:Direct-to-consumer boil-and-bite alternatives bypass traditional professional channels. The United States exhibits the most pronounced channel shift.
- Retail Pharmacies:Over-the-counter night guards and muscle relaxant distribution through established pharmacy networks.
- Others:Employer wellness programs, sleep specialist referrals, and dental school clinics.
Specialty dental clinics retain margin leadership. Online stores are where volume expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors European distribution for dental laboratory supplies, while the Los Angeles-Long Beach port complex handles Pacific Rim imports of intraoral materials into North American fabrication networks.
United States
Employer-sponsored dental plans narrow network coverage, accelerating direct-to-consumer channel migration. FDA 510(k) clearance governs biofeedback device entry, with predicate scarcity extending timelines for novel mechanisms. Henry Schein distribution networks secure preferred vendor status across specialty dental practices in the Greater New York and Pacific Northwest clusters.
Germany
Statutory insurance recognition for oral appliance therapy reduces patient out-of-pocket exposure. EU MDR Class IIa reclassification mandates clinical evidence for dental splints previously exempt from validation. Bavarian notified bodies report application backlogs, compressing first-mover advantages for prepared filers in the Munich-Stuttgart corridor.
Japan
Specialist sleep clinics adopt wearable electromyography systems for patient triage. PMDA biocompatibility requirements for intraoral materials extend validation timelines for foreign manufacturers by 12-18 months. Osaka-based dental laboratories dominate high-precision splint fabrication for the Kansai region's aging demographic.
United Kingdom
NHS England reimbursement gaps for cognitive behavioral therapy constrain behavioral modification adoption. CE marking under EU MDR remains applicable through retained EU law alignment. London's Harley Street specialist cluster captures premium private-pay occlusal therapy demand from Gulf state medical tourists.
Australia
Private health insurance tiered extras coverage determines oral appliance reimbursement eligibility. TGA registration parallels FDA pathways for biofeedback devices with acceptable predicate identification. Sydney-Melbourne dental laboratory networks consolidate through CAD/CAM workflow standardization.
Bruxism Management Market Competitive Environment
Concentration sits with dental supply distributors and precision manufacturing specialists rather than pharmaceutical conglomerates. Three archetypes define competitive positioning: distribution-integrated platforms controlling practice procurement workflows, CAD/CAM-anchored fabricators commanding precision splint production, and diversified dental conglomerates extending software ecosystems into diagnostic protocols. Strategic moves center on EU MDR validation capacity building and tele-dentistry platform integration.
Among Switzerland-based precision manufacturers, Ivoclar Vivadent AG exemplifies the CAD/CAM-anchored archetype through proprietary digital workflows. Henry Schein, Inc. occupies the distribution-integrated position across North American dental practices. Dentsply Sirona sits within the diversified conglomerate tier, leveraging software ecosystem extension into bruxism diagnostic protocols.
| Leading Market Players |
|---|
| Ivoclar Vivadent AG |
| Akervall Technologies, Inc. |
| GlaxoSmithKline plc |
| Pfizer Inc. |
| Carestream Dental |
| Henry Schein, Inc. |
| Procter & Gamble |
| Dentsply Sirona |
| Teva Pharmaceutical Industries Ltd. |
| Others |
Value Chain & Pricing Dynamics
Capacity reservation contracts with German dental laboratories lock in ethylene-vinyl acetate copolymer supply and stabilize fabrication costs for North American distributors navigating EU MDR reclassification timelines. These arrangements bind volume commitments to price ceilings, insulating procurement officers from petrochemical feedstock volatility while securing preferential queue positions for Class IIa device validation.
Pricing Analysis
Volume-discount tiering structures separate Henry Schein's national account pricing from independent dental practice rates. Three-tier pricing stratifies across premium CAD/CAM-fitted splints, standard thermoformed appliances, and economy boil-and-bite alternatives. Price differentiation hinges on customization precision and FDA 510(k) clearance status. Cost compression in the economy tier intensifies as direct-to-consumer brands bypass professional markup. Employer-sponsored dental plans exhibit highest price sensitivity, while private-pay patients in specialist clinics absorb premium positioning.
Supply Chain Analysis
Liege-Port transit through the Port of Hamburg underwrites European distribution of intraoral materials, with customs delays at this chokepoint cascading to North American fabrication networks. Manufacturing concentrates in Germany, Switzerland, and Japan for precision splint production, while China dominates raw acrylic resin supply. The chain draws from Saudi petrochemical feedstocks, German precision machining equipment, and Japanese biocompatibility testing services. Single-source vulnerability sits with EU MDR notified body capacity. Distribution runs through Henry Schein's North American warehouse network and Ivoclar Vivadent's direct laboratory relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Home-based polysomnography and wearable electromyography systems are disrupting patient acquisition pathways, compressing timelines for stakeholders to secure positioning before reimbursement codes solidify.
For Market Incumbents: Shield CAD/CAM fabrication margins by securing backward integration into ethylene-vinyl acetate copolymer supply through long-term offtake agreements with German petrochemical suppliers. Accelerate EU MDR technical documentation submission to Bavarian notified bodies before application backlogs extend validation timelines further. Channel control through Henry Schein distribution networks remains the priority defensive lever against direct-to-consumer disintermediation. For New Entrants and Emerging Players: Lead with tele-dentistry-enabled remote splint fitting to capture employer-sponsored dental plan members excluded from narrowing network coverage. The United States home-use sleep monitoring segment offers the most penetrable white space, pending Medicare reimbursement decisions. A software-companion go-to-market angle integrating EMG data with patient-facing mobile applications bypasses incumbent hardware advantages. For Investors and Strategic Acquirers: Capital is best deployed toward CAD/CAM-anchored fabricators with established EU MDR validation capabilities and proprietary digital workflows. The five-to-ten year viability window favors manufacturers who convert regulatory compliance burdens into competitive moats. Watch FDA coding decisions for home-use biofeedback devices as the inflection signal determining whether direct-to-consumer channels achieve reimbursement parity with clinical pathways.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Bavarian notified body relationships compress validation timelines for Class IIa dental splints. |
| Tele-Dentistry Platform Integration | Remote splint fitting bypasses Henry Schein distribution control in employer-plan networks. |
| Biocompatibility Testing Pre-Validation | Japan PMDA alignment reduces foreign manufacturer entry barriers by 12-18 months. |
| Medicare Reimbursement Strategy | Home-use EMG device coding decisions determine patient out-of-pocket exposure velocity. |
| CAD/CAM-EMG Convergence Development | Real-time jaw muscle monitoring integration enables personalized therapy adjustment protocols. |
Study Parameters
A standing panel of sleep medicine clinicians, dental laboratory technicians, GPO contracts managers, and biomedical engineers provided ongoing calibration against procurement database trends. Primary interviews with Henry Schein distribution account executives and Ivoclar Vivadent digital workflow specialists combined with secondary validation through FDA 510(k) filings, EU MDR notified body registries, and CMS Medicare coding databases. Bottom-up splint shipment estimates and top-down dental supply market sizing were triangulated to constrain projection variance.
Consistency checks against German statutory insurance reimbursement data and Japanese PMDA approval timelines validated analytical outputs across the projection horizon. The forecast framework modeled segmentation across product type, technology modality, end-user facility, and distribution channel, with particular attention to direct-to-consumer channel migration patterns. CAGRs were derived from spline-interpolated adoption curves fitted to historical reimbursement expansion episodes in analogous device categories.
The analysis sits within stated boundaries; outcomes outside FDA coding decisions, EU MDR enforcement intensity, or petrochemical feedstock stability would require recalibration. Forecasts reflect documented assumptions regarding Medicare reimbursement expansion timing and employer dental plan network narrowing velocity. Practitioners should keep alternative scenarios live as home-use diagnostic regulatory pathways and direct-to-consumer channel litigation risk evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Patient Transportation Market
Healthcare Services
Medical Peer & External Physician Review Services Market
Healthcare Services
Healthcare Staffing Market
Healthcare Services
US Acute Hospital Care Market
Healthcare Services
US Healthcare Third-Party Logistics Market
Healthcare Services
Life Science Trade Lane Design and Qualification Services Market
Healthcare Services
Escort Bed Sharing Market
Healthcare Services
Global Acute Hospital Care Market
Healthcare Services
South Korea Healthcare Cold Chain Logistics Market
Healthcare Services
Assisted Living Market
Healthcare Services
Global Perfusion Services Market
Healthcare Services
Sterilization Services Market
Healthcare Services
Hospital Command Center Operations Market
Healthcare Services
Healthcare Logistics Market
Healthcare Services
Contract Research Organization (CRO) Services Market
Healthcare Services
Michigan Urgent Care Center Market