
 US Pharmacy Market | 2026-2036
US Pharmacy Market Size, Share, and Industry Trends Forecast 2026-2036
US Pharmacy Market Analysis
Specialty pharmacy automation is narrowing the gap between centralized distribution and community-based care. CVS Health Corporation leverages its vertically integrated PBM-pharmacy model to control formulary access and patient flow. Walgreens Boots Alliance anchors its position through clinic partnerships and immunization infrastructure. Walmart Inc. competes on price transparency and rural access density.
US pharmacy operations encompass the compounding, dispensing, and clinical management of pharmaceutical products across retail, institutional, and mail-order channels, governed by USP <797> and <800> standards for sterile and hazardous drug handling. Prescription drugs command the dominant value share, while OTC medications and dietary supplements carry higher turnover velocity and front-of-store margin contribution. Mail order and home delivery channels are accelerating fastest, driven by Medicare Part D plan designs and chronic therapy adherence programs.
FDA, DEA, and state boards of pharmacy collectively govern product integrity, controlled substance scheduling, and pharmacist scope of practice, with DSCSA serialization deadlines forcing wholesale infrastructure upgrades. CMS reimbursement rules for medication therapy management directly shape service profitability at the store level. Stakeholders must monitor how IRA Medicare price negotiation timelines reshape specialty drug portfolio economics and PBM contract structures.
Market Dynamics
The US pharmacy market is undergoing structural compression as the FDA's Drug Supply Chain Security Act forces wholesale distributors and retail chains to rebuild inventory infrastructure around unit-level serialization, creating capital intensity that favors scaled operators.
Growth Catalysts
- Medicare Part D plan designs:Chronic therapy adherence programs are expanding mail-order channel penetration among senior populations in Florida and Arizona.
- Specialty pharmacy automation:Robotic dispensing systems are enabling community-based sites to handle high-cost biologics previously restricted to centralized distribution.
- Immunization infrastructure:Federal pharmacy partnership programs have permanently embedded retail locations into preventive care delivery networks.
Market Restraints
- DSCSA compliance costs:Small and mid-sized independent pharmacies face disproportionate technology investment burdens to meet traceability mandates.
- Specialty drug concentration:Limited distribution networks for oncology and rare disease therapies restrict patient access to narrow pharmacy networks.
- Reimbursement compression:CMS direct and indirect remuneration fee adjustments are squeezing generic dispensing margins at the store level.
Strategic Opportunities
- Rural access density:Underserved counties in Texas and the Mountain West present whitespace for telepharmacy-enabled satellite locations.
- Medication therapy management:CMS reimbursement codes for clinical pharmacist services are creating service revenue streams beyond product margins.
- IRA price negotiation timelines:Selected drug portfolio restructuring is forcing PBMs to rebate contract structures, opening negotiation leverage for formulary positioning.
Industry Challenges
- Pharmacist workforce constraints:Clinical service expansion is competing with retail staffing shortages in high-volume markets.
- Legacy system integration:DSCSA-mandated track-and-trace platforms must interface with decades-old pharmacy management software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Pharmacy Market |
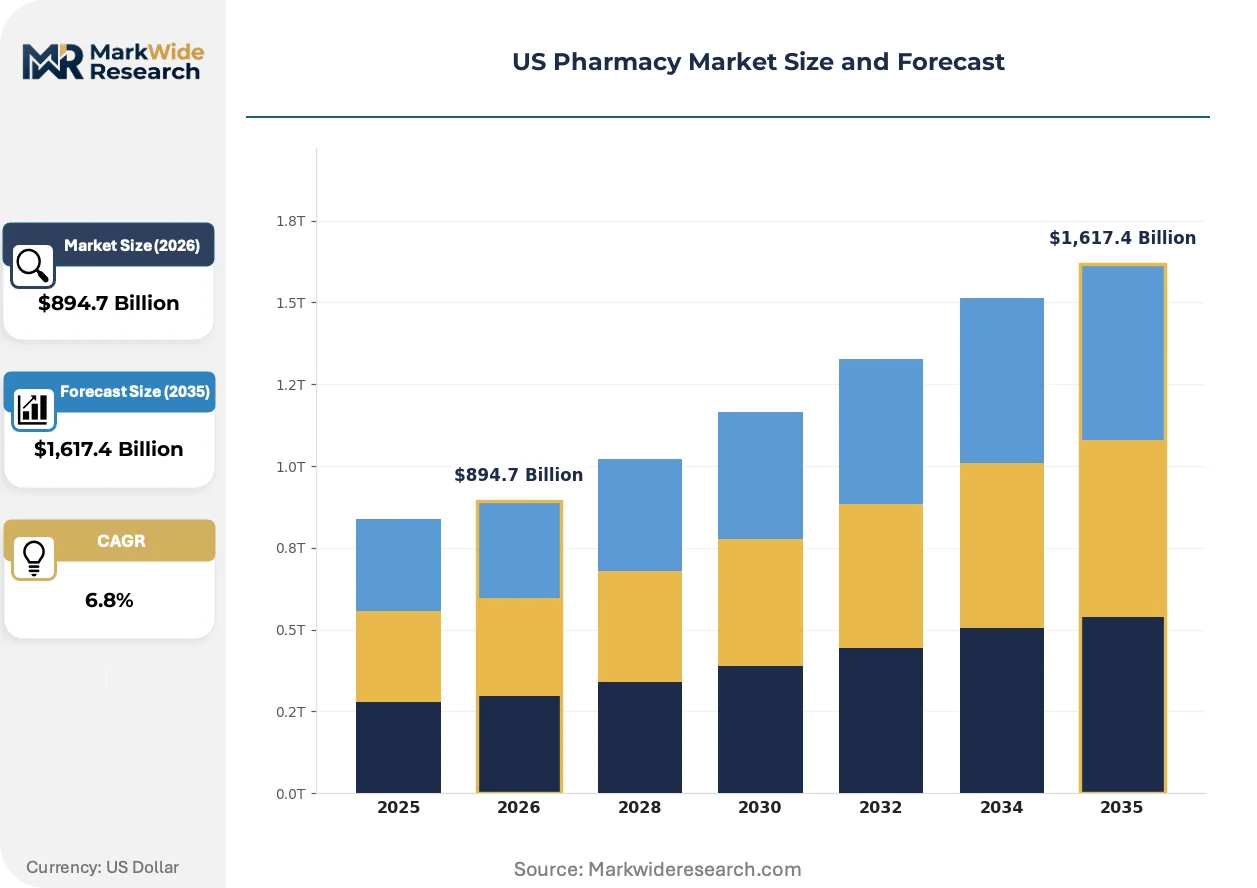
| Market Size in 2026 | $894.7 Billion |
| Market Size in 2035 | $1,617.4 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: OTC Medications, Prescription Drugs, Dietary Supplements, Personal Care Products Customer Type: Retail Customers, Healthcare Providers, Insurers, Hospitals Delivery Mode: In-Store Pickup, Home Delivery, Mail Order, Online Service Type: Pharmaceutical Consultation, Medication Therapy Management, Immunization Services, Counseling |
| Companies Covered | Walmart Inc., Express Scripts, CVS Health Corporation, Publix, Wegmans, Walgreens Boots Alliance, UnitedHealth Group, H-E-B, Cigna, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Pharmacy Market Emerging Trajectories
Automation and virtual care modalities are compressing the distance between centralized specialty distribution and community pharmacy service delivery, while regulatory mandates reshape capital allocation across the supply chain.
Central fill automation is virtualizing inventory positioning for retail chains. These systems consolidate high-volume generic dispensing into regional hubs while maintaining local pickup points. CVS Health and Walgreens Boots Alliance are deploying this architecture to reduce in-store labor intensity. The technology is virtualizing the traditional storefront model by separating patient-facing services from back-of-house fulfillment.
The FDA's Drug Supply Chain Security Act is mandating interoperable electronic tracking systems for prescription drugs at the package level. Wholesale distributors must upgrade warehouse management platforms to capture serialized product data. California and Florida pharmacy operations are experiencing the steepest compliance curves due to volume concentration and state-level enforcement timing.
Home delivery channel preference is hardening among Medicare-eligible populations managing multiple chronic conditions. Mail-order pharmacies are capturing maintenance medication volume previously filled at retail counters. Texas and California senior migration corridors are exhibiting the strongest channel shift intensity as plan designs incentivize 90-day supply fulfillment.
US Pharmacy Market Segmentation
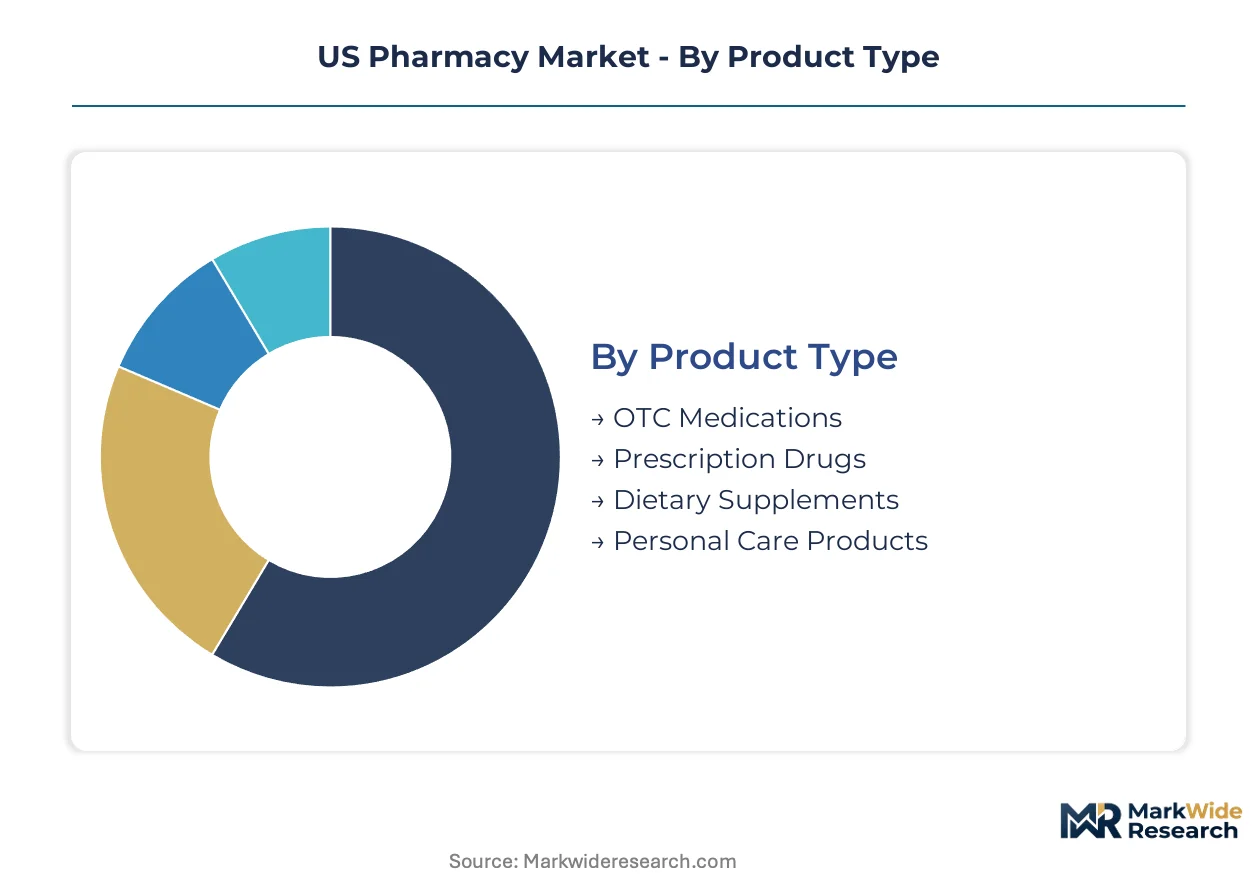
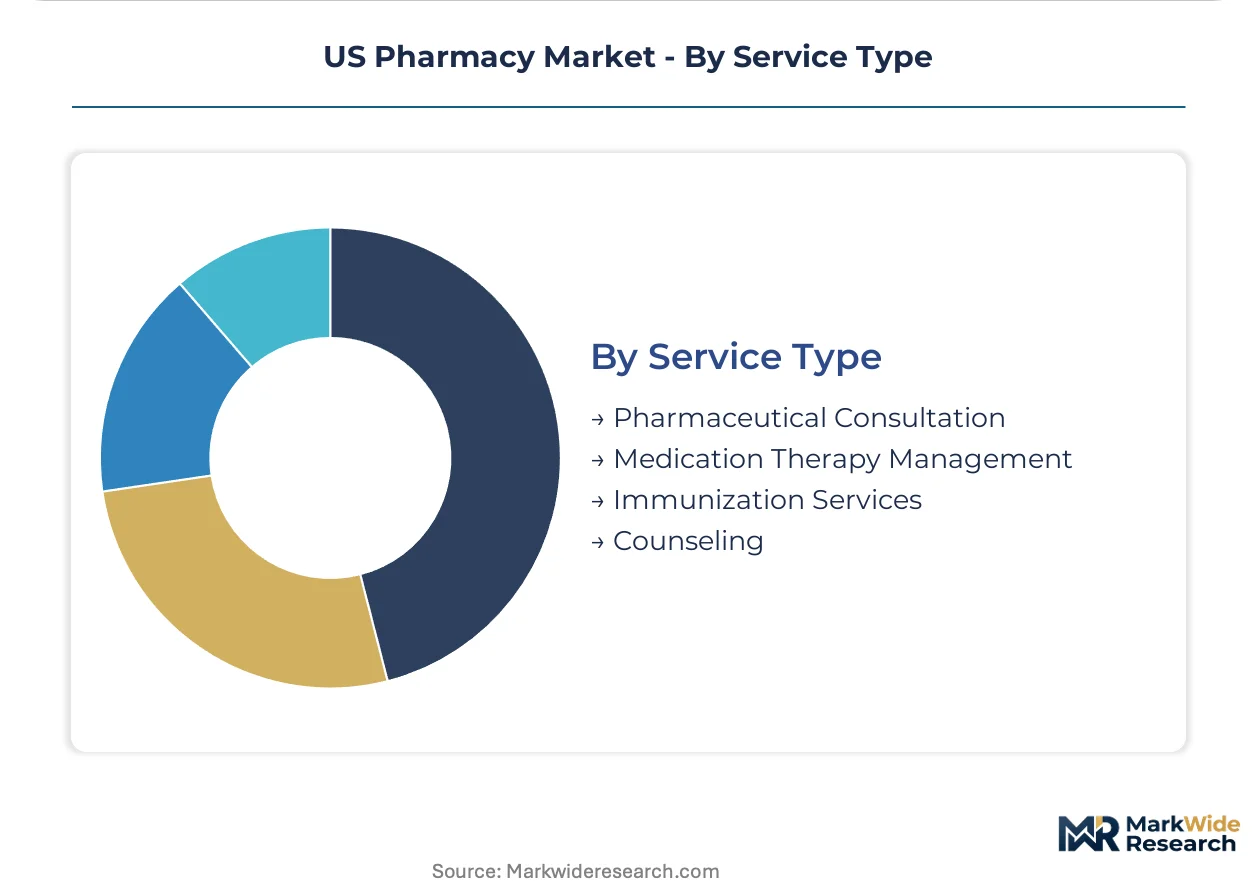
Pharmacy market segmentation reveals how reimbursement flows and patient touchpoints concentrate value across product and service categories. Understanding these divisions exposes where margin pressure intersects with growth opportunity in US healthcare delivery.
Product Type:
After-sales service intensity varies sharply across product categories, with high-touch clinical support commanding premium positioning against commodity dispensing.
- Prescription Drugs:Formulary-controlled pharmaceuticals requiring pharmacist verification, insurance adjudication, and patient counseling. Demand clusters in Florida and Texas senior corridors where Medicare Part D plan designs incentivize 90-day maintenance therapy fulfillment.
- OTC Medications:Self-selected remedies for acute symptom management with minimal professional oversight. Front-of-store placement in California and Arizona retail locations generates impulse purchase velocity that subsidizes prescription dispensing infrastructure.
- Dietary Supplements:Nutraceutical products operating outside FDA drug approval pathways, positioned adjacent to pharmacy counters for cross-sell capture.
- Personal Care Products:Consumer health and hygiene SKUs with high inventory turnover and minimal regulatory burden.
Prescription drugs hold the largest share; momentum sits with OTC medications as front-of-store margin contribution intensifies.
Customer Type:
Cost tier differentiation separates transaction-scale economics across patient and institutional buyer segments.
- Retail Customers:Individual patients filling prescriptions and purchasing health products through commercial insurance or cash payment. Volume concentrates in suburban Texas and Florida locations where senior migration patterns sustain chronic therapy demand.
- Healthcare Providers:Physician practices and clinics sourcing vaccines, injectables, and point-of-care medications. California medical groups drive specialty pharmaceutical procurement through limited distribution networks.
- Hospitals:Inpatient and outpatient pharmacy departments managing 340B drug pricing programs and formulary standardization.
- Insurers:PBM-owned mail-order operations and specialty pharmacy networks controlling patient steerage through formulary design.
Retail customers dominate transaction volume; healthcare providers are expanding most quickly as clinic-based pharmacy integration deepens.
Delivery Mode:
Application context determines channel preference, with chronic disease management favoring convenience over immediacy.
- Home Delivery:Courier-based distribution of maintenance medications directly to patient residences. Arizona and Florida Medicare populations exhibit strongest adoption as plan designs waive copays for mail-order fulfillment.
- Mail Order:USPS-delivered 90-day supplies through PBM-affiliated fulfillment centers, capturing volume from retail displacement.
- In-Store Pickup:Same-day retrieval at retail locations for acute prescriptions and urgent needs.
- Online:Digital ordering platforms with fulfillment through centralized or local pharmacy partners.
In-store pickup retains the largest share; home delivery is gaining share fastest as senior demographic preferences harden.
Service Type:
Margin structure separates commodity dispensing from clinical service reimbursement under CMS fee schedules.
- Medication Therapy Management:Comprehensive medication reviews and adherence interventions billable under Medicare Part D. Texas and California pharmacists are capturing this revenue stream as scope-of-practice expansions enable independent billing.
- Immunization Services:Vaccine administration embedded in federal pharmacy partnership programs, permanently integrating retail locations into preventive care networks.
- Pharmaceutical Consultation:Drug information and interaction screening provided at dispensing counter.
- Counseling:Patient education on therapy initiation, side effect management, and lifestyle modification.
Immunization services hold the largest share; medication therapy management shows the steepest expansion trajectory as reimbursement codes mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medicare-eligible populations cluster in Sun Belt migration corridors, while DSCSA compliance timelines concentrate investment in high-volume distribution hubs. State-level scope-of-practice laws and Medicaid expansion status reshape pharmacy service economics across sub-regional markets.
Texas
Rural access gaps and chronic disease prevalence drive telepharmacy satellite deployment in underserved counties. The state's Medicaid managed care expansion intensifies 340B program participation among safety-net hospitals. Houston and Dallas-Fort Worth anchor specialty pharmacy automation infrastructure serving oncology and rare disease networks.
Florida
Senior migration from the Northeast sustains prescription volume growth in Tampa and Orlando metro areas. Florida's pharmacy board enforces DSCSA serialization deadlines ahead of federal minimums, accelerating wholesaler technology upgrades. Miami-Dade medical groups concentrate limited distribution network access for high-cost biologics.
California
Scope-of-practice expansion enables independent pharmacist billing for medication therapy management in Los Angeles and San Francisco Bay Area clinics. The state's 340B program oversight shapes hospital outpatient pharmacy strategy. Sacramento policy debates on drug pricing transparency influence PBM contract negotiations statewide.
Arizona
Medicare Advantage penetration rates exceed national averages, driving mail-order channel preference among Phoenix and Tucson retirees. The state's pharmacy partnership programs embed retail locations into federal vaccine distribution networks. Northern Arizona telepharmacy pilots address Navajo Nation access disparities.
New York
Medicaid pharmacy benefit carve-outs reshape reimbursement flows for New York City and Long Island independent operators. The state's clinical pharmacist legislation enables hospital discharge medication reconciliation services. Albany regulatory pressure on PBM spread pricing intensifies contract scrutiny across the Northeast corridor.
US Pharmacy Market Vendor Landscape
Channel-controlling players compete with product-specialist players across vertically integrated and standalone operational models. The US pharmacy sector exhibits tiered consolidation where national chains and PBM-affiliated networks capture volume share while regional grocers and independents defend local density. Two strategic archetypes dominate: scale-driven formulary controllers and community-anchored service specialists. Competitive intensity manifests through central fill automation deployment and clinic partnership expansion rather than price-based confrontation.
Among vertically integrated healthcare conglomerates, CVS Health Corporation, UnitedHealth Group, and Cigna occupy positions exemplifying the PBM-pharmacy convergence archetype. These entities represent the formulary-control model where benefit design steers patient flow toward captive dispensing channels. Regional grocery-anchored operators including H-E-B, Publix, and Wegmans sit within a distinct tier emphasizing front-of-store integration and immunization accessibility. Walmart Inc. and Walgreens Boots Alliance anchor scale-driven community presence, with the former emphasizing price transparency and rural footprint density while the latter leverages clinic partnership networks. Express Scripts exemplifies the standalone PBM specialty pharmacy model focused on mail-order fulfillment and limited distribution network management.
| Leading Market Players |
|---|
| Walmart Inc. |
| Express Scripts |
| CVS Health Corporation |
| Publix |
| Wegmans |
| Walgreens Boots Alliance |
| UnitedHealth Group |
| H-E-B |
| Cigna |
| Others |
Supply Flow & Price Mechanics
Indianapolis distribution hub capacity constraints are tightening generic dispensing margins as wholesale consolidation concentrates negotiating leverage among three national distributors. DSCSA-mandated serialization infrastructure is passing through as per-unit handling surcharges, compressing reimbursement-adjusted yields for independent operators.
Pricing Analysis
Cost-plus contracts with named indexation to CMS reimbursement schedules dominate PBM-pharmacy agreements, locking dispensing fees to federal benchmark adjustments. Price differentiation hinges on formulary tier placement and 340B eligibility status, with covered entities capturing spread between acquisition cost and reimbursement rates. Pricing pressure stems from direct and indirect remuneration fee recalculations squeezing generic margins. Cash-pay patients exhibit highest price sensitivity; specialty biologic users show lowest.
Supply Chain Analysis
Export-control regimes limiting active pharmaceutical ingredient flows from China and India are forcing domestic manufacturers to qualify secondary sources for critical starting materials. Supply chains draw from Chinese chemical intermediates, Indian API synthesis, and US finished dose manufacturing. Single-source vulnerability concentrates in oncology injectable APIs. Distribution runs through wholesale distributors operating DSCSA-compliant track-and-trace platforms before retail or mail-order fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
US pharmacy operations face high-growth disruption as IRA Medicare price negotiation timelines force portfolio restructuring across PBM formularies and specialty pharmacy networks.
For Market Incumbents: Build central fill automation moats to separate patient-facing clinical services from back-of-house fulfillment economics. Deploy telepharmacy-enabled satellite locations in Texas rural counties to preempt access-gap competitors. Capture medication therapy management reimbursement codes before scope-of-practice expansion saturates clinical pharmacist billing markets. For New Entrants and Emerging Players: Rural Arizona counties with Medicare Advantage penetration above national averages represent the most penetrable entry point for mail-order channel disruption. Target 340B-eligible safety-net hospital partnerships in California as anchor tenant relationships. Pursue limited distribution network access for oncology biologics as differentiation wedge against commodity dispensing competitors. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among PBM-affiliated specialty pharmacies with captive patient steerage through formulary design. Five-to-ten year viability favors vertically integrated healthcare conglomerates controlling benefit design, pharmacy fulfillment, and clinical service delivery. Monitor IRA negotiation timeline announcements as inflection signal for specialty drug portfolio revaluation.| Strategic Initiative | Industry Significance |
|---|---|
| Central Fill Automation Deployment | CVS Health and Walgreens separate fulfillment from clinical services to reduce labor intensity. |
| Telepharmacy Satellite Expansion | H-E-B and regional grocers address Texas rural access gaps with remote pharmacist oversight. |
| Medication Therapy Management Billing | California scope-of-practice expansion enables independent pharmacist reimbursement under Medicare Part D. |
| 340B Program Participation | Safety-net hospitals in Texas leverage drug pricing discounts for outpatient pharmacy margin capture. |
| Limited Distribution Network Access | Specialty pharmacies in Miami-Dade secure oncology biologic dispensing rights from manufacturer gatekeeping. |
Methodological Framework
Initial hypotheses were tested against primary input from pharmacy benefit managers, retail chain formulary directors, hospital 340B program administrators, and independent pharmacist owners and refined through secondary validation against FDA DSCSA guidance documents, CMS Medicare Part D utilization data, state board of pharmacy enforcement records, and wholesale distributor SEC filings. Bottom-up prescription volume modeling triangulated against top-down healthcare expenditure benchmarks.
Demand-supply balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning product type, customer type, delivery mode, and service type plus state-level regulatory cluster differentiation. CAGRs derived from trend extrapolation of Medicare enrollment growth, chronic disease prevalence trajectories, and channel shift elasticity estimates for mail-order penetration among senior populations.
Macroeconomic conditions sit as an overlay; deviation in CMS reimbursement schedule timing or IRA negotiation implementation pace would shift the trajectory. Forecasts reflect assumptions around DSCSA compliance cost pass-through rates and pharmacist workforce availability. Material shifts in federal pharmacy partnership program funding or state scope-of-practice legislation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Opioid Induced Constipation Drug Market
Pharmaceuticals
Hard Gelatin Capsules Market
Pharmaceuticals
Asia-Pacific Sodium-Dependent Glucose Cotransporter 2 (SGLT-2) Market
Pharmaceuticals
Intravenous (IV) Iron Drugs Market
Pharmaceuticals
Europe Vaccines Market
Pharmaceuticals
Vaginal Antifungals Market
Pharmaceuticals
North America Adenomyosis Drugs Market
Pharmaceuticals
US Oral Solid Dosage Contract Manufacturing Market
Pharmaceuticals
Small Molecule Innovator CDMO Market
Pharmaceuticals
Esomeprazole Market
Pharmaceuticals
Oncology Small Molecule Drugs Market
Pharmaceuticals
Global Dengue Vaccine Market
Pharmaceuticals
Compound Acetaminophen Market
Pharmaceuticals
Multiple System Atrophy (MSA) Therapeutics Market
Pharmaceuticals
Global Electronic Aspirin Market
Pharmaceuticals
Global Anti-Suicide Drugs Market