
 Retail Clinics Market | 2026-2036
Retail Clinics Market Size, Share, and Industry Trends Forecast 2026-2036
Retail Clinics Market Intelligence
Expansion by major pharmacy chains and supercenters in the United States is realigning the market for accessible primary care. CVS Health Corporation leverages its vast retail footprint to embed HealthHUB locations offering a broader scope of services. Walgreens Boots Alliance Inc. competes through its partnership and investment in VillageMD primary care clinics. Walmart Inc. operates its own health centers, focusing on price transparency and accessibility in key suburban and rural markets.
Retail clinics are walk-in healthcare facilities, often located in pharmacies or grocery stores, staffed by nurse practitioners or physician assistants. They provide a limited, transparently priced menu of services for common acute illnesses and preventive care. The model's core function is offering convenient, affordable access for minor medical issues. Among service types, vaccinations and health screenings constitute high-volume traffic drivers, while chronic disease management is an expanding segment targeting insured members.
Clinic operations in the United States must adhere to the Health Insurance Portability and Accountability Act (HIPAA) for patient data privacy. European counterparts navigate the General Data Protection Regulation (GDPR), which governs health information management. These standards dictate the architecture of digital health record systems. Strategic decisions for providers now center on balancing service scope expansion with the capital costs of geographic footprint growth.
Market Dynamics
The central force is consumer demand for convenient, affordable, and transparently priced healthcare. This shift pressures traditional primary care models by offering accessible alternatives for non-emergency and preventive services in retail environments.
Growth Catalysts
- Consumer Convenience:Demand from working professionals for accessible vaccinations, health screenings, and minor illness treatment outside of traditional office hours drives clinic traffic.
- Technology Integration:The adoption of electronic health records (EHR) and telehealth platforms improves care coordination and enables virtual consultations, extending the clinic's reach.
- Cost-Containment Pressure:In the United States, high-deductible health plans encourage patients to seek lower-cost care options for common acute conditions.
Market Restraints
- Scope-of-Practice Laws:State-level regulations in the United States restricting the autonomy of nurse practitioners and physician assistants can limit the menu of available services.
- Capital Investment:Establishing new clinics, equipping them with medical devices, and integrating EHR systems require significant upfront capital expenditure.
- Care Continuity Concerns:Traditional healthcare systems often present retail clinics as a source of fragmented care, creating a barrier to patient trust.
Strategic Opportunities
- Geographic Expansion:Markets outside the United States, such as Canada and the United Kingdom, present opportunities where healthcare systems face similar access and cost pressures.
- Service Line Extension:Moving beyond acute care into managing chronic conditions like hypertension or diabetes for specific patient populations represents a key growth vector.
- Digital Health Integration:Combining in-person visits with remote patient monitoring and telehealth follow-ups creates a more continuous care model.
Industry Challenges
- Talent Acquisition:A competitive labor market for qualified nurse practitioners and physician assistants, particularly in underserved areas, creates staffing and wage pressures.
- System Interoperability:Ensuring data exchange between a clinic's EHR and a patient's primary provider or hospital system remains a major technical hurdle.
- Building Patient Trust:Shifting consumer perception from viewing clinics as only for transactional needs to a trusted source for ongoing care requires proven outcomes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retail Clinics Market |
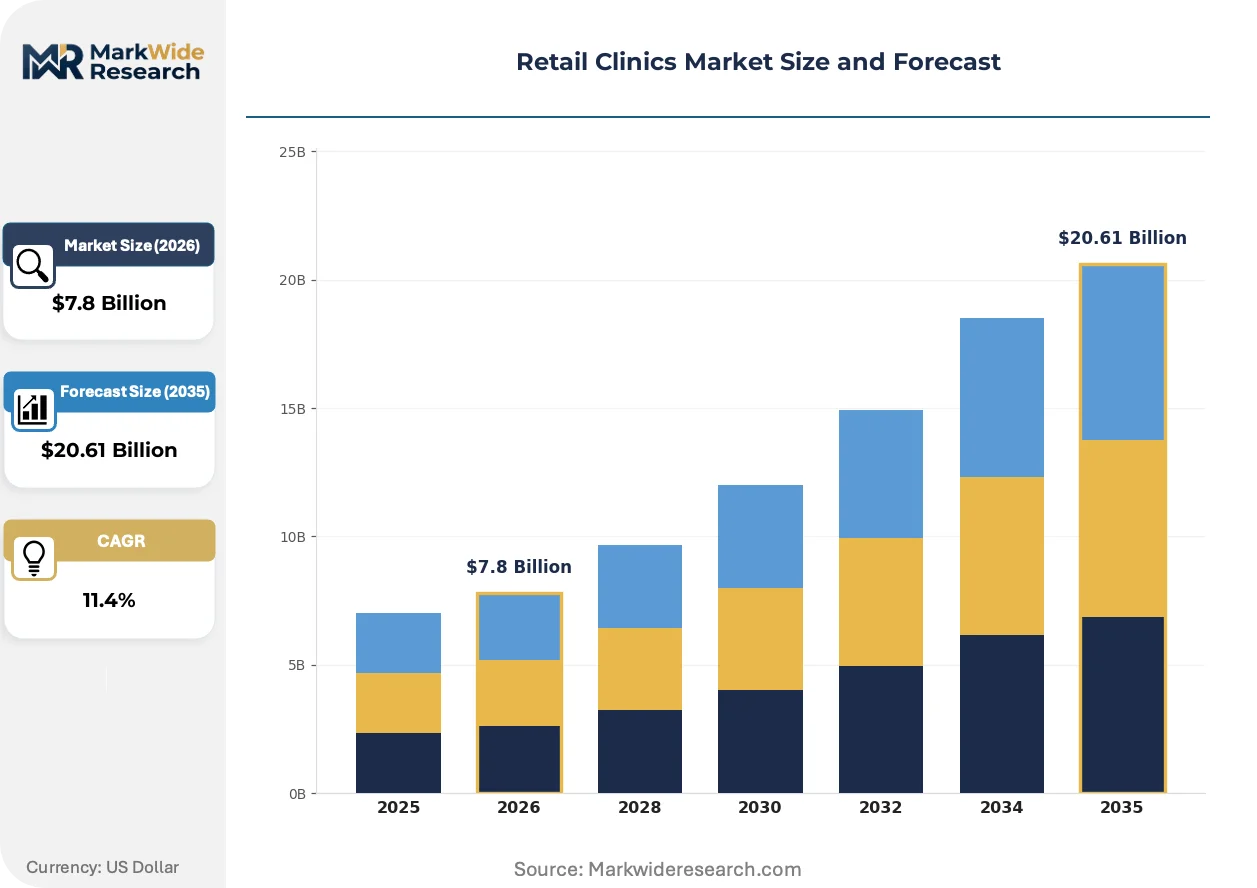
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $20.61 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Vaccination, Preventive Care, Chronic Disease Management, Health Screening, Minor Injury Treatment Customer Type: Walk-in Patients, Insured Members, Senior Citizens, Working Professionals, Families Clinic Size: Small, Medium, Large, Mobile Units, Automated Kiosks Distribution Channel: Pharmacy Chains, Grocery Stores, Malls, Standalone Clinics, Supercenters |
| Companies Covered | The Kroger Co., AtlantiCare, CVS Health Corporation, Rite Aid Corporation, Aurora Health Care, Walgreens Boots Alliance Inc., Target Brands Inc., NextCare Urgent Care, Walmart Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retail Clinics Market Strategic Shifts & Innovations
The evolution of retail clinics is defined by a strategic expansion of service capabilities, enabled by digital tools. This transition moves the model from providing purely episodic care towards establishing more continuous patient relationships.
Telehealth platforms provide the core technology for virtual consultations and remote patient follow-ups. Adoption is highest among younger consumers and individuals in suburban areas who value convenience over traditional appointment structures. The fusion of virtual services with physical locations is expanding into hybrid care models addressing both acute needs and health management.
Strict data privacy regulations, including the US Health Insurance Portability and Accountability Act (HIPAA) and Europe's GDPR, govern health information. These rules influence the architecture of digital health record systems and dictate security protocols for telehealth. Operators in the United States are most impacted by varying state-level scope-of-practice laws determining services nurse practitioners can offer.
Consumer demand for transparent, upfront pricing is changing healthcare purchasing behavior. This preference for clear cost structures challenges the complex billing of traditional providers, favoring the retail clinic's menu-based price list. The shift is most visible in the United States, where high-deductible insurance plans make patients sensitive to out-of-pocket expenses.
Retail Clinics Market Segmentation
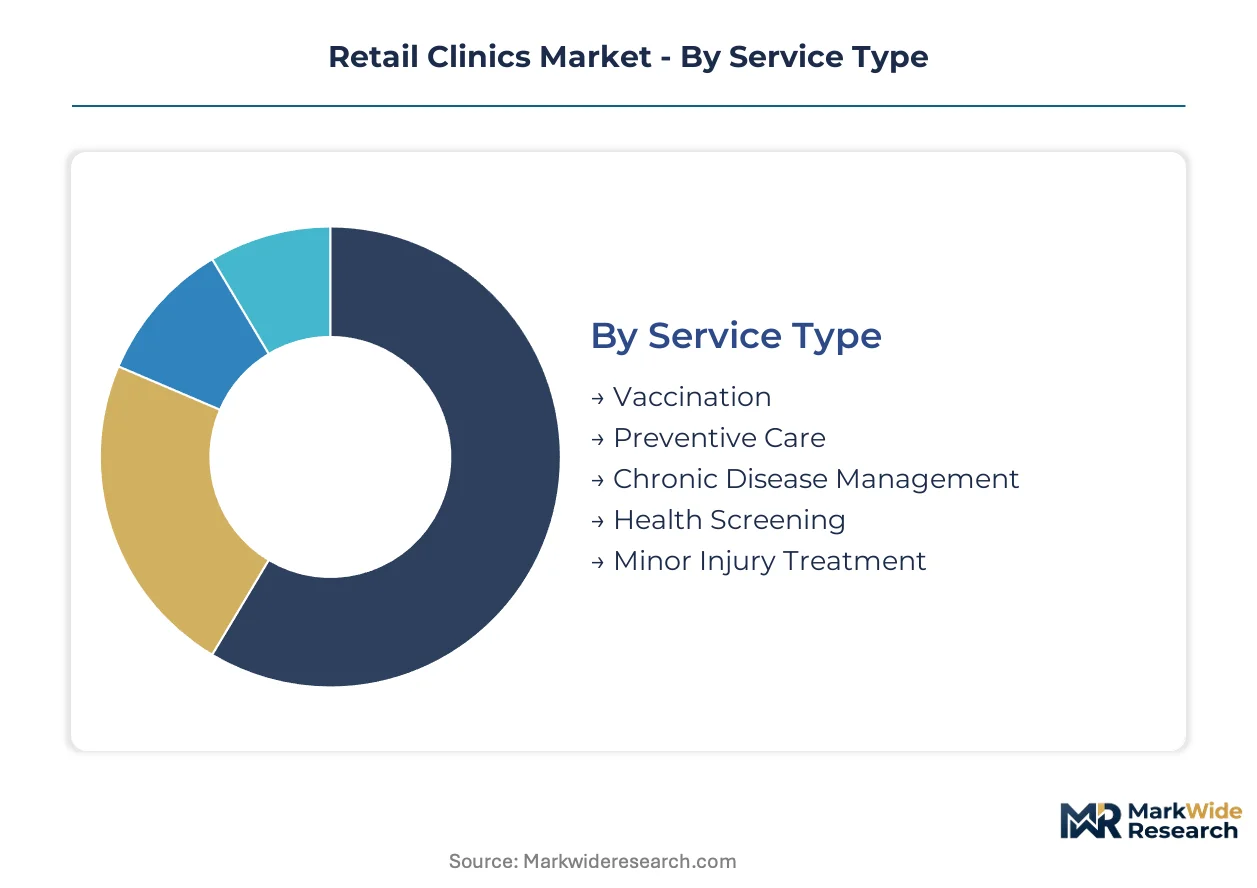
Retail clinics serve diverse patient needs and operate through varied models, making market segmentation critical for understanding demand drivers and strategic positioning. This detailed breakdown highlights how service offerings, customer demographics, clinic infrastructure, and distribution channels shape competitive dynamics.
Service Type:
The supply of retail clinic services often concentrates around immediate, high-volume patient needs, influencing operational specialization and resource allocation.
- Vaccination:These services involve the administration of immunizations for various infectious diseases, including influenza, tetanus, and HPV, providing crucial public health benefits. Working professionals in the United States frequently seek convenient seasonal flu shots, often driven by employer mandates or personal health priorities.
- Preventive Care:This category encompasses services focused on maintaining health and preventing illness, such as routine wellness exams, blood pressure checks, and cholesterol screenings. Families in Canada increasingly seek accessible health check-ups at retail clinics to manage long-term health and identify potential issues early.
- Chronic Disease Management:This segment provides ongoing support for individuals with long-term conditions like diabetes or hypertension, often incorporating remote monitoring and regular follow-ups.
- Health Screening:These services offer quick assessments for the early detection of various health conditions, including basic blood pressure and glucose level checks.
- Minor Injury Treatment:This service type addresses non-life-threatening issues such as small cuts, sprains, minor burns, and insect bites, offering immediate care alternatives to emergency rooms.
Vaccination absorbs the bulk of installed capacity; Chronic Disease Management is expanding most quickly.
Customer Type:
Customer demand patterns dictate service offerings and operational strategies across distinct patient demographics within the retail clinic market.
- Walk-in Patients:These individuals seek immediate medical attention without prior appointments for acute, non-emergency conditions such as colds, flu, or minor infections. Consumers in suburban areas of the United States prioritize convenience for these minor ailments, valuing the accessibility of retail clinics.
- Insured Members:This group comprises patients whose healthcare services are covered by various health insurance plans, often seeking care for chronic condition management or preventive services. Individuals in the United Kingdom increasingly utilize employer-sponsored health benefits for routine check-ups and follow-up care at integrated retail health locations.
- Senior Citizens:This demographic requires accessible care for age-related health concerns, including routine screenings, medication management, and chronic disease support.
- Working Professionals:These individuals seek convenient healthcare options that seamlessly fit into demanding schedules, often for vaccinations, minor illnesses, or quick health screenings.
- Families:This customer segment represents households requiring accessible care for both children and adults, including pediatric vaccinations, common illnesses, and school physicals.
Walk-in Patients represent a foundational revenue stream; Insured Members are increasingly driving service line expansion.
Clinic Size:
Operational scale directly influences the range of services and capital investment required for retail clinic establishments across various market segments.
- Small:These compact facilities are typically integrated within existing retail spaces, offering a limited menu of high-volume services like vaccinations and basic acute care. High-density urban centers in Germany often see these clinics emerge where space is at a premium for quick patient access.
- Medium:These facilities provide a broader range of services, including basic diagnostics, minor injury treatment, and multiple exam rooms to accommodate more complex patient needs. Suburban communities in Australia increasingly require these more comprehensive primary care alternatives due to growing population density.
- Large:This segment includes extensive health centers offering expanded services, potentially incorporating imaging, laboratory services, and specialty consultations, often within supercenter environments.
- Mobile Units:These portable clinics deliver healthcare services to underserved or remote populations, significantly improving access for individuals with transportation barriers.
- Automated Kiosks:These self-service stations provide basic health screenings, vital sign measurements, and sometimes telehealth connectivity, enhancing convenience for quick health checks.
Investment capital flows primarily into Medium-sized clinics; Mobile Units are gaining share fastest in access-constrained regions.
Distribution Channel:
Market penetration and geographic reach vary significantly across different retail clinic distribution channels, impacting consumer accessibility.
- Pharmacy Chains:Clinics co-located within drugstores leverage existing customer traffic and strong brand recognition to offer convenient, accessible healthcare services. CVS Health and Walgreens Boots Alliance in the United States utilize their extensive networks for primary care integration, expanding their health offerings.
- Supercenters:Large retail stores host comprehensive health centers, often providing a wide array of services from primary care to dental, at competitive and transparent prices. Walmart Inc. operates its health centers in key suburban and rural markets, focusing on price transparency and accessibility for local communities.
- Grocery Stores:Clinics situated within supermarkets offer convenient health services alongside daily shopping needs, appealing to consumers seeking integrated solutions for their errands.
- Malls:Healthcare facilities located in shopping centers cater to consumer convenience and high foot traffic, providing accessible care during leisure or shopping trips.
- Standalone Clinics:These independent retail health facilities are not directly affiliated with a larger retail chain, often offering specialized services or broader primary care in community settings.
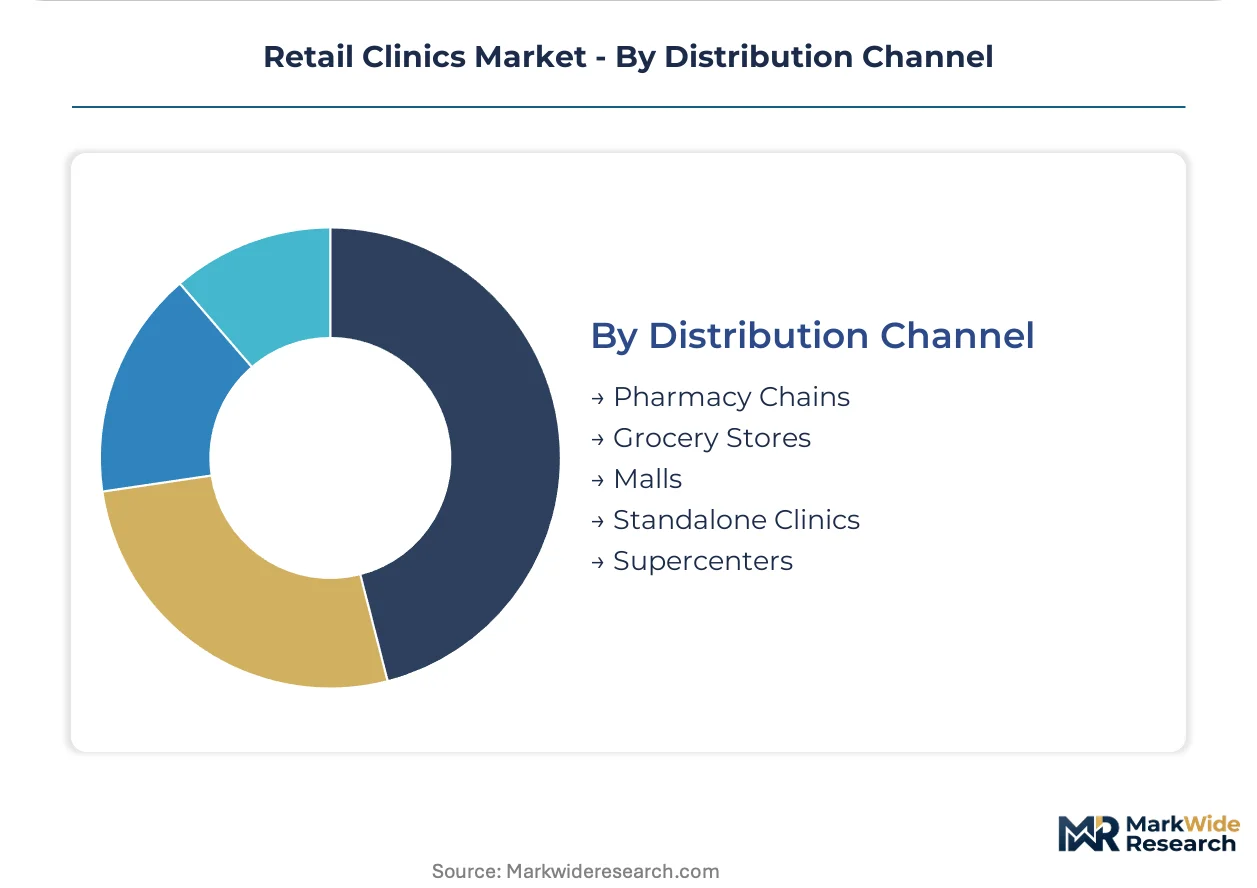
The operational footprint of Pharmacy Chains is extensive; Supercenters show the steepest expansion trajectory for integrated health services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States anchors the global retail clinics market, driving innovation in service delivery and patient access. This market expansion reflects consumer demand for convenient, affordable healthcare options. Other developed economies also experience similar pressures, leading to diverse regional growth patterns.
United States
Consumer demand for accessible vaccinations and minor illness treatment drives significant clinic traffic in the United States. High-deductible health plans encourage patients to seek lower-cost care options for common acute conditions. Major pharmacy chains and supercenters in suburban population centers, such as those operated by CVS Health and Walmart, are rapidly expanding their footprints.
Canada
Families increasingly seek accessible health check-ups and preventive care at retail clinics across Canada. Health Canada regulations influence service offerings and operational standards for these facilities. Toronto and Vancouver metropolitan areas see growing integration of retail clinics within grocery stores and pharmacies.
United Kingdom
Insured members in the United Kingdom increasingly utilize employer-sponsored health benefits for routine check-ups and follow-up care. The National Health Service (NHS) framework shapes how private retail clinics integrate with existing primary care. London and other major urban centers are experiencing growth in integrated retail health locations.
Germany
High-density urban centers in Germany see emerging small clinics for quick patient access and basic acute care. European data protection regulations like GDPR dictate health information management for all operators. Berlin and Munich districts are witnessing the integration of compact retail health facilities within commercial hubs.
Australia
Suburban communities in Australia increasingly require comprehensive primary care alternatives due to growing population density. The Therapeutic Goods Administration (TGA) oversees medical device and pharmaceutical approvals for clinic use. Sydney and Melbourne's expanding suburbs show a demand for medium-sized clinics offering broader services.
Retail Clinics Market Key Industry Players
Global majors compete with regional champions across service scope and geographic reach, influencing market dynamics. The market structure exhibits a tiered consolidation, with large retail corporations and established healthcare systems dominating key segments. Strategic archetypes include integrated pharmacy-health hubs, supercenter-based clinics, and specialized urgent care networks focusing on specific patient needs. Dominant competitive moves involve aggressive geographic expansion into underserved areas and strategic partnerships with local providers to enhance service continuity.
Integrated pharmacy-health operators, such as CVS Health Corporation and Walgreens Boots Alliance Inc., exemplify the model of leveraging existing retail footprints for healthcare delivery. These entities anchor the market's expansion into convenient, accessible primary care services. Walmart Inc. occupies a position among supercenter-based providers, emphasizing price transparency and broad accessibility in suburban and rural markets. These companies represent distinct approaches to capturing consumer demand for retail health solutions.
| Leading Market Players |
|---|
| The Kroger Co. |
| AtlantiCare |
| CVS Health Corporation |
| Rite Aid Corporation |
| Aurora Health Care |
| Walgreens Boots Alliance Inc. |
| Target Brands Inc. |
| NextCare Urgent Care |
| Walmart Inc. |
| Others |
Cost & Logistics Intelligence
Vertical integration by major pharmacy chains anchors their supply position for common medical supplies and dictates their transparent pricing power for basic services. This strategic control minimizes procurement costs and enables competitive, upfront pricing for consumers seeking convenient care options.
Pricing Analysis
Service bundling for preventive care and vaccinations shapes retail clinic pricing. The dominant model is per-unit transactional, with clear menu pricing for specific services. Price differentiation stems from the scope of services offered and the clinic's brand premium. Pricing pressure intensifies from high-deductible health plans in the United States. Walk-in patients are most price-sensitive; insured members are less so for covered services.
Supply Chain Analysis
Reverse logistics for medical waste and expired pharmaceuticals presents a specialized supply chain challenge. Geographic supply concentration for medical devices and diagnostic kits draws from China, Germany, and the United States. Key component dependencies include microprocessors for EHR systems and specialized reagents for diagnostic tests. Single-source vulnerability for proprietary software platforms poses a structural risk. Distribution runs through established medical distributors to clinic locations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The retail clinics market represents a consolidation play, as capital investment requirements for technology integration increasingly force smaller, independent operators out of business.
For Market Incumbents: Anchor comprehensive service offerings around chronic disease management to counter the threat of specialized urgent care networks. Leverage existing retail footprints for geographic expansion, particularly in underserved rural markets, as a key lever for market share growth.
For New Entrants and Emerging Players: HIPAA in the United States opens a window for specialized telehealth providers targeting specific underserved populations. Focus on digital health integration within suburban areas, offering hybrid care models for health screenings. Target the working professionals segment with transparent, subscription-based preventive care plans.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by large pharmacy chains or integrated health systems. The market demonstrates long-term viability over the next decade due to persistent consumer demand for convenience. Monitor the increasing adoption of value-based care models as an inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Telehealth Integration | This enhances patient access to virtual consultations, extending clinic reach. |
| Acquire Regional Clinic Networks | This consolidates market share and expands geographic footprint in key suburban areas. |
| Develop Chronic Care Programs | This captures recurring revenue streams from insured members with long-term conditions. |
| Invest in EHR Interoperability | This improves care coordination with traditional healthcare providers, building patient trust. |
| Broaden Service Scope | This attracts a wider customer base beyond acute care, increasing clinic utilization. |
Research Approach
Government health reports, academic journals, and industry association publications formed the secondary backbone, complemented by primary interviews. Discussions with clinic administrators, nurse practitioners, insurance providers, and retail executives provided critical insights. This approach ensured robust bottom-up and top-down triangulation of market data.
Bottom-up analysis aggregated demand across service types, customer demographics, and clinic sizes. The forecast framework modeled market growth across the analysis window by segmenting data by service type, customer type, and distribution channel. Compound annual growth rates were derived from historical data trends and projected adoption rates, considering technology integration as a key input.
Caveats apply where shifts in healthcare policy or new technology adoption could materially shift the outlook. Forecasts reflect assumptions regarding consumer behavior and regulatory stability. Practitioners should monitor state-level scope-of-practice law changes for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Healthcare Patent Filing Outsourcing Market
Healthcare Services
Prescription Delivery Services Market
Healthcare Services
Hospice Market
Healthcare Services
Escort Bed Sharing Market
Healthcare Services
Healthcare CMO Market
Healthcare Services
Primary Care Physicians Market
Healthcare Services
Kids Sports Injury Treatment Market
Healthcare Services
Hospital Workforce Management Market
Healthcare Services
Hair Transplant Services Market
Healthcare Services
Global Concierge Medicine Market
Healthcare Services
Medical Billing Outsourcing Market
Healthcare Services
Healthcare Revenue Cycle Management (RCM) Outsourcing Market
Healthcare Services
Aged Care Market
Healthcare Services
Tissue Banking Market
Healthcare Services
Healthcare Staffing Market
Healthcare Services
Biopharmaceutical Third Party Logistics (3PL) Market