
 Global Urgent Care Center Market | 2026-2036
Global Urgent Care Center Market Size, Share, and Industry Trends Forecast 2026-2036
Global Urgent Care Center Market Foresight
Telehealth infrastructure is repositioning capital allocation across the urgent care sector. Concentra, Inc. anchors occupational health service lines through employer-direct contracts and workplace injury management protocols. American Family Care leverages franchised expansion to saturate Sun Belt metropolitan areas with standardized clinical workflows. NextCare Holdings, Inc. competes on geographic density in Texas and Arizona through medium-center formats optimized for throughput.
An urgent care center delivers episodic, non-emergency medical services for conditions requiring immediate attention but lacking life-threatening severity, typically operating with extended hours, on-site diagnostic imaging, and point-of-care laboratory capabilities without appointment requirements. Walk-in and telehealth service types command the highest patient volume flows, while appointment-based models capture more complex diagnostic testing revenue with better payer mix profiles. Medium centers and large facilities concentrate margin pools through scale economies in laboratory processing and imaging asset utilization, whereas small clinics face pressure from rising real estate and staffing costs.
FDA oversight of clinical laboratory improvement amendments shapes diagnostic testing capabilities and quality benchmarks for on-site laboratories. CMS reimbursement frameworks directly determine service line profitability and site selection economics for new center development. OSHA workplace health regulations sustain employer demand for occupational health service integration. Stakeholders must monitor state-level scope-of-practice expansions for nurse practitioners and physician assistants as these policies reshape staffing models and geographic reach.
Market Dynamics
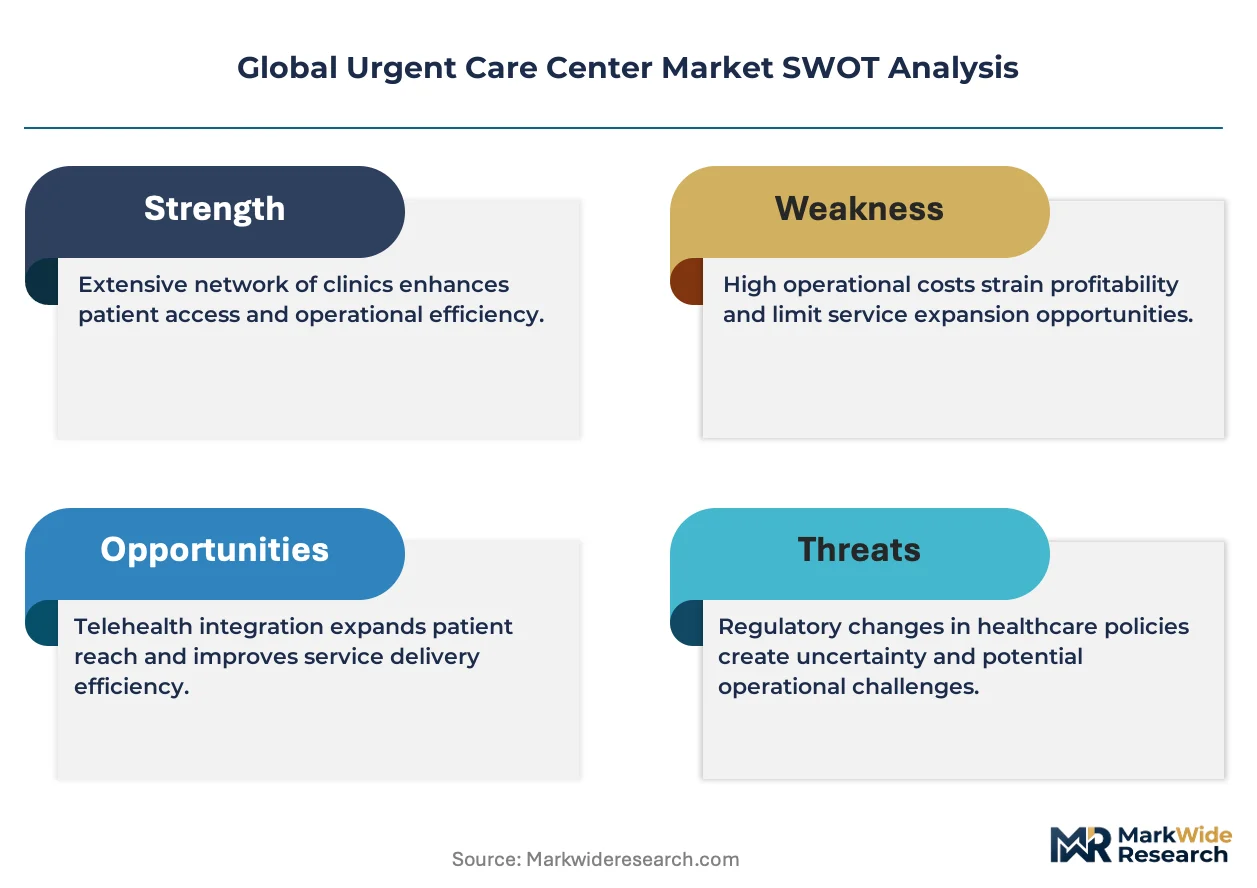
CMS reimbursement parity for telehealth services is compressing capital cycles and forcing urgent care operators to reallocate fixed assets toward hybrid delivery infrastructure. This structural shift rewards platforms with existing digital connectivity while penalizing brick-and-only footprints.
Growth Catalysts
- Employer-Direct Contracting:Large self-insured employers in the United States are channeling occupational health volume toward urgent care networks to capture workers' compensation cost savings and reduce emergency department leakage.
- Scope-of-Practice Expansion:State-level legislative reforms across Texas, Arizona, and Florida now permit nurse practitioners to practice independently, extending clinical capacity into physician-scarce suburban corridors without proportional payroll expansion.
- Point-of-Care Diagnostics:CLIA-waived testing platforms are compressing laboratory turnaround times and capturing revenue previously referred to hospital outpatient departments.
Market Restraints
- Real Estate Cost Escalation:Prime retail corridor rents in Sun Belt metropolitan areas are absorbing 18-24% of center-level revenue, constraining small-format clinic viability.
- Physician Supply Concentration:Graduate medical education placement remains concentrated in Northeast and Midwest academic medical centers, creating persistent hiring friction for Southwest and Southeast expansion targets.
- Reimbursement Compression:Commercial payer rate negotiations are narrowing fee-for-service margins and privileging vertically integrated health system competitors with captive insurance assets.
Strategic Opportunities
- Employer Onsite Integration:Manufacturing and logistics campuses in Mexico's northern border states present white-space demand for occupational health-urgent care hybrid models serving maquiladora workforces.
- Medicaid Managed Care Penetration:State-level Medicaid expansion in North Carolina and Georgia is creating new covered lives pools with assigned primary care gaps that urgent care networks can capture through payer partnerships.
- AI-Enabled Triage Convergence:Natural language processing symptom checkers are converging with telehealth intake workflows to automate acuity stratification and optimize in-person capacity utilization.
Industry Challenges
- Interoperability Fragmentation:Electronic health record integration with hospital emergency departments and primary care networks requires costly custom interfaces that delay network participation agreements.
- Credentialing Cycle Length:Commercial payer enrollment timelines extending 90-180 days post-construction completion compress cash flow during ramp-up phases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Urgent Care Center Market |
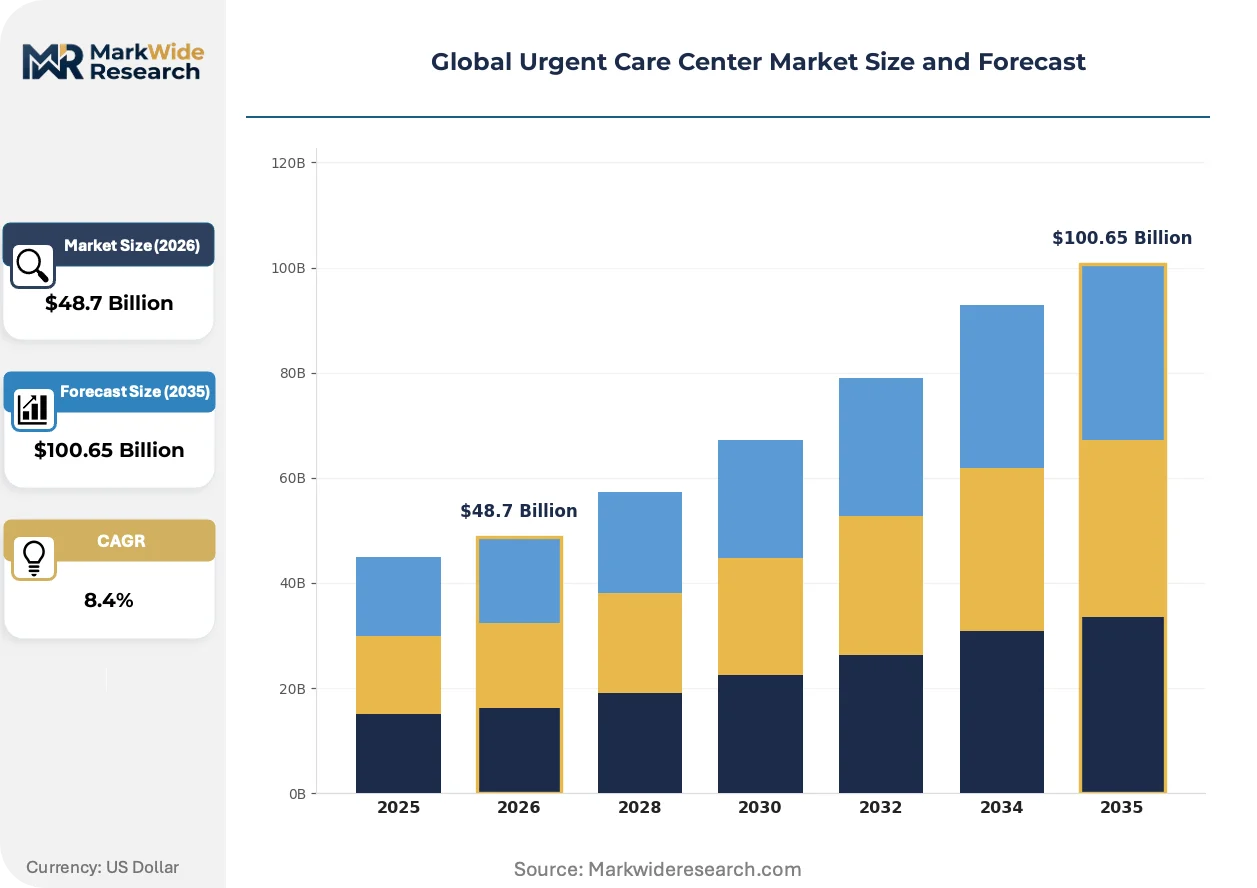
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $100.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Walk-in, Appointment-Based, Telehealth, Mobile Urgent Care, Occupational Health Application: Minor Injuries, Acute Illnesses, Diagnostic Testing, Preventive Care, Vaccination, Physical Exams End User: Working Professionals, Students, Senior Citizens, Military Personnel, Travelers Facility Size: Small Clinics, Medium Centers, Large Facilities, Multi-Specialty Complexes |
| Companies Covered | Concentra, Inc., American Family Care, NextCare Holdings, Inc., FastMed Urgent Care, GoHealth Urgent Care, MedExpress, Patient First, CareSpot Express Healthcare LLC, CityMD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Urgent Care Center Market Shifts & Advancements
Digital front-door strategies are displacing traditional walk-in dependency and forcing urgent care operators to compete on appointment accessibility rather than convenience alone. This transformation privileges technology-forward platforms with capital reserves for platform development.
Remote patient monitoring devices are converging with urgent care intake protocols to enable pre-visit data capture for chronic condition flare-ups. Hypertensive and diabetic patient panels are adopting connected glucometers and blood pressure cuffs at accelerating rates. This convergence is compressing the diagnostic phase of episodic visits and shifting clinical staff time toward intervention rather than assessment.
REACH regulation in the European Union is tightening requirements for disinfectant and medical device sterilization chemistry used in clinical settings. The industrial consequence is a forced reformulation of surface cleaning protocols and supply chain requalification for imported consumables. German and French urgent care networks are responding by consolidating procurement through GPOs with dedicated regulatory compliance functions.
Consumer switching behavior is compressing loyalty cycles as patients treat urgent care as a commodity service selected through real-time availability displays on payer apps and Google Maps. Employer-sponsored populations are replacing traditional primary care attachment with urgent care-first navigation models. This pattern is most visible in Dallas-Fort Worth and Phoenix metropolitan statistical areas where digital-native competitors have saturated locational search results.
Global Urgent Care Center Market Segmentation
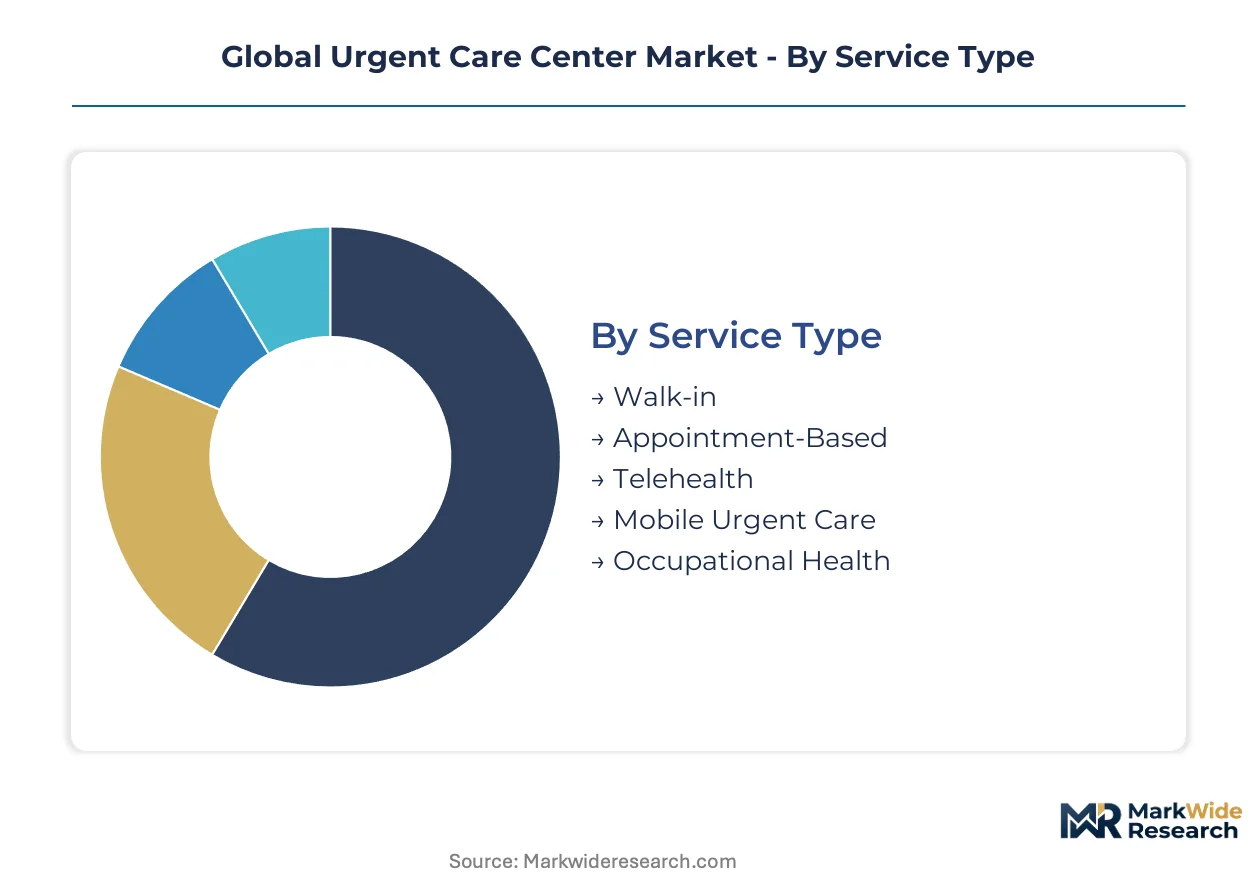
Urgent care segmentation reveals how capital allocation, staffing models, and reimbursement frameworks diverge across service delivery modes. Each dimension captures distinct margin structures and geographic concentration patterns that shape operator strategy.
Service Type:
Patient choice dynamics center on immediacy versus relationship continuity, with digital access now resetting baseline expectations.
- Walk-in:Unscheduled episodic visits for acute conditions dominate volume in suburban corridors. Demand concentrates in Dallas-Fort Worth and Phoenix where physician shortages and employer density converge.
- Telehealth:CMS reimbursement parity has compressed capital cycles toward hybrid infrastructure. This segment captures routine consultations and follow-up care previously requiring physical presence, with CMS frameworks determining profitability.
- Appointment-Based:Scheduled slots accommodate complex diagnostic workups and better payer mix profiles.
- Mobile Urgent Care:Deployable units serve rural gaps and event-based demand.
- Occupational Health:Employer-direct contracts anchor revenue stability through workplace injury protocols.
Volume sits with Walk-in; growth tilts toward Telehealth.
Application:
Clinical acuity stratification determines staffing ratios, equipment requirements, and referral patterns to hospital systems.
- Minor Injuries:Fractures, lacerations, and sprains drive same-day visit volume with high throughput potential. Demand clusters near manufacturing and logistics corridors where workplace incidents concentrate.
- Diagnostic Testing:CLIA-waived point-of-care platforms capture laboratory revenue previously referred to hospital outpatient departments. This application expands fastest where payer steerage programs narrow network options.
- Acute Illnesses:Respiratory and gastrointestinal infections sustain baseline utilization.
- Preventive Care:Screening services extend patient lifetime value.
- Vaccination:Seasonal demand spikes require flexible capacity planning.
- Physical Exams:Employment and sports clearance requirements generate predictable scheduling.
Minor Injuries commands visit frequency; Diagnostic Testing delivers margin expansion.
End User:
Demographic targeting shapes location strategy, hours of operation, and payer contract priorities.
- Working Professionals:Employer-sponsored populations favor urgent care-first navigation over traditional primary care attachment. This cohort drives evening and weekend utilization in Charlotte and Austin suburban nodes.
- Senior Citizens:Medicare Advantage penetration creates covered lives pools with chronic condition monitoring needs. Demand concentrates where supplemental benefits cover transportation and care coordination.
- Students:Campus-adjacent locations capture seasonal illness clusters.
- Military Personnel:TRICARE contracts require specific credentialing and compliance protocols.
- Travelers:Airport and highway corridor sites capture episodic demand.
Working Professionals anchor volume density; Senior Citizens expand per-visit revenue.
Facility Size:
Capital intensity and operating leverage separate viable footprints from margin-constrained competitors.
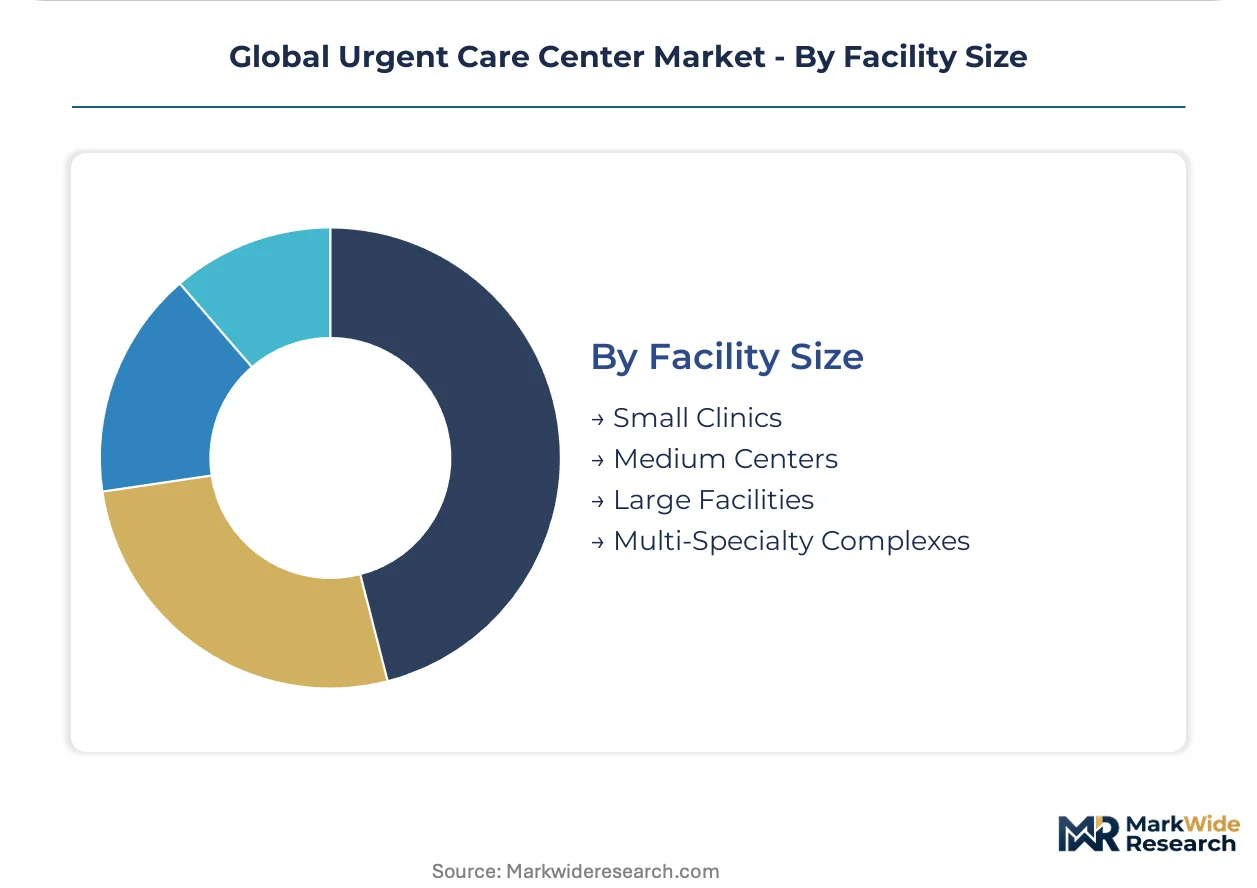
- Medium Centers:Optimized throughput formats balance imaging asset utilization with staffing efficiency. These facilities concentrate in Texas and Arizona where Concentra and NextCare deploy geographic density strategies.
- Large Facilities:Multi-modal service integration captures laboratory and imaging economies at scale. Real estate requirements limit deployment to primary retail corridors with 18-24% revenue absorption tolerance.
- Small Clinics:Limited service menus face pressure from rising rents and staffing costs.
- Multi-Specialty Complexes:Vertical integration with primary and specialty care extends patient capture.
Medium Centers dominate unit economics; Large Facilities claim margin pools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Employer-sponsored health plans concentrate urgent care demand in suburban corridors where physician shortages intersect with population density growth. The United States anchors volume expansion through occupational health integration and CMS reimbursement frameworks. Germany, Japan, and the United Kingdom follow with distinct regulatory and delivery model configurations.
United States
Self-insured employers in Dallas-Fort Worth and Phoenix channel workers' compensation volume toward urgent care networks to capture emergency department cost savings. CMS reimbursement parity for telehealth services accelerates hybrid infrastructure deployment. Suburban nodes surrounding Charlotte and Austin concentrate new center development where digital-native competitors saturate locational search results.
Germany
REACH regulation tightens disinfectant chemistry requirements for clinical sterilization protocols, forcing supply chain requalification for imported consumables. German urgent care networks consolidate procurement through GPOs with dedicated regulatory compliance functions. Industrial clusters in North Rhine-Westphalia and Bavaria integrate occupational health services through employer-direct contracts with manufacturing workforces.
Japan
Aging demographics expand Medicare-equivalent covered lives pools with chronic condition monitoring needs through the Ministry of Health, Labour and Welfare frameworks. METI guidelines on digital health infrastructure accelerate telehealth platform adoption. Tokyo and Osaka metropolitan areas concentrate facility development where supplemental benefits cover transportation and care coordination for senior citizens.
United Kingdom
NHS England procurement frameworks determine service line profitability and site selection economics for new center development in Greater London and the Southeast. The Care Quality Commission shapes diagnostic testing capabilities and quality benchmarks for on-site laboratories. Private urgent care operators compete for NHS contracts through outcome-based payment structures in Manchester and Birmingham corridors.
Canada
Health Canada oversight of medical device licensing shapes point-of-care diagnostic platform deployment across provincial health systems. Ontario and British Columbia concentrate employer-sponsored demand where manufacturing and technology campuses require occupational health integration. Vancouver and Toronto suburban nodes face physician supply friction from graduate medical education concentration in academic medical centers.
Global Urgent Care Center Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with employer-direct networks capturing occupational health volume and franchised platforms saturating metropolitan corridors. The vendor base organizes around three strategic archetypes: occupational health-anchored networks, franchised expansion platforms, and geographic density specialists. Consolidation pressure favors operators with captive insurance assets and vertical integration into laboratory processing. M&A activity targets medium-center formats with optimized throughput economics, while strategic partnerships accelerate digital front-door deployment.
Within the employer-direct tier, Concentra, Inc. and MedExpress exemplify networks capturing workers' compensation cost savings through workplace injury management protocols. Among franchised expansion platforms, American Family Care occupies a position representing standardized clinical workflow deployment across Sun Belt metropolitan areas. NextCare Holdings, Inc. anchors the geographic density archetype, sitting within the Texas and Arizona concentration where medium-center formats optimize throughput for suburban corridor demand.
| Leading Market Players |
|---|
| Concentra, Inc. |
| American Family Care |
| NextCare Holdings, Inc. |
| FastMed Urgent Care |
| GoHealth Urgent Care |
| MedExpress |
| Patient First |
| CareSpot Express Healthcare LLC |
| CityMD |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up urgent care specialists anchor supply behavior through centralized procurement consortia while exerting pricing discipline across employer-direct contracts and CMS-reimbursed service lines. Their ownership structure compresses vendor negotiation cycles and standardizes clinical supply specifications across multi-state footprints, directly linking capital allocation efficiency to margin preservation in competitive metropolitan corridors.
Pricing Analysis
Volume concentrates in walk-in episodic visits while margins accrue to appointment-based diagnostic testing with superior payer mix profiles. Three-tier pricing structure across premium employer-direct contracts, standard commercial insurance rates, and economy Medicaid managed care tiers stratifies revenue per encounter. Pricing pressure stems from commercial payer rate compression privileging vertically integrated health system competitors with captive insurance assets. Self-insured employers exhibit lowest price sensitivity due to workers' compensation cost savings capture, while uninsured and high-deductible plan holders drive commodity shopping behavior through real-time availability platforms.
Supply Chain Analysis
CLIA-waived point-of-care device certification gates supplier qualification and limits sourcing flexibility for diagnostic platforms. Manufacturing concentrates in the United States, Germany, and Japan for imaging equipment and laboratory analyzers, while disposable consumables draw from Mexico and China assembly operations. Single-source vulnerability runs through semiconductor-dependent diagnostic device controllers and specialized reagent chemistries. Distribution runs through group purchasing organizations with dedicated regulatory compliance functions serving multi-site urgent care networks, supplemented by direct manufacturer relationships for high-velocity consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Urgent care operators face a vertical-integration race where backward integration into laboratory processing and captive payer relationships determines sustainable margin capture. Control over diagnostic revenue streams and employer-direct contracting infrastructure represents the decisive competitive lever.
For Market Incumbents: Lock in employer-direct relationships through occupational health service integration and workplace injury management protocol standardization. Expand CLIA-waived point-of-care testing menus to capture laboratory revenue previously referred to hospital outpatient departments. Defend against telehealth-native competitors by accelerating hybrid infrastructure deployment before CMS reimbursement frameworks shift further toward digital-first models. For New Entrants and Emerging Players: Capture Medicaid managed care expansion corridors in North Carolina and Georgia where assigned primary care gaps create covered lives pools accessible through payer partnerships. Target manufacturing and logistics campuses in Mexico's northern border states with occupational health-urgent care hybrid models serving maquiladora workforces. Deploy AI-enabled triage convergence as a differentiated digital front-door strategy to automate acuity stratification and optimize in-person capacity utilization. For Investors and Strategic Acquirers: CMS telehealth reimbursement parity legislation is the leading indicator that hybrid infrastructure deployment separates viable platforms from brick-and-mortar-constrained competitors. Medium-center formats with optimized throughput economics in Texas and Arizona represent priority acquisition archetypes for geographic density strategies. A model refresh is warranted upon material change in state-level scope-of-practice expansion timelines for nurse practitioners and physician assistants.| Strategic Initiative | Industry Significance |
|---|---|
| Employer-Direct Contracting Expansion | Captures workers' compensation volume and reduces emergency department leakage for self-insured employers. |
| CLIA-Waived Testing Menu Expansion | Retains laboratory revenue previously referred to hospital outpatient departments under CMS frameworks. |
| Hybrid Telehealth Infrastructure Deployment | Positions operators for CMS reimbursement parity while compressing capital cycles toward digital connectivity. |
| Geographic Density Concentration | Optimizes throughput economics in suburban corridors surrounding Dallas-Fort Worth and Phoenix. |
| AI-Enabled Triage Integration | Automates acuity stratification and improves in-person capacity utilization for episodic demand. |
Research Methodology
Document review covered CMS reimbursement frameworks, FDA CLIA waiver databases, and state-level scope-of-practice legislation, complemented by interviews with urgent care network executives, occupational health service directors, GPO procurement managers, and commercial payer contracting specialists. Secondary validation drew from hospital procurement databases, employer benefits plan filings, and real estate development records for suburban retail corridor transactions. Bottom-up center-level economics triangulated against top-down market sizing across service type, facility size, and geographic concentration dimensions.
Historical volume trajectories cross-referenced against panel input from clinical operations leaders and payer strategy officers informed the analytical framework across the projection horizon. Segmentation modeling incorporated service delivery mode, clinical application, end-user demographic, and facility format dimensions with regional regulatory cluster variations. CAGRs derived from weighted average of demand elasticity assumptions and reimbursement framework evolution patterns, with specific inputs from telehealth adoption curves and employer-sponsored plan design shifts.
The model holds under stable CMS reimbursement parity and state-level scope-of-practice expansion trajectories; deviation in commercial payer rate negotiations or physician supply concentration would shift center-level viability thresholds. Forecasts reflect documented assumptions regarding employer health plan cost-containment priorities and suburban population density migration patterns. A model refresh is warranted upon material change in FDA diagnostic device oversight or OSHA workplace health regulation enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Healthcare CRO Services Market
Healthcare Services
US Retail Clinics Market
Healthcare Services
Private Healthcare Market
Healthcare Services
US Healthcare Third-Party Logistics Market
Healthcare Services
US Primary Care Physicians Market
Healthcare Services
Global Hospice Care Market
Healthcare Services
UK Pharmaceutical Logistics Market
Healthcare Services
Asia-Pacific Healthcare Cold Chain Logistics Market
Healthcare Services
Ambulatory Healthcare Service Market
Healthcare Services
Long Term Care Market
Healthcare Services
Funeral and Cremation Services Market
Healthcare Services
IVD Contract Manufacturing Services Market
Healthcare Services
Spa Services Market
Healthcare Services
Assisted Living Market
Healthcare Services
Inhaled and Intranasal Products Contract Service Providers Market
Healthcare Services
US Care Services Market