
 US Population Health Management Market | 2026-2036
US Population Health Management Market Size, Share, and Industry Trends Forecast 2026-2036
US Population Health Management Market Intelligence
Subscription-based software-defined analytics is restructuring how population health contracts get priced and renewed. Optum, Inc. leverages its vertically integrated payer-provider data assets to dominate risk-adjustment modeling for Medicare Advantage plans. Oracle anchors enterprise-scale cloud deployments that unify electronic health records with claims data across multi-hospital systems. Cedar Gate Technologies specializes in bundled-payment analytics, competing directly with legacy platforms through outcome-based contracting structures.
Population health management encompasses the aggregation and analysis of clinical, financial, and operational data across defined patient cohorts to improve outcomes and reduce per-capita costs, typically leveraging HL7 FHIR interoperability standards and predictive risk-scoring algorithms. Its primary commercial purpose is enabling providers and payers to transition from fee-for-service reimbursement to value-based care models. Care management platforms currently occupy the largest margin pool as health systems invest in nurse-led care coordination workflows. Cloud-based deployment is displacing on-premises infrastructure fastest among mid-size provider groups seeking lower capital overhead. Patient engagement solutions remain fragmented, though employers increasingly demand these tools as part of self-insured benefit design.
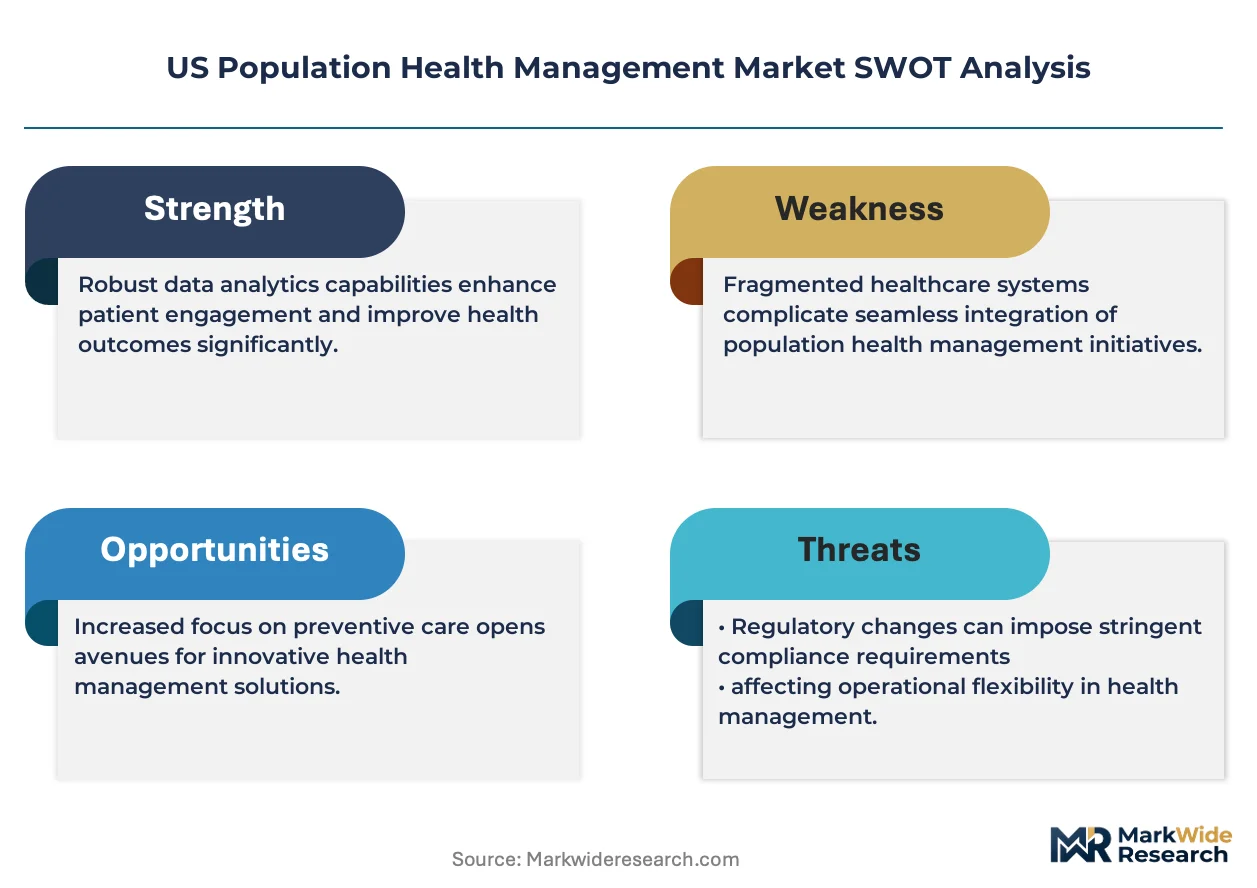
CMS, ONC, and state Medicaid agencies collectively shape market access through interoperability mandates, quality reporting requirements, and value-based payment program eligibility criteria. The 21st Century Cures Act's information-blocking provisions force vendors to open application programming interfaces, lowering switching costs for health systems. Stakeholders must monitor how CMS Innovation Center payment models evolve and whether state Medicaid agencies adopt similar risk-sharing structures.
Market Dynamics
CMS Innovation Center payment models are forcing provider systems into risk-bearing arrangements faster than their data infrastructure can adapt, creating a structural bottleneck where clinical workflow redesign lags behind contractual obligations.
Growth Catalysts
- ACO REACH Model:Medicare's direct contracting pathway accelerates provider participation in downside-risk arrangements, expanding the addressable base for care management platforms.
- Texas Medicaid Expansion:State-level managed care proliferation in Texas and Florida generates demand for unified analytics bridging inpatient and ambulatory data streams.
- HL7 FHIR Interoperability:Federal mandates for standardized data exchange lower integration barriers between disparate electronic health record systems.
Market Restraints
- Cloud Infrastructure Concentration:Dependence on three hyperscale providers for HIPAA-compliant hosting creates single-point-of-failure risk for mid-size health systems.
- 21st Century Cures Act Compliance:Information-blocking enforcement raises vendor development costs while accelerating client switching cycles.
- Legacy EHR Technical Debt:Proprietary data architectures in incumbent hospital systems resist API-based interoperability, fragmenting patient longitudinal records.
Strategic Opportunities
- Behavioral Health Integration:Unmet demand for substance use and mental health care coordination within Medicare Advantage plans creates white space for specialized analytics modules.
- Social Determinants Data Layer:Housing instability and food insecurity screening tools remain underdeveloped relative to clinical risk stratification capabilities.
- Remote Patient Monitoring Convergence:Wearable device data streams merging with claims analytics enable real-time intervention triggers for chronic disease cohorts.
Industry Challenges
- Data Science Talent Scarcity:Health systems compete with technology firms for machine learning engineers capable of building clinically validated predictive models.
- Workflow Integration Complexity:Care management platforms require 18-24 month implementation cycles to retrain nursing staff and redesign patient touchpoint protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Population Health Management Market |
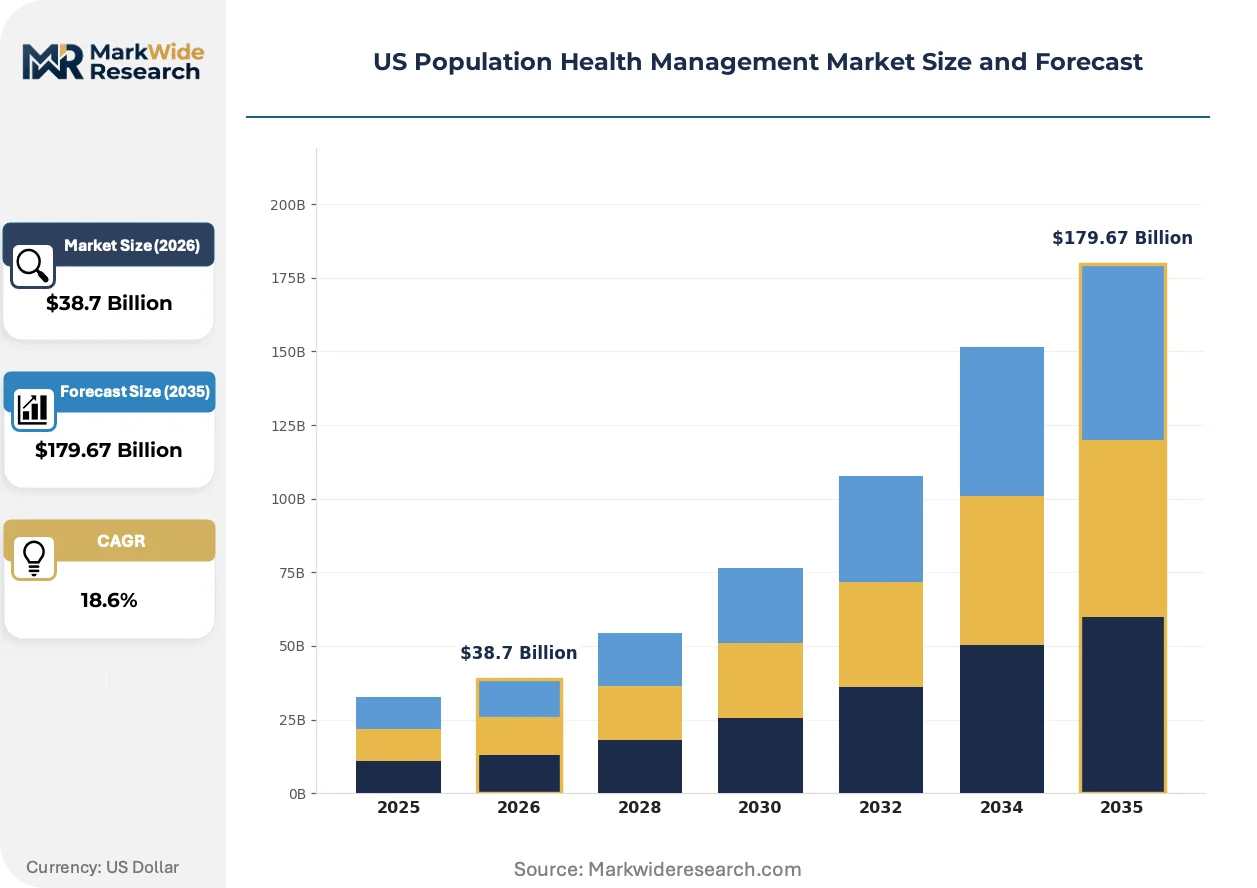
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $179.67 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Data Analytics, Care Management Platforms, Patient Engagement Solutions, Reporting Tools End User: Healthcare Providers, Payers, Government Bodies, Employers Deployment: Cloud-Based, On-Premises, Hybrid, Mobile Solutions Application: Chronic Disease Management, Preventive Care, Population Stratification, Health Risk Assessment |
| Companies Covered | Optum, Inc., Oracle, Veradigm LLC, eClinicalWorks, Conifer Health Solutions, LLC, Cedar Gate Technologies, McKesson Corporation, Athenahealth, Inc., Health Catalyst, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Population Health Management Market Strategic Shifts & Innovations
Real-time data streaming architectures are compressing the latency between clinical events and care team interventions, while regulatory pressure on algorithmic transparency is reshaping how predictive models get deployed in production environments.
Artificial intelligence-based risk stratification engines are absorbing unstructured clinical notes, social determinants data, and claims history into unified patient risk scores. Integrated delivery networks in Texas and Florida are deploying these tools within nurse-led care coordination workflows. The technology is absorbing tasks previously performed by manual chart review, reallocating clinical labor toward high-touch patient engagement.
CMS Innovation Center's mandatory health equity benchmarks in ACO REACH are forcing providers to stratify outcomes by race, ethnicity, and disability status. Vendors must now embed demographic auditing capabilities into their analytics platforms or face program ineligibility. Medicare Advantage plans serving diverse urban populations are responding fastest, investing in supplementary data collection infrastructure to meet reporting requirements.
Employer-sponsored self-insured plans are unbundling patient engagement solutions from traditional carrier offerings, contracting directly with specialized vendors for chronic disease management. This disintermediation bypasses payer intermediaries and redirects data ownership toward large employers. Manufacturing and logistics employers in the Midwest are pioneering this model, driven by high prevalence of diabetes and musculoskeletal conditions in their workforces.
US Population Health Management Market Segmentation
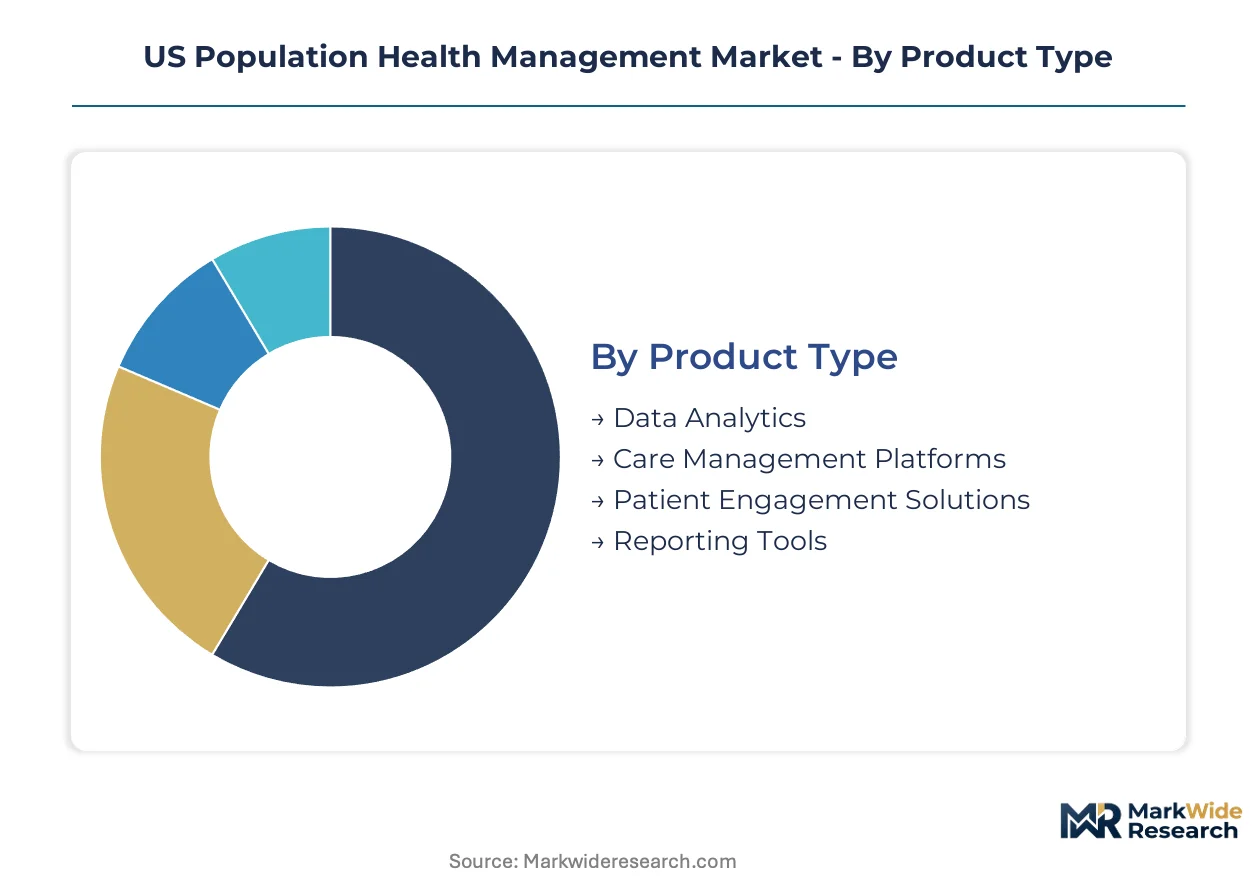
Population health management vendors structure product portfolios around four distinct axes: clinical workflow depth, risk-bearing contract readiness, data infrastructure maturity, and care setting integration. Each segmentation dimension reflects a different buyer calculus—health systems prioritize care management platforms for nursing workflow redesign, while payers demand analytics engines calibrated to Medicare Advantage risk adjustment.
Product Type:
Standardization dominates data analytics and reporting tools, whereas care management platforms and patient engagement solutions require extensive customization to match nursing protocols and employer benefit designs.
- Data Analytics:Risk-scoring algorithms process claims history, electronic health record feeds, and social determinants data into stratified patient cohorts. Texas and Florida integrated delivery networks are consolidating vendor contracts around unified platforms that bridge inpatient and ambulatory data streams.
- Care Management Platforms:Nurse-led workflow engines automate care coordination tasks including appointment scheduling, medication adherence tracking, and transition-of-care handoffs. ACO REACH participants in Medicare's direct contracting pathway are deploying these tools to meet downside-risk obligations.
- Patient Engagement Solutions:Employer self-insured plans in the Midwest are unbundling these capabilities from traditional carrier offerings to address diabetes and musculoskeletal conditions in manufacturing workforces.
- Reporting Tools:CMS-mandated quality metrics and health equity benchmarks require automated extraction capabilities from disparate clinical sources.
Leading the category by volume: Data Analytics. Expanding most quickly: Care Management Platforms.
End User:
Procurement sophistication varies sharply across this dimension—government bodies enforce strict interoperability mandates while employers prioritize cost-containment metrics over clinical integration depth.
- Healthcare Providers:Health systems in Texas and Florida are expanding value-based care contracts with payers, driving demand for platforms that unify analytics across hospital and ambulatory settings. Implementation cycles stretch 18-24 months for nursing workflow redesign.
- Payers:Medicare Advantage plans require risk-adjustment modeling calibrated to hierarchical condition category scoring, with health equity stratification now mandatory under ACO REACH benchmarks.
- Government Bodies:CMS Innovation Center payment models and state Medicaid agencies shape vendor eligibility through interoperability mandates and quality reporting requirements.
- Employers:Self-insured manufacturing and logistics firms are contracting directly with chronic disease management vendors, bypassing payer intermediaries to retain data ownership.
Dominating procurement volume: Healthcare Providers. Gaining share fastest: Employers.
Deployment:
Cost tier structures this category—cloud-based options minimize capital overhead for mid-size groups while hybrid architectures serve health systems with legacy technical debt.
- Cloud-Based:HIPAA-compliant hyperscale hosting displaces on-premises infrastructure fastest among mid-size provider groups seeking operational expenditure models over capital investment.
- On-Premises:Incumbent hospital systems with proprietary EHR architectures maintain these deployments to preserve existing security protocols and data governance frameworks.
- Hybrid:Split architectures house protected health information on-premises while pushing analytics workloads to cloud environments for scalability.
- Mobile Solutions:Care team applications enable point-of-care documentation and real-time patient communication for field-based nursing staff.
Capturing the largest installed base: Cloud-Based. Steepest expansion trajectory: Hybrid.
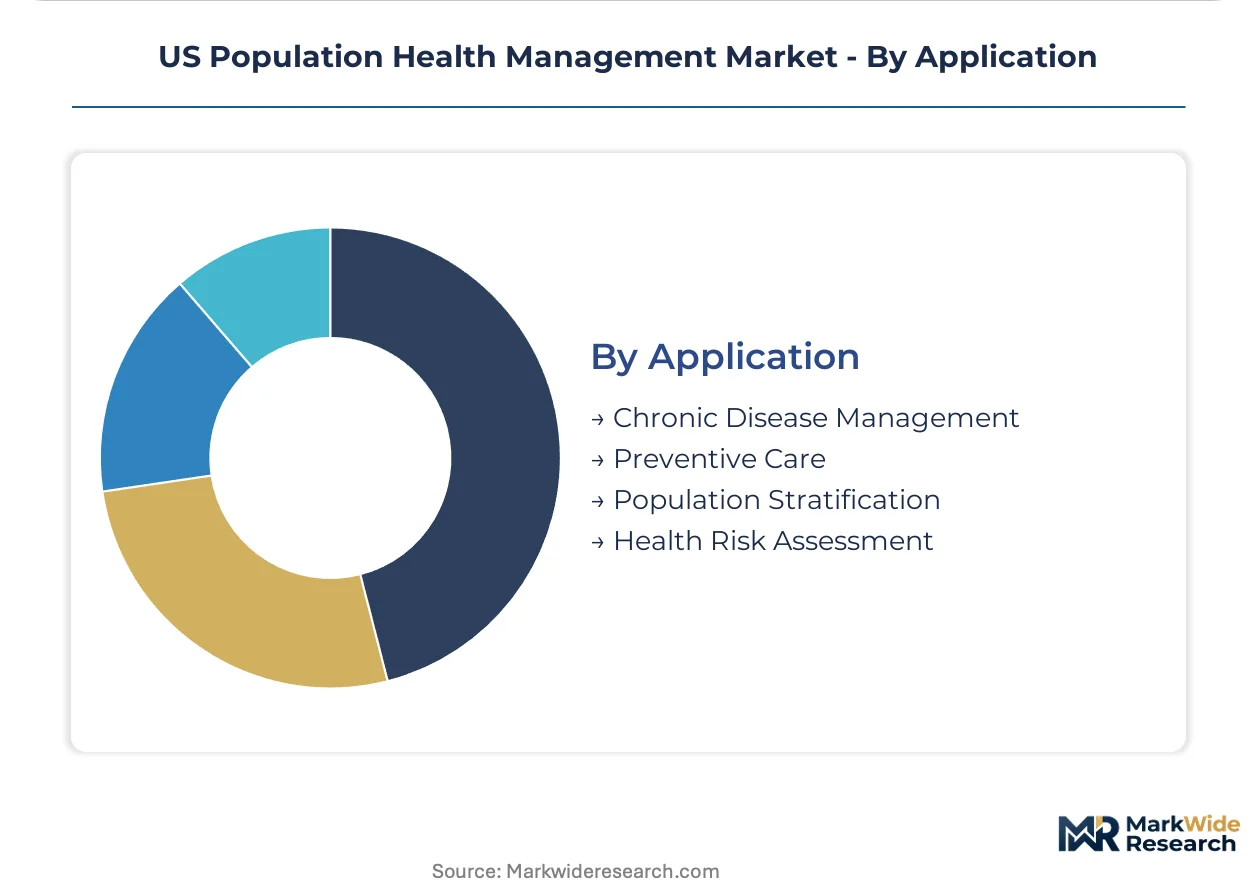
Application:
Maturity gradients separate this category—chronic disease management commands established budgets while population stratification tools represent emerging investment priorities.
- Chronic Disease Management:Diabetes, heart failure, and COPD programs absorb the majority of care management platform spending, with remote patient monitoring convergence enabling real-time intervention triggers.
- Preventive Care:Wellness initiatives and screening outreach target cost avoidance upstream of acute events, particularly in employer-sponsored plans.
- Population Stratification:Risk-scoring engines aggregate clinical, financial, and operational data to prioritize high-cost patient cohorts for intervention.
- Health Risk Assessment:Substance use and mental health screening tools remain underdeveloped relative to clinical capabilities, creating white space for specialized analytics modules.
Highest current spending: Chronic Disease Management. Climbing the fastest: Population Stratification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greater Boston anchors the nation's population health management innovation corridor, hosting dense clusters of health technology startups and academic medical centers piloting value-based care models. Texas and Florida health systems are expanding risk-bearing contracts fastest, while California's integrated delivery networks drive enterprise-scale analytics adoption.
Texas
Texas Medicaid managed care proliferation generates concentrated demand for unified analytics bridging inpatient and ambulatory data streams. The state's Health and Human Services Commission mandates interoperability standards for Medicaid managed care organizations. Dallas-Fort Worth and Houston medical centers are deploying care management platforms to meet downside-risk obligations under Medicare Advantage contracts.
Florida
Florida's Medicare Advantage penetration and retiree population density create robust demand for risk-adjustment modeling and care coordination tools. The state's Agency for Health Care Administration enforces quality reporting requirements for Medicaid managed care plans. The Tampa Bay and South Florida corridors host expanding value-based care contracts between health systems and commercial payers.
California
California's integrated delivery networks invest heavily in cloud-based analytics unifying electronic health records across multi-hospital systems. The Department of Managed Health Care enforces strict data exchange standards for commercial payers. The Bay Area and Los Angeles Basin concentrate vendor development activity and health system procurement for population stratification tools.
New York
New York's Medicaid redesign initiatives and large self-insured employer base drive demand for patient engagement and chronic disease management solutions. The state's Department of Health oversees value-based payment reforms for Medicaid managed care. The New York City metro area anchors procurement for behavioral health integration modules serving diverse urban populations.
Midwest Manufacturing Belt
Self-insured manufacturing and logistics employers across Ohio, Michigan, and Illinois contract directly with chronic disease management vendors to address diabetes and musculoskeletal conditions. The region lacks dominant regulatory bodies but follows CMS Innovation Center payment models. Chicago and Detroit serve as procurement hubs for employer-sponsored population health initiatives bypassing traditional payer intermediaries.
US Population Health Management Market Key Industry Players
Capital-heavy health systems compete with asset-light software vendors for control of analytics infrastructure and care coordination workflows. The vendor base stratifies into three tiers: vertically integrated payer-provider conglomerates, specialized care management platform developers, and legacy electronic health record incumbents expanding into risk-bearing contract support. Dominant competitive moves include strategic partnerships between analytics vendors and cloud hyperscalers, plus portfolio diversification into behavioral health and social determinants screening capabilities.
Within the vertically integrated tier, Optum, Inc. and Oracle exemplify contrasting approaches to market positioning—one leveraging captive payer data assets, the other anchoring enterprise cloud deployments. Cedar Gate Technologies occupies a specialized position in bundled-payment analytics. These three entities represent the strategic archetypes shaping competitive dynamics: payer-affiliated platforms, infrastructure-scale cloud providers, and outcome-based contracting specialists.
| Leading Market Players |
|---|
| Optum, Inc. |
| Oracle |
| Veradigm LLC |
| eClinicalWorks |
| Conifer Health Solutions, LLC |
| Cedar Gate Technologies |
| McKesson Corporation |
| Athenahealth, Inc. |
| Health Catalyst, Inc. |
| Others |
Cost & Logistics Intelligence
ACO REACH downside-risk obligations are compressing procurement timelines for mid-size health systems, forcing vendors to absorb implementation costs upfront and compress SaaS margins across care management platforms.
Pricing Analysis
Margin tightening in cloud-based deployments reflects hyperscale hosting concentration among three providers. Subscription tiers stratify across enterprise, mid-market, and ambulatory levels, with customization depth and HL7 FHIR certification grade driving spreads. Cost-down pressure on nurse-led workflow modules accelerates because health systems demand outcome-based contracting structures. Mid-size provider groups exhibit highest price sensitivity, while integrated delivery networks prioritize clinical integration depth over per-seat costs.
Supply Chain Analysis
Machine learning engineer scarcity in Greater Boston and the Bay Area constrains predictive model development capacity for specialized analytics vendors. Software development draws from India, Ireland, and domestic US technology corridors. Cloud infrastructure rests on hyperscale data centers in Virginia, Oregon, and Ohio. Single-source vulnerability in HIPAA-compliant hosting creates concentration risk. Distribution runs through direct enterprise sales teams and health system GPO contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around vendors with captive payer data assets and cloud-scale infrastructure, as 21st Century Cures Act compliance costs force sub-scale platforms toward exit.
For Market Incumbents: Extend risk-adjustment modeling capabilities into behavioral health integration modules before specialized entrants capture Medicare Advantage white space. Deepen upstream control over social determinants data partnerships to lock in health system switching costs. Counter Cedar Gate Technologies' bundled-payment analytics through outcome-based contracting guarantees. For New Entrants and Emerging Players: Launch via direct employer contracts in the Midwest Manufacturing Belt, bypassing payer intermediaries to capture self-insured chronic disease management budgets. Target substance use and mental health screening tools, where clinical capabilities lag demand from ACO REACH health equity benchmarks. Lead with remote patient monitoring convergence as the go-to-market wedge. For Investors and Strategic Acquirers: Re-rating potential sits with specialized care management platform developers given CMS Innovation Center payment model acceleration. Five-to-ten year viability favors vendors with proven 18-24 month implementation cycles and nurse workflow redesign expertise. Monitor Texas Medicaid managed care procurement volumes as the inflection signal for addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| HL7 FHIR Interoperability Certification | CMS mandates open APIs, lowering health system switching costs and accelerating vendor consolidation. |
| Behavioral Health Module Development | Medicare Advantage plans seek substance use analytics to meet ACO REACH health equity benchmarks. |
| Social Determinants Data Partnership | Housing instability screening tools remain underdeveloped relative to clinical risk stratification capabilities. |
| Cloud Hyperscaler Strategic Partnership | HIPAA-compliant hosting agreements reduce capital overhead for mid-size provider group deployments. |
| Direct Employer Contract Channel | Midwest manufacturing firms bypass payers to retain chronic disease management data ownership. |
Research Approach
CMS Medicare data, hospital procurement databases, and GPO contracts formed the secondary backbone, cross-referenced with primary interviews involving care management platform executives, health system chief medical information officers, Medicare Advantage plan actuaries, and state Medicaid agency technology leads. Bottom-up and top-down triangulation validated vendor revenue estimates against health system IT spending disclosures.
Historical trendline analysis tracked subscription revenue growth across deployment models, with segmentation dimensions including clinical workflow depth, risk-bearing contract readiness, data infrastructure maturity, and care setting integration. CAGRs were derived from modeled adoption curves for cloud-based platforms and care management workflow engines. Forecast inputs incorporated ACO REACH participation trajectories and Texas Medicaid managed care expansion timelines.
CMS payment model cancellation, hyperscale provider service disruptions, and health system merger freezes are the dominant revision risks. Forecasts reflect assumptions regarding interoperability mandate enforcement and value-based contract penetration. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Data Management
Healthcare Archiving and Ediscovery Market
Health Data Management
Population Health Management Platforms Market
Health Data Management
Global Healthcare Quality Management Market
Health Data Management
AI Training Dataset in Healthcare Market
Health Data Management
US Mobile Health Market
Health Data Management
Clinical Data Management Systems (CDMS) Market
Health Data Management
Asia Pacific Healthcare Archiving and Ediscovery Market
Health Data Management
Global Healthcare Financial Analytics Market
Health Data Management
North America Clinical Data Analytics in Healthcare Market
Health Data Management
Healthcare Data Interoperability Market
Health Data Management
Healthcare Data Annotation Tools Market
Health Data Management
Global Chronic Care Management Software Market
Health Data Management
Healthcare Predictive Analytics Market
Health Data Management
Wireless Healthcare Asset Management Market
Health Data Management
Healthcare Data De-Identification Assurance Market
Health Data Management
Global Healthcare Customer Data Platform Market