
 Global Healthcare Quality Management Market | 2026-2036
Global Healthcare Quality Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global Healthcare Quality Management Market Intelligence
Software-defined subscription layers for continuous compliance monitoring is shifting how vendors monetize quality infrastructure. Oracle leverages its cloud architecture to anchor enterprise hospital contracts across multiple geographies. Premier competes through group purchasing integration that bundles analytics with supply chain data. Nuance Communications specializes in voice-enabled documentation tools that feed directly into quality scoring algorithms.
Healthcare quality management encompasses systematic frameworks for measuring, reporting, and improving clinical outcomes through standardized protocols, electronic data capture, and benchmarking against evidence-based thresholds. Its primary purpose is reducing preventable harm while demonstrating accountability to payers and accreditation bodies. Cloud-based deployment models command the largest revenue pool as hospitals prioritize scalability over capital-intensive on-premise installations. Patient safety applications represent the fastest-growing segment as sentinel event tracking becomes a board-level priority. Consulting services retain stable margins where health systems require hands-on guidance for Joint Commission readiness.
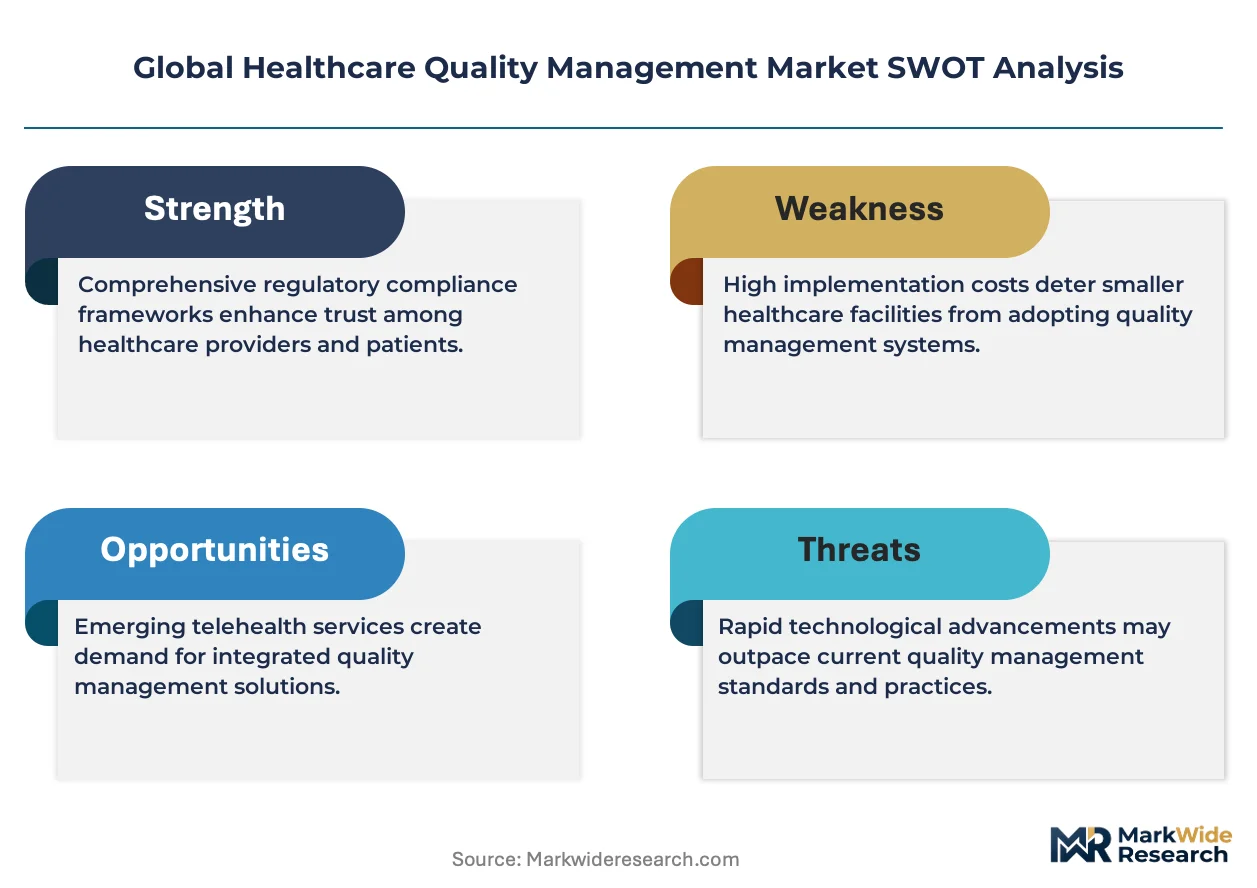
The FDA's digital health software guidelines, the EU MDR's post-market surveillance requirements, and Japan's PMDA quality system regulations collectively elevate documentation and traceability standards. These frameworks force healthcare providers to invest in automated reporting platforms rather than manual audit processes. Stakeholders must weigh interoperability commitments against vendor lock-in risks as regulatory complexity deepens.
Market Dynamics
Cloud-native quality infrastructure is compressing deployment cycles from years to months, forcing vendors to abandon perpetual licenses for recurring-revenue models anchored to continuous compliance validation.
Growth Catalysts
- FDA Digital Health Pre-Certification:The FDA's streamlined software validation pathway accelerates quality management platform rollouts across US hospital networks seeking faster time-to-value.
- EU MDR Post-Market Surveillance:European medical device manufacturers must implement automated adverse event reporting systems, creating immediate procurement mandates for integrated quality suites.
- Sentinel Event Tracking:Board-level accountability for patient safety incidents in Japanese tertiary hospitals drives real-time analytics adoption beyond traditional audit cycles.
Market Restraints
- Interoperability Tax:HL7 FHIR integration requirements impose 18-24 month implementation timelines that stall procurement decisions at mid-size health systems.
- Specialized Talent Scarcity:Clinical informaticists with dual competency in quality protocols and cloud architecture command compensation premiums that inflate total cost of ownership.
- Vendor Concentration Risk:Three hyperscale cloud providers dominate secure healthcare hosting, exposing buyers to egress cost volatility and service continuity dependencies.
Strategic Opportunities
- India Accreditation Wave:NABH standards expansion into tier-2 and tier-3 cities creates first-mover advantage for quality software vendors with localized deployment capabilities.
- Ambulatory Surgery Center Penetration:Freestanding surgical facilities in Germany lack enterprise-grade quality systems, presenting modular, lower-cost platform openings.
- AI-Assisted Documentation Convergence:Natural language processing integration with quality scoring algorithms enables automated clinical pathway compliance verification.
Industry Challenges
- Legacy EHR Integration Complexity:Cerner and Epic installations with decades of customization require expensive middleware development for quality data extraction.
- Joint Commission Survey Preparation:Health systems divert clinical staff to manual documentation reviews, creating organizational resistance to platform adoption despite automation benefits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Healthcare Quality Management Market |
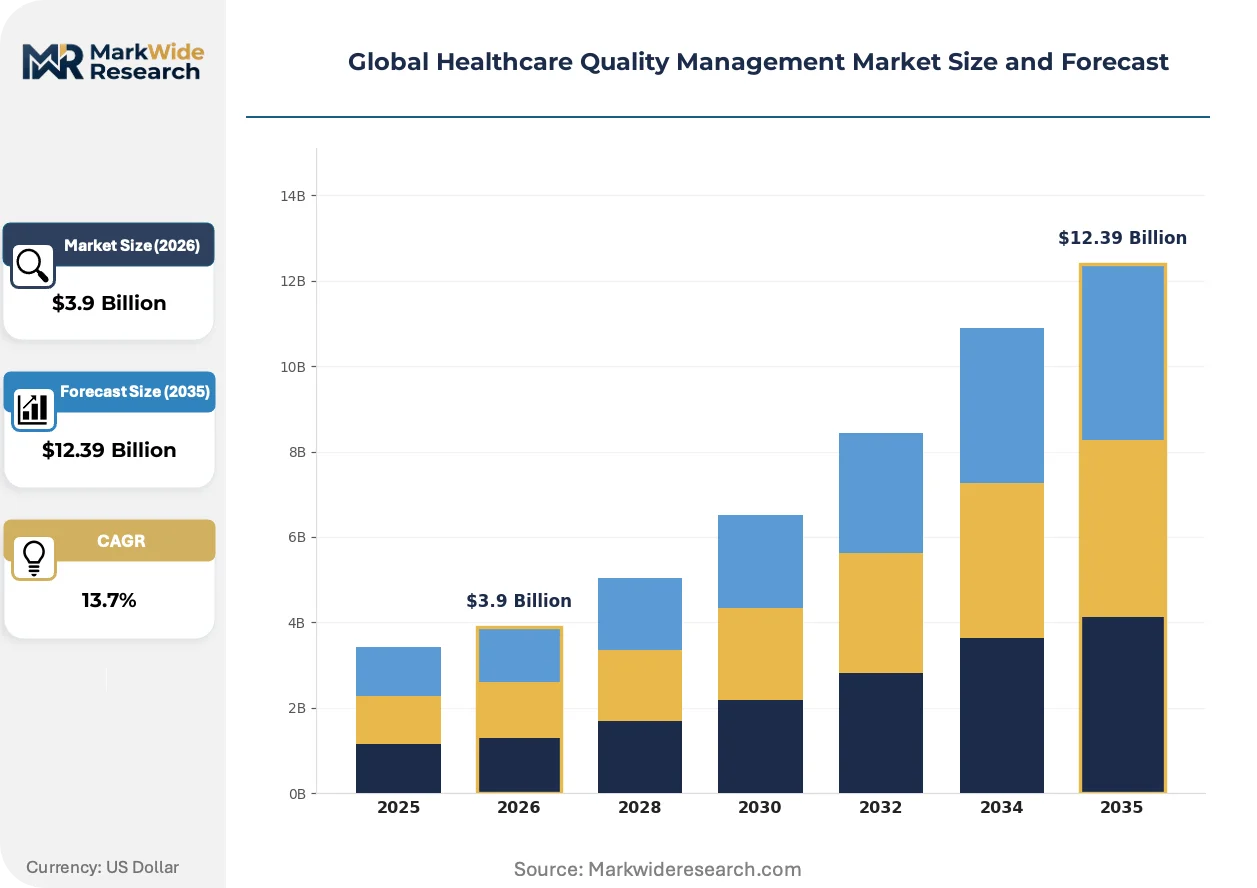
| Market Size in 2026 | $3.9 Billion |
| Market Size in 2035 | $12.39 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software Solutions, Consulting Services, Training Programs, Auditing Tools, Reporting Platforms Application: Patient Safety, Compliance Management, Risk Assessment, Performance Improvement, Data Analytics End User: Hospitals, Diagnostic Centers, Ambulatory Care Facilities, Rehabilitation Centers, Home Care Providers Deployment Model: Cloud-Based, On-Premise, Hybrid, Managed Services, SaaS Platforms |
| Companies Covered | Oracle, Optum, Premier, RLDatix, Nuance Communications, Mckesson, Merative, Health Catalyst, Symplr, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Healthcare Quality Management Market Strategic Shifts & Innovations
Artificial intelligence is embedding directly into quality workflows, transforming retrospective audit processes into real-time intervention systems that flag deviation risks before patient harm occurs.
Machine learning-based predictive risk scoring is overtaking rule-based trigger systems in high-acuity settings. Academic medical centers in the United States deploy these algorithms across sepsis, falls, and medication error domains. The technology is overtaking traditional threshold alerts by reducing false-positive fatigue among frontline nursing staff.
Japan's PMDA revised quality system regulations now mandate electronic records integrity controls comparable to FDA 21 CFR Part 11 standards. Medical device manufacturers exporting to both markets face harmonized validation requirements. Quality management vendors with pre-configured compliance templates capture disproportionate share in dual-jurisdiction supplier portfolios.
Subscription-based platform access is displacing capital-intensive perpetual license purchases among North American community hospital systems. Chief financial officers prefer operational expenditure treatment for technology investments amid reimbursement compression. This procurement evolution concentrates vendor relationships with platforms offering usage-scaled pricing tiers rather than fixed enterprise contracts.
Global Healthcare Quality Management Market Segmentation
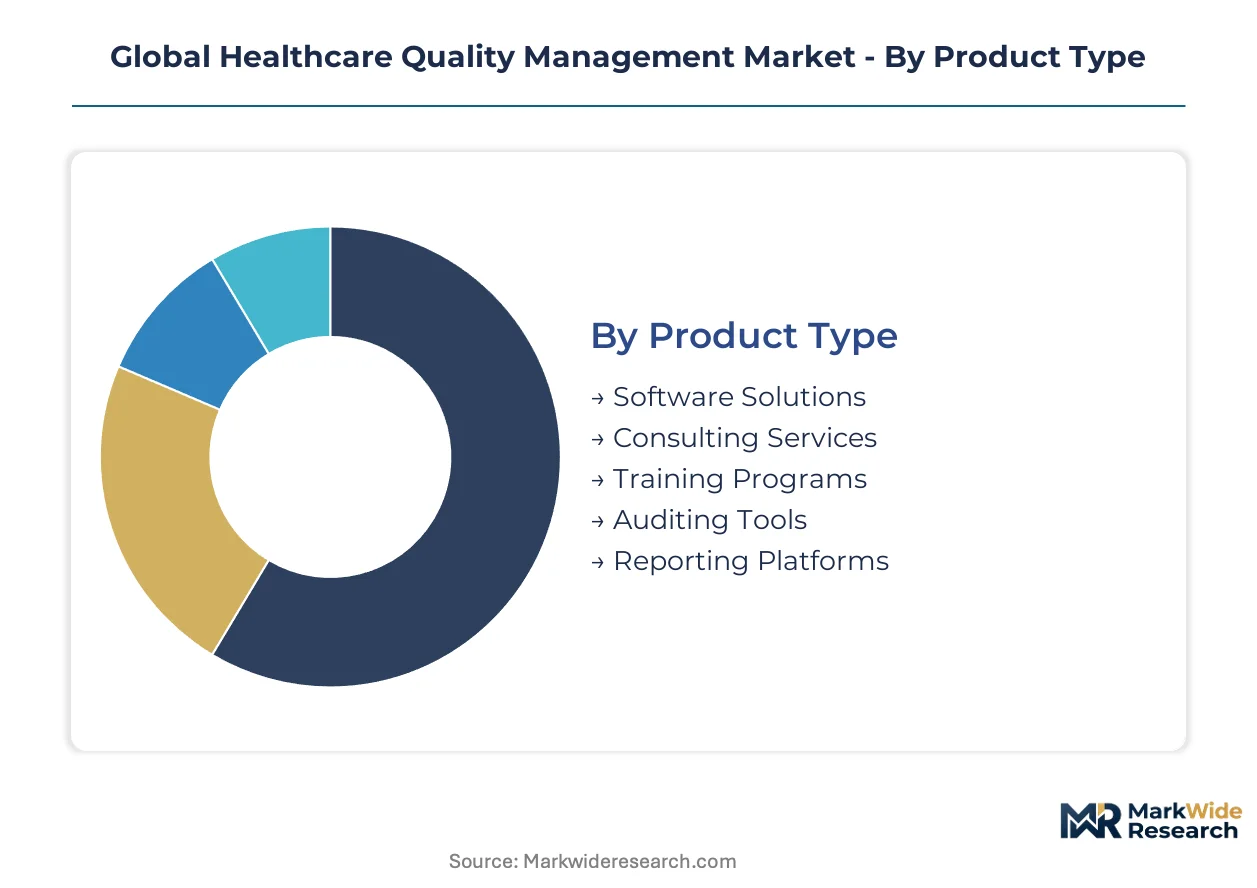
Healthcare quality management platforms serve heterogeneous stakeholders with divergent technical maturity and compliance urgency. Segmentation reveals where procurement budgets concentrate and which deployment architectures match institutional scale.
Product Type:
Supply concentration tilts toward software vendors with pre-validated compliance templates that accelerate FDA 21 CFR Part 11 and EU MDR readiness.
- Software Solutions:Cloud-native platforms automate adverse event reporting, electronic batch records, and deviation management through configurable workflows. Hospital systems in the United States and Germany prioritize these tools as Joint Commission and MDR deadlines compress implementation windows.
- Consulting Services:Specialized firms embed clinical informaticists within health systems to architect quality frameworks, conduct gap analyses, and prepare regulatory submissions. Japanese tertiary hospitals drive demand here as PMDA quality system revisions mandate hands-on validation support.
- Training Programs:Competency-building modules for frontline staff on sentinel event protocols and documentation standards.
- Auditing Tools:Automated checklist systems for internal quality assurance and supplier qualification.
- Reporting Platforms:Dashboard aggregators that consolidate metrics for board-level accountability and payer reporting.
Software Solutions absorb the bulk of installed capacity; Consulting Services is expanding most quickly.
Application:
Cost tier stratification separates enterprise-grade integrated suites from modular point solutions targeting specific compliance gaps.
- Patient Safety:Real-time surveillance systems deploy machine learning to predict sepsis, falls, and medication errors before harm occurs. Academic medical centers in the United States anchor demand as nursing leadership faces board accountability for sentinel events.
- Compliance Management:Automated mapping of clinical workflows against FDA, EU MDR, and PMDA requirements with audit trail preservation. European medical device manufacturers procure these systems aggressively to meet post-market surveillance mandates.
- Risk Assessment:Predictive algorithms scoring procedural complications and readmission probability.
- Performance Improvement:Benchmarking tools comparing clinical outcomes against evidence-based thresholds and peer institutions.
- Data Analytics:Population health aggregation platforms that identify systemic quality gaps across patient cohorts.
Compliance Management commands the largest procurement budgets; Patient Safety is climbing the fastest as predictive analytics mature.
End User:
Volume concentration follows inpatient procedure complexity, with highest per-facility spending at institutions managing the most regulated clinical environments.
- Hospitals:Integrated delivery networks deploy enterprise quality suites across multiple campuses with centralized governance. Systems in the United States, Germany, and Japan represent the core revenue base as accreditation mandates tighten and reimbursement ties to outcomes deepen.
- Diagnostic Centers:Imaging and laboratory facilities require streamlined quality systems for proficiency testing and regulatory reporting. Ambulatory surgery centers in Germany present modular platform opportunities given current underinvestment.
- Ambulatory Care Facilities:Freestanding clinics seeking lightweight compliance tools without enterprise overhead.
- Rehabilitation Centers:Long-term care quality tracking for functional outcome measurement.
- Home Care Providers:Remote patient monitoring integration with quality documentation for post-acute accountability.
Hospitals dominate current deployment; Diagnostic Centers are gaining share fastest as outpatient procedure volume expands.
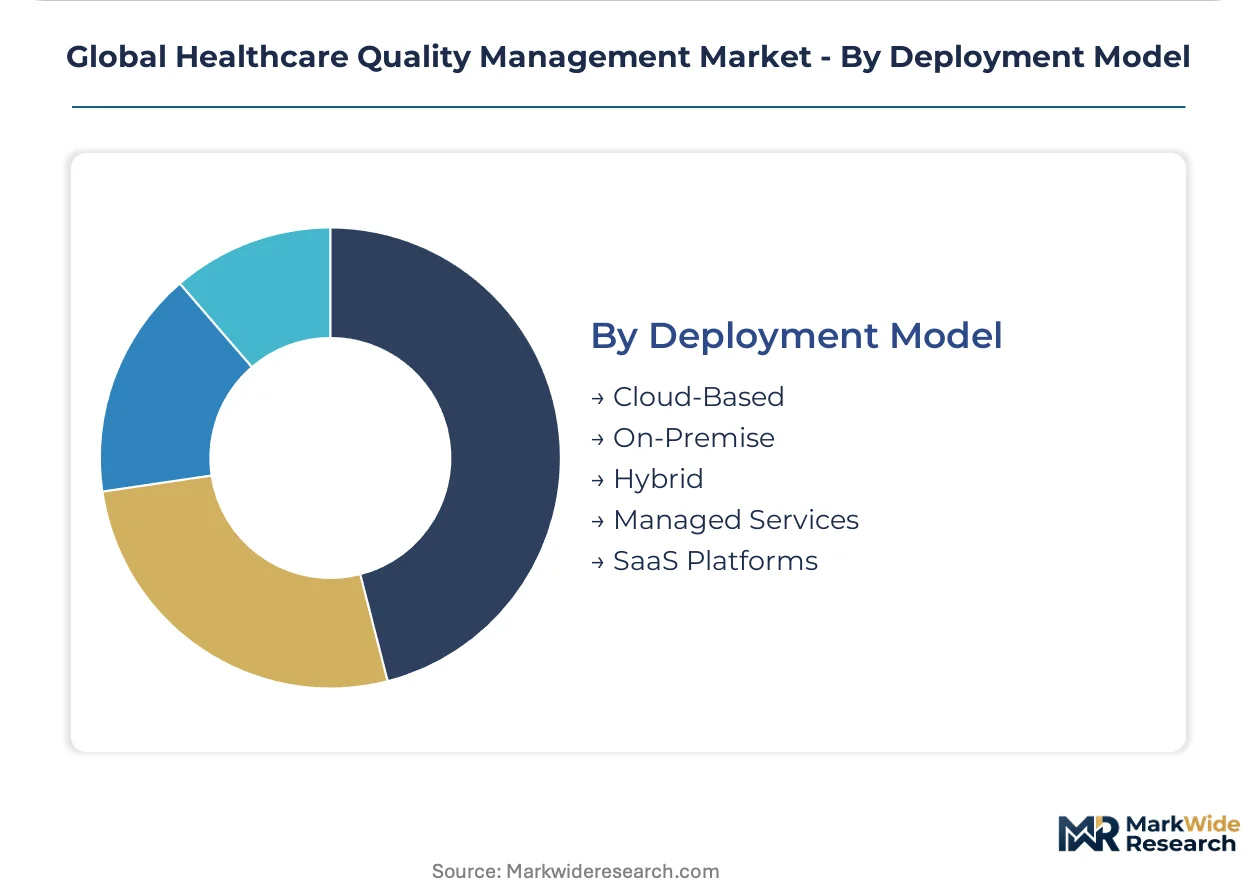
Deployment Model:
Customer type segmentation distinguishes capital-constrained community hospitals from hyperscale systems with dedicated cloud architecture teams.
- Cloud-Based:Multi-tenant platforms with automatic compliance template updates and usage-scaled pricing. North American community hospital systems prefer operational expenditure treatment as reimbursement compression strains capital budgets.
- SaaS Platforms:Subscription access to pre-configured quality modules with rapid deployment cycles. Mid-size health systems in tier-2 Indian cities adopt these as NABH accreditation expands beyond metropolitan centers.
- On-Premise:Legacy installations with full data sovereignty for institutions with restrictive security policies.
- Hybrid:Split architectures keeping sensitive patient data local while leveraging cloud analytics.
- Managed Services:Outsourced quality infrastructure operation with vendor-assumed compliance liability.
Cloud-Based deployments hold the majority of new procurement; SaaS Platforms are expanding most quickly among capital-constrained buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software production concentrates in the United States and Germany, while consumption spreads across hospital systems in Japan, India, and the United Kingdom seeking compliance-ready platforms.
United States
FDA digital health pre-certification and Joint Commission accreditation mandates drive procurement at integrated delivery networks. Hospital systems in Texas and California deploy cloud-native quality suites across multiple campuses. Academic medical centers in Boston anchor predictive analytics adoption for sentinel event reduction.
Germany
EU MDR post-market surveillance deadlines force medical device manufacturers toward automated reporting platforms. Bavarian industrial clusters around Munich host quality software development operations. Ambulatory surgery centers in North Rhine-Westphalia present modular platform opportunities given current infrastructure gaps.
Japan
PMDA revised quality system regulations mandate electronic records integrity controls comparable to FDA standards. Tertiary hospitals in Tokyo and Osaka face board-level accountability for real-time patient safety tracking. Medical device exporters to dual jurisdictions seek pre-configured compliance templates.
India
NABH standards expansion into tier-2 and tier-3 cities creates first-mover demand for localized deployment capabilities. Hospital chains in Maharashtra and Karnataka modernize quality infrastructure ahead of accreditation deadlines. SaaS platforms gain traction among capital-constrained community hospitals in Telangana.
United Kingdom
NHS digital transformation programs prioritize interoperability-ready quality systems for integrated care networks. London-based hospital trusts lead cloud migration for continuous compliance monitoring. Devolved health administrations in Scotland and Wales evaluate modular procurement frameworks.
Global Healthcare Quality Management Market Key Industry Players
Top-tier vendors anchor enterprise hospital contracts, while mid-tier specialists compete through vertical integration and group purchasing alignment. The vendor base stratifies across hyperscale cloud platforms, clinical informatics specialists, and voice-enabled documentation providers. Three strategic archetypes dominate: infrastructure-anchored suites, analytics-integrated purchasing networks, and AI-assisted workflow tools. M&A activity concentrates on data aggregation capabilities and regulatory template libraries.
Within the cloud infrastructure tier, Oracle represents the hyperscale anchor position. Premier exemplifies group purchasing integration that bundles analytics with supply chain data. Nuance Communications occupies the specialized niche for voice-enabled documentation feeding quality scoring algorithms.
| Leading Market Players |
|---|
| Oracle |
| Optum |
| Premier |
| RLDatix |
| Nuance Communications |
| Mckesson |
| Merative |
| Health Catalyst |
| Symplr |
| Others |
Cost & Logistics Intelligence
Cloud-native platform delivery is compressing deployment economics while concentrating vendor relationships around hyperscale infrastructure providers. Subscription-based access models displace perpetual licenses as hospital CFOs prioritize operational expenditure treatment amid reimbursement compression.
Pricing Analysis
Margin tightening in mid-size health systems reflects HL7 FHIR integration costs that extend implementation timelines. Three-tier pricing structure across premium, standard, and economy levels separates enterprise multi-campus deployments from modular point solutions and SaaS entry tiers. Certification-grade differentiation—FDA 21 CFR Part 11 validation versus self-attested compliance—commands substantial premiums. Community hospitals in tier-2 Indian cities exhibit highest price sensitivity; academic medical centers in the United States demonstrate lowest sensitivity due to board-mandated patient safety budgets.
Supply Chain Analysis
FDA, EU MDR, and PMDA qualification gating restricts viable vendor pools to platforms with pre-validated compliance templates. Software development concentrates in the United States, Germany, and Japan where regulatory expertise clusters. Cloud infrastructure draws from hyperscale providers with healthcare-specific security certifications. Single-source vulnerability exists in clinical informaticist talent pipelines. Distribution runs through group purchasing organizations that bundle quality analytics with supply chain data.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration momentum is accelerating as vendors capture regulatory template libraries and clinical data pipelines to defend margin position.
For Market Incumbents: Deploy compliance template pre-certification to lock in multi-jurisdiction medical device manufacturers before EU MDR enforcement tightens. Anchor cloud infrastructure contracts through automatic regulatory update guarantees that reduce buyer switching costs. Acquire clinical informaticist staffing firms to internalize implementation talent scarcity. For New Entrants and Emerging Players: Begin with modular patient safety point solutions targeting German ambulatory surgery centers where enterprise platform penetration remains minimal. Localize deployment capabilities for NABH accreditation waves in tier-2 Indian cities. Pursue SaaS-first pricing to bypass capital budget approval cycles that stall on-premise competitors. For Investors and Strategic Acquirers: Exit pathways concentrate in hyperscaler acquisition of regulatory template libraries and clinical AI training data repositories. Long-term viability hinges on recurring revenue share exceeding perpetual license legacy exposure. Monitor FDA digital health pre-certification expansion as inflection signal for platform consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Compliance Template Pre-Certification | FDA 21 CFR Part 11 validation accelerates procurement at US integrated delivery networks facing Joint Commission deadlines. |
| Cloud Infrastructure Partnership | Hyperscaler alliances embed quality platforms within hospital ERP ecosystems, reducing standalone sales friction. |
| Clinical Informaticist Acquisition | Staffing firm purchases internalize implementation talent commanding compensation premiums that inflate TCO. |
| AI Documentation Integration | NLP-enabled voice tools feed quality scoring algorithms, differentiating against rule-based trigger systems. |
| NABH Localization Investment | Deployment capabilities in tier-2 Indian cities capture first-mover advantage as accreditation expands beyond metros. |
Research Approach
Document review covered FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and GPO contract disclosures, complemented by interviews with chief medical informatics officers, hospital purchasing committee chairs, biomedical engineers, and regulatory affairs leads at medical device manufacturers. Secondary validation drew from CMS Medicare quality reporting data, Joint Commission accreditation surveys, and PMDA quality system inspection records. Bottom-up facility-level deployment estimates were triangulated against top-down vendor revenue segmentation.
Cross-referencing historical adoption curves against expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment architecture, institution scale, application complexity, and regional regulatory cluster. CAGRs were derived from fitted growth curves incorporating compliance deadline proximity and reimbursement policy shifts. Forecast inputs included cloud migration velocity at community hospitals and predictive analytics maturity in academic medical centers.
Regulatory deadline delays, interoperability standard fragmentation, and hyperscaler pricing volatility are the dominant revision risks to modeled outputs. Forecasts reflect assumptions regarding accreditation mandate enforcement consistency and cloud security certification maintenance. A model refresh is warranted upon material change in FDA digital health oversight scope or EU MDR post-market surveillance implementation intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Data Management
Patient Data Management Software Market
Health Data Management
Global Chronic Care Management Software Market
Health Data Management
Point-Of-Care Data Management Software Market
Health Data Management
Global Precision Medicine Software Market
Health Data Management
Healthcare Predictive Analytics Market
Health Data Management
AI Training Dataset in Healthcare Market
Health Data Management
Health Care Quality Management Software Market
Health Data Management
Global Healthcare Data Storage Market
Health Data Management
Data Monetization in Healthcare Market
Health Data Management
Master Data Management in Healthcare Market
Health Data Management
Big Data Healthcare Market
Health Data Management
Healthcare Archiving and Ediscovery Market
Health Data Management
North America Clinical Data Analytics in Healthcare Market
Health Data Management
Global Healthcare Financial Analytics Market
Health Data Management
Healthcare Data Interoperability Market
Health Data Management
Data Democratization in Healthcare Market