
 Saudi Arabia Diabetes Care Devices Market | 2026-2036
Saudi Arabia Diabetes Care Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Diabetes Care Devices Market Analytics
Hospital procurement channels is tilting toward integrated diabetes management contracts that bundle continuous glucose monitors with insulin delivery systems. Abbott Laboratories leverages its FreeStyle Libre platform to anchor high-volume tenders with Saudi Arabia's Ministry of Health. Medtronic competes through its MiniMed ecosystem, which sustains loyalty among endocrinology departments in King Faisal Specialist Hospital and similar referral centers. Dexcom differentiates via direct-to-patient subscription models that bypass traditional distributor markups.
Diabetes care devices encompass electronic and disposable instruments that measure blood glucose, deliver insulin, or monitor metabolic status through enzymatic electrochemical sensors, micro-pump mechanisms, or subcutaneous filament arrays. These systems enable real-time glycemic control for patients with insulin deficiency or resistance, reducing acute complications and long-term end-organ damage. Continuous glucose monitors command expanding margin pools as automated insulin delivery systems integrate algorithm-driven dosing, while blood glucose monitors occupy a mature, price-sensitive segment in retail pharmacy channels. Homecare settings represent the fastest-growing end user category as SFDA-approved remote monitoring platforms expand reimbursement eligibility under the country's health transformation initiatives.
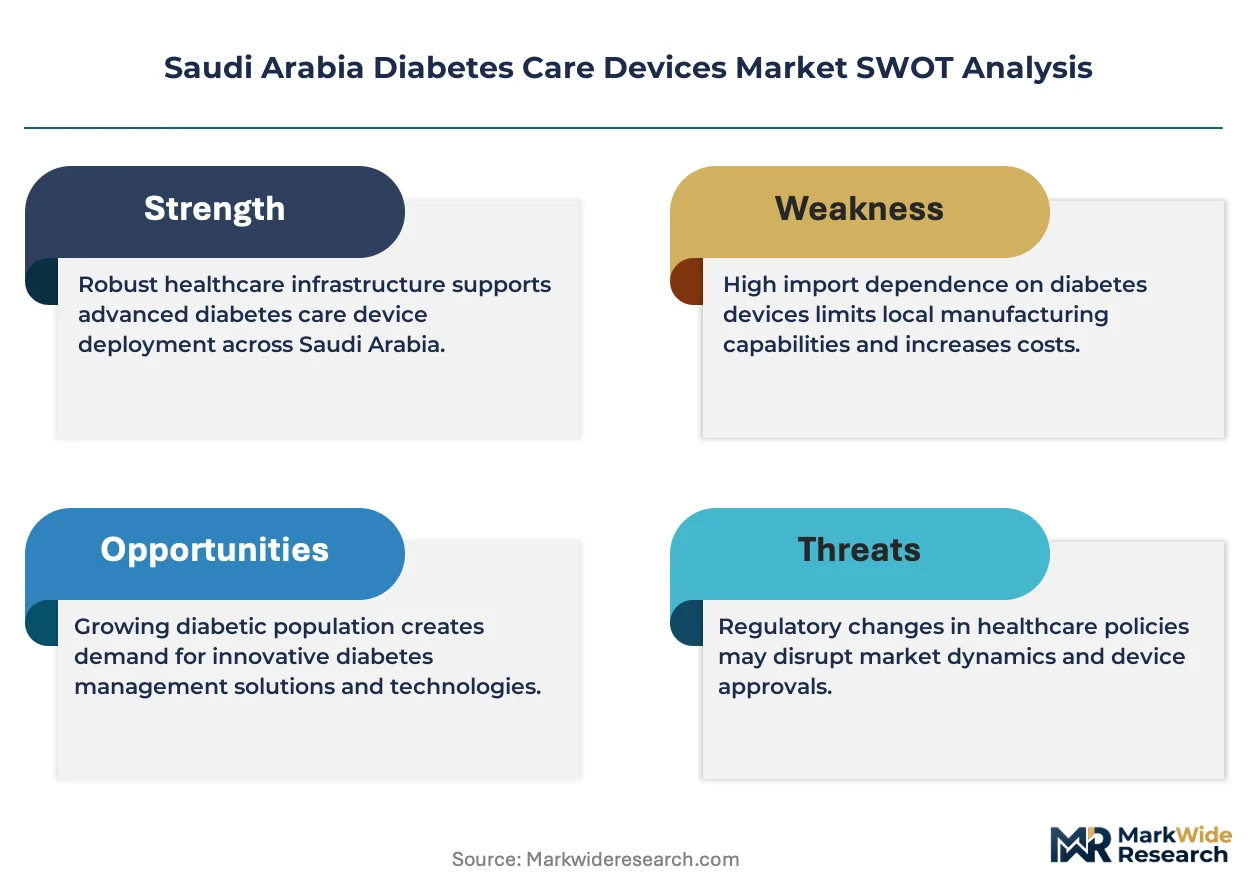
SFDA governs medical device registration, clinical evidence requirements, and post-market surveillance for diabetes care devices in Saudi Arabia, while the Ministry of Health sets procurement standards and hospital formulary inclusion criteria. The country's PLI-linked localization mandates are forcing multinational manufacturers to establish domestic assembly or sterilization capabilities to maintain tender access. Stakeholders must monitor how the Health Sector Transformation Program reshapes reimbursement pathways between public hospitals and emerging private diabetes centers.
Market Dynamics
SFDA's PLI-linked localization mandates are compressing supply chains, forcing multinational diabetes device manufacturers to establish domestic assembly capabilities or surrender hospital tender access to regional competitors.
Growth Catalysts
- Health Sector Transformation Program:Reimbursement expansion for remote monitoring platforms under Saudi Vision 2030 is accelerating patient migration from hospital-based glucose testing to homecare settings.
- Continuous glucose monitor-insulin pump integration:Algorithm-driven automated insulin delivery systems are capturing preference among King Faisal Specialist Hospital's endocrinology departments.
- Riyadh-Jeddah corridor concentration:Tertiary care cluster procurement power in these cities is consolidating demand volumes that justify integrated diabetes management contracts.
Market Restraints
- Sterilization-grade polymer input volatility:Medical-grade polyurethane and silicone supply concentration in East Asian chemical producers exposes Saudi assemblers to freight cost surges.
- SFDA clinical evidence requirements:Mandatory local trial data for novel glucose monitoring algorithms extends registration timelines by 18-24 months versus comparable Gulf Cooperation Authority markets.
- Blood glucose monitor substitution pressure:Mature fingerstick testing devices face margin compression as continuous monitoring penetration deepens in insured patient populations.
Strategic Opportunities
- Eastern Province diabetes centers:Dammam and Khobar exhibit underpenetrated continuous glucose monitor adoption relative to Riyadh, creating whitespace for direct-to-patient subscription models.
- SFDA-approved AI diagnostic integration:Machine learning-enabled hypoglycemia prediction algorithms qualify for expedited review pathways, enabling software differentiation in hardware-commoditized segments.
- Private hospital corridor expansion:Jeddah's premium healthcare infrastructure is attracting medical tourism from Yemen and East Africa, extending addressable patient pools beyond domestic insurance coverage.
Industry Challenges
- Biomedical engineering talent scarcity:Domestic workforce development lags behind SFDA's technical file preparation requirements, forcing manufacturers to retain expatriate regulatory affairs specialists at 40% wage premiums.
- Legacy hospital information system integration:Continuous glucose monitor data streams require middleware development to interface with Ministry of Health's fragmented electronic health record architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Diabetes Care Devices Market |
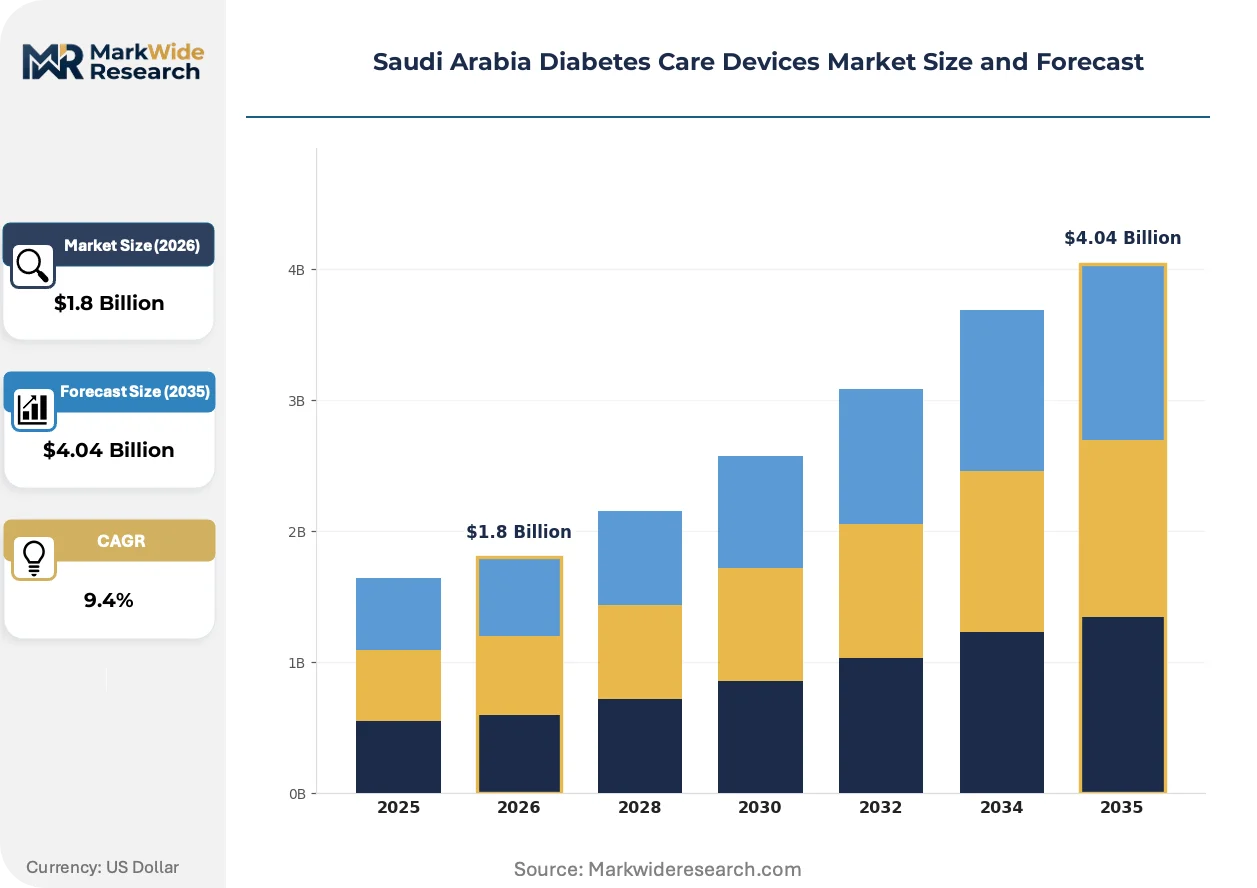
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blood Glucose Monitors, Insulin Pumps, Continuous Glucose Monitors, Lancets End User: Hospitals, Clinics, Homecare, Pharmacies Technology: Self-Monitoring, Continuous Monitoring, Automated Insulin Delivery, Traditional Monitoring Application: Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, Prediabetes |
| Companies Covered | Abbott Laboratories, Medtronic, Dexcom, Roche Holding AG, Becton Dickinson, Johnson & Johnson, Sanofi, Novo Nordisk, B. Braun, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Diabetes Care Devices Market Evolving Landscape
Algorithmic personalization is displacing one-size-fits-all glucose monitoring, while procurement centralization and channel disintermediation are restructuring how devices reach Saudi patients.
Continuous glucose monitoring sensor technology is hybridizing electrochemical enzymatic detection with optical fluorescence methods to extend wear duration beyond 14 days. King Faisal Specialist Hospital and similar tertiary centers are piloting these extended-wear platforms for insulin-dependent populations. This convergence is compressing replacement cycle revenues while expanding per-patient lifetime value through subscription lock-in.
SFDA's 2023 medical device cybersecurity guidance mandates encrypted data transmission for connected diabetes devices, creating compliance differentiation among registrants. Manufacturers must demonstrate end-to-end encryption protocols and vulnerability management procedures to maintain active registration status. Remote monitoring platforms with pre-certified security architectures are capturing preferential formulary placement in Ministry of Health procurement frameworks.
Direct-to-patient subscription channels are bypassing traditional distributor networks that historically captured 25-35% markup layers. Dexcom and comparable platform operators are establishing Saudi-based patient support centers to handle calibration troubleshooting and supply replenishment. This channel shift concentrates in urban private-pay segments where insurance reimbursement flexibility enables monthly billing models.
Saudi Arabia Diabetes Care Devices Market Segmentation
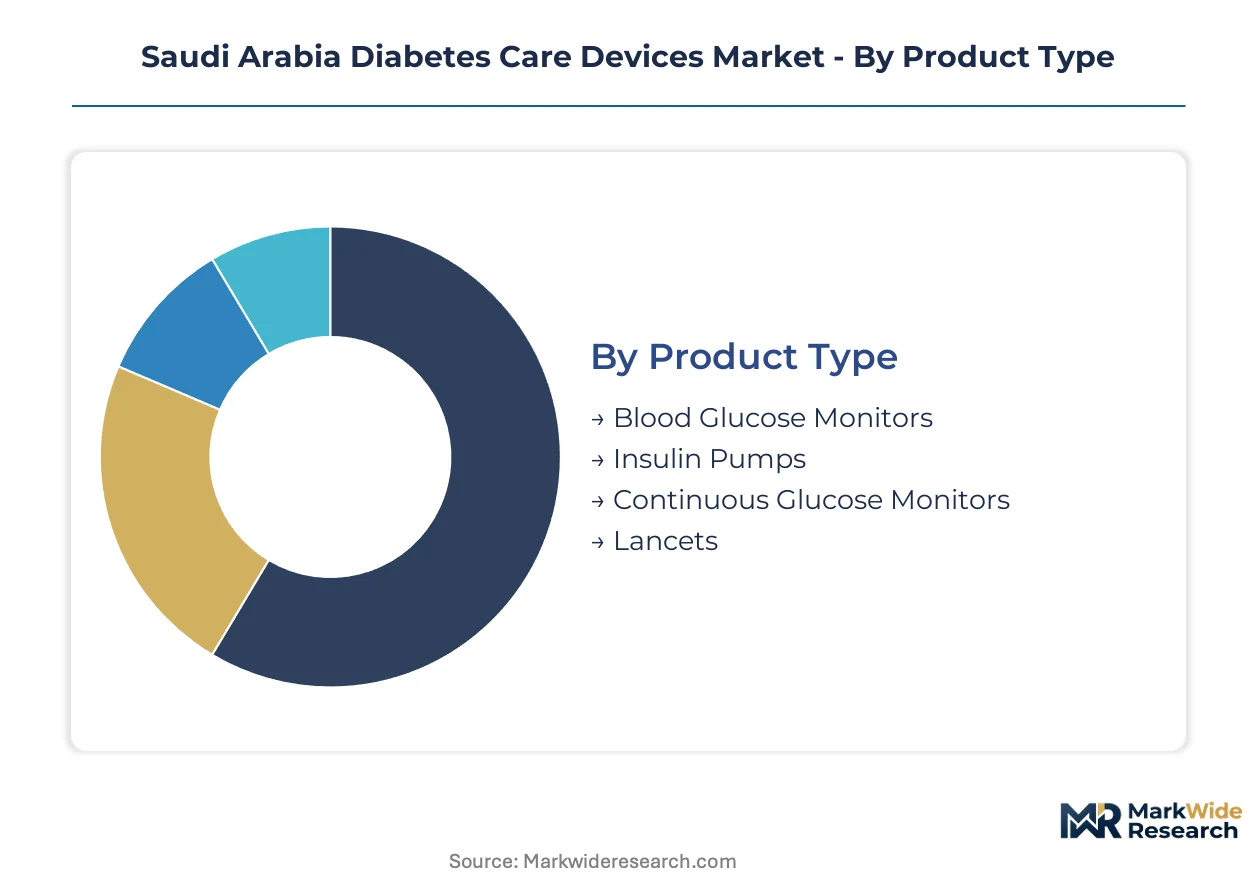
Segmentation reveals how SFDA registration pathways and procurement frameworks fragment demand across device categories. Each dimension carries distinct margin profiles and localization requirements that reshape competitive positioning in Saudi Arabia's health transformation.
Product Type:
Cost tier differentiation separates disposable consumables from capital-intensive electronic platforms, with reimbursement eligibility varying by device complexity and connectivity features.
- Blood Glucose Monitors:Enzymatic electrochemical sensors deliver capillary glucose readings through fingerstick sampling. Retail pharmacy channels in Riyadh and Jeddah concentrate volume for this mature category, though margin compression intensifies as continuous monitoring penetration deepens among insured populations.
- Continuous Glucose Monitors:Subcutaneous filament arrays paired with algorithmic data processing enable real-time glycemic tracking without fingerstick calibration. King Faisal Specialist Hospital's endocrinology departments anchor hospital procurement demand, while SFDA-approved remote monitoring platforms expand homecare reimbursement eligibility.
- Insulin Pumps:Micro-pump mechanisms deliver basal and bolus insulin through programmable infusion protocols.
- Lancets:Single-use penetrating devices for capillary blood sampling occupy commoditized supply tiers with minimal differentiation.
Continuous Glucose Monitors hold installed capacity. Blood Glucose Monitors is rotating up the share rankings as price-sensitive segments retain volume.
End User:
Customer type determines procurement channel access, with Ministry of Health tenders, private insurance networks, and direct-to-patient subscriptions operating under divergent pricing protocols.
- Hospitals:Tertiary care institutions with integrated electronic health record systems drive demand for connected device platforms. The Riyadh-Jeddah corridor concentrates procurement power through centralized formulary committees that favor bundled diabetes management contracts.
- Homecare:Patient-managed settings represent the steepest expansion trajectory as Health Sector Transformation Program initiatives extend reimbursement to remote monitoring platforms. Direct-to-patient subscription models bypass traditional distributor markups in urban private-pay segments.
- Clinics:Outpatient facilities with limited capital budgets prioritize cost-efficient glucose monitoring solutions.
- Pharmacies:Retail distribution channels serve price-sensitive consumers seeking over-the-counter testing supplies.
Hospitals hold installed capacity. Homecare is rotating up the share rankings.
Technology:
Application sophistication stratifies segments from manual testing protocols to closed-loop automated systems, with SFDA cybersecurity mandates adding compliance differentiation layers.
- Continuous Monitoring:Real-time glucose telemetry through subcutaneous sensors enables predictive alerts and trend analysis. Algorithm-driven platforms capture preference among tertiary care centers as automated insulin delivery integration advances, though local trial data requirements extend registration timelines.
- Automated Insulin Delivery:Closed-loop systems combining continuous glucose data with algorithmic insulin dosing represent the most complex regulatory category. King Faisal Specialist Hospital pilots these platforms for insulin-dependent populations, with SFDA's 2023 cybersecurity guidance mandating encrypted data transmission.
- Self-Monitoring:Patient-operated blood glucose testing through portable meters dominates retail pharmacy channels.
- Traditional Monitoring:Basic glucose testing without connectivity features occupies declining share positions.
Continuous Monitoring holds installed capacity. Automated Insulin Delivery is rotating up the share rankings.
Application:
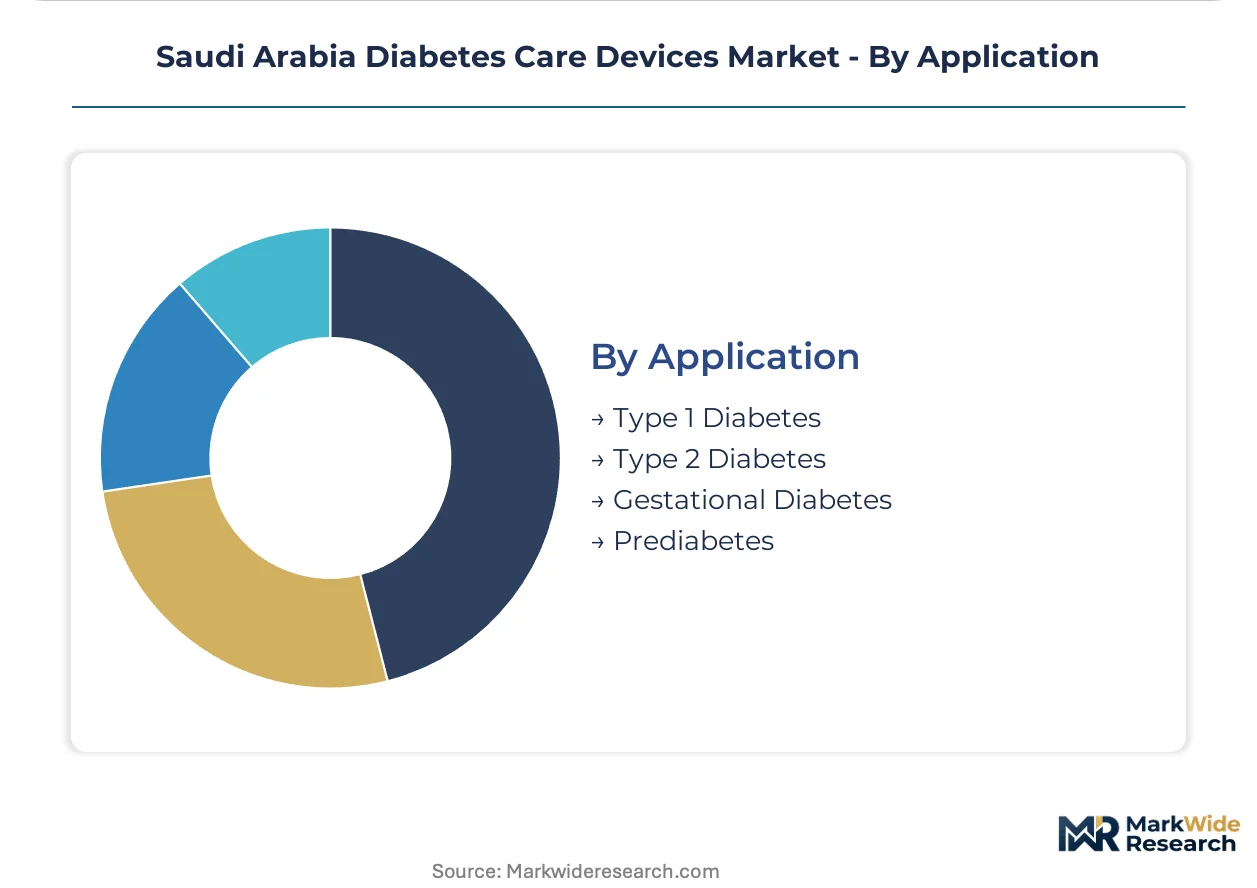
Volume distribution across diabetes phenotypes reflects disease prevalence, treatment intensity, and reimbursement coverage scope within Saudi Arabia's insurance frameworks.
- Type 1 Diabetes:Absolute insulin deficiency requiring intensive glucose monitoring and exogenous insulin replacement drives highest device utilization rates. Pediatric and young adult populations in tertiary referral centers sustain demand for continuous glucose monitor-insulin pump integrated systems.
- Type 2 Diabetes:Insulin resistance and progressive beta-cell dysfunction creates the largest addressable patient pool. Eastern Province diabetes centers in Dammam and Khobar exhibit underpenetrated continuous monitor adoption relative to Riyadh, creating whitespace for platform expansion.
- Gestational Diabetes:Glucose intolerance during pregnancy generates temporary monitoring demand with distinct clinical protocols.
- Prediabetes:Elevated glucose below diabetes thresholds drives preventive monitoring adoption in wellness-focused segments.
Type 2 Diabetes holds installed capacity. Type 1 Diabetes is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The King Abdulaziz Port in Dammam anchors pharmaceutical and medical device import flows into Saudi Arabia's Eastern Province, while the Jeddah Islamic Port on the Red Sea corridor handles Western Region distribution for diabetes care equipment.
Riyadh
King Faisal Specialist Hospital and Research Centre drives demand for integrated continuous glucose monitor-insulin pump systems. The Ministry of Health's centralized procurement frameworks favor bundled diabetes management contracts from tertiary care clusters. The Riyadh medical city corridor concentrates endocrinology referral volumes that justify high-complexity device tenders.
Eastern Province
Dammam and Khobar exhibit underpenetrated continuous glucose monitor adoption relative to Riyadh's saturation levels. The SFDA's regional office in Dammam streamlines registration pathways for manufacturers establishing local assembly capabilities. King Fahd University Hospital anchors diabetes center expansion plans targeting the province's industrial workforce populations.
Western Region
Jeddah's private hospital corridor attracts medical tourism from Yemen and East Africa, extending addressable patient pools beyond domestic insurance coverage. The Health Sector Transformation Program designates Jeddah as a pilot zone for remote monitoring reimbursement expansion. Private diabetes centers along the Mecca-Jeddah highway corridor are deploying direct-to-patient subscription models.
NEOM Northwest
The giga-project's healthcare infrastructure plans incorporate predictive diabetes screening through AI-enabled diagnostic platforms. SFDA's expedited review pathways for software-driven devices align with NEOM's technology-first health system architecture. The zone's regulatory sandbox framework permits pilot deployment of closed-loop automated insulin delivery systems before national registration.
Saudi Arabia Diabetes Care Devices Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying sensors, polymers, and micro-pump mechanisms. The Saudi market structures around three tiers: multinational device ecosystems with SFDA registration history, regional distributors pivoting toward local assembly under PLI mandates, and emerging domestic assemblers capturing commoditized consumable segments. Dominant competitive moves include backward integration into sterilization-grade polymer processing and strategic licensing of algorithmic glucose prediction software to bypass extended local trial requirements.
Among the platform integrators, Abbott Laboratories, Medtronic, and Dexcom occupy positions that exemplify divergent channel strategies. Abbott leverages its FreeStyle Libre ecosystem to anchor Ministry of Health tenders through integrated management contracts. Medtronic represents the closed-loop automated delivery archetype, sustaining institutional loyalty in tertiary referral centers. Dexcom sits within the direct-to-patient subscription tier, bypassing traditional distributor markups through Saudi-based patient support infrastructure.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Medtronic |
| Dexcom |
| Roche Holding AG |
| Becton Dickinson |
| Johnson & Johnson |
| Sanofi |
| Novo Nordisk |
| B. Braun |
| Others |
Value Network & Pricing Analysis
Single-source dependency on East Asian sterilization-grade polymer producers exposes Saudi assemblers to freight cost surges that compress both standard-tier margins and premium-tier pricing power. This input concentration forces manufacturers to absorb volatility or surrender tender access to regional competitors with captive supply chains.
Pricing Analysis
Volume-discount tiering separates Ministry of Health bundled contracts from direct-to-patient subscription models. Pricing stratifies across premium, standard, and economy tiers based on connectivity certification and after-sales service bundling. Cost compression in the blood glucose monitor segment intensifies as continuous monitoring penetration deepens among insured populations. Retail pharmacy channels exhibit highest price sensitivity, while tertiary care procurement committees prioritize integration over unit cost.
Supply Chain Analysis
Tariff exposure between East Asian chemical producers and Saudi manufacturing zones dominates supply chain risk calculations for medical-grade polyurethane and silicone inputs. Manufacturing concentrates in China, South Korea, and Japan for enzymatic sensor substrates and micro-pump mechanisms. Domestic assembly capabilities remain tethered to imported sterilization-grade polymers. Distribution runs through King Abdulaziz Port and Jeddah Islamic Port for Western and Eastern Region hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biomedical engineering talent scarcity constrains SFDA technical file preparation, forcing wage premiums that reshape competitive economics for multinational and domestic players alike.
For Market Incumbents: Pre-empt emerging regional competitors by securing captive sterilization-grade polymer supply through backward integration into East Asian chemical partnerships. Anchor Ministry of Health tender access through integrated diabetes management contracts that bundle continuous glucose monitors with insulin delivery systems, neutralizing price-only challengers. For New Entrants and Emerging Players: Establish a beachhead in Dammam and Khobar's underpenetrated Eastern Province diabetes centers where continuous glucose monitor adoption lags Riyadh saturation levels. Deploy direct-to-patient subscription models with Saudi-based patient support infrastructure to bypass traditional distributor markups in urban private-pay segments. For Investors and Strategic Acquirers: Algorithm-integrated device platforms with expedited SFDA review pathways represent the priority acquisition archetype for long-term viability. Monitor Health Sector Transformation Program reimbursement expansion signals as inflection indicators for homecare setting migration and remote monitoring platform eligibility.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Cybersecurity Certification | Encrypted data transmission compliance secures preferential formulary placement in Ministry of Health procurement frameworks. |
| Domestic Assembly Localization | PLI-linked mandates preserve hospital tender access against regional competitors establishing sterilization capabilities. |
| Algorithm Licensing Partnerships | Machine learning-enabled hypoglycemia prediction bypasses extended local trial timelines for novel glucose monitoring systems. |
| Direct-to-Patient Subscription Infrastructure | Saudi-based patient support centers capture urban private-pay segments through monthly billing models outside distributor networks. |
| Extended-Wear Sensor Development | Hybrid electrochemical-optical platforms compress replacement cycles while expanding per-patient lifetime value through subscription lock-in. |
Research Methodology
A standing panel of hospital procurement managers, biomedical engineers, SFDA regulatory affairs specialists, and GPO contracts managers provided ongoing calibration against secondary validation from hospital procurement databases, SFDA medical device registration filings, Ministry of Health tender documentation, and customs import records. Bottom-up demand modeling across device categories triangulated with top-down market sizing.
Scenario-bracketing around Health Sector Transformation Program implementation pace and PLI localization compliance timelines anchored projections across the analysis window. Segmentation dimensions modeled include product type, end user setting, technology sophistication, and diabetes phenotype application. CAGRs derived from installed base growth rates, replacement cycle compression, and reimbursement pathway expansion assumptions.
Sensitivities concentrate around SFDA cybersecurity guidance enforcement intensity and sterilization-grade polymer supply disruption events. Forecasts reflect documented assumptions regarding remote monitoring reimbursement eligibility and domestic assembly mandate compliance timelines. Material shifts in Health Sector Transformation Program funding allocation or East Asian chemical export restrictions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Australia Continuous Glucose Monitoring Devices Market
Diabetes Care
Europe Diabetic Foot Ulcer Treatment Market
Diabetes Care
Russia Diabetes Care Devices Market
Diabetes Care
North America Continuous Glucose Monitoring Market
Diabetes Care
Brazil Continuous Glucose Monitoring Market
Diabetes Care
France Continuous Glucose Monitoring Market
Diabetes Care
Combination Anti-Diabetes Drugs Market
Diabetes Care
Middle East and Africa Diabetes Pen Market
Diabetes Care
North America and Europe Artificial Pancreas Systems Market
Diabetes Care
Asia Pacific Blood Glucose Test Strip Market
Diabetes Care
Iran Diabetes Care Devices Market
Diabetes Care
Middle East and Africa Insulin Infusion Pumps Market
Diabetes Care
Japan Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Alternatives for Injectable Diabetes Care Market
Diabetes Care
Artificial Intelligence in Diabetes Management Market
Diabetes Care
Global Needle Free Diabetes Care Market