
 Global Chronic Care Management Software Market | 2026-2036
Global Chronic Care Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Chronic Care Management Software Market Foresight
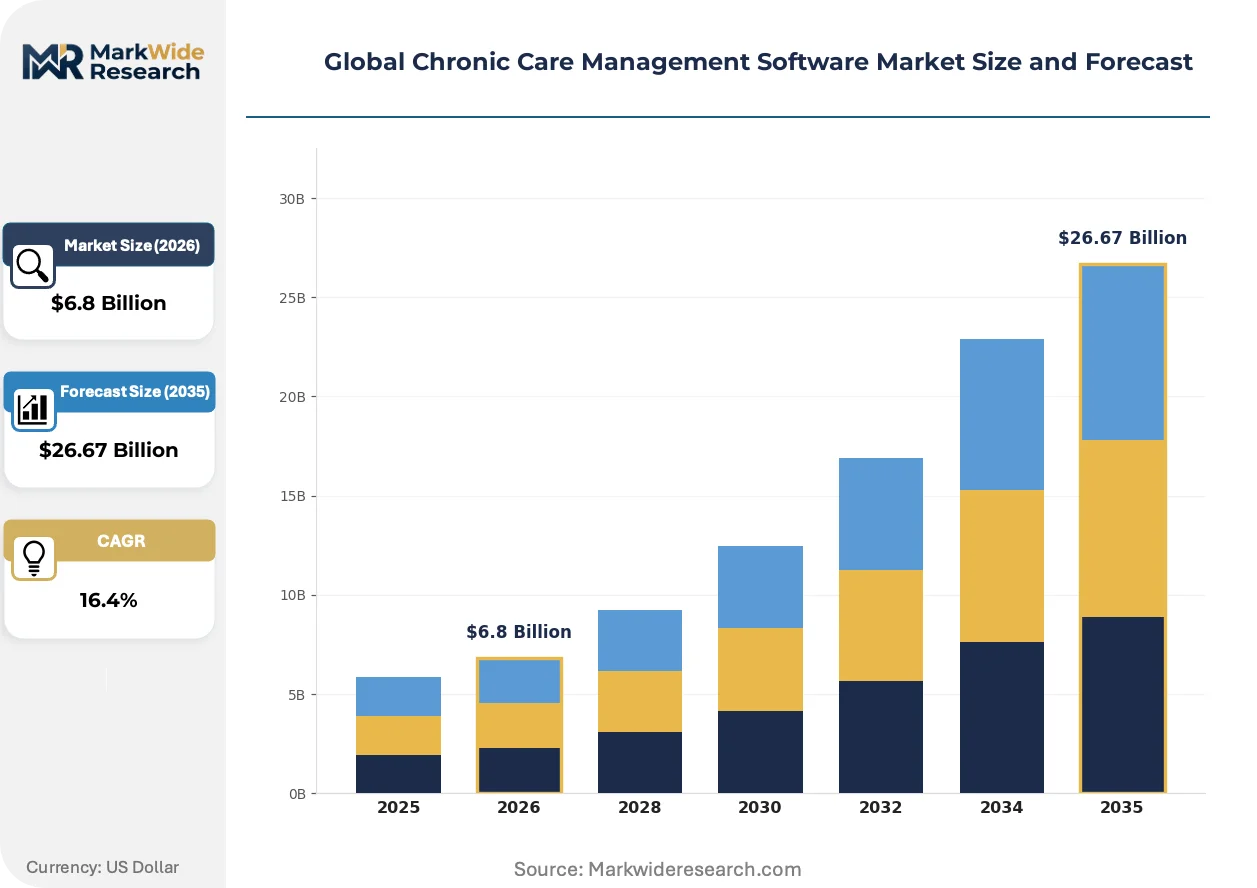
The chronic care management software landscape is restructuring around a sharp split between enterprise-grade integrated platforms and lightweight standalone tools. Optum, Inc. leverages its payer-provider integration to dominate the high-acuity segment, while ChartSpan sustains a narrow focus on Medicare-centric care coordination for smaller practices. ZeOmega competes through deep clinical workflow specialization that anchors its position in complex multi-condition populations.
Chronic care management software encompasses digital platforms that aggregate patient biometric data, medication adherence signals, and care plan milestones for long-term disease oversight, typically interfacing with electronic health record systems via HL7 FHIR or proprietary APIs to enable automated outreach and risk stratification. Cloud-based solutions capture the fastest expansion as health systems abandon capital-intensive on-premises infrastructure, while integrated platforms command the deepest margin pools by embedding analytics, billing, and telehealth within unified architectures. Specialty clinics represent a growing deployment locus where diabetes management and cardiovascular monitoring modules see concentrated uptake.
The US CMS reimbursement framework, HIPAA security mandates, and the EU AI Act's clinical decision-support provisions collectively shape product roadmaps and market access requirements for vendors seeking cross-border scale. FDA oversight of software-as-medical-device classifications and the UK's MHRA equivalent create divergent compliance burdens that favor regionally established players. Stakeholders must monitor how evolving interoperability standards and value-based contracting terms reshape vendor selection criteria across health system procurement cycles.
Market Dynamics
The CMS reimbursement framework for remote patient monitoring is compressing vendor margins while forcing consolidation around integrated platform architectures that bundle billing, analytics, and care coordination.
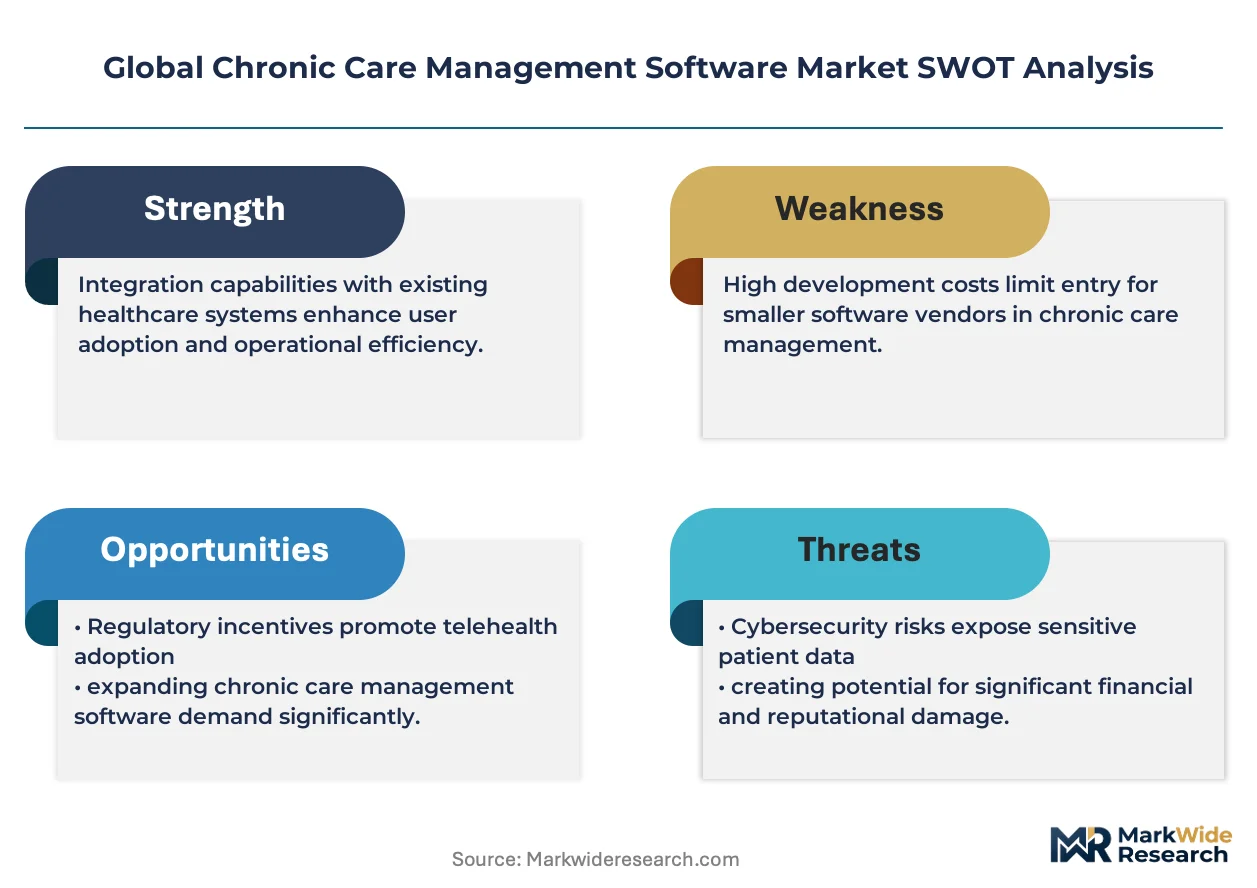
Growth Catalysts
- US CMS reimbursement codes:Medicare's expanding coverage for CPT 99490 and 99491 services incentivizes physician practices to adopt automated care coordination workflows.
- Cloud infrastructure migration:Health systems are abandoning on-premises servers for AWS and Azure deployments, reducing capital barriers to software procurement.
- HL7 FHIR interoperability mandates:The 21st Century Cures Act's data blocking provisions compel EHR vendors to open APIs, enabling seamless CCM platform integration.
Market Restraints
- HIPAA compliance costs:Encryption, audit logging, and business associate agreements add 15-25% overhead to vendor operating expenses.
- Specialist physician shortage:Cardiologists and endocrinologists in rural US counties and Eastern Germany limit care team capacity for program enrollment.
- Legacy EHR fragmentation:Epic, Cerner, and MEDITECH silos create integration friction that delays deployment timelines by 6-18 months.
Strategic Opportunities
- Japan's super-aging population:METI's digital health subsidies for diabetes and dementia management create entry points for predictive analytics modules.
- AI-augmented risk stratification:Machine learning models processing continuous glucose monitor and blood pressure data enable proactive intervention protocols.
- Specialty pharmacy integration:CVS Health and Walgreens hub-and-spoke networks offer new distribution channels for medication adherence tools.
Industry Challenges
- Clinical workflow redesign:Nurses and medical assistants require 40+ hours of training to manage automated outreach queues and escalation protocols.
- FDA SaMD classification uncertainty:Software-as-medical-device determinations for AI-driven dosing recommendations create 12-24 month premarket review timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Chronic Care Management Software Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $26.67 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Software, Integrated Platforms, Mobile Applications, Cloud-Based Solutions, Web Portals Application: Diabetes Management, Cardiovascular Monitoring, Respiratory Care, Mental Health Support, Arthritis Tracking End User: Primary Care Providers, Specialty Clinics, Home Health Agencies, Telehealth Services, Rehabilitation Centers Deployment: On-Premises, SaaS, Hybrid Models, Private Cloud, Public Cloud |
| Companies Covered | Optum, Inc., ExlService Holdings, Inc., NXGN Management, LLC., Cognizant, Medecision, Veradigm LLC, ZeOmega, CareHarmony, Inc., ChartSpan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Chronic Care Management Software Market Shifts & Advancements
Edge computing architectures and ambient clinical intelligence are dissolving the boundary between hospital-based and home-based chronic disease oversight, enabling real-time intervention loops that were previously confined to acute settings.
FHIR-native application programming interfaces are decentralizing data ownership from monolithic electronic health record vendors toward modular best-of-breed solutions. Community health centers and Federally Qualified Health Centers in Texas and California are piloting these architectures fastest, attracted by subscription pricing that eliminates per-patient licensing fees. The structural consequence is compressing vendor switching costs and fragmenting purchasing authority across IT, clinical operations, and revenue cycle departments.
Europe's AI Act clinical decision-support provisions are forcing algorithm transparency disclosures that reshape product development roadmaps. Vendors must now document training data provenance and performance metrics across demographic subgroups before CE marking. German hospital procurement committees are already embedding these requirements into RFP scoring rubrics, favoring established players with regulatory affairs infrastructure over venture-stage entrants.
Accountable care organizations are consolidating vendor relationships from point solutions toward enterprise platforms that span telehealth, remote monitoring, and care management. This concentration is visible in the US Southwest and Pacific Northwest, where Kaiser Permanente and Providence Health have reduced their CCM supplier bases by 60% since 2022. The surviving vendors capture deeper annual contract values but face performance guarantees tied to hospital admission reduction metrics.
Global Chronic Care Management Software Market Segmentation
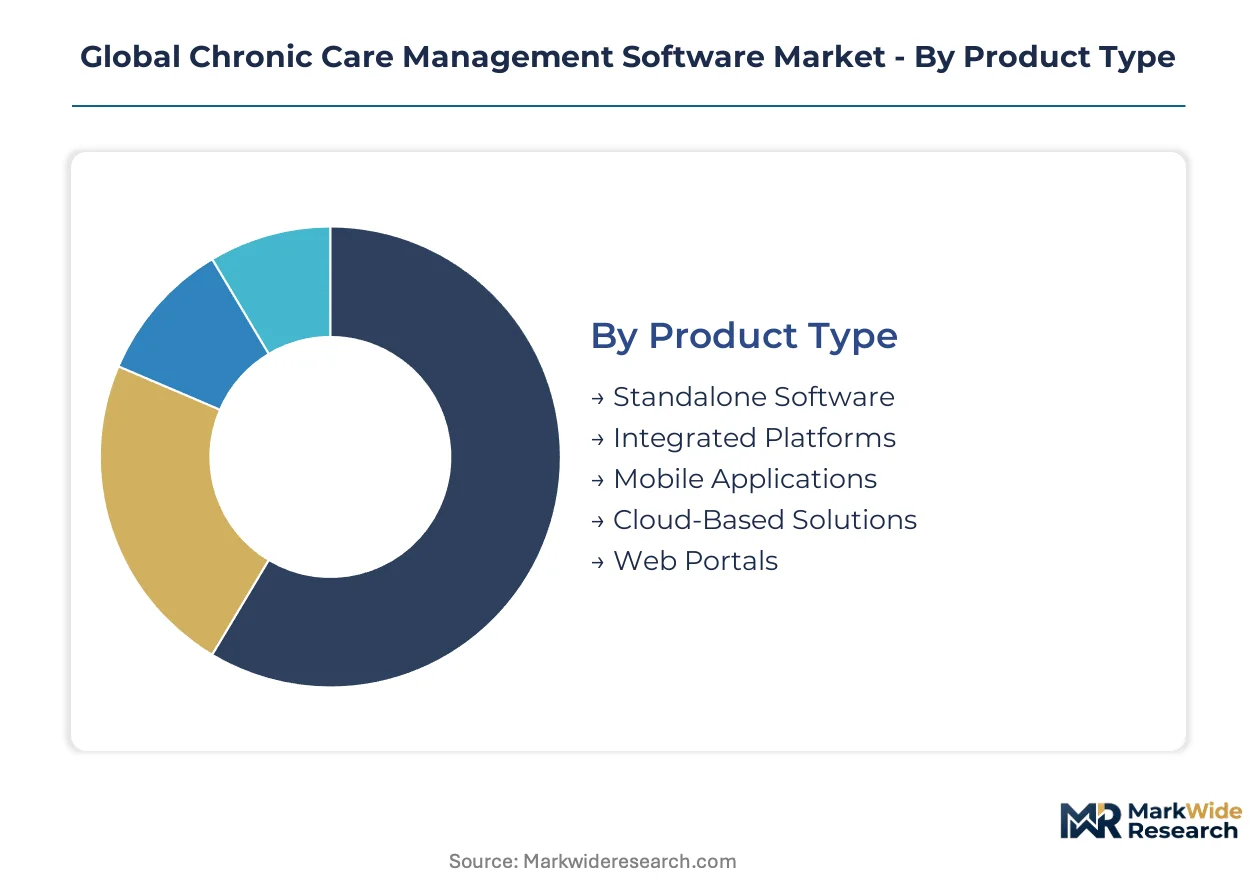
Chronic care management software segments reflect divergent buyer priorities across capital intensity, clinical workflow depth, and reimbursement capture. Procurement patterns split sharply between health systems seeking unified architectures and smaller practices prioritizing rapid deployment.
Product Type:
Buyer differentiation centers on integration requirements versus speed-to-value tradeoffs.
- Integrated Platforms:Unified architectures embed EHR connectivity, billing automation, and analytics within single vendor relationships. Kaiser Permanente and Providence Health in the US Pacific Northwest consolidate supplier bases around these systems to meet hospital admission reduction guarantees.
- Cloud-Based Solutions:AWS and Azure-hosted deployments eliminate capital expenditure for server infrastructure. German hospital networks in Bavaria and North Rhine-Westphalia migrate fastest, driven by METI-aligned digital health subsidies and compressed IT procurement cycles.
- Standalone Software:Point solutions target specific conditions without EHR integration overhead.
- Mobile Applications:Patient-facing interfaces for medication adherence and symptom logging.
- Web Portals:Browser-based care team dashboards with lower device compatibility burdens.
Integrated platforms lead volumes today; cloud-based solutions are gaining share fastest.
Application:
Condition-specific modules concentrate where biometric sensor penetration and CMS reimbursement alignment overlap.
- Diabetes Management:Continuous glucose monitor integration and automated insulin dosing recommendations dominate development roadmaps. Japanese prefectures with super-aging demographics—Aichi and Osaka—deploy predictive analytics modules for Type 2 populations under METI subsidy programs.
- Cardiovascular Monitoring:Blood pressure telemetry and arrhythmia detection anchor remote patient monitoring bundles. Rural US counties in Texas and California face specialist physician shortages that constrain enrollment capacity despite platform availability.
- Respiratory Care:Spirometry and pulse oximetry tracking for COPD populations.
- Mental Health Support:Mood monitoring and therapy adherence tools.
- Arthritis Tracking:Pain score trending and mobility assessment workflows.
Cardiovascular monitoring commands the largest installed base; diabetes management shows the steepest expansion trajectory.
End User:
Customer type determines pricing tolerance, implementation complexity, and regulatory exposure.
- Primary Care Providers:Medicare-centric practices in the US Southwest adopt automated care coordination for CPT 99490 and 99491 reimbursement capture. ChartSpan targets this segment with narrow-focus tools that minimize training overhead.
- Specialty Clinics:Endocrinology and cardiology practices demand deep clinical workflow specialization. ZeOmega anchors its market position through multi-condition population management in German university hospitals.
- Home Health Agencies:Post-acute care coordination and patient outreach.
- Telehealth Services:Virtual-first delivery models with asynchronous monitoring.
- Rehabilitation Centers:Functional recovery tracking and therapy plan adherence.
Primary care providers generate the highest transaction volumes; specialty clinics deliver the deepest per-contract values.
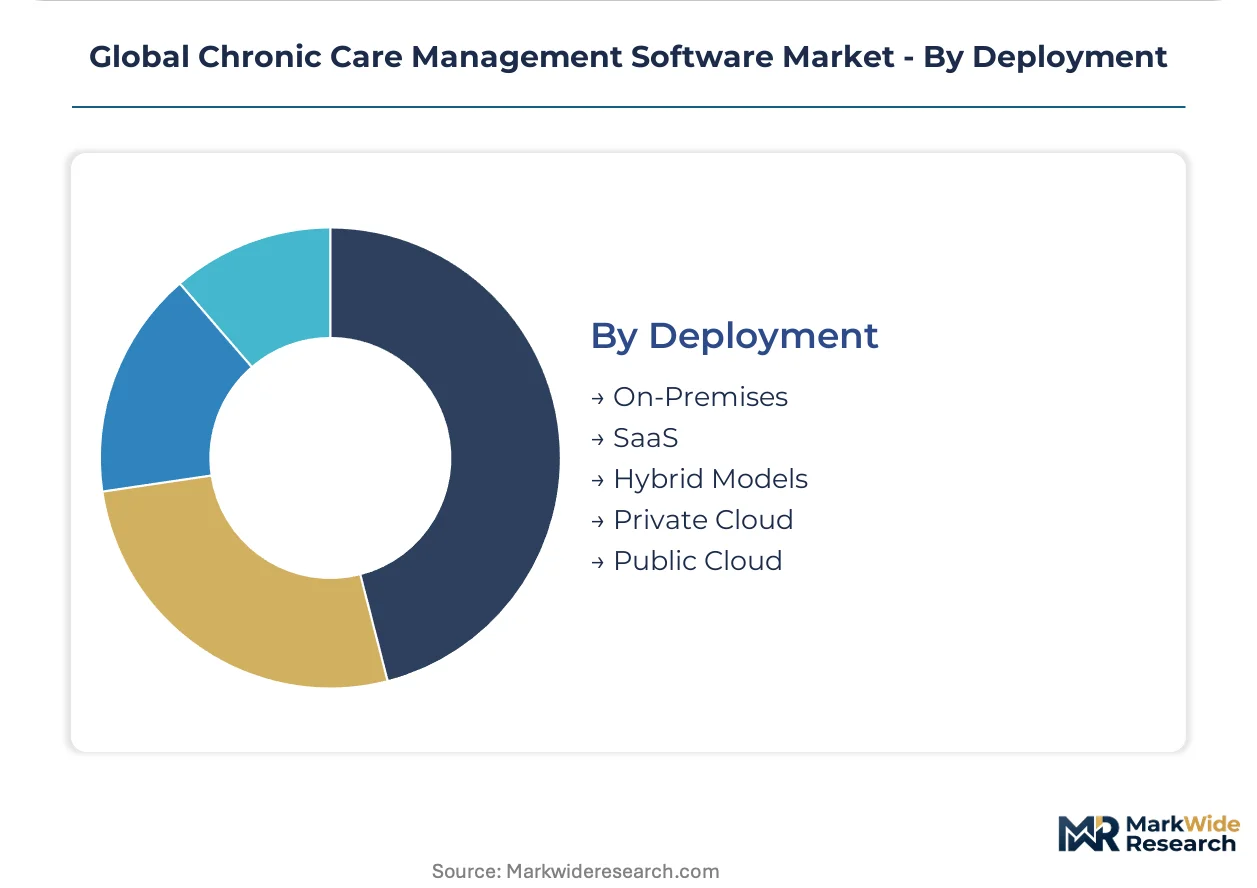
Deployment:
Infrastructure choice reflects data sovereignty requirements and legacy system entanglement.
- SaaS:Subscription pricing eliminates per-patient licensing fees that burden Federally Qualified Health Centers in Texas and California. Community health centers pilot FHIR-native APIs fastest under this model.
- Hybrid Models:Split architectures keep protected health information on-premises while pushing analytics to cloud environments. German hospital procurement committees embed EU AI Act algorithm transparency requirements into RFP scoring for these deployments.
- On-Premises:Capital-intensive server ownership with full data control.
- Private Cloud:Single-tenant hosted environments for security-sensitive institutions.
- Public Cloud:Multi-tenant shared infrastructure with lowest unit economics.
SaaS dominates new procurement; hybrid models are climbing the fastest as HIPAA and GDPR compliance burdens intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Health informatics talent clusters in Boston, Berlin, and Tokyo anchor regional platform development, while reimbursement policy divergence shapes vendor entry strategies across national boundaries.
United States
Accountable care organizations in the Pacific Northwest and Southwest consolidate supplier relationships around enterprise platforms that bundle telehealth, remote monitoring, and care management. CMS reimbursement codes for CPT 99490 and 99491 services accelerate physician practice adoption of automated workflows. Kaiser Permanente in California and Providence Health in Oregon reduce their CCM supplier bases by sixty percent since 2022.
Germany
Hospital networks in Bavaria and North Rhine-Westphalia migrate fastest to cloud-based deployments, driven by compressed IT procurement cycles and digital health infrastructure subsidies. EU AI Act algorithm transparency requirements embed into RFP scoring rubrics, favoring vendors with regulatory affairs infrastructure. ZeOmega anchors its market position through deep clinical workflow specialization in university hospitals across Baden-Württemberg.
Japan
METI digital health subsidies for diabetes and dementia management create entry points for predictive analytics modules targeting super-aging prefectures. Aichi and Osaka deploy Type 2 population management tools under national subsidy programs. The PMDA oversees software-as-medical-device classifications for AI-driven clinical decision support.
United Kingdom
The MHRA creates divergent compliance burdens from FDA pathways, favoring regionally established players with dedicated regulatory affairs teams. London-based health systems pilot FHIR-native APIs to decentralize data ownership from monolithic EHR vendors. Procurement committees embed training data provenance requirements into vendor selection criteria.
India
Software development hubs in Bangalore and Hyderabad supply engineering talent for cloud-native CCM platforms serving export markets. CDSCO oversight of clinical decision-support software creates compliance frameworks for domestic deployment. Health IT vendors leverage cost arbitrage in development while targeting US and European customers.
Global Chronic Care Management Software Market Competitive Landscape
Top-tier vendors anchor integrated platform architectures, while mid-tier specialists compete through condition-specific workflow depth. The market structure splits between payer-provider conglomerates with reimbursement capture advantages and pure-play vendors with clinical specialization. Three strategic archetypes dominate: enterprise consolidators bundling analytics and billing, Medicare-centric coordinators targeting smaller practices, and workflow specialists anchoring multi-condition populations. Competitive moves center on strategic partnerships with specialty pharmacy networks and M&A activity compressing point solution vendors.
Within the payer-integrated tier, Optum, Inc. exemplifies vertical control spanning insurance and provider networks. ChartSpan occupies a position among Medicare-focused coordinators serving smaller physician practices with rapid deployment tools. ZeOmega anchors the clinical workflow specialist archetype through deep multi-condition population management. These three vendors represent divergent strategic bets on whether scale, reimbursement proximity, or clinical depth wins procurement cycles.
| Leading Market Players |
|---|
| Optum, Inc. |
| ExlService Holdings, Inc. |
| NXGN Management, LLC. |
| Cognizant |
| Medecision |
| Veradigm LLC |
| ZeOmega |
| CareHarmony, Inc. |
| ChartSpan |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up software specialists now control the mid-tier vendor landscape, compressing procurement cycles while enforcing subscription pricing discipline that ties annual contract values to patient enrollment guarantees rather than perpetual licenses.
Pricing Analysis
The bundled-versus-unbundled service split defines pricing architecture across the chronic care management software market. Integrated platforms command premium positioning through unified EHR connectivity, billing automation, and analytics under single-vendor relationships, while standalone modules compete on rapid deployment and lower entry thresholds. Three-tier pricing structure across enterprise, mid-market, and practice-level tiers reflects integration depth and care team training overhead. Cost compression in the mid-market tier intensifies as cloud infrastructure migration eliminates capital expenditure barriers and compresses vendor margins. Federally Qualified Health Centers in Texas and California exhibit highest price sensitivity due to constrained operating budgets, while Kaiser Permanente and Providence Health demonstrate lowest sensitivity given performance-guarantee contracting structures.
Supply Chain Analysis
Dual-sourcing requirements from US hospital procurement committees mandate multi-supplier qualification for critical platform components, fragmenting vendor concentration despite enterprise consolidation trends. Engineering talent clusters draw from India, Poland, and Vietnam for cloud-native development, while clinical workflow specialization rests on US and German health informatics expertise. Raw material dependencies center on AWS and Azure compute infrastructure, HL7 FHIR middleware libraries, and biometric sensor APIs from continuous glucose monitor and blood pressure device manufacturers. Single-source vulnerability concentrates in Epic and Cerner EHR integration layers where proprietary APIs create switching friction. Distribution runs through direct enterprise sales teams for health systems and value-added resellers for smaller physician practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in chronic care management software hinges on cloud infrastructure cost-down trajectories and the shift toward value-based contracting that ties vendor compensation to hospital admission reduction outcomes.
For Market Incumbents: Hedge platform commoditization risk by deepening clinical workflow specialization in multi-condition populations and securing backward integration into biometric sensor data streams. Invest in FDA software-as-medical-device regulatory affairs infrastructure to capture AI-augmented risk stratification premiums. Defensive consolidation around integrated architectures protects against point-solution disintermediation while performance guarantees lock in long-term contract renewals.
For New Entrants and Emerging Players: Enter via Japan's super-aging prefectures where METI digital health subsidies reduce customer acquisition costs and algorithm transparency requirements under EU AI Act provisions favor venture-stage transparency. Target Federally Qualified Health Centers in Texas and California with FHIR-native subscription pricing that eliminates per-patient licensing friction. Lead with diabetes management predictive analytics modules where continuous glucose monitor integration creates immediate workflow value.
For Investors and Strategic Acquirers: Valuations sit cheapest among clinical workflow specialists with deep multi-condition population management capabilities and established German university hospital footprints. Long-term viability over the coming decade rests on vendors capturing specialty pharmacy integration channels and ambient clinical intelligence deployment. Acquisition target archetype: SaaS-native platforms with proven CMS reimbursement code capture and sub-12-month implementation timelines. Watch for inflection when CMS expands remote patient monitoring reimbursement beyond current CPT 99490 and 99491 frameworks.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Epic and Cerner FHIR-native API consolidation reduces vendor switching costs for Kaiser Permanente and Providence Health. |
| Strategic Partnership | CVS Health and Walgreens specialty pharmacy networks offer new distribution channels for medication adherence tool vendors. |
| Acquisition of Specialist Firm | Clinical workflow depth in diabetes and cardiovascular modules anchors defensive positioning against enterprise consolidators. |
| Geographic Expansion | METI subsidies in Aichi and Osaka prefectures create subsidized entry points for predictive analytics module deployment. |
| Reimbursement Strategy | CMS CPT 99490 and 99491 code optimization determines physician practice adoption velocity and vendor contract renewal rates. |
Research Methodology
Multiple input streams — structured interviews with health system CIOs and CMIOs, procurement database analysis from GPO contracts and CMS Medicare claims, and regulatory filing review from FDA and PMDA submissions — were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged care coordination directors, revenue cycle managers, biomedical informaticists, and EHR integration specialists across US, German, and Japanese health systems. Secondary validation drew from hospital procurement committee minutes, accountable care organization performance reports, HL7 FHIR implementation case studies, and digital health subsidy program disclosures from METI and EU innovation frameworks.
Historical patient enrollment trajectories and vendor contract value patterns were cross-referenced against panel input from health system executives and software procurement officers to anchor growth assumptions across the projection horizon. Segmentation modeling incorporated deployment architecture, care team size, condition-specific module requirements, EHR integration complexity, and regional reimbursement framework alignment. CAGRs were derived from patient population growth curves, CMS code utilization trends, and cloud infrastructure adoption velocity rather than simple linear extrapolation. Forecast inputs included specialist physician shortage projections, HIPAA compliance cost escalations, and AI Act algorithm transparency implementation timelines.
Inputs from health system procurement databases and regulatory submission records were available through the study window; gaps in longitudinal patient outcome data from remote monitoring deployments introduce uncertainty bands around hospital admission reduction guarantee modeling. Forecasts reflect assumptions regarding CMS reimbursement code stability, FHIR interoperability mandate enforcement, and cloud infrastructure cost trajectories. Deviation in FDA software-as-medical-device classification timelines or EU AI Act CE marking requirements would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Data Management
Europe Healthcare Analytics Market
Health Data Management
Americas Healthcare Archiving and Ediscovery Market
Health Data Management
Population Health Management Solutions Market
Health Data Management
Global Healthcare Financial Analytics Market
Health Data Management
Data Democratization in Healthcare Market
Health Data Management
Global Healthcare Data Storage Market
Health Data Management
Global Big Data Analytics in Healthcare Market
Health Data Management
Global Healthcare Data Analytics Market
Health Data Management
Medical Record Management System Market
Health Data Management
Master Data Management in Healthcare Market
Health Data Management
Clinical Trial Data Management Software Market
Health Data Management
Healthcare Archiving and Ediscovery Market
Health Data Management
Global Healthcare Fraud Analytics Market
Health Data Management
North America Healthcare Analytics Market
Health Data Management
Population Health Management Platforms Market
Health Data Management
Data Monetization in Healthcare Market