

Healthcare Data De-Identification Assurance Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Data De-Identification Assurance Market Insights
The EU AI Act is restructuring procurement criteria for healthcare artificial intelligence systems across European health networks, compelling vendors to demonstrate verifiable de-identification pipelines before market access. IQVIA Privacy Analytics leverages its embedded position within clinical data ecosystems to sustain long-term contracts with major pharmaceutical sponsors. Datavant anchors the North American interoperability layer through its tokenization infrastructure, while TripleBlind competes on privacy-preserving computation architectures that eliminate raw data movement entirely.
Healthcare data de-identification assurance encompasses technical processes and governance frameworks that transform protected health information into non-identifiable datasets through statistical disclosure control, pseudonymization algorithms, and differential privacy mechanisms, enabling secondary use for research and analytics without re-identification risk. Cloud-based services are capturing the fastest expansion as health systems migrate from capital-intensive on-premise installations to consumption-priced SaaS models with embedded compliance monitoring. Software platforms still dominate absolute revenue contribution due to enterprise licensing structures at hospital networks, though hybrid models are emerging where sensitive genomics data remains local while analytics execute in federated cloud nodes.
FDA guidance on determining substantial equivalence for de-identified data streams, coupled with HIPAA Safe Harbor and Expert Determination pathways, creates a dual-track compliance environment that shapes vendor product architecture and customer implementation roadmaps. The EU GDPR and emerging EMA data transparency frameworks add cross-border complexity for multinational clinical trial sponsors operating across jurisdictions. Stakeholders must monitor whether emerging synthetic data standards from ISO technical committees will displace traditional anonymization as the preferred method for privacy-preserving health data sharing.
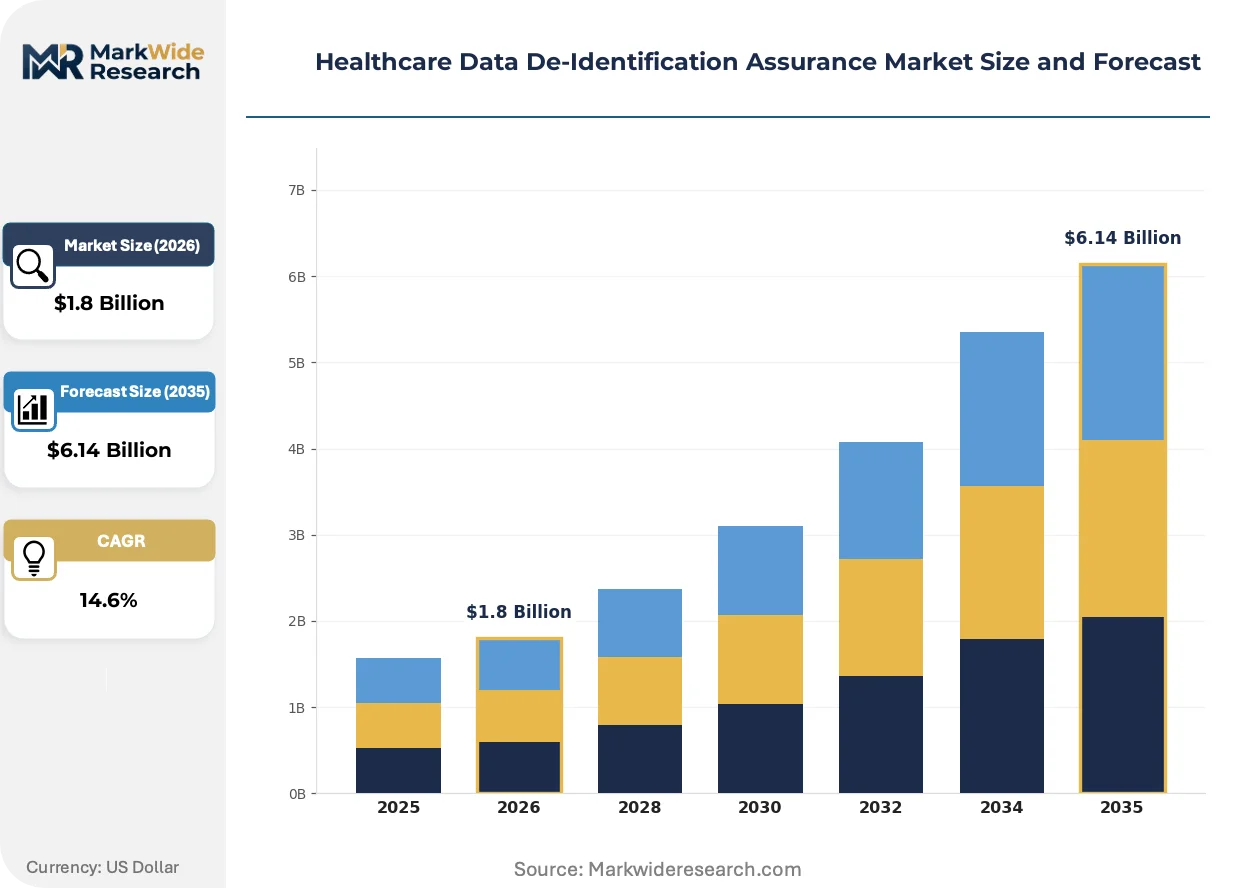
Market Dynamics
The convergence of HIPAA Safe Harbor refinements and EU AI Act anonymization mandates is compressing vendor certification timelines while elevating technical bar requirements for market access.
Growth Catalysts
- Real-world evidence mandates:Pharmaceutical sponsors require de-identified patient streams for post-market surveillance, expanding contract volumes with specialized assurance vendors.
- Federated analytics architectures:Privacy-preserving computation eliminates raw data movement between institutions, enabling multi-site research without centralized data lakes.
- Cloud migration tailwinds:Health systems in the United States are abandoning capital-intensive on-premise installations for consumption-priced SaaS models with embedded compliance monitoring.
Market Restraints
- Genomic re-identification risk:DNA sequences retain latent identifiability even after standard anonymization, limiting secondary use of biobank assets.
- Cross-border data friction:GDPR adequacy decisions and emerging EMA transparency frameworks create jurisdictional complexity for multinational trial sponsors.
- Expert Determination cost concentration:HIPAA's statistical disclosure control pathway requires scarce qualified statisticians, inflating compliance costs for mid-tier health systems.
Strategic Opportunities
- Synthetic data standards emergence:ISO technical committees are developing privacy-preserving health data generation protocols that may displace traditional anonymization for certain research applications.
- Asia-Pacific regulatory alignment:Japan's PMDA and South Korea's MFDS are harmonizing data anonymization requirements with Western frameworks, opening procurement channels for certified vendors.
- Tokenization infrastructure expansion:Patient identity tokens enable longitudinal record linkage without exposing direct identifiers, creating new interoperability revenue streams.
Industry Challenges
- Differential privacy engineering scarcity:Health systems lack personnel trained in epsilon-budget management and noise injection calibration for regulatory-grade implementations.
- Legacy EHR integration complexity:Decades-old hospital information systems require custom API development to feed modern de-identification pipelines, extending deployment timelines.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Data De-Identification Assurance Market Trends and Innovations
Technical architectures for privacy-preserving health analytics are bifurcating between tokenization-based interoperability layers and computation-over-encrypted-data approaches, with regulatory pressure determining adoption velocity by geography.
Synthetic data generation is overtaking statistical disclosure control as the preferred method for sharing sensitive health records in research consortia. Academic medical centers in Germany and the Netherlands are piloting generative adversarial networks that produce artificial patient profiles preserving population-level statistical properties. This shift is compressing demand for traditional anonymization consulting services while expanding software licensing for synthetic data platforms.
The EU AI Act's risk-classification framework is restructuring procurement criteria for healthcare artificial intelligence systems across European health networks. High-risk clinical decision support tools must demonstrate verifiable de-identification pipelines before market authorization, forcing vendors to embed technical safeguards earlier in product development. Medical device manufacturers are responding by acquiring specialized privacy engineering capabilities.
Subscription-based assurance models are displacing perpetual software licenses in hospital network procurement. Chief information officers now prioritize vendors offering continuous compliance monitoring and automated re-identification risk scoring over one-time implementation projects. This preference shift is most visible in United States integrated delivery networks consolidating vendor relationships under enterprise-wide agreements.
Healthcare Data De-Identification Assurance Market Segmentation
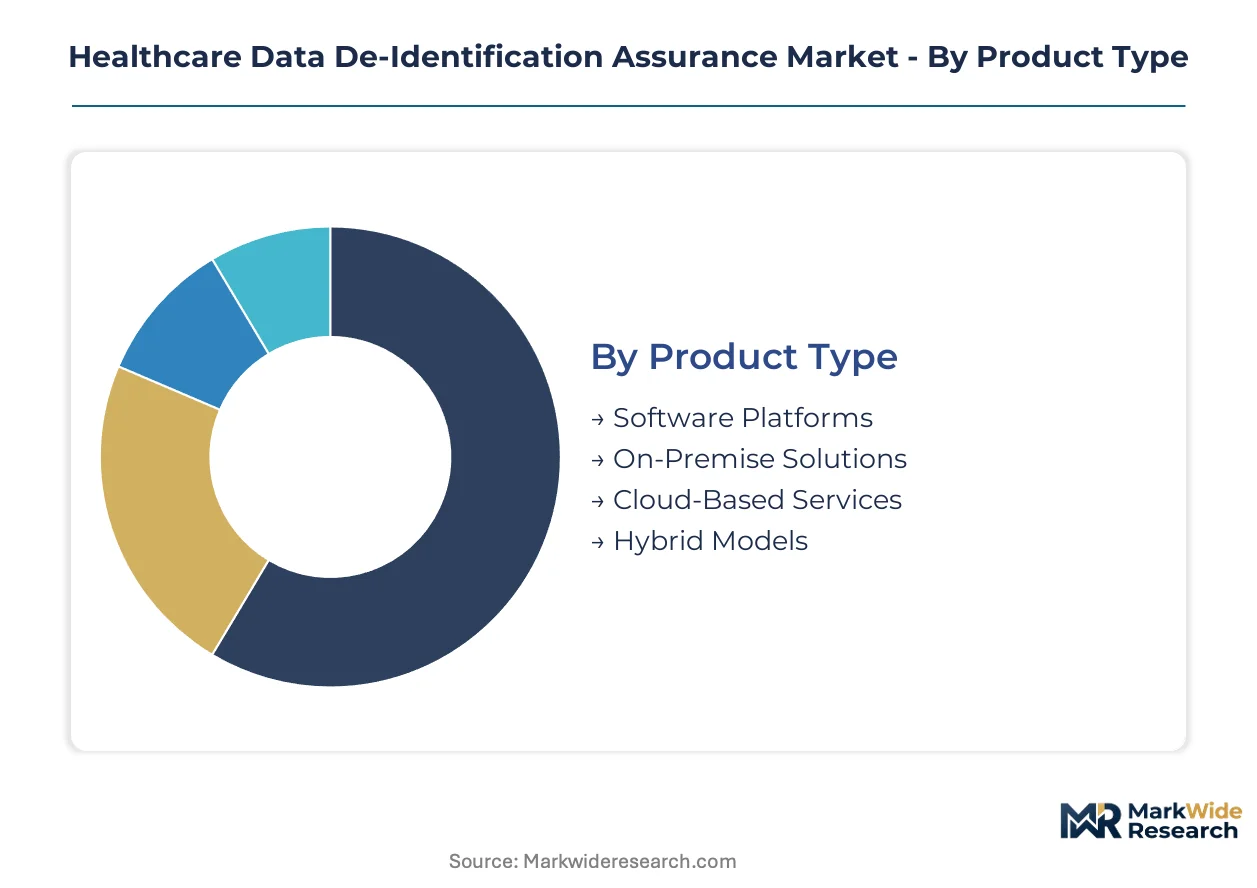
De-identification assurance vendors configure product architectures around four intersecting dimensions: technical delivery mode, clinical use case, buyer procurement sophistication, and infrastructure sovereignty requirements. Each segmentation axis reveals distinct pricing power, implementation complexity, and compliance obligation patterns.
Product Type:
Buyer cost tier determines whether organizations license perpetual software, subscribe to managed services, or operate hybrid estates splitting sensitive processing from analytics.
- Software Platforms:Enterprise licensing structures dominate hospital network procurement, with perpetual deployments anchoring revenue concentration through multi-year maintenance contracts. Academic medical centers in Germany and integrated delivery networks in the United States favor this model for genomics pipelines requiring local control.
- Cloud-Based Services:Consumption-priced SaaS models with embedded compliance monitoring are capturing the steepest expansion trajectory as health systems abandon capital-intensive installations. Mid-tier United States hospitals lacking in-house privacy engineering personnel drive subscription volumes.
- On-Premise Solutions:Sovereign data requirements from national biobanks and military health systems sustain demand despite higher total cost of ownership.
- Hybrid Models:Sensitive genomics data remains local while federated analytics execute in cloud nodes, addressing HIPAA Safe Harbor and EU GDPR cross-border constraints simultaneously.
Software platforms anchor absolute revenue today; cloud-based services are climbing the fastest.
Application:
Regulatory pressure intensity varies sharply by use case, with clinical research and cross-border data sharing facing the most stringent anonymization verification requirements.
- Regulatory Compliance:HIPAA Safe Harbor and Expert Determination pathways, plus EU AI Act mandates for high-risk clinical decision support, create dual-track compliance environments shaping vendor product roadmaps. Pharmaceutical sponsors allocate the largest implementation budgets here.
- Clinical Research:Real-world evidence mandates from FDA and EMA post-market surveillance programs expand contract volumes with specialized assurance vendors. Multi-site federated analytics eliminate raw data movement between institutions.
- Patient Privacy:State-level breach notification laws in California and New York drive recurring risk assessment demand.
- Data Sharing:Tokenization infrastructure enables longitudinal record linkage without exposing direct identifiers.
- Fraud Detection:Health insurance firms apply pattern recognition to de-identified claims streams for anomaly detection.
Regulatory compliance commands premium pricing; clinical research shows the fastest contract velocity acceleration.
End User:
Procurement sophistication and technical staffing depth separate buyers, with pharmaceutical companies driving advanced feature requirements and hospitals prioritizing turnkey implementation.
- Pharmaceutical Companies:Post-market surveillance obligations and real-world evidence mandates accelerate adoption of de-identification tools for unlocking patient streams while preserving privacy. Sponsors demand verifiable pipelines before clinical trial data sharing.
- Hospitals & Healthcare Providers:Chief information officers prioritize vendors offering continuous compliance monitoring and automated re-identification risk scoring over one-time implementation projects.
- Research Institutes:Academic medical centers pilot synthetic data generation using generative adversarial networks that produce artificial patient profiles.
- Health Insurance Firms:Claims analytics and fraud detection applications require high-throughput de-identification at population scale.
Pharmaceutical companies dominate enterprise deal sizes; research institutes are expanding procurement most rapidly.
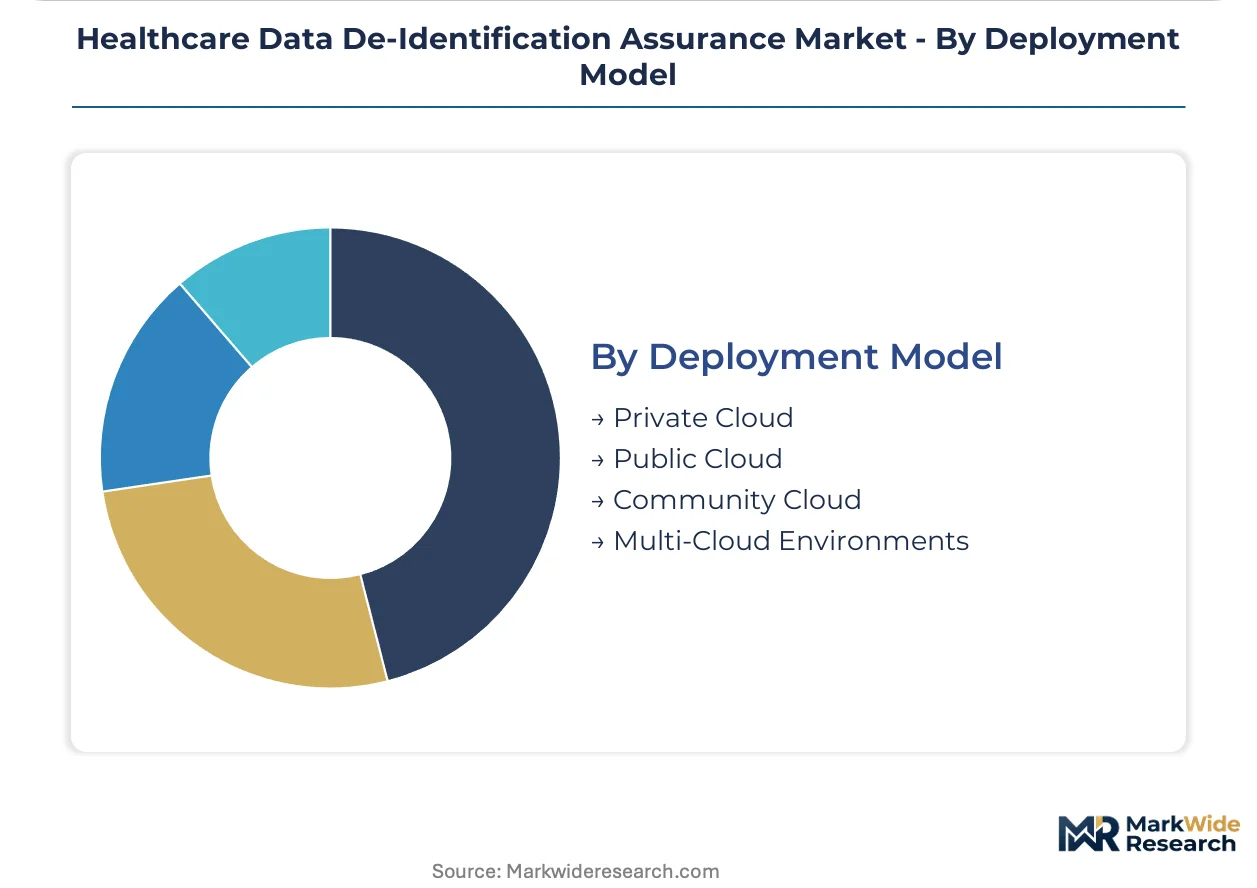
Deployment Model:
Infrastructure sovereignty requirements and data residency regulations determine cloud architecture selection, with multi-cloud strategies emerging to satisfy conflicting jurisdictional mandates.
- Private Cloud:Single-tenant environments satisfy HIPAA and GDPR requirements for health systems processing sensitive genomics data. National biobanks in the Netherlands and military health systems mandate this architecture.
- Multi-Cloud Environments:Workload portability across hyperscalers addresses vendor lock-in concerns while enabling geographic data residency compliance. Multinational clinical trial sponsors operating across United States and European jurisdictions drive adoption.
- Public Cloud:Shared infrastructure delivers cost efficiency for non-sensitive analytics workloads and development environments.
- Community Cloud:Collaborative platforms serve regional health information exchanges and research consortia with common governance frameworks.
Private cloud retains the largest installed base; multi-cloud environments are gaining adoption fastest among multinational sponsors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States pioneered HIPAA Safe Harbor methodologies in the late 1990s, establishing the technical and legal foundations that spread to other jurisdictions. Health system digitization and research data liquidity requirements continue concentrating procurement demand in North America.
United States
Post-market surveillance mandates from FDA accelerate pharmaceutical sponsor spending on verifiable de-identification pipelines. HIPAA Safe Harbor and Expert Determination pathways create dual-track compliance environments that shape vendor product architectures. Academic medical centers in Massachusetts and California pilot federated analytics eliminating raw data movement between institutions.
Germany
EMA data transparency frameworks and national biobank sovereignty requirements sustain demand for on-premise solutions with local control. EU AI Act anonymization mandates for high-risk clinical decision support compel vendors to embed technical safeguards earlier in development. Research consortia in Heidelberg and Munich deploy generative adversarial networks producing synthetic patient profiles.
United Kingdom
NHS Digital transformation programs expand procurement for cloud-based services with embedded compliance monitoring. GDPR adequacy decisions and emerging MHRA guidance on real-world evidence create cross-border complexity for multinational trial sponsors. London-based integrated delivery networks consolidate vendor relationships under enterprise-wide subscription agreements.
Japan
PMDA harmonization with Western anonymization frameworks opens procurement channels for certified international vendors. Pharmaceutical manufacturers in Tokyo and Osaka require de-identified patient streams for post-market surveillance obligations. METI funding for privacy-preserving computation research accelerates adoption of tokenization infrastructure.
Netherlands
National biobank sovereignty requirements and GDPR stringency sustain private cloud deployments for sensitive genomics processing. Academic medical centers in Amsterdam and Rotterdam lead European pilots in synthetic data generation for research consortia. EMA headquarters proximity concentrates regulatory-grade assurance vendor activity.
Healthcare Data De-Identification Assurance Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and regulatory-grade implementation capability. The vendor base clusters around three strategic archetypes: embedded clinical data ecosystem operators, privacy-preserving computation architects, and synthetic data platform specialists. Consolidation pressure intensifies as medical device manufacturers acquire specialized privacy engineering capabilities. Strategic partnerships between tokenization infrastructure providers and cloud hyperscalers represent the dominant competitive move alongside vertical integration into federated analytics orchestration.
Within the embedded ecosystem tier, IQVIA Privacy Analytics and Datavant occupy positions anchoring long-term pharmaceutical sponsor relationships through clinical data network integration. TripleBlind represents the privacy-preserving computation archetype, competing on architectures that eliminate raw data movement entirely. These three companies exemplify how technical differentiation across tokenization, statistical disclosure control, and encrypted computation creates defensible positioning against commodity anonymization tools.
| Leading Market Players |
|---|
| Datavant |
| IQVIA Privacy Analytics |
| John Snow Labs |
| MDClone |
| Privacert |
| TripleBlind |
| Duality Technologies |
| Enveil |
| Tonic.ai |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between HIPAA Expert Determination vendors and commodity Safe Harbor tool providers manifests in divergent pricing architectures and supply chain configurations. Premium-grade assurance vendors command enterprise licensing premiums through embedded clinical data network positions, while commodity anonymization software faces cost compression from open-source alternatives and cloud-native entrants.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates vendor revenue models, with differentiation anchored in certification depth and regulatory-grade implementation capability. Premium tiers bundle continuous compliance monitoring and automated re-identification risk scoring; economy tiers offer basic pseudonymization without statistical disclosure control. Pricing pressure stems from cloud-native SaaS entrants undercutting perpetual license maintenance contracts. Mid-tier United States hospitals exhibit highest price sensitivity, while pharmaceutical sponsors prioritize verifiable pipeline assurance over cost minimization.
Supply Chain Analysis
Domestic-content mandates in Germany, Japan, and South Korea are reshaping sourcing patterns for sensitive health data processing infrastructure. Software development concentrates in the United States, Israel, and Estonia, while cloud compute infrastructure draws from hyperscaler regions in Virginia, Frankfurt, and Tokyo. Single-source vulnerability runs through tokenization algorithm providers and specialized differential privacy engineering talent pools. Distribution runs through direct enterprise sales teams for hospital networks and clinical research organizations, with channel partnerships serving mid-tier health systems lacking procurement sophistication.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
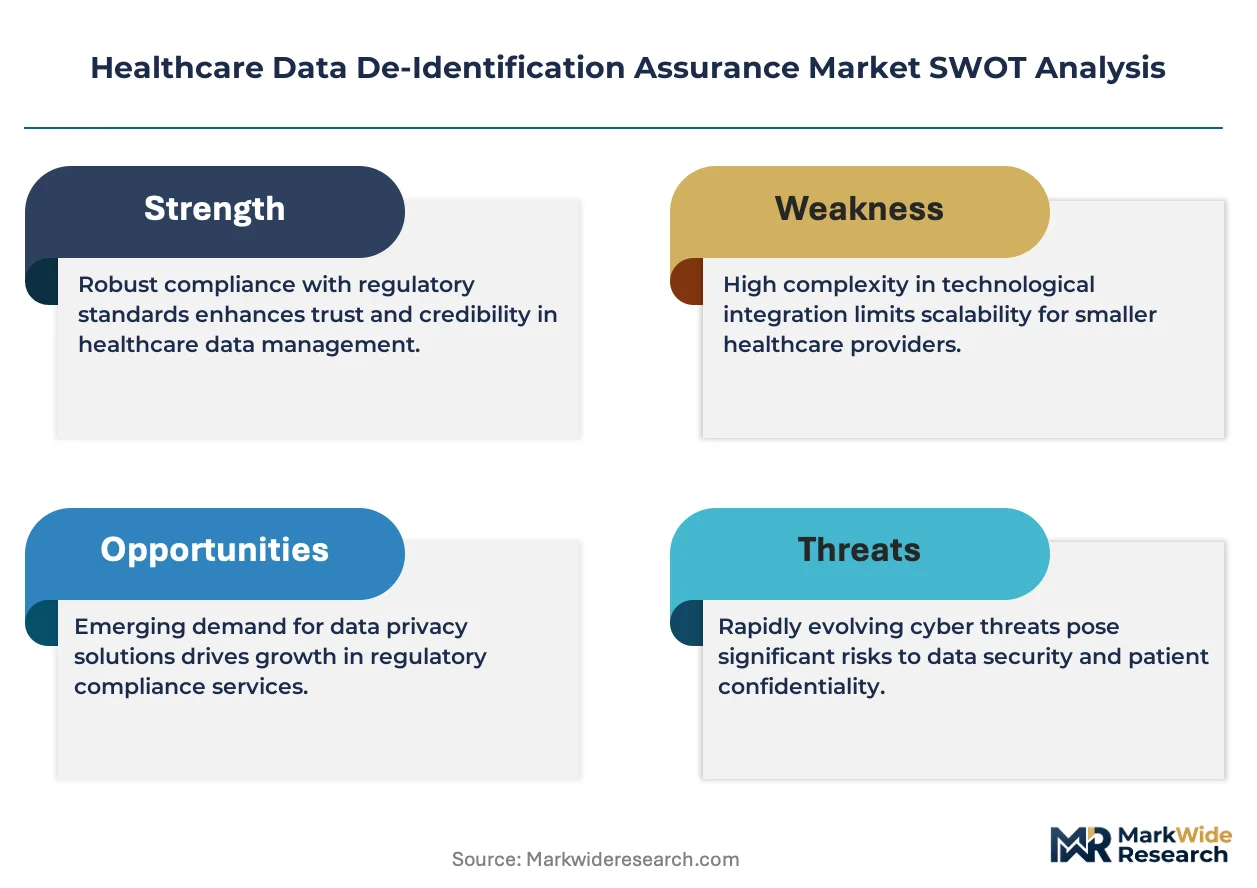
This market compounds steadily as regulatory fragmentation across jurisdictions forces continuous compliance investment. HIPAA refinements and EU AI Act mandates create durable demand for assurance services regardless of macroeconomic cycles.
For Market Incumbents: Deepen embedded positions within clinical data ecosystems through federated analytics orchestration capabilities that eliminate raw data movement. Acquire specialized differential privacy engineering teams to defend margin position against cloud-native entrants offering automated anonymization at commodity price points. Extend certification coverage to emerging synthetic data standards before ISO technical committees finalize protocols. For New Entrants and Emerging Players: The price-point gap between premium Expert Determination services and basic Safe Harbor tools creates white-space opportunity in mid-market hospital networks seeking automated compliance without enterprise consulting overhead. Target United States integrated delivery networks consolidating vendor relationships under enterprise-wide agreements. Lead with consumption-priced SaaS models featuring embedded re-identification risk scoring to bypass incumbent maintenance contract lock-in. For Investors and Strategic Acquirers: Consolidation pressure builds where medical device manufacturers lack in-house privacy engineering capabilities for EU AI Act compliance. The market exhibits long-term viability as a regulated services compounder with recurring revenue characteristics. Prioritize acquisition targets possessing tokenization infrastructure and pharmaceutical sponsor relationships. Watch FDA guidance on synthetic data equivalence as the inflection indicator for displacement risk to traditional anonymization.| Strategic Initiative | Industry Significance |
|---|---|
| Federated Analytics Platform Integration | Eliminates raw data movement between institutions, satisfying HIPAA and EU AI Act cross-border constraints simultaneously. |
| Synthetic Data Generation Capability Acquisition | Positions vendors ahead of ISO technical committee standards that may displace statistical disclosure control methods. |
| Tokenization Infrastructure Partnership | Enables longitudinal record linkage revenue streams through patient identity tokens without direct identifier exposure. |
| Continuous Compliance Monitoring Launch | Captures subscription revenue from hospital CIOs prioritizing automated re-identification risk scoring over one-time projects. |
| Asia-Pacific Regulatory Certification Pathway | Opens procurement channels in Japan and South Korea as PMDA and MFDS harmonize with Western anonymization frameworks. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with privacy engineering leads at pharmaceutical sponsors, hospital CIOs, clinical data network operators, and regulatory affairs specialists at EMA and FDA with secondary validation. Bottom-up triangulation against top-down market sizing utilized hospital procurement databases, GPO contracts, CMS Medicare data, and clinical trial registry filings. The approach cross-referenced vendor licensing disclosures, cloud hyperscaler health vertical revenue segmentation, and academic medical center pilot program documentation.
Segment-weighting across product type, application, end user, and deployment model dimensions structured the analytical framework over the projection horizon. Modeled dimensions included technical delivery mode, clinical use case sophistication, buyer procurement maturity, and infrastructure sovereignty requirements. CAGRs derived from elasticity analysis of pharmaceutical R&D spending, health system cloud migration velocity, and regulatory enforcement intensity. Forecast inputs incorporated HIPAA Safe Harbor refinement timelines, EU AI Act implementation phases, and synthetic data standardization progress.
The model assumes a particular technology adoption path; alternative pathways for privacy-preserving computation architectures would alter the outlook if federated analytics deployment accelerates beyond baseline assumptions. Forecasts reflect documented assumptions about regulatory enforcement consistency and cloud migration rates. Genomic re-identification breakthroughs or GDPR adequacy decision reversals represent specific risk factors warranting revision. A small set of named triggers—FDA synthetic data guidance, ISO standard finalization, and major hospital network vendor consolidation—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.