
 Clinical Data Management Systems (CDMS) Market | 2026-2036
Clinical Data Management Systems (CDMS) Market Size, Share, and Industry Trends Forecast 2026-2036
Clinical Data Management Systems (CDMS) Market Analysis
Cloud infrastructure is pivoting away from legacy on-premises data hosting in clinical research economics. Oracle Corporation leverages its database heritage to anchor enterprise-scale CDMS deployments across multinational pharmaceutical sponsors. Veeva Systems differentiates through vertical software integration spanning clinical operations and regulatory submission workflows. Medidata Solutions specializes in cloud-native randomization and trial supply management modules that complement core data capture platforms.
Clinical Data Management Systems comprise software platforms that collect, validate, store, and analyze patient data from clinical trials and post-market surveillance, typically operating under ALCOA+ principles (attributable, legible, contemporaneous, original, accurate, plus complete, consistent, enduring, and available) with audit trail functionality embedded at the database level. Their primary commercial purpose is ensuring regulatory-compliant evidence generation for drug and device approval submissions while reducing query resolution cycles. Cloud-based deployment leads functionality expansion due to elastic computing demands during trial database lock periods, whereas on-premises installations retain preference among sponsors with strict data residency requirements. Contract research organizations represent the fastest-growing end-user category as sponsor companies outsource protocol execution to specialized service providers.
FDA 21 CFR Part 11 mandates electronic signature and audit trail standards that directly determine CDMS validation scope and software vendor qualification burdens. EMA's ICH E6(R2) Good Clinical Practice guidelines reinforce risk-based monitoring requirements that push platforms toward real-time data quality analytics and centralized statistical oversight. GDPR and HIPAA frameworks impose cross-border patient data transfer restrictions that shape server architecture decisions and subcontractor due diligence protocols. Stakeholders must weigh cloud provider geopolitical exposure against the operational agility required for adaptive trial designs.
Market Dynamics
Cloud migration is compressing database lock cycles from weeks to days, forcing vendors to rearchitect validation protocols around elastic compute infrastructure rather than fixed-capacity server farms.
Growth Catalysts
- Adaptive trial protocols:FDA guidance on master protocols enables basket and umbrella trial designs that require real-time data integration across multiple sites. Pharmaceutical sponsors demand platforms supporting mid-study amendments without database rebuilds.
- EMA ICH E6(R3) convergence:The guideline's emphasis on proportionate quality management pushes mid-tier CROs toward centralized monitoring dashboards. Risk-based data review replaces 100% source data verification.
- Decentralized trial expansion:Direct-to-patient data capture via wearable sensors and ePRO platforms generates unstructured data volumes. CDMS vendors embed AI-assisted coding modules to handle adverse event narratives.
Market Restraints
- Validation cost escalation:FDA 21 CFR Part 11 compliance requires documented IQ/OQ/PQ protocols for each software update. SaaS release cycles clash with pharmaceutical quality assurance timelines.
- Data residency fragmentation:China's Personal Information Protection Law and Russia's data localization rules force multi-region server deployments. Cloud providers must maintain separate instances per jurisdiction.
- Legacy system entrenchment:Large pharmaceutical sponsors operate hybrid environments where 1990s-era Oracle Clinical databases persist. Migration risk aversion delays full cloud transitions.
Strategic Opportunities
- Real-world evidence integration:EHR-to-EDC data pipelines enable hybrid trials combining randomized controlled data with observational cohorts. Platforms supporting FHIR standards capture this workflow.
- Patient-centric trial design:FDA's Project Patient Voice encourages direct patient-reported outcome capture. CDMS modules supporting eCOA and digital biomarkers differentiate vendor offerings.
- Asia-Pacific regulatory harmonization:Singapore's HSA and Australia's TGA mutual recognition agreements reduce duplicate database builds. Regional CROs seek single-platform multi-country submission support.
Industry Challenges
- Statistical programmer scarcity:SAS-to-R migration creates dual-skill requirements. CROs compete for talent capable of validating CDISC-compliant datasets in both languages.
- Interoperability protocol divergence:CDISC SDTM and ADaM implementation guides vary across therapeutic areas. Sponsor-specific mapping specifications prevent standardization.
- Cybersecurity validation burden:HIPAA Security Rule assessments and SOC 2 Type II audits extend vendor onboarding timelines. Penetration testing requirements add six-month procurement delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clinical Data Management Systems (CDMS) Market |
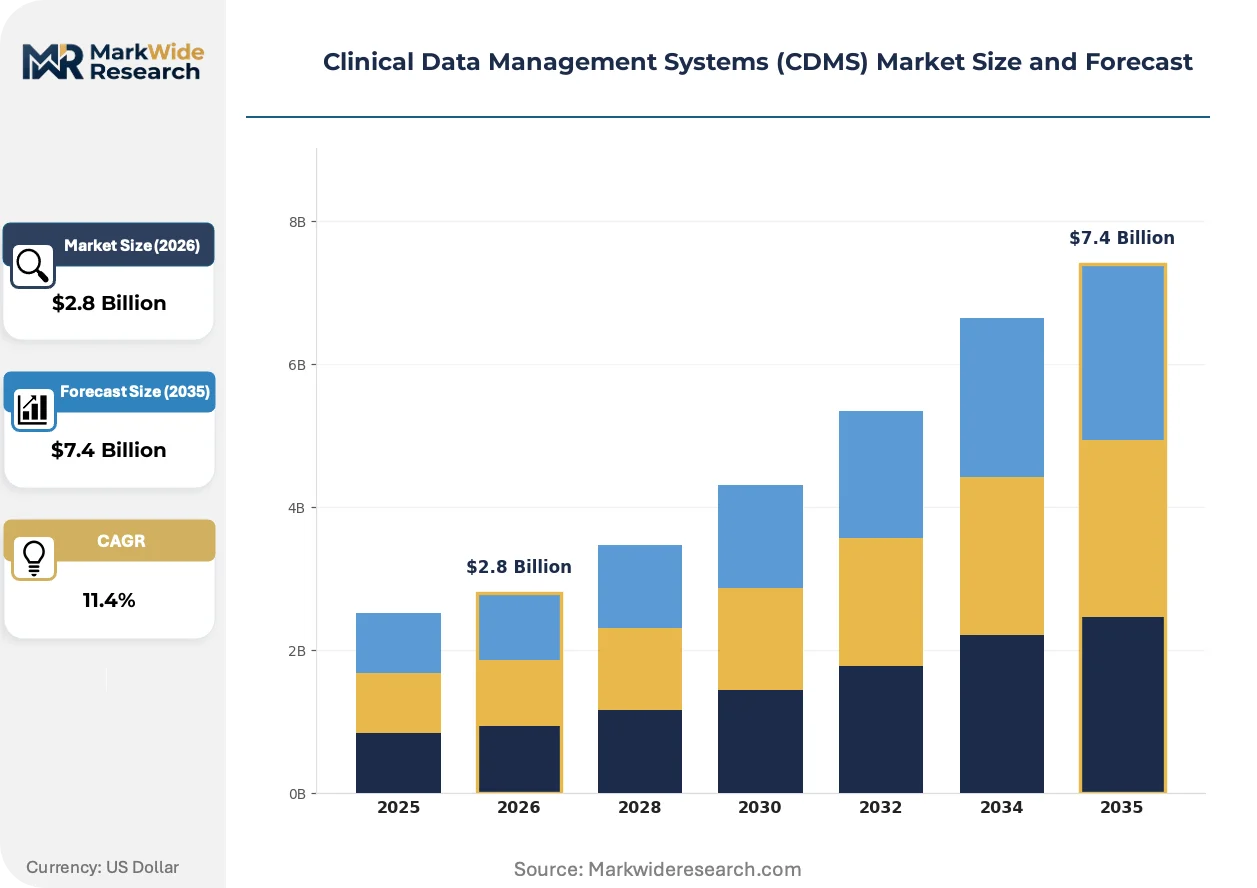
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application Type: Clinical Trials, Electronic Health Records, Patient Registries, Pharmacovigilance Deployment Model: On-Premises, Cloud-Based, Hybrid, Web-Based End User: Pharmaceutical Companies, Contract Research Organizations, Hospitals, Academic Institutions Functionality: Data Collection, Data Storage, Data Analysis, Reporting |
| Companies Covered | Oracle Corporation, Veeva Systems, Medidata Solutions, eClinical Solutions LLC, IBM Watson Health, Fortress Medical Systems, OpenClinica LLC, Ennov, Axiom Real-Time Metrics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clinical Data Management Systems (CDMS) Market Emerging Trajectories
Artificial intelligence is rewriting data management workflows from query generation to medical coding, compressing manual review cycles while introducing new validation complexities for algorithmic decision trails.
Natural language processing engines are overtaking manual medical coding for adverse event narratives. Large CROs deploy these tools across Phase III trials with 48-hour turnaround requirements. The technology is overtaking traditional dictionary coding workflows by extracting MedDRA preferred terms from unstructured physician notes without human intermediary review.
EMA's Clinical Trial Regulation (EU No 536/2014) mandates single submission portals through the Clinical Trials Information System. Sponsor companies reconfigure document management modules to support centralized EU portal uploads. Small biotech firms without Brussels regulatory affairs presence outsource CTIS navigation to specialized service providers.
Site payment automation is restructuring CRO-sponsor contracting models. Traditional per-visit fee structures give way to milestone-based disbursement tied to query resolution and database lock targets. This shift is most visible in oncology trials where adaptive designs compress enrollment windows and cash flow timing becomes critical for investigative sites.
Clinical Data Management Systems (CDMS) Market Segmentation
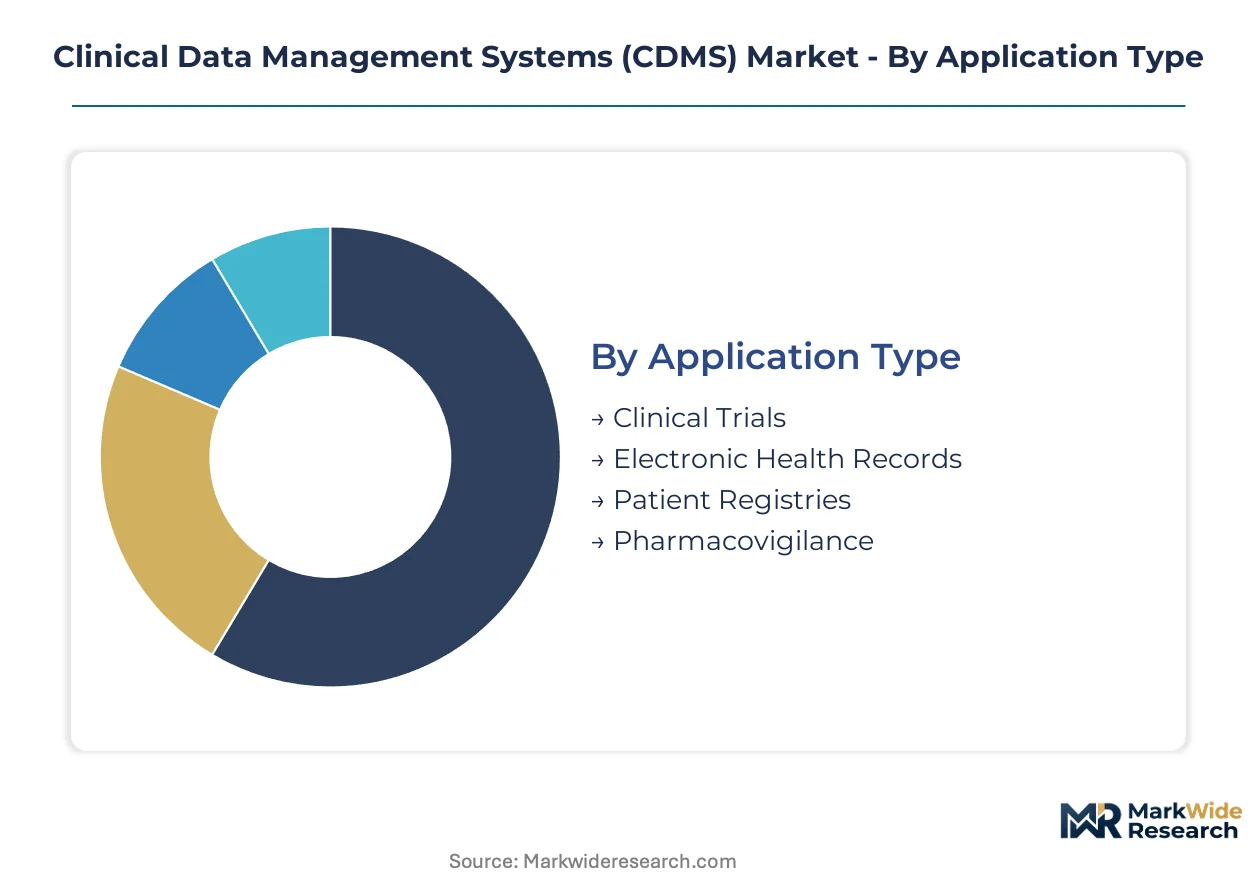
CDMS purchasing decisions hinge on trial complexity, regulatory jurisdiction, and data sensitivity. Each segmentation dimension reveals distinct capital allocation patterns and vendor selection criteria across sponsor organizations.
Application Type:
Clinical trial applications command the highest upfront platform investment due to validation rigor and audit trail requirements.
- Clinical Trials:Platforms manage protocol-specific case report forms, randomization schedules, and query workflows across Phase I-IV studies. Pharmaceutical sponsors in the United States concentrate demand here, driven by FDA submission timelines and database lock pressures.
- Electronic Health Records:Integration modules extract structured data from hospital EMR systems for hybrid trial designs. Academic medical centers in Germany and the Netherlands are expanding deployments, constrained by GDPR cross-border transfer rules.
- Patient Registries:Post-market surveillance databases track long-term safety outcomes across dispersed populations.
- Pharmacovigilance:Adverse event case processing systems automate MedDRA coding and regulatory reporting workflows.
Clinical Trials absorbs the bulk of installed capacity; Electronic Health Records is expanding most quickly.
Deployment Model:
Cloud infrastructure shifts capital expenditure patterns from depreciated hardware to recurring subscription commitments.
- Cloud-Based:Multi-tenant SaaS platforms offer elastic compute during database lock periods and automatic software updates. Contract research organizations in India and Singapore favor this model for rapid study startup without server procurement delays.
- On-Premises:Dedicated server installations within sponsor or CRO data centers retain preference where data residency mandates apply. Russian and Chinese sponsors maintain these deployments under national data localization statutes.
- Hybrid:Split architectures place sensitive patient data on-premises while leveraging cloud analytics for non-identifiable datasets.
- Web-Based:Browser-accessible platforms with centralized hosting but limited customization compared to full cloud-native stacks.
Cloud-Based deployments now dominate new contract signings; Hybrid configurations are climbing the fastest among mid-tier pharmaceutical sponsors.
End User:
Organizational scale determines module complexity and integration depth requirements.
- Contract Research Organizations:Multi-sponsor platforms require tenant isolation, white-labeling capabilities, and rapid study configuration tools. Indian CROs serving North American sponsors are driving seat expansion.
- Pharmaceutical Companies:Enterprise deployments span global trial portfolios with standardized SDTM mapping and regulatory submission integration. Swiss and German headquarters clusters concentrate purchasing authority.
- Hospitals:Site-level systems focus on investigator-initiated trials and local regulatory compliance.
- Academic Institutions:Grant-funded research platforms prioritize cost efficiency over commercial-grade validation protocols.
Pharmaceutical Companies retain the largest cumulative license base; Contract Research Organizations are gaining share fastest.
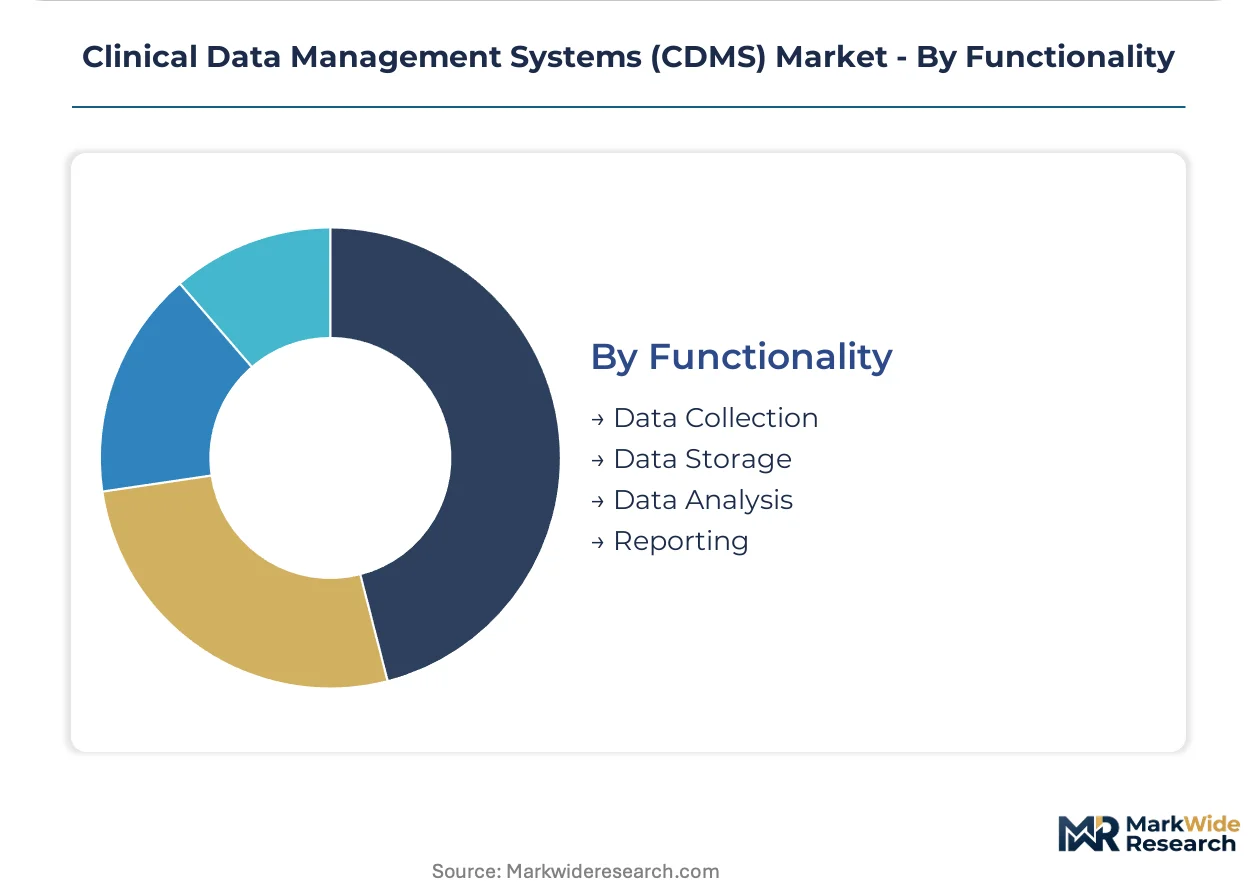
Functionality:
Core data capture modules anchor platform pricing, while analytics layers command premium add-on fees.
- Data Collection:Electronic data capture systems with edit check programming, query management, and source data verification workflows. EDC remains the non-negotiable foundation for every CDMS procurement.
- Data Analysis:Statistical computing environments with CDISC-compliant dataset generation and visualization tools. Biostatistics departments in Boston and Basel are expanding these modules for adaptive trial support.
- Data Storage:Long-term archival systems with audit trail preservation and retrieval capabilities for regulatory inspections.
- Reporting:Automated clinical study report generation and regulatory submission document assembly.
Data Collection commands the deepest installed base; Data Analysis is expanding most steeply as real-time analytics reshape trial monitoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical sponsor headquarters density and clinical trial volume concentrate demand in specific national markets. Regulatory stringency and data localization mandates reshape vendor deployment strategies across jurisdictions.
United States
FDA submission timelines and database lock pressures drive enterprise CDMS procurement among Boston and San Francisco biotech clusters. The agency's 21 CFR Part 11 electronic records requirements enforce validation protocols that favor established vendors with documented IQ/OQ/PQ histories. New Jersey and North Carolina pharmaceutical corridors anchor North American implementation capacity.
Germany
EMA centralized procedure submissions and ICH E6(R3) convergence push Munich and Frankfurt pharmaceutical sponsors toward risk-based monitoring platforms. The country's data protection authority enforces GDPR cross-border transfer restrictions that complicate cloud-native deployments. Baden-Württemberg medical device manufacturers expand post-market surveillance database investments.
China
NMPA clinical trial application reforms accelerate domestic biopharma data management platform adoption. The Personal Information Protection Law mandates data localization that forces multi-region server architectures for multinational sponsors. Shanghai and Suzhou biotech parks attract CDMS vendors establishing compliant in-country instances.
India
CDSCO clinical trial registry expansion and CRO export services drive cloud-based platform demand among Mumbai and Bengaluru service providers. The country's IT services heritage enables rapid study startup without server procurement delays. Hyderabad and Ahmedabad clinical research parks concentrate contract research organization seat expansion.
Switzerland
Swissmedic regulatory submission requirements and Basel pharmaceutical headquarters clustering sustain premium-tier CDMS licensing. The country's data residency preferences favor hybrid deployments with sensitive patient data on-premises. Geneva and Zurich biostatistics departments expand real-time analytics module procurement.
Clinical Data Management Systems (CDMS) Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with enterprise pharmaceutical sponsors consolidating around validated platforms while mid-tier CROs fragment across specialized solutions. The vendor base organizes into three strategic archetypes: database heritage incumbents anchoring multinational deployments, vertical SaaS specialists integrating clinical operations workflows, and open-source platforms serving academic and emerging market price sensitivity. Dominant competitive moves include cloud infrastructure rearchitecture for elastic compute during database lock periods and AI-assisted medical coding module development.
Within the database heritage tier, Oracle Corporation represents enterprise-scale deployment anchoring through its validated infrastructure footprint. Veeva Systems occupies a position exemplifying vertical software integration spanning clinical operations and regulatory submission workflows. Medidata Solutions sits within the cloud-native specialization archetype, with randomization and trial supply management modules complementing core data capture platforms.
| Leading Market Players |
|---|
| Oracle Corporation |
| Veeva Systems |
| Medidata Solutions |
| eClinical Solutions LLC |
| IBM Watson Health |
| Fortress Medical Systems |
| OpenClinica LLC |
| Ennov |
| Axiom Real-Time Metrics |
| Others |
Supply Flow & Price Mechanics
Pharmaceutical sponsor procurement concentration in Boston and Basel biotech corridors anchors subscription-based SaaS pricing with tiered enterprise commitments. CRO seat expansion in India and Singapore drives volume discounts that compress per-license economics while cloud infrastructure costs feed through to renewal negotiations.
Pricing Analysis
Enterprise pharmaceutical sponsors absorb premium pricing for validated 21 CFR Part 11 compliance modules, while mid-tier CROs face margin compression from elastic compute surcharges during database lock periods. Pricing stratifies across enterprise validation tiers, mid-market functional bundles, and entry-level EDC-only configurations. Cost compression in mid-market SaaS tiers is intensifying because Indian and Singaporean CROs negotiate volume-based seat commitments. Academic institutions and emerging biotechs exhibit highest price sensitivity; Swiss and German headquarters clusters show lowest sensitivity due to regulatory risk aversion.
Supply Chain Analysis
Cloud infrastructure supply rests on hyperscaler data center networks concentrated in the United States, Ireland, and Singapore for GDPR-compliant EU operations. CDMS vendors draw from AWS, Azure, and Google Cloud compute instances; Oracle database licensing; and AI/ML coding modules from specialized NLP providers. Single-source vulnerability concentrates around FDA-validated server instances with documented IQ/OQ/PQ histories. Distribution runs through direct enterprise sales teams for pharmaceutical sponsors and channel partnerships for CRO seat expansion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race into AI-assisted medical coding and real-time analytics engines. Vendors are pursuing downstream control over biostatistics service workflows to capture recurring revenue beyond software licensing.
For Market Incumbents: Deepen validation protocol automation to compress FDA 21 CFR Part 11 compliance timelines against emerging cloud-native entrants. Anchor enterprise renewals through embedded SDTM mapping expertise that raises switching costs. Expand in-country server instances in China and Russia to neutralize data localization threats from NMPA and Personal Information Protection Law mandates. For New Entrants and Emerging Players: Enter via AI-native adverse event coding modules that promise 48-hour turnaround against legacy manual workflows. Target mid-tier oncology CROs in India and Singapore with modular pricing that avoids enterprise validation overhead. Position through FHIR-standard EHR integration for hybrid trial designs where incumbents lack native connectivity. For Investors and Strategic Acquirers: Distressed-cycle entries favor cloud-native specialists with proven CTIS navigation capabilities in Brussels regulatory corridors. Long-term viability hinges on adaptive trial protocol support across basket and umbrella designs. Watch FDA guidance velocity on master protocols as inflection signal for platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Assisted Medical Coding Module Launch | Compresses adverse event narrative processing from weeks to 48-hour cycles for Phase III oncology trials. |
| FHIR-Standard EHR Integration Partnership | Enables hybrid trial data pipelines linking hospital EMR systems to EDC platforms under GDPR constraints. |
| Multi-Region Cloud Instance Expansion | Establishes NMPA-compliant data localization in Shanghai and Suzhou biotech parks for China market access. |
| CTIS Navigation Service Acquisition | Captures outsourced regulatory affairs demand from small biotechs lacking Brussels presence under EU No 536/2014. |
| Real-Time Analytics Platform Integration | Supports EMA ICH E6(R3) risk-based monitoring mandates through centralized statistical oversight dashboards. |
Methodological Framework
FDA 21 CFR Part 11 guidance documents, EMA ICH E6(R2) and E6(R3) implementation guidelines, and ClinicalTrials.gov registry data formed the secondary backbone. Primary interviews with CDMS vendor product managers, pharmaceutical regulatory affairs directors, CRO data management leads, and biostatistics department heads at academic medical centers supplied operational validation. Bottom-up triangulation across deployment model, end-user organization scale, and functional module adoption combined with top-down cross-checks against cloud infrastructure spending disclosures from hyperscaler filings.
Bottom-up modeling segmented revenue across cloud-based, on-premises, hybrid, and web-based deployment architectures, then cross-referenced against pharmaceutical sponsor headquarters clustering and CRO export service volumes. The analysis window spans from base year through projection horizon with CAGRs derived from elastic compute demand curves during database lock periods and adaptive trial protocol adoption trajectories. Forecast inputs incorporated CDISC SDTM implementation guide version changes and EMA Clinical Trial Regulation portal submission volumes.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA guidance acceleration or geopolitical cloud infrastructure restrictions. Assumptions reflect current regulatory validation timelines and cloud provider geopolitical exposure. A small set of named triggers warrants ongoing watch: NMPA data localization enforcement, ICH E6(R3) final guideline publication, and hyperscaler data center certification delays for 21 CFR Part 11 compliance.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Data Management
Europe Healthcare Analytics Market
Health Data Management
Hospital Management Software Market
Health Data Management
Healthcare Data Interoperability Market
Health Data Management
Global Chronic Care Management Software Market
Health Data Management
Global Healthcare Data Storage Market
Health Data Management
Healthcare Data Collection and Labeling Market
Health Data Management
United States Healthcare Big Data Analytics Market
Health Data Management
Population Health Management Platforms Market
Health Data Management
North America Clinical Data Analytics in Healthcare Market
Health Data Management
Data Democratization in Healthcare Market
Health Data Management
Americas Healthcare Archiving and Ediscovery Market
Health Data Management
Global Healthcare Quality Management Market
Health Data Management
Healthcare Data Monetization Solutions Market
Health Data Management
Health Care Quality Management Software Market
Health Data Management
Data Monetization in Healthcare Market
Health Data Management
AI Training Dataset in Healthcare Market