
 North America Clinical Data Analytics in Healthcare Market | 2026-2036
North America Clinical Data Analytics in Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
North America Clinical Data Analytics in Healthcare Market Insights
Hospital procurement of clinical data analytics is hardening as health systems prioritize value-based reimbursement models. Health Catalyst Inc leverages cloud-native architectures to anchor its position in outcome measurement contracts. McKesson Corporation sustains channel control through embedded distribution within pharmaceutical supply chains. IBM Corporation competes via specialized natural language processing modules that extract unstructured clinical notes.
Clinical Data Analytics in Healthcare encompasses the computational processing of electronic health records, claims data, and biometric streams to generate actionable insights for care optimization. Systems typically employ machine learning algorithms trained on longitudinal patient datasets with throughput requirements exceeding millions of records per hour, serving primarily to reduce clinical variation and operational waste. Cloud-Based Solutions dominate deployment preferences as health systems seek elastic compute for population health cohort analysis. Predictive Analytics represents the fastest-expanding technology segment, with margin pools concentrating in readmission risk stratification and sepsis early-warning applications. Patient Management applications retain mature revenue bases while Data Integration infrastructure attracts new capital for interoperability compliance.
FDA guidance on artificial intelligence and machine learning in medical devices shapes algorithm validation requirements for clinical decision support tools. HIPAA privacy frameworks and the 21st Century Cures Act information-blocking provisions jointly determine data access architectures and vendor liability exposure. Stakeholders must monitor evolving ONC certification timelines and state-level Medicaid expansion patterns to align platform investment with reimbursement trajectory shifts.
Market Dynamics
The 21st Century Cures Act interoperability mandates are forcing health systems to dismantle data silos, creating immediate procurement pressure for integration infrastructure that can normalize fragmented EHR architectures into queryable longitudinal records.
Growth Catalysts
- FDA AI/ML Medical Device Guidance:The framework creates validation pathways for clinical decision support algorithms, reducing regulatory uncertainty for predictive analytics vendors seeking 510(k) clearance.
- Hospital value-based reimbursement:Medicare readmission penalty programs are hardening demand for risk stratification tools that identify high-acuity patients before discharge.
- Cloud-native architectures:Elastic compute provisioning enables population health cohort analysis at scale without capital-intensive on-premise infrastructure commitments.
Market Restraints
- HIPAA technical safeguard complexity:Encryption and access control requirements impose architectural constraints that extend implementation timelines for multi-site deployments.
- Specialized talent scarcity:Health informaticists with dual competency in clinical workflows and machine learning engineering command compensation premiums that inflate platform development costs.
- Legacy EHR technical debt:Proprietary data formats in incumbent systems resist standardization, forcing expensive middleware layers for interoperability compliance.
Strategic Opportunities
- Canadian provincial health networks:Ontario and British Columbia are consolidating regional EHR instances, creating procurement windows for analytics platforms with FHIR-native ingestion.
- Sepsis early-warning convergence:Real-time biometric streams from ICU monitoring devices are fusing with laboratory values to enable automated alert generation.
- Medicaid managed care expansion:State-level program growth is generating demand for social determinants integration into risk scoring models.
Industry Challenges
- ONC certification timeline volatility:Shifting compliance deadlines for information-blocking rules create uncertainty in platform roadmap prioritization.
- Algorithmic bias audit requirements:Emerging expectations for demographic performance validation are expanding quality assurance overhead without standardized methodologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Clinical Data Analytics in Healthcare Market |
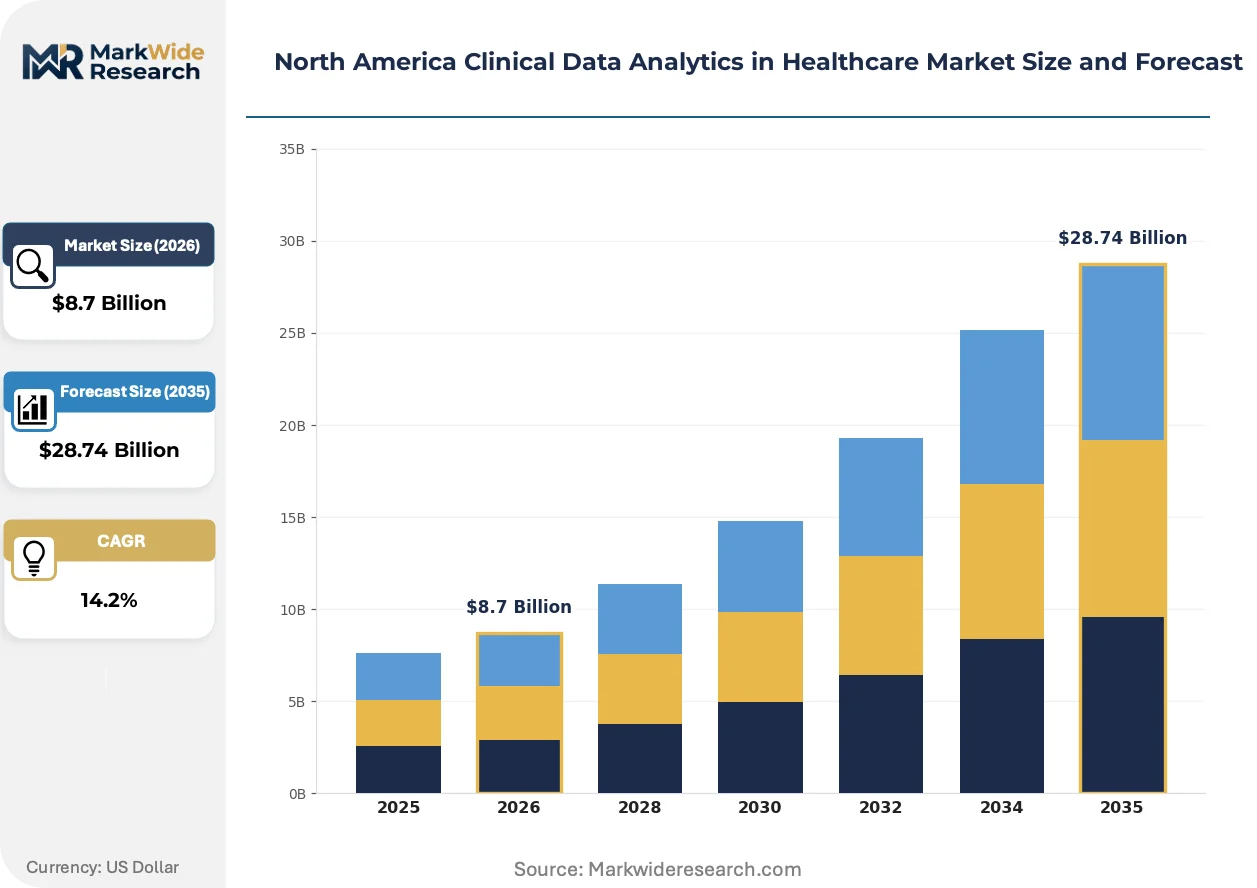
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based Solutions, On-Premise Solutions, Hybrid Solutions, Mobile Applications End User: Hospitals, Clinics, Research Institutions, Pharmaceuticals Technology: Machine Learning, Predictive Analytics, Data Mining, Natural Language Processing Application: Patient Management, Population Health, Clinical Workflow, Data Integration |
| Companies Covered | Health Catalyst Inc, McKesson Corporation, IBM Corporation, Allscripts Healthcare Solutions Inc, Siemens Healthineers AG, Koninklijke Philips N.V., Oracle Corporation, CareEvolution LLC, Cerner Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Clinical Data Analytics in Healthcare Market Trends and Innovations
Natural language processing engines are extracting unstructured clinical documentation at scale, converting free-text notes into structured data elements that feed predictive models. This capability is compressing implementation cycles for analytics deployments.
Federated learning architectures are absorbing sensitive patient data without centralizing raw records, enabling multi-site model training while preserving institutional firewalls. Academic medical centers in the United States are piloting these frameworks for rare disease phenotype detection. The approach is absorbing liability concerns that previously blocked cross-system data pooling.
The 21st Century Cures Act information-blocking provisions are mandating standardized APIs for EHR data exchange, forcing incumbent vendors to expose previously proprietary endpoints. Health systems are responding by renegotiating vendor contracts to include API access guarantees. The enforcement mechanism is accelerating replacement of point-to-point interfaces with FHIR-based integration.
Subscription pricing for analytics modules is displacing perpetual license structures, aligning vendor revenue with ongoing utilization rather than upfront deployment. Health system CFOs are demanding outcome-based fee components tied to measurable utilization or quality metric improvements. This shift is most visible in United States hospital systems with mature value-based care contracts.
North America Clinical Data Analytics in Healthcare Market Segmentation
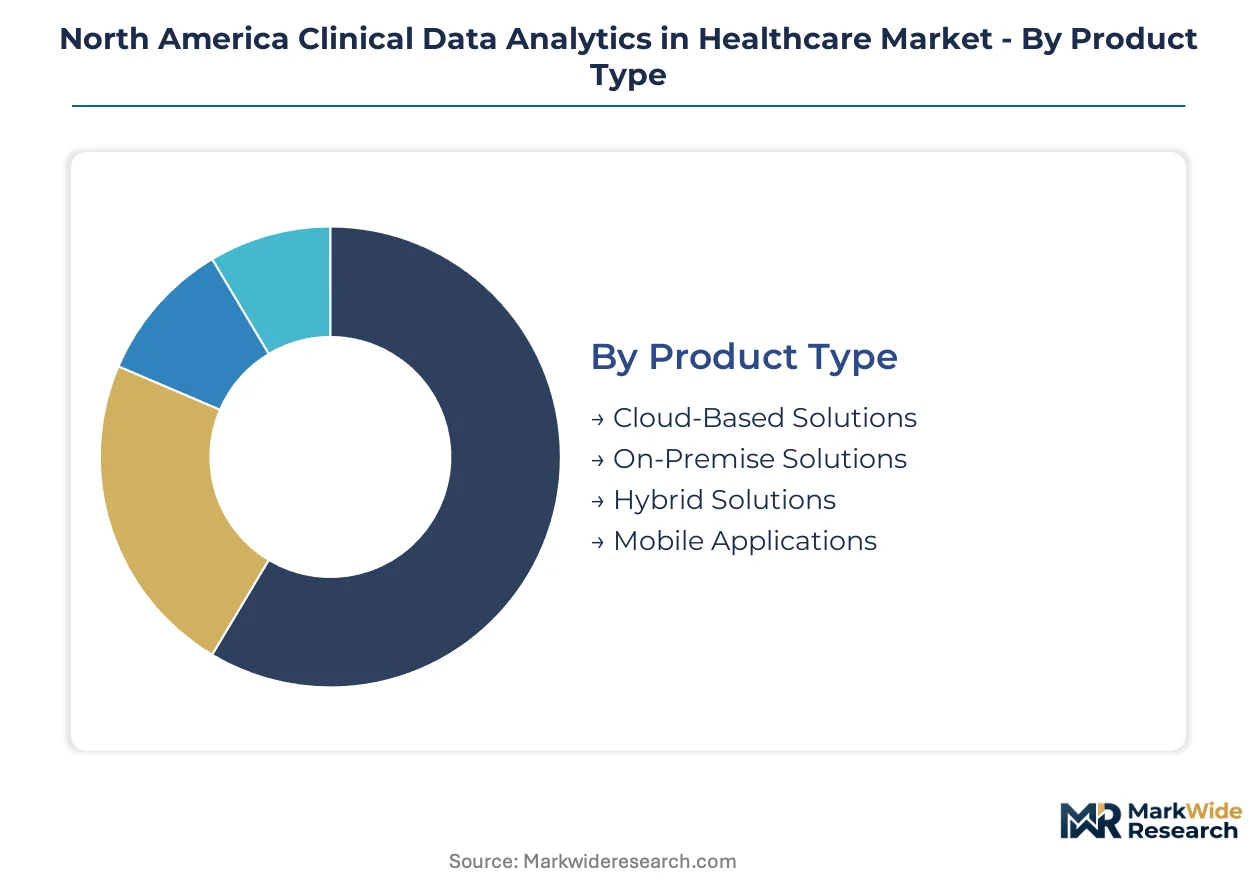
Segmentation in clinical data analytics reveals how procurement priorities diverge across infrastructure preferences, care settings, and algorithmic capabilities. Understanding these fault lines exposes where vendor margin pools concentrate and where compliance mandates are reshaping purchasing patterns.
Product Type:
Standardization dominates at the infrastructure layer while customization intensifies at the presentation tier, creating a deployment spectrum from commodity compute to tailored clinical interfaces.
- Cloud-Based Solutions:Elastic compute provisioning enables health systems to scale analytics throughput during seasonal patient volume spikes without capital-intensive server commitments. United States hospital systems with mature value-based contracts are consolidating procurement around multi-tenant architectures that normalize fragmented EHR data into queryable longitudinal records. Most installed capacity flows through Cloud-Based Solutions. Expansion is steepest in Hybrid Solutions.
- On-Premise Solutions:Dedicated hardware installations persist in Canadian provincial health networks where data residency requirements and legacy firewall architectures resist migration. These deployments demand specialized infrastructure teams and extended implementation timelines that inflate total cost of ownership relative to cloud alternatives.
- Hybrid Solutions:Split architectures anchor sensitive patient data on local servers while pushing compute-intensive model training to cloud environments. United States academic medical centers are piloting these configurations for federated learning applications that train algorithms across institutional boundaries.
- Mobile Applications:Point-of-care dashboards deliver risk scores and alert notifications to clinician smartphones, with adoption concentrating in emergency departments where rapid decision cycles demand ambient data access.
Procurement committees are standardizing on cloud-native cores while preserving on-premise options for specific compliance scenarios, compressing pure on-premise growth trajectories.
End User:
Volume concentration sits with integrated delivery networks while margin expansion follows specialized research and pharmaceutical partnerships requiring bespoke algorithm development.
- Hospitals:Enterprise analytics platforms process millions of records hourly to stratify readmission risk and flag sepsis deterioration, with Medicare penalty programs hardening demand for predictive modules. United States health systems with 500+ beds are consolidating vendor relationships around platforms that embed clinical decision support directly into EHR workflows.
- Clinics:Federally qualified health centers and ambulatory surgery centers deploy lighter-weight analytics for population health reporting and quality metric tracking, constrained by limited IT staffing and smaller data volumes that resist complex model training.
- Research Institutions:Academic medical centers in Ontario and British Columbia are procuring platforms with FHIR-native ingestion to support multi-site phenotype studies and rare disease cohort identification, absorbing higher per-seat costs for specialized data science tooling.
- Pharmaceuticals:Real-world evidence generation contracts require analytics infrastructure that can normalize claims data, EHR extracts, and registry inputs into regulatory-grade evidence packages for FDA submission.
Hospital procurement dominates current revenue bases while pharmaceutical partnerships offer the steepest expansion trajectory as real-world evidence mandates intensify.
Technology:
Maturity gradients separate established statistical methods from emerging neural architectures, with validation requirements creating divergent commercialization timelines across the technology stack.
- Predictive Analytics:Risk stratification algorithms trained on historical admissions data now anchor virtually every hospital analytics deployment, with readmission and mortality prediction representing the most mature commercial segment. United States health systems are demanding outcome-based pricing tied to measured reductions in penalty exposure.
- Natural Language Processing:Clinical documentation extraction converts unstructured physician notes into structured data elements, compressing implementation cycles by eliminating manual abstraction. Academic medical centers are deploying these engines to unlock decades of free-text pathology reports for research reuse.
- Machine Learning:Deep learning architectures for imaging and waveform analysis face extended FDA validation timelines but promise step-change performance in diagnostic accuracy for specific clinical domains.
- Data Mining:Pattern detection across administrative and operational datasets identifies utilization inefficiencies and supply chain waste, with demand concentrating in revenue cycle management applications.
Predictive Analytics carries the largest installed base while Natural Language Processing is gaining share fastest as health systems prioritize unstructured data activation.
Application:
Workflow integration depth determines switching costs, with modules embedded deeply into clinical decision-making commanding pricing premiums over retrospective reporting tools.
- Data Integration:Interoperability infrastructure normalizes proprietary EHR formats into FHIR-compliant resources, with the 21st Century Cures Act information-blocking provisions forcing procurement of API gateway layers. United States health systems are renegotiating vendor contracts to guarantee standardized endpoint access.
- Patient Management:Care coordination dashboards and risk registry tools represent the most mature revenue segment, with functionality now table stakes for hospital analytics procurement rather than differentiator.
- Population Health:Cohort identification and stratification tools enable accountable care organizations to target interventions toward high-utilization patient segments, with Medicaid managed care expansion in multiple United States states driving new procurement.
- Clinical Workflow:Real-time decision support embedded at the point of care requires sub-second latency and EHR-native rendering, with sepsis early-warning and medication dosing alerts representing the most clinically validated use cases.
Data Integration infrastructure is absorbing the largest share of new capital as compliance deadlines harden, while Clinical Workflow applications offer the most defensible competitive positioning through deep EHR embedding.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
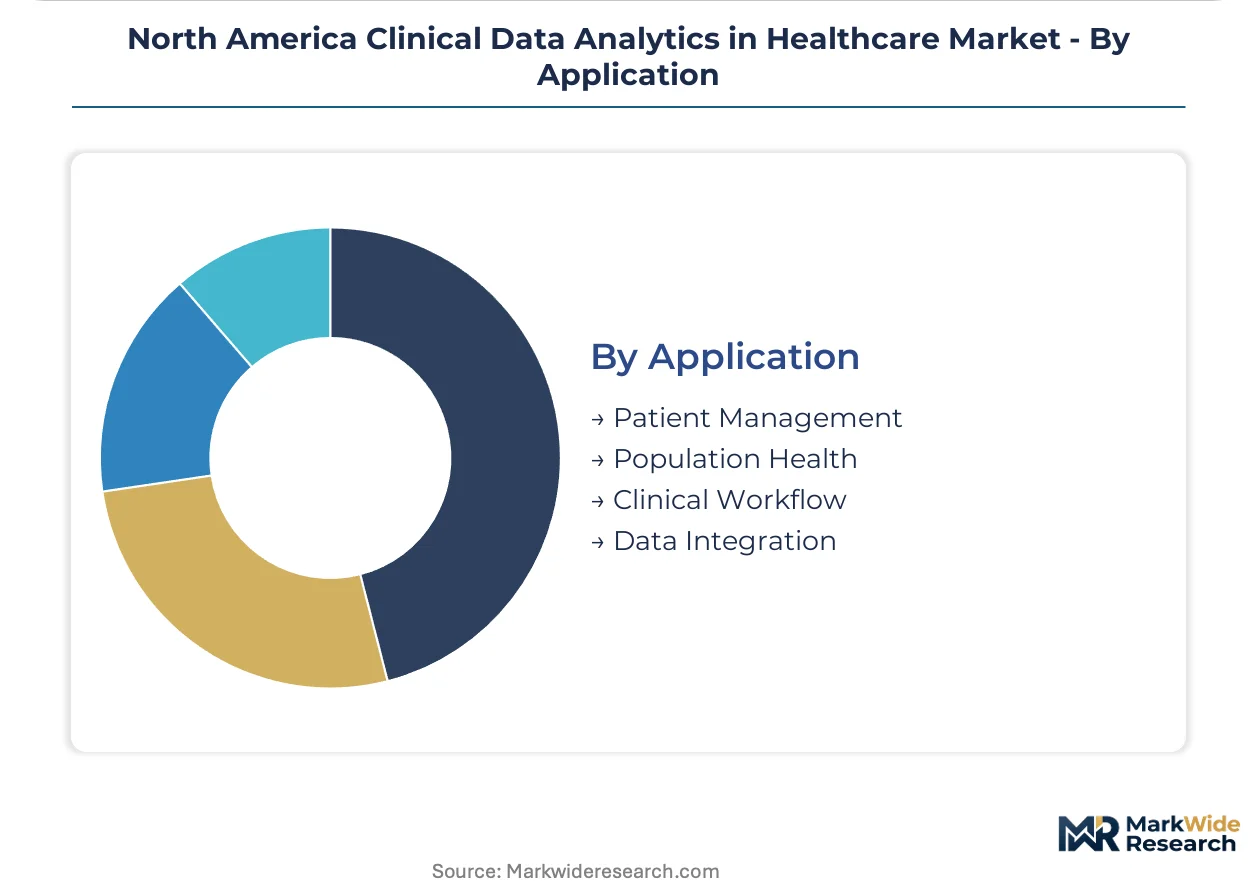
Regulatory arbitrage between HIPAA technical safeguard requirements and provincial data residency mandates is fragmenting procurement patterns across North America. Health systems migrate analytics workloads toward jurisdictions with clarified liability frameworks, accelerating cloud-region specialization among vendors.
United States
Medicare readmission penalty programs and value-based reimbursement contracts are hardening demand for predictive risk stratification tools. FDA AI/ML medical device guidance creates validation pathways for clinical decision support algorithms seeking 510(k) clearance. The Greater Boston and San Francisco Bay Area clusters concentrate academic medical center pilot programs for federated learning architectures.
Canada
Provincial health networks in Ontario and British Columbia are consolidating regional EHR instances, creating procurement windows for FHIR-native analytics platforms. Health Canada and provincial privacy commissioners enforce data residency requirements that resist pure cloud migration. Toronto and Vancouver anchor emerging adoption corridors for hybrid deployment models.
Mexico
Private hospital chains in Mexico City and Monterrey are deploying lighter-weight analytics for population health reporting as they expand insurance-linked care models. The national pharmaceutical regulator shapes data quality expectations for cross-border research collaborations. Guadalajara's medical device manufacturing cluster is piloting real-world evidence generation for FDA-aligned export markets.
North America Clinical Data Analytics in Healthcare Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with cloud-native platforms capturing procurement from health systems seeking elastic compute without capital commitments. The vendor base concentrates around three strategic archetypes: EHR-embedded incumbents with workflow integration advantages, cloud-native specialists with outcome-based pricing models, and diversified technology conglomerates with natural language processing capabilities. Competitive positioning hardens through M&A activity targeting FHIR integration expertise and strategic partnerships with academic medical centers for algorithm validation.
Among United States-based platforms, Health Catalyst Inc exemplifies the cloud-native specialist archetype with outcome measurement contract structures. McKesson Corporation occupies a position within supply chain-embedded distribution models that channel analytics through pharmaceutical procurement relationships. IBM Corporation anchors the diversified technology tier, competing via specialized natural language processing modules that extract unstructured clinical documentation.
| Leading Market Players |
|---|
| Health Catalyst Inc |
| McKesson Corporation |
| IBM Corporation |
| Allscripts Healthcare Solutions Inc |
| Siemens Healthineers AG |
| Koninklijke Philips N.V. |
| Oracle Corporation |
| CareEvolution LLC |
| Cerner Corporation |
| Others |
Pricing and Supply Chain Analysis
Hospital procurement committees in the United States are consolidating vendor relationships around cloud-native platforms with outcome-based pricing clauses, forcing analytics vendors to absorb implementation risk and compress upfront licensing revenue into multi-year subscription streams.
Pricing Analysis
Distributor margins in pharmaceutical supply chain-embedded analytics average fifteen to twenty percent, with McKesson Corporation channel partners extracting additional value through bundled distribution and data services. Pricing stratifies across premium, standard, and economy tiers based on FHIR integration depth and FDA 510(k) clearance status. Cost compression in the mid-market tier is intensifying because health system CFOs are demanding proof-of-value pilots before enterprise commitments. Federally qualified health centers exhibit the highest price sensitivity, while academic medical centers with research funding demonstrate willingness to absorb premium per-seat costs for specialized phenotype tooling.
Supply Chain Analysis
Freight costs for on-premise hardware deployments to Canadian provincial networks add eight to twelve percent to total landed cost, reinforcing preference for cloud-native solutions where data residency permits. Software development talent concentrates in the United States, India, and Ireland, with machine learning engineering hubs in Boston and San Francisco commanding compensation premiums that inflate platform development costs. The supply chain draws from specialized health informaticists with dual clinical and technical competency, creating single-source vulnerability for rare skill sets. Distribution runs through direct enterprise sales teams for hospital systems, with GPO contracts channeling mid-market procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where procurement committees are prioritizing validated algorithm performance over undifferentiated feature breadth, with FDA-cleared sepsis prediction modules commanding pricing premiums.
For Market Incumbents: Deploy federated learning architectures to neutralize data-pooling liability concerns that previously blocked multi-site contracts. Health Catalyst Inc and Cerner Corporation should anchor defensive positioning through exclusive academic medical center partnerships for algorithm validation, while embedding clinical decision support deeper into EHR workflows to elevate switching costs. Cloud-native specialists threaten margin compression through outcome-based pricing that shifts implementation risk onto vendors. For New Entrants and Emerging Players: The gap between premium FHIR-native platforms and economy-tier legacy reporting tools creates entry space for hybrid deployment specialists serving Canadian provincial networks with data residency constraints. Ontario and British Columbia consolidation programs represent the most penetrable geography, with FHIR ingestion expertise as the essential go-to-market credential. Target mid-market United States hospital systems with 200-500 beds that lack internal data science capacity but face Medicare penalty exposure. For Investors and Strategic Acquirers: Asymmetric upside sits with cloud-native platforms holding outcome measurement contracts with mature value-based care health systems. Long-term viability hinges on regulatory validation depth rather than feature velocity, favoring acquisition targets with FDA-cleared algorithm portfolios and embedded EHR integration. Watch ONC certification timeline shifts as the inflection signal for platform roadmap prioritization and vendor liability exposure.| Strategic Initiative | Industry Significance |
|---|---|
| FHIR-Native Platform Development | ONC information-blocking enforcement mandates standardized API access, rewarding early FHIR investment with procurement preference. |
| Federated Learning Pilot Programs | Academic medical centers in Boston and San Francisco validate privacy-preserving architectures that unlock multi-site training contracts. |
| Outcome-Based Pricing Restructuring | Health system CFOs demand fee components tied to measured readmission reduction, aligning vendor revenue with clinical impact. |
| Sepsis Early-Warning FDA Submission | 510(k) clearance for real-time ICU monitoring algorithms creates defensible competitive positioning in highest-margin application segment. |
| Canadian Provincial Network Partnership | Ontario and British Columbia EHR consolidation creates procurement windows for hybrid deployment models with data residency compliance. |
Research Methodology
Multiple input streams — structured hospital procurement database extracts, CMS Medicare claims filings, and FDA 510(k) clearance records — were reconciled with primary interviews conducted with hospital purchasing committee chairs, health informaticists, GPO contracts managers, and cloud platform engineering leads. Secondary validation drew from hospital EHR implementation case studies, ONC certification timelines, and provincial health network procurement disclosures in Ontario and British Columbia. Bottom-up deployment counts were triangulated against top-down health system IT budget allocations.
Data-stream reconciliation anchored the analytical framework across the projection horizon, with segmentation modeled by deployment architecture, end-user scale tier, technology maturity gradient, and application workflow depth. CAGRs were derived from elasticity-adjusted adoption curves calibrated to value-based reimbursement contract penetration. Forecast inputs included Medicare readmission penalty program evolution and Medicaid managed care expansion patterns across United States states.
Caveats apply where ONC certification deadline shifts or HIPAA technical safeguard reinterpretations could materially shift the outlook for interoperability infrastructure investment. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Data Management
Global Healthcare Fraud Analytics Market
Health Data Management
Global Healthcare Data Storage Market
Health Data Management
Healthcare Data De-Identification Assurance Market
Health Data Management
Global Big Data Analytics in Healthcare Market
Health Data Management
Wireless Healthcare Asset Management Market
Health Data Management
Healthcare Data Integration Market
Health Data Management
Point of Care (POC) Data Management Systems Market
Health Data Management
North America Healthcare Analytics Market
Health Data Management
Point-Of-Care Data Management Software Market
Health Data Management
Asia Pacific Healthcare Archiving and Ediscovery Market
Health Data Management
Master Data Management in Healthcare Market
Health Data Management
Healthcare Analytics Market
Health Data Management
Global Healthcare Data Analytics Market
Health Data Management
Healthcare Data Monetization Solutions Market
Health Data Management
Population Health Management Solutions Market
Health Data Management
Global Healthcare Customer Data Platform Market