
 Portable Medical Electronic Products Market | 2026-2036
Portable Medical Electronic Products Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Medical Electronic Products Market Outlook
Contract electronics manufacturers in Southeast Asia are consolidating assembly capacity for portable medical devices as OEMs shift from in-house production. GE Healthcare leverages its imaging heritage to anchor premium diagnostic portfolios, while Abbott Laboratories sustains glucose monitoring leadership through sensor miniaturization. Koninklijke Philips N.V. competes across patient monitoring and sleep therapy with integrated platform strategies.
Portable medical electronic products encompass battery-powered diagnostic, therapeutic, and monitoring instruments designed for point-of-care and ambulatory use, typically operating on rechargeable lithium-ion cells with wireless connectivity protocols and FDA Class II or CE-marked safety enclosures. These devices transmit physiological data to clinical decision systems, enabling decentralized care models outside traditional hospital infrastructure. Patient monitors and wearable sensors capture expanding margin pools as hospitals prioritize early discharge protocols, while diagnostic devices face margin compression from commoditized blood pressure and pulse oximetry units. Therapeutic devices occupy a middle ground where reimbursement codes determine geographic rollout speed.
FDA 510(k) premarket notification and EU MDR conformity assessment shape product development timelines and market access costs for manufacturers seeking multi-region distribution. The FCC regulates wireless transmission frequencies for Bluetooth and Wi-Fi-enabled devices, creating interoperability requirements that influence chipset selection and software architecture. Stakeholders must monitor evolving cybersecurity guidance from FDA and post-market surveillance obligations under MDR Article 83 as connected device vulnerabilities attract regulatory scrutiny.
Market Dynamics
Homecare migration is compressing hospital purchasing cycles while elevating reimbursement complexity for ambulatory device categories. This structural force reshapes how manufacturers allocate R&D between clinical-grade precision and consumer-grade usability.
Growth Catalysts
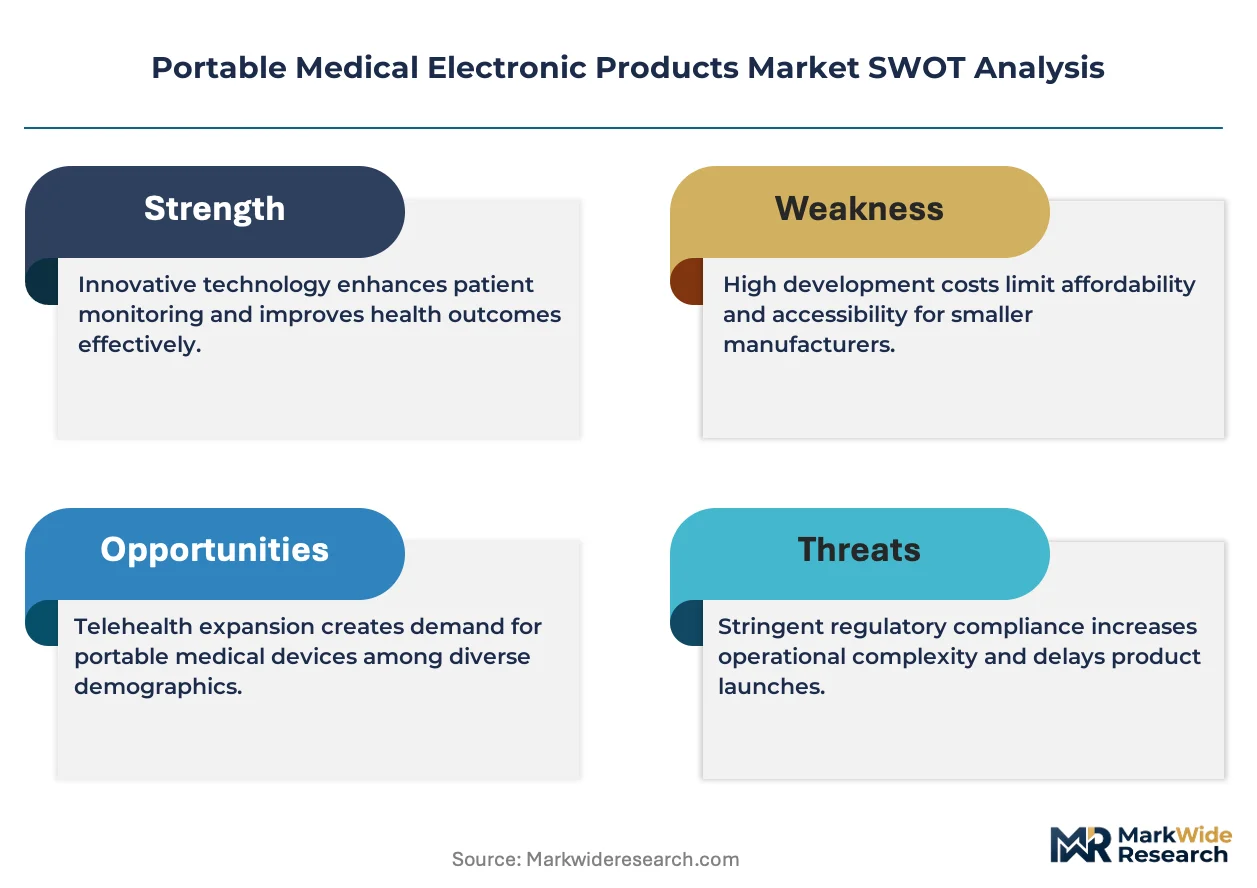
- EU MDR Article 83 surveillance mandates:Post-market data collection requirements accelerate software update cycles, creating recurring revenue streams for connected diagnostic platforms.
- Lithium-ion cell energy density improvements:Extended battery life enables continuous glucose monitoring and multi-parameter patient monitors to operate 72+ hours without recharge.
- Japan's super-aged society:METI reimbursement incentives for home-based cardiac monitoring expand addressable demand for portable ECG devices outside institutional settings.
Market Restraints
- Semiconductor foundry concentration in Taiwan:PMIC and Bluetooth SoC supply vulnerability constrains production scaling for mid-tier device manufacturers.
- FDA 510(k) predicate device requirements:Substantial equivalence pathways for novel sensor algorithms extend clearance timelines by 8-14 months.
- Disposable electrode cost volatility:Silver/silver chloride price fluctuations compress margins on single-use consumable attachments.
Strategic Opportunities
- India's PLI scheme for medical electronics:Domestic manufacturing incentives reduce import duty exposure for devices assembled in Tamil Nadu and Karnataka clusters.
- AI-integrated arrhythmia detection:Edge computing convergence with MEMS accelerometers enables stroke-risk stratification without cloud dependency.
- Pharmacy channel expansion:CVS and Walgreens retail clinics create direct-to-patient distribution for blood pressure and pulse oximetry devices.
Industry Challenges
- Embedded systems cybersecurity expertise:FDA premarket guidance on software bill of materials exceeds talent availability in most OEM engineering departments.
- Legacy hospital IT integration:HL7 FHIR interoperability requirements force middleware development that delays commercial launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Medical Electronic Products Market |
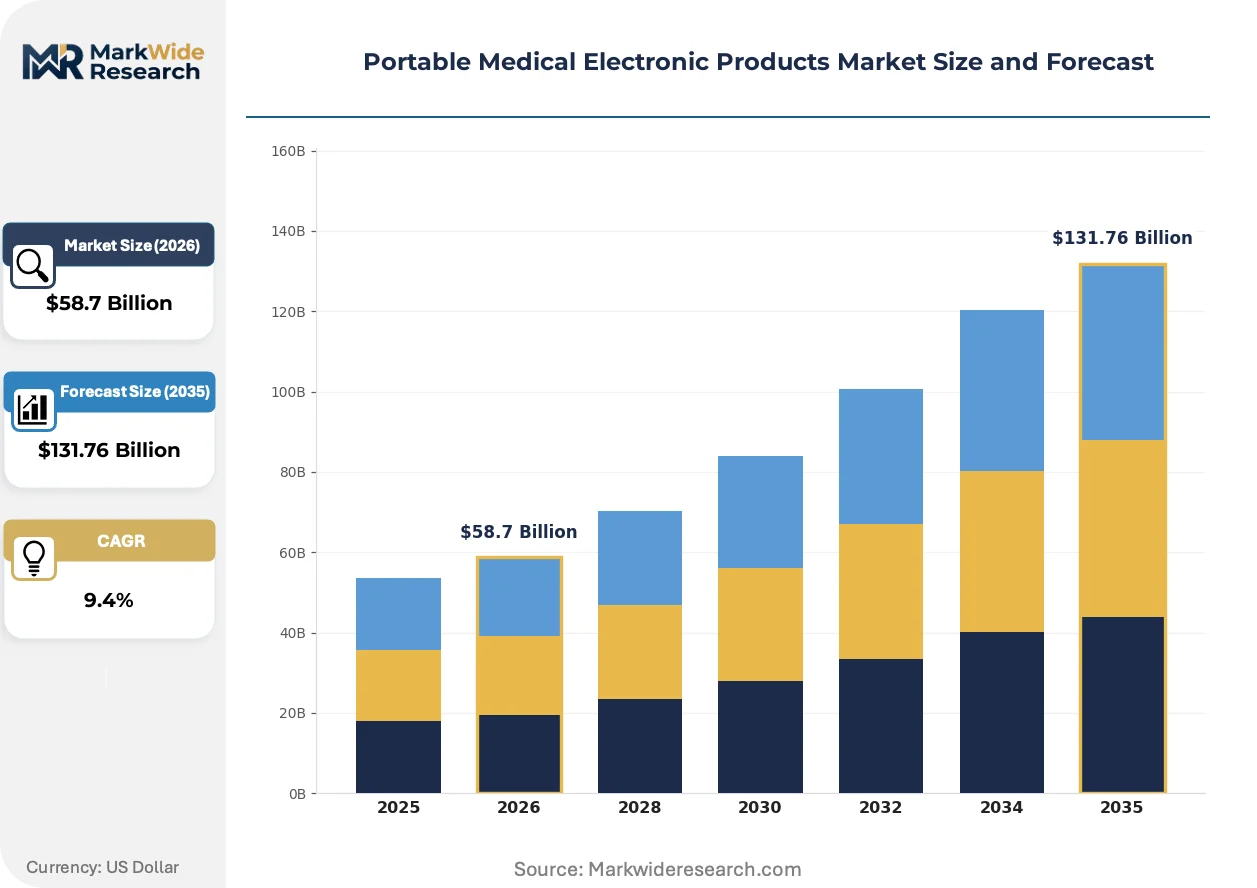
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $131.76 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Patient Monitors, Diagnostic Devices, Therapeutic Devices, Wearable Sensors Application: Remote Patient Monitoring, Chronic Disease Management, Emergency Care, Fitness Tracking End User: Hospitals, Homecare Settings, Rehabilitation Centers, Fitness Facilities Technology: Bluetooth, Wi-Fi, IoT, GSM |
| Companies Covered | GE Healthcare, Abbott Laboratories, Koninklijke Philips N.V., Medtronic plc, Omron Healthcare, Siemens Healthineers, Roche Diagnostics, Hologic Inc., General Electric Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Medical Electronic Products Market Strategic Shifts
Sensor fusion architectures and edge AI inference are collapsing the functional boundary between consumer wearables and clinical monitors. This convergence pressures regulatory frameworks to distinguish wellness claims from diagnostic accuracy.
Flexible printed circuit board assemblies with stretchable interconnects are modularizing physical form factors for wearable cardiac monitors. Hospital-at-home programs in Germany and the Netherlands are adopting these platforms for 30-day post-discharge surveillance. The technology is modularizing how OEMs segment premium diagnostic tiers from economy wellness offerings without redesigning core sensing elements.
EU MDR cybersecurity annex requirements entered force in 2024, mandating SBOM documentation and vulnerability disclosure protocols for all radio-enabled devices. Manufacturers serving European markets must revalidate legacy Bluetooth stacks or replace chipsets entirely. Sleep therapy and continuous monitoring categories face the steepest compliance costs due to cloud data transmission architectures.
Hospital procurement departments are consolidating vendor panels for point-of-care devices, favoring platforms that bundle hardware, connectivity, and analytics under single-source contracts. This behavior concentrates purchasing power among IDNs in the US and university hospital networks in Japan. The shift is most visible in patient monitoring, where Philips and GE Healthcare have captured multi-year enterprise agreements that exclude smaller device specialists.
Portable Medical Electronic Products Market Segmentation
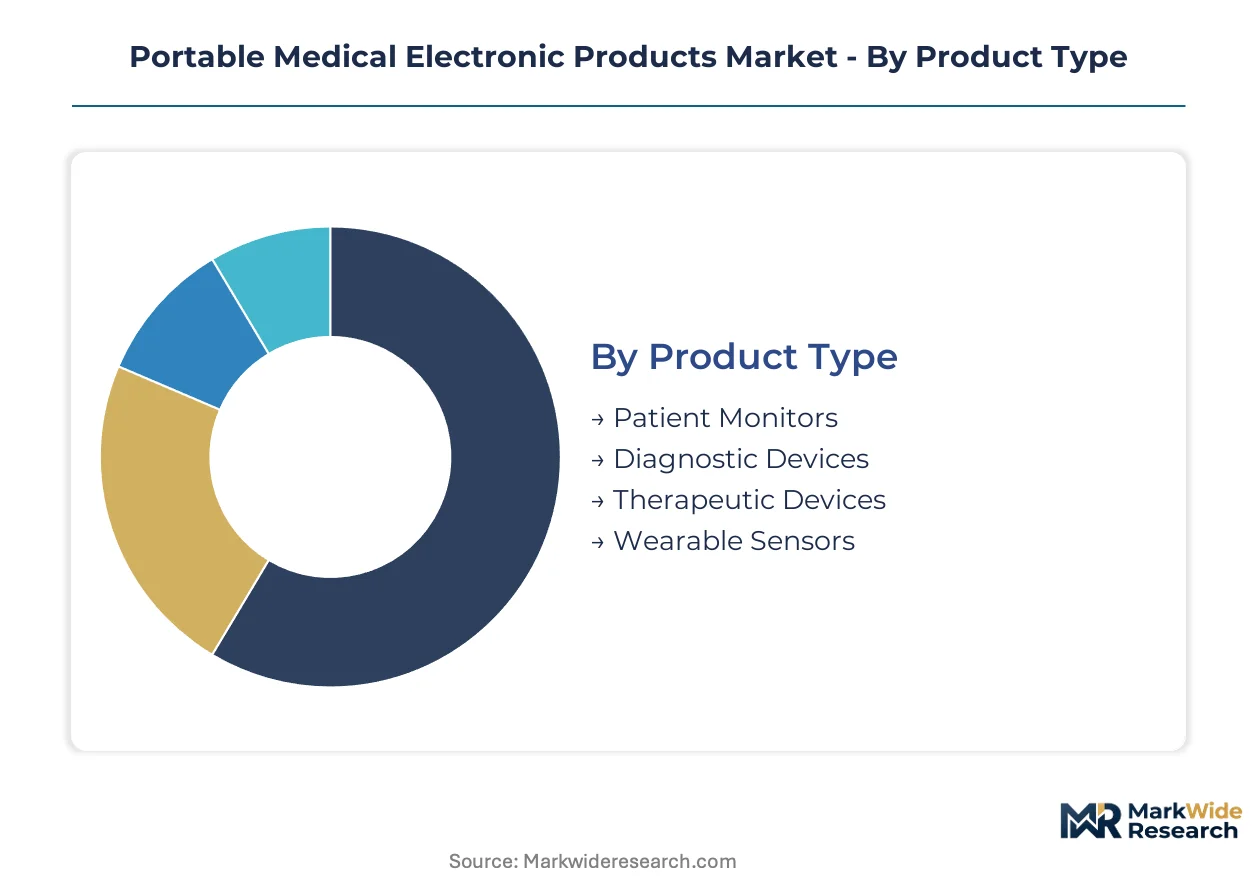
Portable medical electronic products fragment across four intersecting dimensions that determine regulatory pathways, margin structures, and customer procurement behavior. Each segmentation axis carries distinct capital requirements and competitive dynamics that shape how manufacturers prioritize R&D and distribution investments.
Product Type:
Patient monitors demand the heaviest upfront capital outlay for FDA 510(k) clinical validation and multi-parameter sensor integration, while diagnostic devices require less initial investment but face steeper margin erosion from commoditization.
- Patient Monitors:Multi-parameter bedside and ambulatory units integrate ECG, SpO2, NIBP, and temperature sensing through ARM-based processing architectures. Demand concentrates in US hospital-at-home programs and German university hospital networks where early discharge protocols prioritize continuous physiological surveillance. Reimbursement complexity under Medicare's remote patient monitoring codes constrains rollout speed for multi-channel configurations.
- Diagnostic Devices:Blood pressure monitors, pulse oximeters, and handheld ECG units employ MEMS pressure sensors and photoplethysmography arrays for point-of-care screening. Japanese METI incentives for home-based cardiac assessment and US retail pharmacy clinic expansion drive volume concentration, though silver/silver chloride electrode cost volatility compresses margins on single-use consumables.
- Therapeutic Devices:Portable defibrillators, insulin pumps, and continuous positive airway pressure machines deliver automated intervention through closed-loop control systems. Reimbursement code availability determines geographic prioritization for OEM commercial teams.
- Wearable Sensors:Patch-based cardiac monitors and activity trackers utilize flexible printed circuit assemblies with stretchable interconnects for extended ambulatory use. Hospital-at-home adoption in the Netherlands and Germany favors 30-day post-discharge surveillance form factors.
Most installed capacity flows through patient monitors. Expansion is steepest in wearable sensors.
Application:
Remote patient monitoring commands premium pricing through recurring connectivity fees, while fitness tracking operates at economy margins with consumer-grade durability standards.
- Remote Patient Monitoring:Cloud-connected devices transmit physiological data to clinical decision support systems through HL7 FHIR interoperability protocols. US integrated delivery networks and Japanese super-aged society demographics concentrate demand, though legacy hospital IT integration forces costly middleware development that delays commercial launches.
- Chronic Disease Management:Continuous glucose monitors and ambulatory blood pressure systems enable longitudinal disease tracking outside institutional settings. Abbott's sensor miniaturization leadership and Dexcom's factory automation investments define competitive intensity.
- Emergency Care:Portable defibrillators and vital signs monitors support pre-hospital intervention through ruggedized enclosures and extended temperature operating ranges. EMS procurement cycles favor multi-year fleet replacement contracts with established device specialists.
- Fitness Tracking:Consumer-oriented heart rate and blood oxygen saturation monitors compete on price through retail pharmacy and direct-to-patient e-commerce channels. FDA wellness claim boundaries limit diagnostic accuracy marketing.
Revenue concentration sits with remote patient monitoring. Chronic disease management is climbing the fastest.
End User:
Homecare settings impose consumer-grade usability requirements on clinical-precision hardware, creating engineering tension absent in hospital procurement.
- Hospitals:Acute care facilities prioritize multi-parameter integration and enterprise IT connectivity over single-function portability. US IDN vendor consolidation favors platform suppliers bundling hardware, connectivity, and analytics under multi-year agreements.
- Homecare Settings:Decentralized care models require rechargeable lithium-ion operation exceeding 72 hours and simplified patient interfaces for elderly users. Japan's METI reimbursement incentives and US Medicare remote monitoring codes accelerate category expansion.
- Rehabilitation Centers:Post-acute facilities balance clinical oversight with patient mobility, favoring telemetry-enabled cardiac and respiratory monitors during supervised recovery protocols.
- Fitness Facilities:Corporate wellness programs and gym chains deploy basic vital signs screening for member engagement, with procurement decisions driven by per-unit cost rather than diagnostic accuracy certification.
Hospital procurement dominates current installed base. Homecare settings are gaining share fastest.
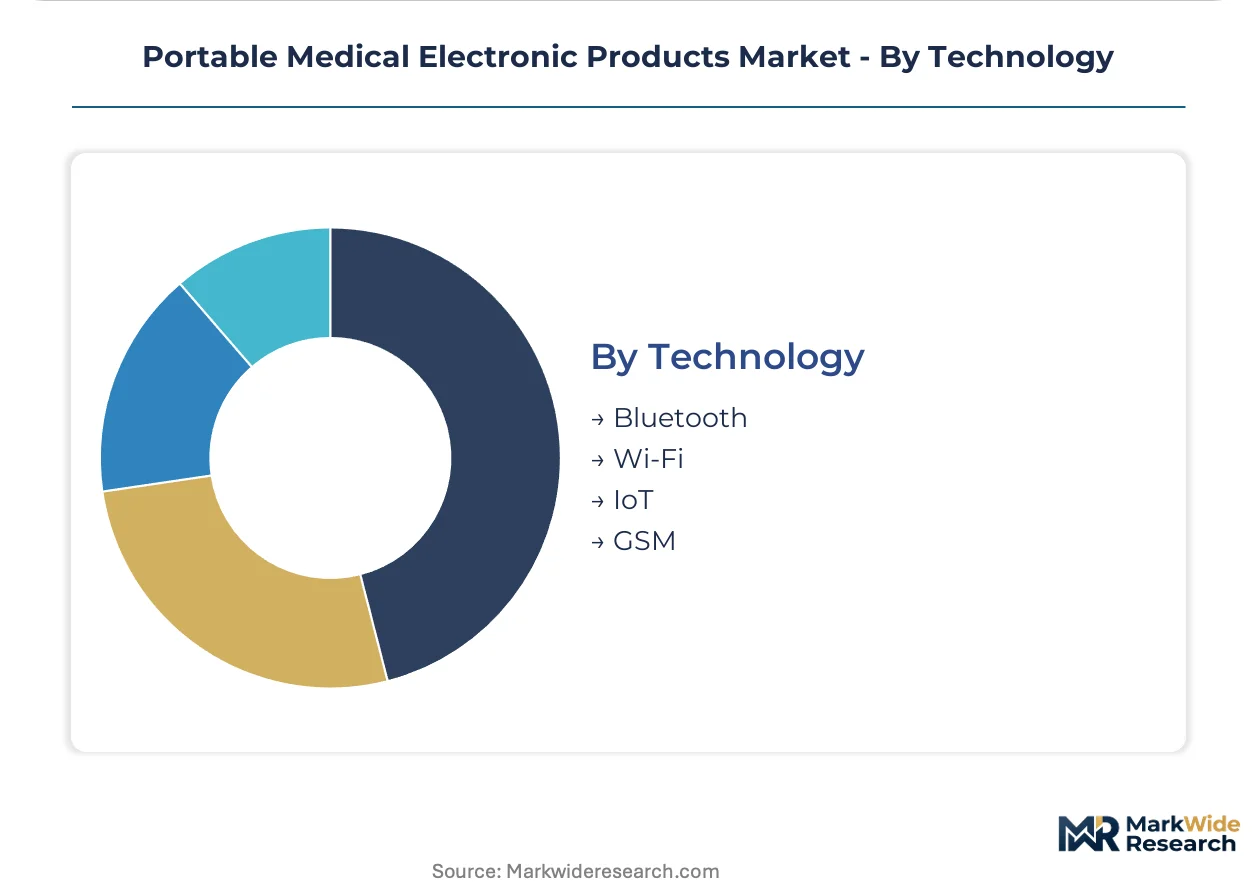
Technology:
Wireless protocol selection determines chipset sourcing strategy, cybersecurity compliance burden, and geographic certification complexity.
- Bluetooth:Low-energy 5.0 and 5.3 implementations dominate wearable cardiac monitors and continuous glucose sensors through Nordic Semiconductor and Silicon Labs SoC platforms. EU MDR cybersecurity annex requirements mandate software bill of materials documentation that forces legacy stack revalidation or chipset replacement.
- Wi-Fi:802.11ac and Wi-Fi 6 enable high-bandwidth telemetry for multi-parameter patient monitors in hospital-at-home deployments. FCC frequency allocation and hospital IT security policies constrain implementation architecture.
- IoT:Cellular LPWAN and proprietary mesh protocols support rural and mobile health applications outside reliable broadband coverage. Module certification timelines extend product development cycles.
- GSM:Legacy 2G/3G connectivity persists in emerging market diagnostic devices though carrier sunset schedules force migration planning.
Bluetooth silicon volumes lead current deployment. Wi-Fi connectivity is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's super-aged society generates concentrated demand for home-based cardiac monitoring, while the United States drives volume through Medicare reimbursement incentives for remote patient monitoring. Germany anchors European procurement through university hospital networks and early discharge protocols. India and the Netherlands represent emerging deployment corridors with distinct regulatory and infrastructure profiles.
United States
Medicare's remote patient monitoring reimbursement codes accelerate hospital-at-home program adoption for multi-parameter patient monitors. FDA 510(k) premarket notification shapes clearance timelines for Bluetooth-enabled diagnostic devices. Boston and Minneapolis medical device clusters concentrate engineering talent for MEMS sensor integration and wireless connectivity development.
Germany
University hospital networks prioritize enterprise-grade patient monitoring platforms with HL7 FHIR interoperability for early discharge surveillance. EU MDR Article 83 post-market surveillance mandates force software update cycles and SBOM documentation for radio-enabled devices. The Baden-Württemberg region hosts precision engineering suppliers for flexible printed circuit board assemblies.
Japan
METI reimbursement incentives for home-based cardiac monitoring expand addressable demand for portable ECG devices outside institutional settings. PMDA conformity assessment aligns with international standards while maintaining distinct timeline requirements for novel sensor algorithms. The Kanto region around Tokyo concentrates OEM headquarters and domestic manufacturing partnerships.
India
PLI scheme incentives for medical electronics reduce import duty exposure for devices assembled in Tamil Nadu and Karnataka clusters. CDSCO medical device rules create parallel registration pathways alongside international certifications. Bengaluru and Chennai electronics manufacturing corridors attract contract assembly capacity from mid-tier device manufacturers.
Netherlands
Hospital-at-home programs adopt wearable cardiac monitors for 30-day post-discharge surveillance protocols. EU MDR cybersecurity annex requirements mandate legacy Bluetooth stack revalidation for cloud-connected sleep therapy devices. The Eindhoven region supplies stretchable interconnect technologies for flexible printed circuit board modularization.
Portable Medical Electronic Products Market Competitive Environment
United States producers anchor premium diagnostic and patient monitoring tiers; European specialists hold regulatory compliance and platform integration capabilities. The vendor base concentrates around imaging heritage companies, sensor miniaturization leaders, and integrated platform strategists. Three archetypes dominate: diversified healthcare conglomerates with enterprise IT relationships, pure-play monitoring specialists with FDA clearance expertise, and contract manufacturers scaling assembly for mid-tier OEMs. Competitive moves center on multi-year enterprise agreements with integrated delivery networks and chipset replacement cycles driven by EU MDR cybersecurity mandates.
Among diversified healthcare conglomerates, GE Healthcare and Koninklijke Philips N.V. occupy positions defined by imaging heritage and enterprise platform bundling. Abbott Laboratories exemplifies sensor miniaturization leadership through its focus on continuous glucose monitoring form factors. These three entities represent distinct competitive vectors: GE Healthcare anchors premium diagnostic portfolios, Philips competes across patient monitoring and sleep therapy with integrated strategies, and Abbott sustains leadership in consumable sensor technologies. Their positioning reflects how FDA clearance pathways and reimbursement code availability stratify market access for different device categories.
| Leading Market Players |
|---|
| GE Healthcare |
| Abbott Laboratories |
| Koninklijke Philips N.V. |
| Medtronic plc |
| Omron Healthcare |
| Siemens Healthineers |
| Roche Diagnostics |
| Hologic Inc. |
| General Electric Company |
| Others |
Value Chain & Pricing Dynamics
Silver/silver chloride electrode spot price volatility cascades through portable medical device manufacturing, compressing margins on single-use diagnostic attachments while forcing OEMs to stratify pricing across FDA-cleared premium tiers and retail economy offerings.
Pricing Analysis
Distributor margin layers absorb 15-25 points before retail pharmacy markup, leaving manufacturers to defend position through three-tier pricing structure across premium, standard, and economy levels. FDA 510(k) clearance tier and Bluetooth SoC certification grade drive price differentiation, with clinical-grade patient monitors commanding multiples over wellness-claim pulse oximeters. Cost compression in commoditized blood pressure units intensifies as pharmacy channel expansion concentrates procurement volume, while hospital IDN direct contracts exhibit lowest price sensitivity due to bundled analytics requirements.
Supply Chain Analysis
Biomedical engineering talent scarcity in Tamil Nadu and Karnataka electronics corridors constrains contract manufacturer scaling for mid-tier OEMs shifting from in-house production. Taiwan semiconductor foundries and South Korea battery cell suppliers anchor component sourcing, with lithium-ion cathode materials and Nordic Semiconductor Bluetooth SoCs feeding assembly lines. Single-source PMIC vulnerability from TSMC concentration creates tariff-agnostic disruption risk. Distribution runs through integrated delivery network procurement committees in the United States and university hospital networks in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR Article 83 post-market surveillance mandates compound demand for software-update-enabled diagnostic platforms, creating recurring revenue anchoring for manufacturers with cloud infrastructure.
For Market Incumbents: Lock in multi-year enterprise agreements with US integrated delivery networks before vendor panel consolidation excludes specialist competitors. Invest in FDA 510(k) predicate device libraries to accelerate clearance timelines for novel sensor algorithms. Backward integration into flexible printed circuit board assembly through Baden-Württemberg precision engineering partnerships defends margin position against contract manufacturer commoditization. For New Entrants and Emerging Players: Capture India's PLI scheme manufacturing incentives in Tamil Nadu clusters to bypass import duty exposure on battery-powered diagnostic devices. Target homecare settings in Japan's super-aged society where METI reimbursement codes create addressable demand outside hospital procurement. Lead with direct-to-patient pharmacy channel distribution through CVS and Walgreens retail clinics for blood pressure and pulse oximetry categories. For Investors and Strategic Acquirers: Consolidation pressure builds where EU MDR cybersecurity annex compliance costs exceed mid-tier OEM engineering department capacity. Long-term viability centers on platform suppliers bundling hardware, connectivity, and analytics under single-source hospital contracts. Watch FDA guidance on software bill of materials documentation as inflection signal for chipset replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Premarket notification pathway shapes clearance timelines for Bluetooth-enabled cardiac monitors. |
| CE Marking Pathway | EU MDR conformity assessment mandates SBOM documentation for radio-enabled sleep therapy devices. |
| Hospital System Partnership | Multi-year enterprise agreements with German university hospital networks lock out smaller specialists. |
| Software Companion Development | HL7 FHIR interoperability middleware enables cloud-connected remote patient monitoring reimbursement. |
| Reimbursement Strategy | Medicare remote patient monitoring codes determine geographic rollout speed for multi-parameter configurations. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs leads at OEMs with secondary validation from FDA 510(k) filings, EU MDR notified body certificates, CMS Medicare reimbursement databases, and hospital procurement contract registries. Bottom-up patient monitor and diagnostic device unit economics triangulated against top-down market sizing from contract manufacturer capacity disclosures.
Segment-weighting across product type, application, end user, and wireless technology dimensions anchored volume and value outputs throughout the forecast period. CAGR derivation rested on lithium-ion cell energy density improvement curves, semiconductor foundry capacity expansion timelines, and reimbursement code adoption trajectories by geography. Modeling incorporated EU MDR cybersecurity annex compliance cost burdens and FDA premarket guidance evolution as structural modifiers.
Regulatory timeline delays, silver/silver chloride commodity price spikes, and Taiwan semiconductor supply disruptions are the dominant revision risks to baseline projections. Forecasts reflect assumptions on reimbursement code stability and foundry capacity allocation. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Ingestible Thermometers Market
Medical Devices
US Nurse Call Systems Market
Medical Devices
Global Orthopedic Power Tools Market
Medical Devices
Engine-Driven Endodontic File Market
Medical Devices
Pacemaker/Defibrillator Lead Extraction Kits Market
Medical Devices
Europe Cardiac Rhythm Management Devices Market
Medical Devices
Chest Drainage System Market
Medical Devices
France Ophthalmic Devices Market
Medical Devices
Smart Vision Aids Market
Medical Devices
Global Vaginal Speculum Market
Medical Devices
Parenteral Feeding Devices Market
Medical Devices
Vortex Mixer Market
Medical Devices
Smart Medical Devices Market
Medical Devices
Non-Invasive Pulse Oximeter Market
Medical Devices
Radiolucent Wrist Fixator Market
Medical Devices
Global Brachytherapy Treatment Planning Systems Market