
 Healthcare Data Interoperability Market | 2026-2036
Healthcare Data Interoperability Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Data Interoperability Market Analysis
FHIR R4 certification is unwinding legacy HL7 v2 dominance across enterprise health IT procurement. Epic Systems Corporation leverages its nationwide hospital network to sustain proprietary integration dominance while navigating federal open-API mandates. Cerner Corporation anchors cloud-based interoperability platforms for multi-facility health systems. InterSystems Corporation specializes in health information exchange infrastructure for regional data-sharing consortia.
Healthcare data interoperability denotes the structured exchange of clinical, administrative, and operational information across disparate software systems using standardized protocols, message formats, and application programming interfaces with defined data-element dictionaries and security profiles. Its primary purpose eliminates information silos between care settings, enabling continuity of treatment, population-level analytics, and real-time clinical decision support. Cloud-based deployment architectures are capturing the fastest growth trajectory as health systems migrate from capital-intensive on-premises infrastructure to subscription API models. FHIT technology standards are consolidating market leadership while DICOM retains entrenched position in medical imaging workflows where pixel-data fidelity requirements resist protocol substitution.
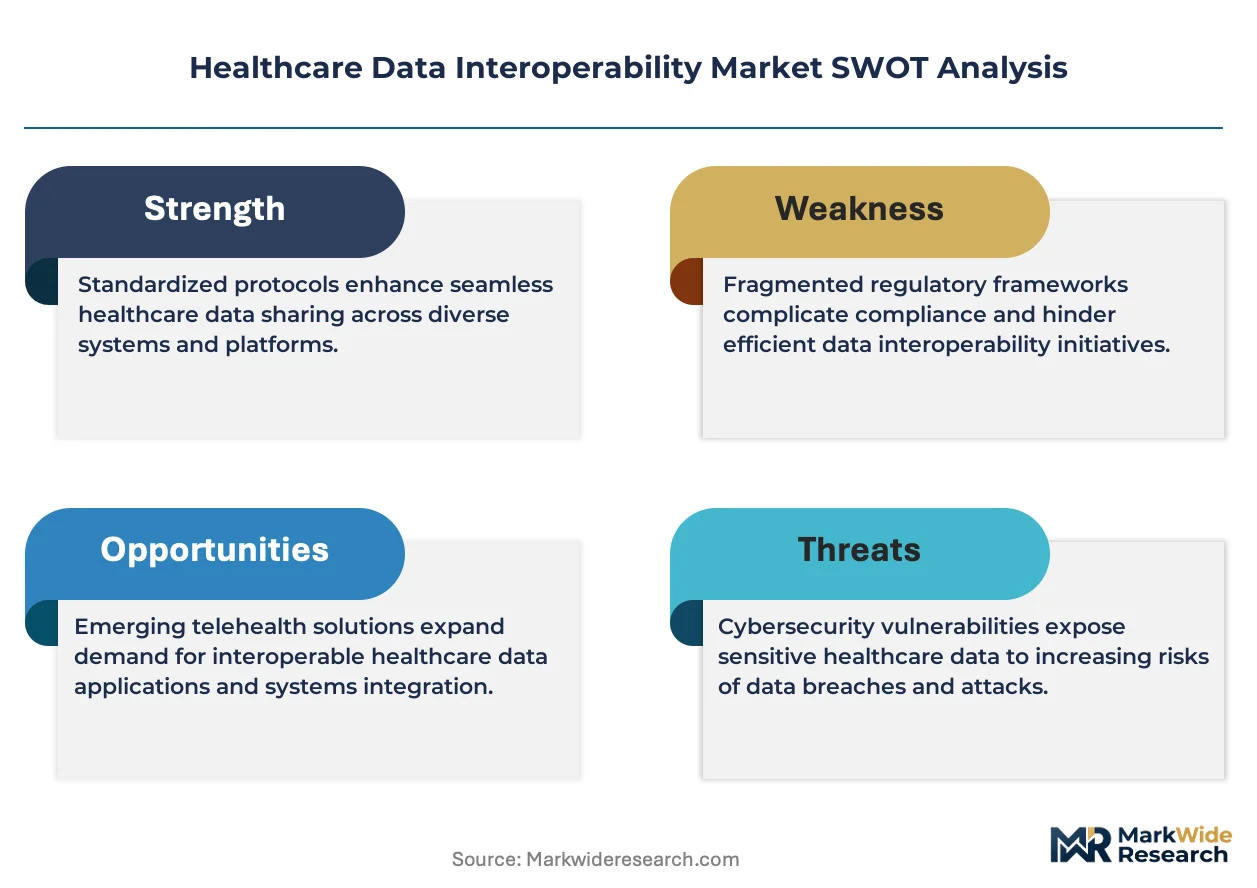
The US Office of the National Coordinator for Health IT enforces information-blocking rules under the 21st Century Cures Act, compelling vendors to expose patient data through standardized APIs or face civil monetary penalties. CMS ties interoperability compliance to Medicare reimbursement schedules, converting regulatory adherence into direct revenue protection for provider organizations. Stakeholders must monitor how TEFCA's national network framework reshapes competitive dynamics between point-to-point integration vendors and health information exchange utilities.
Market Dynamics
FHIR R4 certification is compressing procurement cycles as health systems retire HL7 v2 interfaces. Cloud-based API architectures are displacing capital-intensive on-premises integration engines. Federal information-blocking enforcement converts compliance into competitive survival.
Growth Catalysts
- CMS Reimbursement Ties:Medicare payment schedules now condition full reimbursement on demonstrated interoperability compliance, compelling hospital networks to accelerate API deployment timelines.
- 21st Century Cures Act:Civil monetary penalties for information blocking force EHR vendors to expose patient data through standardized interfaces, dismantling proprietary data silos.
- Health Information Exchange Utilities:Regional HIE consortia in the United States are consolidating data-sharing infrastructure, creating procurement pull for enterprise-grade integration platforms.
Market Restraints
- Legacy System Technical Debt:Decades of HL7 v2 custom interface development create path dependency that resists rapid protocol migration, extending implementation timelines.
- Cloud Subscription Cost Burden:Recurring API gateway fees and data egress charges accumulate unpredictably, straining hospital IT operating budgets already compressed by labor inflation.
- Vendor Concentration Risk:Dominant EHR platforms control integration layer access, extracting premium pricing for third-party connectivity and limiting buyer negotiating leverage.
Strategic Opportunities
- TEFCA National Network Framework:The Trusted Exchange Framework and Common Agreement creates standardized connectivity rules, enabling new entrants to compete against incumbent point-to-point integration vendors.
- Real-Time Clinical Decision Support:Streaming FHIR data feeds enable AI-driven diagnostic assistance at the point of care, opening subscription revenue models for analytics vendors.
- Patient-Authorized Data Exchange:Consumer-facing apps leveraging SMART on FHIR standards unlock direct patient engagement, bypassing traditional provider-controlled data access.
Industry Challenges
- Interoperability Engineer Talent Scarcity:Health IT departments face acute shortages of specialists fluent in both FHIR R4 implementation and legacy HL7 v2 maintenance, delaying project delivery.
- Multi-Vendor Certification Complexity:Each EHR platform maintains proprietary certification requirements for third-party applications, fragmenting development resources across incompatible testing regimes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Data Interoperability Market |
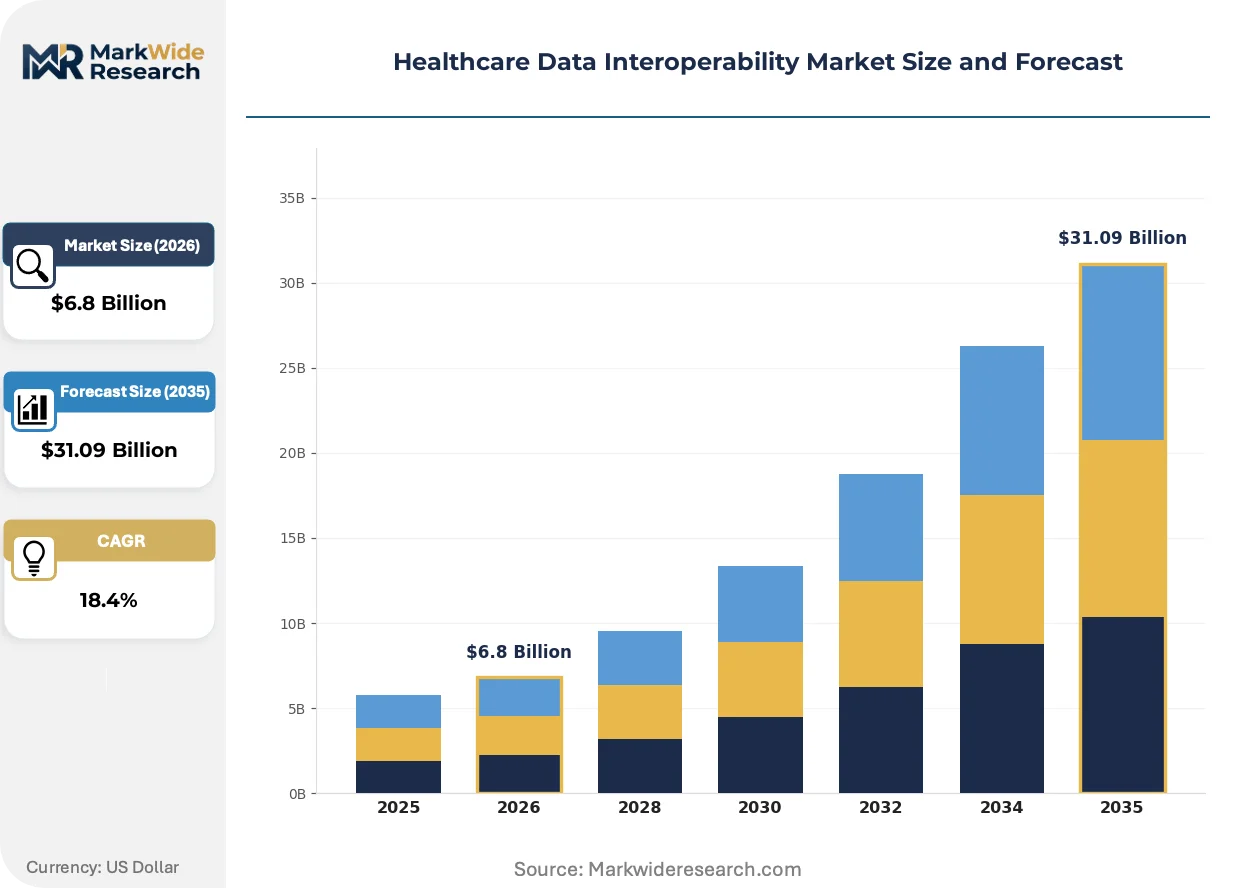
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $31.09 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: FHIR, HL7, DICOM, CCD Application: Clinical Data Exchange, Population Health Management, EHR Integration, Telehealth End User: Hospitals, Clinics, Laboratories, Health Information Exchanges Deployment: Cloud-based, On-premises, Hybrid, API |
| Companies Covered | Epic Systems Corporation, Cerner Corporation, InterSystems Corporation, Oracle Corporation, Koninklijke Philips N.V., Veradigm Inc., Allscripts Healthcare Solutions, NextGen Healthcare, IBM Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Data Interoperability Market Emerging Trajectories
Standardized API architectures are dismantling decades of proprietary health data exchange. Regulatory enforcement is accelerating vendor compliance investments. Buyer procurement criteria are hardening around real-time data liquidity.
FHIR R4 is supplanting legacy HL7 v2 message-based workflows across enterprise health IT procurement. Hospital networks are mandating FHIR-native interfaces for all new system acquisitions, compressing vendor development roadmaps. This protocol shift is enabling real-time patient data aggregation that v2's batch-processing architecture could not support.
The US Office of the National Coordinator for Health IT is escalating civil monetary penalty enforcement for information-blocking violations. EHR vendors now face direct revenue risk from non-compliance, restructuring product roadmaps to prioritize open API exposure. Multi-facility health systems are responding by consolidating vendor contracts around platforms with demonstrated compliance certification.
Health system procurement teams are unbundling integration capabilities from monolithic EHR contracts, creating standalone API gateway purchasing decisions. This disintermediation fragments vendor lock-in strategies and opens evaluation criteria to specialized interoperability platforms. The United States leads this pattern, with integrated delivery networks in Texas and California pioneering multi-vendor API orchestration architectures.
Healthcare Data Interoperability Market Segmentation
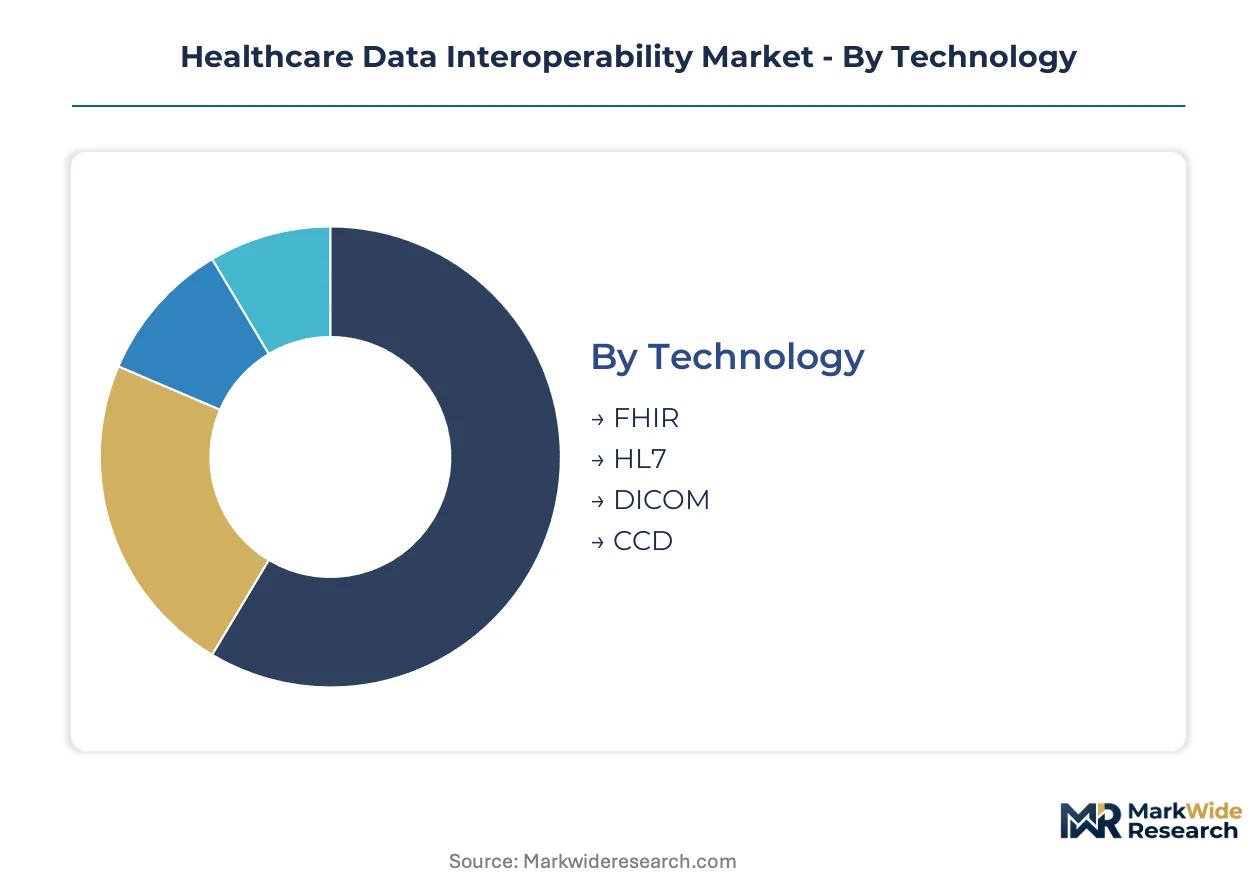
Segmentation in healthcare data interoperability reveals how procurement patterns diverge across technical standards, clinical use cases, and infrastructure architectures. Each dimension carries distinct compliance obligations, cost structures, and vendor selection criteria that reshape competitive positioning.
Technology:
Channel distribution varies sharply by protocol maturity — established standards flow through incumbent EHR vendors while emerging specifications reach buyers via specialized integration platforms and cloud API marketplaces.
- FHIR:RESTful API architecture using JSON and XML resource definitions that enables real-time patient data queries. Demand concentrates in US hospital networks where ONC certification mandates and CMS reimbursement rules compel R4 implementation. Interoperability engineers fluent in SMART on FHIR command premium salaries, constraining deployment velocity.
- HL7:Message-based protocol suite including v2.x and v3 CDA that dominates legacy system connectivity. Large integrated delivery networks in Texas and California maintain thousands of custom v2 interfaces, creating path dependency that resists rapid migration despite federal pressure.
- DICOM:Medical imaging standard securing pixel-data fidelity across radiology and cardiology workflows.
- CCD:Continuity of Care Document format for structured patient summary exchange between disparate systems.
By volume, HL7 leads due to installed base inertia. By growth pace, FHIR is climbing the fastest as procurement teams mandate API-native architectures for new acquisitions.
Application:
Cost tier stratification separates enterprise-wide platforms from point solutions — clinical data exchange commands premium pricing while telehealth modules compete on subscription elasticity.
- Clinical Data Exchange:Real-time transmission of diagnostic results, medication histories, and care summaries across provider networks. US health information exchanges in California and New York anchor procurement volume, driven by TEFCA framework participation requirements and malpractice liability reduction.
- Population Health Management:Aggregation and risk-stratification of patient cohorts across geographic and organizational boundaries. Medicare accountable care organizations drive demand concentration, tying reimbursement to demonstrated care coordination metrics.
- EHR Integration:Middleware connecting proprietary electronic health record systems with third-party applications.
- Telehealth:Virtual care platforms requiring synchronous and asynchronous data synchronization.
Clinical data exchange captures the largest revenue share. Population health management is expanding most quickly as value-based payment models proliferate.
End User:
Customer type determines contract structure — hospitals negotiate enterprise licenses while laboratories prioritize per-test transaction pricing.
- Hospitals:Multi-facility health systems operating emergency departments, inpatient units, and specialty centers. IDNs in Florida and Illinois consolidate vendor contracts around platforms with demonstrated 21st Century Cures Act compliance, extracting volume discounts from EHR incumbents.
- Clinics:Ambulatory practices and urgent care centers requiring lightweight integration. Federally qualified health centers drive procurement in underserved regions, constrained by limited IT capital budgets and staffing shortages.
- Laboratories:Clinical and pathology testing facilities exchanging results with ordering providers.
- Health Information Exchanges:Regional data-sharing utilities connecting competing provider organizations.
Hospitals dominate absolute spending. Health information exchanges are gaining share fastest as TEFCA national network participation becomes a competitive necessity.
Deployment:
Maturity curves separate established infrastructure from emerging delivery models — on-premises installations face depreciation pressure while API-first architectures attract venture-backed entrants.
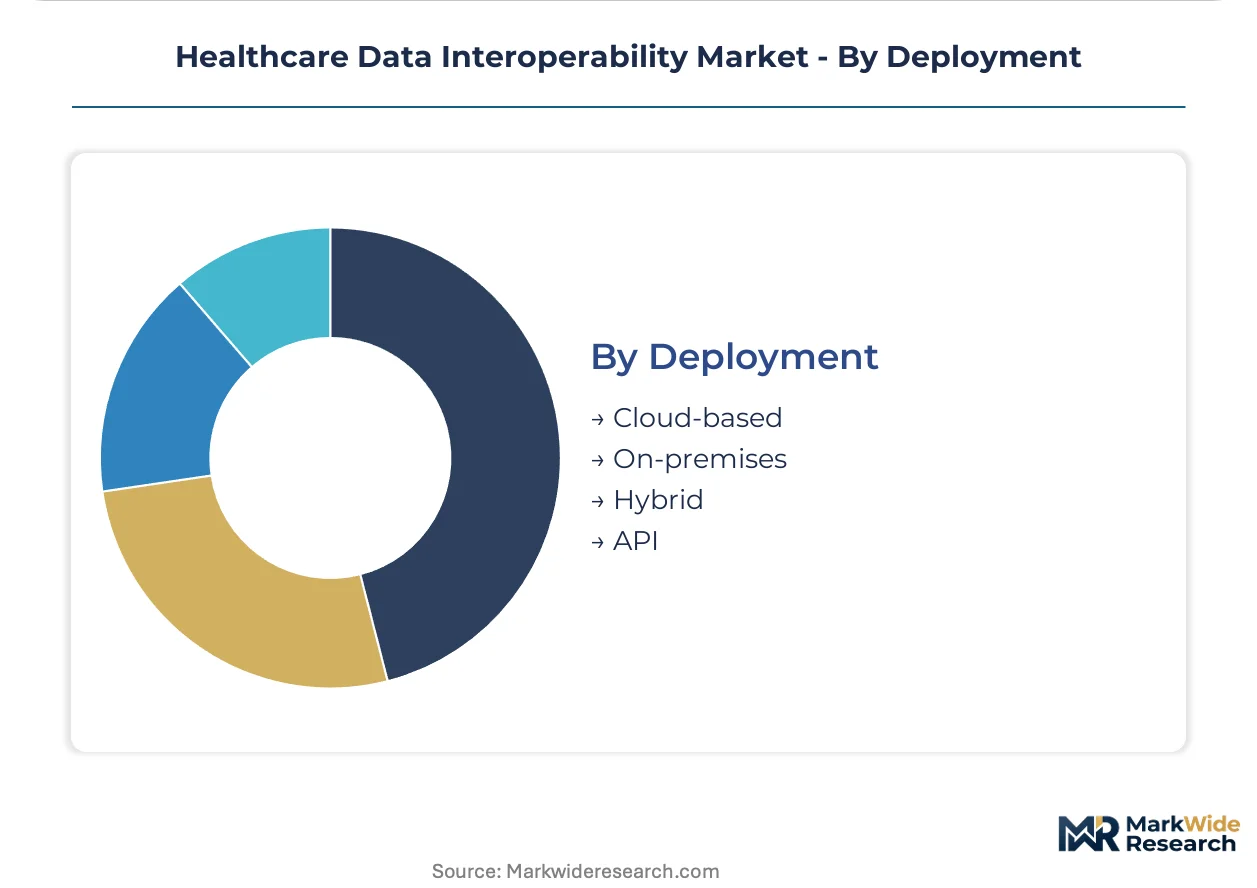
- Cloud-based:Subscription API gateways and managed integration platforms hosted by hyperscale providers. Health systems in Washington and Massachusetts accelerate migration to escape capital-intensive server refresh cycles, though data egress fees strain operating budgets.
- On-premises:Self-managed integration engines within hospital data centers. Rural critical access hospitals retain this model due to limited broadband reliability and cybersecurity risk tolerance.
- Hybrid:Split architectures preserving sensitive workloads on-premises while exposing non-clinical data through cloud APIs.
- API:Standalone gateway products decoupled from monolithic EHR contracts.
On-premises retains the largest installed base. Cloud-based deployment shows the steepest expansion trajectory as procurement teams unbundle integration from core EHR agreements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement teams in the United States absorb premium pricing for certified FHIR platforms, while health systems in India and Southeast Asia prioritize cost-efficient HL7 middleware, creating a demand elasticity gradient that shapes vendor pricing architectures.
United States
Federal reimbursement rules and malpractice liability pressures drive hospital network investment in real-time data exchange infrastructure. The 21st Century Cures Act information-blocking provisions enforced by the Office of the National Coordinator for Health IT compel EHR vendors to expose standardized APIs. Integrated delivery networks in Texas and California anchor procurement volume, with multi-facility systems consolidating vendor contracts around compliance-certified platforms.
Germany
Hospital federation purchasing cooperatives and statutory health insurance digitization mandates accelerate interoperability platform deployment. The country's national pharmaceutical regulator supports EUDAMED connectivity requirements for medical device data integration. Industrial clusters in North Rhine-Westphalia and Bavaria concentrate health IT development, with university hospitals in Munich and Cologne piloting FHIR-based care coordination networks.
United Kingdom
NHS England's federated data platform procurement and integrated care system restructuring create centralized demand for population health analytics infrastructure. The country's national health technology regulator enforces medical software interoperability standards through UKCA marking requirements. London and the Greater Manchester health innovation cluster concentrate vendor development activity, with academic medical centers testing AI-enabled diagnostic data feeds.
Japan
Aging population care coordination requirements and hospital group consolidation drive investment in cross-facility data sharing platforms. METI's Society 5.0 healthcare digitization roadmap incentivizes standardized API adoption for chronic disease management. The Kanto region around Tokyo and the Kansai cluster centered on Osaka host the densest concentration of health IT procurement, with regional medical associations mandating electronic referral data exchange.
India
Central government health mission digitization targets and private hospital chain expansion create fragmented but volume-heavy demand for affordable integration solutions. The country's national pharmaceutical regulator advances medical device and software registration requirements that presume data exchange capabilities. Health IT procurement concentrates in Maharashtra's Mumbai-Pune corridor and Karnataka's Bangalore hub, where hospital networks balance cost constraints against ABHA registry compliance obligations.
Healthcare Data Interoperability Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the healthcare data interoperability market. The vendor base organizes into three tiers: dominant EHR platforms controlling integration layer access, specialized health information exchange infrastructure providers, and cloud-native API gateway entrants. Consolidation pressure intensifies as procurement teams unbundle integration capabilities from monolithic contracts. M&A activity targets FHIR certification assets, while strategic partnerships between EHR incumbents and hyperscale cloud providers reshape deployment economics.
Among dominant EHR-integrated platforms, Epic Systems Corporation, Cerner Corporation, and InterSystems Corporation exemplify the incumbent archetype that leverages installed base density to sustain proprietary integration dominance. These vendors occupy positions where federal open-API mandates intersect with hospital network procurement consolidation, representing the compliance-driven competitive vector that structures pricing power and vendor selection criteria across enterprise health IT markets.
| Leading Market Players |
|---|
| Epic Systems Corporation |
| Cerner Corporation |
| InterSystems Corporation |
| Oracle Corporation |
| Koninklijke Philips N.V. |
| Veradigm Inc. |
| Allscripts Healthcare Solutions |
| NextGen Healthcare |
| IBM Corporation |
| Others |
Supply Flow & Price Mechanics
Cloud-based API gateway adoption replacing capital-intensive on-premises integration engines simultaneously redistributes supply geography toward hyperscale data center regions and compresses pricing power for legacy hardware vendors while elevating recurring subscription revenue streams.
Pricing Analysis
After-sales service contracts and API gateway management fees drive lifetime value for interoperability platform vendors. The dominant pricing structure centers on tiered SaaS subscriptions scaled by transaction volume and data throughput tiers. Price differentiation rests on FHIR R4 certification grade and geographic deployment complexity. Pricing pressure stems from health system procurement teams unbundling integration from monolithic EHR contracts. Federally qualified health centers exhibit acute price sensitivity, while multi-facility integrated delivery networks absorb premium pricing for compliance-certified platforms.
Supply Chain Analysis
The United States anchors health information exchange infrastructure development, while India and Ireland concentrate cloud API gateway engineering talent. The supply chain draws from hyperscale cloud compute capacity, FHIR implementation specialist labor pools, and legacy HL7 v2 interface maintenance expertise. Single-source vulnerability concentrates around dominant EHR platform integration layer access. Distribution runs through direct enterprise sales teams serving hospital procurement committees and health information exchange utility consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as integrated delivery networks consolidate vendor contracts around compliance-certified platforms, extracting volume discounts and fragmenting incumbent lock-in strategies.
For Market Incumbents: Consolidate integration layer control by deepening FHIR R4 certification assets and acquiring specialized health information exchange infrastructure providers. Cloud-native API gateway entrants threaten proprietary data silo economics. Vertical integration into real-time clinical decision support analytics preserves pricing power against unbundling pressures. For New Entrants and Emerging Players: Anchor in patient-authorized data exchange applications leveraging SMART on FHIR standards, where provider-controlled access gates are weakest. Federally qualified health centers present the most penetrable buyer segment due to limited IT capital budgets. A direct-to-clinic subscription model bypasses entrenched hospital procurement committee gatekeeping. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed health information exchange utilities seeking exit liquidity as TEFCA national network participation becomes competitive necessity. Long-term viability favors platforms with demonstrated 21st Century Cures Act compliance certification and cloud-native API architectures. Monitor CMS reimbursement rule adjustments as inflection indicators for hospital network procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FHIR R4 Certification Investment | ONC certification mandates and CMS reimbursement rules compel rapid protocol migration across US hospital networks. |
| Health Information Exchange Partnership | TEFCA framework participation requirements create procurement pull for enterprise-grade integration platforms in California and New York. |
| Cloud API Gateway Expansion | Hyperscale provider partnerships reshape deployment economics for multi-facility systems escaping capital-intensive server refresh cycles. |
| Real-Time Clinical Decision Support Development | Streaming FHIR data feeds enable AI-driven diagnostic assistance subscription revenue models at the point of care. |
| Patient-Facing App Launch | SMART on FHIR standards unlock direct consumer engagement, bypassing traditional provider-controlled data access channels. |
Methodological Framework
A spread of perspectives from interoperability engineers, hospital procurement managers, health information exchange utility directors, and EHR platform product strategists converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against hospital procurement databases, GPO contracts, CMS Medicare reimbursement filings, and ONC certification registries. Bottom-up deployment estimates triangulated against top-down market sizing from federal health IT expenditure disclosures.
Segmentation dimensions modeled encompass technology protocol, clinical application use case, end-user facility type, and deployment architecture across the projection horizon. CAGRs derived from trend extrapolation of federal mandate compliance timelines and health system capital expenditure patterns. Forecast inputs incorporated TEFCA network participation trajectories and cloud migration velocity indices for integrated delivery networks.
Decision-makers should treat outputs as directional under sustained federal information-blocking enforcement and stable CMS reimbursement tie structures; material deviation in regulatory intensity or health system consolidation pace would warrant model refresh. Recalibration cycles align with material shifts in ONC certification requirement updates and TEFCA framework implementation milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Data Management
United States Healthcare Big Data Analytics Market
Health Data Management
Data Monetization in Healthcare Market
Health Data Management
Data Democratization in Healthcare Market
Health Data Management
Healthcare Predictive Analytics Market
Health Data Management
Point of Care (POC) Data Management Systems Market
Health Data Management
Global Precision Medicine Software Market
Health Data Management
Europe Healthcare Analytics Market
Health Data Management
Medical Record Management System Market
Health Data Management
Healthcare Archiving and Ediscovery Market
Health Data Management
Patient Data Management Systems Market
Health Data Management
US Mobile Health Market
Health Data Management
Healthcare Data Annotation Tools Market
Health Data Management
Population Health Management Platforms Market
Health Data Management
Wireless Healthcare Asset Management Market
Health Data Management
Healthcare Data Collection and Labeling Market
Health Data Management
Point-Of-Care Data Management Software Market