
 Healthcare Archiving and Ediscovery Market | 2026-2036
Healthcare Archiving and Ediscovery Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Archiving and Ediscovery Market Outlook
HIPAA data retention mandates is hardening compliance requirements for long-term healthcare record preservation. IBM Corporation leverages its enterprise AI infrastructure to anchor large-scale archiving deployments across integrated delivery networks. Commvault Systems Inc. specializes in hybrid cloud data protection, while Exterro Inc. competes in the legal hold and ediscovery workflow segment with integrated governance tools.
Healthcare archiving and ediscovery encompasses the systematic retention, indexing, and legally defensible retrieval of electronic health records, clinical communications, and billing documentation, typically requiring immutable storage with cryptographic verification and chain-of-custody audit trails. Cloud-based solutions lead deployment preferences as hospitals seek elastic capacity for petabyte-scale imaging archives and unstructured clinical data lakes. Artificial intelligence and machine learning represent the fastest-expanding technology layer, automating predictive coding and privilege detection in litigation response workflows.
FDA 21 CFR Part 11, HIPAA Security Rule, and state-level data breach notification laws collectively shape product standards for audit logging, access controls, and encryption in healthcare archiving platforms. The SEC and DOJ have expanded ediscovery scope to include clinical trial communications and promotional materials, forcing vendors to certify defensible deletion and legal hold capabilities. Stakeholders must monitor evolving state privacy statutes and federal interoperability rules to calibrate retention architectures against compliance exposure.
Market Dynamics
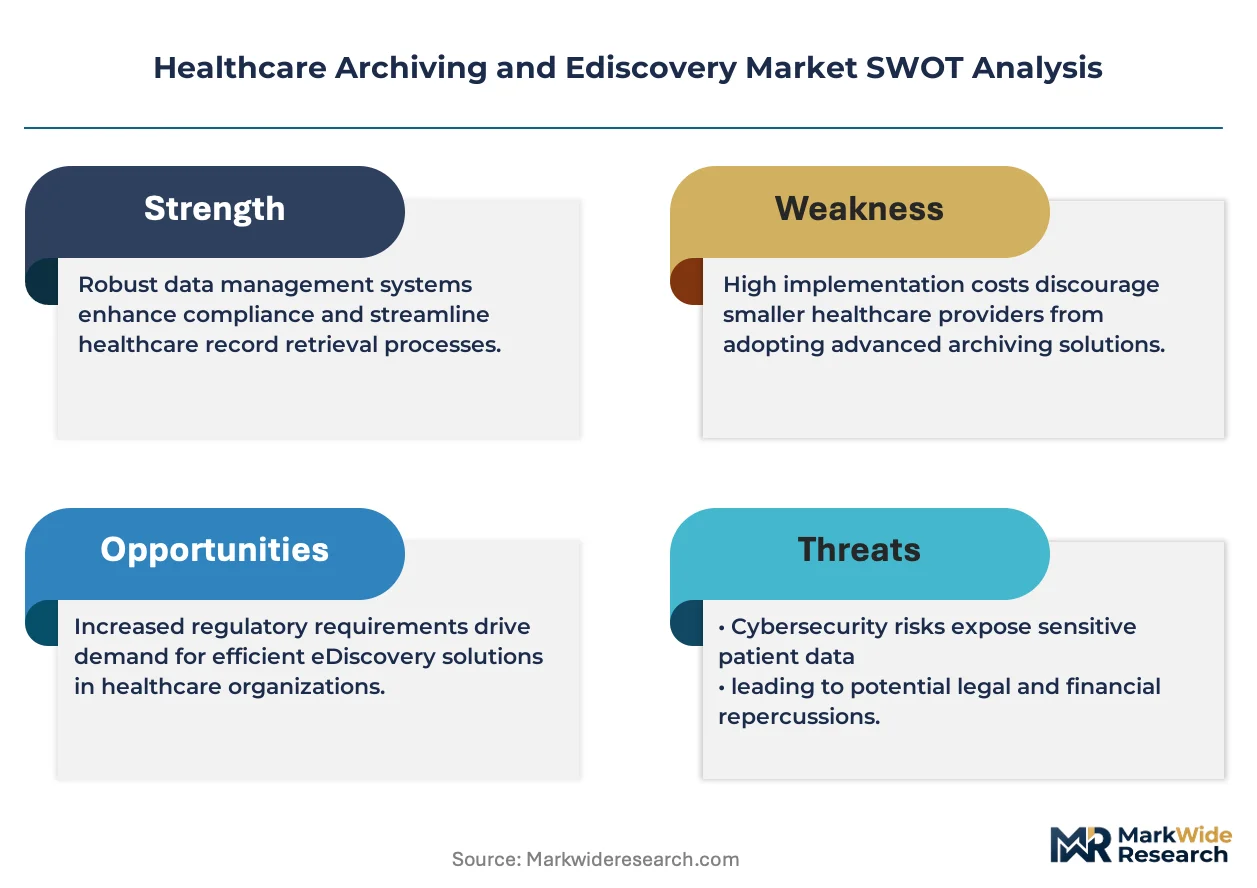
Hospital networks are consolidating data infrastructure under unified governance frameworks, forcing vendors to architect petabyte-scale archiving platforms that satisfy simultaneous HIPAA, FDA 21 CFR Part 11, and state-level discovery mandates.
Growth Catalysts
- HIPAA Security Rule enforcement:Federal audits of access controls and encryption standards are compelling health systems to replace fragmented storage with certified enterprise archives.
- Litigation volume against US health systems:Malpractice and billing disputes are generating discovery requests that require immutable chain-of-custody documentation.
- Artificial intelligence in predictive coding:Machine learning algorithms are automating privilege detection and document classification, compressing ediscovery timelines from months to weeks.
Market Restraints
- Cloud egress cost volatility:Petabyte-scale imaging archives generate unpredictable data transfer fees that strain hospital IT budgets.
- FDA validation requirements:21 CFR Part 11 compliance for electronic records demands extensive documentation, extending sales cycles.
- Legacy EMR fragmentation:Proprietary data formats from Epic, Cerner, and Meditech systems resist standardized indexing and retrieval.
Strategic Opportunities
- Medicaid expansion states:Newly insured populations in Texas and Florida are generating additional clinical documentation requiring long-term retention.
- Clinical trial communications:SEC and DOJ ediscovery scope expansion into promotional materials creates demand for defensible deletion tools.
- FHIR interoperability mandates:Federal rules requiring standardized health data exchange are accelerating archive modernization investments.
Industry Challenges
- Forensic data science talent scarcity:Health systems struggle to hire specialists capable of bridging clinical informatics with legal hold procedures.
- Multi-jurisdictional retention conflicts:State privacy statutes impose varying deletion timelines that complicate unified archiving architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Archiving and Ediscovery Market |
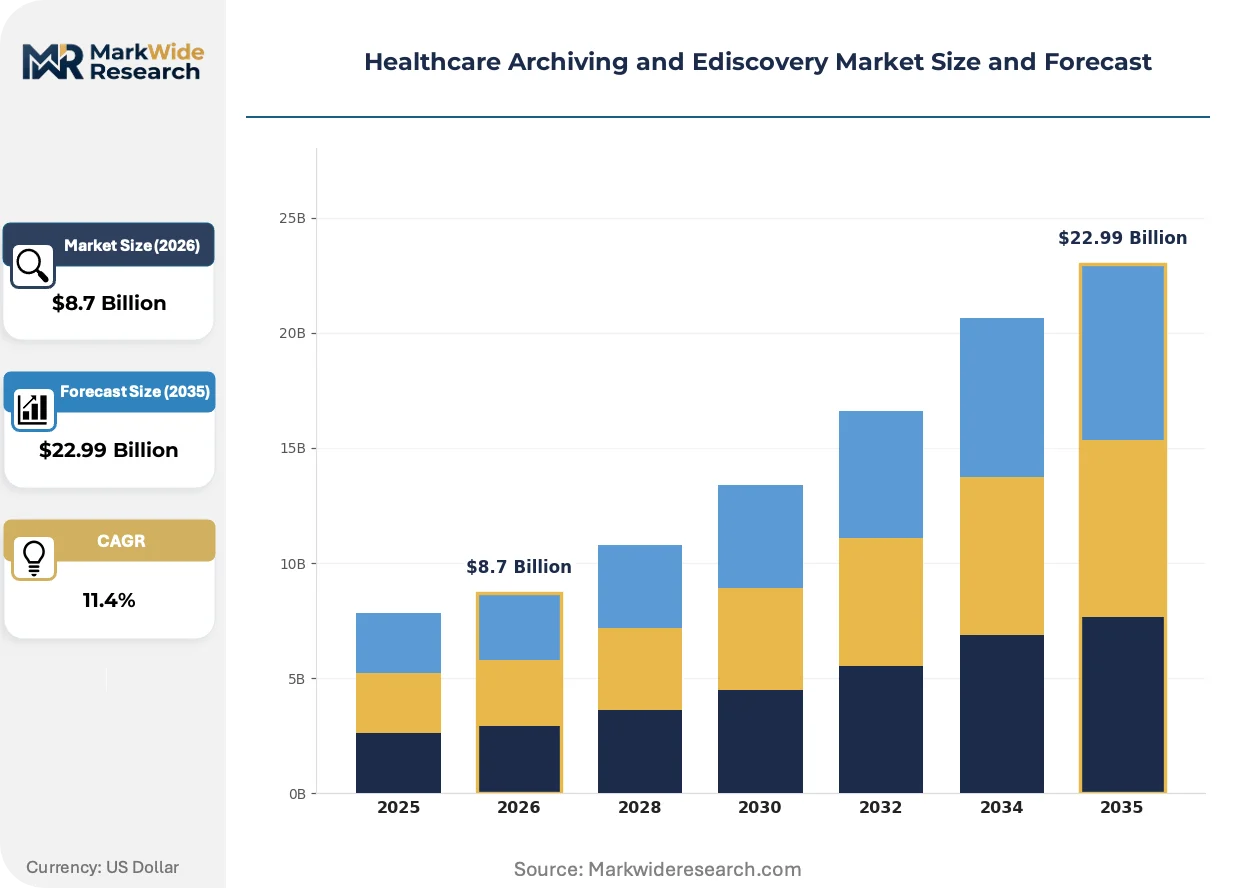
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based Solutions, On-Premises Solutions, Hybrid Solutions, Data Storage Devices End User: Hospitals, Clinics, Laboratories, Insurance Providers Technology: Artificial Intelligence, Machine Learning, Blockchain, Encryption Techniques Deployment: Managed Services, On-Demand Services, Subscription-Based Services, Custom Solutions |
| Companies Covered | Commvault Systems Inc., Allscripts Healthcare Solutions Inc., Barracuda Networks Inc., GE Healthcare, IBM Corporation, Intradyn, Exterro Inc., Global Relay Communications Inc., ZL Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Archiving and Ediscovery Market Strategic Shifts
Healthcare archiving is pivoting from passive storage to active governance platforms, with artificial intelligence and regulatory automation reshaping how health systems manage litigation readiness and compliance documentation.
Immutable object storage with cryptographic verification is expanding into integrated delivery networks as the foundational layer for defensible ediscovery. Academic medical centers and large hospital systems are deploying these architectures to satisfy simultaneous FDA, HIPAA, and state audit requirements. The technology is expanding into previously underserved mid-tier health systems through managed service offerings that eliminate capital expenditure barriers.
State-level data breach notification laws are proliferating beyond California's CCPA model, creating a patchwork of retention and deletion mandates that archiving vendors must encode into automated policy engines. Health systems operating across multiple states face compliance complexity that favors platforms with jurisdiction-aware workflow automation. The US Southeast and Southwest regions, where Medicaid expansion and population growth concentrate, are experiencing the most acute demand for multi-state governance tools.
General counsel offices are consolidating vendor relationships from point solutions to integrated governance suites, collapsing separate contracts for archiving, legal hold, and ediscovery into single-platform procurement. Health system purchasing committees now mandate API connectivity between archiving platforms and existing EMR investments. This consolidation pattern is most pronounced in the Northeast, where integrated delivery networks with mature legal operations functions lead vendor rationalization initiatives.
Healthcare Archiving and Ediscovery Market Segmentation
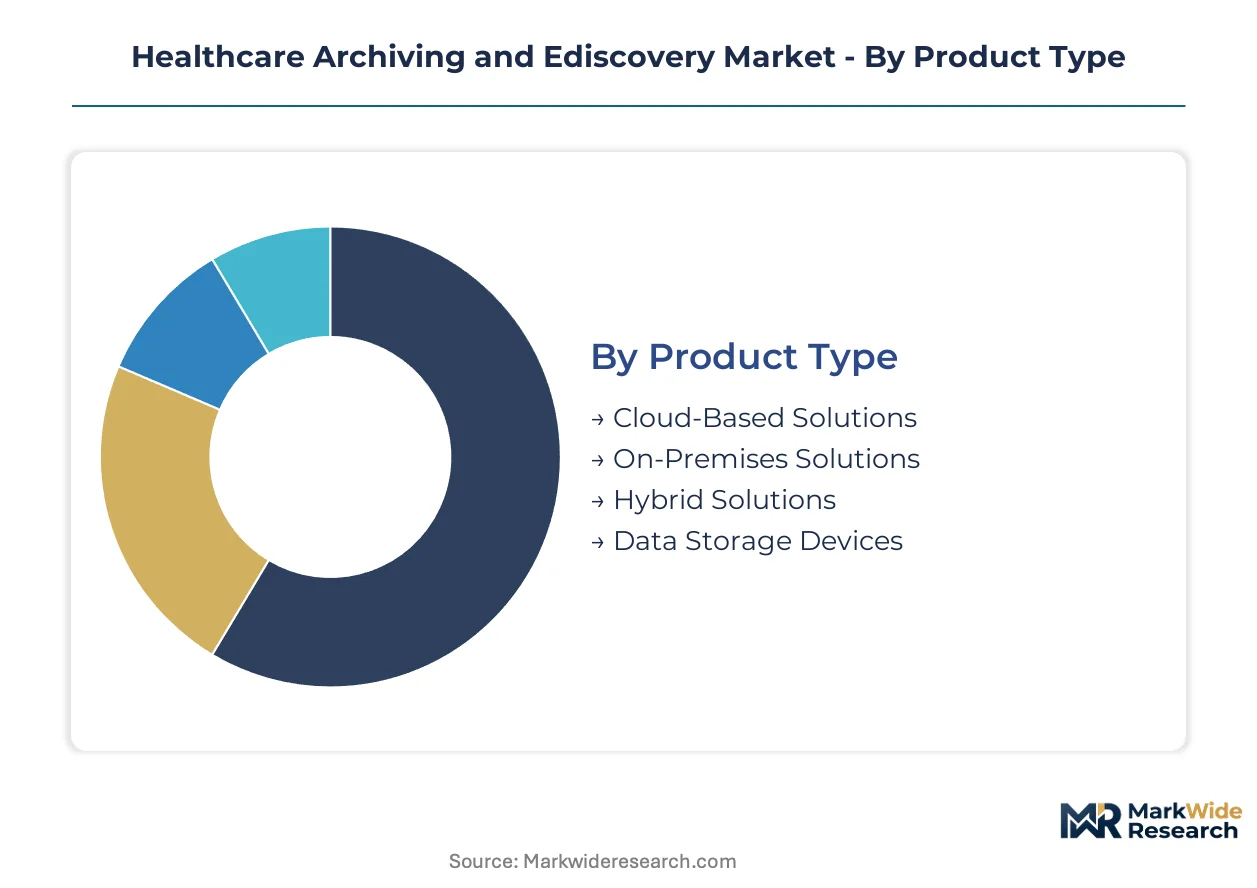
Healthcare archiving and ediscovery segmentation reflects divergent infrastructure maturity across health systems, with upgrade cycles accelerating where HIPAA enforcement and litigation risk intersect. Procurement patterns split between cloud-native architectures favored by consolidating networks and on-premises retention demanded by research institutions with FDA-regulated trials.
Product Type:
Replacement cycles for legacy storage infrastructure are compressing as federal audits expose compliance gaps in fragmented environments, forcing unified platform decisions.
- Cloud-Based Solutions:Elastic object storage architectures with cryptographic immutability serve petabyte-scale imaging archives and unstructured clinical data lakes. Academic medical centers in California and Texas are deploying these platforms to satisfy simultaneous HIPAA Security Rule encryption mandates and state-level discovery obligations.
- On-Premises Solutions:Air-gapped storage arrays with hardware-based encryption keys address FDA 21 CFR Part 11 validation requirements for electronic records in pharmaceutical research settings. Pharmaceutical sponsors running multi-site clinical trials prefer these configurations for audit trail integrity.
- Hybrid Solutions:Tiered architectures combining local SSD caches with cloud cold storage optimize retrieval latency for active litigation holds.
- Data Storage Devices:Tape libraries and optical media systems persist in long-term retention scenarios exceeding seven-year statutory minimums.
Cloud-Based Solutions sits at the top of the volume ranking, with Hybrid Solutions climbing the fastest.
End User:
Customer concentration follows litigation exposure and documentation complexity, with procurement authority consolidating under general counsel oversight.
- Hospitals:Integrated delivery networks with mature legal operations functions are collapsing separate archiving, legal hold, and ediscovery contracts into single-platform procurement. Northeast health systems lead this vendor rationalization pattern.
- Clinics:Federally qualified health centers in Medicaid expansion states generate surging documentation volumes requiring retention infrastructure scaled to limited IT budgets.
- Laboratories:Clinical and anatomic pathology operations produce imaging and genomic datasets with 10-25 year retention horizons tied to malpractice statutes.
- Insurance Providers:Payers face SEC and DOJ ediscovery scope expansion into promotional materials and prior authorization communications.
Hospitals command the dominant procurement volume, while Insurance Providers are gaining share fastest as regulatory scrutiny intensifies.
Technology:
Technology adoption correlates with ediscovery timeline compression, where automation substitutes for scarce forensic data science talent.
- Artificial Intelligence:Natural language processing engines automate predictive coding and privilege detection in litigation response workflows, compressing document review from months to weeks. Northeast health systems with dedicated legal operations teams are deploying these capabilities.
- Machine Learning:Supervised classification algorithms trained on historical privilege determinations reduce false positive rates in privilege logs. Vendors serving mid-tier health systems offer these as managed service overlays.
- Blockchain:Distributed ledger verification creates tamper-evident audit trails for chain-of-custody documentation.
- Encryption Techniques:AES-256 and format-preserving encryption satisfy HIPAA Security Rule technical safeguards for data at rest.
Artificial Intelligence leads technology investment, with Machine Learning expanding most quickly through vendor-managed service models.
Deployment:
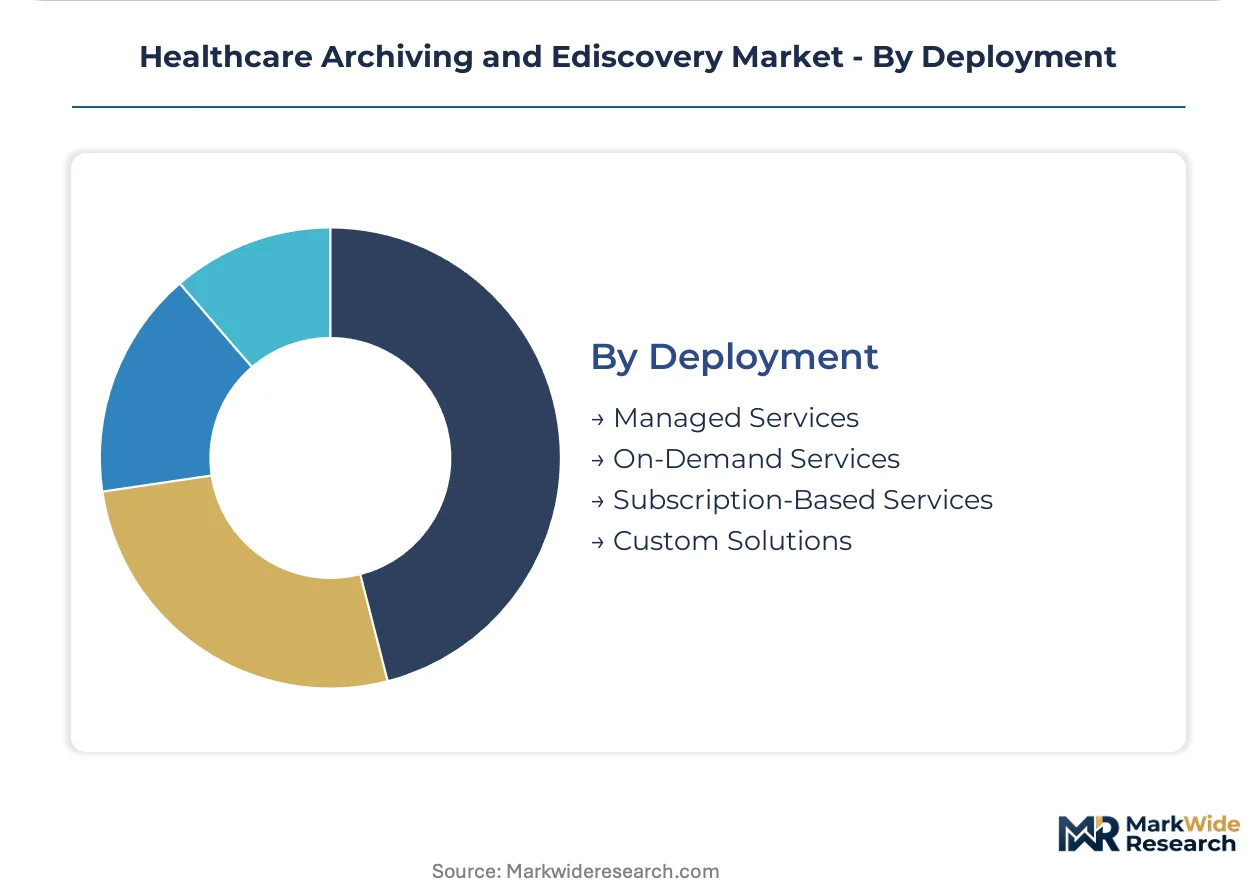
Commercial structure selection reflects capital availability and internal technical capacity, with subscription models penetrating mid-tier health systems.
- Managed Services:Fully outsourced archiving operations eliminate capital expenditure barriers for community hospitals and rural health networks. Southeast and Southwest regions, where Medicaid expansion concentrates, show strongest uptake.
- On-Demand Services:Pay-per-matter ediscovery processing addresses episodic litigation spikes without committed infrastructure investment.
- Subscription-Based Services:Predictable monthly fees for storage and processing capacity appeal to CFOs managing constrained IT budgets.
- Custom Solutions:Bespoke architectures serve academic medical centers with unique research data governance requirements.
Managed Services represents the fastest-growing trajectory as vendor consolidation accelerates, with Custom Solutions remaining concentrated in elite research institutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The healthcare archiving and ediscovery industry traces its commercial origins to United States hospital network consolidation during the 2010s, when HIPAA enforcement and malpractice litigation first compelled enterprise-scale record retention infrastructure.
United States
Federal litigation volume against health systems and SEC ediscovery scope expansion into clinical trial communications drive platform procurement. HIPAA Security Rule audits and FDA 21 CFR Part 11 validation requirements shape vendor certification standards. Texas and Florida Medicaid expansion states generate acute demand for multi-state governance tools as newly insured populations swell documentation volumes.
Germany
GDPR retention-deletion conflicts and EU MDR clinical data mandates complicate unified archiving architectures for pharmaceutical sponsors. The country's national data protection regulator enforces strict cross-border transfer limitations on health records. Bavaria's medical device manufacturing clusters around Munich deploy validated on-premises systems for trial audit trail integrity.
United Kingdom
NHS Digital transformation programs and NHSX data standards accelerate cloud migration for imaging archives and unstructured clinical data lakes. The national health service's information governance framework mandates immutable storage with cryptographic verification. London's integrated care systems lead vendor consolidation from point solutions to unified governance suites.
Japan
PMDA pharmacovigilance data retention rules and METI healthcare digitization initiatives extend archiving horizons for pharmaceutical R&D operations. The country's pharmaceutical regulator requires extensive documentation for electronic records in multi-site clinical trials. Kanto region academic medical centers deploy hybrid architectures combining local SSD caches with cloud cold storage for litigation holds.
Australia
TGA therapeutic goods documentation requirements and state-level health record privacy statutes create jurisdiction-aware workflow automation demand. The national therapeutic goods regulator mandates audit logging and access controls for clinical trial materials. New South Wales and Victoria hospital networks consolidate separate archiving, legal hold, and ediscovery contracts into single-platform procurement.
Healthcare Archiving and Ediscovery Market Competitive Environment
Capital-heavy infrastructure vendors compete with asset-light workflow specialists across the healthcare archiving landscape. The market structure fragments across enterprise technology conglomerates, pure-play data protection vendors, and legal technology specialists. Three strategic archetypes dominate: cloud-native platform providers, hybrid infrastructure specialists, and ediscovery workflow integrators. M&A activity concentrates on legal hold automation capabilities, while strategic partnerships target EMR system API connectivity.
Within the enterprise technology tier, IBM Corporation and GE Healthcare occupy positions anchored by healthcare industry vertical expertise. Commvault Systems Inc. exemplifies the hybrid cloud data protection archetype, while Exterro Inc. represents the legal hold and ediscovery workflow specialization. These three companies illustrate the competitive spectrum from infrastructure-scale archiving through governance-centric litigation readiness platforms.
| Leading Market Players |
|---|
| Commvault Systems Inc. |
| Allscripts Healthcare Solutions Inc. |
| Barracuda Networks Inc. |
| GE Healthcare |
| IBM Corporation |
| Intradyn |
| Exterro Inc. |
| Global Relay Communications Inc. |
| ZL Technologies |
| Others |
Value Chain & Pricing Dynamics
Hospital procurement committees collapsing separate archiving, legal hold, and ediscovery contracts into single-platform decisions are compressing vendor margins and forcing infrastructure providers to absorb cloud storage costs upfront. This buyer consolidation dynamic rewards scale players with balance sheet capacity to underwrite multi-year subscriptions while squeezing point-solution specialists.
Pricing Analysis
Subscription-based SaaS tiers with consumption-scaled storage fees dominate healthcare archiving contracts, with pricing stratifying across enterprise-grade immutability certifications, hybrid deployment flexibility, and managed service overlays. Cost compression in mid-tier hospital segments is intensifying because Medicaid expansion states demand elastic capacity without capital expenditure commitments. Federally qualified health centers exhibit acute price sensitivity, while academic medical centers with FDA-regulated trials prioritize audit trail integrity over unit economics.
Supply Chain Analysis
Specialized encryption hardware supply rests on semiconductor fabrication concentrated in Taiwan, South Korea, and the United States, with cryptographic processor availability tethered to advanced node production schedules. Immutable object storage arrays draw from NAND flash supply chains anchored in Japanese and Korean component manufacturers, while tape library mechanisms source from precision engineering clusters in Japan and Germany. Single-source vulnerability in FIPS 140-2 certified encryption modules creates procurement bottlenecks for vendors serving federal healthcare contracts. Distribution runs through direct enterprise sales teams supplemented by EMR system integration partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Healthcare archiving has entered a late-cycle quality phase where HIPAA Security Rule audit failures and FDA 21 CFR Part 11 validation gaps are filtering procurement toward certified enterprise platforms. Hospital networks now mandate cryptographic immutability and chain-of-custody automation as baseline specifications.
For Market Incumbents: Acquire legal hold automation capabilities to collapse point-solution competition into unified governance suites. Defensive consolidation should prioritize API connectivity with Epic and Cerner EMR systems to entrench switching costs. Cloud-native entrants with consumption-based pricing threaten mid-tier hospital accounts where capital expenditure constraints dominate. For New Entrants and Emerging Players: Capture Medicaid expansion states in the US Southeast and Southwest where newly insured populations strain documentation infrastructure beyond legacy capacity. Rural health networks and community hospitals represent the most penetrable segment, with managed service overlays eliminating upfront storage investment as the critical go-to-market wedge. For Investors and Strategic Acquirers: Asymmetric upside sits with hybrid infrastructure specialists possessing both on-premises FDA validation expertise and cloud-native scalability. Long-term viability hinges on jurisdiction-aware policy engines encoding multi-state privacy statutes. Watch SEC and DOJ ediscovery scope expansion into clinical trial communications as the signal for defensible deletion tool demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API connectivity with Epic and Cerner EMR systems locks in hospital switching costs. |
| Acquisition of Specialist Firm | Legal hold automation capabilities collapse fragmented vendor relationships into unified procurement. |
| Geographic Expansion | Medicaid expansion states in Texas and Florida generate surging documentation retention demand. |
| Product Launch | Managed service overlays eliminate capital barriers for rural health network penetration. |
| Strategic Partnership | Cloud infrastructure alliances with hyperscalers absorb petabyte-scale storage cost volatility. |
Study Parameters
Direct dialogue with hospital CIOs, health system general counsel, biomedical informatics directors, and GPO contracts managers grounded qualitative insights in procurement decision dynamics. Secondary validation drew from FDA 21 CFR Part 11 guidance documents, HIPAA Security Rule audit protocols, hospital procurement databases, and CMS Medicare reimbursement filings. Bottom-up and top-down triangulation cross-checked vendor capacity claims against health system infrastructure spend patterns.
Bottom-up modeling aggregated individual health system archiving deployments by technology layer, deployment model, and end-user segment across the projection horizon. Segmentation dimensions included product architecture, regulatory certification tier, organization scale, and regional litigation exposure density. CAGRs derived from fitted growth curves applied to documented replacement cycles and Medicaid expansion enrollment trajectories. Forecast inputs incorporated HIPAA enforcement audit frequency and SEC ediscovery scope precedent.
Regulatory enforcement intensity, cloud storage cost volatility, and EMR system fragmentation are the dominant revision risks to modeled demand. Forecasts reflect documented assumptions about hospital network consolidation velocity and federal audit resource allocation. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Data Management
Data Democratization in Healthcare Market
Health Data Management
Europe Healthcare Analytics Market
Health Data Management
Global Healthcare Content Management System Market
Health Data Management
Healthcare Analytics Market
Health Data Management
Healthcare Data Monetization Solutions Market
Health Data Management
Global Healthcare Customer Data Platform Market
Health Data Management
Healthcare Data Collection and Labeling Market
Health Data Management
Healthcare Data Interoperability Market
Health Data Management
Healthcare Data De-Identification Assurance Market
Health Data Management
Global Healthcare Data Analytics Market
Health Data Management
Americas Healthcare Archiving and Ediscovery Market
Health Data Management
Hospital Management Software Market
Health Data Management
Medical Record Management System Market
Health Data Management
Global Healthcare Financial Analytics Market
Health Data Management
Global Precision Medicine Software Market
Health Data Management
Global Chronic Care Management Software Market