
 Healthcare Predictive Analytics Market | 2026-2036
Healthcare Predictive Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Predictive Analytics Market Intelligence
The buyer landscape for predictive analytics is pivoting from large, monolithic hospital systems to a more fragmented base that includes specialized clinics, insurers, and research organizations. Optum leverages its vast claims data to deliver risk assessment models for insurance companies. IBM specializes in advanced AI platforms for complex clinical decision support in large medical centers. Health Catalyst differentiates through its data-as-a-service offerings that are tailored for regional hospital networks.
Healthcare predictive analytics applies statistical algorithms and machine learning techniques to historical health data to forecast future outcomes. These models process vast datasets, including electronic health records, claims data, and genomic information, to identify key patterns. Cloud-based deployment models are displacing traditional on-premises installations due to superior scalability and lower upfront capital expenditure. Among applications, clinical decision support and patient management represent the fastest-growing areas, driven by provider needs.
Data privacy regulations, including HIPAA in the United States and GDPR in Europe, impose strict controls on the storage and use of protected health information. Concurrently, frameworks like the developing EU AI Act are shaping the emerging requirements for model transparency and algorithmic accountability in medical devices. Stakeholders must now navigate the complex ethical considerations of algorithmic bias to ensure equitable healthcare outcomes across diverse populations.
Market Dynamics
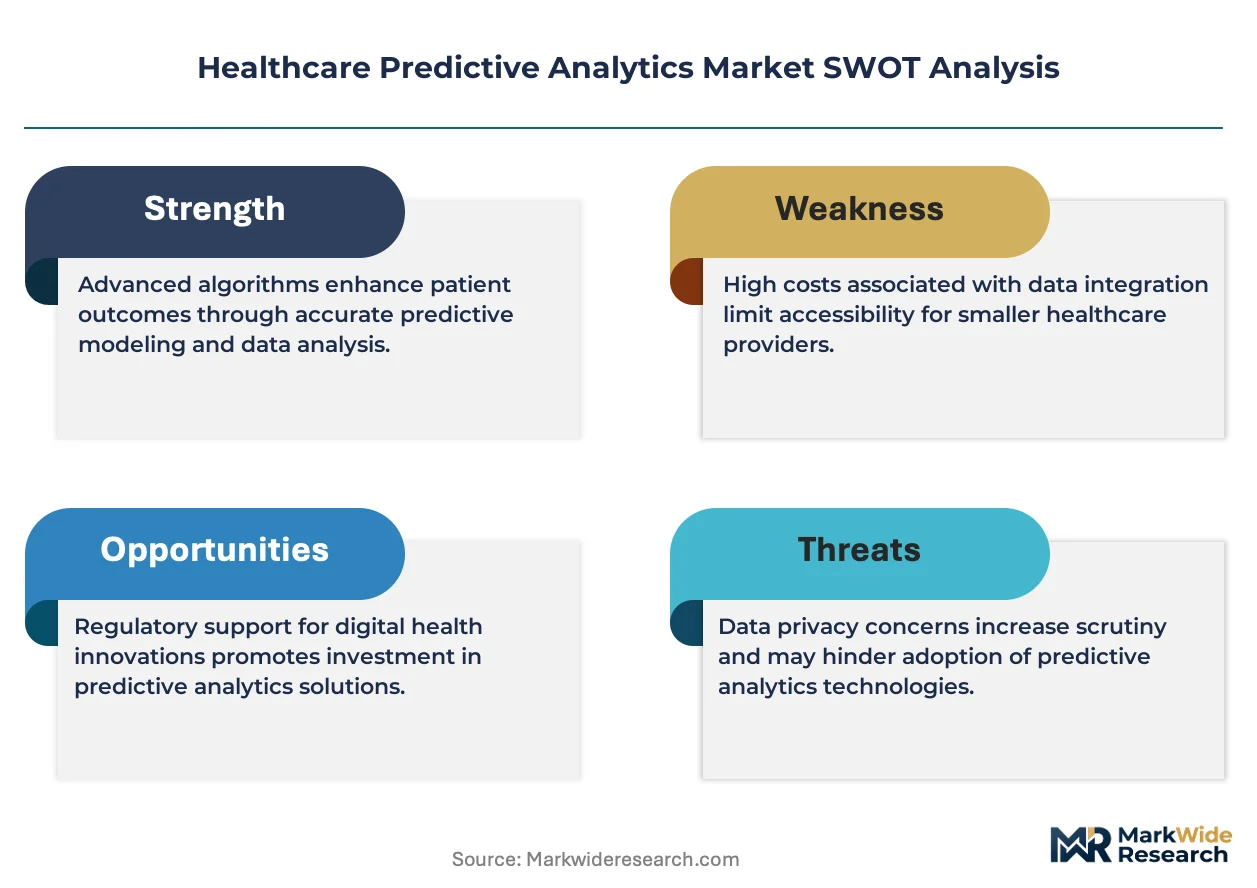
The core market dynamic involves the tension between the need for vast health datasets and stringent data privacy regulations. Frameworks like HIPAA and GDPR directly constrain how developers utilize electronic health records and claims data for model training and validation.
Growth Catalysts
- Value-Based Care Initiatives:Payer and government mandates in the United States are pushing providers toward outcome-based reimbursement. This creates direct financial incentives to adopt predictive analytics for managing patient risk and optimizing resource utilization.
- Cloud Computing Scalability:The shift to cloud-based deployment models lowers capital expenditure for hospital systems. This enables specialized clinics and research organizations to access powerful analytics tools without large on-premise infrastructure investments.
- Genomic Data Integration:The increasing availability of genomic information for clinical use provides a new input for predictive models. This is particularly relevant in oncology and rare disease diagnostics, enhancing precision medicine applications.
Market Restraints
- Algorithmic Transparency Rules:Emerging regulations like the EU AI Act impose requirements for model explainability and accountability. This creates development overhead and legal risk for black-box machine learning models common in the industry.
- Data Interoperability Barriers:A lack of standardized formats for electronic health records across different vendor systems creates significant data siloes. This fragmentation limits the scope and accuracy of models that require integrated, longitudinal patient data.
- High Implementation Costs:The initial cost of integrating predictive analytics platforms with legacy hospital IT systems remains a significant barrier, including software licensing, data migration, and extensive staff training.
Strategic Opportunities
- Population Health Management:A significant opportunity exists in developing models for public health surveillance and managing chronic disease across large populations. This extends beyond individual patient care to serve government health agencies and large insurers.
- Asia-Pacific Healthcare Digitization:Rapid healthcare infrastructure development in countries like India and South Korea presents new markets. Providers are leapfrogging legacy systems, creating demand for modern, cloud-native analytics platforms.
- Federated Learning Models:This machine learning approach allows models to be trained across decentralized data sources without exchanging raw patient data, providing a pathway to overcome data privacy and sovereignty issues imposed by GDPR.
Industry Challenges
- Data Science Talent Scarcity:A persistent shortage of data scientists with specific healthcare domain expertise creates a bottleneck for vendors and providers. This challenge slows down custom model development and the assembly of in-house analytics teams.
- Legacy System Integration:The complexity of integrating new analytics platforms with decades-old hospital information systems and EHRs is a major operational hurdle. This often leads to lengthy, costly, and high-risk implementation cycles.
- Algorithmic Bias Mitigation:Ensuring models are equitable and do not perpetuate existing health disparities across demographic groups is a critical challenge. It requires sophisticated validation techniques and careful dataset curation to avoid biased predictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Predictive Analytics Market |
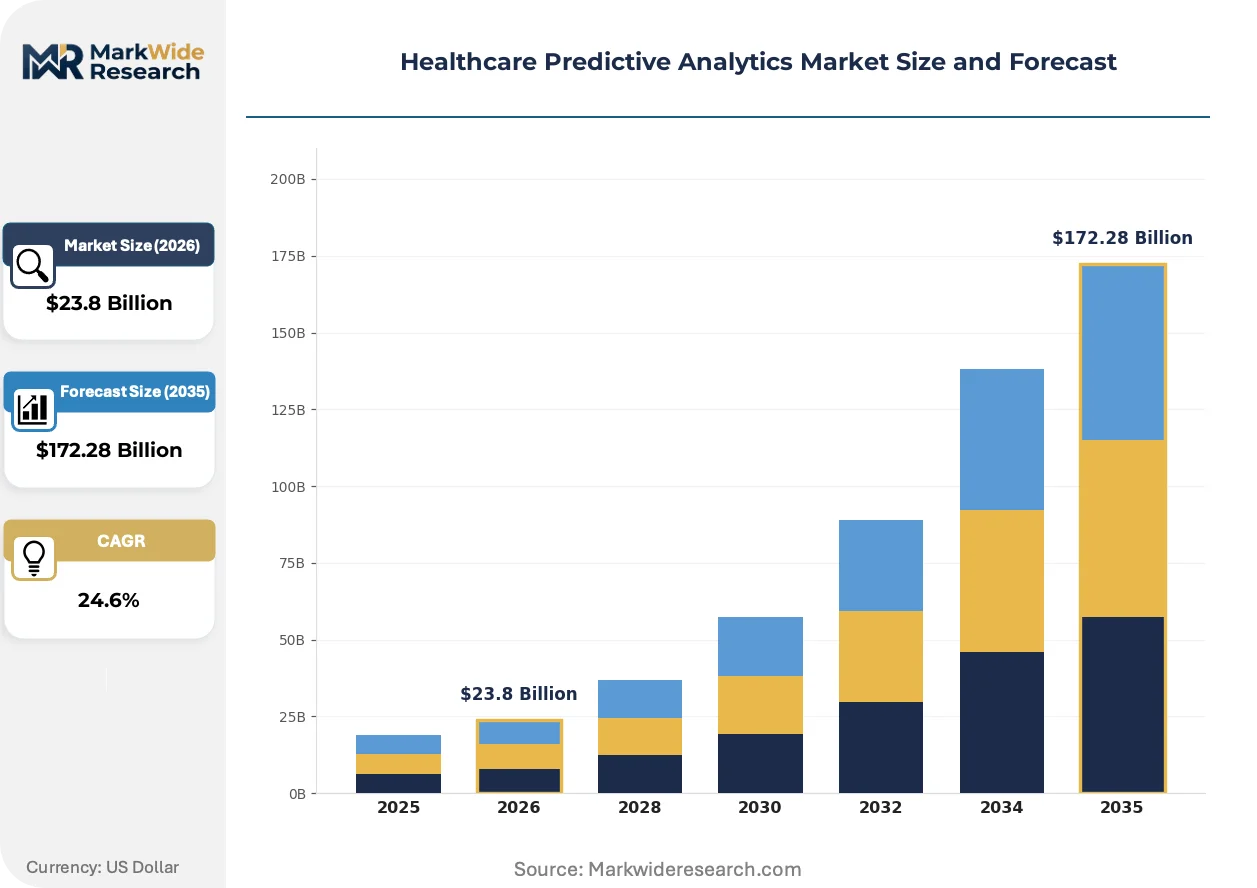
| Market Size in 2026 | $23.8 Billion |
| Market Size in 2035 | $172.28 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Platform, Solution, Service End User: Hospitals, Clinics, Insurance Companies, Research Organizations Deployment: Cloud, On-Premises, Hybrid, SaaS Application: Patient Management, Risk Assessment, Revenue Cycle Management, Clinical Decision Support |
| Companies Covered | IBM, Cerner Corporation, Oracle, SAS Institute, Allscripts (Veradigm), McKesson Corporation, Optum, Verisk Analytics, Health Catalyst, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Predictive Analytics Market Strategic Shifts & Innovations
The field is shifting from broad statistical forecasting toward embedded, AI-driven intelligence for specific clinical and operational tasks. This evolution prioritizes real-time decision support and workflow automation, demanding greater model specificity and deeper integration into existing hospital systems.
Generative AI and Large Language Models (LLMs) provide new capabilities for processing unstructured clinical data. Hospital systems are adopting these tools to automate the summarization of physician notes and draft patient correspondence. The rapid emergence of these functionalities is consolidating the market from numerous point solutions into fewer, more powerful multimodal AI platforms that handle diverse data types.
Development of the EU AI Act creates a risk-based framework for artificial intelligence systems used in critical sectors like healthcare. This regulation classifies many predictive clinical decision support tools as high-risk, requiring stringent conformity assessments and post-market surveillance. Software-as-a-medical-device (SaMD) vendors are now embedding algorithmic accountability and data governance directly into their development cycles to meet these new European Union requirements.
Buyers are shifting from acquiring large, monolithic platforms to procuring specific predictive models through API-driven marketplaces. This disintermediates traditional enterprise software vendors, creating space for specialized algorithm developers to compete on model performance. This procurement pattern is most evident in the United States, particularly within large academic medical centers that possess the technical teams to integrate these best-of-breed API solutions.
Healthcare Predictive Analytics Market Segmentation
Understanding the distinct segmentation of the healthcare predictive analytics market is crucial for identifying targeted growth opportunities and tailoring solutions to specific industry needs. The market's complexity demands precise categorization across various dimensions to address the varied requirements of providers, payers, and research entities.
Product Type:
The upgrade and replacement cycles for healthcare predictive analytics are significantly influenced by the underlying product type, dictating investment patterns across the ecosystem.
- Software:This refers to standalone programs or modules designed for specific analytical tasks, often integrated into existing IT infrastructure. Demand concentrates in hospital systems seeking to enhance specific departmental functions, driven by the need for customized analytical capabilities.
- Service:This encompasses managed analytical offerings, including data processing, model development, and expert consultation provided by third parties. Procurement patterns are shifting towards service models for specialized clinics and research organizations, driven by a scarcity of in-house data science talent.
- Platform:These are comprehensive, integrated environments that provide tools for data ingestion, model building, and deployment across various healthcare applications.
- Solution:Packaged offerings combine software, services, and sometimes hardware, tailored to address specific healthcare challenges like chronic disease management.
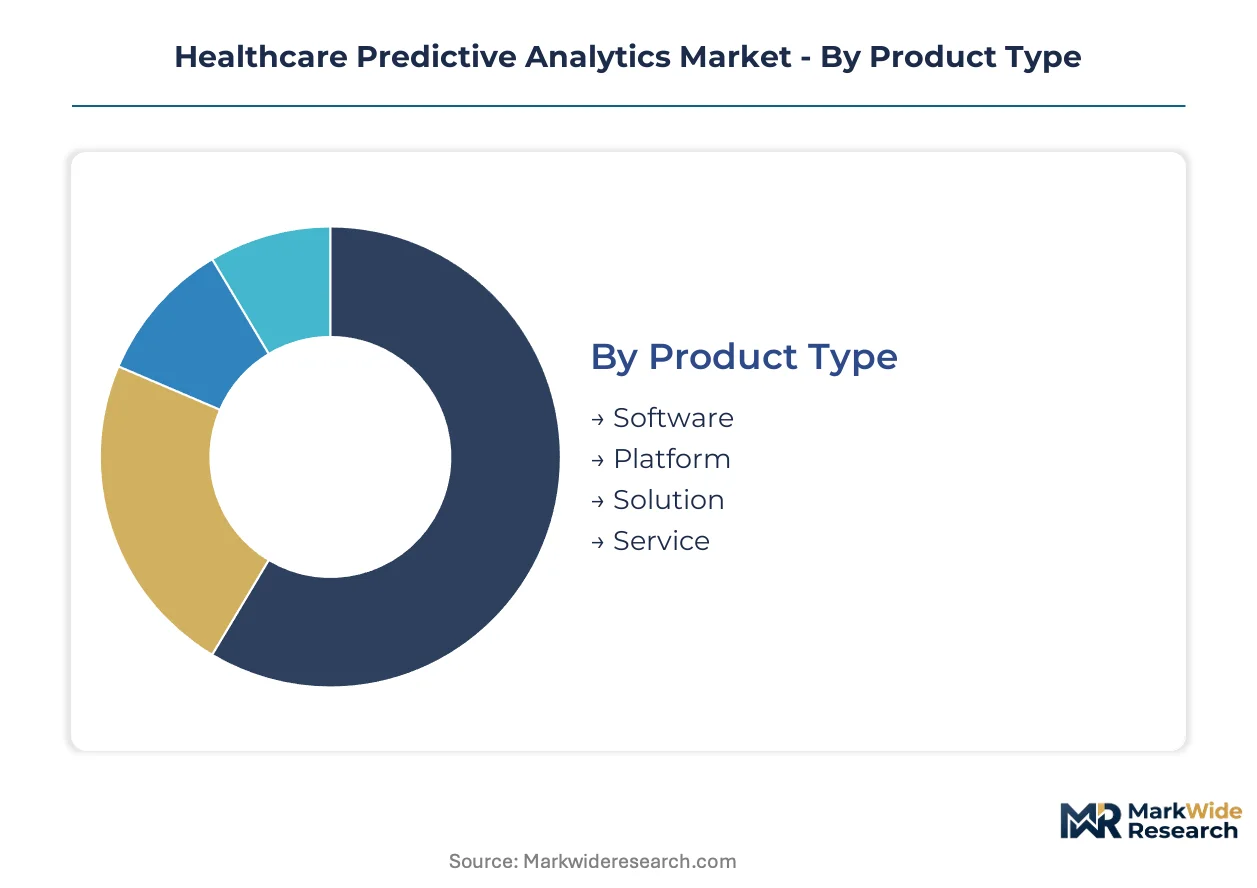
Software sits at the top of the volume ranking, with Service climbing the fastest.
End User:
End-user segments exhibit distinct application priorities, influencing the feature sets and integration requirements for predictive analytics solutions.
- Hospitals:These large medical institutions require robust, scalable predictive analytics for patient management, operational efficiency, and clinical decision support. Demand is concentrating in large academic medical centers, driven by complex patient populations and extensive data volumes.
- Insurance Companies:Payers leverage predictive analytics for risk assessment, fraud detection, and population health management, utilizing vast claims datasets. Procurement patterns for insurers prioritize models that integrate seamlessly with existing claims processing and actuarial systems.
- Clinics:Smaller healthcare facilities adopt analytics for patient scheduling, resource optimization, and basic risk stratification, often through cloud-based SaaS models.
- Research Organizations:These entities utilize advanced analytics for genomic studies, drug discovery, and clinical trial optimization, demanding high-performance computing capabilities.
Hospitals represent the largest consumer base, while insurance companies are rapidly expanding their analytical capabilities.
Deployment:
The choice of deployment model directly impacts the initial capital outlay and long-term operational scalability for healthcare providers.
- Cloud:Cloud-based deployments offer superior scalability, lower upfront capital expenditure, and flexible access to analytical tools via internet infrastructure. Demand is concentrating in specialized clinics and new healthcare entrants, driven by the need for cost-effective, agile solutions.
- SaaS:Software-as-a-Service models provide fully managed predictive analytics applications accessible via subscription, eliminating the need for local infrastructure management. Procurement is shifting towards SaaS for smaller organizations and those seeking rapid implementation with minimal IT overhead.
- On-Premises:Traditional deployments involve installing and managing software and hardware within the healthcare organization's own data centers for maximum data control.
- Hybrid:This model combines elements of both on-premises and cloud deployments, allowing sensitive data to remain local while leveraging cloud resources for scalable processing.
Cloud deployments are gaining significant traction, displacing traditional on-premises installations due to their inherent flexibility.
Application:
Each application area addresses distinct strategic imperatives for healthcare entities, from improving patient outcomes to optimizing financial performance.
- Clinical Decision Support:These applications provide real-time, evidence-based recommendations to clinicians at the point of care, improving diagnostic accuracy and treatment efficacy. Demand is concentrating in large medical centers and specialized clinics, driven by the integration of advanced AI platforms.
- Patient Management:This category includes tools for patient scheduling, resource allocation, and care pathway optimization, enhancing operational efficiency within hospital systems. Procurement patterns are shifting towards solutions that integrate deeply with existing electronic health record systems to streamline workflows.
- Risk Assessment:These models identify patients at high risk for specific conditions, readmissions, or adverse events, enabling proactive interventions and personalized care plans.
- Revenue Cycle Management:Analytics optimizes billing, claims processing, and denial management, improving financial performance and reducing administrative burdens for providers.
Clinical Decision Support and Patient Management represent the fastest-growing areas, driven by provider needs for enhanced efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States leads in the adoption of predictive analytics due to value-based care mandates, while European nations like Germany focus on stringent data governance. These differing approaches shape regional market development. Asia-Pacific countries, including India and Japan, are rapidly digitizing their healthcare infrastructure.
United States
The United States drives demand for advanced predictive analytics through its focus on value-based care and operational efficiency in hospital systems. HIPAA regulations govern data privacy, influencing model development and deployment strategies. Major technology hubs like Silicon Valley and Boston concentrate research and development in AI for healthcare applications.
Germany
German healthcare providers seek predictive models for clinical decision support and hospital process optimization. GDPR and the developing EU AI Act impose strict requirements for data privacy and algorithmic transparency. Innovation clusters in Munich and Berlin foster collaborations between AI startups and established medical institutions.
India
India presents significant opportunities for population health management and chronic disease prediction. The National Digital Health Mission aims to standardize health data, supporting analytics adoption. Technology centers like Bengaluru and Hyderabad are becoming hubs for cloud-native healthcare AI solutions.
Japan
Japanese demand concentrates on predictive tools for managing its aging population and advancing precision medicine initiatives. The PMDA regulates medical devices, including AI-driven diagnostics, ensuring safety and efficacy. Research institutions in Tokyo and Osaka are pioneering genomic data integration into predictive models.
United Kingdom
The United Kingdom prioritizes predictive analytics for enhancing NHS efficiency and public health surveillance. UK GDPR and the NHS data strategy guide secure data utilization for analytical purposes. London and Cambridge serve as key centers for health tech innovation and AI development.
Healthcare Predictive Analytics Market Key Industry Players
United States producers anchor one tier, offering broad platforms and services, while European specialists hold niche positions in explainable AI. The market exhibits a tiered structure, with large technology conglomerates alongside specialized health data providers. Strategic archetypes include enterprise software vendors, data-as-a-service providers, and AI-first clinical decision support developers. Companies engage in strategic partnerships to integrate diverse data sources and expand geographic reach.
Among the established technology giants, IBM exemplifies a provider of advanced AI platforms for complex clinical decision support, leveraging its deep research capabilities for large medical centers. Optum, a United States-based entity, represents a major player in risk assessment models for insurance companies, underpinned by its vast claims data. Health Catalyst, also based in the United States, occupies a position as a data-as-a-service specialist, tailoring offerings for regional hospital networks with its focused analytical solutions and integration expertise.
| Leading Market Players |
|---|
| IBM |
| Cerner Corporation |
| Oracle |
| SAS Institute |
| Allscripts (Veradigm) |
| McKesson Corporation |
| Optum |
| Verisk Analytics |
| Health Catalyst |
| Others |
Cost & Logistics Intelligence
Data science talent scarcity, particularly in high-cost regions like the United States, drives significant labor-cost differentials which directly influence pricing-tier spreads for complex predictive analytics solutions. These specialized skills are critical for model development and implementation.
Pricing Analysis
Capacity additions in cloud infrastructure are reshaping price floors for analytics deployments, favoring scalable, subscription-based models. Customization level and integration complexity are key price differentiation drivers. Pricing softness reflects the emergence of API-driven marketplaces, allowing buyers to procure specific models. Large academic medical centers with in-house technical teams are less price-sensitive, while specialized clinics prioritize cost-effective SaaS solutions.
Supply Chain Analysis
Single-source vulnerability sits with access to high-quality, diverse health datasets, which are often siloed within specific hospital systems or payer networks. Key geographic supply points for advanced AI development include the United States, Germany, and India. Raw material dependencies include electronic health records, claims data, and genomic information. Data interoperability barriers pose a structural risk. Distribution channels primarily involve direct sales to large healthcare organizations and cloud-based SaaS platforms for smaller entities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market for healthcare predictive analytics presents a geographic-arbitrage opportunity, driven by differing regulatory frameworks for data privacy and AI accountability between the United States and the European Union. These regional variances influence development costs and market access strategies.
For Market Incumbents: Cement existing relationships with large hospital systems by deepening integration capabilities for electronic health records. Acquire specialized algorithm developers to expand proprietary model libraries, mitigating the threat from API-driven marketplaces. Invest in advanced data governance frameworks to navigate evolving EU AI Act requirements, leveraging existing scale. This strategy reinforces market leadership against emerging point solutions.
For New Entrants and Emerging Players: Federated learning models offer a technology-first wedge into data-sensitive markets, enabling model training without direct data exchange. Target specialized clinics and research organizations seeking cloud-native analytics platforms with minimal IT overhead. A go-to-market angle focusing on specific clinical decision support tasks provides rapid demonstrable value. This approach bypasses traditional data interoperability barriers.
For Investors and Strategic Acquirers: Large technology conglomerates are the most active acquirer in this space, seeking to integrate healthcare AI capabilities into broader enterprise platforms. Long-term viability hinges on continued digitization of healthcare infrastructure and the shift towards value-based care models. Acquisition targets should include data-as-a-service providers and innovative AI startups specializing in genomic data integration. Regulatory clarity surrounding algorithmic accountability is a critical signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Integrating predictive models into existing EHR systems streamlines clinical workflows for hospital staff. |
| Strategic Partnership | Collaborating with large payers provides access to vast claims data for robust risk assessment model development. |
| Acquisition of Specialist Firm | Acquiring niche AI companies accelerates expertise in areas like genomic data analysis for precision medicine. |
| Geographic Expansion | Entering Asia-Pacific markets leverages rapid healthcare digitization and demand for cloud-native analytics. |
| Regulatory Approval Pathway | Navigating the EU AI Act for high-risk models ensures market access and builds trust in AI-driven diagnostics. |
Research Approach
Bottom-up patient management modeling reconciled against top-down platform provider tracking forms the analytical core. This approach combined extensive primary interviews with CIOs, Chief Medical Officers, and health system administrators. Secondary validation involved reviewing EHR vendor reports, claims data aggregators, and government health agency publications. This triangulation ensures comprehensive market understanding.
Historical trendline analysis established baseline growth trajectories for market segments across the analysis window. The analytical framework incorporated regression models and scenario planning to project future demand. Segmentation dimensions modeled included product type, end user, deployment model, application, and regional adoption patterns. Compound annual growth rates were derived from observed historical growth, technology adoption curves, and key industry-specific forecast inputs like EHR adoption rates and value-based care mandate penetration.
The model holds under stable regulatory conditions and consistent technological advancement; deviation in data privacy enforcement or healthcare funding models would shift projected outcomes. Forecasts reflect assumptions documented through extensive research. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Data Management
Americas Healthcare Archiving and Ediscovery Market
Health Data Management
Population Health Management (PHM) Market
Health Data Management
US Population Health Management Market
Health Data Management
Hospital Management Software Market
Health Data Management
Healthcare Archiving and Ediscovery Market
Health Data Management
Europe Healthcare Analytics Market
Health Data Management
Asia Pacific Healthcare Archiving and Ediscovery Market
Health Data Management
Point of Care (POC) Data Management Systems Market
Health Data Management
Healthcare Data Integration Market
Health Data Management
Global Healthcare Quality Management Market
Health Data Management
Global Healthcare Fraud Analytics Market
Health Data Management
US Mobile Health Market
Health Data Management
Global Healthcare Data Storage Market
Health Data Management
Patient Data Management Systems Market
Health Data Management
Patient Data Management Software Market
Health Data Management
North America Clinical Data Analytics in Healthcare Market