
 AI Training Dataset in Healthcare Market | 2026-2036
AI Training Dataset in Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
AI Training Dataset in Healthcare Market Analytics
The EU AI Act is pivoting how healthcare AI developers source and validate training data across European markets. Google, LLC leverages its cloud infrastructure to host de-identified hospital datasets at scale. Microsoft Corporation anchors enterprise partnerships through Azure Health Data Services integration with major health systems. Scale AI, Inc. specializes in human-in-the-loop annotation workflows for radiology and pathology imaging.
AI training datasets in healthcare comprise curated, labeled collections of clinical, imaging, genomic, and textual medical information formatted for machine learning model development, with strict requirements for de-identification, interoperability standards such as FHIR, and bias mitigation protocols. These datasets enable algorithmic diagnostics, predictive risk stratification, and automated treatment recommendations across care settings. Imaging data commands premium valuation due to the labor intensity of radiologist-led annotation and regulatory scrutiny of computer-aided detection systems. Text data from electronic health records is expanding fastest as natural language processing models extract structured insights from unstructured clinician notes. Genomic data occupies a concentrated margin pool where specialized bioinformatics expertise creates vendor scarcity.
The FDA, HIPAA privacy frameworks, and the EU AI Act collectively govern data provenance, patient consent documentation, and algorithmic transparency requirements for healthcare AI training datasets. Compliance costs are rising as regulators mandate prospective validation cohorts and demographic performance equity assessments. Stakeholders must monitor evolving cross-border data transfer restrictions and emerging liability standards for model drift in deployed clinical environments.
Market Dynamics
The FDA's prospective validation mandates for AI/ML-based medical devices are compressing development timelines while elevating data provenance requirements across pharmaceutical and diagnostic pipelines.
Growth Catalysts
- FHIR interoperability standards:The Fast Healthcare Interoperability Resources framework is accelerating dataset exchange between health systems and AI developers, reducing integration friction for multi-site training cohorts.
- Pharmaceutical drug discovery pipelines:Labeled clinical datasets are compressing target identification cycles, with biopharma R&D organizations prioritizing structured genomic and phenotypic data for predictive modeling.
- United States health system centralization:Major academic medical centers are consolidating de-identified imaging and EHR repositories, creating concentrated supply nodes for radiology and pathology AI training.
Market Restraints
- HIPAA de-identification costs:Expert determination protocols and Safe Harbor compliance are adding fixed cost layers to dataset preparation, particularly for free-text clinical notes requiring sophisticated natural language processing pipelines.
- Radiologist annotation bottlenecks:The labor intensity of imaging segmentation is creating supply constraints for computer-aided detection system developers, with specialized pathologist and radiologist time commanding premium rates.
- EU AI Act data provenance requirements:Conformity assessment obligations for high-risk medical AI are extending validation timelines and requiring documented consent chains that many legacy datasets lack.
Strategic Opportunities
- Synthetic data generation:Generative adversarial networks and diffusion models are creating privacy-preserving training alternatives that bypass HIPAA constraints for rare disease and pediatric populations.
- India's clinical data ecosystem:The country's digitized hospital networks and English-language medical records are attracting annotation investment for global NLP model development.
- Federated learning architectures:Distributed training across institutional boundaries is enabling multi-site collaboration without centralized data pooling, addressing cross-border transfer restrictions under GDPR and emerging national data localization laws.
Industry Challenges
- Bioinformatics talent scarcity:The specialized skill set spanning genomic analysis, machine learning, and clinical domain knowledge is concentrating at a handful of academic centers and specialized vendors.
- Demographic performance equity validation:FDA guidance on algorithmic bias assessment is requiring expanded prospective cohorts that span age, race, and comorbidity distributions, extending study timelines.
- Model drift liability frameworks:Unclear standards for post-deployment monitoring and recertification are creating legal exposure for health systems deploying diagnostic AI trained on historical datasets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI Training Dataset in Healthcare Market |
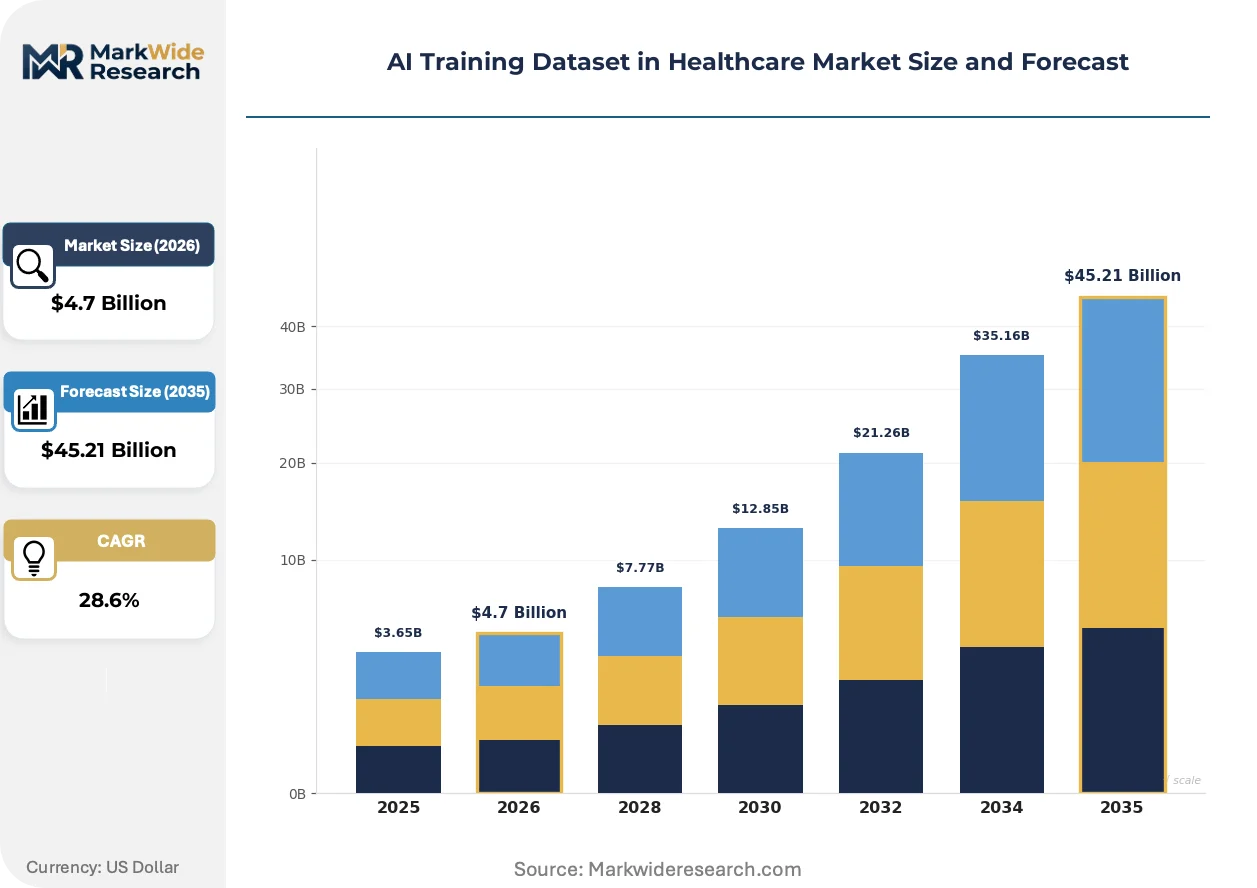
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $45.21 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Dataset Type: Clinical Data, Imaging Data, Genomic Data, Text Data Application Area: Diagnostics, Treatment Planning, Patient Monitoring, Research Data Source: Electronic Health Records, Medical Imaging, Wearable Devices, Surveys End User: Hospitals, Research Institutions, Pharmaceutical Companies, AI Developers |
| Companies Covered | Amazon Web Services, Inc., Appen Limited, Google, LLC, Microsoft Corporation, Scale AI, Inc., Alegion, Lionbridge Technologies, Inc., Cogito Tech LLC, Shaip, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI Training Dataset in Healthcare Market Evolving Landscape
Multimodal dataset fusion is compressing the boundary between imaging, genomic, and clinical text sources, enabling predictive models that integrate previously siloed patient information streams.
Synthetic data generation platforms are integrating differential privacy mechanisms to produce statistically equivalent training cohorts without exposing individual patient records. Pharmaceutical companies and diagnostic developers are adopting these tools for rare disease modeling where real-world data scarcity previously blocked algorithm development. The technology is integrating regulatory-grade audit trails that satisfy FDA documentation requirements for training data provenance.
The EU AI Act's high-risk system classification is mandating conformity assessments for diagnostic algorithms before market placement, with notified body involvement extending certification timelines. Developers are restructuring quality management systems to address risk management, post-market monitoring, and human oversight requirements. Imaging-based computer-aided detection systems face the most stringent documentation burdens, with manufacturers building prospective validation cohorts specifically for European market access.
Hospital procurement committees are consolidating vendor relationships around integrated data platform providers rather than point-solution annotation services. Health systems in the United States are prioritizing long-term data partnership contracts that bundle cloud infrastructure, de-identification pipelines, and continuous labeling services. This consolidation favors vendors with captive cloud capacity and established HIPAA business associate agreements, compressing opportunities for standalone annotation boutiques.
AI Training Dataset in Healthcare Market Segmentation
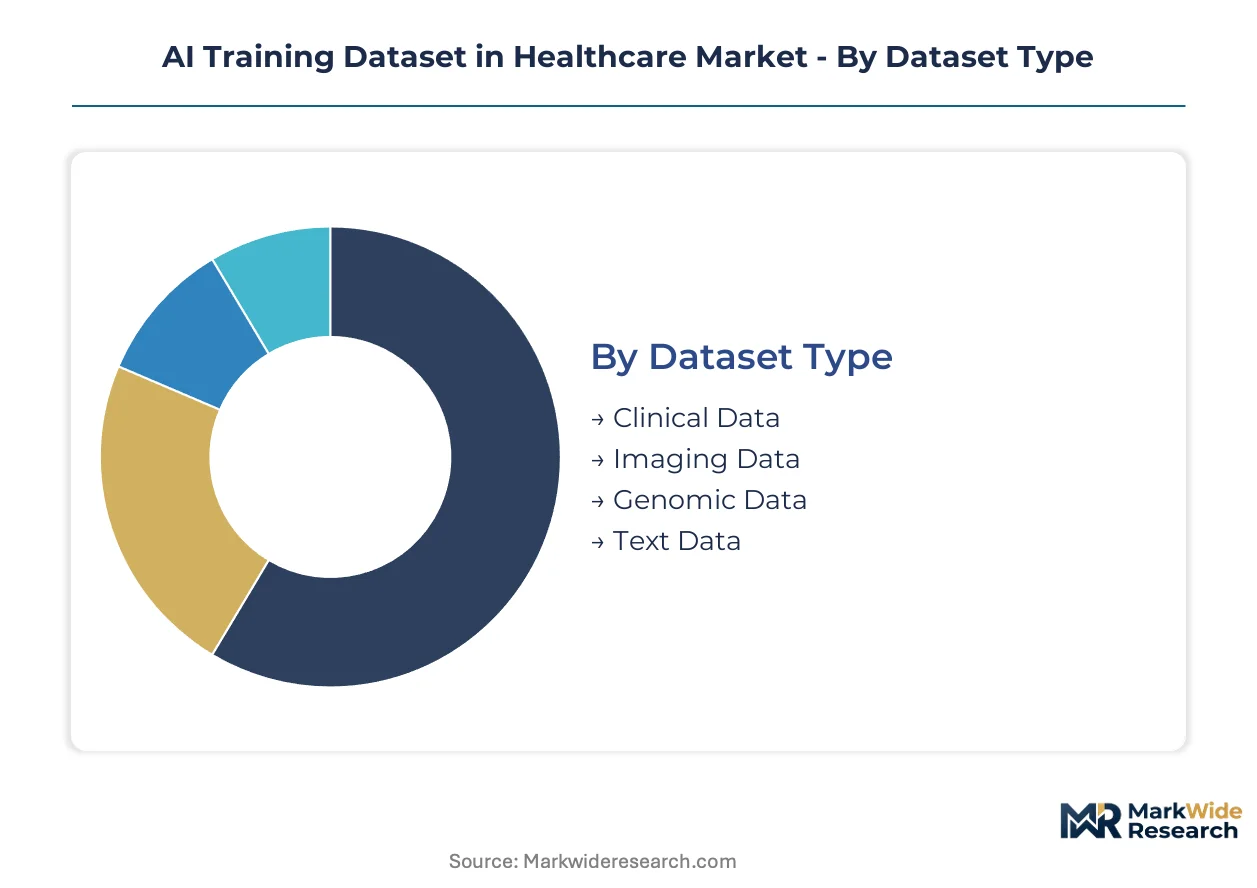
Segmentation of AI training datasets reveals how supply constraints and regulatory requirements concentrate value across distinct data modalities and customer workflows. Understanding these divisions exposes where annotation bottlenecks, compliance costs, and platform consolidation reshape competitive positioning.
Dataset Type:
Supply concentration in annotation labor and specialized infrastructure drives tiered pricing and vendor scarcity across data modalities.
- Clinical Data:Structured patient records, laboratory values, and medication histories formatted for predictive modeling and cohort identification. Pharmaceutical companies in the United States anchor demand for longitudinal clinical datasets that compress target validation timelines in drug discovery pipelines.
- Imaging Data:Radiological and pathological images requiring pixel-level segmentation by board-certified specialists. The labor intensity of radiologist-led annotation creates supply constraints that elevate pricing for computer-aided detection system developers facing FDA scrutiny.
- Genomic Data:Sequencing outputs and variant annotations demanding bioinformatics expertise.
- Text Data:Unstructured clinical notes and discharge summaries processed through natural language extraction pipelines.
Imaging data absorbs the bulk of installed capacity; text data is expanding most quickly.
Application Area:
Cost tier differentiation separates high-stakes diagnostic deployments from lower-complexity research applications.
- Diagnostics:Algorithmic detection and classification systems deployed in clinical decision support. FDA validation mandates for AI/ML-based medical devices elevate data provenance requirements and extend development timelines for radiology and pathology applications.
- Treatment Planning:Personalized therapeutic recommendations derived from multimodal patient profiles. Academic medical centers in the United States concentrate demand for integrated datasets spanning imaging, genomic, and clinical text sources.
- Patient Monitoring:Continuous risk stratification from wearable and bedside sensor streams.
- Research:Exploratory model development without immediate clinical deployment obligations.
Diagnostics commands premium pricing; research volumes are climbing the fastest as synthetic data tools mature.
Data Source:
Volume concentration in electronic health records is displacing traditional survey-based collection as health systems digitize.
- Electronic Health Records:Comprehensive longitudinal patient histories from integrated health system databases. FHIR interoperability standards are accelerating multi-site dataset exchange between United States academic medical centers and AI developers.
- Medical Imaging:DICOM-standard radiology and pathology archives from hospital picture archiving systems. Centralized repositories at major United States health systems create concentrated supply nodes for computer-aided detection training.
- Wearable Devices:Consumer and clinical-grade biometric streams from continuous monitoring hardware.
- Surveys:Structured patient-reported outcome instruments and epidemiological questionnaires.
Electronic health records absorb the bulk of installed capacity; wearable devices are gaining share fastest as ambulatory monitoring expands.
End User:
Customer type determines procurement complexity, with hospital systems bundling long-term data partnerships versus transactional research licensing.
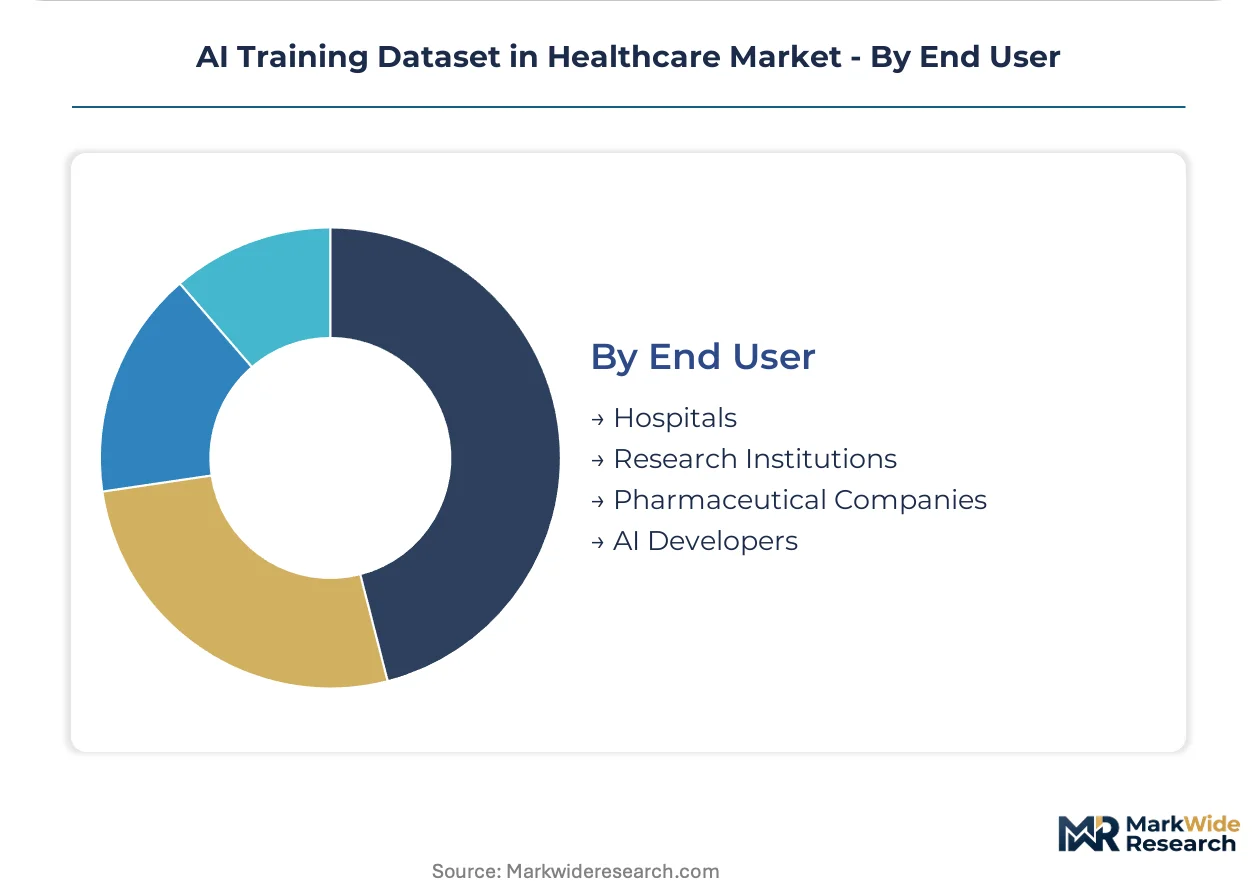
- Hospitals:Integrated health systems deploying diagnostic AI and building internal algorithm development capabilities. Procurement committees in the United States are consolidating vendor relationships around cloud-integrated platform providers with established HIPAA business associate agreements.
- Research Institutions:Academic centers generating and annotating novel datasets for publication and commercialization. Federated learning architectures enable multi-site collaboration without centralized data pooling, addressing cross-border transfer restrictions.
- Pharmaceutical Companies:Biopharma R&D organizations sourcing labeled datasets for target identification and clinical trial optimization.
- AI Developers:Specialized algorithm vendors without captive data generation infrastructure.
Hospitals absorb the bulk of installed capacity; pharmaceutical companies are expanding most quickly as drug discovery pipelines accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's academic medical corridor anchors North American demand for de-identified clinical datasets, with Massachusetts General Hospital and Brigham and Women's Hospital operating centralized imaging repositories that supply radiology AI developers.
United States
FDA prospective validation mandates for AI/ML-based medical devices are tightening data provenance requirements across pharmaceutical and diagnostic pipelines. HIPAA Safe Harbor de-identification protocols add fixed cost layers to dataset preparation, particularly for free-text clinical notes. The Research Triangle Park in North Carolina concentrates bioinformatics talent pools where specialized vendors annotate genomic sequencing outputs.
Germany
The EU AI Act's high-risk system classification is mandating conformity assessments for diagnostic algorithms before European market placement. EMA guidance on algorithmic transparency is extending validation timelines for computer-aided detection systems. Berlin's Charité hospital network is building federated learning infrastructure that enables multi-site collaboration without centralized data pooling under GDPR constraints.
United Kingdom
NHS Digital's consolidation of electronic health records is creating concentrated supply nodes for natural language processing model development. MHRA post-market surveillance requirements are elevating documentation burdens for training data provenance. London's King's College Hospital operates one of Europe's largest de-identified radiology archives for computer-aided detection training.
India
Digitized hospital networks and English-language medical records are attracting annotation investment for global NLP model development. CDSCO emerging guidance on AI-based medical devices is creating compliance frameworks that mirror FDA structures. Hyderabad's Health City cluster concentrates medical transcription and clinical coding services that feed structured dataset pipelines.
China
NMPA regulatory pathways for AI medical devices are accelerating domestic algorithm development while restricting cross-border data transfers under cybersecurity law. National health system digitization is generating imaging volumes that rival United States repositories. Shanghai's Ruijin Hospital operates a centralized picture archiving system supplying computer-aided detection developers.
AI Training Dataset in Healthcare Market Competitive Landscape
Premium-margin players sit above commodity-margin players across annotation labor intensity and regulatory certification depth. Cloud hyperscalers with captive infrastructure dominate hospital procurement committees, while specialized annotation boutiques compete on radiologist-led segmentation quality. Three archetypes define positioning: infrastructure-integrated platforms, human-in-the-loop specialists, and synthetic data generators. Strategic moves concentrate on long-term data partnership contracts and federated learning architecture deployment.
Within the infrastructure-integrated tier, Google, LLC and Microsoft Corporation anchor enterprise positioning through cloud-native health data services. Scale AI, Inc. exemplifies the human-in-the-loop specialist archetype, occupying a position focused on radiology and pathology imaging workflows where board-certified annotation commands premium rates.
| Leading Market Players |
|---|
| Amazon Web Services, Inc. |
| Appen Limited |
| Google, LLC |
| Microsoft Corporation |
| Scale AI, Inc. |
| Alegion |
| Lionbridge Technologies, Inc. |
| Cogito Tech LLC |
| Shaip |
| Others |
Value Network & Pricing Analysis
Synthetic data generation platforms are compressing cost economics for rare disease and pediatric cohorts while simultaneously concentrating supply among vendors with differential privacy engineering capabilities and FDA-grade audit infrastructure. This technology transition is elevating pricing power for synthetic data providers while eroding margins for traditional annotation boutiques dependent on radiologist labor pools.
Pricing Analysis
Value-based pricing anchored to diagnostic accuracy outcomes dominates diagnostics applications, with FDA-cleared computer-aided detection systems commanding premium rates against research-grade datasets. Price differentiation hinges on certification tier (FDA 510(k) pathway versus CE marking under EU AI Act) and annotation depth (pixel-level segmentation versus bounding-box labeling). Cost compression in text data annotation is intensifying because natural language processing pipelines automate extraction from unstructured clinical notes. Pharmaceutical companies exhibit lowest price sensitivity due to drug discovery timeline pressures, while standalone AI developers face acute budget constraints.
Supply Chain Analysis
Direct-to-hospital channels handle hyperscale demand from United States academic medical centers consolidating vendor relationships around cloud-integrated platform providers. Geographic supply concentrates in the United States, India, and Germany, with United States health systems anchoring imaging repository capacity, India feeding English-language medical transcription pipelines, and Germany building federated learning infrastructure under GDPR constraints. Raw material dependencies span de-identified patient records, board-certified specialist annotation hours, and bioinformatics processing compute. Single-source vulnerability in radiologist-led segmentation creates supply risk for computer-aided detection developers. Distribution runs through long-term data partnership contracts bundling cloud infrastructure, de-identification pipelines, and continuous labeling services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Radiologist annotation bottlenecks prop pricing power for human-in-the-loop specialists, while synthetic data generators capture margin expansion in privacy-constrained segments. Supply scarcity in bioinformatics talent further concentrates value among vendors with captive genomic analysis capabilities.
For Market Incumbents: Cement cloud infrastructure dominance by deepening HIPAA business associate agreement coverage across United States health systems and accelerating federated learning architecture deployment to address cross-border transfer restrictions. Synthetic data generators threaten traditional annotation revenue pools; defend by acquiring differential privacy engineering capabilities and integrating regulatory-grade audit trails that satisfy FDA documentation requirements. For New Entrants and Emerging Players: The mid-tier pricing gap between premium radiologist-led segmentation and economy-grade automated annotation creates white-space opportunity in pathology imaging workflows where board-certified specialist time commands less premium than radiology. Target India's digitized hospital networks for English-language medical record annotation serving global NLP model development. Pursue hospital system partnerships in secondary United States markets where procurement committees lack captive cloud capacity. For Investors and Strategic Acquirers: Exit pathways concentrate in infrastructure-integrated platform acquisitions by cloud hyperscalers seeking captive health data services and synthetic data generator roll-ups by pharmaceutical companies building internal rare disease modeling capabilities. Long-term viability favors vendors with multi-modal dataset fusion capabilities spanning imaging, genomic, and clinical text sources. Watch FDA guidance evolution on algorithmic bias assessment as inflection indicator for expanded prospective validation cohort requirements.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Regulatory clearance unlocks diagnostic AI reimbursement and hospital procurement eligibility under United States coverage frameworks. |
| EU AI Act Conformity Assessment | Notified body involvement extends certification timelines but enables European market access for high-risk medical AI systems. |
| Hospital System Data Partnership | Long-term contracts bundle cloud infrastructure, de-identification pipelines, and continuous labeling services, compressing standalone annotation vendor opportunities. |
| Federated Learning Architecture Deployment | Distributed training across institutional boundaries addresses GDPR cross-border transfer restrictions and emerging national data localization laws. |
| Synthetic Data Platform Integration | Generative models with differential privacy mechanisms bypass HIPAA constraints for rare disease populations while satisfying FDA provenance documentation. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with hospital procurement managers, biomedical engineers, GPO contracts managers, and regulatory affairs leads at AI diagnostic developers. FDA 510(k) clearance databases, EMA submission records, hospital procurement databases, and CMS Medicare claims data provided quantitative validation. Bottom-up dataset volume estimates triangulated against top-down pharmaceutical R&D spending allocations for AI-enabled drug discovery.
Data-stream reconciliation across imaging annotation volume, EHR text extraction throughput, and genomic sequencing output anchored the analytical framework across the analysis window. Segmentation dimensions modeled include dataset type (imaging, clinical, genomic, text), application area (diagnostics, treatment planning, patient monitoring, research), data source (electronic health records, medical imaging, wearable devices), and end user (hospitals, research institutions, pharmaceutical companies, AI developers). CAGRs derived from logistic adoption curves fitted to health system digitization trajectories and regulatory validation timeline assumptions. Synthetic data penetration rates and federated learning deployment timelines served as scenario variables.
Inputs from FDA guidance documents and EU AI Act implementing acts were available through the study window; gaps in post-market surveillance performance data and model drift liability precedent introduce uncertainty bands around deployment timeline assumptions. Forecasts reflect documented assumptions regarding regulatory clarity evolution and health system procurement centralization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Data Management
Healthcare Data Monetization Solutions Market
Health Data Management
Europe Healthcare Analytics Market
Health Data Management
Europe Healthcare Big Data Analytics Market
Health Data Management
Global Healthcare Data Storage Market
Health Data Management
Clinical Trial Data Management Software Market
Health Data Management
Data Monetization in Healthcare Market
Health Data Management
Point of Care (POC) Data Management Systems Market
Health Data Management
Healthcare Data Collection and Labeling Market
Health Data Management
Wireless Healthcare Asset Management Market
Health Data Management
North America Clinical Data Analytics in Healthcare Market
Health Data Management
Master Data Management in Healthcare Market
Health Data Management
Population Health Management (PHM) Market
Health Data Management
Healthcare Data Integration Market
Health Data Management
Global Healthcare Fraud Analytics Market
Health Data Management
Healthcare Archiving and Ediscovery Market
Health Data Management
United States Healthcare Big Data Analytics Market