
 Global Healthcare Financial Analytics Market | 2026-2036
Global Healthcare Financial Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Healthcare Financial Analytics Market Foresight
Cloud-native data architectures is reconfiguring how healthcare financial analytics platforms ingest, normalize, and analyze disparate claims and clinical datasets. Optum Analytics leverages its payer-provider integration to anchor large-scale risk adjustment workflows. IQVIA sustains competitive differentiation through its real-world data infrastructure spanning multiple therapeutic areas. Health Catalyst specializes in data operating system architectures that unify financial and operational metrics for medical groups.
Healthcare financial analytics encompasses software platforms and algorithmic tools that process claims data, cost accounting records, and patient billing information to optimize revenue cycles, detect fraud, and allocate clinical resources. These systems employ statistical modeling, machine learning classifiers, and natural language processing to transform raw financial transactions into actionable intelligence for payer and provider decision-making. Revenue cycle management solutions dominate current deployment volumes as health systems prioritize accounts-receivable automation and denial prevention. Cloud-based and SaaS deployment models capture the fastest expansion trajectory by eliminating capital-intensive infrastructure commitments and enabling API-driven interoperability with electronic health records. Fraud detection applications command premium pricing due to regulatory mandates for pre-payment integrity screening and retrospective audit capabilities.
FDA oversight of clinical decision support tools, HIPAA security requirements for protected health information, and CMS value-based reimbursement rules collectively shape product development priorities and customer procurement criteria in the United States. EMA's data governance frameworks and GDPR privacy standards constrain cross-border data flows for European payer analytics deployments, necessitating region-specific infrastructure. Stakeholders must monitor evolving interoperability mandates from ONC and emerging AI transparency requirements that will determine which algorithmic platforms qualify for federal reimbursement pathways.
Market Dynamics
Cloud-native architectures are displacing legacy on-premises installations across Germany, Japan, and Australia, forcing vendors to rebuild data pipelines for API-driven interoperability with electronic health records and payer systems.
Growth Catalysts
- CMS Value-Based Reimbursement:Hospital systems in the United States deploy predictive models to reduce readmission penalties and capture quality incentive payments under federal programs.
- Automated Claims Adjudication:Health insurers accelerate procurement of revenue cycle management platforms to process high-volume transactions with machine learning classifiers.
- API-Driven Interoperability:ONC mandates for FHIR-based data exchange create procurement pull for platforms that normalize disparate claims and clinical datasets.
Market Restraints
- GDPR Cross-Border Constraints:EMA data governance frameworks and GDPR privacy standards block seamless data flows for European payer analytics deployments.
- Technical Debt Burden:Legacy COBOL-based billing systems in established health systems resist cloud migration without multimillion-dollar replacement cycles.
- Specialized Talent Scarcity:Shortage of professionals combining clinical domain knowledge with machine learning engineering constrains implementation velocity.
Strategic Opportunities
- Brazilian Private Insurance Expansion:ANVISA regulatory clarity and growing middle-class enrollment create whitespace for fraud detection and risk adjustment platforms.
- Real-World Evidence Convergence:Integration of financial analytics with clinical outcomes data opens new product categories for pharmaceutical contract negotiations.
- Pre-Payment Integrity Mandates:CMS audit expansion and state Medicaid program requirements drive demand for prospective claims screening before disbursement.
Industry Challenges
- HIPAA Technical Safeguards Implementation:Encryption and access control requirements for protected health information extend deployment timelines and certification costs.
- Legacy System Integration Complexity:Health systems running 15-20 year-old practice management software require custom middleware development for analytics connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Healthcare Financial Analytics Market |
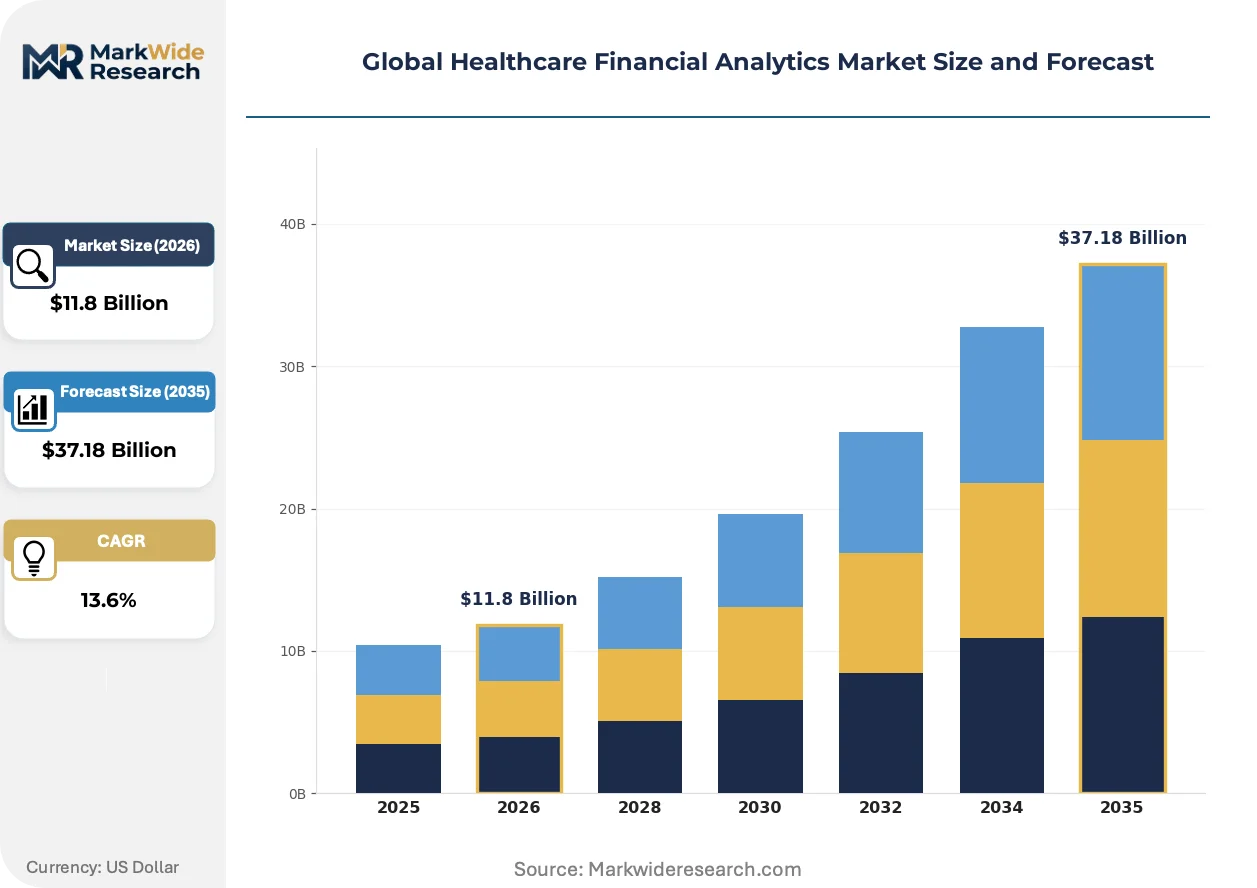
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $37.18 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Offering: Revenue Cycle Management, Cost Analytics, Risk Adjustment, Claims Management, Payment Integrity Deployment: On-Premises, Cloud-Based, Hybrid, SaaS, API Integration Application: Budgeting, Fraud Detection, Patient Billing Optimization, Financial Reporting, Resource Allocation End User: Health Insurers, Medical Groups, Pharmacy Benefit Managers, Accountable Care Organizations, Government Payers |
| Companies Covered | Innovaccer, SAS Healthcare Analytics, Health Catalyst, Prognos Health, Kodjin, Optum Analytics, IQVIA, Clearsense, MedeAnalytics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Healthcare Financial Analytics Market Shifts & Advancements
Algorithmic transparency requirements and AI audit mandates are reshaping how vendors architect explainable models for federal reimbursement qualification and clinical decision support deployment.
Natural language processing engines are digitizing unstructured clinical notes into structured billing codes and risk adjustment factors. Revenue cycle vendors athenahealth and R1 RCM deploy these tools across ambulatory networks to accelerate charge capture and reduce manual coding labor. The technology is digitizing documentation workflows that previously required specialized clinical coders.
The EU AI Act's risk classification framework imposes conformity assessment obligations on clinical decision support tools deployed in European health systems. Vendors must maintain technical documentation, human oversight protocols, and accuracy benchmarking for high-risk applications. German hospital procurement committees now require AI Act compliance certifications before contract execution.
Subscription-based SaaS pricing is displacing perpetual license models as health systems prioritize operational expenditure flexibility over capital-intensive infrastructure ownership. Large integrated delivery networks in Australia negotiate consumption-based contracts tied to claims volume processed. This shift concentrates vendor selection criteria around interoperability depth rather than upfront cost minimization.
Global Healthcare Financial Analytics Market Segmentation
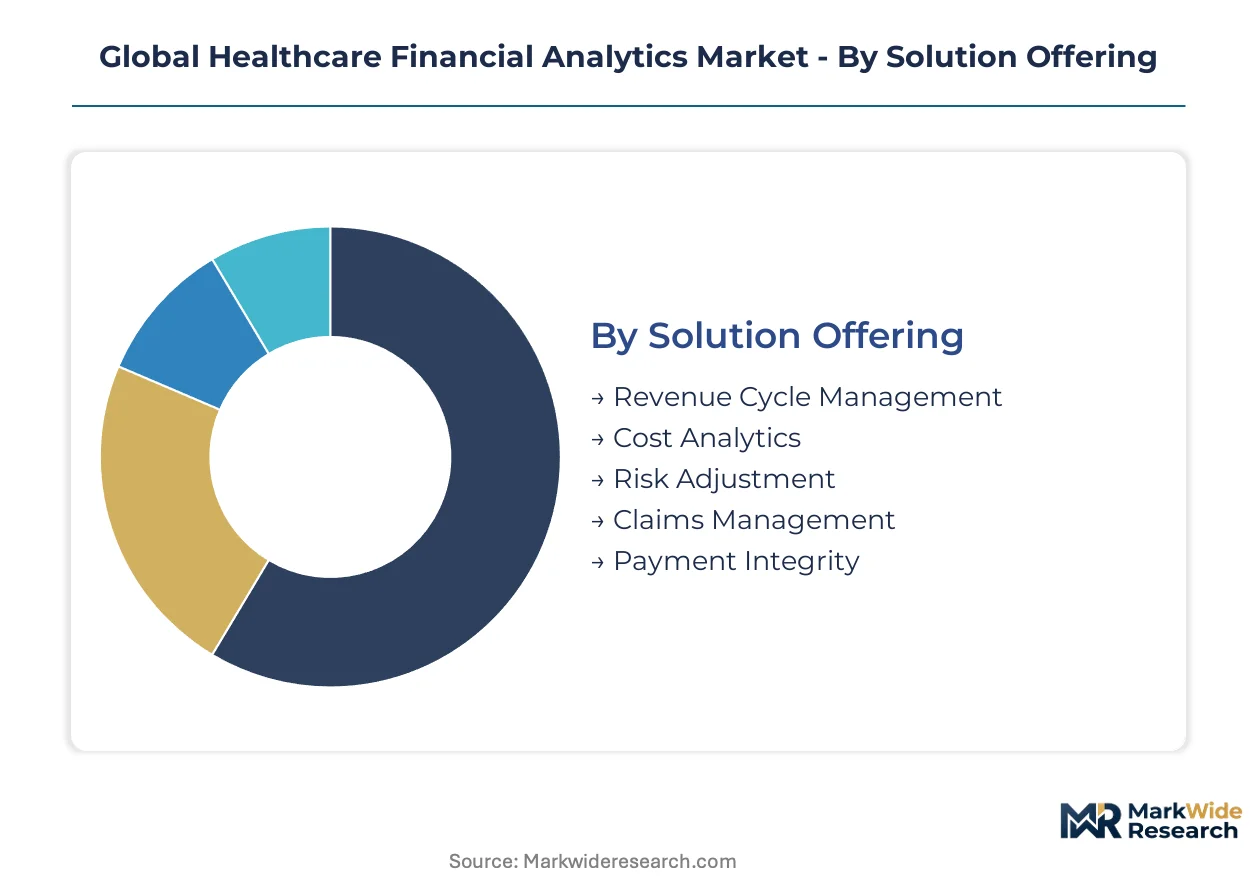
Healthcare financial analytics vendors architect product portfolios around distinct solution architectures, deployment models, and buyer workflows. Segmentation clarity determines pricing discipline, sales cycle length, and customer success resource allocation across payer and provider organizations.
Solution Offering:
After-sales service intensity varies sharply across solution types, with revenue cycle management platforms demanding continuous algorithm tuning and denial management support while cost analytics tools require periodic refresh cycles.
- Revenue Cycle Management:Platforms automate patient registration, eligibility verification, charge capture, and claims submission workflows. Hospital systems in the United States concentrate procurement here to reduce days in accounts receivable and capture CMS quality incentive payments.
- Cost Analytics:Activity-based costing engines allocate overhead across service lines and patient episodes. Medical groups in Germany deploy these tools to optimize DRG reimbursement under statutory health insurance frameworks.
- Risk Adjustment:Algorithms identify undocumented chronic conditions from claims patterns to optimize Medicare Advantage and ACA exchange payments.
- Claims Management:End-to-end platforms for intake, editing, routing, and settlement of payer-provider transactions.
- Payment Integrity:Pre-payment screening and post-payment audit modules detect fraud, waste, and abuse before disbursement.
By volume, Revenue Cycle Management leads. By growth pace, Payment Integrity is ahead.
Deployment:
Cost tier stratification separates capital-intensive on-premises installations from consumption-based SaaS contracts, with hybrid architectures occupying a mid-market position for organizations transitioning legacy infrastructure.
- On-Premises:Legacy installations in established health systems with dedicated data center operations and strict HIPAA technical safeguard requirements.
- Cloud-Based:Multi-tenant architectures hosted on AWS, Azure, or Google Cloud infrastructure with SOC 2 Type II certification. Health insurers in Australia accelerate migration here to eliminate hardware refresh cycles.
- Hybrid:Sensitive patient data remains on-premises while analytics workloads process in cloud environments. Medical groups in Japan favor this model under METI data localization guidance.
- SaaS:Subscription pricing with API-driven interoperability and automatic feature updates. Pharmacy Benefit Managers prefer consumption-based contracts tied to claims volume.
- API Integration:Embedded modules connecting directly to EHR and practice management systems via FHIR standards.
Cloud-Based deployments dominate new contract value. API Integration is climbing the fastest as ONC mandates harden interoperability requirements.
Application:
Application segmentation maps to distinct buyer personas and budget authorities, with fraud detection commanding premium pricing due to regulatory audit mandates while resource allocation tools compete on operational efficiency metrics.
- Budgeting:Forecasting and variance analysis tools for hospital finance departments. Accountable Care Organizations in the United States deploy these to manage shared savings distributions.
- Fraud Detection:Machine learning classifiers identifying anomalous billing patterns, upcoding, and phantom provider schemes. CMS audit expansion drives procurement across state Medicaid programs.
- Patient Billing Optimization:Price transparency tools and propensity-to-pay algorithms for revenue cycle teams. Medical groups use these to reduce bad debt exposure.
- Financial Reporting:Automated dashboards for executive leadership and board governance requirements.
- Resource Allocation:Optimization engines for staffing, equipment, and facility utilization decisions.
Fraud Detection captures the highest average contract value. Patient Billing Optimization is gaining share fastest as price transparency regulations tighten.
End User:
Customer type determines sales channel strategy, with health insurers demanding enterprise-scale implementations and pharmacy benefit managers seeking modular, API-first architectures.
- Health Insurers:Commercial payers and Medicare Advantage plans with complex claims adjudication volumes. United States carriers prioritize automated prior authorization and risk adjustment accuracy.
- Medical Groups:Ambulatory practices and multi-specialty clinics with limited IT resources. Cloud-native platforms with minimal implementation burden win here.
- Pharmacy Benefit Managers:Organizations managing drug formularies, rebate negotiations, and specialty pharmacy networks.
- Accountable Care Organizations:Medicare Shared Savings Program participants requiring cost and quality benchmarking.
- Government Payers:State Medicaid agencies, CMS contractors, and national health services with public procurement requirements.
Health Insurers represent the largest addressable spend. Accountable Care Organizations show the steepest expansion trajectory as value-based enrollment grows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital systems and health insurers in the United States drive the largest procurement volumes for financial analytics platforms. German statutory health insurance funds and Australian private insurers accelerate cloud migration to modernize claims infrastructure.
United States
Medicare Advantage plans and Medicaid managed care organizations deploy risk adjustment algorithms to optimize capitation payments. CMS value-based reimbursement programs mandate predictive analytics for readmission reduction. The Boston-Cambridge corridor anchors Health Catalyst and other vendors building data operating systems for integrated delivery networks.
Germany
Statutory health insurance funds under the GKV-Spitzenverband require activity-based costing tools to manage DRG reimbursement accuracy. The EU AI Act imposes conformity assessments on clinical decision support tools with financial implications. Berlin and Munich host payer analytics clusters where vendors rebuild data pipelines for API-driven EHR interoperability.
Australia
Private health insurers including Bupa and Medibank accelerate procurement of automated claims adjudication platforms. The Australian Digital Health Agency enforces FHIR-based interoperability standards through the My Health Record system. Sydney and Melbourne concentrate cloud-native deployments as insurers eliminate on-premises hardware refresh cycles.
Japan
Medical groups under the Ministry of Health, Labour and Welfare's Diagnosis Procedure Combination system adopt cost analytics for episode-based reimbursement optimization. METI data localization guidance favors hybrid cloud architectures with sensitive data remaining on-premises. The Nagoya-Osaka corridor hosts implementation specialists combining clinical domain expertise with machine learning engineering.
Brazil
Private health insurance enrollment growth among middle-class consumers creates demand for fraud detection and pre-payment integrity screening. ANVISA regulatory clarity enables vendor entry for risk adjustment platforms. São Paulo anchors the dominant payer analytics cluster where carriers modernize legacy COBOL billing systems.
Global Healthcare Financial Analytics Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. Payer-provider integrated entities and standalone analytics vendors occupy distinct strategic layers, with consolidation pressures intensifying around interoperability depth and real-world data scale. Three archetypes dominate: vertically integrated health services conglomerates, pure-play analytics platform vendors, and EHR-embedded solution providers. Competitive moves concentrate on API-first architecture development and payer-provider workflow integration.
Among payer-integrated analytics providers, Optum Analytics and IQVIA exemplify channel-control strategies leveraging claims volume and clinical data infrastructure. Health Catalyst occupies a position within the standalone platform tier, specializing in data operating system architectures that unify financial and operational metrics. These three entities represent contrasting approaches to customer acquisition—integrated service bundling versus modular platform deployment—without any single archetype commanding definitive market dominance.
| Leading Market Players |
|---|
| Innovaccer |
| SAS Healthcare Analytics |
| Health Catalyst |
| Prognos Health |
| Kodjin |
| Optum Analytics |
| IQVIA |
| Clearsense |
| MedeAnalytics |
| Others |
Supply & Pricing Matrix
Cloud infrastructure concentration in the United States, Germany, and Australia anchors margin capture for healthcare financial analytics vendors, with hyperscaler capacity commitments dictating downstream SaaS pricing flexibility for hospital systems and health insurers.
Pricing Analysis
Cost-plus contracts with AWS, Azure, and Google Cloud indexation clauses dominate vendor procurement, passing through compute and storage volatility to end customers via annual escalators. Pricing stratifies across enterprise, mid-market, and ambulatory tiers based on claims volume processed and API integration depth. Cost compression in the mid-market tier is intensifying because Optum Analytics and IQVIA bundle analytics with core claims processing at marginal cost. Hospital systems with dedicated IT procurement teams exhibit the highest price sensitivity, while Medicare Advantage plans prioritize accuracy guarantees over per-seat economics.
Supply Chain Analysis
Upstream feedstock for healthcare financial analytics platforms draws from cloud compute infrastructure concentrated in the United States, Ireland, and Singapore, with specialized GPU clusters for machine learning training residing primarily in Northern Virginia and Frankfurt. Raw material dependencies center on proprietary claims datasets, FHIR-standardized clinical records, and licensed NLP model weights. Single-source vulnerability runs through Epic and Cerner EHR integration pathways that control patient data ingress. Distribution runs through direct enterprise sales teams for health insurers and channel partners for medical group deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Healthcare financial analytics operates as a defensive-moat market where regulatory entrenchment around HIPAA technical safeguards and CMS certification requirements creates substantial switching costs for established vendor relationships.
For Market Incumbents: Entrench position by deepening API-first architectures that embed workflow automation directly into Epic and Cerner EHR environments, raising replacement costs for hospital systems. Pursue backward integration into real-world data assets through exclusive payer-provider data partnerships, countering the threat of pure-play AI vendors with superior model performance but inferior data access. Invest in EU AI Act conformity assessment capabilities to preempt German and French procurement committee requirements. For New Entrants and Emerging Players: Build out specialized fraud detection modules for Brazilian private insurers where ANVISA regulatory clarity has lowered entry barriers but incumbent presence remains thin. Target the Accountable Care Organization segment in the United States, where shared savings program participation is accelerating but analytics penetration lags Medicare Advantage plans. Lead with consumption-based SaaS pricing and rapid FHIR implementation to bypass lengthy procurement cycles. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed revenue cycle management vendors lacking cloud-native architecture and facing margin compression from athenahealth and R1 RCM platform consolidation. Long-term viability hinges on interoperability depth and payer-provider workflow integration rather than standalone algorithmic performance. Watch CMS pre-payment integrity mandate expansion as the signal indicating accelerated procurement velocity for prospective claims screening platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-driven interoperability with Epic and Cerner EHR systems locks in hospital system renewals. |
| Strategic Partnership | Payer-provider data sharing agreements with UnitedHealth and Anthem secure proprietary training datasets. |
| Acquisition of Specialist Firm | NLP coding automation targets address manual clinical documentation bottlenecks in ambulatory networks. |
| Geographic Expansion | Brazilian private insurance enrollment growth creates whitespace for fraud detection platform deployment. |
| Product Launch | EU AI Act-compliant clinical decision support modules unlock German statutory health insurance procurement. |
Research Methodology
Initial hypotheses were tested against primary input from hospital CIOs, health insurer actuarial directors, revenue cycle management executives, and EHR integration specialists and refined through secondary validation against CMS Medicare cost reports, hospital procurement databases, GPO contracts, and hyperscaler healthcare vertical disclosures. Bottom-up sizing of claims volume processed and top-down cross-check against payer IT spending allocations established demand-side boundaries.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation modeled by solution architecture, deployment model, end-user type, and regional regulatory cluster. CAGRs were derived from trajectory fitting to historical procurement volumes and elasticity estimates around CMS value-based program expansion. Forecast inputs incorporated ONC interoperability mandate compliance timelines and EU AI Act implementation sequencing.
Sensitivities concentrate around CMS audit expansion timing, GDPR cross-border data flow enforcement, and cloud infrastructure cost inflation. Forecasts reflect documented assumptions regarding payer technology refresh cycles and hospital system consolidation patterns. Material shifts in federal reimbursement pathway qualification requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Data Management
North America Clinical Data Analytics in Healthcare Market
Health Data Management
Global Big Data Analytics in Healthcare Market
Health Data Management
Global Healthcare Quality Management Market
Health Data Management
North America Healthcare Analytics Market
Health Data Management
Asia Pacific Healthcare Archiving and Ediscovery Market
Health Data Management
United States Healthcare Big Data Analytics Market
Health Data Management
Patient Data Management Systems Market
Health Data Management
Patient Data Management Software Market
Health Data Management
Healthcare Data Interoperability Market
Health Data Management
Global Healthcare Compliance Software Market
Health Data Management
Data Monetization in Healthcare Market
Health Data Management
Medical Record Management System Market
Health Data Management
Healthcare Data Collection and Labeling Market
Health Data Management
Global Healthcare Data Analytics Market
Health Data Management
Population Health Management Solutions Market
Health Data Management
Global Healthcare Content Management System Market