
 Global Healthcare Customer Data Platform Market | 2026-2036
Global Healthcare Customer Data Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Global Healthcare Customer Data Platform Market Foresight
Healthcare data architecture is fragmenting across cloud-native, hybrid, and legacy on-premise environments simultaneously. Oracle leverages its Cerner acquisition to anchor electronic health record integration within its cloud infrastructure stack. Microsoft competes through Azure Health Data Services, which sustains deep interoperability with FHIR standards. Innovaccer Inc. specializes in building unified patient records for health systems navigating multi-source data ingestion.
A Healthcare Customer Data Platform is a software system that ingests, unifies, and activates patient data from disparate clinical, operational, and financial sources through deterministic and probabilistic identity resolution algorithms; its primary purpose is to enable real-time personalization of care pathways and population health interventions while maintaining audit-grade data lineage. Cloud-Based deployment leads among new implementations because health systems prioritize elastic compute for seasonal patient volume spikes and disaster recovery. Patient Engagement applications represent the fastest-growing segment as providers seek to reduce readmission penalties through automated outreach protocols. Provider Profiling remains a mature margin pool where data vendors sell credentialing and quality scorecards to payers under long-term contracts.
FDA guidance on clinical decision support software intersects with HIPAA breach notification rules to shape how platform vendors architect audit trails and consent management modules. The EU AI Act's risk classification for health-related artificial intelligence systems is forcing vendors to reengineer algorithmic transparency features before European market access. Stakeholders must monitor whether CMS interoperability mandates will eventually require real-time patient data activation as a condition of Medicare reimbursement participation.
Market Dynamics
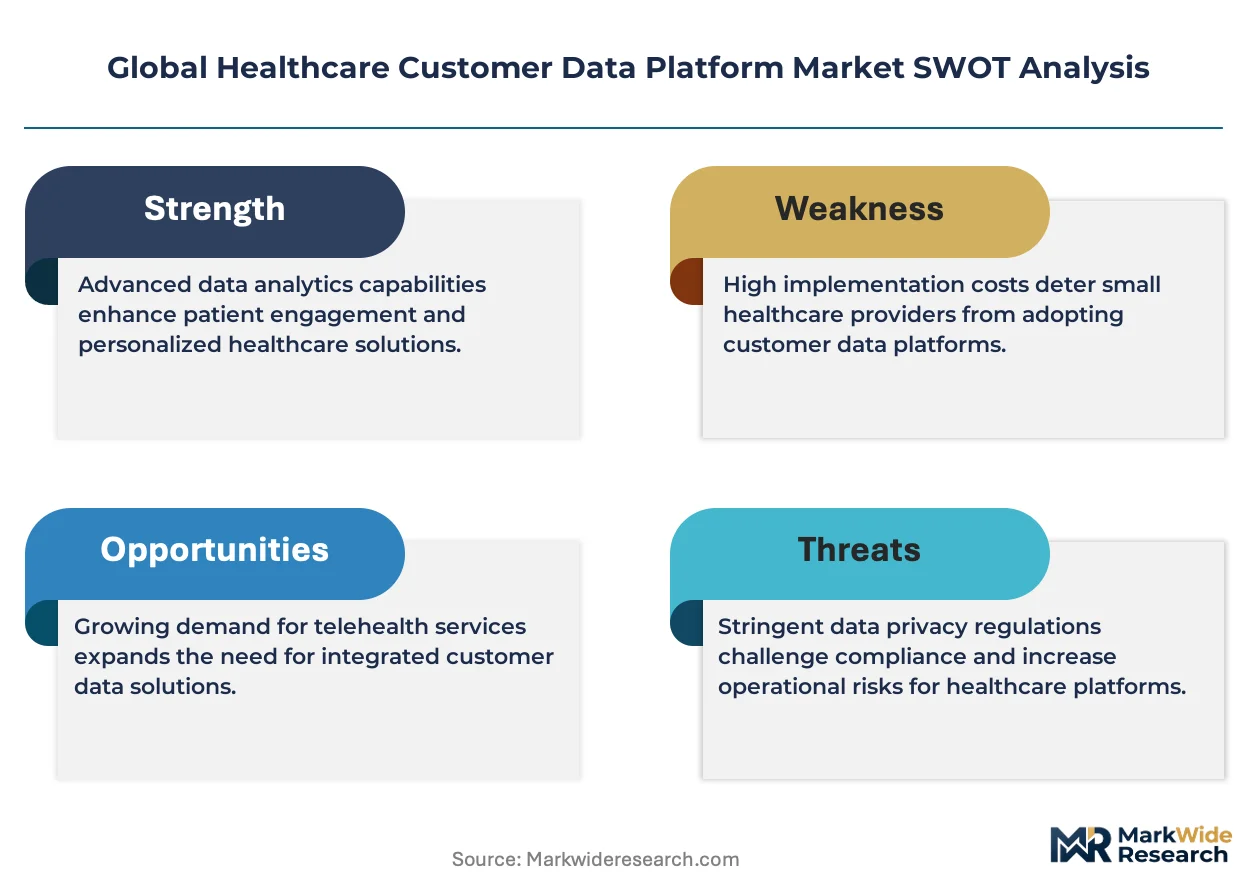
Health systems confront a data gravity problem where patient records fragment across cloud, on-premise, and edge environments simultaneously. The EU AI Act's risk classification system is forcing platform vendors to reengineer algorithmic transparency modules before European market access, compressing product roadmaps and reshaping competitive positioning.
Growth Catalysts
- FHIR Standards Maturation:The interoperability framework now supports bulk data export and subscription mechanisms. United States integrated delivery networks accelerate platform procurement to meet CMS mandates.
- United States Readmission Penalty Expansion:CMS hospital-acquired condition reduction programs now tie reimbursement to automated patient outreach capabilities. Provider systems purchase engagement modules to avoid payment cuts.
- Real-Time Identity Resolution:Probabilistic matching algorithms now achieve deterministic-grade accuracy for patient record linkage. Health information exchanges deploy these engines to reduce duplicate record rates.
Market Restraints
- Cross-Border Data Localization:China's Personal Information Protection Law and India's Digital Personal Data Protection Act impose data residency requirements that fragment cloud architecture strategies.
- Specialized Talent Scarcity:Health informaticists with dual competency in clinical workflows and cloud infrastructure command premium compensation. Health systems in secondary markets struggle to staff platform implementation teams.
- Legacy ERI Integration Friction:Decades-old electronic health record systems lack modern API layers. Custom middleware development consumes 40-60% of platform deployment budgets.
Strategic Opportunities
- Brazilian Unified Health System Modernization:The country's national health infrastructure program allocates capital for patient data unification. International platform vendors partner with local systems integrators for market entry.
- Synthetic Data Generation:Privacy-preserving algorithms create de-identified patient cohorts for research. Pharmaceutical manufacturers purchase these datasets to accelerate clinical trial design.
- Edge Computing Convergence:Low-latency processing at hospital sites enables real-time clinical decision support. Rural health networks deploy edge nodes to maintain operations during connectivity outages.
Industry Challenges
- Multi-Cloud Governance Complexity:Health systems operate patient data across AWS, Azure, and Google Cloud simultaneously. Consistent policy enforcement requires specialized cloud security architects.
- Consent Management at Scale:State-level privacy laws in California, Virginia, and Colorado create conflicting patient consent requirements. Platform vendors maintain jurisdiction-specific rule engines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Healthcare Customer Data Platform Market |
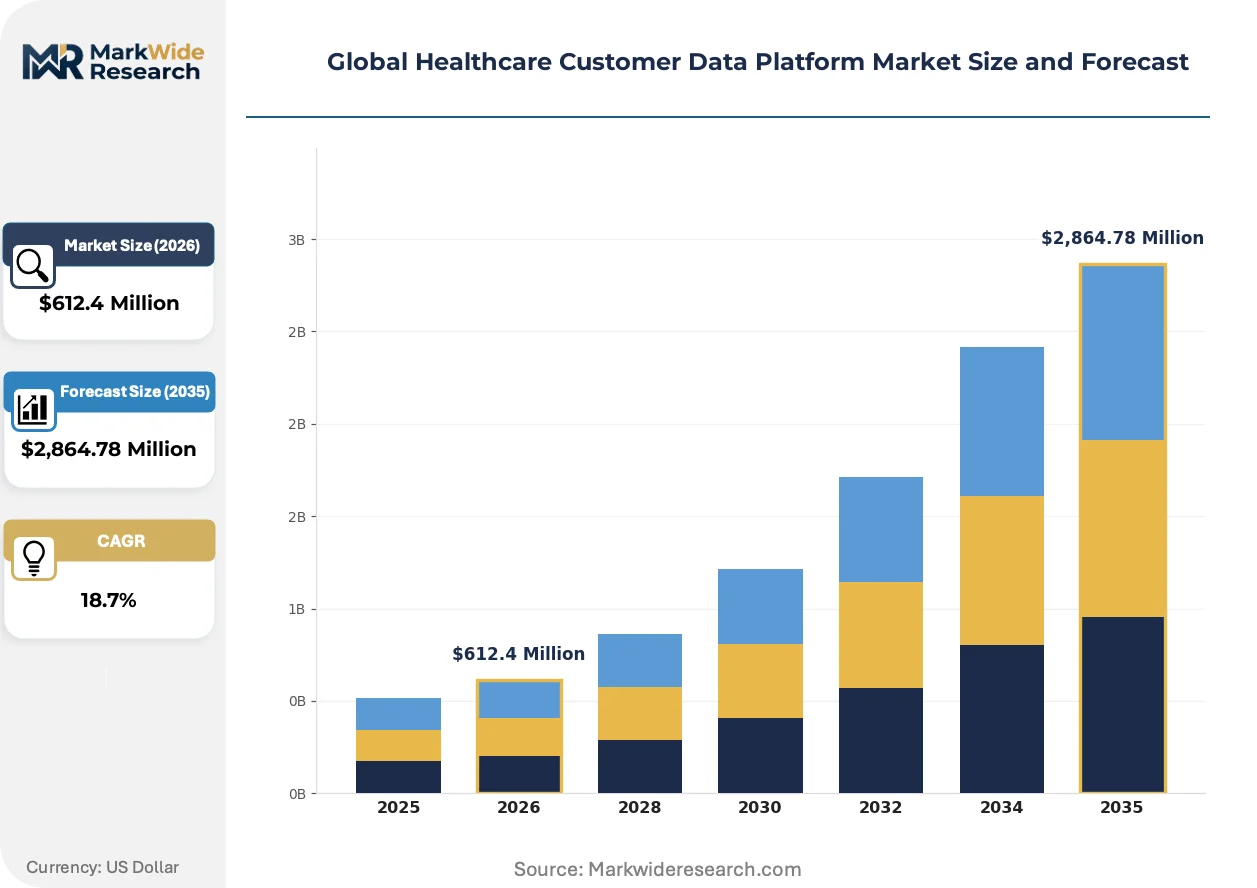
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $2,864.78 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
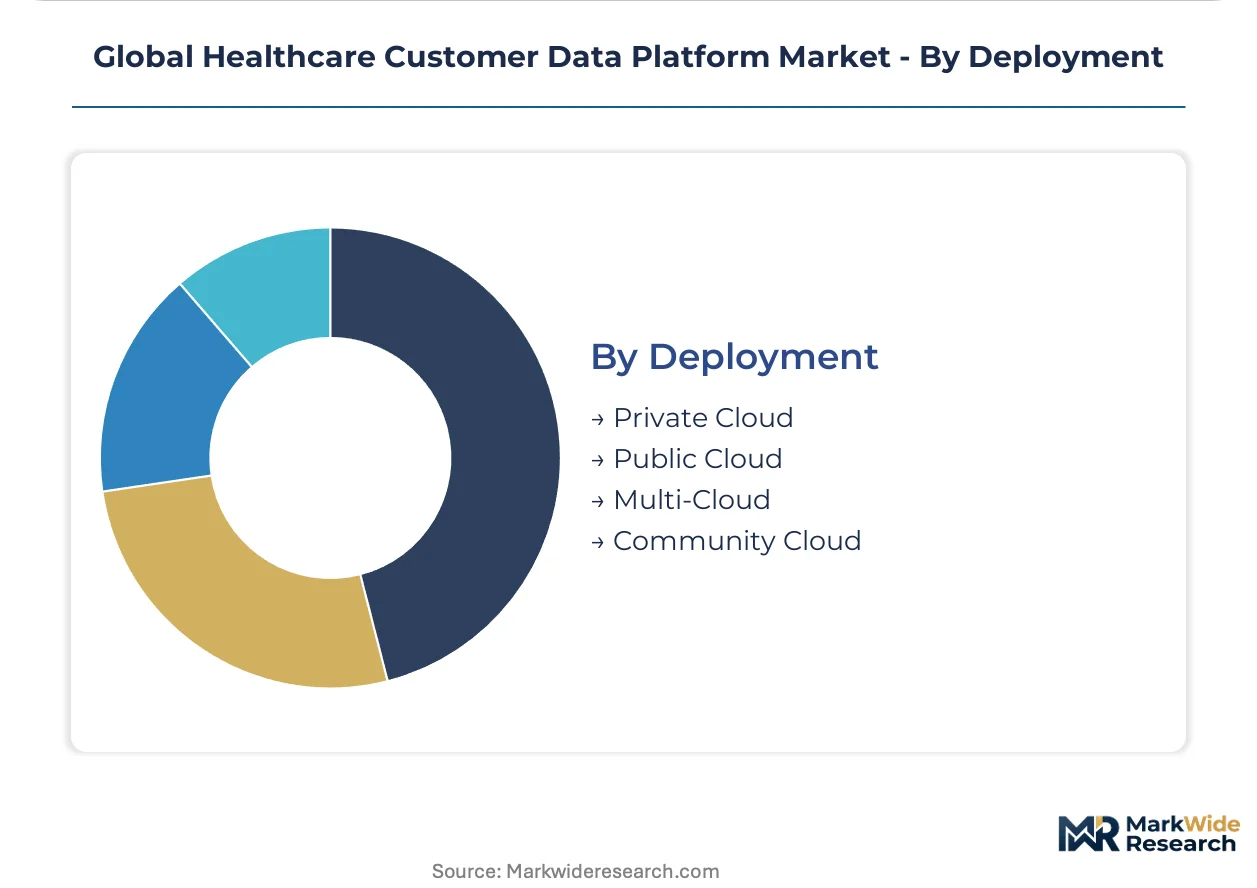
| Segmentation | Product Type: On-Premise, Cloud-Based, Hybrid, SaaS Application: Patient Engagement, Claims Management, Marketing Automation, Revenue Cycle Management, Provider Profiling End User: Hospitals, Health Systems, Insurance Providers, Research Institutes, Pharmaceutical Firms Deployment: Private Cloud, Public Cloud, Multi-Cloud, Community Cloud |
| Companies Covered | Oracle, Treasure Data Inc., Microsoft, Reltio, Tealium Inc., Salesforce, Innovaccer Inc., Health Catalyst, Adobe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Healthcare Customer Data Platform Market Shifts & Advancements
Platform architecture is fragmenting across three simultaneous vectors: compute location, data sovereignty jurisdiction, and interoperability protocol. Vendors that abstract these complexities through unified control planes capture disproportionate pricing power.
Containerized microservices architectures are virtualizing legacy electronic health record integration patterns. Health systems in the United States adopt Kubernetes-orchestrated data pipelines to isolate patient workloads across hybrid environments. This virtualization is compressing the traditional 18-month platform deployment cycle into 6-9 month implementations.
The EU AI Act's high-risk system classification for clinical decision support software is mandating algorithmic audit trails and human oversight interfaces. European health technology procurement now requires conformity assessments before contract execution. Germany's university hospitals are piloting standardized model cards to document AI training data provenance and performance characteristics.
Subscription-based platform licensing is displacing perpetual software purchases in North American health systems. Chief information officers prefer operational expenditure models that align costs with patient volume fluctuations. This shift concentrates vendor revenue into annual recurring streams and intensifies customer success investment to reduce churn.
Global Healthcare Customer Data Platform Market Segmentation
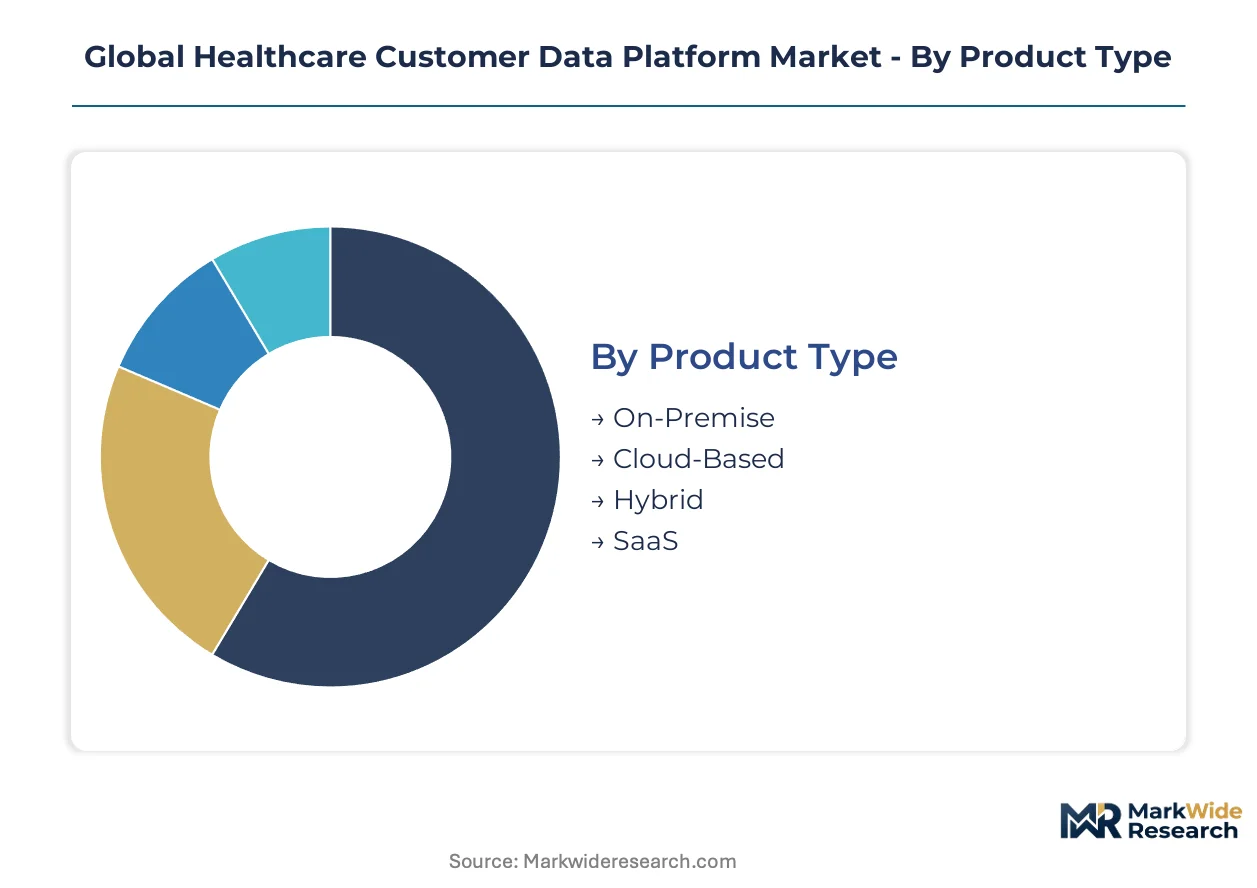
Healthcare Customer Data Platform segmentation reveals how procurement priorities diverge across infrastructure maturity levels and regulatory exposure. Platform vendors must architect modular pricing that aligns compute costs with patient volume seasonality while accommodating fragmented data sovereignty requirements.
Product Type:
After-sales service intensity varies dramatically across deployment modes, with Cloud-Based implementations demanding continuous optimization support for elastic workload management while On-Premise installations require intensive legacy integration engineering.
- Cloud-Based:Native elasticity enables health systems to scale compute resources during flu season patient surges without capital expenditure spikes. United States integrated delivery networks favor this model to satisfy CMS interoperability mandates while outsourcing disaster recovery liability.
- Hybrid:Combines on-premise patient record storage with cloud-based analytics processing to satisfy data residency requirements. German university hospitals deploy hybrid architectures to maintain local control over genomic data while leveraging cloud AI training infrastructure.
- On-Premise:Legacy infrastructure requiring substantial middleware development for EHR connectivity. Japanese regional health authorities retain on-premise stacks to comply with METI data localization guidelines for sensitive patient information.
- SaaS:Subscription licensing with standardized FHIR connectors reducing implementation timelines. Brazilian municipal health departments adopt SaaS platforms to bypass scarce domestic health informatics talent pools.
Cloud-Based holds the largest share; momentum sits with Hybrid as cross-border data governance tightens.
Application:
Margin structures diverge sharply across use cases, with Patient Engagement commanding premium pricing for real-time outreach automation while Provider Profiling operates as a commoditized data resale business with long-term contract lock-in.
- Patient Engagement:Automated outreach protocols reduce CMS readmission penalties through personalized care pathway notifications. United States hospital systems purchase engagement modules to avoid reimbursement cuts under hospital-acquired condition reduction programs.
- Provider Profiling:Credentialing and quality scorecards sold to payers under multi-year agreements with limited pricing power. Data vendors in this segment face compression as self-service analytics tools displace custom reporting.
- Claims Management:Real-time adjudication engines integrating payer and provider data streams. Indian insurance regulators mandate standardized claims platforms to reduce fraud detection latency.
- Marketing Automation:Campaign orchestration for service line growth and patient acquisition. Australian private hospital networks deploy these tools to compete for elective procedure volume.
- Revenue Cycle Management:Financial clearance and prior authorization workflow optimization. United States rural health clinics prioritize this application to address staffing shortages in billing departments.
Provider Profiling dominates current revenue; Patient Engagement is expanding most quickly as penalty structures intensify.
End User:
Procurement authority concentrates differently across buyer types, with Health Systems negotiating enterprise-wide platform licenses while Pharmaceutical Firms purchase discrete synthetic data modules for clinical trial design.
- Health Systems:Integrated delivery networks consolidating EHR investments across acquired facilities. These buyers demand unified patient records spanning multi-source data ingestion with deterministic identity resolution.
- Hospitals:Standalone acute care facilities prioritizing edge computing nodes for real-time clinical decision support during connectivity outages.
- Insurance Providers:Payers acquiring provider profiling data and risk stratification algorithms. South Korean health insurers invest in platforms to support value-based reimbursement pilots.
- Pharmaceutical Firms:Research-focused buyers purchasing privacy-preserving synthetic patient cohorts. These customers accelerate clinical trial design without exposing protected health information.
- Research Institutes:Academic medical centers requiring algorithmic audit trails for EU AI Act conformity assessments. German university hospitals pilot standardized model cards for AI training data provenance.
Health Systems command the largest procurement volume; Pharmaceutical Firms are gaining share fastest through synthetic data partnerships.
Deployment:
Supply concentration among hyperscale cloud providers shapes architecture decisions, with Multi-Cloud strategies emerging as risk mitigation against single-vendor lock-in despite governance complexity premiums.
- Public Cloud:Shared infrastructure delivering lowest unit compute costs for non-sensitive analytics workloads. United States federally qualified health centers leverage public cloud for population health reporting.
- Private Cloud:Dedicated tenant environments satisfying strict data isolation requirements. Saudi Arabian health clusters mandate private cloud for patient data under national cybersecurity frameworks.
- Multi-Cloud:Distributed workloads across AWS, Azure, and Google Cloud simultaneously. This architecture requires specialized cloud security architects for consistent policy enforcement.
- Community Cloud:Shared infrastructure for regional health information exchanges. Brazilian state health networks deploy community cloud to achieve economies of scale without surrendering data sovereignty.
Public Cloud retains dominant share; Multi-Cloud shows steepest expansion trajectory as vendor diversification priorities intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States health systems export patient data platform expertise to Canadian integrated delivery networks and Mexican hospital consortia seeking FHIR-compliant infrastructure templates.
United States
Integrated delivery networks consolidate electronic health record investments across acquired facilities. HIPAA breach notification rules intersect with FDA clinical decision support guidance to shape audit trail architectures. The Boston-Cambridge corridor anchors health informatics talent pools where Massachusetts General Hospital pilots real-time identity resolution engines.
Germany
University hospitals demand algorithmic transparency modules for EU AI Act conformity assessments. METI guidelines influence data localization preferences for sensitive genomic information. The Munich-Heidelberg cluster hosts pilot programs for standardized model cards documenting AI training data provenance.
China
Personal Information Protection Law mandates data residency requirements fragmenting cloud architecture strategies. The national pharmaceutical regulator tightens cross-border health information exchange protocols. Shanghai's Pudong district concentrates health technology procurement authority where municipal hospitals deploy edge computing nodes.
Brazil
ANVISA collaborates with municipal health departments on national infrastructure modernization programs. The country's national health infrastructure program allocates capital for patient data unification. São Paulo state health networks deploy community cloud architectures to achieve economies of scale without surrendering data sovereignty.
India
Digital Personal Data Protection Act imposes localization requirements complicating multi-cloud governance. CDSCO guidelines shape clinical decision support software deployment standards. Bengaluru's health technology corridor attracts international platform vendors partnering with domestic systems integrators for market entry.
Global Healthcare Customer Data Platform Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three structural tiers. Hyperscale cloud providers anchor the infrastructure layer through electronic health record integration stacks. Independent software vendors occupy the middleware tier with deterministic identity resolution engines. Systems integrators capture implementation margins through legacy EHR connectivity engineering. M&A activity concentrates among cloud providers acquiring clinical workflow assets. Strategic partnerships dominate between international platforms and regional integrators.
Among United States-based technology conglomerates, Oracle and Microsoft occupy positions anchoring cloud infrastructure competition through electronic health record integration capabilities. Innovaccer Inc. exemplifies the independent software vendor archetype specializing in unified patient records for multi-source data ingestion. These three entities represent the dominant competitive positioning vectors: infrastructure control, clinical workflow depth, and identity resolution specialization.
| Leading Market Players |
|---|
| Oracle |
| Treasure Data Inc. |
| Microsoft |
| Reltio |
| Tealium Inc. |
| Salesforce |
| Innovaccer Inc. |
| Health Catalyst |
| Adobe |
| Others |
Supply & Pricing Matrix
Elastic compute undercapacity in United States health systems during seasonal patient surges drives both vendor capacity expansion and subscription pricing premiums. Cloud-native platform providers leverage utilization spikes to anchor annual recurring revenue models while buyers absorb cost-plus indexation tied to AWS and Azure compute pricing.
Pricing Analysis
Cost-plus contracts with CPI indexation dominate enterprise health system procurement, tying platform fees to hyperscaler infrastructure costs. Three-tier pricing structure across premium, standard, and economy levels segments by integration complexity and after-sales support intensity. Pricing pressure stems from Brazilian municipal health departments and Indian state networks demanding SaaS tiers that bypass scarce implementation talent. Health systems in secondary United States markets exhibit highest price sensitivity due to constrained capital budgets, while German university hospitals accept premium tiers for EU AI Act compliance modules.
Supply Chain Analysis
Contract manufacturing concentration rests with AWS, Microsoft Azure, and Google Cloud as the dominant infrastructure-as-a-service providers holding global compute capacity. Software development draws from engineering talent pools in India, Poland, and Vietnam for platform engineering and FHIR connector development. Supply chain risk centers on single-source vulnerability for identity resolution algorithms licensed from specialized vendors. Distribution runs through systems integrators and GPO contracts for United States health system procurement, with direct sales teams penetrating European and Latin American markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards defensive moats built on regulatory entrenchment. HIPAA compliance architectures and EU AI Act conformity assessments create switching costs that cement incumbent positions across multi-year procurement cycles.
For Market Incumbents: Build data network effects by embedding deterministic identity resolution engines into health information exchange infrastructure. Consolidate position through backward integration into legacy EHR middleware development, capturing 40-60% of deployment budgets currently lost to third-party integrators. Counter threat from synthetic data startups by expanding pharmaceutical firm partnerships for privacy-preserving research cohorts. For New Entrants and Emerging Players: Geographic underpenetration in Brazilian state health networks and Indian municipal clinics offers white-space entry points. Target SaaS-native deployments that bypass on-premise integration complexity and scarce health informatics talent. Pursue go-to-market partnerships with regional systems integrators holding existing ANVISA and CDSCO regulatory relationships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-native platform vendors with health system enterprise contracts exceeding three-year terms. Long-term viability hinges on algorithmic transparency capabilities for EU market access and synthetic data generation pipelines for pharmaceutical research partnerships. Monitor CMS interoperability mandate expansion as inflection signal for real-time patient data activation requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidates EHR investments across acquired facilities within United States integrated delivery networks. |
| Strategic Partnership | Enables ANVISA-aligned market entry for international vendors via Brazilian systems integrators. |
| Geographic Expansion | Captures Brazilian national health infrastructure program allocations for patient data unification. |
| Acquisition of Specialist Firm | Absorbs deterministic identity resolution engines from health information exchange middleware vendors. |
| Product Launch | Introduces EU AI Act-compliant algorithmic audit trail modules for German university hospital procurement. |
Research Methodology
The analysis maps cloud-native, hybrid, and on-premise deployment modes, each validated through chief information officers, health informaticists, and GPO contracts managers at United States integrated delivery networks. Primary interviews with platform engineers and FHIR integration specialists combined with secondary validation against CMS Medicare data, hospital procurement databases, and hyperscaler capex disclosures. Bottom-up patient volume modeling and top-down health system IT spend analysis triangulate market sizing.
Assumptions held fixed include HIPAA breach notification rule enforcement intensity and EU AI Act risk classification thresholds for clinical decision support software, while variables included CMS interoperability mandate expansion timing and cross-border data localization enforcement in China and India. Segmentation dimensions modeled encompass deployment architecture, application use case, and end-user procurement authority across the projection horizon. CAGRs derive from elastic compute demand curves and health system consolidation velocity, with synthetic data generation adoption and edge computing deployment as industry-specific forecast inputs.
Practitioners should monitor EU AI Act conformity assessment timeline acceleration and CMS real-time data activation mandate signals for early revision triggers. Forecasts reflect assumptions regarding health system cloud migration pace and pharmaceutical firm synthetic data purchasing patterns. Quarterly review of health informatics talent compensation inflation and hyperscaler infrastructure pricing indices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Data Management
AI Training Dataset in Healthcare Market
Health Data Management
Wireless Healthcare Asset Management Market
Health Data Management
Global Healthcare Data Storage Market
Health Data Management
Global Healthcare Fraud Analytics Market
Health Data Management
Data Democratization in Healthcare Market
Health Data Management
Medical Record Management System Market
Health Data Management
Global Chronic Care Management Software Market
Health Data Management
Global Big Data Analytics in Healthcare Market
Health Data Management
Clinical Trial Data Management Software Market
Health Data Management
Healthcare Predictive Analytics Market
Health Data Management
Patient Data Management Systems Market
Health Data Management
Healthcare Data Monetization Solutions Market
Health Data Management
Population Health Management Solutions Market
Health Data Management
Population Health Management (PHM) Market
Health Data Management
Point of Care (POC) Data Management Systems Market
Health Data Management
Americas Healthcare Archiving and Ediscovery Market