
 Population Health Management Platforms Market | 2026-2036
Population Health Management Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
Population Health Management Platforms Market Analytics
Software-defined analytics modules is restructuring how population health platforms monetize capability, shifting perpetual licenses toward consumption-based data services. Epic Systems Corporation leverages its dominant EHR install base to anchor integrated risk stratification workflows within provider networks. Oracle Health sustains enterprise-scale cloud infrastructure for payer-provider data convergence. Health Catalyst differentiates through proprietary data operating systems that standardize clinical and financial metrics across disparate sources.
Population health management platforms are integrated software ecosystems that aggregate electronic health records, claims data, and social determinants of health into unified patient registries for predictive intervention and care gap closure. These systems typically process structured and unstructured clinical data through HL7 FHIR APIs and natural language processing engines to generate real-time risk scores and automated outreach triggers. Data analytics segments occupy the deepest margin pools as health systems prioritize predictive modeling for readmission reduction and cost-of-care optimization. Care management applications are expanding fastest among payers integrating remote patient monitoring feeds with nurse care coordinator dashboards. Cloud-based deployment leads adoption as HIPAA-compliant multi-tenant architectures replace aging on-premises data warehouses.
The US Office of the National Coordinator for Health IT mandates interoperability standards through the 21st Century Cures Act Final Rule, compelling platforms to enable patient-directed data exchange and blocking prohibitions. CMS value-based purchasing programs and Medicare Advantage star ratings shape demand by tying reimbursement to documented quality metrics and health equity reporting. The FDA's evolving software-as-a-medical-device guidance creates compliance thresholds for algorithmic clinical decision support embedded within these platforms. Stakeholders must monitor how state-level all-payer claims database mandates and emerging AI transparency requirements will reshape platform architecture and vendor liability exposure.
Market Dynamics
Value-based reimbursement mandates from CMS are forcing health systems to restructure care delivery around documented outcomes rather than service volume, compressing legacy fee-for-service workflows and accelerating platform consolidation.
Growth Catalysts
- Medicare Shared Savings Program:CMS accountable care organization incentives reward documented cost reductions and quality improvements, driving provider investment in unified patient registries.
- Remote patient monitoring:Bluetooth-enabled biometric devices and cellular gateways feed continuous data streams into care coordinator dashboards, enabling real-time intervention triggers.
- Interoperability mandates:The US Office of the National Coordinator for Health IT 21st Century Cures Act Final Rule compels platforms to enable patient-directed data exchange and prohibits information blocking.
Market Restraints
- Cloud infrastructure concentration:HIPAA-compliant multi-tenant architectures depend on a limited set of hyperscale providers, creating single-point-of-failure exposure for mid-size health systems.
- Legacy EHR fragmentation:Proprietary data formats from entrenched electronic health record vendors resist standardized HL7 FHIR API implementation, prolonging integration timelines.
- Algorithmic liability uncertainty:FDA software-as-a-medical-device guidance for clinical decision support remains in draft status, delaying deployment of predictive risk scoring modules.
Strategic Opportunities
- Social determinants integration:Housing instability, food security, and transportation data layers represent underexploited predictive inputs for readmission risk models.
- Behavioral health convergence:Depression screening tools and substance use disorder registries are integrating with physical health platforms under CMS Medicare Advantage star rating incentives.
- Community health worker enablement:Mobile-first care coordination applications extend platform reach into Medicaid populations previously excluded from digital health workflows.
Industry Challenges
- Data science talent scarcity:Health systems compete with technology firms for machine learning engineers capable of deploying natural language processing on unstructured clinical notes.
- Multi-source data harmonization:Claims feeds, laboratory results, and pharmacy records arrive in incompatible formats, requiring expensive normalization pipelines before risk stratification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Population Health Management Platforms Market |
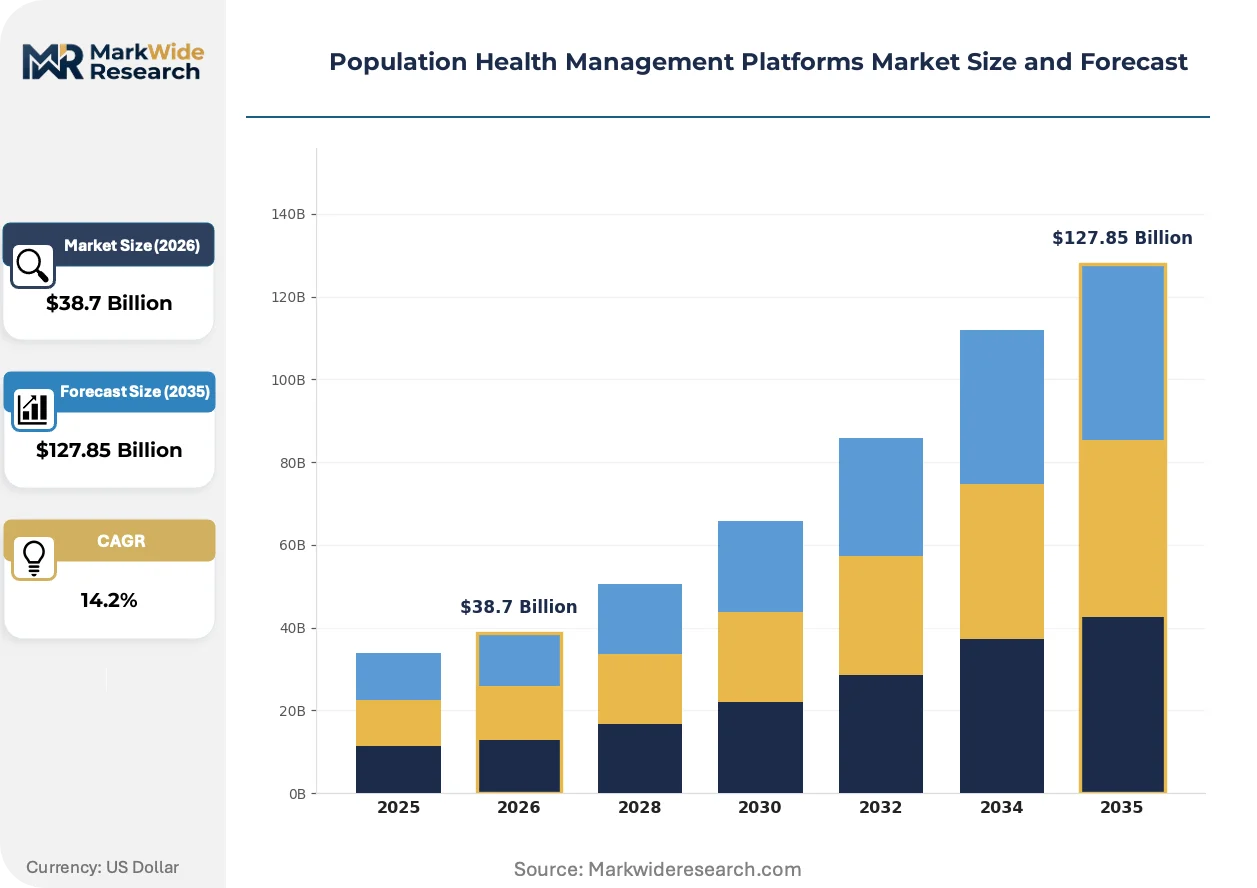
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $127.85 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
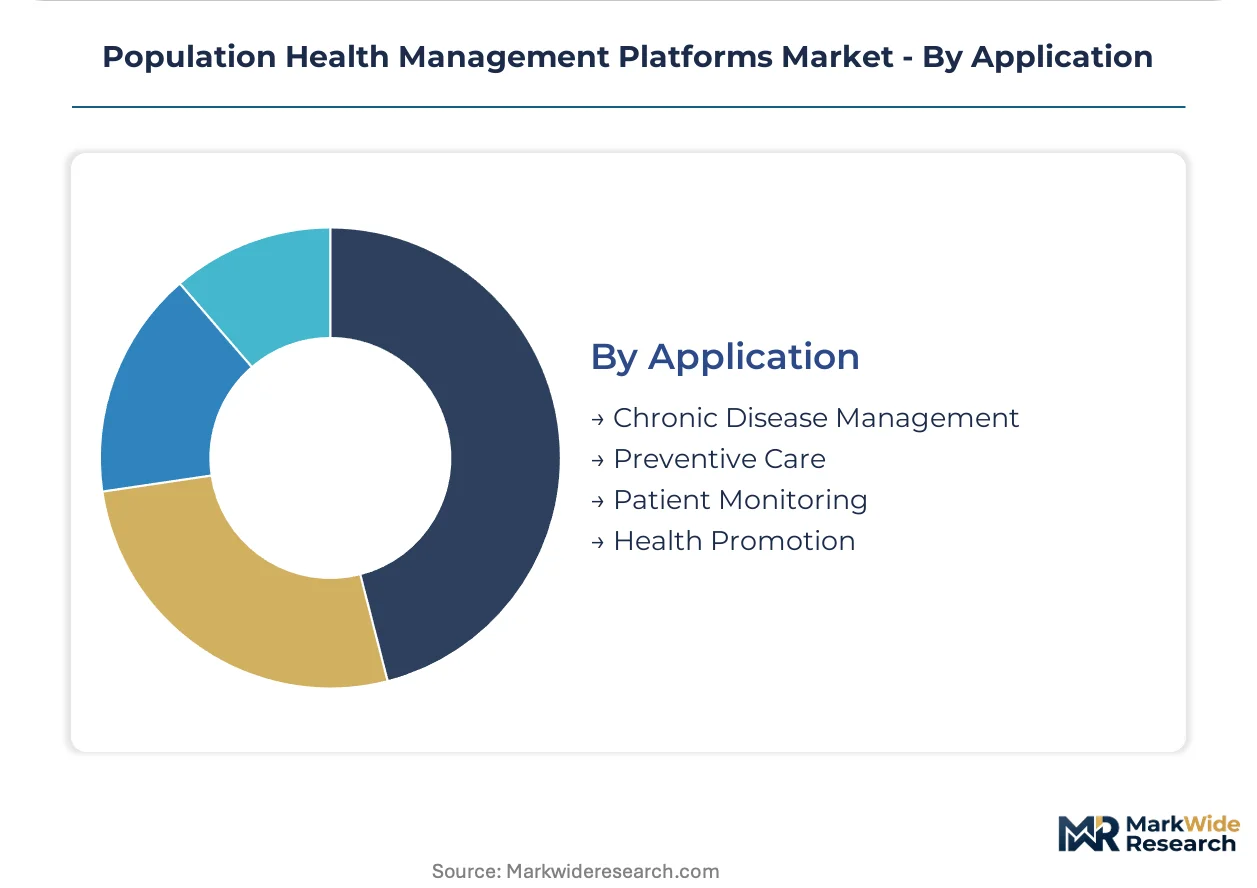
| Segmentation | Product Type: Data Analytics, Care Management, Patient Engagement, Risk Stratification End User: Healthcare Providers, Payers, Government Agencies, Employers Deployment: Cloud-Based, On-Premises, Hybrid, Software as a Service Application: Chronic Disease Management, Preventive Care, Patient Monitoring, Health Promotion |
| Companies Covered | Epic Systems Corporation, Oracle Health, Athenahealth, Veradigm, eClinicalWorks, Optum, Health Catalyst, NextGen Healthcare, Arcadia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Population Health Management Platforms Market Evolving Landscape
Artificial intelligence and federated learning architectures are restructuring how population health platforms process sensitive clinical data, shifting computation toward edge deployment while preserving privacy constraints.
Natural language processing engines are integrating unstructured clinical notes, discharge summaries, and radiology reports into structured risk scores. Large health systems in the US and Germany are deploying these modules to identify undocumented comorbidities. The technology is integrating previously siloed narrative data into automated care gap closure workflows.
The EU AI Act risk classification framework imposes conformity assessment requirements on clinical decision support algorithms deployed in European health networks. High-risk systems must demonstrate bias mitigation and human oversight protocols. French and Dutch hospital systems are restructuring procurement specifications to exclude non-compliant vendors.
Subscription-based platform licensing is displacing perpetual software purchases as health systems prioritize operational flexibility over capital ownership. Payer organizations in California and Texas are leading this transition, negotiating per-member-per-month pricing tied to documented quality metric improvements. The model transfers implementation risk from buyer to vendor while aligning incentives around measurable outcomes.
Population Health Management Platforms Market Segmentation
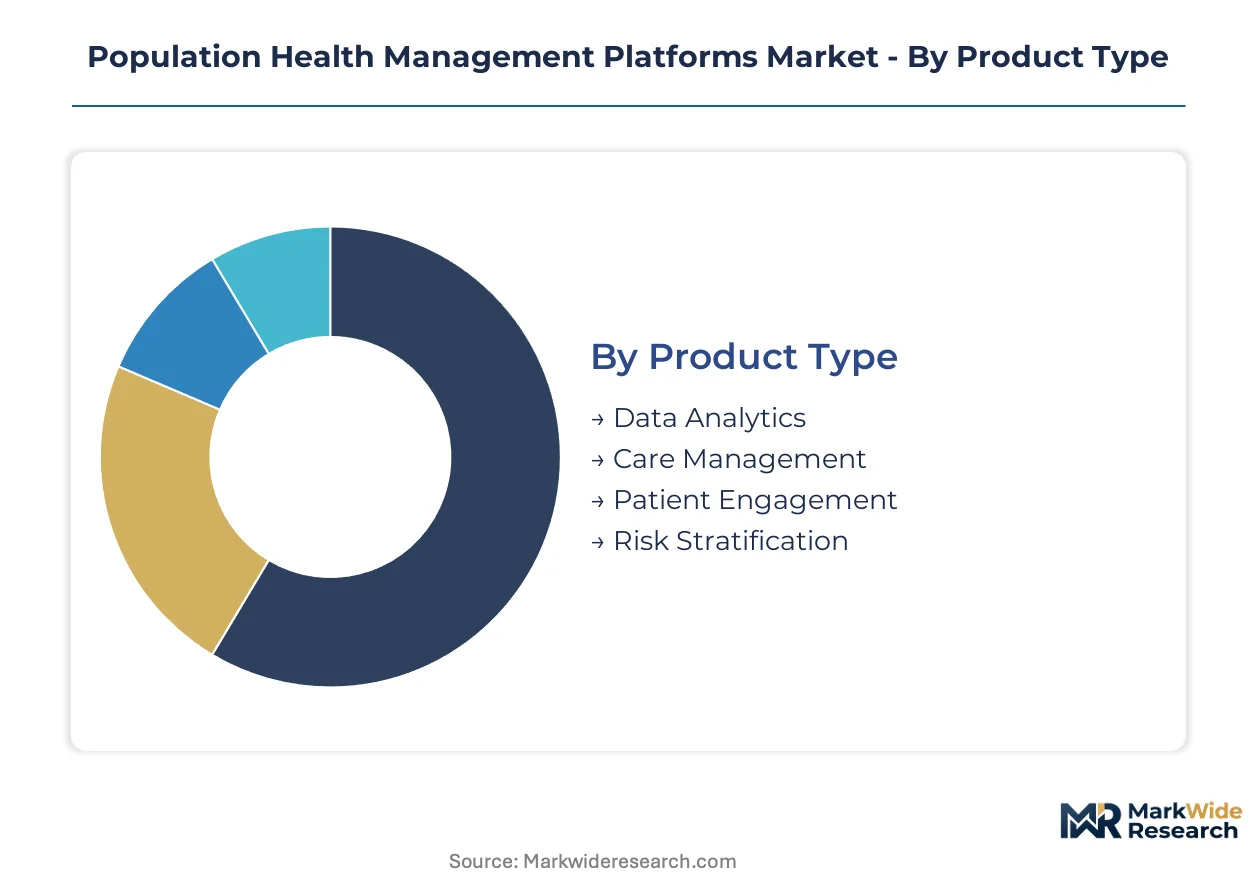
Population health management platforms segment across technical architecture, customer economics, and clinical use cases. Each dimension carries distinct procurement patterns and integration requirements that shape vendor positioning and deployment timelines.
Product Type:
Capital intensity varies sharply across product categories, with infrastructure-heavy analytics modules demanding the largest upfront investment in data pipelines and compute resources.
- Data Analytics:Proprietary data operating systems aggregate structured and unstructured clinical feeds through HL7 FHIR APIs and natural language processing engines. US health systems prioritize predictive modeling for readmission reduction and cost-of-care optimization. Cloud infrastructure and specialized machine learning talent drive the highest deployment costs in this segment.
- Care Management:Integrated nurse care coordinator dashboards combine remote patient monitoring feeds with automated outreach triggers. Payer organizations in California and Texas are expanding adoption fastest under value-based contracting arrangements. Bluetooth-enabled biometric devices and cellular gateways require moderate capital outlay but scale efficiently.
- Patient Engagement:Mobile-first applications extend platform reach into Medicaid populations through community health worker enablement.
- Risk Stratification:Algorithmic clinical decision support modules generate real-time risk scores from unified patient registries.
Most installed capacity flows through Data Analytics. Expansion is steepest in Care Management as payers integrate remote monitoring workflows.
End User:
Customer type determines procurement complexity, with government agencies imposing the most stringent compliance and certification requirements.
- Healthcare Providers:Hospital systems and physician networks anchor demand through Medicare Shared Savings Program participation. Epic Systems Corporation leverages its dominant EHR install base to anchor integrated risk stratification workflows within these networks. Accountable care organization incentives reward documented cost reductions and quality improvements.
- Payers:Insurance organizations negotiate per-member-per-month pricing tied to documented quality metric improvements. Subscription-based licensing is displacing perpetual software purchases as these buyers prioritize operational flexibility over capital ownership.
- Government Agencies:CMS value-based purchasing programs and Medicare Advantage star ratings shape platform specifications through reimbursement tie-ins.
- Employers:Self-insured corporations purchase population health capabilities to manage workforce chronic disease burdens.
Procurement volume concentrates with Healthcare Providers. Payers are gaining share fastest through outcome-based contracting models.
Deployment:
Technical architecture choice reflects organizational scale and data sovereignty requirements, with hybrid models commanding premium pricing for flexibility.
- Cloud-Based:HIPAA-compliant multi-tenant architectures replace aging on-premises data warehouses across North American health systems. Oracle Health sustains enterprise-scale cloud infrastructure for payer-provider data convergence. Hyperscale provider concentration creates single-point-of-failure exposure for mid-size deployments.
- On-Premises:Legacy data centers persist in organizations with strict data residency mandates or limited IT modernization budgets.
- Hybrid:Split architectures process sensitive patient data locally while leveraging cloud analytics for population-level insights.
- Software as a Service:Consumption-based data services are restructuring platform monetization, shifting from perpetual licenses toward variable pricing.
Cloud-Based deployment carries the majority of new installations. Hybrid models are climbing fastest as organizations balance flexibility with compliance.
Application:
Clinical use case maturity spans from well-established chronic disease protocols to emerging health promotion workflows with unproven ROI documentation.
- Chronic Disease Management:Diabetes, hypertension, and heart failure registries form the core installed base with established quality metrics and CMS reimbursement pathways. Integrated care coordination tools manage these populations through documented outcomes rather than service volume.
- Preventive Care:Screening gap closure and vaccination tracking align with Medicare Advantage star rating incentives. Depression screening tools and substance use disorder registries are integrating with physical health platforms under these programs.
- Patient Monitoring:Continuous biometric feeds enable real-time intervention triggers for acute episode prevention.
- Health Promotion:Wellness coaching and lifestyle modification programs target employer and commercial payer segments.
Chronic Disease Management retains the deepest installed base. Preventive Care is gaining share fastest as star rating incentives reshape payer investment priorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's hospital networks deploy population health platforms at roughly twice the density of French systems, reflecting divergent federal investment patterns in digital health infrastructure across Europe's two largest economies.
United States
CMS Medicare Shared Savings Program incentives drive provider consolidation around unified patient registries. The 21st Century Cures Act Final Rule mandates patient-directed data exchange through standardized APIs. Epic Systems Corporation anchors integrated risk stratification workflows within provider networks concentrated in the Upper Midwest and Pacific Northwest.
Germany
German hospital networks prioritize predictive modeling for readmission reduction under Diagnosis-Related Group reimbursement reforms. The EU AI Act imposes conformity assessment requirements on clinical decision support algorithms. Charité – Universitätsmedizin Berlin and Heidelberg University Hospital pilot federated learning architectures for cross-institutional data collaboration.
United Kingdom
NHS England's Integrated Care Systems expand adoption of care coordination tools for chronic disease populations. The UK Medicines and Healthcare products Regulatory Agency issues software-as-a-medical-device guidance for algorithmic clinical support. London's academic medical centers lead deployment of natural language processing engines for unstructured clinical notes.
Japan
Japan's Ministry of Health, Labour and Welfare promotes cloud-based health data platforms under Society 5.0 digital transformation goals. METI funding supports interoperability standards alignment with HL7 FHIR specifications. Tokyo and Osaka metropolitan hospital clusters integrate remote patient monitoring feeds with nurse care coordinator dashboards.
Australia
Australian Primary Health Networks invest in population health capabilities for rural chronic disease management. The Therapeutic Goods Administration regulates clinical decision support software under medical device frameworks. Melbourne and Sydney health systems deploy subscription-based platform licensing tied to documented quality metric improvements.
Population Health Management Platforms Market Competitive Landscape
Top-tier vendors anchor enterprise-scale deployments, while mid-cap specialists occupy niche workflow segments. The vendor landscape stratifies across three functional tiers: electronic health record incumbents extending into analytics, pure-play data platform specialists, and payer-owned technology divisions. Dominant competitive moves include strategic partnerships between cloud infrastructure providers and clinical workflow developers, plus portfolio diversification into social determinants data layers.
Among EHR-anchored platform developers, Epic Systems Corporation and Oracle Health exemplify the incumbent expansion archetype, leveraging installed base density to integrate risk stratification workflows. Health Catalyst occupies a position within the pure-play data operating system tier, standardizing clinical and financial metrics across disparate sources. These three companies represent contrasting strategic postures: captive EHR integration, enterprise cloud infrastructure convergence, and proprietary data harmonization pipelines.
| Leading Market Players |
|---|
| Epic Systems Corporation |
| Oracle Health |
| Athenahealth |
| Veradigm |
| eClinicalWorks |
| Optum |
| Health Catalyst |
| NextGen Healthcare |
| Arcadia |
| Others |
Value Network & Pricing Analysis
Machine learning engineer concentration in the San Francisco Bay Area and Boston corridor drives labor-cost differentials that widen pricing-tier spreads between premium analytics modules and standard care management dashboards.
Pricing Analysis
Capacity additions in India and Eastern Europe are reshaping price floors for implementation services and data pipeline development. Subscription-based SaaS licensing dominates, with three-tier pricing structure across premium, standard, and economy levels differentiated by FHIR API volume and NLP processing depth. Pricing pressure stems from hyperscale cloud provider consolidation forcing mid-size health systems toward bundled infrastructure-software contracts. Payer organizations exhibit highest price sensitivity due to per-member-per-month margin constraints, while government agencies show lowest sensitivity given mandated compliance requirements.
Supply Chain Analysis
Direct-to-provider channels handle enterprise health system demand, while value-added resellers serve mid-market physician networks. Cloud infrastructure concentrates in the United States, Ireland, and Singapore. Software development draws from specialized health informatics talent pools and FHIR-certified integration engineers. Supply chain risk centers on single-source hyperscale provider dependency for HIPAA-compliant multi-tenant architectures. Distribution runs through certified implementation partners with Epic Systems and Oracle Health credentials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Population health management platforms function as stable compounders, with CMS value-based reimbursement mandates providing durable demand visibility across economic cycles.
For Market Incumbents: Deepen vertical integration into social determinants data layers and remote patient monitoring hardware to preempt pure-play specialists. Anchor risk stratification workflows within dominant EHR install bases to raise switching costs for provider networks. Invest in federated learning architectures to defend against cloud-native entrants with privacy-preserving capabilities.
For New Entrants and Emerging Players: Capture Medicaid-focused community health worker enablement segments where legacy platforms lack mobile-first penetration. Target behavioral health convergence workflows as the most penetrable application area under Medicare Advantage star rating incentives. Pursue channel partnerships with federally qualified health centers as the primary go-to-market angle.
For Investors and Strategic Acquirers: Health system technology divisions are the most active acquirer in this space, consolidating point-solution vendors into integrated platforms. Long-term viability favors proprietary data operating systems with cross-source normalization capabilities. Watch FDA finalization of software-as-a-medical-device guidance as the critical inflection signal for algorithmic clinical decision support deployment velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| FHIR API Certification Investment | CMS interoperability mandates under the 21st Century Cures Act Final Rule compel standardized data exchange capabilities. |
| Social Determinants Data Partnership | Housing instability and food security layers from community organizations enhance predictive readmission risk models. |
| Cloud Infrastructure Diversification | Multi-cloud architectures mitigate single-point-of-failure exposure from hyperscale provider concentration. |
| Natural Language Processing Module Development | Unstructured clinical notes integration unlocks undocumented comorbidities for automated care gap closure. |
| Subscription Pricing Model Transition | Per-member-per-month structures align vendor incentives with payer quality metric improvements under value-based contracts. |
Research Methodology
Direct dialogue with hospital CIOs, payer technology officers, health informatics directors, and CMS policy specialists combined with secondary validation from hospital procurement databases, GPO contracts, CMS Medicare Shared Savings Program filings, and FDA software guidance documents. Bottom-up and top-down triangulation reconciled vendor-reported deployments with health system contract disclosures.
Segment-level value outputs across the projection horizon reflect modeled adoption curves for cloud-based versus on-premises deployment, provider versus payer end-user economics, and chronic disease management versus preventive care application maturity. CAGRs derive from fitted logistic growth curves incorporating CMS reimbursement timeline assumptions and HL7 FHIR adoption saturation patterns. Industry-specific inputs include Medicare Advantage star rating incentive structures and state-level all-payer claims database mandate progressions.
Underlying measurement precision varies by segment; cloud-based deployment and chronic disease management carry tighter precision than emerging health promotion applications. Forecasts reflect documented assumptions regarding CMS program continuity and interoperability enforcement intensity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Data Management
Point of Care (POC) Data Management Systems Market
Health Data Management
Global Healthcare Data Analytics Market
Health Data Management
AI Training Dataset in Healthcare Market
Health Data Management
Global Chronic Care Management Software Market
Health Data Management
Global Healthcare Quality Management Market
Health Data Management
Europe Healthcare Analytics Market
Health Data Management
Wireless Healthcare Asset Management Market
Health Data Management
Global Healthcare Financial Analytics Market
Health Data Management
Healthcare Predictive Analytics Market
Health Data Management
Healthcare Data Monetization Solutions Market
Health Data Management
Europe Healthcare Big Data Analytics Market
Health Data Management
Global Healthcare Data Storage Market
Health Data Management
Population Health Management Solutions Market
Health Data Management
North America Healthcare Analytics Market
Health Data Management
Healthcare Data Interoperability Market
Health Data Management
Clinical Data Management Systems (CDMS) Market