
 US Mobile Health Market | 2026-2036
US Mobile Health Market Size, Share, and Industry Trends Forecast 2026-2036
US Mobile Health Market Outlook
End-user demand is shifting from fitness enthusiasts toward healthcare providers and corporate wellness programs as reimbursement pathways mature. Teladoc Health anchors virtual care infrastructure across employer-sponsored plans. Medtronic dominates connected cardiac devices through in-house production of glucose monitoring sensors. Abbott differentiates its Libre ecosystem with pharmacy channel control.
Mobile health encompasses software-enabled medical services delivered through smartphones, tablets, and connected peripherals operating on iOS and Android architectures with Bluetooth Low Energy and cellular connectivity protocols. The primary commercial purpose centers on decentralizing diagnostics, enabling continuous biometric capture, and reducing acute care utilization. Chronic disease management leads application revenue as hypertension and diabetes programs secure durable CMS billing codes. Wearables capture expanding margin pools as FDA-cleared devices command premium subscription pricing. Telehealth platforms mature into commodity infrastructure while remote monitoring devices sustain hardware replacement cycles.
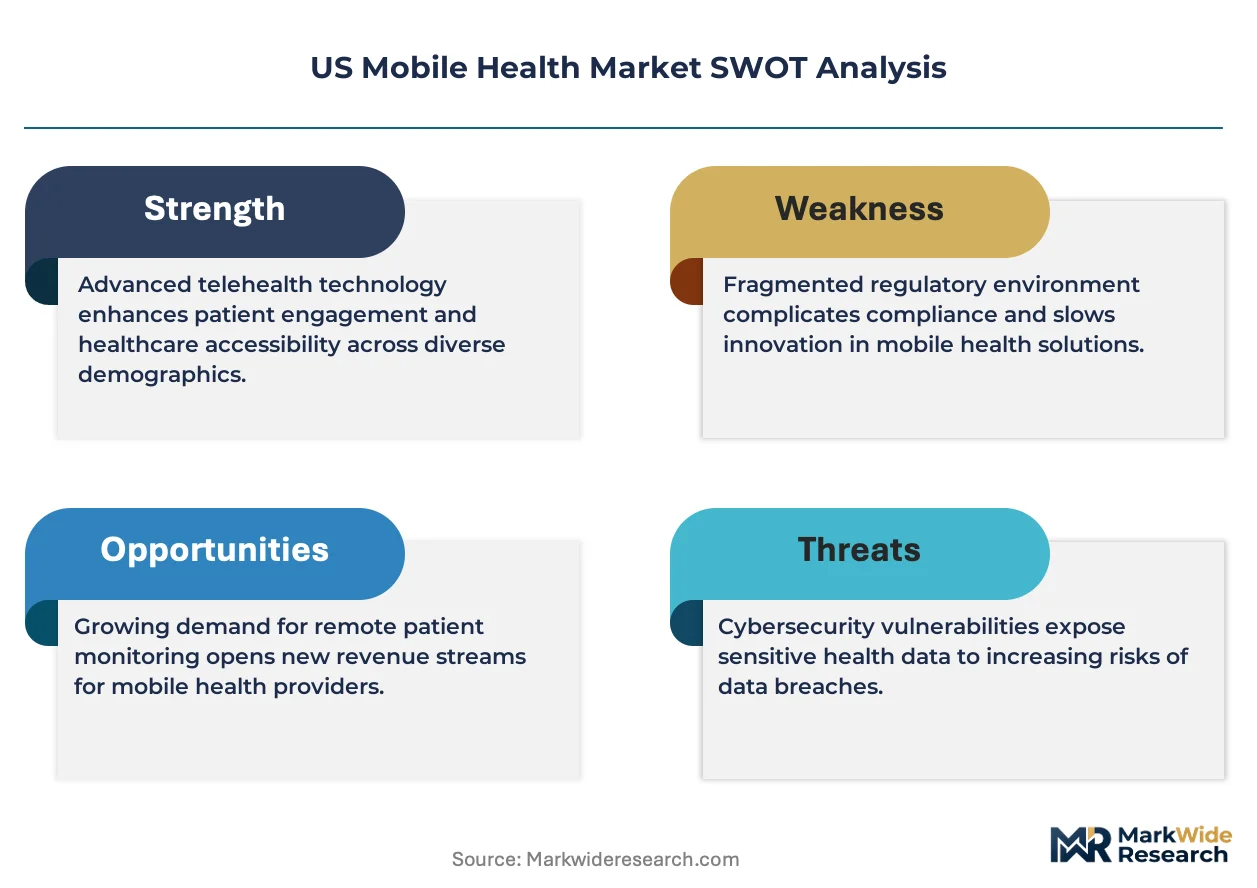
FDA digital health pre-certification, CMS remote therapeutic monitoring reimbursement rules, and HIPAA security frameworks collectively determine product viability and market access velocity. The FDA's software-as-medical-device pathway accelerates clearance timelines for algorithm-driven diagnostics. Stakeholders must monitor evolving state-level telehealth parity laws and prescribing regulations that fragment commercial deployment across Texas, Florida, and New York.
Market Dynamics
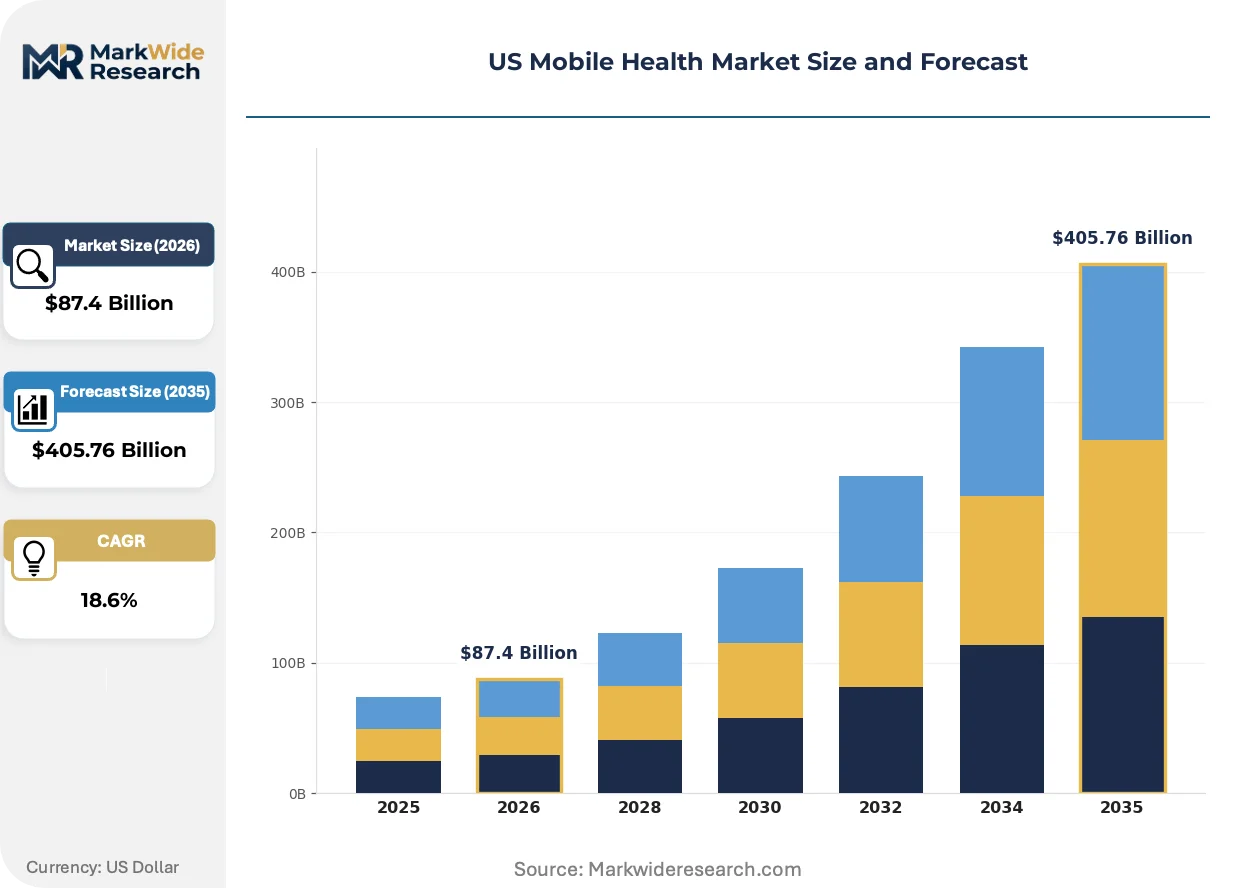
CMS reimbursement codes for remote patient monitoring are restructuring provider economics and accelerating capital deployment into connected diagnostic infrastructure across Medicare Advantage networks.
Growth Catalysts
- Remote Therapeutic Monitoring:CMS billing codes for respiratory and musculoskeletal monitoring are expanding reimbursable service categories beyond traditional remote patient monitoring, pulling new provider specialties into digital health adoption.
- Bluetooth Low Energy protocols:Standardized connectivity architectures are reducing device integration costs for health systems deploying multi-vendor biometric ecosystems.
- Medicare Advantage chronic disease management:Risk-adjusted capitation models are incentivizing plans to invest in continuous glucose monitoring and hypertension management applications to reduce acute utilization.
Market Restraints
- Sensor supply concentration:Precision photodiode and MEMS accelerometer production clusters in Taiwan and South Korea create single-source vulnerability for wearable device manufacturers.
- HIPAA compliance infrastructure:Encryption and audit-log requirements for protected health information impose fixed cost barriers for sub-scale software vendors entering clinical workflows.
- State-level telehealth parity fragmentation:Inconsistent prescribing authority and reimbursement rules across Texas, Florida, and New York force redundant regulatory compliance architectures.
Strategic Opportunities
- Behavioral health integration:FDA digital health pre-certification pathways for cognitive behavioral therapy applications are opening reimbursement channels previously restricted to in-person psychiatric services.
- Pharmacy channel control:Direct distribution through CVS Health and Walgreens networks bypasses traditional durable medical equipment intermediaries, capturing margin previously lost to third-party logistics.
- AI-driven diagnostic algorithms:Machine learning pattern recognition for atrial fibrillation detection is automating preliminary ECG interpretation, extending cardiologist capacity into underserved rural counties.
Industry Challenges
- Interoperability standards fragmentation:Competing data exchange protocols between Epic, Cerner, and Meditech systems force custom integration engineering for each health system deployment.
- FDA 510(k) clearance timelines:Software-as-medical-device submissions for algorithm updates require resubmission cycles that compress product iteration velocity relative to consumer technology benchmarks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Mobile Health Market |
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $405.76 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Apps, Wearables, Telehealth Platforms, Remote Monitoring Devices End User: Patients, Healthcare Providers, Fitness Enthusiasts, Corporate Wellness Programs Application: Chronic Disease Management, Fitness Tracking, Medication Adherence, Mental Health Support Delivery Model: Subscription-Based, One-Time Purchase, Freemium, Pay-Per-Use |
| Companies Covered | Apple Inc., Google Inc., Samsung Electronics, AT&T, Medtronic, Koninklijke Philips, Boston Scientific, Teladoc Health, Abbott, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Mobile Health Market Strategic Shifts
Algorithmic diagnostic tools are compressing the gap between consumer wearables and clinical-grade monitoring, forcing recalibration of regulatory frameworks and reimbursement boundaries.
Continuous glucose monitoring is automating insulin dosing decisions through closed-loop pump integration, accelerating adoption among Type 1 diabetes patients in integrated delivery networks. Endocrinology practices in California and Massachusetts are deploying these systems at scale, reducing HbA1c variability and emergency department admissions for hypoglycemic events.
FDA digital health pre-certification is streamlining clearance pathways for companies with established quality management systems, compressing time-to-market for algorithm-driven diagnostics. The software-as-medical-device pathway most directly affects cardiovascular monitoring applications, where developers are restructuring submission strategies around real-world performance data rather than traditional clinical trial architectures.
Employer-sponsored plans are consolidating virtual care procurement around single-vendor platforms, displacing point-solution telehealth contracts. Benefits administrators at Fortune 500 companies are bundling primary care, mental health, and chronic condition management into integrated subscriptions, with the procurement shift most visible in technology and financial services sectors concentrated in the San Francisco Bay Area and Manhattan.
US Mobile Health Market Segmentation
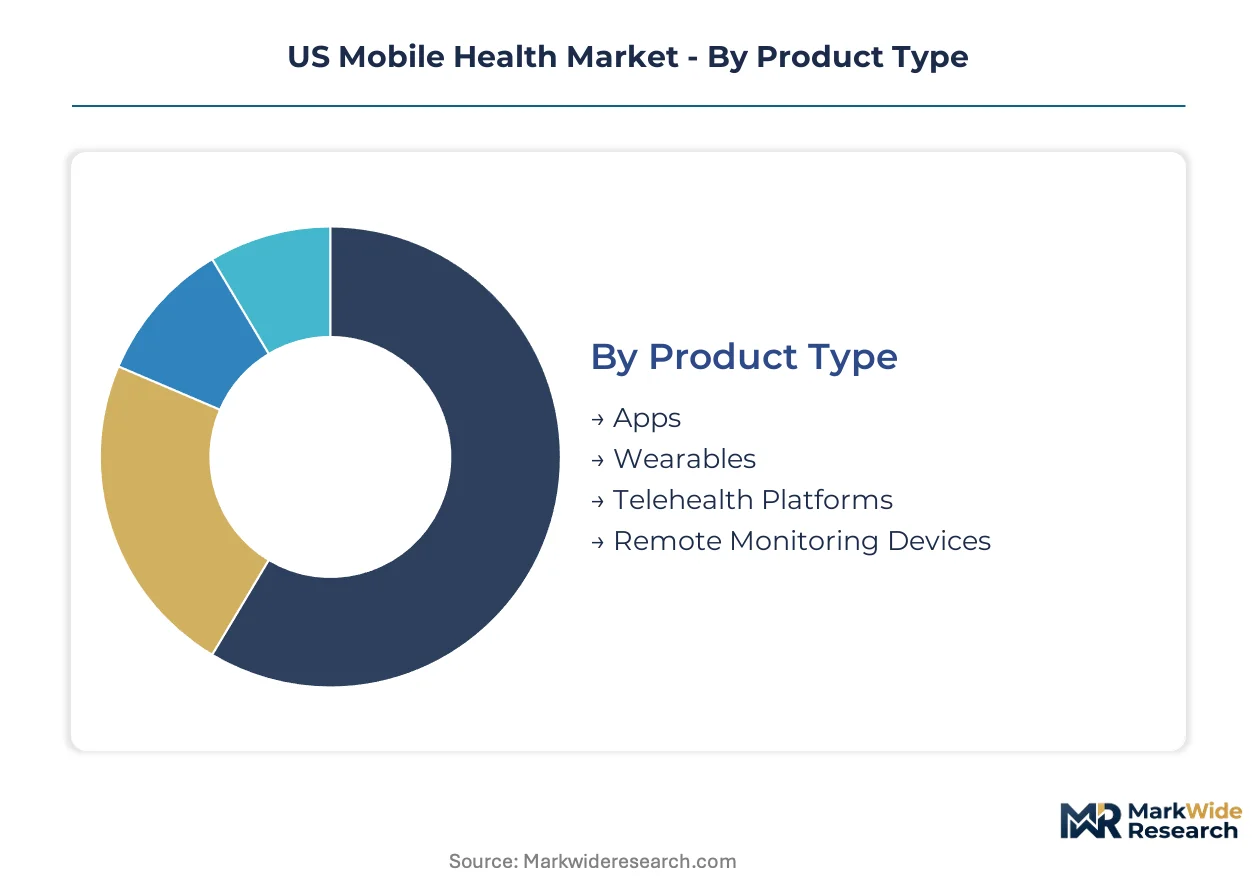
Product architecture and reimbursement pathways determine how mobile health solutions capture value across the care continuum. Segmentation reveals where FDA clearance requirements create margin premiums versus where commodity pricing dominates.
Product Type:
Purchase decisions hinge on clinical validation requirements and hardware replacement cycles.
- Wearables:FDA-cleared biometric sensors with Bluetooth Low Energy connectivity command recurring subscription revenue from integrated delivery networks. California's digital health cluster and Massachusetts' medical device corridor concentrate manufacturing and early adoption.
- Remote Monitoring Devices:Cellular-connected diagnostic peripherals capture continuous data streams for CMS-reimbursed remote patient monitoring programs. Medicare Advantage plans in Florida and Texas drive volume deployment for hypertension and diabetes management.
- Apps:Software-only solutions face margin compression from platform dependency on iOS and Android architectures.
- Telehealth Platforms:Video consultation infrastructure matures toward commodity pricing as employer-sponsored plans consolidate procurement.
Wearables lead on scale; remote monitoring devices lead on momentum.
End User:
Reimbursement pathway maturity determines which customer segments sustain premium pricing.
- Healthcare Providers:Hospital systems and physician practices purchase FDA-cleared devices through group purchasing organizations, with procurement concentrated in Medicare Advantage networks seeking risk-adjusted capitation benefits.
- Corporate Wellness Programs:Fortune 500 benefits administrators in the San Francisco Bay Area and Manhattan bundle subscriptions for integrated virtual care platforms.
- Patients:Direct-to-consumer purchases concentrate in chronic disease populations seeking continuous glucose monitoring and hypertension tracking outside traditional clinical workflows.
- Fitness Enthusiasts:Consumer wearable demand shifts toward clinical-grade features as algorithm accuracy improves, though this segment faces pricing pressure from unregulated wellness applications.
Healthcare providers anchor current revenue; corporate wellness programs climb the fastest.
Application:
Clinical outcome measurability determines which use cases secure durable reimbursement codes.
- Chronic Disease Management:Diabetes and hypertension programs leverage established CMS billing codes for remote therapeutic monitoring, with endocrinology practices in California deploying closed-loop insulin systems at scale.
- Mental Health Support:FDA pre-certification pathways for cognitive behavioral therapy applications expand reimbursable service categories into digital psychiatric care.
- Medication Adherence:Smart pill dispensers and reminder systems integrate with pharmacy benefit managers, though reimbursement remains fragmented across state Medicaid programs.
- Fitness Tracking:Consumer activity monitoring faces margin erosion as basic step-counting commoditizes, forcing differentiation toward clinical-grade biometric accuracy.
Chronic disease management leads on scale; mental health support leads on momentum.
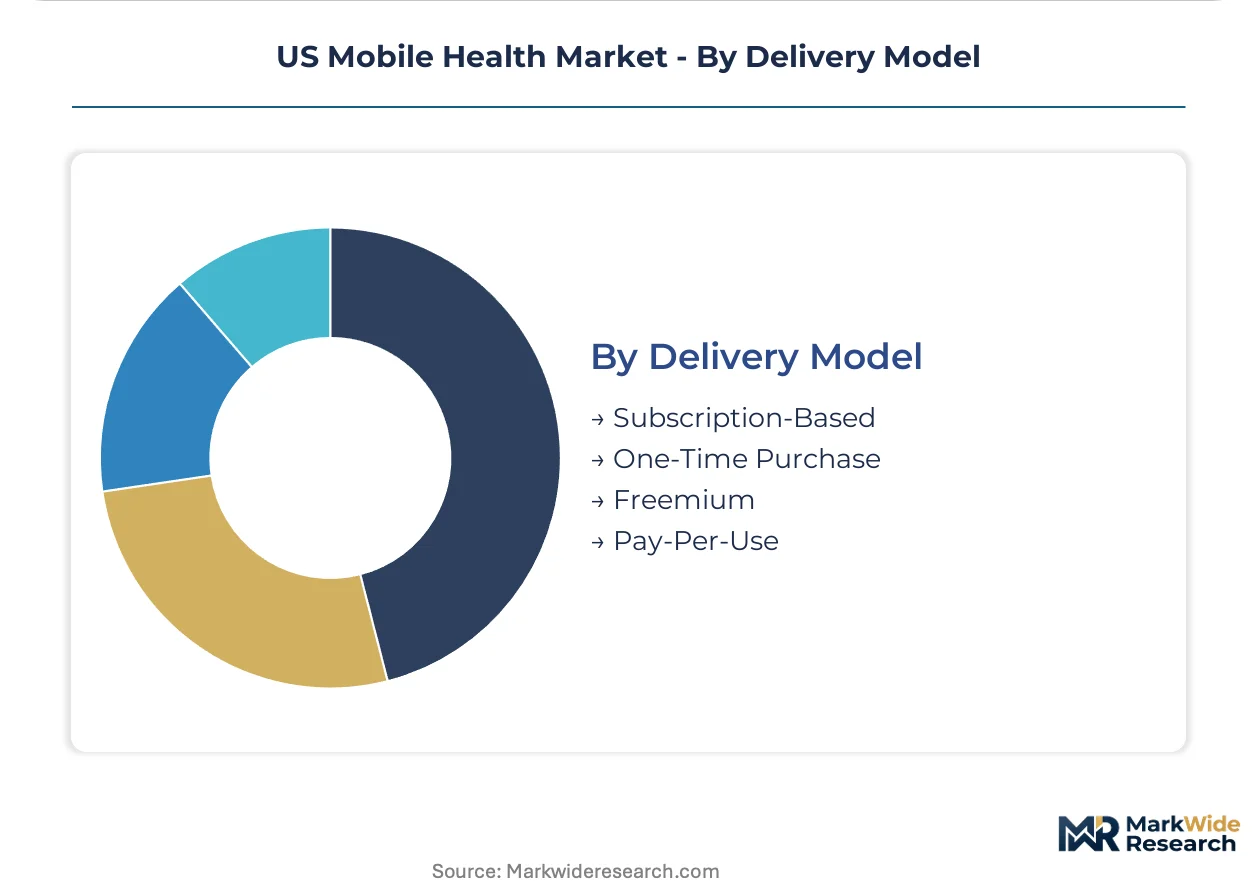
Delivery Model:
Customer lifetime value and acquisition cost economics vary sharply across pricing architectures.
- Subscription-Based:Monthly recurring revenue models dominate connected device ecosystems, with hardware subsidies recovered through multi-year service commitments from Medicare Advantage plans.
- Freemium:Basic feature tiers drive user acquisition for mental health and fitness applications, with conversion to paid clinical services concentrated among diagnosed chronic disease populations.
- Pay-Per-Use:On-demand telehealth consultations face pricing pressure as employer plans shift toward bundled per-member-per-month contracts.
- One-Time Purchase:Upfront hardware sales persist for non-connected wellness devices, though this model loses share to recurring revenue alternatives.
Subscription-based models lead on scale; freemium architectures gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping mobile health deployment as FDA digital health pre-certification accelerates clearance timelines relative to European EMA pathways, drawing algorithm-driven diagnostic development toward US jurisdictions while hardware manufacturing concentrates in established medical device corridors seeking proximity to reimbursement decision-makers.
California
Silicon Valley's digital health cluster anchors software-enabled diagnostic development, with FDA software-as-medical-device submissions flowing through San Francisco-based quality management systems. CMS remote therapeutic monitoring reimbursement rules are pulling venture deployment into continuous glucose monitoring platforms. Endocrinology practices in Stanford's integrated delivery network deploy closed-loop insulin systems at scale.
Massachusetts
Greater Boston's medical device corridor concentrates connected cardiac device manufacturing, with Bluetooth Low Energy protocol standardization reducing integration costs for multi-vendor biometric ecosystems. FDA 510(k) clearance timelines compress product iteration for algorithm-driven cardiovascular monitoring. MIT-connected startups populate Kendall Square with remote patient monitoring hardware development.
Texas
Medicare Advantage networks in Houston and Dallas drive volume deployment for hypertension management applications, with risk-adjusted capitation models incentivizing continuous biometric capture. State-level telehealth parity laws fragment prescribing authority relative to federal benchmarks. Austin's emerging digital health cluster attracts corporate wellness platform development for employer-sponsored plans.
Florida
Retiree-dense Medicare Advantage markets in Miami and Tampa accelerate remote monitoring device adoption for diabetes and respiratory management. CMS billing codes for remote patient monitoring restructure provider economics across hospital systems. Jacksonville's logistics infrastructure supports pharmacy channel distribution for connected diagnostic peripherals.
New York
Manhattan's employer-sponsored plan concentration consolidates virtual care procurement around integrated platforms bundling primary care and mental health services. State prescribing regulations impose redundant compliance architectures relative to neighboring jurisdictions. Buffalo's medical device manufacturing heritage supports sensor production for FDA-cleared wearables.
US Mobile Health Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with FDA-cleared device makers commanding premium subscription pricing while telehealth platforms commoditize toward infrastructure pricing. Market structure tilts toward consolidation at the platform layer and fragmentation among point-solution vendors. Three archetypes dominate: integrated health system vendors, consumer electronics crossovers, and pure-play remote monitoring specialists. Competitive moves center on pharmacy channel bypass strategies and AI diagnostic algorithm acquisitions.
Among consumer electronics crossovers, Apple Inc. and Google Inc. exemplify platform-scale entry into FDA-regulated health monitoring, occupying positions that leverage smartphone distribution architecture for biometric sensor integration. Samsung Electronics anchors the hardware-centric tier with connected device manufacturing capabilities. Teladoc Health represents the virtual care infrastructure archetype, sitting within the employer-sponsored procurement consolidation trend. Medtronic and Abbott exemplify the established medical device specialist model, with in-house sensor production and pharmacy channel control differentiating their positions in continuous glucose monitoring ecosystems.
| Leading Market Players |
|---|
| Apple Inc. |
| Google Inc. |
| Samsung Electronics |
| AT&T |
| Medtronic |
| Koninklijke Philips |
| Boston Scientific |
| Teladoc Health |
| Abbott |
| Others |
Value Chain & Pricing Dynamics
Precision photodiode costs from Taiwan and South Korea flow through FDA-cleared wearable tiers to Medicare Advantage plans, with Bluetooth Low Energy module pricing compressing mid-market remote monitoring margins while cellular-connected diagnostics sustain premium subscription recoveries.
Pricing Analysis
Pharmacy channel margins bypass traditional durable medical equipment markups, with CVS Health and Walgreens direct distribution capturing value previously lost to third-party logistics intermediaries. Three-tier pricing structure across FDA-cleared premium, clinical-grade standard, and consumer wellness economy levels reflects certification burden and reimbursement code eligibility. Pricing pressure stems from employer-sponsored plan consolidation around single-vendor virtual care platforms. Corporate wellness programs show lowest price sensitivity due to per-member-per-month bundling, while direct-to-consumer fitness applications face acute sensitivity to unregulated wellness competition.
Supply Chain Analysis
Regional distribution centers in Jacksonville and Memphis anchor pharmacy channel fulfillment for connected diagnostic peripherals, with hub-and-spoke patterns radiating toward Medicare Advantage networks in Florida and Texas. Sensor production clusters in Taiwan and South Korea feed MEMS accelerometer demand for wearable manufacturers, while domestic Buffalo facilities support FDA-cleared device assembly. Single-source vulnerability concentrates in precision photodiode supply from Taiwanese foundries. Distribution runs through GPO contracts to hospital systems and direct-to-plan arrangements for remote patient monitoring programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
US mobile health has entered a late-cycle quality phase where FDA pre-certification and CMS reimbursement code access separate sustainable margin pools from commoditizing telehealth infrastructure, with demand tilting toward closed-loop insulin systems and algorithm-driven cardiovascular monitoring.
For Market Incumbents: Cement defensible positions through in-house glucose sensor production and pharmacy channel control, countering consumer electronics crossovers leveraging smartphone distribution architecture. Prioritize backward integration into Bluetooth Low Energy module supply to reduce Taiwan and South Korea dependency. Lock in multi-year Medicare Advantage remote therapeutic monitoring contracts before employer-sponsored plan consolidation accelerates. For New Entrants and Emerging Players: Begin with behavioral health integration white space, where FDA pre-certification pathways for cognitive behavioral therapy applications remain underdeveloped relative to chronic disease management saturation. Target mental health support segments in Texas and New York where state-level prescribing regulations create compliance moats against platform incumbents. Pursue direct-to-employer sales bypassing health system procurement committees. For Investors and Strategic Acquirers: Roll-up economics work for remote monitoring hardware specialists because Medicare Advantage risk-adjusted capitation creates durable recurring revenue visibility independent of telehealth commodity pricing. Focus acquisition screens on FDA-cleared device makers with established CMS billing code portfolios rather than software-only platforms. Watch for AI-driven diagnostic algorithm FDA submission volume as inflection signal for cardiologist capacity extension plays.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Digital Health Pre-Certification | Accelerates clearance timelines for algorithm-driven diagnostics at established quality management system companies. |
| CMS Reimbursement Strategy | Secures remote therapeutic monitoring billing codes that pull new provider specialties into adoption. |
| Hospital System Partnership | Locks in group purchasing organization procurement for integrated delivery network deployments. |
| Software Companion Development | Enables closed-loop insulin automation that reduces HbA1c variability in Type 1 diabetes populations. |
| Pharmacy Channel Expansion | Bypasses durable medical equipment intermediaries through CVS Health and Walgreens distribution control. |
Study Parameters
Multiple input streams — executive interviews with digital health CTOs, hospital purchasing committee deliberations, and biomedical engineer workflow assessments — were reconciled against CMS Medicare reimbursement databases, FDA 510(k) submission records, and GPO contract filings. Secondary validation drew from hospital procurement databases, employer benefits administrator surveys, and connected device shipment manifests. Bottom-up segmentation modeling and top-down market sizing triangulated around revenue recognition patterns across subscription and hardware transaction archetypes.
Historical revenue trajectories were cross-referenced against panel input from Medicare Advantage plan medical directors and corporate wellness benefits administrators to anchor projection assumptions across the analysis window. Segmentation dimensions spanned product type, end user archetype, clinical application, and delivery model pricing architecture. CAGRs were derived from fitted growth curves calibrated to FDA clearance velocity and CMS code expansion schedules, with remote patient monitoring device replacement cycles and telehealth platform consolidation rates serving as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including unannounced FDA guidance revisions, state-level telehealth parity law changes, and sensor supply disruptions from Taiwan Strait logistics. Forecasts reflect documented assumptions around Medicare Advantage penetration curves and employer-sponsored plan procurement consolidation timing. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Data Management
Population Health Management Solutions Market
Health Data Management
Patient Data Management Software Market
Health Data Management
Global Healthcare Financial Analytics Market
Health Data Management
Healthcare Predictive Analytics Market
Health Data Management
Global Healthcare Fraud Analytics Market
Health Data Management
Healthcare Data Collection and Labeling Market
Health Data Management
Global Healthcare Data Storage Market
Health Data Management
Global Chronic Care Management Software Market
Health Data Management
Healthcare Data Integration Market
Health Data Management
Data Monetization in Healthcare Market
Health Data Management
Europe Healthcare Analytics Market
Health Data Management
Global Healthcare Customer Data Platform Market
Health Data Management
Population Health Management Platforms Market
Health Data Management
Point of Care (POC) Data Management Systems Market
Health Data Management
Global Healthcare Content Management System Market
Health Data Management
Hospital Management Software Market