
 Asia Pacific Healthcare Archiving and Ediscovery Market | 2026-2036
Asia Pacific Healthcare Archiving and Ediscovery Market Size, Share, and Industry Trends Forecast 2026-2036
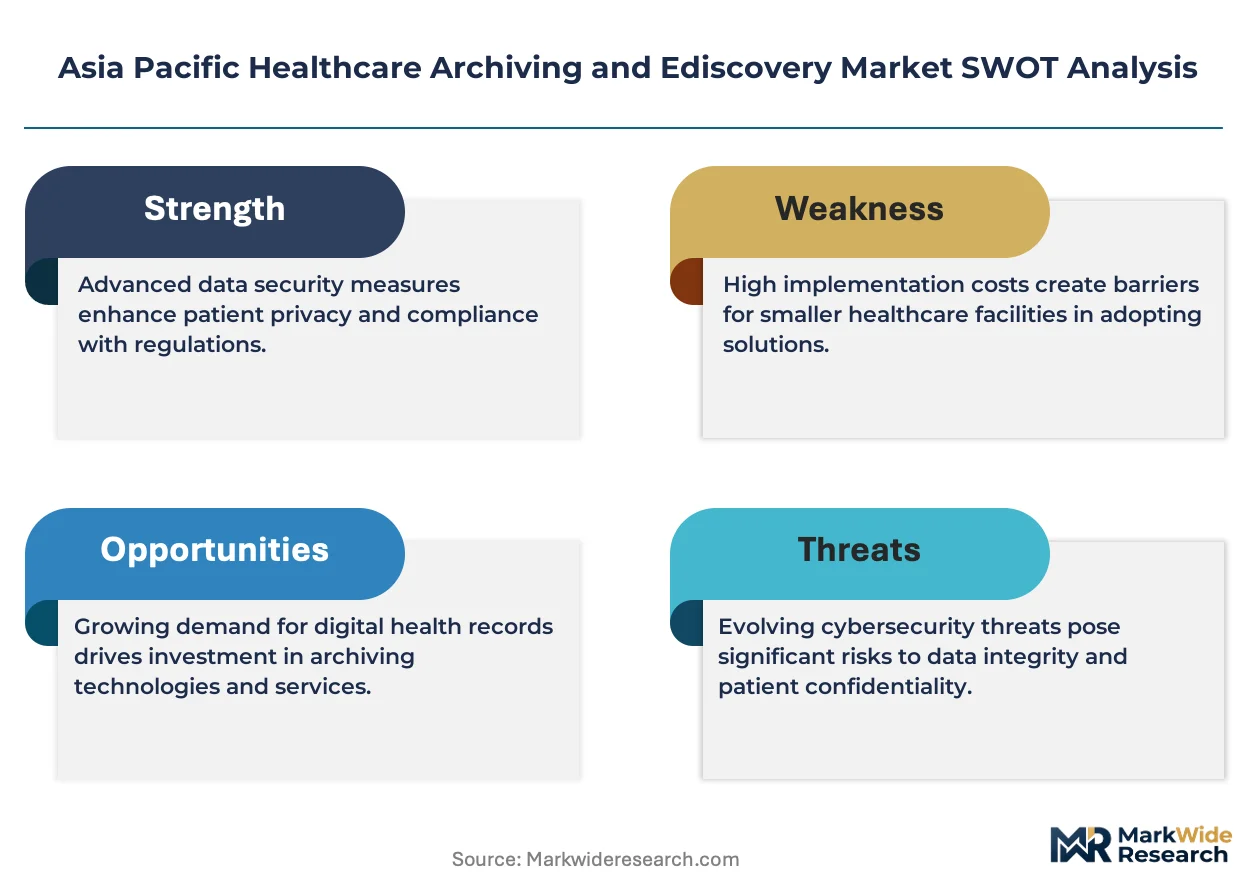
Asia Pacific Healthcare Archiving and Ediscovery Market Analysis
The capability gap between cloud-native specialists and legacy on-premise vendors is unwinding competitive dynamics across the region. IBM Corporation leverages its hybrid cloud architecture to anchor large hospital consortiums in Australia and Japan. Microsoft Corporation competes through Azure-based compliance integrations that sustain recurring revenue from multi-site clinic networks. Commvault Systems specializes in data management layers that dominate mid-tier laboratory chains seeking granular retention policies.
Healthcare archiving and ediscovery encompasses the systematic retention, indexing, and legally defensible retrieval of electronic health records, diagnostic images, and clinical communications, typically governed by retention periods spanning seven to twenty-five years depending on jurisdiction and record type. Its primary purpose is to enable regulatory compliance, litigation readiness, and operational continuity across distributed care delivery networks. Ediscovery software and cloud-based deployment models are capturing disproportionate investment as margin pools shift toward subscription architectures that reduce capital expenditure for hospitals and clinics. On-premise installations retain share in laboratories with stringent data sovereignty requirements, though hybrid configurations are emerging as the default compromise for health insurance providers balancing cost and control.
Japan's PMDA electronic record guidelines, Australia's Privacy Act amendments, and India's Digital Information Security in Healthcare Act collectively elevate data governance standards and compel provider investment in auditable archiving infrastructure. These frameworks create compliance-driven demand that favors vendors with pre-certified platforms and localized data residency options. Stakeholders must monitor evolving cross-border data flow restrictions and assess whether their current architectures can adapt to forthcoming interoperability mandates without disruptive migration costs.
Market Dynamics
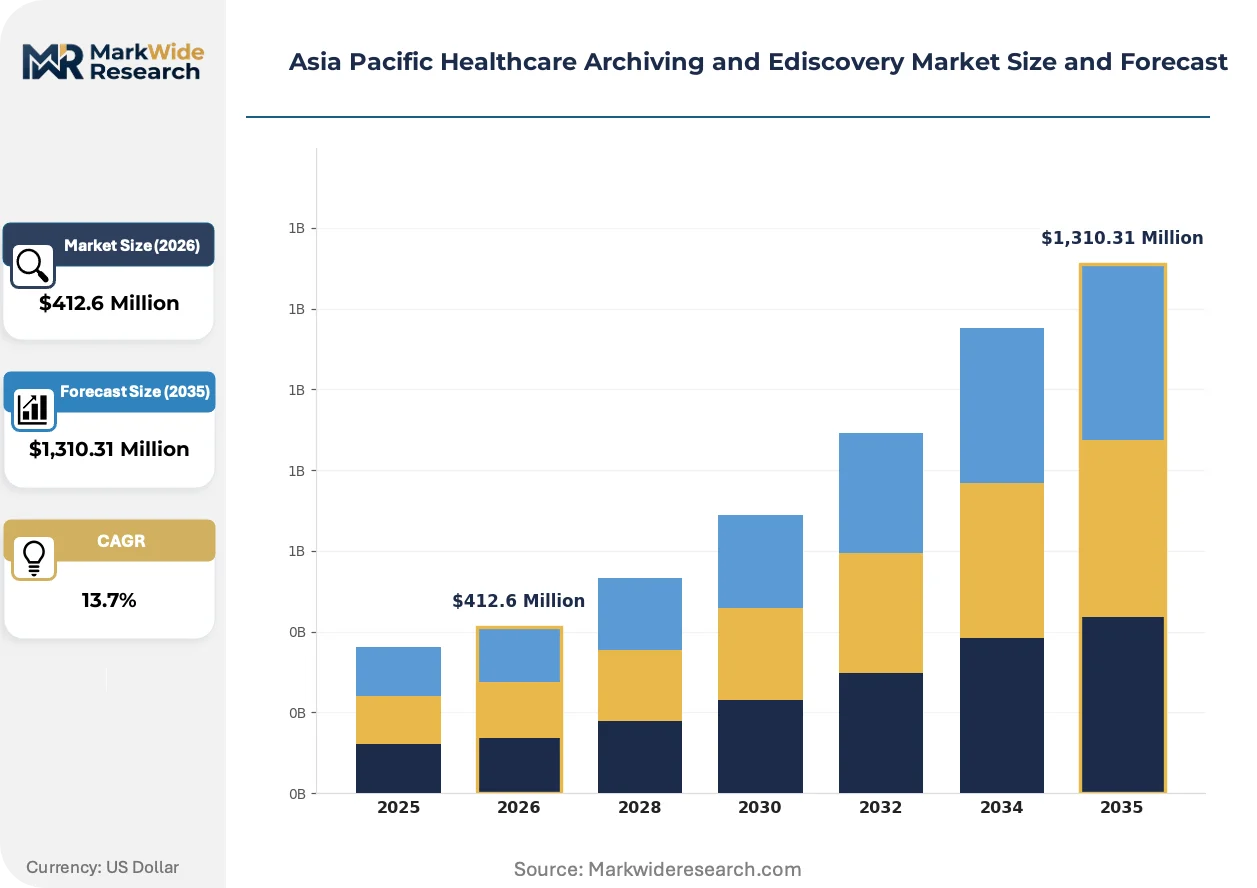
Hybrid cloud architectures are collapsing the traditional boundary between on-premise data sovereignty and subscription-based operational flexibility across Asia Pacific hospital networks. Japan's PMDA electronic record guidelines and Australia's Privacy Act amendments are forcing infrastructure decisions that favor vendors with pre-certified platforms and localized data residency capabilities.
Growth Catalysts
- PMDA electronic record guidelines:Japan's pharmaceutical and medical device agency mandates auditable archiving infrastructure with twenty-five-year retention periods, compelling hospital consortiums to replace legacy tape systems with compliant cloud-native platforms.
- Diagnostic imaging proliferation:PET-CT and MRI scan volumes across India's tier-1 hospital chains are generating petabyte-scale storage requirements that exceed on-premise capacity and drive managed service adoption.
- Cross-border telemedicine:Southeast Asian health networks serving medical tourism corridors require interoperable record exchange between Singapore, Thailand, and Malaysia, creating demand for standardized ediscovery protocols.
Market Restraints
- Data sovereignty compliance costs:Australia's mandatory data breach notification regime and India's Digital Information Security in Healthcare Act impose localization requirements that fragment cloud economies of scale and inflate infrastructure expenditure for multinational vendors.
- Specialized technical talent scarcity:Health informatics professionals capable of bridging clinical workflows with forensic data retrieval protocols command premium compensation in Sydney, Tokyo, and Bangalore, constraining mid-tier provider expansion.
- Legacy system entrenchment:Decades-old hospital information systems in South Korea's public health network resist API-based integration, forcing expensive middleware layers that erode cloud migration business cases.
Strategic Opportunities
- Vietnam's hospital digitization wave:Ho Chi Minh City and Hanoi's emerging private hospital chains lack entrenched vendor relationships, creating first-mover advantage for platforms offering Vietnamese-language compliance dashboards.
- AI-assisted ediscovery convergence:Natural language processing engines trained on clinical terminology are reducing document review timelines from weeks to days, enabling premium pricing for litigation-ready archiving services.
- Indonesia's national health insurance expansion:BPJS Kesehatan's growing claims dispute volume requires defensible audit trails, opening subscription revenue from regional clinic networks previously outside the addressable market.
Industry Challenges
- Forensic chain-of-custody certification:ISO 27037-compliant evidence handling requires specialized personnel training and procedural documentation that most regional IT service providers lack, narrowing the qualified vendor pool.
- Multi-jurisdictional retention conflict:Australian twenty-year oncology record requirements clash with Singapore's seven-year standard for outpatient records, forcing complex policy engines that increase implementation risk.
- Interoperability standard fragmentation:HL7 FHIR adoption varies across Japan's prefectural health systems, complicating regional archive consolidation projects and delaying revenue recognition for platform vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Healthcare Archiving and Ediscovery Market |
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $1,310.31 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Data Archiving, Ediscovery Software, Compliance Solutions, Data Management End User: Hospitals, Clinics, Laboratories, Health Insurance Providers Deployment Model: Cloud-Based, On-Premise, Hybrid, SaaS Compliance Standard: HIPAA, GDPR, HITECH, ISO 27001 |
| Companies Covered | IBM Corporation, Microsoft Corporation, Allscripts, GE Healthcare, Siemens Healthineers, Barracuda Networks, Actiance, Commvault Systems, Global Relay Communications, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Healthcare Archiving and Ediscovery Market Emerging Trajectories
Containerized microservices architectures are fragmenting monolithic health record platforms into composable compliance modules. Vendors are repositioning around specific regulatory jurisdictions rather than geographic expansion, while hospital procurement committees are weighting data portability guarantees above upfront licensing costs.
Immutable object storage with blockchain-anchored integrity proofs is decomposing the traditional tape-backup paradigm for long-term clinical record retention. Australia's major pathology networks are piloting these systems for medico-legal defense readiness. The technology is decomposing capital-intensive on-premise silos into consumption-indexed subscription tiers that align hospital finance committee approval cycles.
Australia's Privacy Act amendments introduced mandatory notification thresholds that compress breach disclosure windows to seventy-two hours. Healthcare providers now require real-time anomaly detection layered atop archival systems. The laboratory segment is responding fastest, with Melbourne and Sydney-based chains deploying automated classification engines that flag potential breaches before regulatory exposure crystallizes.
Hospital procurement committees are unbundling after-sales technical support from core platform licenses and competitively tendering these services separately. Singapore's public hospital clusters pioneered this practice, and the model is spreading to Kuala Lumpur and Bangkok private networks. The shift is most visible in diagnostic imaging archives, where specialized DICOM retrieval expertise commands standalone pricing power.
Asia Pacific Healthcare Archiving and Ediscovery Market Segmentation
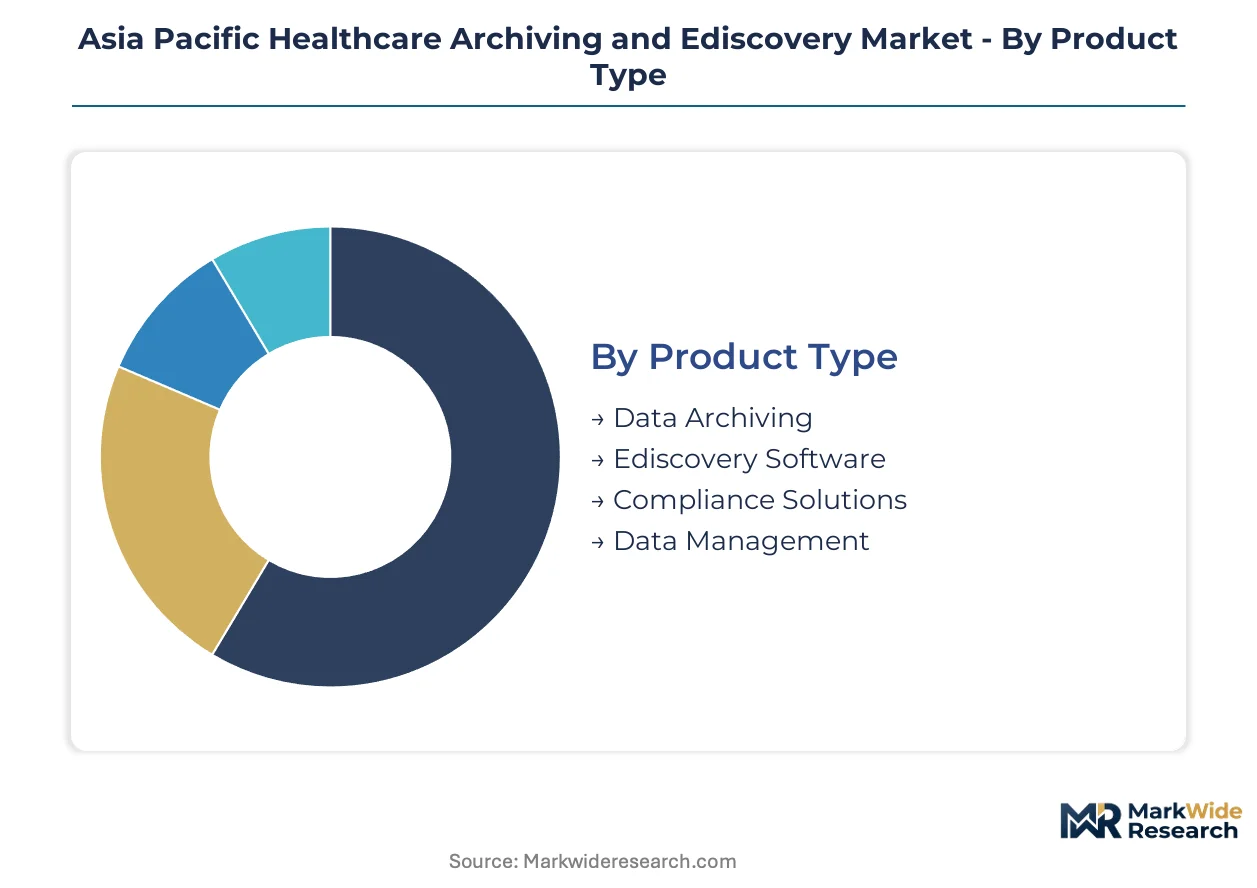
Healthcare archiving and ediscovery segmentation reveals how procurement committees weight regulatory mandates against infrastructure constraints. Vendors must align product architectures with jurisdiction-specific retention periods and data sovereignty requirements.
Product Type:
Regulatory differentiation separates commodity storage from premium ediscovery platforms that carry pre-certification for PMDA and TGA audit protocols.
- Data Archiving:Immutable storage systems with blockchain-anchored integrity proofs anchor long-term clinical record retention. Australia's pathology networks deploy these for twenty-year oncology record mandates. Tape-backup paradigms decompose as hospitals shift to consumption-indexed subscription tiers.
- Ediscovery Software:Natural language processing engines trained on clinical terminology compress document review timelines from weeks to days. Litigation-ready archiving services command premium pricing in Singapore and Sydney where medical malpractice dispute volumes are climbing.
- Compliance Solutions:Pre-certified platforms with localized data residency capabilities capture procurement preference in Japan and Australia.
- Data Management:Granular retention policy engines address multi-jurisdictional conflicts between Australian twenty-year and Singapore seven-year standards.
Data Archiving handles the majority of throughput; Ediscovery Software is expanding most quickly on share.
End User:
Cost tier stratification concentrates investment in hospital consortiums with capital committee approval for multi-year cloud migrations.
- Hospitals:Tier-1 chains across India and Southeast Asia generate petabyte-scale storage requirements from diagnostic imaging proliferation. Melbourne and Sydney public hospital clusters unbundle after-sales technical support from core licenses and tender separately.
- Clinics:Multi-site networks in Kuala Lumpur and Bangkok favor subscription architectures that reduce capital expenditure. Vietnamese-language compliance dashboards attract first-mover advantage in Ho Chi Minh City and Hanoi.
- Laboratories:Mid-tier chains seek granular retention policies with DICOM retrieval expertise commanding standalone pricing power.
- Health Insurance Providers:BPJS Kesehatan's claims dispute volume in Indonesia requires defensible audit trails from regional clinic networks.
Hospitals absorb the dominant share of platform investment; Health Insurance Providers are climbing the fastest as claims digitization accelerates.
Deployment Model:
Volume concentration shifts toward hybrid configurations that balance data sovereignty requirements against operational flexibility.
- Cloud-Based:Azure-based compliance integrations sustain recurring revenue from multi-site clinic networks. Real-time anomaly detection layers address Australia's seventy-two-hour breach disclosure windows.
- On-Premise:Laboratories with stringent data sovereignty requirements retain installed base despite higher total cost of ownership. South Korea's public health network resists API-based integration, forcing expensive middleware.
- Hybrid:Default compromise for health insurance providers balancing cost and control across distributed care delivery networks. Japan's PMDA guidelines favor vendors with localized data residency options.
- SaaS:Containerized microservices architectures fragment monolithic platforms into composable compliance modules.
Hybrid deployments capture the majority of new infrastructure decisions; Cloud-Based models are gaining share fastest among greenfield installations.
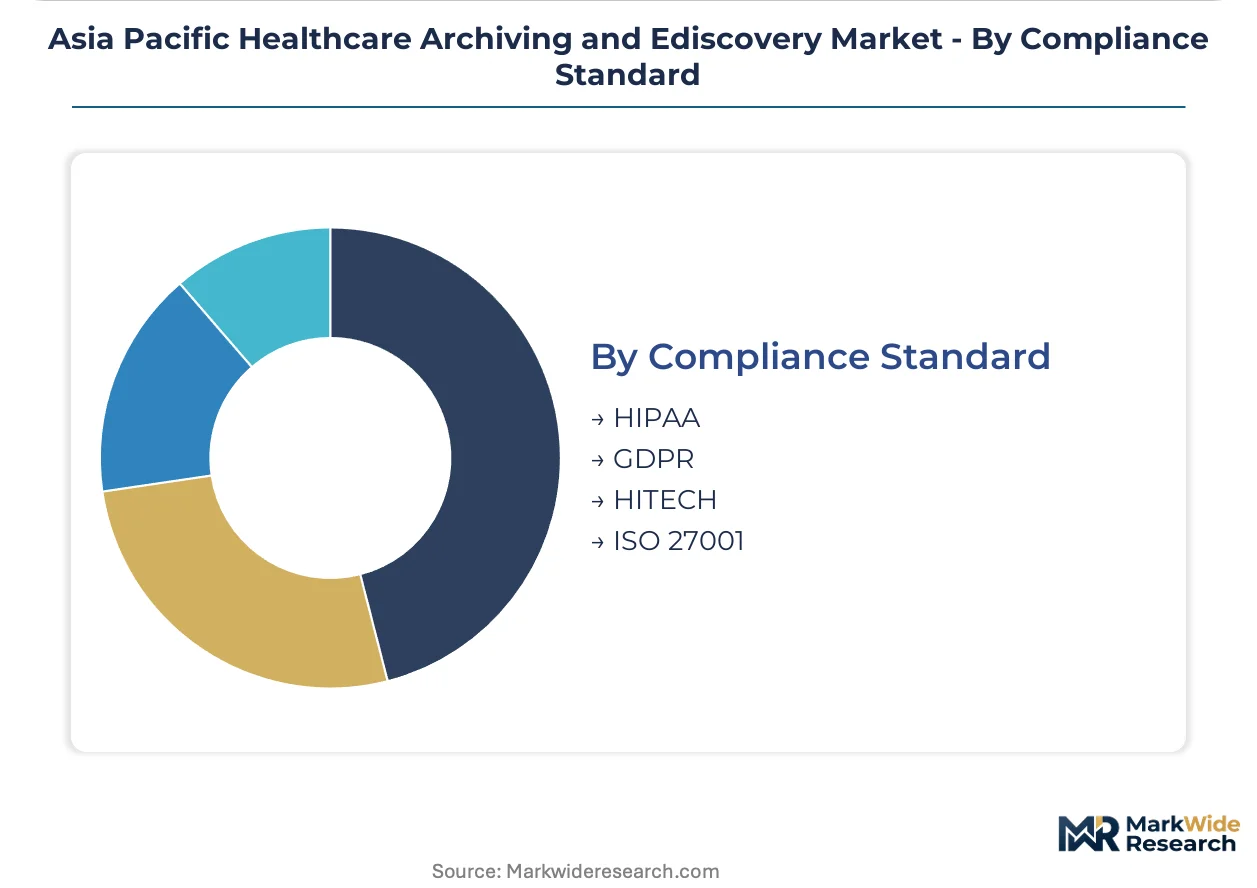
Compliance Standard:
Customer type segmentation follows certification burden, with multinational vendors fragmenting cloud economies of scale to meet localization mandates.
- HIPAA:US-origin platforms adapt for Asia Pacific medical tourism corridors requiring interoperable record exchange.
- GDPR:Cross-border telemedicine between Singapore, Thailand, and Malaysia demands standardized protocols for EU patient data.
- HITECH:Breach notification architectures influence Australia's Privacy Act amendment implementations.
- ISO 27001:Forensic chain-of-custody certification narrows the qualified vendor pool for litigation-ready services.
ISO 27001 carries the heaviest implementation burden; HIPAA-aligned platforms are penetrating fastest in medical tourism corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across the region. India's tier-1 hospital chains negotiate aggressively on per-petabyte storage costs, while Australian pathology networks prioritize forensic certification over unit economics.
Japan
PMDA electronic record guidelines mandate twenty-five-year retention periods that exceed on-premise tape capacity. Tokyo and Osaka hospital consortiums are replacing legacy systems with compliant cloud-native platforms. Kanto prefectural health networks drive regional demand for localized data residency options.
Australia
Mandatory data breach notification regimes compress disclosure windows to seventy-two hours, forcing real-time anomaly detection investments. TGA audit protocols govern pathology network procurement in Melbourne and Sydney. New South Wales laboratory chains pilot blockchain-anchored integrity proofs for medico-legal defense.
India
Diagnostic imaging proliferation across tier-1 hospital chains generates petabyte-scale storage requirements. The Digital Information Security in Healthcare Act imposes localization mandates that fragment cloud economies of scale. Bangalore and Mumbai health networks modernize legacy patient data infrastructure through managed service adoption.
Singapore
Cross-border telemedicine corridors serving medical tourism demand interoperable record exchange with Thailand and Malaysia. Seven-year outpatient retention standards clash with Australian oncology mandates, forcing complex policy engines. Public hospital clusters pioneer unbundled technical support tendering.
Vietnam
Ho Chi Minh City and Hanoi private hospital chains lack entrenched vendor relationships, creating first-mover opportunities. Vietnamese-language compliance dashboards attract platforms seeking greenfield penetration. Emerging chains favor subscription architectures that reduce capital expenditure burdens.
Asia Pacific Healthcare Archiving and Ediscovery Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the Asia Pacific healthcare archiving landscape. The vendor base separates into hybrid cloud specialists, legacy infrastructure incumbents, and compliance-focused niche providers. Three strategic archetypes dominate: multinational technology conglomerates with pre-certified platforms, mid-tier data management specialists with granular retention engines, and regional service providers with localized language support. Competitive dynamics center on M&A activity consolidating mid-tier laboratories and strategic partnerships between cloud platforms and hospital consortiums.
Within the multinational tier, IBM Corporation and Microsoft Corporation exemplify divergent approaches to hybrid cloud dominance. IBM leverages architecture depth to anchor large hospital consortiums in Australia and Japan, while Microsoft competes through Azure-based compliance integrations sustaining recurring revenue from multi-site clinic networks. Commvault Systems occupies a position among mid-tier specialists, dominating laboratory chains seeking granular retention policies.
| Leading Market Players |
|---|
| IBM Corporation |
| Microsoft Corporation |
| Allscripts |
| GE Healthcare |
| Siemens Healthineers |
| Barracuda Networks |
| Actiance |
| Commvault Systems |
| Global Relay Communications |
| Others |
Supply Flow & Price Mechanics
PMDA's twenty-five-year retention mandate gates both vendor qualification and price tiering across Japan's hospital procurement committees. Vendors lacking pre-certified platforms face exclusion regardless of unit cost, while certified incumbents command subscription premiums that reflect compliance risk transfer rather than storage commodity pricing.
Pricing Analysis
After-sales technical support contracts drive lifetime value beyond core platform licenses. Subscription tiers stratify across forensic-certified premium, standard compliance, and economy storage levels, with price differentiation anchored in ISO 27037 chain-of-custody certification and localized data residency. Cost compression in economy tiers intensifies as Indian tier-1 hospital chains negotiate aggressively on per-petabyte costs, while Australian pathology networks show lowest price sensitivity, prioritizing TGA audit readiness over unit economics.
Supply Chain Analysis
Japan and Australia anchor compliance-certified platform development, while India and Singapore concentrate cloud infrastructure delivery. Raw material dependencies span immutable object storage hardware, blockchain anchoring modules, and clinical NLP training datasets. Single-source vulnerability concentrates in specialized health informatics talent pools across Sydney, Tokyo, and Bangalore. Distribution runs through direct enterprise sales to hospital consortiums, with GPO-style procurement emerging in Singapore's public clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Containerized microservices architectures threaten incumbent margin pools by enabling modular substitution of monolithic platforms. Incumbents must defend against disaggregation before procurement committees unbundle core licenses from compliance services.
For Market Incumbents: Consolidate through exclusive hospital system partnerships in Vietnam's greenfield private chains, locking in first-mover relationships before competitors localize Vietnamese-language dashboards. Deepen backward integration into immutable storage hardware to reduce dependency on third-party blockchain anchoring providers facing capacity constraints.
For New Entrants and Emerging Players: Vietnamese-language compliance dashboards represent the most penetrable service-layer gap, as Ho Chi Minh City and Hanoi hospital chains lack entrenched vendor relationships. Target mid-tier laboratory chains in Malaysia and Thailand seeking granular retention policies without enterprise-scale minimum commitments. Lead with AI-assisted ediscovery pilots that compress document review timelines, demonstrating litigation-ready value before subscription negotiations.
For Investors and Strategic Acquirers: India's Digital Information Security in Healthcare Act reshapes the acquisition landscape by fragmenting cloud economies of scale and elevating localized data residency capabilities. Long-term viability centers on platforms with pre-certified multi-jurisdictional policy engines. Watch for PMDA guideline amendments expanding retention scope as the inflection signal for compliance-driven consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Compliance Certification Investment | PMDA and TGA pre-certification gates procurement access in Tokyo and Melbourne hospital networks. |
| AI-Assisted Ediscovery Development | Clinical NLP engines trained on diagnostic terminology reduce litigation review timelines from weeks to days. |
| Localized Data Residency Expansion | India's DISHA Act mandates fragment cloud scale, favoring in-country infrastructure deployment. |
| Hospital System Partnership | Singapore's unbundled support tendering spreads to Kuala Lumpur and Bangkok procurement committees. |
| Blockchain-Anchored Integrity Proof | Australian pathology networks pilot immutable storage for twenty-year oncology record mandates. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with hospital procurement managers, health informatics directors, GPO contracts specialists, and laboratory compliance officers; and secondary validation through PMDA guideline filings, TGA audit protocols, DISHA Act implementation circulars, and hospital procurement database extracts. Bottom-up and top-down triangulation reconciled vendor-reported subscription volumes with facility-level storage capacity estimates.
Across the analysis window, the forecasting framework modeled deployment model, end-user tier, compliance standard, and regional regulatory cluster dimensions. CAGRs derived from segment-level growth rate reconciliation against macro healthcare IT expenditure trends. Industry-specific inputs included diagnostic imaging volume trajectories and cross-border telemedicine corridor development timelines.
Underlying assumptions cover regulatory retention period stability and cloud infrastructure cost curves, with deviation risk concentrated in data sovereignty law amendments and health informatics talent supply shocks. Recalibration cycles align with material shifts in PMDA guideline scope, Australian Privacy Act enforcement thresholds, and DISHA Act localization mandate implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Data Management
Data Monetization in Healthcare Market
Health Data Management
US Population Health Management Market
Health Data Management
Global Healthcare Content Management System Market
Health Data Management
Global Healthcare Compliance Software Market
Health Data Management
Medical Record Management System Market
Health Data Management
Americas Healthcare Archiving and Ediscovery Market
Health Data Management
Healthcare Archiving and Ediscovery Market
Health Data Management
Patient Data Management Software Market
Health Data Management
Healthcare Data Annotation Tools Market
Health Data Management
North America Clinical Data Analytics in Healthcare Market
Health Data Management
AI Training Dataset in Healthcare Market
Health Data Management
Master Data Management in Healthcare Market
Health Data Management
Population Health Management Platforms Market
Health Data Management
Patient Data Management Systems Market
Health Data Management
Europe Healthcare Analytics Market
Health Data Management
Healthcare Data Monetization Solutions Market