
 US Behavioral Health Market | 2026-2036
US Behavioral Health Market Size, Share, and Industry Trends Forecast 2026-2036
US Behavioral Health Market Intelligence
Revenue from traditional inpatient care is narrowing as value shifts toward scalable outpatient and teletherapy models, which offer lower operational costs. Large providers like Universal Health Services are diversifying their care settings to capture this shift. Acadia Healthcare sustains its market position by operating a balanced portfolio of residential facilities and outpatient clinics. Technology specialists such as Netsmart Technologies enable this transition with software solutions for providers.
Behavioral health encompasses the diagnosis, treatment, and prevention of mental illnesses and substance use disorders. It involves clinical interventions, including psychotherapy and medication management, designed to promote well-being and manage conditions affecting mood and behavior. Within service types, teletherapy represents the fastest-growing segment, expanding access beyond traditional settings. Cognitive Behavioral Therapy remains a dominant treatment modality, widely applied across various care settings from primary care centers to residential facilities.
The US market operates under strict federal oversight, with HIPAA governing patient data privacy across all care settings. The Mental Health Parity and Addiction Equity Act (MHPAEA) shapes insurance reimbursement, mandating equitable coverage for behavioral health services. Provider strategy will hinge on successfully integrating new technologies while navigating the complex landscape of state-level licensing and payer models.
Market Dynamics
The fundamental shift from inpatient to scalable outpatient and digital care models defines the US behavioral health market's current trajectory. This transition is driven by the economic advantages of lower operational costs and the technological capability to deliver services remotely.
Growth Catalysts
- Parity Legislation:The Mental Health Parity and Addiction Equity Act (MHPAEA) mandates that insurers provide behavioral health coverage comparable to medical coverage, which expands the pool of reimbursed services and improves patient access.
- Adolescent Demographics:Concentrated demand for specialized adolescent programs, particularly in high-population states like California and Texas, is driving investment in school-based and youth-focused mental health infrastructure.
- Telehealth Expansion:Evolving HIPAA guidelines for digital health are supporting the widespread adoption of teletherapy, enabling providers to reach patients in previously underserved rural and urban areas with greater efficiency.
Market Restraints
- Workforce Shortages:A persistent national shortage of licensed psychiatrists, psychologists, and therapists, especially in rural counties, creates significant bottlenecks in service delivery and limits market expansion despite high demand.
- Reimbursement Complexity:Navigating the fragmented payer landscape, with inconsistent reimbursement rates and policies across different private and public insurers, imposes a significant administrative burden on providers.
- State Licensing Barriers:State-specific professional licensing requirements restrict the ability of clinicians to provide teletherapy services across state lines, complicating the operating models of national virtual care providers.
Strategic Opportunities
- Integrated Care Models:Embedding behavioral health services within primary care settings and hospitals represents a significant opportunity to improve early detection, streamline referrals, and provide holistic patient care.
- Employer-Sponsored Programs:Developing direct-to-employer platforms that offer mental wellness and behavioral health benefits provides a new distribution channel, bypassing traditional insurance models to reach a large patient population.
- Digital Therapeutics (DTx):FDA-cleared prescription digital therapeutics for conditions like ADHD and substance use disorder open a new, scalable modality for treatment that complements traditional clinical intervention.
Industry Challenges
- Data Interoperability:The lack of seamless data exchange between different electronic health record (EHR) systems used by hospitals, outpatient clinics, and teletherapy platforms hinders care coordination and clinical efficiency.
- Ensuring Care Quality:As teletherapy becomes mainstream, providers face the challenge of maintaining clinical quality, ensuring patient engagement, and measuring outcomes effectively in a virtual environment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Behavioral Health Market |
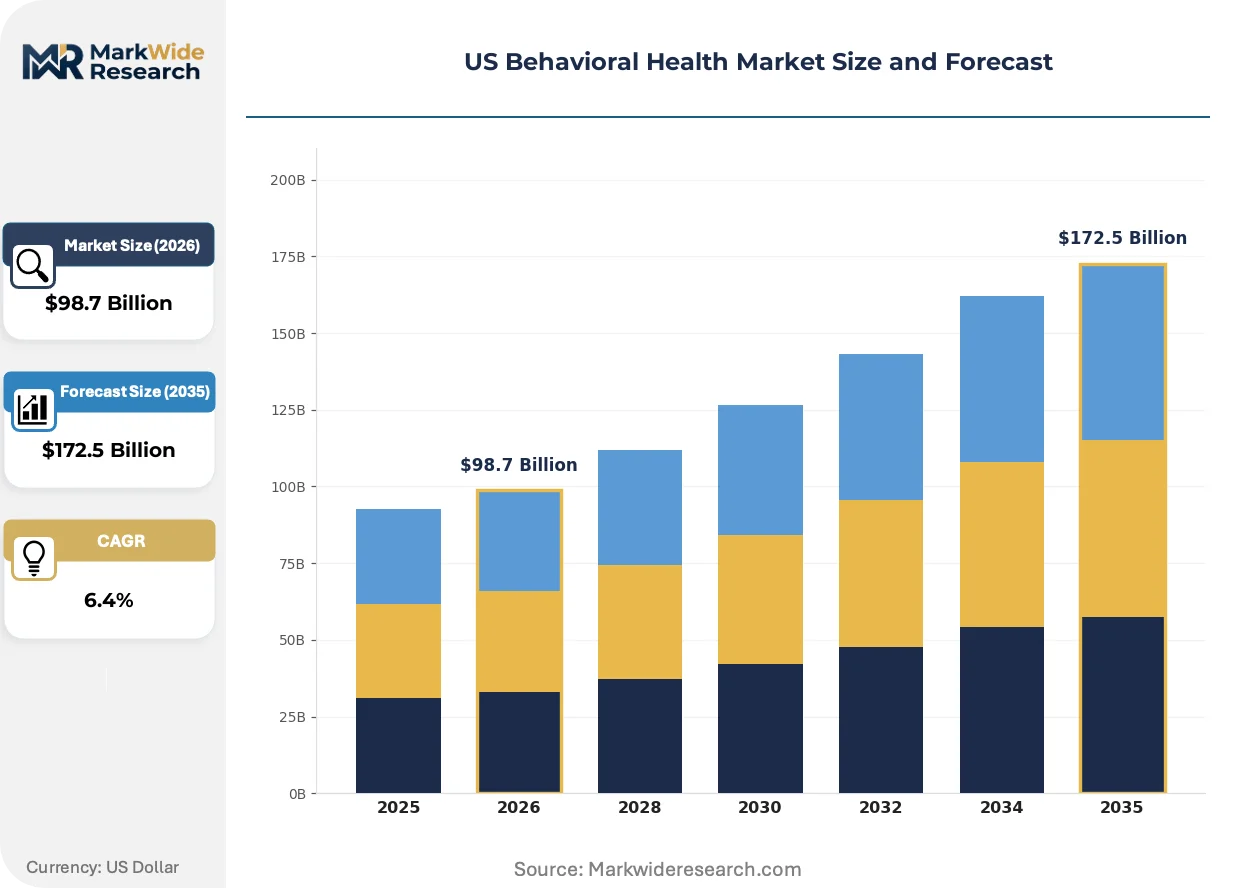
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $172.5 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Inpatient Care, Outpatient Services, Teletherapy, Crisis Intervention, Community Support Treatment Modality: Cognitive Behavioral Therapy, Psychodynamic Therapy, Dialectical Behavior Therapy, Group Counseling, Medication Management Care Setting: Behavioral Clinics, Residential Facilities, Primary Care Centers, Rehabilitation Centers, School-Based Programs Patient Demographic: Adolescents, Adults, Seniors, Veterans, Caregivers |
| Companies Covered | Acadia Healthcare, Universal Health Services, Behavioral Health Group, Promises Behavioral Health, CuraLinc Healthcare, Sevita, Pyramid Healthcare, Core Solutions, Netsmart Technologies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Behavioral Health Market Strategic Shifts & Innovations
Value is migrating from facility-based services toward technology-enabled, accessible care continuums. This evolution prioritizes early intervention and personalized treatment paths, reshaping provider strategies and patient engagement models across the US.
Digital therapeutics and app-based tools provide structured, self-guided interventions based on principles like Cognitive Behavioral Therapy. Large employers and health plans are adopting these solutions to supplement traditional therapy for lower-acuity conditions. The proliferation of these validated digital health tools is collapsing the historical separation between formal clinical treatment and daily mental wellness management.
Recent federal updates to HIPAA rules for digital health are providing clearer guidance on data security, patient consent, and interoperability for teletherapy platforms. This regulatory clarity encourages provider investment in compliant software and secure patient portals. Outpatient clinics and private practices are most affected, as they leverage this framework to expand virtual services.
A significant shift in consumption patterns involves employers contracting directly with behavioral health providers for enhanced employee assistance programs. This model circumvents traditional insurance pathways, offering employees faster, confidential access to care for conditions like anxiety and burnout. This trend is most prominent in the technology and finance sectors, where mental wellness support is a key part of talent retention.
US Behavioral Health Market Segmentation
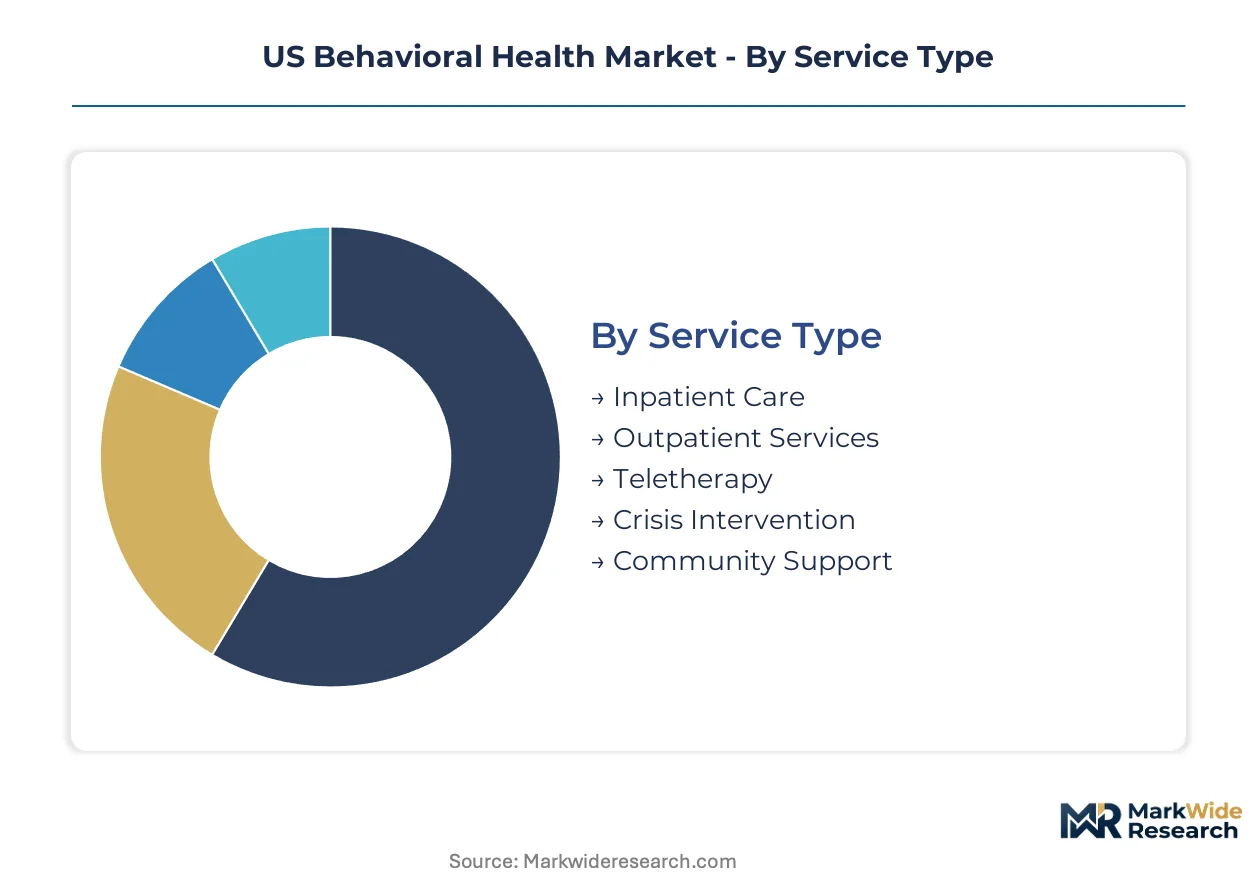
The US behavioral health market segmentation reveals the diverse approaches to mental wellness and substance use disorder treatment. Understanding these segments helps providers tailor services and optimize resource allocation across the complex US healthcare landscape. This breakdown highlights service delivery evolution and patient needs.
Service Type:
The service type landscape exhibits a clear distinction between mature, facility-based models and emerging, technology-driven care. This evolution prioritizes accessibility and cost-efficiency for US patients.
- Teletherapy:This segment provides remote mental health services through video conferencing, phone calls, or digital platforms. Evolving HIPAA guidelines support its widespread adoption, especially expanding access in rural US regions.
- Outpatient Services:These services include therapy, counseling, and medication management delivered in clinics or offices without an overnight stay. Value shifts from inpatient care drive investment in these scalable models across US states.
- Inpatient Care:Patients receive 24-hour supervision and structured treatment in a hospital or residential facility for acute conditions.
- Crisis Intervention:Immediate, short-term support is provided during mental health emergencies to stabilize individuals in distress.
- Community Support:Programs and resources offered locally assist individuals with recovery and reintegration into daily life.
Inpatient Care retains volume leadership; Teletherapy holds the steepest expansion curve.
Treatment Modality:
Treatment modalities vary significantly in their therapeutic approach and evidence base, targeting specific behavioral health conditions. These interventions are applied across diverse US care settings.
- Cognitive Behavioral Therapy:This structured, goal-oriented psychotherapy helps individuals identify and change negative thought patterns and behaviors. It remains a dominant treatment, widely applied in US primary care centers and residential facilities.
- Medication Management:Psychiatrists or other qualified medical professionals prescribe and monitor psychiatric medications to manage symptoms of mental illness. This clinical intervention is crucial for comprehensive treatment plans across US health systems.
- Psychodynamic Therapy:This approach explores unconscious processes and past experiences to understand current emotional patterns.
- Dialectical Behavior Therapy:DBT combines cognitive-behavioral techniques with mindfulness for individuals with intense emotional dysregulation.
- Group Counseling:Multiple individuals participate in therapy sessions, fostering shared experiences and peer support.
Cognitive Behavioral Therapy shows the broadest adoption; Medication Management demonstrates consistent clinical integration.
Care Setting:
Care settings delineate where behavioral health services are delivered, ranging from specialized facilities to integrated community programs. Each setting addresses distinct patient needs within the US healthcare framework.
- Behavioral Clinics:These outpatient facilities offer a range of services including individual therapy, group counseling, and medication management. They are central to accessible behavioral healthcare delivery across US urban and suburban areas.
- School-Based Programs:Services provided within educational institutions support students' mental health, often through counseling and early intervention. Demand concentrates in high-population US states like California and Texas.
- Residential Facilities:Patients receive intensive, live-in treatment for severe mental health or substance use disorders.
- Primary Care Centers:Behavioral health services are integrated into general medical practices for holistic patient care.
- Rehabilitation Centers:These facilities focus on recovery from substance use disorders, providing therapy and life skills training.
Strategic investment is highest in School-Based Programs; Behavioral Clinics form the foundational service delivery network.
Patient Demographic:
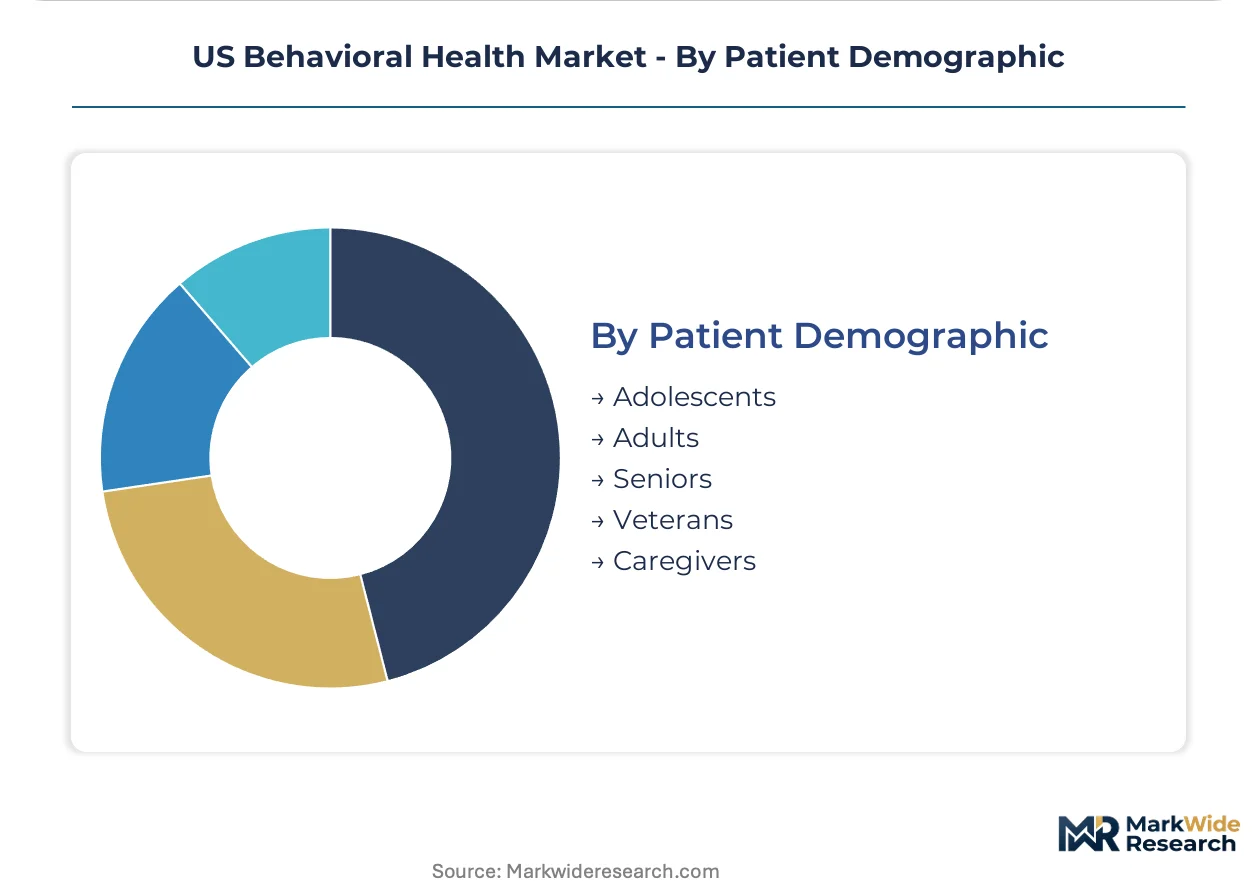
Patient demographics highlight specific population groups with unique behavioral health needs and service requirements. This segmentation informs targeted program development across the US.
- Adolescents:This group requires specialized programs addressing developmental challenges, peer pressure, and academic stress. Concentrated demand drives investment in youth-focused mental health infrastructure across the US.
- Adults:The largest patient demographic experiences a broad spectrum of mental illnesses and substance use disorders. Employer-sponsored programs increasingly target this group for mental wellness benefits across US industries.
- Seniors:This demographic often faces mental health challenges related to aging, chronic illness, and social isolation.
- Veterans:Military veterans require specialized care for conditions like PTSD and depression, often through VA healthcare systems.
- Caregivers:Individuals providing care for others frequently experience stress, burnout, and mental health strain.
Policy initiatives increasingly focus on Adolescents; Adults represent the largest addressable patient base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US behavioral health market exhibits varied demand elasticity across its diverse regions. Certain areas demonstrate high price sensitivity for basic services, while others prioritize specialized care, creating a complex landscape for providers. This regional variation influences investment strategies and service delivery models across the nation.
California
California experiences concentrated demand for specialized adolescent programs and tech-enabled mental wellness solutions. State-level initiatives like the Mental Health Services Act (MHSA) fund community-based behavioral health programs, expanding access. Silicon Valley and Los Angeles areas see significant investment in digital therapeutics and school-based mental health infrastructure.
Texas
Texas faces a growing need for mental health services, particularly among its expanding adolescent population and in underserved rural communities. Texas state legislation emphasizes mental health parity, improving reimbursement for a wider range of services. Major metropolitan areas like Houston and Dallas are expanding outpatient clinics and teletherapy services to address both urban and surrounding rural demands.
New York Metro
New York Metro demands comprehensive behavioral health services due to its high-stress urban environment and diverse patient demographics. New York State mandates extensive behavioral health coverage, impacting both private insurers and public health systems. New York City serves as a hub for specialized outpatient clinics and innovative digital therapeutic providers, addressing complex urban mental health needs.
Southeast (Florida/Georgia)
The Southeast, including Florida and Georgia, experiences high demand driven by rapid population growth and increasing needs for substance use disorder treatment. States in this region are expanding Medicaid coverage for behavioral health services, which improves access for lower-income populations. Cities like Atlanta and Miami are developing integrated care models within primary care settings, streamlining patient pathways and early detection.
US Behavioral Health Market Key Industry Players
Capability concentration sits with specialized technology providers and niche therapeutic innovators; scale advantage sits with large, diversified healthcare systems. The US behavioral health market is characterized by a mix of large integrated providers and numerous smaller, specialized clinics. Strategic archetypes include national multi-site operators, regional specialty providers, and technology enablers. Providers are pursuing portfolio diversification and strategic partnerships to expand their reach.
Within the national multi-site operator archetype, Acadia Healthcare and Universal Health Services, Inc. exemplify diversified care delivery. Acadia Healthcare sustains its market position by operating a balanced portfolio of residential facilities and outpatient clinics across multiple states. Universal Health Services, Inc. continues diversifying its care settings to capture value shifts towards outpatient and teletherapy models. Netsmart Technologies, Inc. represents the technology enabler segment, providing software solutions that facilitate this transition for numerous providers.
| Leading Market Players |
|---|
| Acadia Healthcare |
| Universal Health Services |
| Behavioral Health Group |
| Promises Behavioral Health |
| CuraLinc Healthcare |
| Sevita |
| Pyramid Healthcare |
| Core Solutions |
| Netsmart Technologies |
| Others |
Cost & Logistics Intelligence
California's concentration of specialized behavioral health technology providers influences pricing power for digital solutions across the US market. This dynamic reflects the state's early adoption of teletherapy and its robust investment in mental wellness infrastructure. Supply chain efficiency in this sector increasingly depends on technology integration and a skilled workforce.
Pricing Analysis
Subscription-based teletherapy platforms and value-based care models drive revenue in the US behavioral health market. Price differentiation stems from the customization level of specialized programs for adolescents and geographic delivery costs, particularly for rural access. Pricing softness affects traditional inpatient care due to the value shift toward outpatient and digital services. Employer-sponsored programs exhibit lower price sensitivity, while individual cash-pay patients are most sensitive to costs.
Supply Chain Analysis
US-based technology providers, particularly those in California and Texas, host significant teletherapy infrastructure capacity. The supply chain for behavioral health services draws from licensed clinicians, including psychiatrists and therapists, and secure digital platforms. Workforce shortages in licensed professionals, especially in rural counties, create a significant bottleneck risk. Distribution runs through direct-to-consumer digital platforms and integrated primary care networks, bypassing traditional facility-based models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Behavioral health presents a significant service-attach opportunity, with teletherapy subscriptions expanding faster than traditional facility-based services. This growth underpins a strategic shift toward accessible, technology-enabled care models.
For Market Incumbents: Harden existing patient relationships by diversifying care settings to include scalable outpatient and teletherapy options. Acquire niche digital therapeutics firms to counter margin pressure from lower-cost digital entrants. Invest in technology for enhanced EHR interoperability to improve care coordination across diversified portfolios. Focus on integrating behavioral health services within primary care to capture early intervention opportunities.
For New Entrants and Emerging Players: Build out specialized school-based programs and employer-sponsored mental wellness platforms. Target adolescents in high-population states like California and Texas as a penetrable segment with specific needs. Implement a direct-to-employer sales strategy to bypass traditional insurers, offering faster, confidential access to care. Leverage FDA-cleared Digital Therapeutics to provide scalable, evidence-based interventions for specific conditions.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among technology enablers and digital health platforms in the US behavioral health market. The long-term viability of this sector rests on the sustained shift towards value-based care and digital service delivery. Identify acquisition targets that offer integrated care capabilities or specialized Digital Therapeutics platforms. Payer adoption rates for digital health solutions serve as a critical signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Telehealth Platform Integration | Enhances patient access across underserved US regions. |
| Digital Therapeutics Development | Offers scalable treatment modalities for specific conditions. |
| Integrated Care Model Expansion | Improves early detection within primary care settings. |
| Workforce Development Programs | Addresses the persistent US clinician shortage. |
| Employer Partnership Cultivation | Creates new distribution channels for mental wellness benefits. |
Research Approach
A standing panel of clinical directors, health plan executives, digital health entrepreneurs, and policy analysts provided ongoing calibration throughout this analysis. The research combined extensive primary interviews with industry stakeholders and rigorous secondary validation. Data sources included HIPAA guidelines, Mental Health Parity and Addiction Equity Act reports, CMS data, and state health department statistics, triangulated using both bottom-up and top-down approaches.
Scenario-bracketing framed the analytical framework across the analysis window, considering various market conditions. Segmentation dimensions modeled included service type, treatment modality, care setting, patient demographic, and regional regulatory adherence. Compound annual growth rates were derived from historical trends and projected market shifts. Key forecast inputs included telehealth adoption rates and insurance reimbursement policy changes within the US.
Stress conditions across workforce availability and regulatory shifts were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding market evolution and policy stability. Quarterly review of teletherapy utilization and workforce supply indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mental Health Services
Behavioral Health Care Software and Services Market
Mental Health Services
Agoraphobia Treatment Market
Mental Health Services
Germany Post-Traumatic Stress Disorder Treatment Market
Mental Health Services
Relationship Counselling Market
Mental Health Services
North America Maternal Mental Health Market
Mental Health Services
Anxiety Disorders and Depression Treatment Market
Mental Health Services
Mental Health Software Market
Mental Health Services
US Psychiatry Clinic Market
Mental Health Services
Global Mental Health Apps Market
Mental Health Services
Schizoaffective Disorders Treatment Market
Mental Health Services
Schizophrenia Market
Mental Health Services
Obsessive-Compulsive Disorder Market
Mental Health Services
Global Anxiety Disorder Treatment Market
Mental Health Services
Spain Post-Traumatic Stress Disorder Treatment Market
Mental Health Services
Seasonal Affective Disorder (SAD) Market
Mental Health Services
Global Behavioral Health Market