
 United States Veterinary Healthcare Market | 2026-2036
United States Veterinary Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
United States Veterinary Healthcare Market Analytics
AVMA accreditation standards for veterinary education and practice certification is bifurcating market access between credentialed hospital networks and independent operators. Zoetis leverages its vertically integrated manufacturing of vaccines and parasiticides to sustain pricing power across distribution channels. IDEXX Laboratories anchors the diagnostics layer with in-clinic analyzers and reference lab services that dominate companion animal workflows.
United States veterinary healthcare encompasses the prevention, diagnosis, and treatment of disease in companion animals, livestock, and exotic species through pharmaceuticals, biologics, medical devices, and clinical services, typically delivered via intramuscular or subcutaneous injection, oral formulation, or imaging modality with temperature-controlled supply chain requirements. Its primary purpose is to maintain animal health for food security, zoonotic disease control, and human-animal bond preservation. Pharmaceuticals and diagnostics command the deepest margin pools, while preventive care among companion animals shows the steepest volume trajectory as pet owners shift from episodic sick visits to wellness subscription models.
FDA Center for Veterinary Medicine, USDA APHIS, and state veterinary medical boards collectively shape product approval pathways, compounding restrictions, and practice mobility rules that determine which services can scale across state lines. The DEA's classification of veterinary controlled substances further constrains anesthesia and pain management protocols in clinic settings. Stakeholders must monitor how state-level telemedicine parity legislation evolves, as this will determine whether corporate veterinary groups can centralize specialist consultations or remain bound to physical facility footprints.
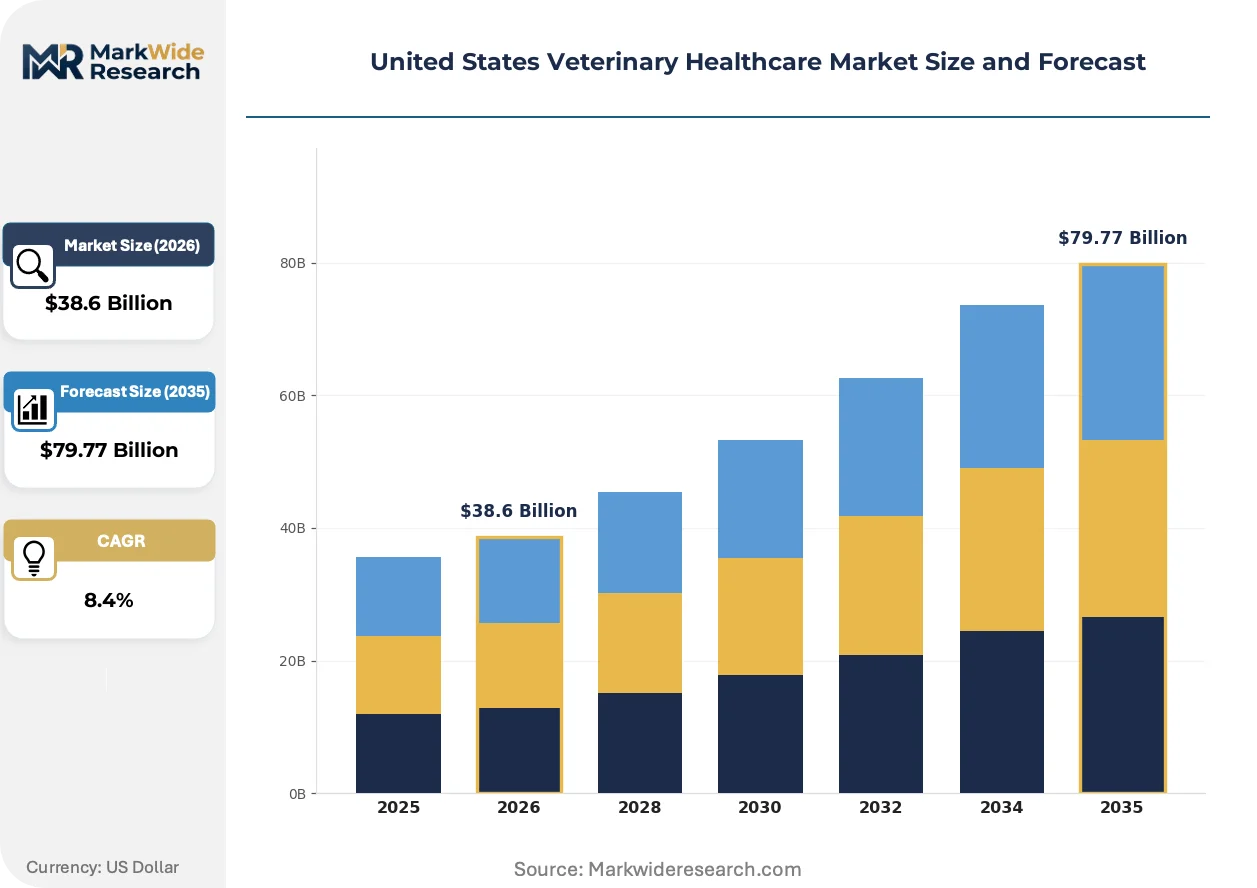
Market Dynamics
The FDA Center for Veterinary Medicine's expanded oversight of compounded drugs and telemedicine prescribing is compressing service delivery models while concentrating decision-making authority in credentialed hospital networks across state lines.
Growth Catalysts
- Preventive Diagnostics Expansion:Companion animal owners in Texas, California, and Florida now demand chronic disease management protocols that extend clinic visit frequency and diagnostic panel adoption.
- USDA APHIS Zoonotic Surveillance:Federal livestock health monitoring mandates sustain biologics procurement for food security applications across cattle and swine operations.
- Wellness Subscription Models:Corporate veterinary groups deploy membership-based preventive care packages that lock in recurring revenue and reduce client attrition.
Market Restraints
- DEA Controlled Substance Classification:Federal scheduling constraints limit anesthesia and pain management protocol flexibility in clinic settings, requiring specialized storage and documentation.
- Temperature-Controlled Supply Chain Concentration:Cold chain logistics for vaccines and biologics cluster around third-party distributors in metropolitan corridors, creating single-point vulnerability.
- AVMA Accreditation Bottleneck:Limited veterinary school output restricts credentialed practitioner supply, capping expansion velocity for hospital networks.
Strategic Opportunities
- State Telemedicine Parity Legislation:Evolving veterinary medical board rules in Florida and Texas may permit centralized specialist consultations across physical facility footprints.
- Exotic Species Service Gaps:Underpenetrated demand for avian and reptile care in suburban markets offers premium pricing capture for trained specialists.
- Reference Laboratory Integration:In-clinic analyzer connectivity with centralized pathology services enables same-day turnaround for complex diagnostics.
Industry Challenges
- Veterinary Technician Attrition:Burnout and compensation gaps in support staff roles constrain clinic throughput and extend appointment wait times.
- Legacy Practice Management System Migration:Independent operators face integration friction when adopting cloud-based electronic health records and billing platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Veterinary Healthcare Market |
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $79.77 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceuticals, Vaccines, Nutraceuticals, Diagnostics End User: Veterinary Clinics, Animal Hospitals, Research Laboratories, Pet Shops Treatment Type: Preventive Care, Emergency Care, Surgical Procedures, Routine Check-ups Animal Type: Companion Animals, Livestock, Exotic Pets, Aquatic Animals |
| Companies Covered | Elanco Animal Health, Mars Veterinary Health, Zoetis, Bond Vet, Vetcove, IDEXX Laboratories, Merck & Co., Modern Animal, Boehringer Ingelheim International GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Veterinary Healthcare Market Evolving Landscape
Artificial intelligence diagnostics and point-of-care testing platforms are compressing decision timelines while fragmenting traditional reference laboratory relationships across companion animal workflows.
Point-of-care molecular diagnostics is bifurcating infectious disease testing workflows. PCR-based pathogen detection now operates within 30-minute windows in primary care settings. Large corporate hospital groups deploy these analyzers to capture revenue previously routed to external reference laboratories, compressing turnaround time while fragmenting diagnostic service relationships.
The FDA Center for Veterinary Medicine's 2023 guidance on telemedicine prescribing establishes conditional remote care protocols. State veterinary medical boards must now reconcile federal flexibility with existing physical examination requirements. Texas and California regulators are piloting amended practice acts that permit synchronous video consultations for established patients, with specialist referral networks testing centralized triage models.
Pet owner purchasing behavior now favors bundled wellness plans over episodic sick visits. Corporate veterinary groups disaggregate traditional service packaging into monthly subscription tiers covering preventive diagnostics, vaccinations, and parasite control. This shift concentrates client lifetime value capture in metropolitan markets where household pet density supports membership scale economics.
United States Veterinary Healthcare Market Segmentation
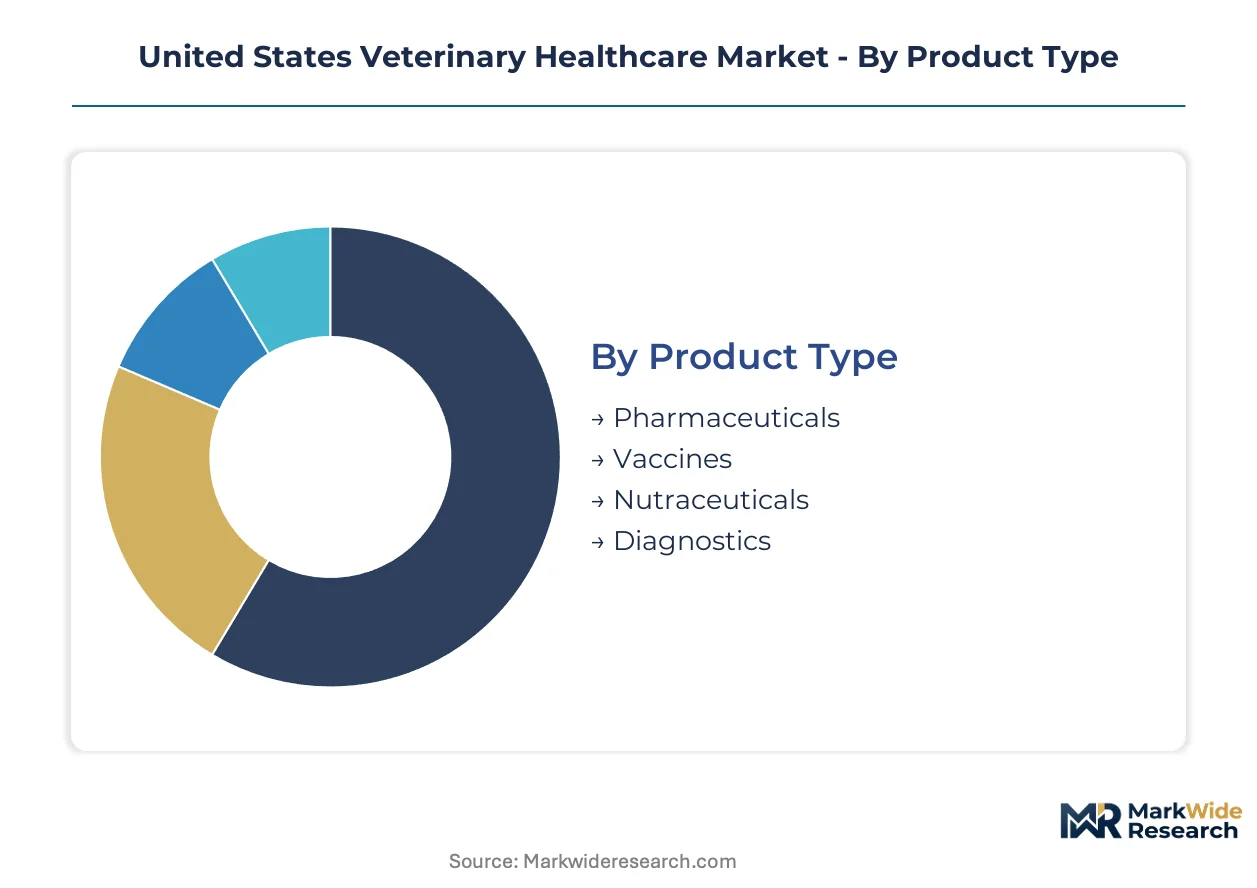
Segmentation in United States veterinary healthcare reveals how FDA Center for Veterinary Medicine regulations, USDA APHIS mandates, and state veterinary medical board rules create divergent compliance burdens across product categories and service delivery models. Understanding these divisions enables stakeholders to align R&D investment, distribution infrastructure, and clinical staffing with specific regulatory pathways and end-user requirements.
Product Type:
FDA Center for Veterinary Medicine approval pathways differentiate segments by clinical trial requirements, manufacturing standards, and post-market surveillance obligations.
- Pharmaceuticals:Small-molecule therapeutics and biologics for chronic disease management face stringent New Animal Drug Application (NADA) requirements. Demand concentrates in Texas and California specialty hospitals where oncology and cardiomyopathy protocols drive off-label human drug adaptation under AMDUCA provisions.
- Vaccines:USDA APHIS-licensed biologics for core and non-core immunization schedules require batch purity testing and cold chain maintenance. Large cattle operations in Nebraska and Kansas sustain bulk procurement of clostridial and respiratory vaccines under federal livestock health mandates.
- Nutraceuticals:Dietary supplements and functional feeds operate under lighter FDA enforcement discretion, though structure-function claims face FTC scrutiny.
- Diagnostics:In-vitro analyzers and reagent kits fall under FDA device classification with 510(k) clearance pathways for point-of-care platforms.
Established volume favors vaccines; emerging adoption favors diagnostics.
End User:
Capital intensity and staffing ratios separate segments by fixed-cost absorption capacity and service complexity tolerance.
- Veterinary Clinics:Primary care facilities with 2-4 veterinarians deliver preventive services and minor procedures. Florida's suburban corridors concentrate independent practices competing with corporate roll-ups on wellness plan penetration.
- Animal Hospitals:Multi-specialty referral centers with 24-hour emergency capacity and advanced imaging infrastructure command premium pricing for orthopedic surgery and internal medicine consultations. California's metropolitan clusters host the densest concentration of Level II trauma-certified facilities.
- Research Laboratories:Academic and contract research organizations supporting pharmaceutical development and toxicology studies.
- Pet Shops:Retail channels for over-the-counter parasiticides, nutritional products, and basic grooming supplies with limited professional oversight.
Capital deployment favors animal hospitals; margin preservation favors veterinary clinics.
Treatment Type:
Revenue predictability and reimbursement exposure divide segments by cash-flow stability and client acquisition economics.
- Preventive Care:Scheduled vaccinations, parasite screening, and wellness examinations form the subscription revenue base for corporate veterinary groups. Texas markets show the steepest expansion in membership-based preventive packages as Banfield and VCA standardize tiered offerings.
- Emergency Care:Unscheduled critical interventions including trauma stabilization and toxicosis management carry the highest per-visit revenue but irregular volume patterns. After-hours facilities in Phoenix and Miami capture premium pricing from pet owners lacking daytime flexibility.
- Surgical Procedures:Elective and urgent interventions from spay-neuter to orthopedic repair requiring anesthesia protocols and specialized equipment.
- Routine Check-ups:Annual physical examinations and minor ailment assessments serving as client retention touchpoints.
Recurring revenue favors preventive care; pricing power favors emergency care.
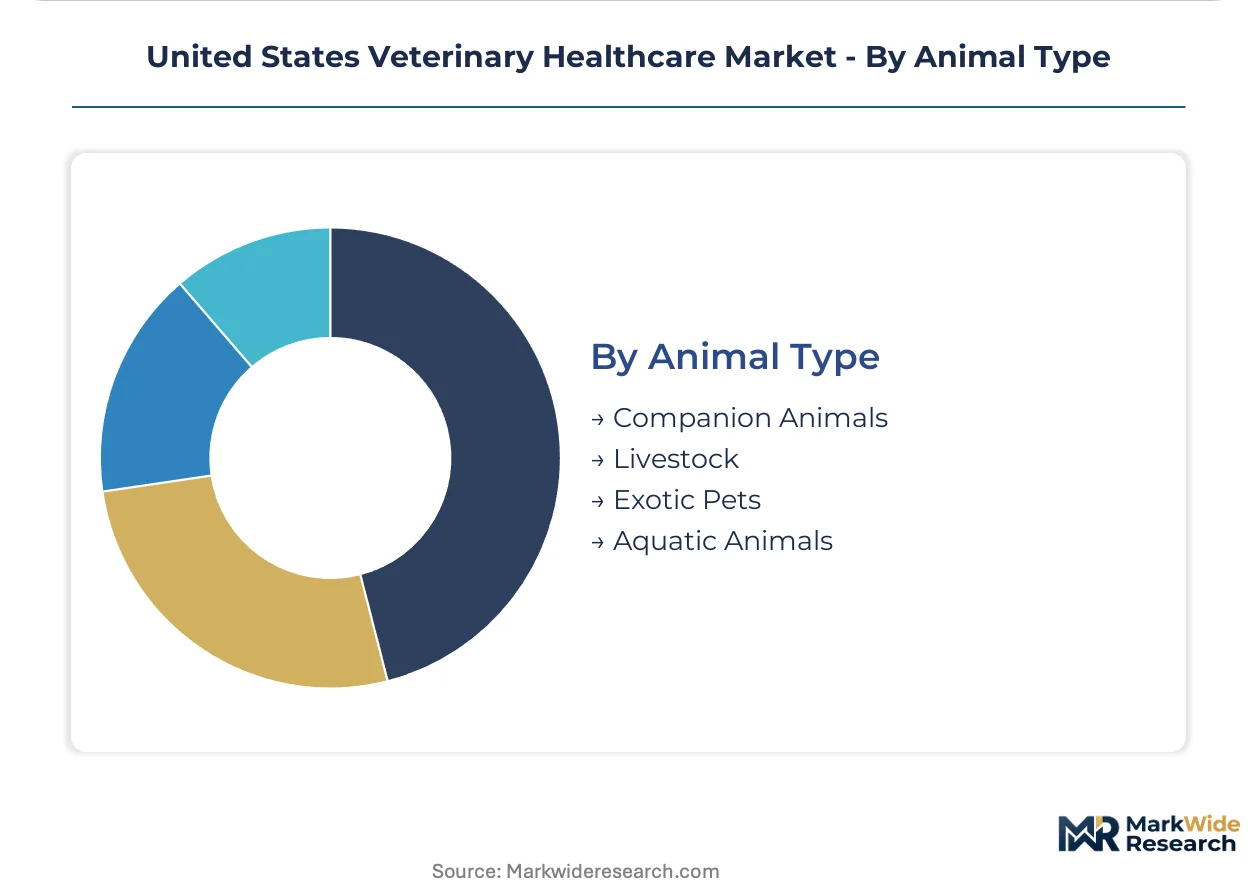
Animal Type:
Species-specific regulatory frameworks and practitioner training availability determine service accessibility and fee structures.
- Companion Animals:Dogs and cats drive pharmaceutical R&D investment and diagnostic platform development. Urban California households generate the highest per-capita spending on chronic disease management and advanced imaging.
- Livestock:Cattle, swine, and poultry operations depend on USDA APHIS-monitored herd health programs and antimicrobial stewardship compliance. Iowa and North Carolina pork producers anchor demand for reproductive and respiratory biologics under federal food security mandates.
- Exotic Pets:Avian, reptile, and small mammal species requiring specialized veterinary training with limited practitioner supply.
- Aquatic Animals:Ornamental fish and commercial aquaculture operations with niche diagnostic and therapeutic options.
Service infrastructure favors companion animals; regulatory integration favors livestock.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA Center for Veterinary Medicine oversight of compounded drugs and telemedicine prescribing creates divergent compliance environments across state veterinary medical boards. Texas, California, and Florida concentrate demand through specialized referral hospitals and large pet populations.
Texas
Texas hosts dense concentrations of cattle operations and suburban companion animal households driving biologics procurement and wellness subscription adoption. State veterinary medical board pilots amended practice acts permitting synchronous video consultations for established patients. Dallas-Fort Worth and Houston metropolitan corridors anchor corporate veterinary group expansion with membership-based preventive care packages.
California
California urban households generate the highest per-capita spending on chronic disease management and advanced imaging for companion animals. FDA Center for Veterinary Medicine guidance on telemedicine prescribing intersects with state-level flexibility trials for remote specialist consultations. Los Angeles and San Francisco Bay Area clusters concentrate Level II trauma-certified facilities and multi-specialty referral centers.
Florida
Florida suburban corridors concentrate independent practices competing with corporate roll-ups on wellness plan penetration among aging pet populations. State regulators pilot telemedicine parity legislation determining whether centralized specialist consultations can operate across physical facility footprints. Miami and Phoenix after-hours facilities capture premium pricing from pet owners lacking daytime flexibility for emergency interventions.
Nebraska and Kansas
Nebraska and Kansas large cattle operations sustain bulk procurement of clostridial and respiratory vaccines under USDA APHIS federal livestock health mandates. USDA APHIS-licensed biologics requirements for batch purity testing and cold chain maintenance shape distribution infrastructure. Omaha and Kansas City metropolitan areas anchor third-party distributor concentration for temperature-controlled vaccine logistics.
Iowa and North Carolina
Iowa and North Carolina pork producers anchor demand for reproductive and respiratory biologics under federal food security and antimicrobial stewardship compliance programs. USDA APHIS-monitored herd health programs sustain veterinary service relationships across concentrated animal feeding operations. Des Moines and Raleigh-Durham corridors host veterinary diagnostic laboratory networks supporting regional livestock health monitoring.
United States Veterinary Healthcare Market Competitive Landscape
Player mix skews toward vertically integrated pharmaceutical manufacturers and corporate veterinary service networks with multi-state footprints. Market structure concentrates decision-making authority in credentialed hospital networks capable of absorbing fixed costs for advanced imaging and anesthesia infrastructure. Two strategic archetypes dominate: integrated pharmaceutical-biologics manufacturers with captive distribution, and corporate veterinary groups deploying subscription-based preventive care models. Competitive moves center on M&A roll-ups of independent practices and technology licensing for point-of-care diagnostic platforms.
Within the integrated pharmaceutical tier, Zoetis and Elanco Animal Health represent archetypes of vertically controlled vaccine and parasiticide production. IDEXX Laboratories anchors the diagnostics layer with in-clinic analyzers and reference laboratory services. Among corporate veterinary service networks, Mars Veterinary Health exemplifies multi-brand hospital consolidation with standardized wellness subscription offerings.
| Leading Market Players |
|---|
| Elanco Animal Health |
| Mars Veterinary Health |
| Zoetis |
| Bond Vet |
| Vetcove |
| IDEXX Laboratories |
| Merck & Co. |
| Modern Animal |
| Boehringer Ingelheim International GmbH |
| Others |
Value Network & Pricing Analysis
FDA Center for Veterinary Medicine's New Animal Drug Application (NADA) requirements gate both supply qualification and price differentiation simultaneously, separating credentialed manufacturers from compounders while concentrating premium pricing power in vertically integrated vaccine and pharmaceutical producers.
Pricing Analysis
Certification level (FDA NADA/USDA APHIS biologics licensing) creates the primary spread between premium therapeutics and commodity generics. Three-tier pricing structure across premium specialty formulations, standard approved drugs, and economy compounders dominates pharmaceutical procurement. Cost compression in the compounding tier is intensifying because FDA enforcement discretion is tightening on bulk ingredient sourcing. Corporate hospital networks show least price sensitivity for biologics, while independent clinics in rural corridors exhibit highest sensitivity to parasiticide cost fluctuations.
Supply Chain Analysis
Port congestion at Los Angeles-Long Beach and container availability constraints on Asia-Pacific trade lanes are elevating inbound logistics costs for active pharmaceutical ingredients and diagnostic reagent kits. Supply concentrates in Ireland and Singapore for API synthesis, with Puerto Rico anchoring sterile fill-finish capacity for biologics. Raw material dependencies rest on Chinese-manufactured small-molecule intermediates, German-engineered precision optics for imaging equipment, and Indian-sourced excipients. Single-source vulnerability clusters around temperature-controlled distribution for vaccines. Distribution runs through third-party logistics providers with validated cold chain infrastructure to veterinary clinics and hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a service-attach opportunity where wellness subscription revenue layers expand faster than hardware diagnostics, concentrating client lifetime value in recurring preventive care relationships.
For Market Incumbents: Secure reference laboratory integration through in-clinic analyzer connectivity that captures same-day diagnostic revenue previously routed to external vendors. Defend against point-of-care molecular diagnostic fragmentation by locking exclusive reagent supply agreements with corporate hospital networks. Vertical integration into telemedicine infrastructure offers channel control as state veterinary medical boards amend practice acts. For New Entrants and Emerging Players: FDA 510(k) fast-track for veterinary diagnostic devices offers regulatory entry into the companion animal point-of-care segment with compressed approval timelines versus human medical pathways. Target exotic species service gaps in suburban Texas and Florida corridors where practitioner supply constraints support premium pricing capture. Deploy mobile veterinary units with telemedicine triage capability to penetrate independent practice white space. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across multi-specialty animal hospital networks requiring advanced imaging and anesthesia infrastructure. Long-term viability over the next decade favors corporate veterinary groups with membership-based recurring revenue models over episodic-care-dependent independents. Acquisition target archetype: regional hospital networks with established wellness subscription penetration. Monitor state telemedicine parity legislation as inflection signal for centralized specialist consultation scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Reference Laboratory Integration | IDEXX Laboratories' in-clinic analyzer connectivity captures same-day diagnostic revenue from corporate hospital networks. |
| Telemedicine Infrastructure Buildout | Texas and Florida state veterinary medical board pilots enable centralized specialist consultations across physical facility footprints. |
| Wellness Subscription Standardization | Banfield and VCA membership tiers lock recurring revenue and reduce client attrition in metropolitan markets. |
| Cold Chain Distribution Partnership | Third-party logistics providers with validated vaccine temperature control mitigate single-point vulnerability in biologics procurement. |
| Exotic Species Specialist Training | Avian and reptile care certification programs unlock premium pricing in underpenetrated suburban corridors. |
Research Methodology
Desk research of FDA Center for Veterinary Medicine guidance documents, USDA APHIS livestock health program reports, and state veterinary medical board practice act amendments preceded structured interviews with veterinary practice owners, corporate hospital group operations executives, pharmaceutical regulatory affairs leads, and third-party distribution logistics managers. Secondary validation drew from AVMA workforce studies, FDA NADA approval databases, and GPO procurement contract disclosures. Bottom-up clinic and hospital service volume estimates triangulated against top-down pharmaceutical manufacturer shipment data.
Variance decomposition across product type, end user, treatment category, and animal species segments structured the analytical framework over the projection horizon. Companion animal preventive care, livestock biologics procurement, and exotic species service gaps served as primary segmentation dimensions. CAGRs derived from historical volume trajectories adjusted for regulatory inflection points including telemedicine prescribing guidance and compounded drug enforcement shifts. Forecast inputs incorporated AVMA-accredited veterinary school output projections and state-level corporate practice ownership regulation evolution.
Underlying assumptions cover FDA enforcement continuity on compounded drugs, USDA APHIS livestock health mandate stability, and state telemedicine parity legislation progression, with deviation risk concentrated in DEA controlled substance rescheduling and veterinary technician workforce availability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary Medicine
Veterinary Skin Care Products Market
Veterinary Medicine
Global Veterinary/Animal Vaccines Market
Veterinary Medicine
Global Veterinary Autogenous Vaccines Market
Veterinary Medicine
Animal Drugs Market
Veterinary Medicine
Veterinary Pain Management Market
Veterinary Medicine
US Veterinary Orthopedic Medicine Market
Veterinary Medicine
Over-The-Counter (OTC) Veterinary Drugs Market
Veterinary Medicine
Veterinary Anesthesia Market
Veterinary Medicine
Global Brucellosis Vaccines Market
Veterinary Medicine
Veterinary Assistive Reproduction Technology Market
Veterinary Medicine
US Veterinary Diagnostics Market
Veterinary Medicine
Veterinary Orthopedic Medicine Market
Veterinary Medicine
Veterinary Anti-Infectives Market
Veterinary Medicine
Global Veterinary Eye Care Market
Veterinary Medicine
US Veterinarians Market
Veterinary Medicine
Global Newcastle Disease Vaccine Market