
 US Pharmaceutical Isolators Market | 2026-2036
US Pharmaceutical Isolators Market Size, Share, and Industry Trends Forecast 2026-2036
US Pharmaceutical Isolators Market Intelligence
Qualified cleanroom technicians and aseptic processing specialists is reorganizing how pharmaceutical manufacturers scale containment infrastructure across the United States. Bioquell, An Ecolab Solution leverages vaporized hydrogen peroxide expertise to anchor decontamination protocols for isolator-integrated facilities. The Baker Company competes through sustained engineering depth in biological safety cabinet crossover designs. NuAire, Inc. specializes in modular isolator architectures that reduce facility retrofit timelines for biotechnology companies.
US pharmaceutical isolators are sealed, ergonomically accessed enclosures engineered to maintain ISO 5 or better air cleanliness through unidirectional HEPA-filtered airflow, with glove ports enabling operator manipulation without breaching containment boundaries; they serve primarily to protect sterile drug products from environmental contamination and personnel from exposure to cytotoxic or potent compounds. Sterile isolators command the largest installed base among product types, though restricted access barrier systems are gaining share as fill-finish lines modernize. Vaporized hydrogen peroxide technology leads decontamination methodology, while laminar airflow remains foundational to contamination control architectures. Cloud-based deployment models are emerging fastest for environmental monitoring integration, though on-premises systems still dominate validated production environments.
FDA cGMP guidance for sterile drug products, USP <797> and <800> compounding standards, and OSHA containment requirements collectively mandate validated isolator performance for hazardous and non-hazardous sterile preparation across pharmaceutical and biotechnology facilities. These frameworks drive capital allocation toward closed-system isolators with documented decontamination cycles and real-time particle monitoring capabilities. Stakeholders must weigh total cost of ownership against compliance risk as regulatory inspectors intensify scrutiny of isolator qualification documentation and operator training records.
Market Dynamics
FDA enforcement of USP <797> and <800> containment standards is forcing pharmaceutical manufacturers to accelerate isolator replacement cycles ahead of scheduled facility upgrades. This regulatory pressure concentrates capital deployment in the Northeast and Mid-Atlantic corridor where sterile compounding volumes remain highest.
Growth Catalysts
- High-Potency API Manufacturing:Contract manufacturing organizations handling cytotoxic compounds are expanding isolator footprints to meet containment verification requirements under OSHA guidelines.
- USP <800> Hazardous Drug Standards:Revised compounding mandates for sterile preparations are triggering facility retrofits across hospital pharmacies and 503B outsourcing facilities.
- Biopharma Cluster Concentration:Massachusetts and New Jersey manufacturing corridors are driving replacement demand as legacy open-fronted biological safety cabinets reach end-of-life.
Market Restraints
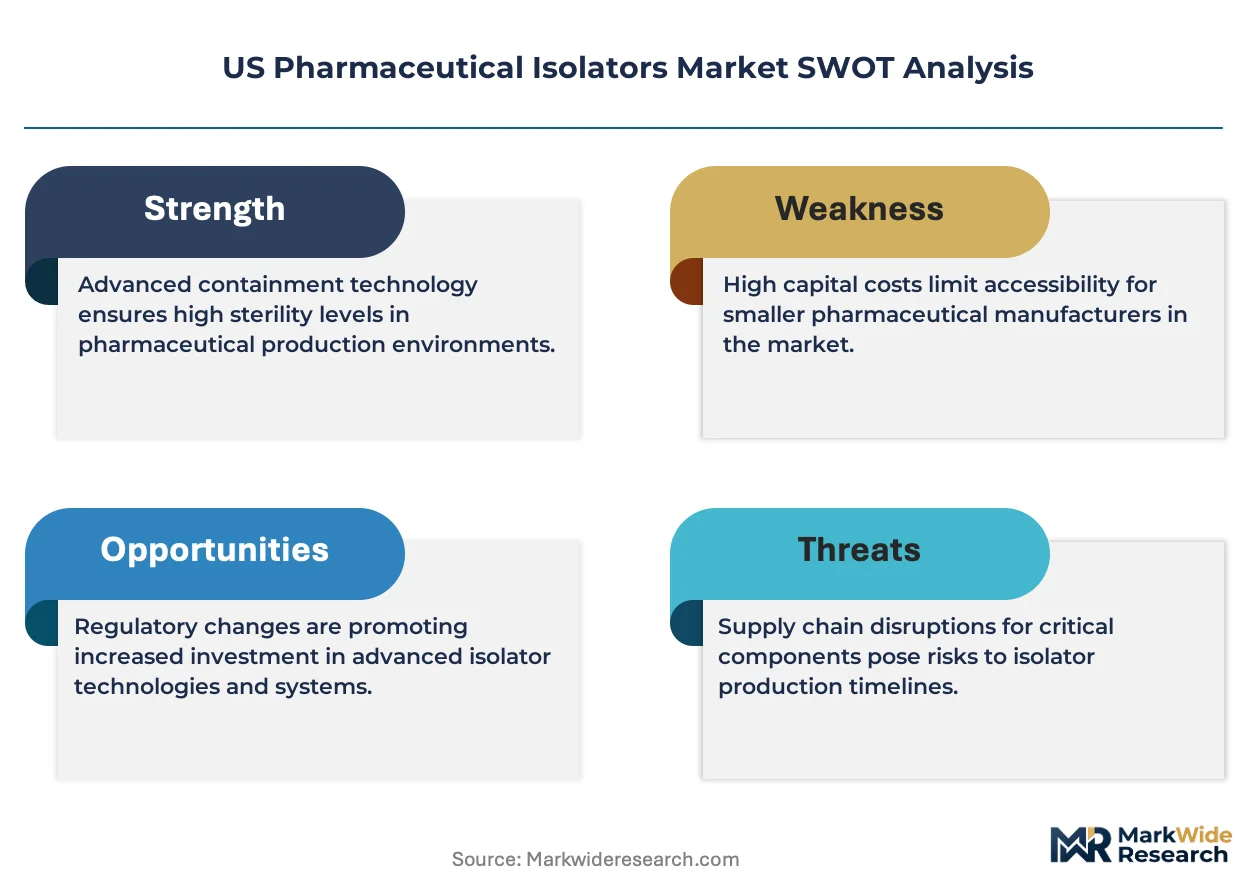
- Stainless Steel Input Volatility:Grade 316L pharmaceutical-grade steel price fluctuations compress margins for custom isolator fabricators serving mid-tier biotechnology companies.
- Specialized Vendor Concentration:HEPA filtration system supply depends on a limited base of certified domestic manufacturers, creating single-source vulnerability for rapid deployment timelines.
- Validation Documentation Burden:FDA cGMP qualification protocols extend commissioning timelines, delaying revenue recognition for capital projects.
Strategic Opportunities
- Cell and Gene Therapy Manufacturing:Emerging viral vector production facilities in Texas and North Carolina present greenfield isolator installation demand outside traditional Northeast strongholds.
- Cloud-Integrated Environmental Monitoring:Real-time particle and pressure data streaming to validated cloud platforms enables predictive maintenance contracts for installed isolator bases.
- Modular Facility Architecture:Pre-fabricated isolator suites reduce construction timelines for biotechnology companies seeking accelerated GMP readiness.
Industry Challenges
- Aseptic Processing Specialist Shortage:Qualified cleanroom technicians with isolator-specific glove port certification remain scarce, constraining operational scale-up for new installations.
- Legacy System Integration:Retrofitting vaporized hydrogen peroxide decontamination cycles into existing fill-finish lines requires extensive mechanical and control system reconfiguration.
- Multi-Site Standardization:Pharmaceutical companies with distributed manufacturing networks face complexity harmonizing isolator protocols across facilities with varying vintage and configuration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Pharmaceutical Isolators Market |
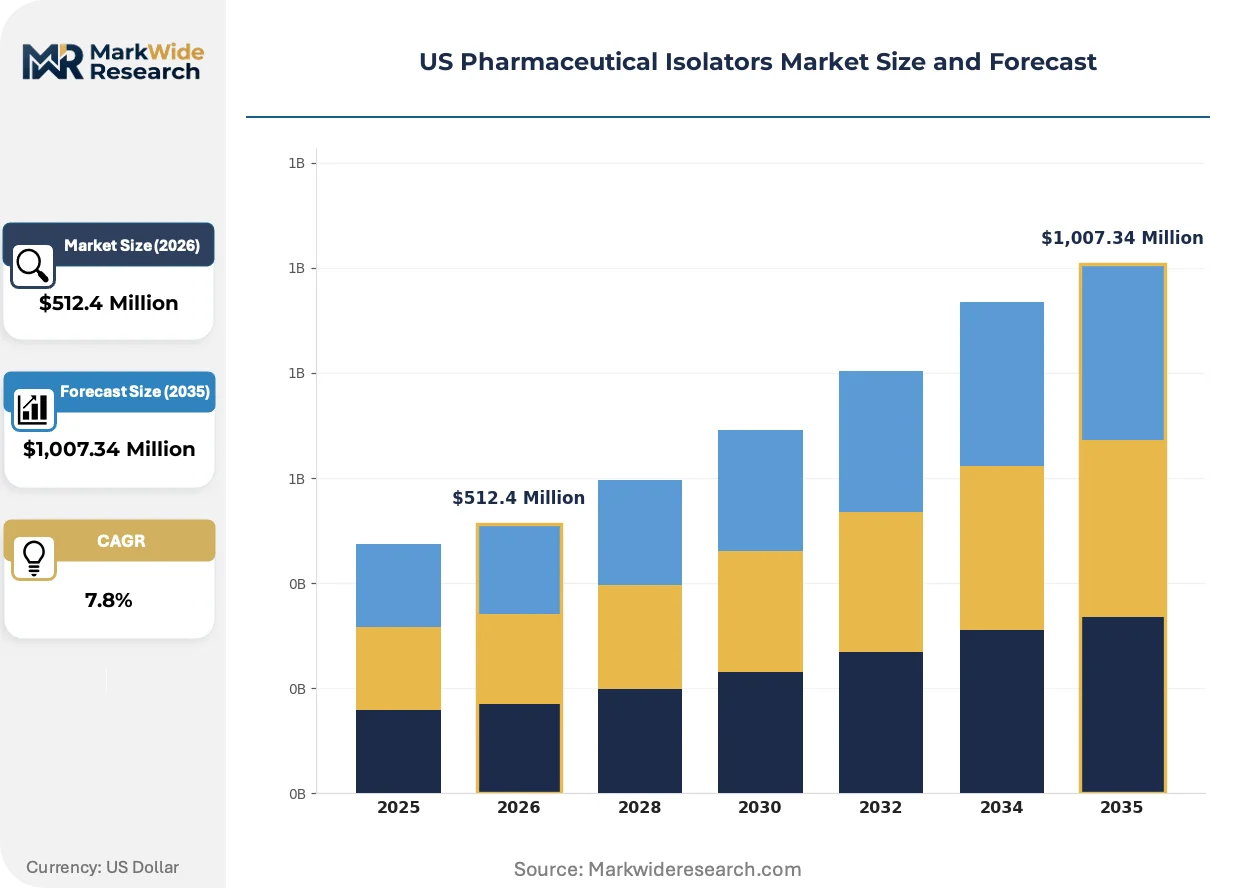
| Market Size in 2026 | $512.4 Million |
| Market Size in 2035 | $1,007.34 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glovebox, Restricted Access Barrier System, Sterile Isolator, Compounding Isolator Technology: Vaporized Hydrogen Peroxide, Ultraviolet Light, Contamination Control, Laminar Airflow End User: Pharmaceutical Manufacturers, Biotechnology Companies, Research Laboratories, Contract Manufacturing Organizations Deployment: On-Premises, Cloud-Based, Hybrid, Mobile |
| Companies Covered | Bioquell, An Ecolab Solution, The Baker Company, NuAire, Inc., Containment Technologies Group, Inc., Terra Universal, Inc., Germfree, Labconco, Schaefer Technologies, Esco Micro Pte. Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Pharmaceutical Isolators Market Strategic Shifts & Innovations
Isolator technology is bifurcating between closed-system sterile enclosures and restricted access barrier systems as fill-finish modernization accelerates. This divergence reflects divergent risk tolerances across pharmaceutical and biotechnology end-uses.
Vaporized hydrogen peroxide decontamination technology is bifurcating isolator procurement into two tiers: facilities requiring sub-6-log sporicidal validation versus those accepting conventional surface disinfection protocols. Biotechnology companies with accelerated clinical timelines are adopting rapid-cycle VHP systems to compress batch turnaround. This split is compressing market share for legacy manual wipe-down decontamination methods in new installations.
FDA cGMP guidance for sterile drug products is tightening documentation requirements for isolator qualification and operator training records. Pharmaceutical manufacturers must now demonstrate continuous environmental monitoring data integrity across multi-year production campaigns. The sterile compounding segment is responding by investing in automated data logging systems with audit trail capabilities.
Hospital pharmacy procurement patterns are consolidating vendor relationships to reduce qualification overhead for 503B outsourcing facilities. Group purchasing organizations are negotiating enterprise isolator service contracts spanning installation through decommissioning. This concentration is most visible in the Southeast, where health system consolidation has created regional sterile compounding hubs serving multiple acute care networks.
US Pharmaceutical Isolators Market Segmentation
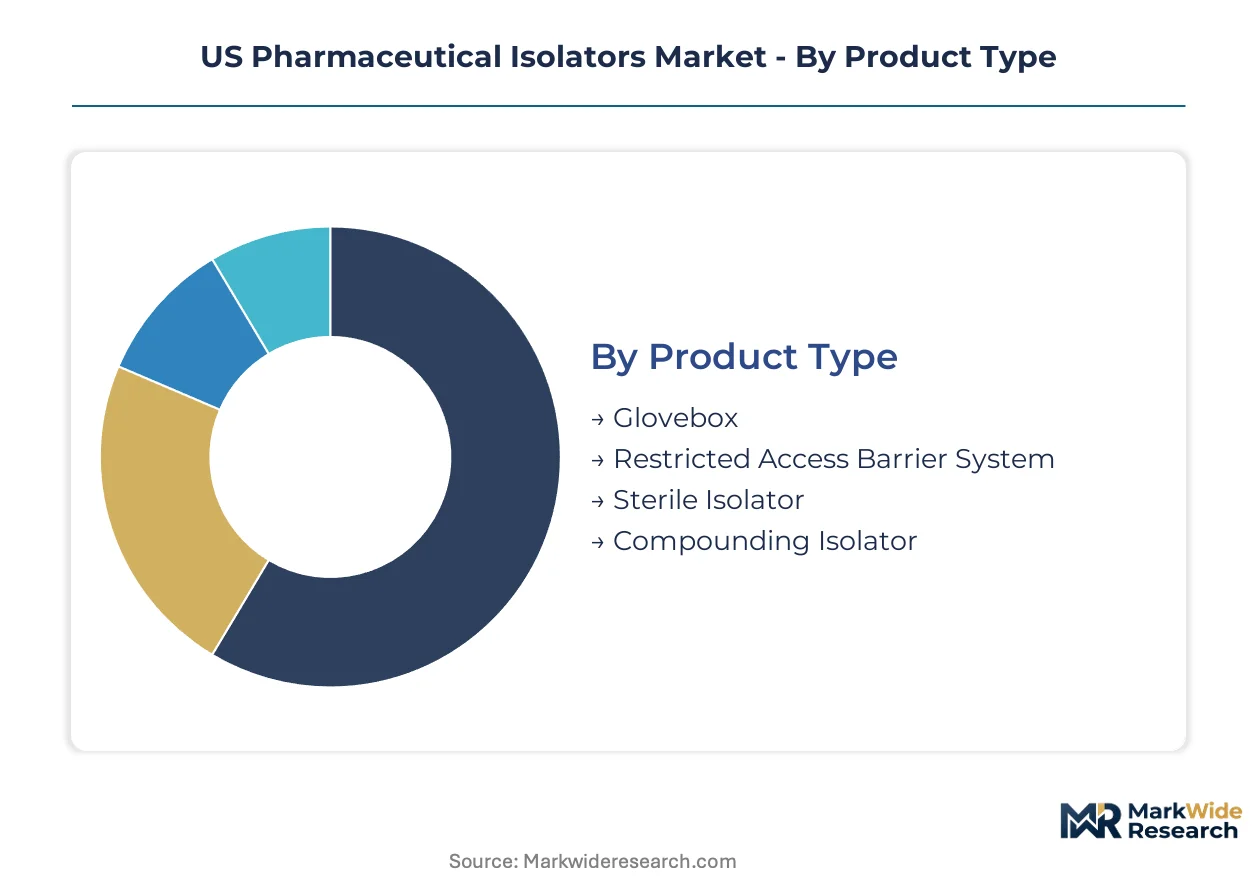
Isolator procurement patterns diverge sharply across product architectures, decontamination methodologies, and facility deployment models. Understanding where capital concentrates within each dimension reveals which specifications command premium pricing versus commodity positioning.
Product Type:
Margins pool heaviest in closed-system sterile enclosures where FDA validation requirements create technical barriers to substitution.
- Sterile Isolator:Sealed enclosures maintaining ISO 5 unidirectional HEPA airflow through rigid wall construction with integrated glove ports. Massachusetts and New Jersey biopharma clusters drive replacement demand as legacy units face USP <797> compliance deadlines.
- Restricted Access Barrier System:Partial enclosure designs separating operators from critical zones via glove sleeves and transfer hatches rather than full isolation. Fill-finish modernization programs in Texas and North Carolina are rotating this architecture up from niche status.
- Compounding Isolator:Compact units engineered for hospital pharmacy and 503B outsourcing facility hazardous drug preparation under USP <800> containment mandates.
- Glovebox:Basic containment enclosures for laboratory-scale manipulation of potent compounds without integrated environmental monitoring systems.
Sterile Isolator holds installed capacity. Restricted Access Barrier System is rotating up the share rankings.
Technology:
Decontamination cycle speed and sporicidal validation depth determine contract value and recurring service attachment rates.
- Vaporized Hydrogen Peroxide:Automated gaseous decontamination achieving sub-6-log sporicidal kill across complex geometries. Bioquell's integrated protocol expertise anchors adoption among CMOs handling high-potency APIs under OSHA containment guidelines.
- Laminar Airflow:Unidirectional HEPA-filtered air delivery forming the foundational contamination control architecture for all validated isolator designs. Northeast corridor facilities specify this technology as baseline for regulatory inspection readiness.
- Contamination Control:Real-time particle monitoring and pressure differential management systems with automated alarm protocols.
- Ultraviolet Light:Surface decontamination adjunct for rapid turnaround applications where VHP cycle times create bottlenecks.
Vaporized Hydrogen Peroxide captures the steepest expansion trajectory as batch compression demands intensify.
End User:
Customer scale and regulatory exposure breadth shape procurement sophistication and total contract value.
- Contract Manufacturing Organizations:Multi-client facilities requiring flexible isolator configurations to accommodate varying potency classifications and batch sizes. CMOs in New Jersey and Pennsylvania are expanding footprints to capture high-potency API outsourcing demand.
- Pharmaceutical Manufacturers:Integrated drug companies with dedicated fill-finish lines and standardized qualification protocols across distributed networks. These buyers concentrate spend in the Northeast where legacy biological safety cabinet replacement cycles peak.
- Biotechnology Companies:Emerging viral vector and cell therapy producers prioritizing modular isolator suites for accelerated GMP readiness in Texas and North Carolina.
- Research Laboratories:Academic and preclinical facilities with lower validation stringency and smaller unit specifications.
Contract Manufacturing Organizations dominate current order intake. Biotechnology Companies are climbing the fastest in forward procurement pipelines.
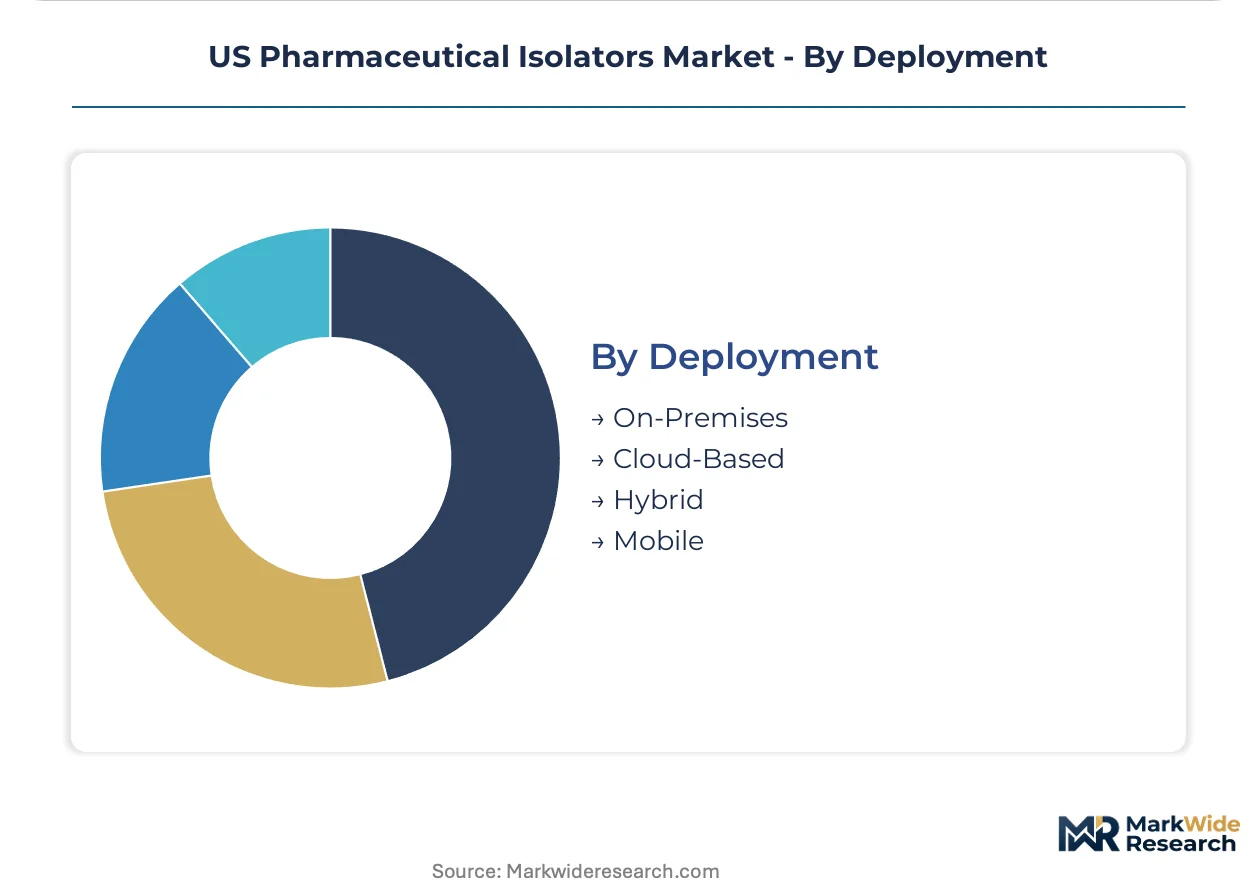
Deployment:
Data residency requirements and validation complexity create divergent adoption curves across infrastructure models.
- On-Premises:Local server architectures maintaining environmental monitoring data within facility firewalls for direct FDA audit trail compliance. Validated production environments in the US still specify this model exclusively.
- Cloud-Based:Remote data streaming enabling predictive maintenance and multi-site dashboard visibility. Early adoption concentrates among cell therapy facilities seeking operational agility outside traditional compliance frameworks.
- Hybrid:Partitioned architectures keeping critical control data local while streaming non-validated analytics to cloud platforms.
- Mobile:Trailer-mounted isolator suites for temporary manufacturing capacity or emergency sterile compounding.
On-Premises retains validated dominance. Cloud-Based is gaining share fastest among greenfield biotechnology installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA cGMP enforcement and USP containment standards are reshaping capital deployment across United States pharmaceutical manufacturing corridors. Regional demand concentrates where biopharma clusters intersect with regulatory inspection intensity.
Northeast Corridor
New Jersey and Massachusetts anchor domestic isolator demand through dense contract manufacturing and fill-finish operations. USP <797> and <800> compliance deadlines are accelerating replacement cycles for legacy biological safety cabinets. Boston-Cambridge biopharma clusters and New Jersey's high-potency API manufacturing belt are driving premium closed-system isolator procurement.
Mid-Atlantic
Pennsylvania pharmaceutical manufacturing is expanding isolator footprints to capture outsourcing demand from integrated drug companies. OSHA containment guidelines for cytotoxic compounds are tightening verification requirements. Philadelphia and Pittsburgh metropolitan areas are seeing greenfield installations for viral vector production facilities.
Southeast
North Carolina's Research Triangle and emerging Texas biotech corridors are attracting cell and gene therapy manufacturing investment. FDA cGMP readiness timelines are compressing, favoring modular isolator suites over conventional construction. Raleigh-Durham and Houston metropolitan clusters are witnessing accelerated commissioning schedules for pre-fabricated containment systems.
West Coast
California's biotechnology ecosystem is prioritizing rapid-cycle decontamination technologies to support accelerated clinical development. USP <800> hazardous drug standards are extending to 503B outsourcing facilities. San Francisco Bay Area and San Diego biotech clusters are specifying cloud-integrated environmental monitoring for operational agility.
US Pharmaceutical Isolators Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, creating a bifurcated competitive structure. The upper tier commands premium positioning through validated decontamination protocol integration and multi-site service contracts. Mid-tier fabricators compete on modular architecture and compressed delivery timelines. Dominant competitive moves include strategic partnerships for HEPA filtration supply security and backward integration into stainless steel fabrication capabilities.
Among decontamination technology specialists, Bioquell, An Ecolab Solution represents integrated protocol expertise spanning vaporized hydrogen peroxide systems and facility-wide bioburden control. The Baker Company exemplifies sustained engineering depth in containment crossover designs between biological safety cabinets and full isolator architectures. NuAire, Inc. occupies a position within the modular fabrication tier, anchoring pre-engineered isolator suites for accelerated GMP readiness.
| Leading Market Players |
|---|
| Bioquell, An Ecolab Solution |
| The Baker Company |
| NuAire, Inc. |
| Containment Technologies Group, Inc. |
| Terra Universal, Inc. |
| Germfree |
| Labconco |
| Schaefer Technologies |
| Esco Micro Pte. Ltd. |
| Others |
Cost & Logistics Intelligence
Capacity utilization at Grade 316L stainless steel mills shapes both supply concentration and price floors for custom isolator fabricators, compressing margins for mid-tier biotechnology companies while reinforcing premium positioning for validated decontamination protocol integrators. FDA cGMP qualification requirements amplify this dynamic by embedding documentation costs that commodity fabricators cannot absorb.
Pricing Analysis
Northeast corridor pricing commands substantial premiums over Southeast and Texas markets, reflecting proximity to dense biopharma clusters and accelerated USP compliance deadlines. Three-tier pricing structure across premium, standard, and economy levels separates closed-system sterile enclosures with sub-6-log VHP validation from basic glovebox architectures. Cost compression in standard-tier units is intensifying because stainless steel input volatility and HEPA filtration supply bottlenecks squeeze fabricator margins. Hospital pharmacy procurement through group purchasing organizations demonstrates highest price sensitivity, while contract manufacturing organizations handling high-potency APIs prioritize containment verification over unit cost.
Supply Chain Analysis
The United States anchors HEPA filtration system fabrication and vaporized hydrogen peroxide decontamination equipment production, while Germany and Japan supply precision pneumatic components for glove port mechanisms. Domestic isolator assembly draws from Chinese-sourced electronics, Indian pharmaceutical-grade steel shipments, and domestic stainless steel rolling capacity. Single-source vulnerability concentrates in certified HEPA media manufacturing, where limited domestic producers create qualification bottlenecks for rapid deployment timelines. Distribution runs through direct manufacturer relationships with large pharmaceutical manufacturers and group purchasing organization contracts serving hospital pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA cGMP enforcement of USP containment standards is accelerating replacement cycles ahead of traditional facility upgrade timelines, compressing commissioning windows and favoring modular pre-fabricated architectures over conventional construction.
For Market Incumbents: Compound service attachment rates by embedding predictive maintenance contracts within vaporized hydrogen peroxide decontamination system sales, countering modular specialist encroachment. Deepen backward integration into stainless steel fabrication capabilities to insulate margin structures from Grade 316L price volatility. Prioritize multi-site standardization protocols for pharmaceutical manufacturers with distributed manufacturing networks, converting replacement demand into enterprise service relationships. For New Entrants and Emerging Players: FDA 510(k) fast-track for cloud-integrated environmental monitoring modules offers entry pathway into validated production environments without confronting incumbent decontamination protocol dominance. Target biotechnology companies in Texas and North Carolina seeking accelerated GMP readiness, where modular isolator suite demand outpaces established service infrastructure. Lead with rapid-cycle VHP system specifications that compress batch turnaround for cell therapy manufacturers with accelerated clinical timelines. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors decontamination protocol integrators over standalone hardware fabricators, as recurring service revenue stabilizes cash flows through capital expenditure cycles. Long-term viability hinges on backward integration depth and multi-site service contract penetration rather than unit shipment volume. Monitor FDA inspection citation rates for isolator qualification documentation as inflection indicator for replacement demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA cGMP qualification documentation accelerates commissioning timelines for closed-system sterile enclosures. |
| Manufacturing Scale-Up | Modular isolator suite production reduces facility retrofit timelines for biotechnology companies. |
| Backward Integration | Captive stainless steel fabrication insulates margin structures from commodity price volatility. |
| Strategic Partnership | HEPA filtration supply agreements reduce single-source vulnerability for rapid deployment. |
| Geographic Expansion | Texas and North Carolina greenfield facilities capture cell therapy manufacturing investment outside Northeast corridor. |
Research Approach
Cross-validation between primary interviews with regulatory affairs leads, aseptic processing specialists, hospital pharmacy procurement managers, and contract manufacturing executives anchors the qualitative findings. Secondary validation incorporates FDA cGMP guidance documents, USP <797> and <800> compounding standards, OSHA containment directives, and SEC filings from publicly traded equipment manufacturers. Bottom-up isolator shipment data triangulates against top-down capital expenditure tracking across biopharma manufacturing clusters.
Sensitivity analysis around stainless steel price trajectories and regulatory inspection intensity informs projection robustness across the analysis window. Segmentation modeling incorporates product architecture, decontamination methodology, end-user scale, and deployment model dimensions. CAGRs derive from fitted growth curves calibrated to historical replacement cycle patterns and announced facility expansion timelines. Forecast inputs include USP compliance deadline schedules and announced biopharma manufacturing capacity additions.
Underlying assumptions cover sustained FDA enforcement posture and stable HEPA filtration supply capacity, with deviation risk concentrated in tariff exposure for Chinese-sourced electronics and accelerated cell therapy clinical timelines. Recalibration cycles align with material shifts in USP revision schedules and biopharma cluster migration patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Lyophilization Equipment and Services Market
Pharmaceutical Equipment
North America Pharmacy Automation Market
Pharmaceutical Equipment
Sterile Injectable Contract Manufacturing Market
Pharmaceutical Equipment
Global Pharmacy Automation Systems Market
Pharmaceutical Equipment
Global Rotary Tablet Press Market
Pharmaceutical Equipment
Europe Pharmacy Automation Market
Pharmaceutical Equipment
Europe Pharmaceutical Vials Market
Pharmaceutical Equipment
Sterile Vials Market
Pharmaceutical Equipment
Automated Radiosynthesis Modules Market
Pharmaceutical Equipment
Pharmaceutical Sterilization Equipment Market
Pharmaceutical Equipment
North America Unit Dose Manufacturing Market
Pharmaceutical Equipment
Shell Vials Market
Pharmaceutical Equipment
Drug Infusion System Market
Pharmaceutical Equipment
Asia-Pacific Pharmacy Automation Market
Pharmaceutical Equipment
Pharmaceutical Equipment Market
Pharmaceutical Equipment
Pharmerging Contract Manufacturing Market