
 North America Ultrasound Probe Disinfection Market | 2026-2036
North America Ultrasound Probe Disinfection Market Size, Share, and Industry Trends Forecast 2026-2036
North America Ultrasound Probe Disinfection Market Analytics
Automated high-level disinfection systems are reshaping how ultrasound probes move from procedure room to reuse, replacing manual wipe-down workflows with validated, traceable cycles. CS Medical LLC dominates the automated systems segment with hardware-software integration that logs every disinfection event. Nanosonics competes through trophon technology specialization in point-of-care environments. STERIS leverages its installed base in central sterile processing to cross-sell probe-specific workflows.
Ultrasound probe disinfection encompasses the chemical, thermal, or ultraviolet elimination of pathogenic microorganisms from transducer surfaces between patient contacts, requiring sporicidal efficacy against Mycobacterium terrae and vegetative bacteria while preserving acoustic lens integrity. The primary purpose is preventing healthcare-associated infections during semi-critical procedures involving mucous membrane or non-intact skin contact. Automated systems capture the largest revenue pool due to capital intensity and recurring consumable attachments, while hydrogen peroxide-based chemical methods represent the fastest-growing disinfection category as facilities seek alternatives to glutaraldehyde. Wipes retain share in emergency and transport settings where electrical outlets remain scarce.
FDA reprocessing guidance, CDC HICPAC recommendations, and Joint Commission accreditation standards collectively mandate high-level disinfection for semi-critical ultrasound probes, creating compliance-driven replacement cycles and documentation requirements. The EPA regulates disinfectant chemistry claims through pesticide registration, constraining which active ingredients manufacturers can deploy. Stakeholders must monitor whether emerging photodynamic or cold plasma technologies can satisfy sporicidal efficacy thresholds without the material degradation risks that limit current options.
Market Dynamics
FDA's updated guidance on reusable medical device reprocessing is compelling hospitals and ambulatory surgical centers to abandon visual-inspection protocols in favor of validated, traceable disinfection systems with automated documentation.
Growth Catalysts
- Joint Commission accreditation standards:Mandatory high-level disinfection requirements for semi-critical probes are accelerating capital equipment replacement cycles across US hospital networks.
- Integrated health network consolidation:Standardized probe disinfection workflows are spreading across multi-site ambulatory systems in the Northeast corridor, creating pooled procurement leverage.
- Ultrasound-guided procedural expansion:Rising volumes of transesophageal echocardiography and intracavitary imaging are multiplying probe turnover rates and disinfection frequency requirements.
Market Restraints
- Capital intensity of automated systems:Hardware-software integration platforms require substantial upfront investment, constraining adoption among independent imaging centers and rural critical access hospitals.
- Glutaraldehyde substitution costs:Facilities transitioning to hydrogen peroxide-based chemistries face retraining expenses and compatibility validation for existing probe inventories.
- Supply concentration in automated disinfection hardware:Limited domestic manufacturing capacity for specialized probe reprocessing equipment creates procurement bottlenecks during facility expansion cycles.
Strategic Opportunities
- Point-of-care environment penetration:Emergency departments and transport units lacking electrical infrastructure represent untapped demand for battery-operated or chemical-based disinfection alternatives.
- CDC HICPAC guideline alignment:Anticipated updates to disinfection efficacy thresholds will create replacement demand for systems capable of documented sporicidal performance.
- Ultraviolet-C and photodynamic technology convergence:Emerging non-thermal modalities that preserve acoustic lens integrity while achieving high-level disinfection could capture share from chemical-dependent workflows.
Industry Challenges
- Biomedical engineering skill scarcity:Validation of automated disinfection cycles requires specialized expertise in thermal disinfection engineering and EPA pesticide registration interpretation that outpaces training pipeline output.
- Legacy probe fleet incompatibility:Acoustic lens materials in older transducer models degrade under hydrogen peroxide exposure, forcing parallel inventory management or accelerated capital replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Ultrasound Probe Disinfection Market |
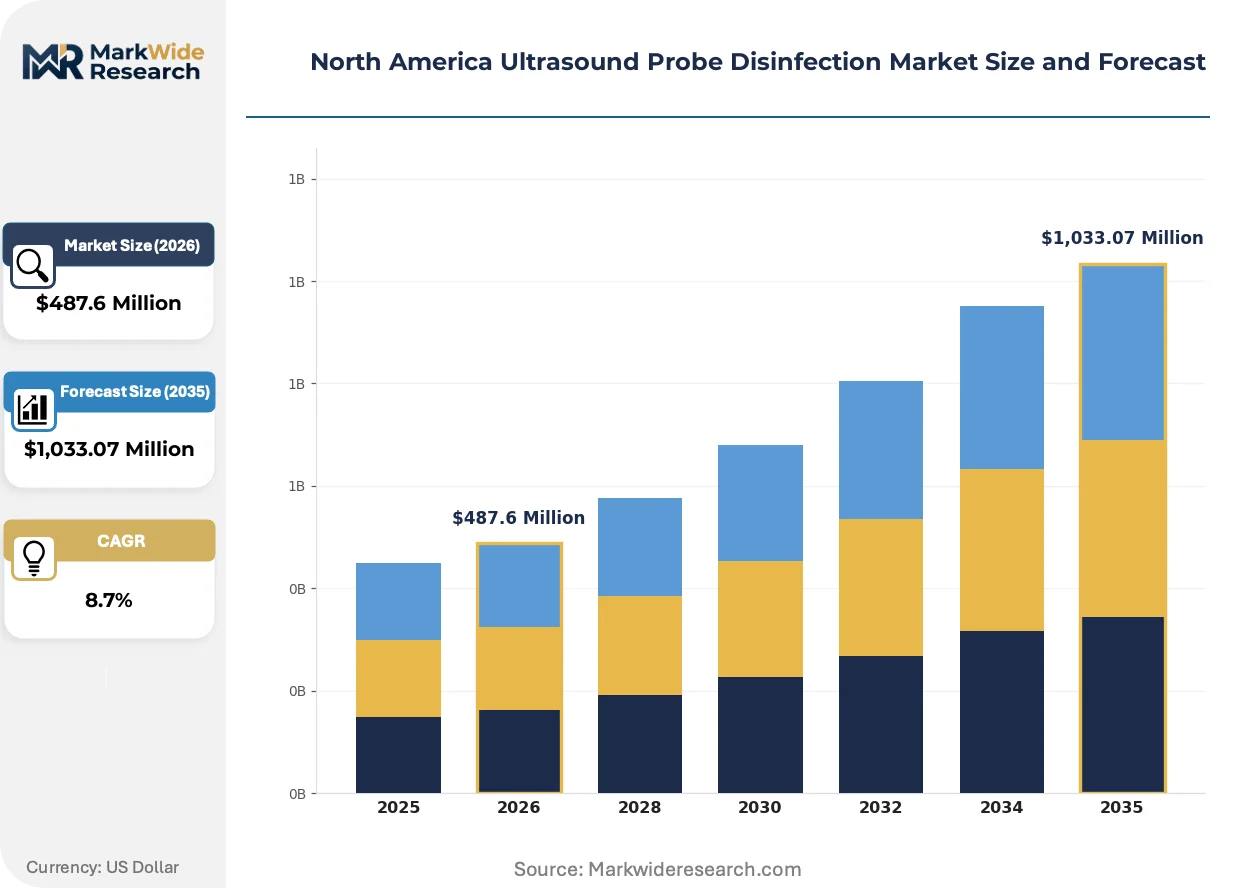
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Systems, Wipes, Soaking Solutions, Sprays Disinfection Method: Ultraviolet Light, Heat, Chemical, Hydrogen Peroxide Application: Hospitals, Clinics, Laboratories, Point-of-Care End User: Healthcare Providers, Diagnostic Centers, Research Facilities, Ambulatory Surgical Centers |
| Companies Covered | CS Medical LLC, STERIS, Nanosonics, ASP, Tristel Plc, CIVCO Medical Solutions, Ecolab Inc., General Electric Company, Germitec, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Ultrasound Probe Disinfection Market Evolving Landscape
Traceability and documentation automation are displacing paper-based compliance logs, while non-chemical disinfection modalities challenge incumbent chemistries. Procurement patterns are compressing toward integrated system contracts rather than standalone consumable purchasing.
Radio-frequency identification and cloud-based cycle logging is digitizing compliance documentation for every probe disinfection event. Hospital infection control departments are mandating these systems to satisfy Joint Commission surveyor demands for objective evidence. This capability is compressing liability exposure and enabling real-time audit readiness.
EPA pesticide registration requirements for sporicidal disinfectant claims are tightening chemistry validation protocols for manufacturers seeking alternative active ingredients. Facilities face reformulation-driven supply disruptions as glutaraldehyde alternatives undergo extended efficacy testing. Hydrogen peroxide-based systems are capturing preference in California and Northeast states with stricter occupational exposure regulations.
Consolidated procurement through integrated delivery networks is displacing site-by-site purchasing autonomy. Ambulatory imaging centers within health system orbits are losing independent vendor selection authority as central sterile processing departments standardize workflows. This concentration is most visible in Texas and Florida health systems pursuing multi-state operational uniformity.
North America Ultrasound Probe Disinfection Market Segmentation
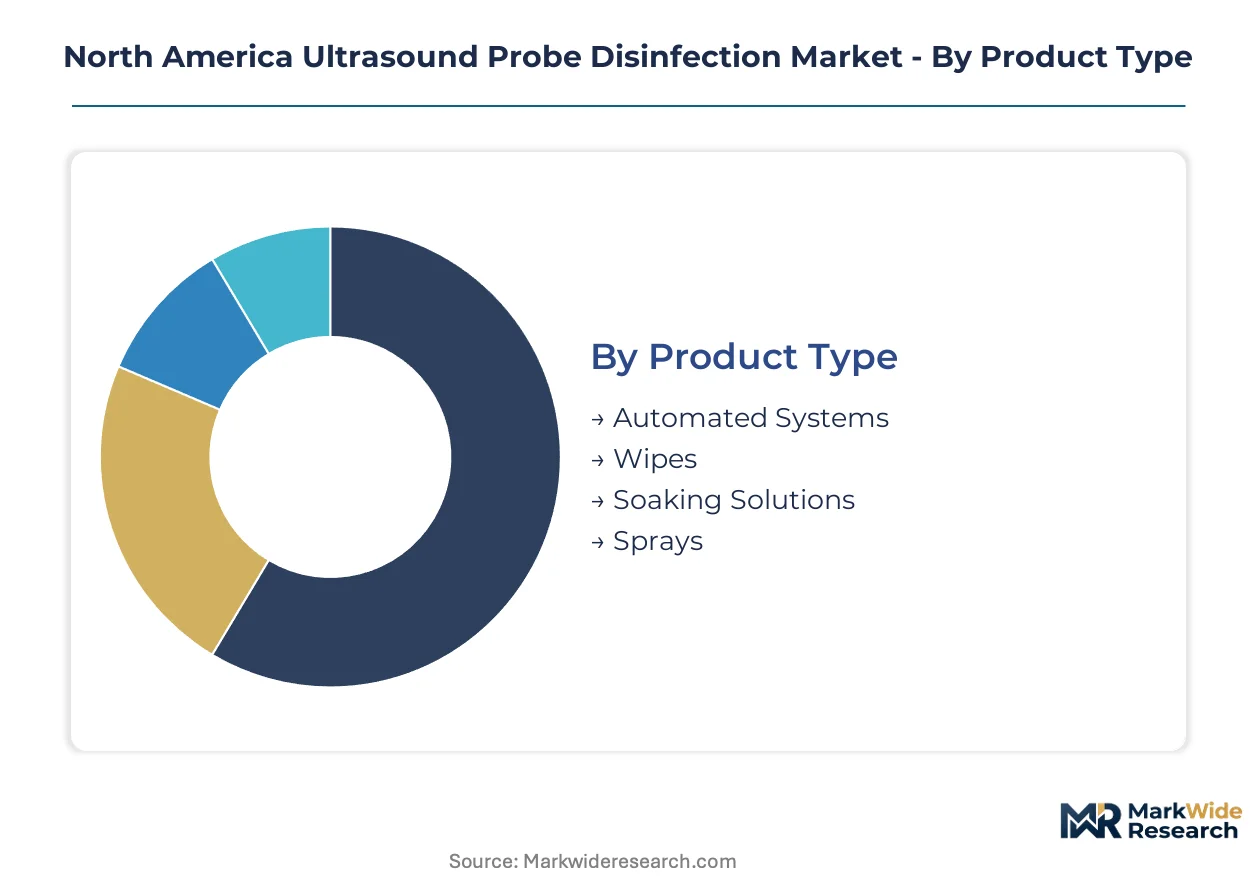
Probe disinfection markets segment along workflow intensity and capital deployment patterns. Cycle times vary dramatically: automated systems amortize over years while consumables turn weekly. Understanding these velocity differences clarifies where procurement leverage concentrates and where vendor lock-in forms.
Product Type:
Automated systems command the longest replacement cycles at seven to ten years, while wipes and sprays turn over in quarterly purchasing rhythms.
- Automated Systems:Hardware-software platforms with RFID logging and thermal or chemical disinfection chambers. Demand clusters in Northeast corridor integrated delivery networks where Joint Commission audit readiness justifies capital expenditure.
- Wipes:Pre-saturated towelettes with quaternary ammonium or hydrogen peroxide chemistry. Emergency departments and air ambulance services in rural Montana and Alaska depend on these where electrical infrastructure remains unreliable.
- Soaking Solutions:Glutaraldehyde or peracetic acid baths requiring manual probe submersion. Small independent imaging centers in Texas and Florida maintain these for legacy probe fleets.
- Sprays:Aerosolized disinfectant formulations for surface coverage. Transport units and temporary field hospitals stock these for rapid deployment scenarios.
Automated systems dominate installed base. Wipes represent where expansion concentrates for point-of-care penetration.
Disinfection Method:
Capital intensity stratifies sharply: ultraviolet and thermal modalities require fixed infrastructure while chemical methods travel.
- Ultraviolet Light:UVC emitters targeting nucleic acid disruption without thermal stress. Research hospitals in Boston and San Francisco pilot these for TEE probe preservation.
- Heat:Automated pasteurization cycles reaching sporicidal temperatures. Central sterile processing departments in Ontario and Quebec health systems standardize on thermal validation.
- Chemical:Glutaraldehyde and ortho-phthalaldehyde formulations with established EPA registrations. Legacy adoption persists where retraining budgets remain constrained.
- Hydrogen Peroxide:Low-temperature vapor or liquid systems with faster turnaround times. California and Washington State facilities favor these under stricter OSHA exposure limits.
Chemical methods retain the broadest installed footprint. Hydrogen peroxide is climbing the fastest on regulatory tailwinds.
Application:
Patient volume throughput and probe turnover frequency determine method selection across settings.
- Hospitals:High-throughput environments with dedicated sterile processing staff. Academic medical centers in New York and Pennsylvania drive automated system procurement.
- Clinics:Lower-volume settings with mixed-procedure schedules. Cardiology and OB-GYN clinics in suburban Chicago and Dallas favor compact tabletop units.
- Laboratories:Research and preclinical imaging facilities with non-patient probes. Biotech corridors in San Diego and Research Triangle Park maintain specialized protocols.
- Point-of-Care:Bedside and emergency environments requiring immediate reuse. Level I trauma centers in Houston and Los Angeles deploy battery-compatible alternatives.
Hospitals anchor capital deployment. Point-of-care is gaining share fastest on ultrasound-guided procedure expansion.
End User:
Procurement autonomy varies: health systems centralize purchasing while independent operators retain vendor flexibility.
- Healthcare Providers:Hospital networks and physician groups with infection control committees. Kaiser Permanente and Mayo Clinic systems standardize cross-facility workflows.
- Diagnostic Centers:Independent imaging facilities with procedure-specific probe fleets. Freestanding echocardiography labs in Florida and Arizona negotiate consumable contracts.
- Research Facilities:Universities and contract research organizations with non-regulatory probe use. NIH-funded institutions in Maryland maintain separate validation protocols.
- Ambulatory Surgical Centers:Medicare-certified same-day surgery facilities with compressed turnaround requirements. Multi-site ASC chains in Texas pursue group purchasing organization leverage.
Healthcare providers dominate volume commitment. Ambulatory surgical centers represent the steepest expansion trajectory on site-of-service migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian manufacturers supply automated disinfection systems to United States hospital networks along the Northeast corridor trade route. Cross-border procurement standardization is accelerating as integrated delivery networks consolidate purchasing authority.
United States
Academic medical centers in New York and Pennsylvania drive automated system deployment for Joint Commission audit readiness. FDA's updated reprocessing guidance mandates validated documentation beyond visual inspection. The Texas Medical Center in Houston anchors point-of-care disinfection demand from Level I trauma throughput.
Canada
Ontario and Quebec health systems standardize thermal disinfection validation across provincial hospital networks. Health Canada aligns device reprocessing standards with FDA frameworks to facilitate cross-border equipment certification. Toronto's central sterile processing hubs supply disinfection protocols to satellite clinics throughout the province.
Mexico
Border-state hospitals in Tijuana and Ciudad Juárez adopt US-equivalent disinfection standards for medical tourism accreditation. COFEPRIS, the national pharmaceutical and medical device regulator, harmonizes sporicidal efficacy requirements with EPA pesticide registration benchmarks. Mexico City Metro hospitals pilot hydrogen peroxide systems under stricter OSHA-aligned occupational exposure limits.
North America Ultrasound Probe Disinfection Market Competitive Landscape
Channel-controlling players compete with product-specialist players across hardware-software integration and consumable chemistry vectors. The market structure concentrates around automated system vendors with recurring revenue attachments and chemical suppliers with EPA-registered formulations. Three archetypes dominate: integrated platform providers, point-of-care specialists, and legacy chemistry incumbents. Competitive moves center on health system contract consolidation and cross-selling into central sterile processing departments.
Among platform-integrated vendors, CS Medical LLC and STERIS exemplify the hardware-software convergence archetype with traceable cycle documentation. Nanosonics occupies a specialist position in compact point-of-care systems. These three companies anchor the competitive map without exhausting the vendor ecosystem.
| Leading Market Players |
|---|
| CS Medical LLC |
| STERIS |
| Nanosonics |
| ASP |
| Tristel Plc |
| CIVCO Medical Solutions |
| Ecolab Inc. |
| General Electric Company |
| Germitec |
| Others |
Value Network & Pricing Analysis
Undercapacity in domestic automated disinfection hardware manufacturing is concentrating supplier leverage toward CS Medical LLC and STERIS, enabling premium pricing for integrated platforms while forcing mid-tier facilities toward extended financing terms or chemical alternatives.
Pricing Analysis
Current-generation automated systems command substantial premiums over prior-generation soaking solutions and next-generation ultraviolet-C platforms still in pilot validation. Pricing stratifies across FDA-validated premium tiers, standard chemical-based systems, and economy wipe formats, with certification grade and volume scale as primary differentiation drivers. Cost compression in the mid-tier is intensifying because integrated delivery networks are consolidating procurement authority and demanding fleet-wide standardization discounts. Independent imaging centers in rural Texas and Montana exhibit highest price sensitivity, while academic medical centers in the Northeast corridor prioritize audit-ready documentation over unit economics.
Supply Chain Analysis
Extended payment terms from 45 to 90 days are becoming standard as suppliers absorb working capital strain from health system procurement consolidation. Manufacturing draws from domestic US assembly for automated systems, Canadian thermal component suppliers, and German precision electronics for RFID logging modules. Specialized hydrogen peroxide chemistry feeds from Belgian and US Gulf Coast production facilities. Single-source vulnerability concentrates in semiconductor chips for cycle documentation hardware. Distribution runs through group purchasing organizations and direct hospital system contracts rather than independent distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as ultrasound-guided procedural volumes multiply probe turnover rates and mandate validated disinfection infrastructure across ambulatory networks previously reliant on visual inspection.
For Market Incumbents: Harden platform stickiness by embedding software companion tools that lock hospital systems into proprietary RFID logging ecosystems, resisting substitution from emerging ultraviolet-C entrants. Deepen backward integration into hydrogen peroxide consumable production to capture margin compression from chemistry suppliers. Prioritize certification investment for anticipated CDC HICPAC guideline updates that will disqualify non-sporicidal systems.
For New Entrants and Emerging Players: Rural critical access hospitals in the Mountain West represent the most penetrable white-space, where capital constraints have delayed automated system adoption and battery-compatible chemical alternatives face minimal competition. Target air ambulance and emergency transport units with portable disinfection formats that circumvent electrical infrastructure gaps. Pursue group purchasing organization bypass strategies that sell direct to independent imaging centers outside integrated delivery network orbits.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among automated system vendors with consumable attachment rates and multi-year service contracts, offering superior cash flow predictability versus standalone chemistry suppliers. The five-to-ten-year viability window favors platforms with EPA-registered sporicidal claims and documented acoustic lens compatibility across major probe OEMs. Watch FDA enforcement patterns on reprocessing validation as the inflection signal—accelerated warning letters would compress replacement cycles and expand addressable market for compliant systems.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission Pathway | 510(k) clearance for novel ultraviolet-C systems accelerates hospital procurement committees' vendor evaluation timelines. |
| Hospital System Partnership | Exclusive supply agreements with Kaiser Permanente or Mayo Clinic networks establish reference sites for multi-site standardization. |
| Software Companion Development | Cloud-based cycle logging integrations satisfy Joint Commission surveyor demands for real-time compliance documentation. |
| Reimbursement Strategy | CPT code alignment for ultrasound-guided procedures indirectly drives probe turnover and disinfection frequency requirements. |
| CE Marking Pathway | Health Canada mutual recognition agreements facilitate cross-border equipment certification for Ontario and Quebec health systems. |
Research Methodology
Cross-validation between primary interviews with infection control officers, biomedical engineering directors, and GPO contracts managers and secondary sources including FDA 510(k) filings, EPA pesticide registration databases, and hospital procurement records anchors the qualitative findings. Bottom-up demand modeling triangulates against top-down health system capital expenditure surveys across the analysis window.
Calibration against historical automated system installation rates and chemistry consumable purchasing patterns informs the projection framework. Segmentation dimensions span product type, disinfection method, application setting, and end-user procurement autonomy. CAGRs derive from probe fleet expansion rates, procedural volume trajectories, and regulatory compliance deadline clustering without year-specific anchoring.
Macroeconomic conditions sit as an overlay; deviation in health system capital expenditure cycles or federal reimbursement policy would shift the trajectory. Forecasts reflect documented assumptions regarding FDA enforcement continuity and CDC guideline update timing. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Adsorption Apheresis Devices Market
Medical Devices
Medical Coatings for Implants Market
Medical Devices
Spinal Machined Bone Allograft Market
Medical Devices
Implantable Cardiac Rhythm Management Device Market
Medical Devices
Echogenic Catheters Market
Medical Devices
Global Transcatheter Pulmonary Valve Market
Medical Devices
US C-Arms Market
Medical Devices
Hyperpigmentation Treatment Devices Market
Medical Devices
Veno-Venous Extracorporeal Life Support (VV ECLS) Devices Market
Medical Devices
Global Pathological Microscopes Market
Medical Devices
Spinal Traction Market
Medical Devices
Vascular Guidewires Market
Medical Devices
Defibrillator Pads Market
Medical Devices
Canada Aesthetic Devices Market
Medical Devices
General Surgical Devices Market
Medical Devices
China Electrocardiograph (ECG) Market