
 Europe Pharmaceutical Vials Market | 2026-2036
Europe Pharmaceutical Vials Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Pharmaceutical Vials Market Foresight
Buyer concentration across European biologics manufacturers is broadening as mid-sized CDMOs and emerging biotech firms diversify procurement beyond traditional large pharma relationships. Gerresheimer AG leverages its molded glass expertise to anchor supply contracts with insulin and vaccine producers. Schott AG competes through its fiolax borosilicate glass platform, sustaining premium positioning in high-pH biologic containment. Stevanato Group differentiates via integrated capabilities spanning glass tubing, processing, and device assembly.
Europe pharmaceutical vials are small-volume primary containers, typically fabricated from borosilicate glass or cyclic olefin polymer, engineered to maintain sterility, chemical stability, and seal integrity for parenteral drug products across freeze-thaw cycles and long shelf lives. Their commercial purpose centers on protecting sensitive biologics, vaccines, and hormones from contamination, oxidation, and moisture ingress throughout manufacturing, distribution, and administration. Glass vials occupy the dominant share of value given regulatory familiarity and inertness, while plastic vials are gaining traction in single-use and temperature-sensitive applications where breakage risk and weight reduction matter. The closure type dimension shows crimp-cap configurations leading in biologics due to validated seal integrity, though needle-safe caps are expanding with self-injection and safety-engineered device growth.
EMA guidelines, the EU Medical Device Regulation, and revised Annex 1 of the EU GMP framework collectively mandate container closure integrity verification, particulate control, and sterilization validation that elevate barrier-performance requirements for vial suppliers. REACH and RoHS constraints further limit extractables and leachables profiles, directing R&D investment toward compliant material formulations and surface treatments. Stakeholders must monitor how evolving EMA quality guidelines and national competent authority inspections reshape qualification timelines and supplier audit intensity.
Market Dynamics
EU Medical Device Regulation and revised Annex 1 of GMP guidelines are compressing supplier qualification timelines while elevating sterility assurance requirements for borosilicate glass and cyclic olefin polymer containment systems across biologics manufacturing clusters.
Growth Catalysts
- EMA Annex 1 revisions:The updated EU GMP framework mandates enhanced container closure integrity verification, forcing biologics manufacturers to upgrade primary containment specifications and driving replacement demand for legacy vial inventories.
- Injectable biologics expansion:Insulin, monoclonal antibodies, and mRNA therapeutics are scaling production across German and Swiss manufacturing corridors, concentrating procurement of high-barrier molded glass and pre-sterilized ready-to-use formats.
- Single-use adoption:Temperature-sensitive biologics and point-of-care distribution networks are accelerating uptake of polymer vials where breakage risk and cold-chain weight reduction outweigh glass inertness advantages.
Market Restraints
- Borosilicate glass supply concentration:Fiolax tubing production concentrates among limited European suppliers, exposing biologics manufacturers to input bottlenecks when furnace capacity tightens or energy costs spike.
- REACH extractables constraints:ECHA limitations on leachable profiles from closure elastomers and surface treatments extend R&D cycles and narrow qualified material options for high-pH biologic formulations.
- Siliconization complexity:Interior surface treatment consistency for protein stability remains technically demanding, yielding batch rejection risks that elevate effective cost per validated vial.
Strategic Opportunities
- Polish and Hungarian CDMO corridors:Mid-sized contract manufacturing expansion in Eastern Europe creates demand for flexible-volume vial supply with shorter lead times than incumbent Western European sources.
- Ready-to-sterilize nested formats:Integration of pre-sterilized vial nests with robotic filling lines reduces aseptic intervention risk, aligning with EMA quality guidelines on contamination control.
- RoHS-compliant polymer formulations:Cyclic olefin polymer innovations that satisfy restricted substance directives open substitution pathways for glass-dominated vaccine and hormone segments.
Industry Challenges
- Annex 1 compliance timeline compression:The August 2023 enforcement deadline for revised EU GMP sterility assurance requirements compressed supplier audit and qualification windows, straining regulatory affairs capacity across biologics firms.
- Specialized molding technician scarcity:Precision glass-forming expertise for pharmaceutical-grade dimensional tolerance is concentrating among aging workforces in Thuringia and Bavaria, constraining capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Pharmaceutical Vials Market |
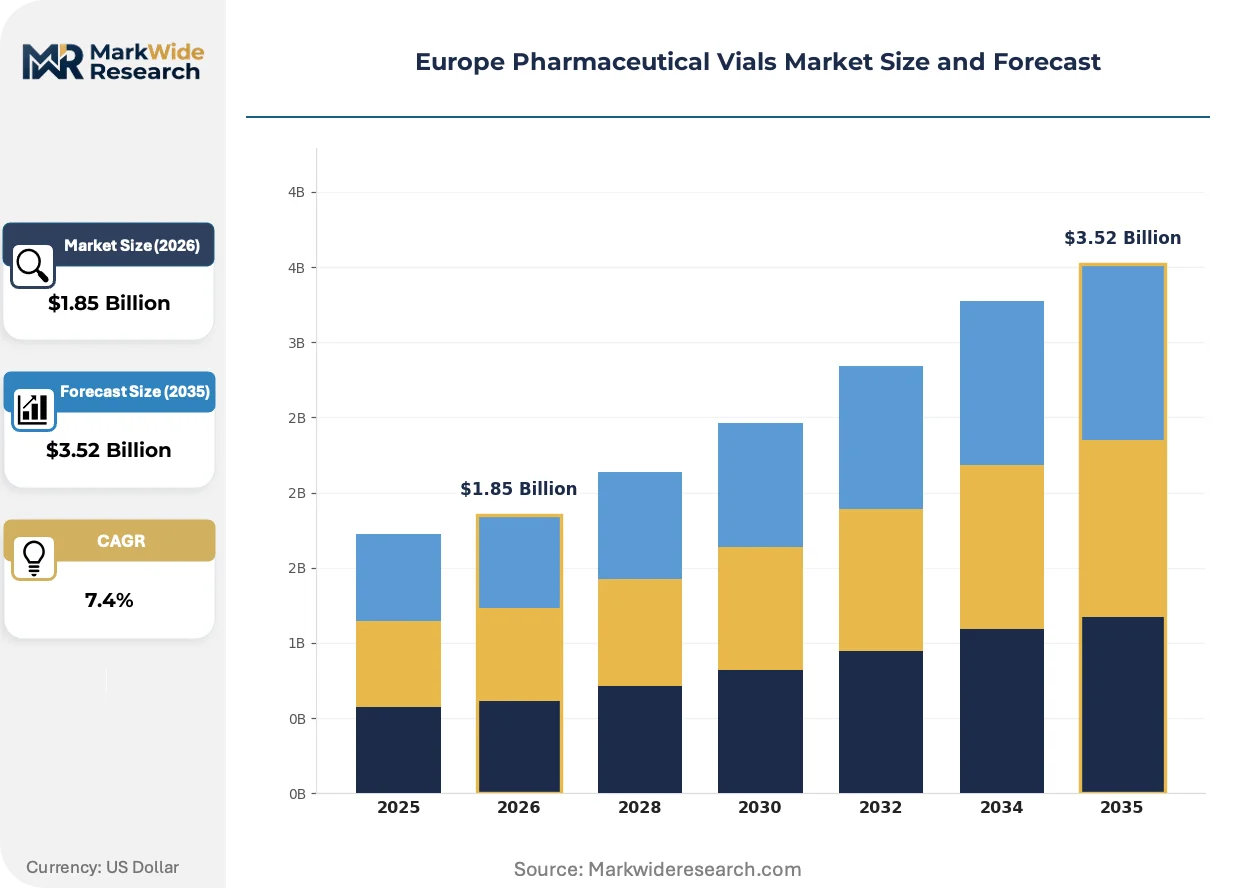
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.52 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass Vials, Plastic Vials, Sterile Vials, Non-Sterile Vials Closure Type: Stopper, Screw Cap, Needle-Safe Cap, Crimp Cap End User: Hospitals, Pharmacies, Research Laboratories, Biotechnology Firms Application: Vaccines, Insulin, Hormones, Antibodies |
| Companies Covered | Schott AG, Gerresheimer AG, Stevanato Group, SGD Pharma, Bormioli Pharma, West Pharmaceutical Services, Nipro Corporation, DWK Life Sciences, Stölzle-Oberglas GmbH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Pharmaceutical Vials Market Shifts & Advancements
Containment technology is bifurcating between premium barrier-performance glass for long-cycle biologics and engineered polymers for distributed cold-chain networks, with regulatory chemistry driving material selection more than cost alone.
Ready-to-use pre-sterilized vial formats are electrifying fill-finish operations by eliminating depyrogenation tunnels and reducing line intervention risk. Biologics manufacturers in the Rhine-Main corridor are adopting these nested configurations at accelerating pace. The technology is compressing facility capital requirements while elevating outsourcing economics for mid-sized CDMOs competing against integrated large pharma operations.
EMA quality guidelines on visible particulate control and closure integrity testing are tightening batch release protocols for parenteral drug products. The industrial consequence is expanded investment in automated inspection systems and probabilistic leak detection methods. High-value biologics segments in Germany and Switzerland are responding by qualifying suppliers with demonstrated particle control capabilities and validated container closure integrity platforms.
Buyer concentration patterns are fragmenting as emerging biotech firms and specialized CDMOs diversify procurement beyond traditional single-source relationships with incumbent glass manufacturers. Direct contracting with tubing converters and secondary processors is displacing bundled supply arrangements in the Netherlands and Denmark. This pattern is most visible among cell and gene therapy developers requiring customized volume formats and rapid qualification timelines.
Europe Pharmaceutical Vials Market Segmentation
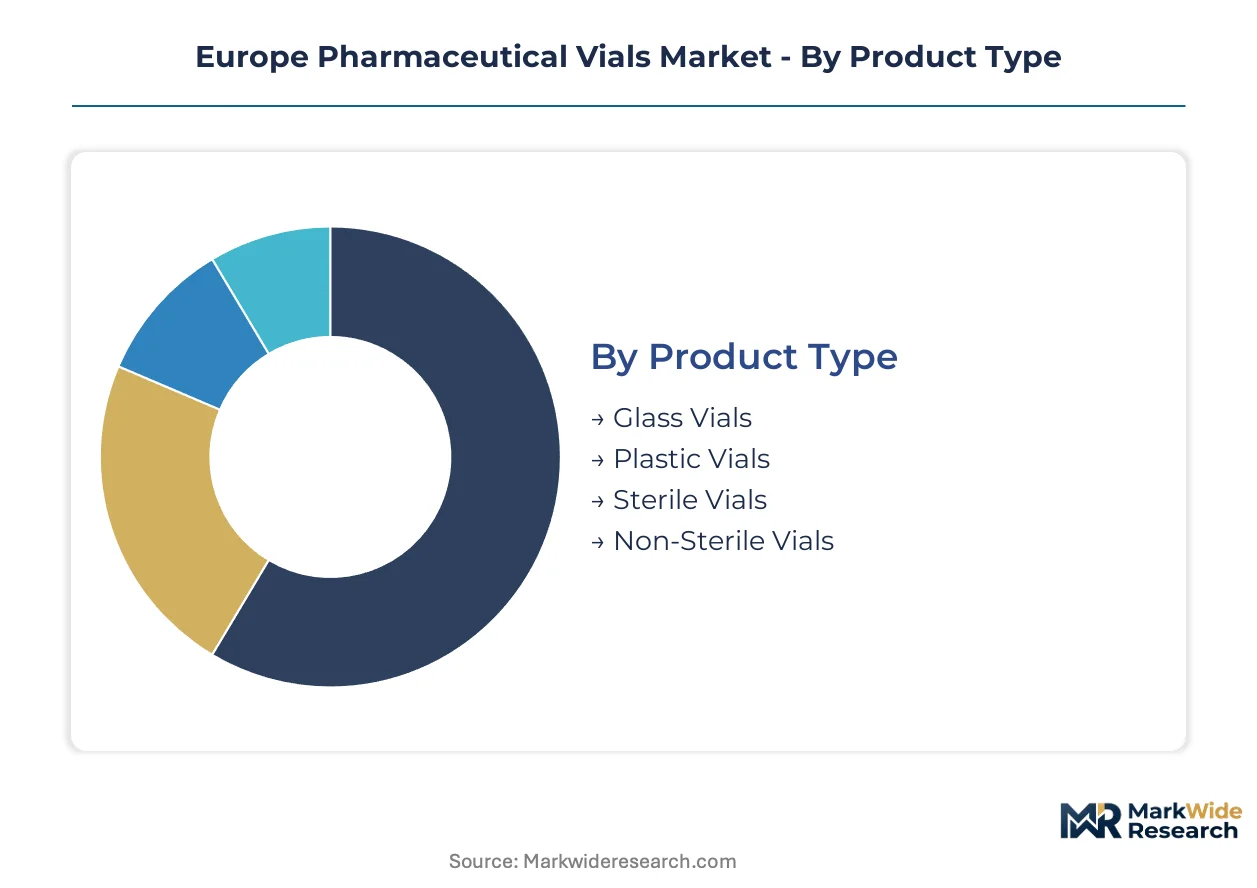
Containment technology selection in European pharmaceutical manufacturing hinges on barrier-performance requirements, sterilization protocols, and distribution logistics. Segmentation reveals how material science and regulatory chemistry partition procurement decisions across biologics value chains.
Product Type:
Glass formats command premium positioning against polymer alternatives, with sterility status separating capital-intensive from commodity supply tiers.
- Glass Vials:Borosilicate construction delivers chemical inertness and thermal shock resistance for freeze-thaw biologics cycles. German insulin and vaccine manufacturers around Frankfurt cluster procurement here, driven by EMA familiarity with Type I glass DMF filings and validated extractables profiles.
- Plastic Vials:Cyclic olefin polymer formulations reduce cold-chain weight and eliminate breakage risk in point-of-care distribution. Demand concentrates among Swiss mRNA therapeutics developers and temperature-sensitive logistics networks where polymer barrier advances now satisfy short-shelf-life containment requirements.
- Sterile Vials:Pre-sterilized ready-to-use formats eliminate depyrogenation tunnels and reduce aseptic intervention risk in fill-finish operations.
- Non-Sterile Vials:Bulk unsterilized supply serves compounders and secondary processors with in-house sterilization capacity.
Mature deployment sits with Glass Vials. Newer deployment is concentrated in Plastic Vials.
Closure Type:
Seal integrity validation and administration safety differentiate closure economics across parenteral drug categories.
- Crimp Cap:Aluminum seal systems with validated container closure integrity dominate long-cycle biologics where sterility assurance over multi-year shelf life is non-negotiable. Rhine-Main corridor manufacturers specify crimp configurations for monoclonal antibody portfolios, compelled by revised EU GMP Annex 1 enforcement on seal verification protocols.
- Needle-Safe Cap:Integrated safety-engineered designs prevent sharps injury during self-injection. Dutch and Danish cell and gene therapy developers are qualifying these formats for patient-administered therapies, aligning with EU Medical Device Regulation requirements on combination product safety.
- Stopper:Bromobutyl and chlorobutyl elastomer formulations provide primary seal interfaces for lyophilized and liquid parenterals.
- Screw Cap:Threaded polypropylene closures serve oral and topical repackaging applications outside sterile injectable standards.
Established biologics manufacturing favors Crimp Cap deployment. Self-injection therapy expansion is driving Needle-Safe Cap qualification fastest.
End User:
Procurement scale and technical specification intensity vary sharply between integrated manufacturing and distributed clinical settings.
- Biotechnology Firms:Emerging and mid-sized developers require flexible-volume supply with rapid qualification timelines for customized formats. Eastern European CDMO corridors in Poland and Hungary are fragmenting procurement patterns here, displacing bundled arrangements with incumbent Western European glass manufacturers.
- Hospitals:Central pharmacy and clinical trial units demand unit-dose and safety-engineered configurations for bedside administration. Swiss and German university hospital networks are consolidating procurement of ready-to-use nested formats to reduce compounding labor and contamination risk.
- Research Laboratories:Small-batch, non-GMP supply for preclinical and analytical applications.
- Pharmacies:Retail and specialty pharmacy repackaging of multi-dose presentations into patient-specific quantities.
Volume concentration rests with Biotechnology Firms. Safety-engineered format uptake is expanding most quickly among Hospitals.
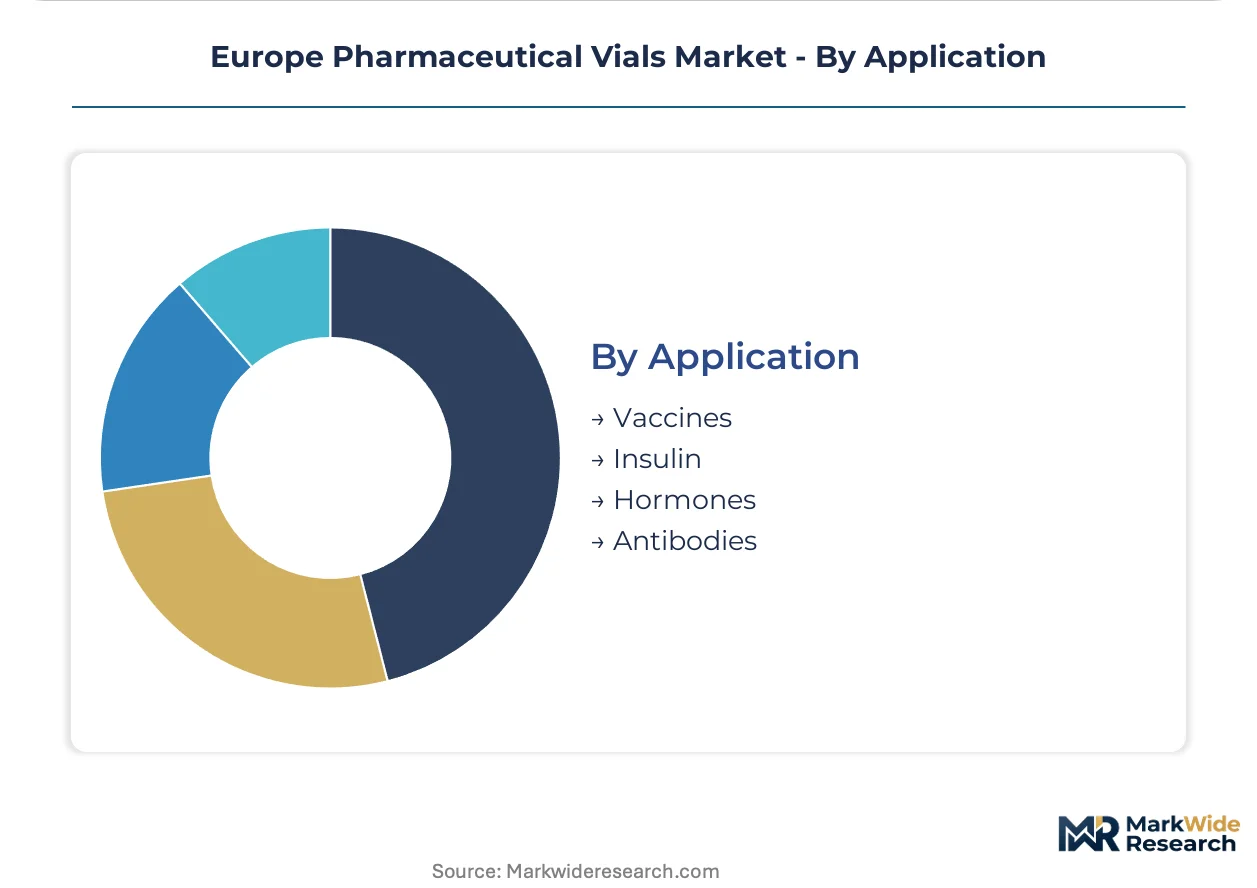
Application:
Therapeutic category determines barrier-performance specifications, with protein stability and oxidation sensitivity driving material selection.
- Antibodies:Monoclonal and polyclonal formulations demand premium borosilicate containment with siliconized interior surfaces to prevent protein aggregation. Bavarian and Thuringian manufacturing clusters specify validated vial-tubing combinations here, constrained by REACH limitations on leachable profiles from closure elastomers.
- Vaccines:Temperature excursion tolerance and distribution weight reduction are accelerating polymer vial trials. mRNA and viral vector platforms in Belgian and Dutch manufacturing corridors are testing cyclic olefin polymer alternatives to glass for cold-chain efficiency gains.
- Insulin:High-volume, multi-dose presentations with established glass-based supply chains and siliconization protocols.
- Hormones:Peptide and steroid formulations requiring light protection and moisture barrier performance.
Antibody applications anchor current premium supply. Vaccine distribution logistics are propelling alternative material qualification fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Injectable biologics manufacturing concentrates in Germany and Switzerland, with emerging CDMO corridors in Poland and Hungary fragmenting traditional procurement patterns toward Eastern Europe.
Germany
Frankfurt and Munich anchor insulin and monoclonal antibody production clusters, driving procurement of high-barrier borosilicate vials. EMA Annex 1 revisions compress supplier qualification timelines for Bavarian manufacturers. Thuringian glass-forming expertise constrains capacity expansion as aging workforces limit precision molding technician availability.
Switzerland
Swissmedic oversight elevates sterility assurance requirements for mRNA therapeutics developers testing cyclic olefin polymer alternatives. Basel and Zurich corridors concentrate viral vector platform manufacturing. Cold-chain weight reduction priorities accelerate polymer vial qualification for temperature-sensitive distribution networks.
Netherlands
Rotterdam and Amsterdam logistics hubs enable direct contracting with tubing converters, displacing bundled supply arrangements. Dutch cell and gene therapy developers qualify needle-safe cap formats for patient-administered therapies. EU Medical Device Regulation combination product safety requirements reshape procurement specifications.
Poland
Warsaw and Krakow CDMO corridors create demand for flexible-volume vial supply with shorter lead times than Western European sources. REACH extractables constraints extend R&D cycles for high-pH biologic formulations. Mid-sized contract manufacturing expansion fragments buyer concentration patterns.
Belgium
Antwerp and Ghent manufacturing clusters test polymer alternatives for vaccine distribution logistics. ECHA limitations on leachable profiles narrow qualified material options. Belgian mRNA platform developers drive alternative material qualification fastest among European vaccine producers.
Europe Pharmaceutical Vials Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue ready-to-use and polymer-based containment solutions. The supplier base concentrates among German and Italian glass specialists with furnace-based borosilicate capacity, while polymer converters and integrated device assemblers occupy adjacent positions. Three archetypes dominate: tubing-integrated glass manufacturers, polymer formulation specialists, and fill-finish line integrators. Capacity expansion and strategic partnerships represent the dominant competitive vectors as EMA compliance timelines compress.
Within the tubing-integrated tier, Schott AG and Gerresheimer AG exemplify archetypes anchored in European glass heritage. Stevanato Group occupies a position spanning glass processing and device assembly. These three represent the structural concentration of supply-side capability as regulatory chemistry elevates barrier-performance requirements and supplier audit intensity across biologics manufacturing corridors.
| Leading Market Players |
|---|
| Schott AG |
| Gerresheimer AG |
| Stevanato Group |
| SGD Pharma |
| Bormioli Pharma |
| West Pharmaceutical Services |
| Nipro Corporation |
| DWK Life Sciences |
| Stölzle-Oberglas GmbH |
| Others |
Supply & Pricing Matrix
Ready-to-use pre-sterilized vial formats simultaneously compress facility capital requirements and concentrate procurement leverage among tubing-integrated manufacturers with validated nested configurations. EMA Annex 1 compliance timelines force biologics producers toward premium supply tiers, amplifying price spreads between qualified and unqualified vial sources.
Pricing Analysis
Volume procurement by German insulin manufacturers anchors the standard tier while Swiss mRNA developers pay premium spreads for polymer barrier validation. Three-tier pricing structure across premium, standard, and economy levels separates EMA-compliant ready-to-use formats from bulk unsterilized supply and commodity repackaging grades. Cost compression in the standard tier intensifies because REACH extractables testing extends R&D cycles and narrows qualified supplier pools. Mid-sized CDMOs in Eastern Europe exhibit highest price sensitivity; integrated large pharma operations with captive fill-finish capacity show lowest.
Supply Chain Analysis
Cold-chain freight costs from Thuringian glass-forming sites to Swiss biologics corridors amplify total landed cost differentials against polymer alternatives shipped from Benelux conversion hubs. Borosilicate tubing supply draws from Germany, Italy, and limited Czech furnace capacity; elastomer closure formulations rest on bromobutyl rubber sources in France and Belgium. Single-source vulnerability concentrates in fiolax-grade tubing production where furnace energy intensity exposes input costs to continental power price volatility. Distribution runs through Rhine-Main logistics clusters serving Frankfurt and Munich manufacturing bases, with Rotterdam and Amsterdam hubs enabling direct converter contracting for Dutch cell therapy developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
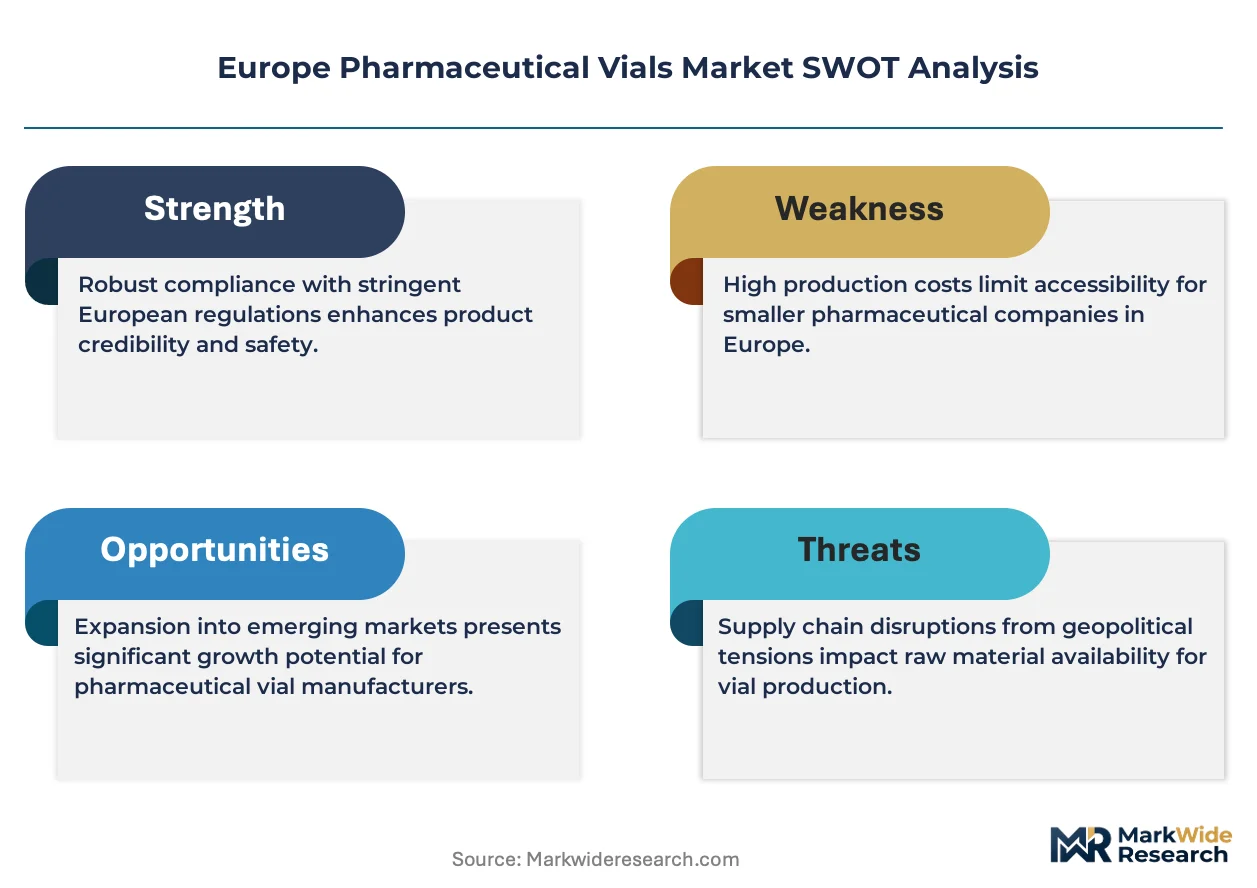
Europe pharmaceutical vials function as a cost-of-compliance market where EU GMP Annex 1 revisions erect regulatory moats favoring incumbents with validated container closure integrity platforms and established EMA quality guideline track records.
For Market Incumbents: Anticipate polymer substitution threats by securing backward integration into cyclic olefin polymer formulation capabilities or exclusive tolling arrangements with specialized converters. Capacity addition in Polish and Hungarian CDMO corridors captures procurement fragmentation from mid-sized biotech firms escaping bundled Western European supply. Certification investment in ready-to-sterilize nested formats defends margin position against robotic fill-finish line integrators encroaching on traditional glass supply. For New Entrants and Emerging Players: Direct-to-biotech digital procurement platforms bypass incumbent distributor networks and compress qualification timelines for customized volume formats. Eastern European CDMO corridors represent the most penetrable geography where shorter lead time requirements outrank brand heritage in supplier selection. Needle-safe cap integration for patient-administered cell therapies offers a defensible entry wedge against tubing-integrated glass manufacturers lacking device assembly capabilities. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by fill-finish line integrators seeking captive vial supply and by polymer converters pursuing pharmaceutical-grade barrier validation. Long-term viability over the next decade hinges on demonstrated EMA inspection pass rates and documented particle control capabilities rather than furnace scale alone. Watch for inflection when Belgian and Dutch mRNA developers announce polymer vial qualification at commercial scale as signal of material substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Ready-to-Sterilize Nested Format Expansion | Aligns with EMA Annex 1 contamination control mandates while reducing fill-finish line capital intensity for CDMOs. |
| Polymer Barrier Formulation Development | RoHS-compliant cyclic olefin innovations open substitution pathways in vaccine and hormone segments dominated by glass. |
| Eastern European CDMO Corridor Targeting | Polish and Hungarian contract manufacturing growth fragments procurement toward flexible-volume suppliers with regional logistics advantage. |
| Automated Inspection System Integration | Visible particulate control investments satisfy tightening EMA batch release protocols for high-value biologics. |
| Closure Elastomer REACH Compliance Program | ECHA leachable limitations on bromobutyl formulations demand reformulation R&D to maintain qualified material status. |
Research Methodology
EMA quality guideline documentation, EU Medical Device Regulation implementation records, and REACH compliance filings formed the secondary backbone for regulatory constraint mapping. Primary interviews with fill-finish operations directors, regulatory affairs managers at biologics manufacturers, pharmaceutical procurement leads, and glass-forming technical specialists validated supply-side capacity assumptions. Bottom-up triangulation across tubing furnace utilization rates and top-down reconciliation against biologics production capacity announcements anchored volume estimates.
Historical trendline analysis of borosilicate glass and polymer vial procurement patterns informed projection modeling across the analysis window. Segmentation dimensions included material type, sterility status, closure configuration, end-user scale, and therapeutic application category. CAGRs derived from regression analysis of disclosed capacity expansions, qualified supplier audit timelines, and regulatory enforcement phase-in schedules. Forecast inputs incorporated REACH extractables testing cycle durations and Annex 1 compliance deadline impacts on replacement demand.
The model holds under steady EMA enforcement intensity and stable energy cost assumptions; deviation in furnace fuel price volatility or accelerated polymer barrier validation would shift supplier mix projections. Stakeholders should weight assumptions against their own operating context and regulatory inspection history.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Latin America Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Closed Funnel Ampoules Market
Pharmaceutical Equipment
Global Contract Development and Manufacturing Organization (CDMO) Outsourcing Market
Pharmaceutical Equipment
Europe Pharmaceutical Isolator Market
Pharmaceutical Equipment
Sterile Injectable Contract Manufacturing Market
Pharmaceutical Equipment
Sterile Vials Market
Pharmaceutical Equipment
Global Pharmaceutical Contract Manufacturing and Contract Research Market
Pharmaceutical Equipment
Small Molecule CDMO Market
Pharmaceutical Equipment
Pharmaceutical Anti-Counterfeiting Technologies Market
Pharmaceutical Equipment
Sterile Fill-Finish Process Simulation and Media Fill Test Equipment Market
Pharmaceutical Equipment
Inhalation CDMO Market
Pharmaceutical Equipment
Radiosynthesis Equipment Market
Pharmaceutical Equipment
India Contract Manufacturing Organization (CMO) Market
Pharmaceutical Equipment
Flip Top Vials Market
Pharmaceutical Equipment
Middle East and Africa Pharmacy Automation Market
Pharmaceutical Equipment
Pharmaceutical Refrigerators and Freezers Market