
 North America Pharmacy Automation Market | 2026-2036
North America Pharmacy Automation Market Size, Share, and Industry Trends Forecast 2026-2036
North America Pharmacy Automation Market Analytics
USP 800-compliant engineering is redrawing capital deployment across the North America Pharmacy Automation Market. Omnicell Inc. leverages vertical integration across hardware and cloud-hosted software to control hospital formularies. Capsa Healthcare anchors its position through specialized cart-based automation for long-term care facilities. ARxIUM competes with deep specialization in IV robotics for sterile compounding workflows.
North America pharmacy automation encompasses electromechanical systems, software platforms, and verification technologies that receive, store, dispense, and track pharmaceuticals with minimal human intervention; these systems integrate barcode scanners, robotic arms, and weight verification sensors to achieve dispensing accuracy rates exceeding manual processes. Robotic dispensing systems dominate capital expenditure budgets across hospital end users, while automated medication management solutions capture recurring software revenue through subscription-based implementation models. RFID tracking technology is displacing legacy barcode verification in high-value oncology and biologics dispensing, where real-time location tracking reduces diversion risk and supports cold chain integrity.
The US FDA enforces Drug Supply Chain Security Act serialization requirements that mandate interoperable track-and-trace systems, directly shaping barcode verification and software integration purchasing decisions. State boards of pharmacy in California and Florida impose distinct sterile compounding regulations that filter which IV robot configurations qualify for licensure. Health Canada and provincial health authorities in Ontario coordinate procurement standards that determine which automated packaging systems receive hospital formulary approval. Stakeholders must monitor evolving state-level pharmacy practice acts and federal interoperability mandates to time capital replacement cycles and avoid stranded equipment investments.
Market Dynamics
USP 800 compliance mandates are compressing replacement cycles for sterile compounding infrastructure across hospital and long-term care settings, forcing capital redeployment toward negative-pressure robotics and isolator-based workflows.
Growth Catalysts
- FDA Drug Supply Chain Security Act:Serialization requirements for interoperable track-and-trace systems are accelerating barcode verification and RFID integration investments across hospital formularies.
- Ontario Health procurement coordination:Provincial standardization for automated packaging systems is consolidating vendor qualification pathways and reducing hospital procurement friction.
- IV robotics:Sterile compounding automation is capturing expanded capital allocation as state boards of pharmacy tighten personnel exposure limits for hazardous drug handling.
Market Restraints
- Stainless steel and servo motor cost volatility:Input price swings for precision mechanical components are squeezing gross margins on robotic dispensing hardware.
- Single-source component concentration:Specialty pneumatic actuators and machine vision modules face supply bottlenecks from concentrated Asian manufacturing clusters.
- California Board of Pharmacy sterile compounding:Distinct state-level engineering requirements create regulatory friction that delays multi-state equipment deployment.
Strategic Opportunities
- Quebec long-term care automation:Underpenetrated skilled nursing facilities present white space for cart-based medication management systems with French-language software interfaces.
- Cold chain biologics convergence:Integration of RFID temperature logging with robotic dispensing is opening oncology and cell therapy pharmacy workflows.
- Subscription software models:Cloud-hosted inventory management platforms are displacing perpetual license structures and capturing recurring revenue from health system consolidation.
Industry Challenges
- Pharmacy informatics specialist scarcity:Shortage of technicians cross-trained in both clinical workflows and automation troubleshooting is extending implementation timelines.
- Legacy HIS integration complexity:Proprietary communication protocols between vendor-specific robotics and existing hospital information systems are requiring costly middleware development.
- USP 800 facility renovation capex:Physical infrastructure upgrades for negative-pressure suites are competing with automation hardware for limited capital budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Pharmacy Automation Market |
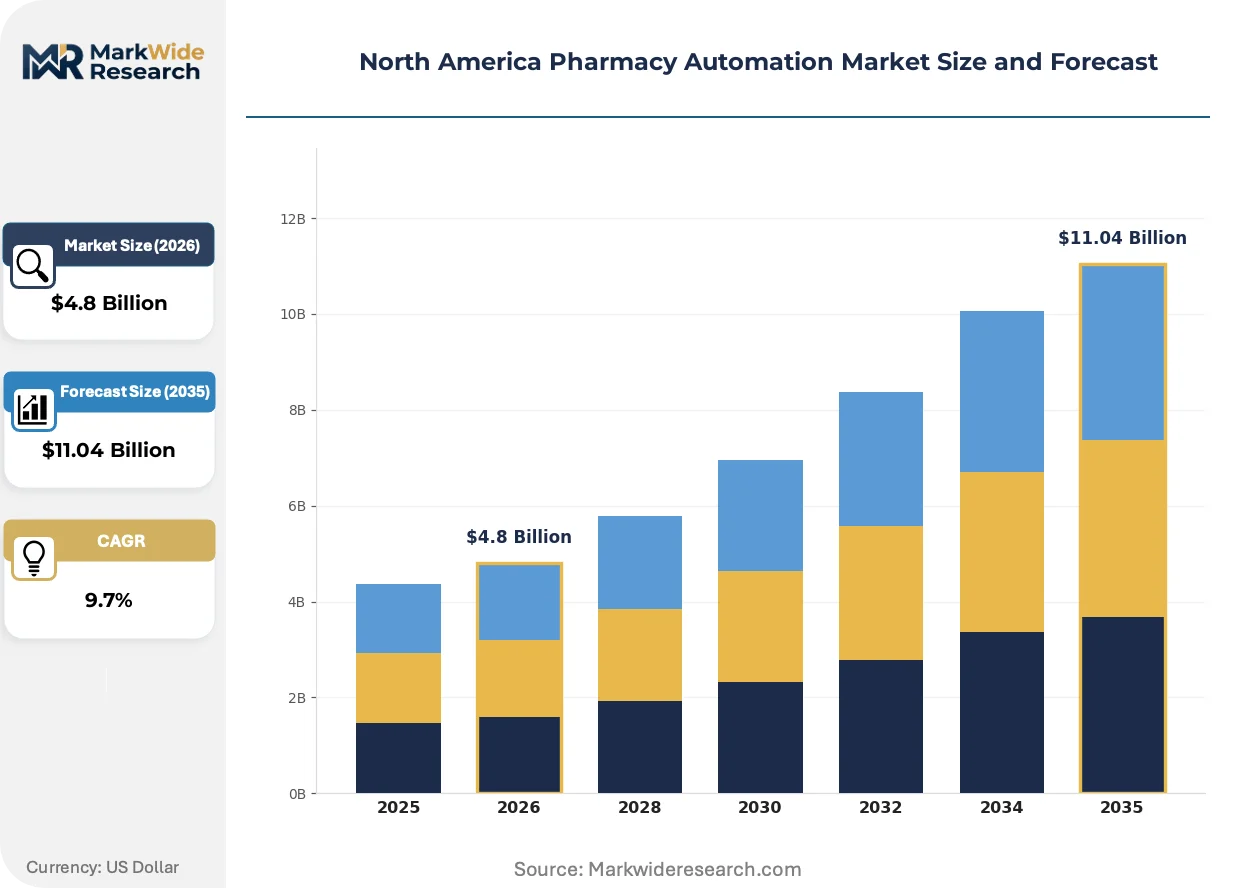
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Dispensing Systems, Automated Medication Management, IV Robots, Automated Packaging Systems End User: Hospitals, Retail Pharmacies, Long-term Care Facilities, Clinics Technology: Barcode Verification, RFID Tracking, Software Integration, Cloud-based Solutions Implementation Model: On-premise, Cloud-hosted, Hybrid, Outsourced |
| Companies Covered | Omnicell Inc., Capsa Healthcare, ARxIUM, ScriptPro LLC, RxSafe, Becton Dickinson and Company, Baxter International, Parata Systems LLC, McKesson, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Pharmacy Automation Market Evolving Landscape
Workflow automation is compressing the boundary between dispensing hardware and clinical decision support, with real-time inventory intelligence now embedded directly at the point of care.
Autonomous mobile dispensing cabinets are miniaturizing to unit-dose capacity for bedside medication administration. Rural critical access hospitals in Montana and Idaho are piloting these units to extend centralized pharmacy coverage. The form factor shift is miniaturizing capital deployment thresholds and opening community hospital segments previously priced out of robotics.
Florida's Board of Pharmacy has imposed distinct beyond-use dating requirements for sterile compounds that exceed federal minimums. This regulatory layering is forcing IV robot vendors to engineer state-specific software configurations. High-volume oncology centers in Miami-Dade and Tampa are absorbing these compliance costs to maintain compounding licensure.
Health system procurement committees are consolidating vendor relationships through enterprise framework agreements that bundle hardware, software, and maintenance across multiple facilities. Group purchasing organizations are displacing individual hospital negotiations in California and Texas. This concentration is most visible among Catholic health systems spanning multiple states.
North America Pharmacy Automation Market Segmentation
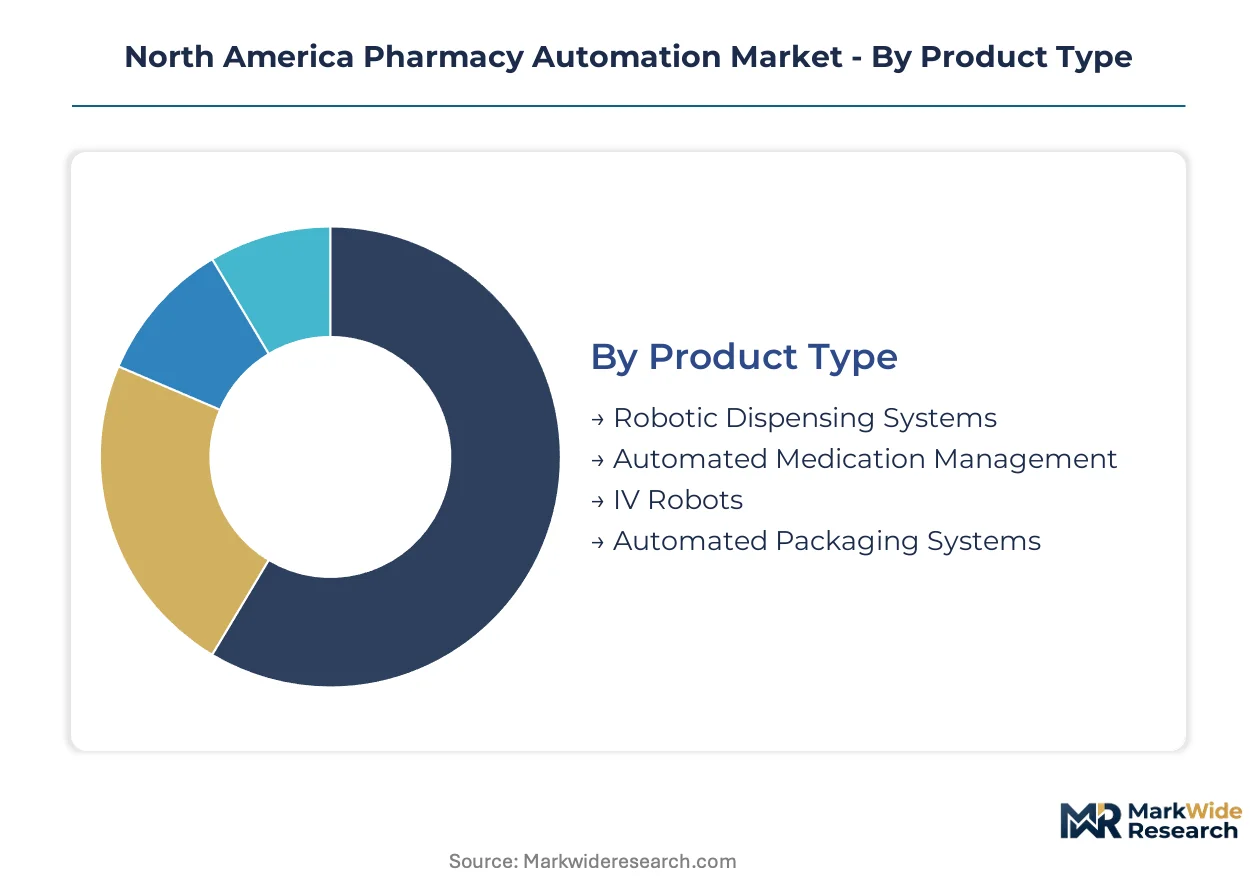
Pharmacy automation purchasing in North America fragments across product architectures, care settings, and deployment models. Each segmentation axis reveals distinct capital allocation patterns shaped by regulatory mandates and reimbursement structures.
Product Type:
Domestic manufacturing concentration varies sharply across product categories, with robotic dispensing systems and IV robots drawing heavily from US-based precision engineering while automated packaging systems rely more on cross-border component flows.
- Robotic Dispensing Systems:Electromechanical platforms with robotic arms, weight verification sensors, and barcode scanners achieve dispensing accuracy exceeding manual processes. Hospital pharmacies in the United States deploy these systems most intensively, driven by FDA Drug Supply Chain Security Act serialization mandates that require interoperable track-and-trace infrastructure.
- IV Robots:Sterile compounding automation with negative-pressure robotics and isolator-based workflows handles hazardous drug preparation. Demand concentrates in Florida and California where state boards of pharmacy impose distinct beyond-use dating and personnel exposure limits that exceed federal minimums.
- Automated Medication Management:Cart-based systems and cabinet automation for medication storage and retrieval.
- Automated Packaging Systems:Unit-dose and multi-dose packaging machinery with integrated verification.
Robotic dispensing systems hold the largest share; momentum sits with IV robots as USP 800 compliance compresses replacement cycles for sterile compounding infrastructure.
End User:
Capital deployment thresholds and procurement authority structures diverge meaningfully across care settings, with hospitals commanding enterprise framework agreements while long-term care facilities navigate fragmented purchasing.
- Hospitals:Acute care facilities with centralized pharmacy operations and enterprise-scale automation budgets. Ontario Health's provincial standardization for automated packaging systems is consolidating vendor qualification pathways and reducing procurement friction across hospital networks in Canada.
- Long-term Care Facilities:Skilled nursing and assisted living operations with decentralized medication administration. Quebec's underpenetrated facilities present expansion opportunity for cart-based systems with French-language software interfaces, though capital constraints limit deployment velocity relative to hospital segments.
- Retail Pharmacies:Community and chain pharmacy operations with high-volume dispensing requirements.
- Clinics:Ambulatory and specialty care sites with limited on-site pharmacy infrastructure.
Hospitals dominate absolute spending; long-term care facilities are climbing the fastest as demographic pressure and staffing shortages force automation adoption.
Technology:
Technology selection tracks directly to regulatory compliance requirements, with barcode verification anchored to FDA mandates and RFID tracking advancing where cold chain integrity demands real-time monitoring.
- Barcode Verification:Optical scanning systems for medication identification and dispensing confirmation. US FDA serialization requirements under the Drug Supply Chain Security Act are accelerating barcode infrastructure investments as the foundational compliance layer across hospital formularies.
- RFID Tracking:Radio-frequency identification for real-time location and temperature monitoring. Oncology and biologics dispensing in high-value therapeutic areas are adopting RFID to reduce diversion risk and support cold chain integrity, displacing legacy barcode verification in these workflows.
- Software Integration:Middleware and API connectivity between automation hardware and hospital information systems.
- Cloud-based Solutions:Hosted inventory management and analytics platforms with subscription revenue models.
Barcode verification maintains the largest installed base; RFID tracking is gaining share fastest as biologics volume expands and diversion enforcement tightens.
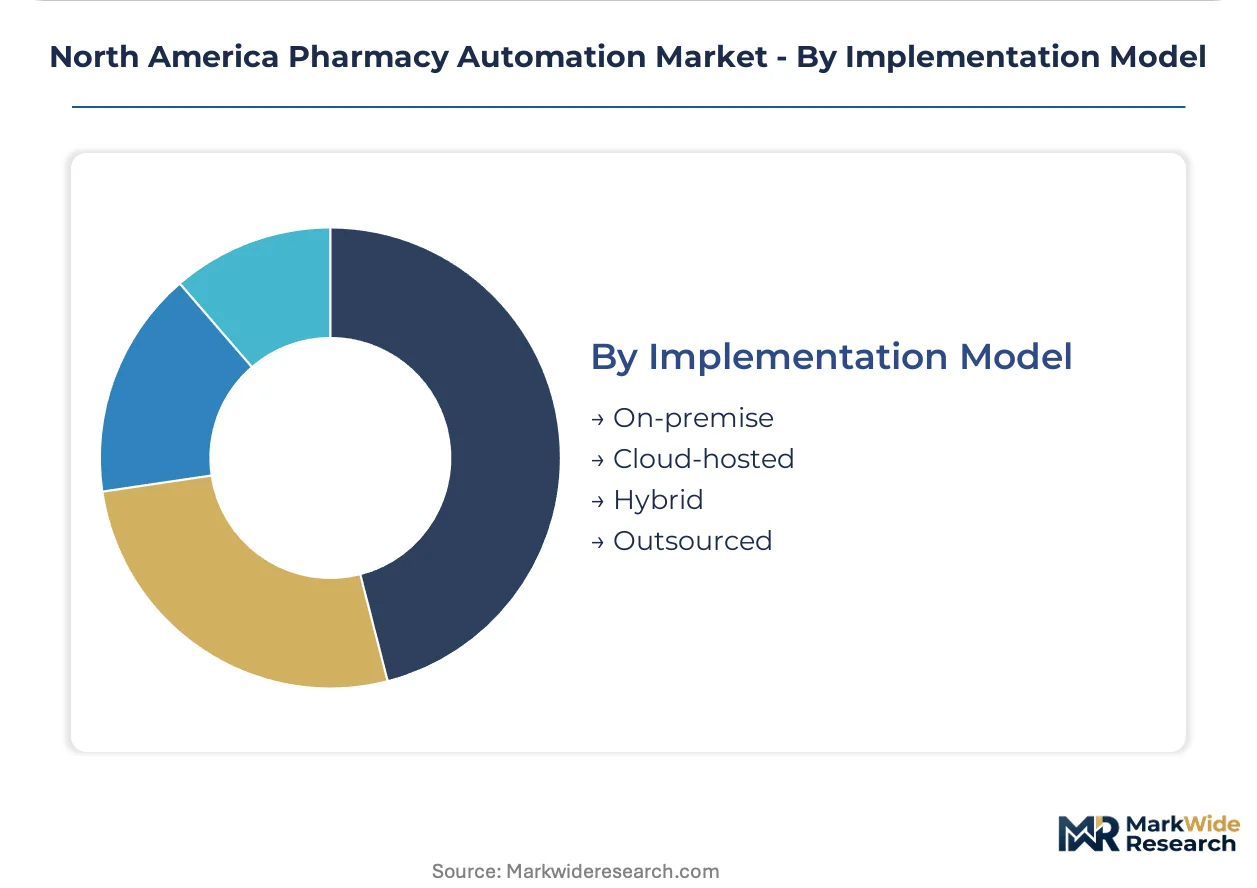
Implementation Model:
Procurement patterns are shifting from perpetual licenses toward recurring revenue structures, with cloud-hosted platforms capturing health system consolidation opportunities and hybrid models addressing legacy infrastructure constraints.
- Cloud-hosted:Subscription-based software platforms with remote inventory management and analytics. Health system consolidation across Catholic networks spanning multiple US states is driving enterprise framework agreements that bundle cloud-hosted solutions across dozens of facilities.
- Hybrid:Mixed deployment combining on-premise hardware with cloud-connected software layers. Rural critical access hospitals in Montana and Idaho are piloting hybrid configurations to extend centralized pharmacy coverage without full capital replacement of legacy systems.
- On-premise:Fully local hardware and software installation with perpetual licensing.
- Outsourced:Third-party operated automation services with performance-based contracting.
On-premise retains the largest share; cloud-hosted solutions are expanding most quickly as procurement committees prioritize operational expenditure over capital deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian automated packaging systems flow southward into United States hospital networks, while Mexican contract manufacturers supply precision mechanical components to US-based robotics integrators. Cross-border regulatory harmonization under USMCA facilitates equipment certification transfers between the three markets.
United States
Hospital pharmacies in California and Florida drive IV robotics procurement as state boards impose distinct sterile compounding requirements exceeding federal minimums. FDA Drug Supply Chain Security Act serialization mandates accelerate barcode verification investments across hospital formularies. Miami-Dade and Tampa oncology centers absorb state-specific compliance costs to maintain hazardous drug compounding licensure.
Canada
Ontario Health coordinates provincial standardization for automated packaging systems, consolidating vendor qualification pathways across hospital networks. Health Canada and provincial authorities in Quebec determine which robotics configurations receive formulary approval. Montreal and Quebec City long-term care facilities present underpenetrated demand for cart-based medication management with French-language software interfaces.
Mexico
Contract manufacturers in Tijuana and Monterrey produce precision pneumatic actuators and machine vision modules for US robotics integrators. The country's national pharmaceutical regulator aligns medical device certification with FDA quality system requirements to maintain USMCA market access. Baja California medical device clusters specialize in subassembly production for sterile compounding isolators.
North America Pharmacy Automation Market Competitive Landscape
Listed leaders compete with private specialists across hardware-software integration depth, with publicly traded entities commanding enterprise framework agreements while private firms anchor niche automation segments. The vendor base organizes around three strategic archetypes: full-stack platform providers spanning hardware and cloud software, specialized robotics fabricators focused on sterile compounding workflows, and cart-based automation specialists serving decentralized care settings. Competitive moves concentrate on backward integration into precision mechanical components and strategic partnerships with health system purchasing cooperatives.
Within the full-stack tier, Omnicell Inc. and Becton Dickinson and Company exemplify platform breadth through combined hardware and subscription software offerings. ARxIUM occupies a position among specialized robotics fabricators, representing deep workflow integration for IV sterile compounding. Capsa Healthcare anchors the cart-based specialist segment, exemplifying decentralized medication management for long-term care deployment.
| Leading Market Players |
|---|
| Omnicell Inc. |
| Capsa Healthcare |
| ARxIUM |
| ScriptPro LLC |
| RxSafe |
| Becton Dickinson and Company |
| Baxter International |
| Parata Systems LLC |
| McKesson |
| Others |
Value Network & Pricing Analysis
Ninety-day lead times for specialty pneumatic actuators concentrate pricing power among Asian component suppliers, while hospital procurement committees exploit cloud-hosted subscription models to shift capital expenditure toward operational budgets. This inventory pressure feeds directly into tiered hardware pricing that separates USP 800-compliant isolator configurations from standard robotic dispensing platforms.
Pricing Analysis
Hospital system buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with USP 800 certification grade and French-language software localization driving differentiation. Cost compression in economy-tier cart-based systems is intensifying because stainless steel and servo motor input volatility squeezes integrator margins. Long-term care facilities in Quebec exhibit the highest price sensitivity due to capital constraints, while enterprise hospital networks in California and Florida absorb premium pricing for state-specific IV robot configurations.
Supply Chain Analysis
Ninety-day lead times for precision components expose concentrated supply dependencies on China, South Korea, and Japan for machine vision modules and specialty pneumatic actuators. Domestic US robotics integrators draw from cross-border component flows while maintaining final assembly in Tijuana and Monterrey clusters. Single-source vulnerability in Asian manufacturing clusters for servo motors creates structural risk, while distribution runs through health system group purchasing organizations and enterprise framework agreements that consolidate vendor relationships across Catholic hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Pharmacy Automation Market represents high-growth disruption as FDA Drug Supply Chain Security Act serialization mandates force wholesale infrastructure replacement across hospital formularies. USP 800 compliance deadlines compress replacement cycles and concentrate purchasing authority among procurement committees with enterprise-scale budgets.
For Market Incumbents: Secure backward integration into precision mechanical components to offset servo motor cost volatility and supply bottlenecks. Deepen cloud-hosted software subscription penetration across health system consolidation waves to lock out emerging competitors. Control channel access through exclusive group purchasing organization partnerships that bundle hardware, software, and maintenance across multi-state Catholic hospital networks.
For New Entrants and Emerging Players: Lead with French-language cart-based automation for Quebec's underpenetrated long-term care facilities, where demographic pressure and staffing shortages force adoption despite capital constraints. Target hybrid deployment models for rural critical access hospitals in Montana and Idaho seeking to extend centralized pharmacy coverage without full infrastructure replacement. Pursue strategic partnerships with provincial health authorities to accelerate vendor qualification pathways.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compounding play because federal serialization mandates and state-level sterile compounding requirements create sustained replacement demand with limited pricing elasticity. Target specialized robotics fabricators with deep IV sterile compounding workflow integration and existing FDA 510(k) clearances. Watch Ontario Health procurement standardization as the signal indicating when enterprise framework agreements will consolidate vendor relationships across Canadian hospital networks.
| Strategic Initiative | Industry Significance |
|---|---|
| USP 800 Compliance Certification | FDA and state board mandates force infrastructure replacement across hazardous drug compounding workflows. |
| Cloud-Hosted Platform Migration | Subscription revenue models capture health system consolidation and displace perpetual license structures. |
| French-Language Software Localization | Quebec procurement standards require localized interfaces for long-term care facility formulary approval. |
| Enterprise Framework Agreements | Group purchasing organizations consolidate vendor relationships across Catholic health system networks. |
| RFID Cold Chain Integration | Oncology and biologics dispensing demands real-time temperature logging to reduce diversion risk. |
Research Methodology
Desk research of FDA 510(k) filings, Health Canada medical device registrations, and hospital procurement databases preceded structured interviews with pharmacy automation executives, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Primary fieldwork with sterile compounding specialists and long-term care facility administrators cross-validated secondary data on replacement cycle timing and capital allocation priorities. Bottom-up installation base modeling and top-down health system expenditure analysis were triangulated against provincial procurement disclosures.
Variance decomposition across product type, end user setting, technology tier, and implementation model shaped the analytical framework over the projection horizon. CAGRs were derived from segmented demand modeling that weighted USP 800 compliance deadlines, FDA serialization phase-in requirements, and Ontario Health standardization timelines. Forecast inputs incorporated health system consolidation velocity, cloud subscription adoption curves, and RFID displacement rates in high-value therapeutic areas.
Forecasts assume regulatory continuity in FDA Drug Supply Chain Security Act enforcement and state board of pharmacy sterile compounding regimes; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Vials and Ampoules Market
Pharmaceutical Equipment
Global Depyrogenated Sterile Empty Vials Market
Pharmaceutical Equipment
Depyrogenation Oven Market
Pharmaceutical Equipment
Global Pharmaceutical Contract Manufacturing and Contract Research Market
Pharmaceutical Equipment
Sterile Injectable Contract Manufacturing Market
Pharmaceutical Equipment
Pharmaceutical Stability and Storage Services Market
Pharmaceutical Equipment
Investigational New Drug CDMO Market
Pharmaceutical Equipment
Lyophilization Equipment and Services Market
Pharmaceutical Equipment
Fill-Finish Pharmaceutical Contract Manufacturing Market
Pharmaceutical Equipment
Global Pharmacy Automation Systems Market
Pharmaceutical Equipment
Interlock Vials Market
Pharmaceutical Equipment
Pharmerging Contract Manufacturing Market
Pharmaceutical Equipment
Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
CMO/CDMO Market
Pharmaceutical Equipment
Malaysia Pharmacy Automation Market
Pharmaceutical Equipment
Shell Vials Market