
 Global Pneumatic Tourniquets Market | 2026-2036
Global Pneumatic Tourniquets Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pneumatic Tourniquets Market Foresight
Chinese medical device manufacturers is recalibrating their export strategies toward higher-margin pneumatic tourniquet systems. Stryker leverages its integrated surgical technologies portfolio to dominate North American hospital purchasing. Zimmer Biomet anchors its position through deep orthopedic channel relationships and specialized cuff configurations. Ulrich medical differentiates via precision German engineering in electronically controlled pressure regulation systems.
Pneumatic tourniquets are inflatable pressure devices applied to limbs during surgery to create a bloodless operative field, typically utilizing silicone or thermoplastic elastomer cuffs with microprocessor-controlled inflation systems maintaining pressures between 50-350 mmHg. Their primary commercial purpose centers on reducing intraoperative blood loss and improving visualization during extremity procedures. Single cuff systems still occupy the largest installed base, though electronically controlled automatic units are capturing the fastest growth trajectory as hospitals prioritize pressure accuracy and nerve injury prevention. Orthopedic surgery generates the deepest margin pools among applications, while ambulatory surgery centers represent the most rapidly expanding end-user channel.
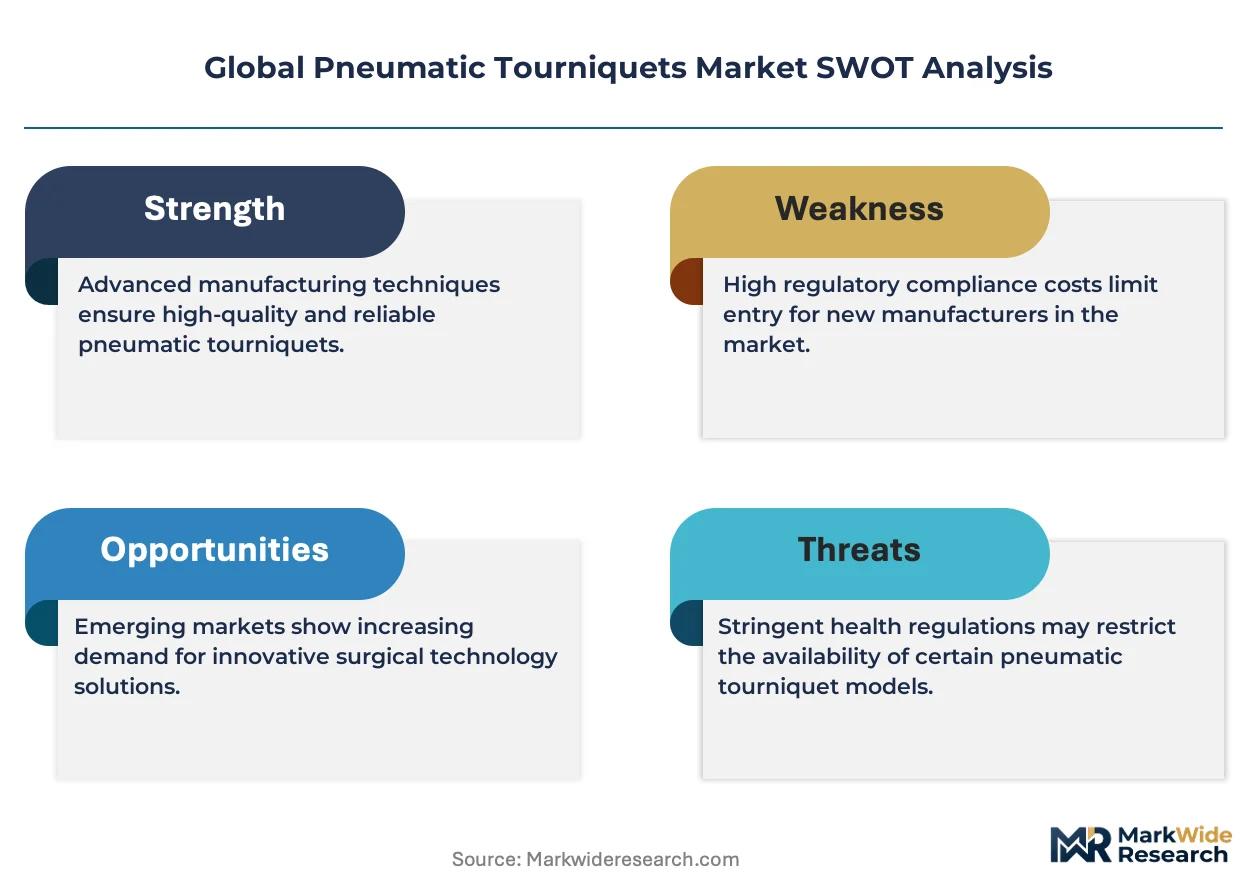
FDA 510(k) clearance pathways and EU MDR conformity assessments shape product development timelines and market access costs for pneumatic tourniquet manufacturers. ISO 13485 quality management certification and IEC 60601 electrical safety standards further constrain supplier participation in regulated markets. Stakeholders must monitor evolving limb perfusion monitoring guidelines from surgical societies and pressure-sensitive reimbursement policies in Germany and Japan.
Market Dynamics
Electronically controlled limb occlusion systems are compressing the installed base of mechanical pneumatic tourniquets across surgical suites, forcing manufacturers to reconfigure R&D priorities around pressure-sensing accuracy and nerve protection protocols.
Growth Catalysts
- Ambulatory Surgery Center Expansion:Freestanding orthopedic facilities in the United States and Germany are outfitting procedure rooms with dual-port automatic tourniquet systems to support same-day discharge protocols.
- EU MDR Compliance Deadlines:The European Union Medical Device Regulation's stricter clinical evidence requirements are filtering out low-accuracy legacy devices, elevating demand for validated pressure-monitoring platforms.
- Silicone Cuff Material Advances:Thermoplastic elastomer blends with embedded pressure sensors are extending cuff lifecycle durability while reducing per-procedure consumable costs.
Market Restraints
- Specialized Polymer Supply Concentration:Medical-grade silicone sheeting production concentrates among three German and Japanese chemical suppliers, creating input cost volatility during semiconductor-driven demand surges.
- ISO 13485 Certification Timelines:Quality management system audits for new market entrants routinely extend eighteen to twenty-four months, compressing capital recovery windows for automated system launches.
- Manual Tourniquet Substitution:Low-acuity emergency departments in price-sensitive health systems continue defaulting to mechanical sphygmomanometer-style devices for trauma stabilization.
Strategic Opportunities
- Pediatric Surgical Protocols:Underserved neonatal and pediatric orthopedic centers in India and Brazil lack appropriately sized low-pressure cuff systems, creating white space for specialized configurations.
- Japan's Reimbursement Modernization:METI's pressure-sensitive procedure coding reforms are incentivizing hospitals to upgrade from mechanical to electronic limb occlusion systems.
- Wearable Perfusion Monitoring Convergence:Integration of pulse oximetry sensors with tourniquet cuffs is enabling real-time tissue oxygenation feedback during prolonged procedures.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Cross-functional expertise combining pneumatic system design with embedded software development remains concentrated among legacy surgical device manufacturers.
- Legacy EMR Integration Complexity:Automated tourniquet data streams require HL7 FHIR-compliant middleware that many hospital IT departments lack bandwidth to deploy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pneumatic Tourniquets Market |
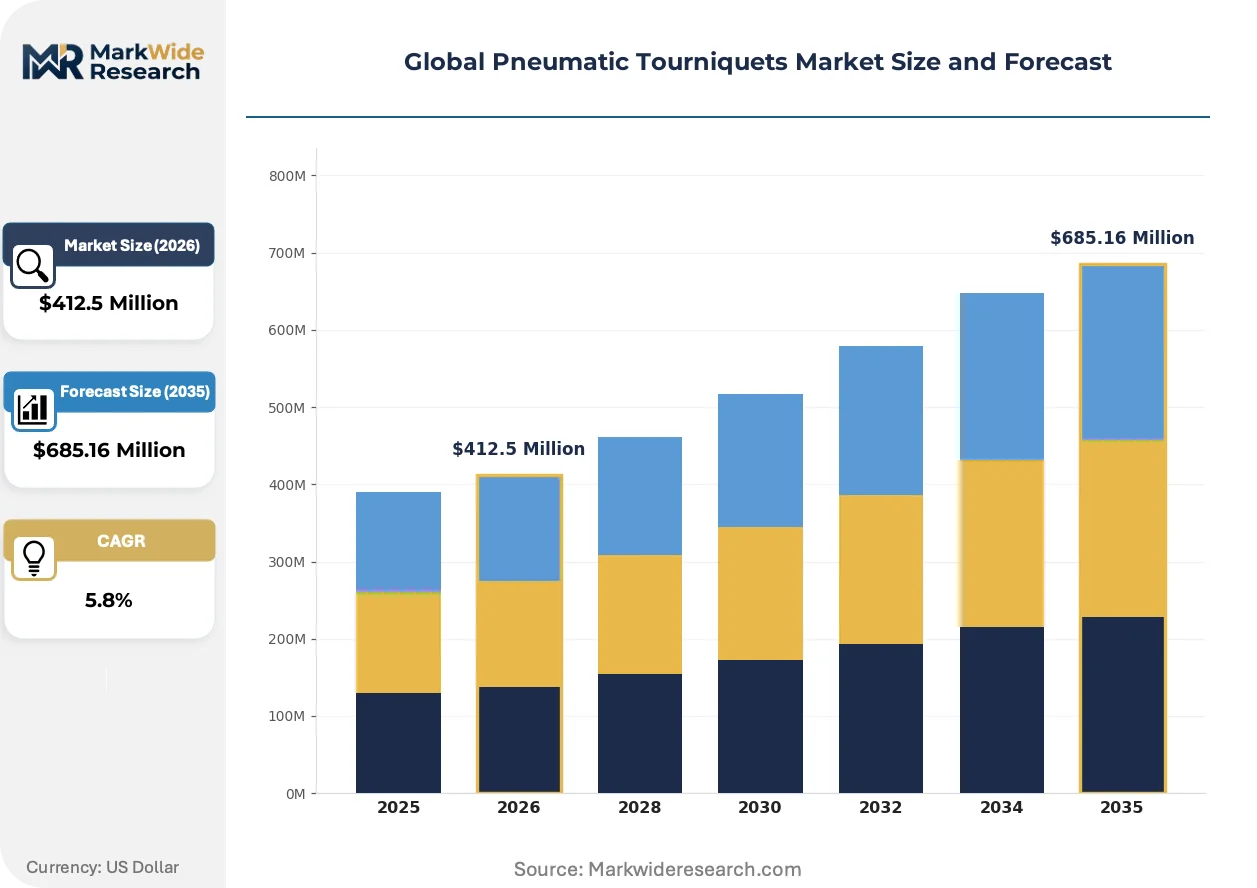
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $685.16 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Cuff, Double Cuff, Multi-Cuff, Combination Cuff Application: Orthopedic Surgery, Vascular Surgery, Plastic Surgery, Emergency Care End User: Ambulatory Surgery Centers, Specialty Clinics, Home Care, Physiotherapy Centers Operation Mode: Manual, Semi-Automatic, Automatic, Electronically Controlled |
| Companies Covered | Stryker, Zimmer Biomet, AneticAid, Ulrich medical, VBM Medizintechnik GmbH, Dessillions & Dutrillaux, DSMAREF Co. Ltd., Shanghai Huifeng Medical Instrument, Hangzhou Kimislab Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pneumatic Tourniquets Market Shifts & Advancements
Pressure-sensing microprocessors and wireless connectivity modules are redrawing competitive boundaries between standalone tourniquet manufacturers and integrated surgical platform vendors.
Bluetooth-enabled cuff pressure monitoring is decentralizing intraoperative data capture from centralized anesthesia workstations to individual surgical team members. Orthopedic surgeons in high-volume United States hospital networks are piloting tablet-based pressure alerts during arthroscopic procedures. This distributed monitoring architecture is compressing response times to occlusion pressure drift while reducing anesthesia staff cognitive load.
EU MDR's post-market surveillance requirements are forcing manufacturers to maintain active implantable device-style vigilance systems for Class IIa pneumatic tourniquets. German notified bodies are demanding real-world pressure accuracy data from clinical registries as a condition of certificate renewal. Mid-tier suppliers without dedicated clinical affairs functions are exiting the European market rather than absorbing compliance infrastructure costs.
Hospital procurement committees are consolidating vendor relationships around single-source surgical technology platforms that bundle tourniquet systems with power tools and irrigation pumps. Integrated purchasing agreements in United States health systems are displacing standalone tourniquet specialists from approved vendor lists. This concentration dynamic is most visible in the southeastern United States, where regional hospital networks have standardized around unified capital equipment contracts.
Global Pneumatic Tourniquets Market Segmentation
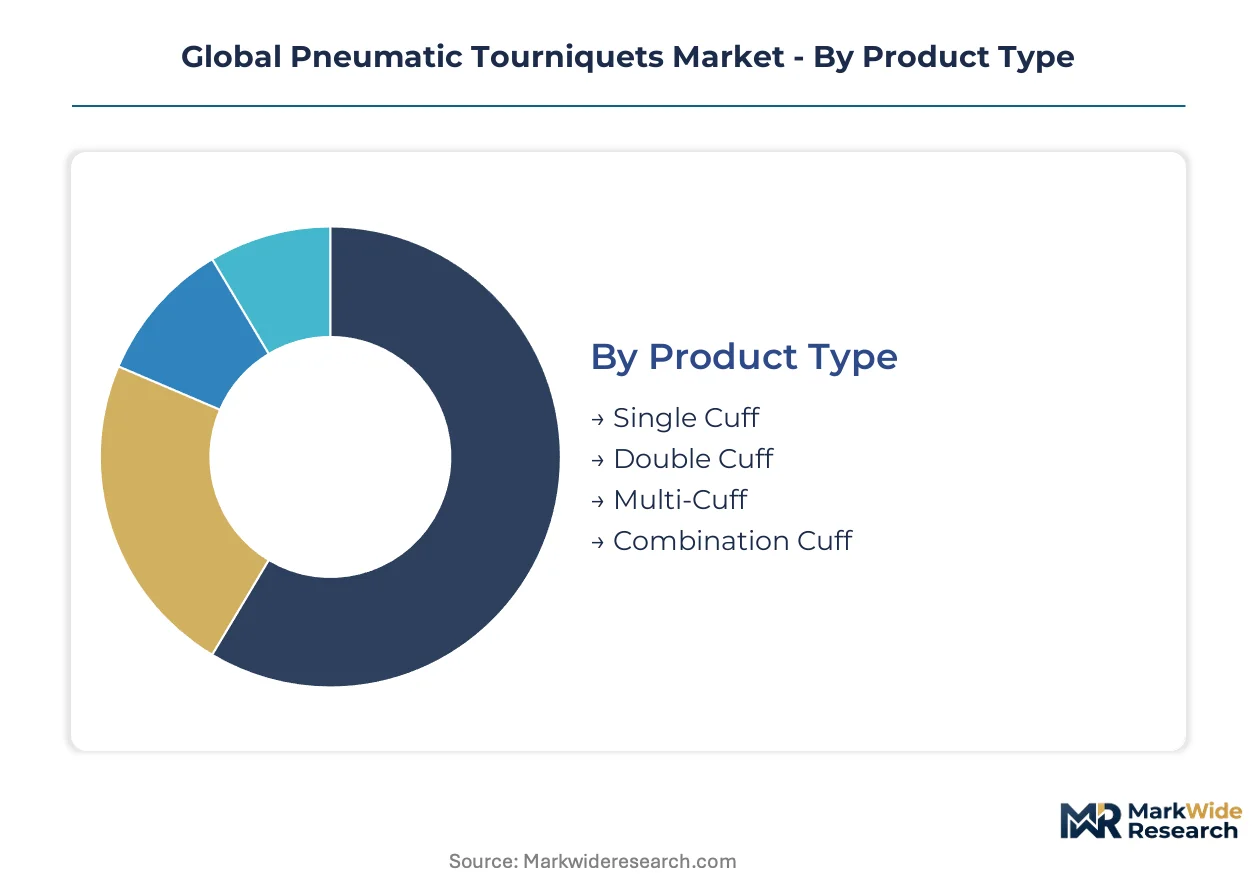
Pneumatic tourniquet manufacturers configure product portfolios around surgical workflow intensity and pressure precision requirements. Segmentation choices directly determine pricing architecture, regulatory pathway complexity, and channel access strategies across hospital procurement systems.
Product Type:
Standardization dominates high-volume disposable segments while customization concentrates in reusable surgical platforms requiring precise limb geometry matching.
- Single Cuff:Silicone or thermoplastic elastomer construction in fixed circumference dimensions serves routine extremity procedures. Demand concentrates in United States ambulatory surgery centers where same-day discharge protocols prioritize setup speed over configurability. Cost-per-procedure advantages sustain this segment's installed base dominance despite pressure accuracy limitations.
- Double Cuff:Dual-bladder designs enable sequential inflation protocols for prolonged procedures requiring intermittent perfusion. German orthopedic departments in university hospitals drive specification requirements for nerve protection during complex arthroplasties. Bovie Medical and Zimmer Biomet anchor their European positions through proprietary double-cuff configurations.
- Multi-Cuff:Modular circumference systems address pediatric through bariatric patient populations with interchangeable bladder assemblies.
- Combination Cuff:Hybrid disposable-reusable platforms integrate single-use patient contact surfaces with sterilizable pressure delivery hardware.
Most installed capacity flows through Single Cuff systems. Expansion is steepest in Double Cuff configurations.
Application:
Procedure reimbursement intensity and blood loss risk profiles shape demand concentration across surgical specialties.
- Orthopedic Surgery:Total joint arthroplasties and arthroscopic procedures generate the deepest margin pools through high procedure volumes and pressure precision requirements. United States hospital networks in Texas and Florida prioritize electronic limb occlusion systems for knee and shoulder reconstruction workflows. FDA 510(k) clearance pathways for orthopedic-specific configurations impose steeper clinical evidence burdens than general surgery platforms.
- Vascular Surgery:Aneurysm repairs and bypass grafting demand ultra-low pressure maintenance to preserve fragile vessel walls during clamping sequences. Japanese academic medical centers in Osaka and Tokyo specify vascular-specific pressure algorithms with sub-5 mmHg accuracy tolerances.
- Plastic Surgery:Hand and microvascular reconstruction requires pediatric-scale cuff dimensions with graduated pressure staging.
- Emergency Care:Trauma stabilization defaults to mechanical sphygmomanometer-style devices in price-sensitive health systems.
Orthopedic Surgery captures the majority of revenue flow. Plastic Surgery applications are climbing the fastest.
End User:
Capital equipment budgets and procedure throughput determine purchasing authority concentration across care delivery settings.
- Ambulatory Surgery Centers:Freestanding orthopedic facilities in the United States and Germany outfit procedure rooms with dual-port automatic systems. METI reimbursement modernization in Japan is accelerating electronic system deployment in independent surgical facilities.
- Specialty Clinics:Hand surgery and sports medicine practices in São Paulo and Mumbai concentrate demand for portable battery-powered units.
- Home Care:Post-operative lymphedema management drives demand for consumer-grade pressure garments with simplified inflation mechanics.
- Physiotherapy Centers:Rehabilitation protocols in Australian and Canadian outpatient networks utilize graduated compression systems for edema reduction.
Specialty Clinics hold the largest installed base. Ambulatory Surgery Centers are gaining share fastest.
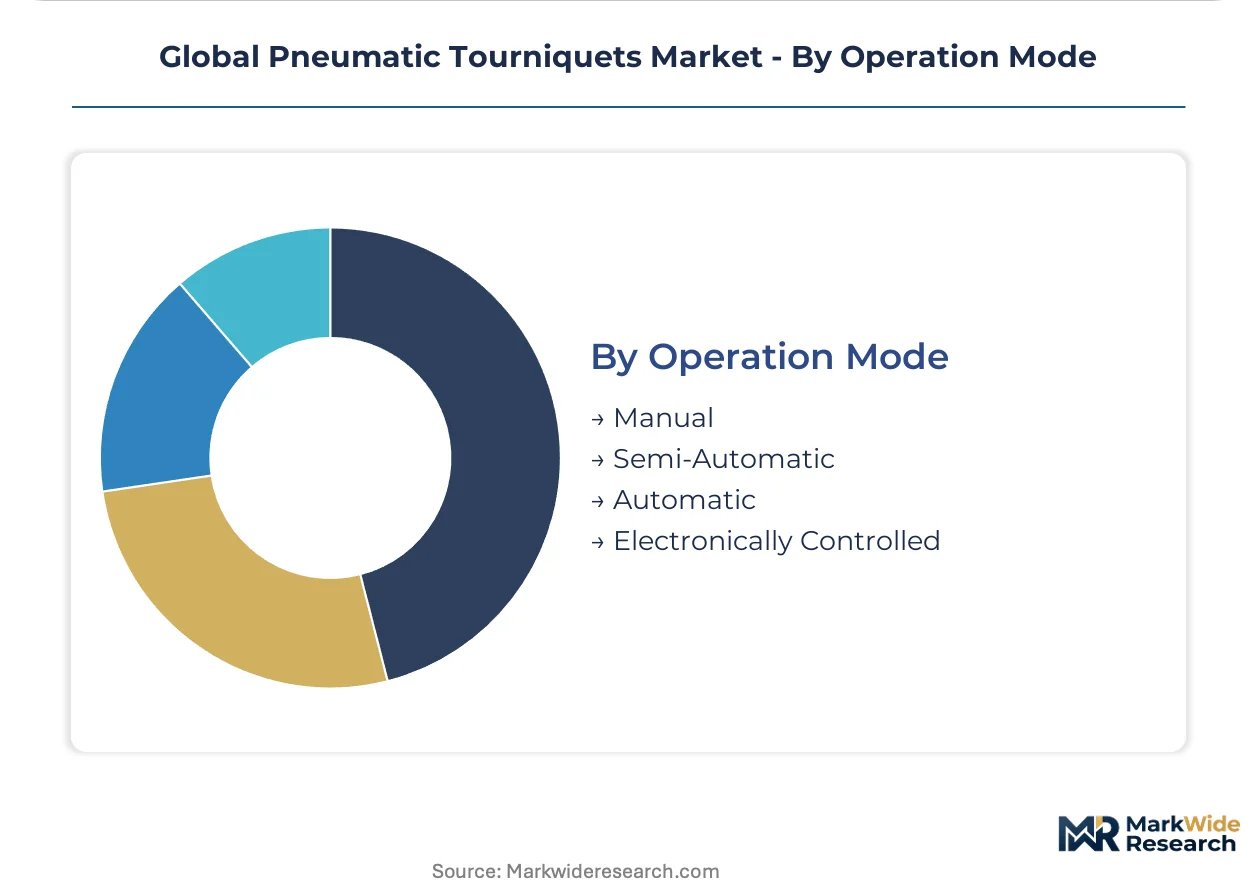
Operation Mode:
Automation depth separates legacy mechanical platforms from next-generation pressure-sensing systems commanding procurement committee attention.
- Manual:Spring-loaded mechanical gauges and bulb inflation assemblies persist in emergency departments and resource-constrained settings. Indian district hospitals and Brazilian public trauma centers default to these devices for cost containment.
- Semi-Automatic:Pre-set pressure targets with manual initiation bridge workflow efficiency and capital budget constraints. Chinese tier-2 city hospitals prioritize these units during surgical suite modernization programs.
- Automatic:Microprocessor-controlled inflation with timed deflation alarms addresses anesthesia staff workload reduction priorities. German notified bodies under EU MDR are elevating validation requirements for automatic pressure accuracy claims.
- Electronically Controlled:Real-time limb occlusion pressure monitoring with Bluetooth data streaming enables integration with anesthesia information management systems. United States health systems in the Southeast are standardizing around these platforms through unified capital equipment contracts.
Manual systems retain the broadest geographic footprint. Electronically Controlled platforms are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping manufacturing footprints as EU MDR compliance costs drive some assembly operations toward lower-cost jurisdictions while premium engineering remains anchored in Germany. Production migration patterns reflect divergent cost-of-compliance calculations across major surgical device markets.
United States
Ambulatory surgery centers in Texas and Florida are driving dual-port automatic system procurement for same-day discharge protocols. FDA 510(k) clearance pathways impose steep clinical evidence burdens for orthopedic-specific configurations. Hospital procurement committees in the Southeast are consolidating vendor relationships around unified capital equipment contracts.
Germany
University hospitals in Munich and Berlin specify double-cuff designs with sequential inflation protocols for complex arthroplasties. EU MDR notified bodies demand real-world pressure accuracy data from clinical registries as a condition of certificate renewal. Precision engineering clusters in Baden-Württemberg concentrate electronically controlled pressure regulation system production.
China
Tier-2 city hospitals prioritize semi-automatic units during surgical suite modernization programs. NMPA registration requirements are elevating quality management system standards for domestic manufacturers. Zhengzhou and Shanghai medical device zones are recalibrating export strategies toward higher-margin pneumatic tourniquet systems.
Japan
Academic medical centers in Osaka and Tokyo specify vascular-specific pressure algorithms with sub-5 mmHg accuracy tolerances. METI reimbursement modernization is incentivizing hospitals to upgrade from mechanical to electronic limb occlusion systems. Independent surgical facilities in Kansai are accelerating electronic system deployment.
India
District hospitals default to mechanical devices for cost containment while metropolitan orthopedic centers pilot automatic platforms. CDSCO medical device rules are tightening quality certification requirements for imported systems. Mumbai and Delhi-NCR specialty clinics concentrate demand for portable battery-powered units.
Global Pneumatic Tourniquets Market Competitive Landscape
German producers anchor the premium engineering tier; Chinese fabricators hold volume manufacturing positions. The vendor base separates into three functional layers: integrated surgical platform vendors with unified capital equipment contracts, specialized pneumatic system manufacturers with deep orthopedic channel relationships, and regional fabricators serving price-sensitive health systems. Consolidation pressure is intensifying as hospital procurement committees narrow approved vendor lists. Strategic moves center on portfolio bundling with power tools and irrigation pumps, plus backward integration into medical-grade silicone supply.
Within the integrated platform tier, Stryker and Zimmer Biomet exemplify archetypes that leverage broad surgical technology portfolios to dominate North American hospital purchasing. Among precision engineering specialists, Ulrich medical occupies a position representing German electronically controlled pressure regulation expertise. Shanghai Huifeng Medical Instrument and Hangzhou Kimislab Co. Ltd. sit within the regional manufacturing tier, reflecting Chinese production capacity recalibration toward export-oriented higher-margin systems.
| Leading Market Players |
|---|
| Stryker |
| Zimmer Biomet |
| AneticAid |
| Ulrich medical |
| VBM Medizintechnik GmbH |
| Dessillions & Dutrillaux |
| DSMAREF Co. Ltd. |
| Shanghai Huifeng Medical Instrument |
| Hangzhou Kimislab Co. Ltd. |
| Others |
Supply & Pricing Matrix
Family-owned German mid-caps with multi-generational engineering heritage anchor premium-tier pricing discipline through captive silicone processing capabilities, while private-equity-rolled surgical device specialists compress channel margins to defend market share against integrated platform vendors.
Pricing Analysis
Distributor markups spanning 35-50 percent separate factory pricing from hospital procurement committees in United States health systems. Three-tier pricing structure across premium, standard, and economy levels stratifies by pressure-sensing accuracy and EU MDR certification tier, with electronically controlled systems commanding brand premiums over semi-automatic alternatives. Cost compression in economy mechanical tourniquets is intensifying because Indian district hospitals and Brazilian public trauma centers prioritize capital budget containment over precision specifications. Ambulatory surgery centers in Texas and Florida exhibit lowest price sensitivity due to bundled capital equipment contracts, while emergency departments in resource-constrained settings drive hard per-unit negotiations.
Supply Chain Analysis
ISO 13485 and IEC 60601 certification gating restricts component sourcing to qualified medical-grade suppliers in Germany, Japan, and the United States. Medical-grade silicone sheeting and thermoplastic elastomer blends draw from concentrated chemical production clusters in Baden-Württemberg and Osaka prefecture, with embedded pressure sensor modules resting on semiconductor fabrication capacity in Taiwan and South Korea. Single-source vulnerability in specialized polymer sheeting creates input cost volatility during electronics demand surges. Distribution runs through orthopedic-focused surgical device distributors with GPO contract access, supplemented by direct hospital contracting for integrated platform bundles in southeastern United States networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in pneumatic tourniquets hinges on silicone cuff lifecycle extension reducing per-procedure consumable costs, while premium-tier shift toward electronically controlled systems with Bluetooth data streaming captures pricing power from anesthesia information management integration.
For Market Incumbents: Extend pressure-sensing accuracy validation investments to satisfy EU MDR post-market surveillance demands from German notified bodies, while deepening backward integration into medical-grade silicone supply to offset raw material volatility from Japanese chemical suppliers. Channel control through unified capital equipment contracts with power tool and irrigation pump bundling defends against displacement by standalone tourniquet specialists. For New Entrants and Emerging Players: Bluetooth-enabled cuff pressure monitoring with tablet-based alert systems offers a technology-first wedge into United States ambulatory surgery centers piloting distributed monitoring architectures. Pediatric and neonatal low-pressure cuff configurations for underserved orthopedic centers in India and Brazil represent the most penetrable white space, with portable battery-powered unit development targeting São Paulo and Mumbai specialty clinics as the optimal go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier pneumatic system manufacturers lacking dedicated clinical affairs functions for EU MDR compliance, creating acquisition opportunities before European market exit accelerates. Long-term viability over the coming decade favors precision engineering specialists with embedded software development capabilities and existing FDA 510(k) clearance portfolios. The signal to watch is METI reimbursement modernization progress in Japan, which would accelerate electronic system upgrade cycles and validate pressure-sensitive procedure coding models.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Pathway | Real-world pressure accuracy data from clinical registries satisfies German notified body renewal conditions. |
| Hospital System Partnership | Unified capital equipment contracts in southeastern United States displace standalone tourniquet vendors. |
| Software Companion Development | HL7 FHIR-compliant middleware enables anesthesia information management system integration. |
| Backward Integration | Captive medical-grade silicone processing insulates against German and Japanese supplier concentration. |
| Reimbursement Strategy | Pressure-sensitive procedure coding alignment with METI reforms accelerates Japanese hospital upgrades. |
Research Methodology
Direct dialogue with orthopedic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers grounded qualitative insights, validated against FDA 510(k) filings, EU MDR notified body databases, hospital procurement records, and CMS Medicare reimbursement data. Bottom-up unit demand modeling across cuff type, operation mode, and end-user channel triangulated with top-down market sizing from manufacturer revenue disclosures.
Segment-level value outputs across the projection horizon reflect installed base replacement cycles, ambulatory surgery center expansion trajectories, and regulatory compliance cost absorption patterns. Modeled dimensions span product configuration, application specialty, end-user setting, and automation depth, with CAGRs derived from procedure volume growth elasticities and equipment upgrade intensity by geography.
The model holds under stable regulatory enforcement timelines and silicone supply continuity; deviation in EU MDR audit backlogs or semiconductor-driven polymer allocation disruptions would shift equipment procurement schedules. A model refresh is warranted upon material change in Japanese reimbursement coding implementation or FDA guidance on limb occlusion pressure monitoring accuracy standards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Wireless ECG Devices Market
Medical Devices
Global Gamma Probe Device Market
Medical Devices
Osteosynthesis Devices Market
Medical Devices
India Minimally Invasive Surgery Devices Market
Medical Devices
Cast Removal Devices Market
Medical Devices
Global Motion Preservation Devices Market
Medical Devices
Intravascular Warming Systems Market
Medical Devices
Laryngoscopes Market
Medical Devices
Nanomedical Devices Market
Medical Devices
Pen Needles Market
Medical Devices
Patient Warming Devices Market
Medical Devices
Asia Pacific Reprocessed Medical Devices Market
Medical Devices
Acellular Dermal Matrix Market
Medical Devices
Gutta Percha Obturator Market
Medical Devices
Magnetic Ablation Catheter Market
Medical Devices
Global Tumor Tracking Systems Market