
 North America Unit Dose Manufacturing Market | 2026-2036
North America Unit Dose Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
North America Unit Dose Manufacturing Market Intelligence
The North America unit dose manufacturing landscape is pivoting on a widening gap between high-complexity sterile injectables and standard oral solid formats. Catalent Inc. leverages its integrated biologics network to dominate sterile fill-finish capacity for specialty therapies. Thermo Fisher Scientific anchors its position through end-to-end clinical-to-commercial services spanning multiple dosage forms. PCI Pharma Services differentiates via dedicated high-potency handling capabilities that command premium pricing.
Unit dose manufacturing produces individually packaged medications containing a single administration of a drug product, typically sealed in blister packs or vials with barcoded identification for bedside verification. The process employs form-fill-seal automation, blow-fill-seal technology for liquids, and cold-form aluminum laminates for moisture-sensitive compounds to ensure dose accuracy and patient safety. Injectable delivery modes lead value contribution due to sterility requirements and cold-chain handling, while blister pack packaging types capture the highest volume share across oral solid portfolios. Long-term care end users represent the fastest-growing demand channel as aging demographics expand medication management needs outside acute settings.
FDA Current Good Manufacturing Practice regulations and USP <797> sterile compounding standards shape facility investments, forcing upgrades to isolator-based filling lines and continuous monitoring systems. Health Canada's ICH Q10 pharmaceutical quality system guidelines align cross-border compliance burdens for multi-site operators. NHTSA and DOT hazardous materials rules further constrain transport packaging for cytotoxic unit dose products. Stakeholders must weigh capital allocation between capacity expansion for biologic-compatible formats and automation retrofitting for existing oral solid infrastructure.
Market Dynamics
Serialization mandates from the US FDA and Health Canada are forcing contract manufacturers to consolidate packaging lines into integrated track-and-trace systems, compressing margins for mid-scale operators while advantaging facilities with capital reserves for isolator-based upgrades.
Growth Catalysts
- USP <797> sterile compounding standards:Hospital pharmacies across the United States are outsourcing high-risk compounding to specialized unit dose facilities, expanding addressable demand for outsourced sterile manufacturing services.
- Long-term care medication management:Aging demographics in Florida and Arizona are driving demand for blister-packed oral solids with barcode verification for nursing home administration.
- Blow-fill-seal automation:Liquid unit dose formats for ophthalmic and respiratory therapies are capturing share from traditional vial filling through reduced contamination risk and extended shelf stability.
Market Restraints
- Aluminum laminate supply concentration:Cold-form blister materials depend on a limited supplier base in the southeastern United States, exposing manufacturers to input cost volatility and allocation constraints during demand spikes.
- FDA validation timelines:New isolator-based filling lines require 18-24 month qualification periods, delaying revenue recognition and freezing capital in non-productive assets.
- Prefilled syringe substitution:Biologic therapies increasingly bypass unit dose vials in favor of ready-to-inject formats, constraining growth in traditional sterile fill-finish segments.
Strategic Opportunities
- Canadian biologics corridor:Montreal and Toronto clusters lack dedicated high-potency unit dose capacity, creating white space for US-based contract manufacturers with Health Canada establishment licenses.
- Radio-frequency identification convergence:Integration of RFID-enabled blister packs with electronic medication administration records opens new pricing tiers for hospital pharmacy customers.
- IRA domestic manufacturing incentives:US-based production of unit dose oncology products qualifies for tax credits under clean energy and reshoring provisions, improving project returns.
Industry Challenges
- Isolator technician scarcity:Qualified operators for restricted access barrier systems command 40% wage premiums over conventional cleanroom staff, inflating labor costs in high-complexity segments.
- Legacy line integration:Retrofitting existing oral solid packaging equipment with serialization modules requires custom engineering, extending downtime and disrupting production schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Unit Dose Manufacturing Market |
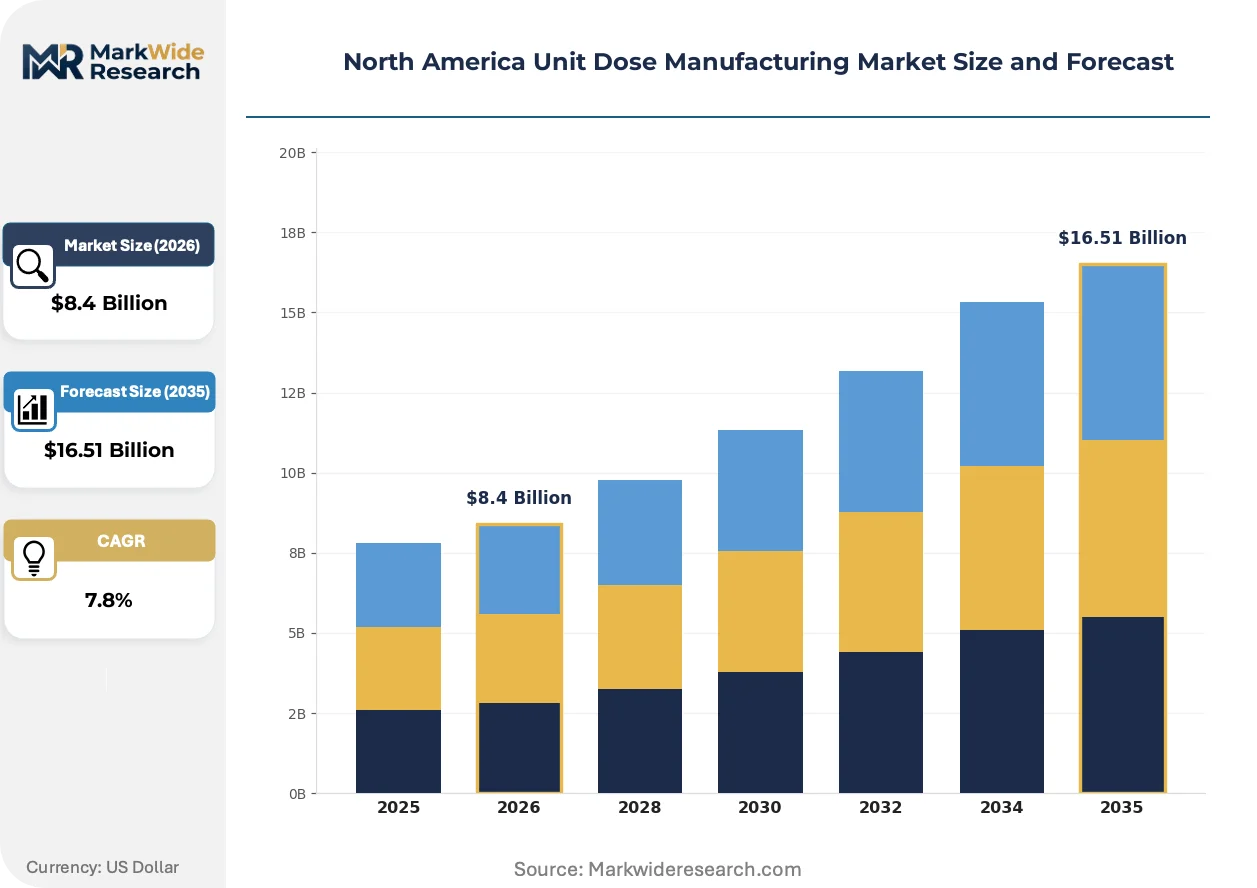
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $16.51 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Tablets, Injections, Powders Delivery Mode: Oral, Injectable, Intravenous, Topical End User: Pharmacies, Hospitals, Clinics, Long-term Care Packaging Type: Blister Packs, Vials, Sachets, Bottles |
| Companies Covered | Catalent Inc., Thermo Fisher Scientific, Unither Pharmaceuticals, PCI Pharma Services, Corden Pharma, Mikart LLC, LTS LOHMANN Therapie-Systeme AG, Renaissance Lakewood LLC, Medical Packaging Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Unit Dose Manufacturing Market Strategic Shifts & Innovations
Automation architectures are converging with cold-chain infrastructure, reshaping how unit dose facilities balance speed, compliance, and temperature integrity across oral and injectable formats.
Robotic deblistering and reconstitution systems are integrating into hospital pharmacy central fill operations, enabling remote verification of high-risk sterile preparations. Health systems in Texas and California are deploying these platforms to extend pharmacist oversight without proportional headcount expansion. The technology is integrating previously separate packaging and clinical review workflows, compressing turnaround times for patient-specific unit doses.
Health Canada's ICH Q10 pharmaceutical quality system guidelines are tightening documentation requirements for multi-site operators running parallel US-Canada production. Cross-border facilities must maintain harmonized deviation investigations and change control protocols, increasing quality assurance overhead. Sterile injectable manufacturers with integrated US-Canada networks are responding by centralizing batch record review functions in Toronto-area hubs.
Consolidated service agreements are displacing transactional outsourcing relationships as pharmacy benefit managers and specialty distributors seek single-source accountability for unit dose supply. Three-year committed capacity contracts with penalty clauses for non-performance are replacing spot purchasing for oncology and immunology portfolios. This shift is most visible in the southeastern United States, where contract manufacturers with integrated packaging and logistics capabilities are capturing multi-product mandates from regional health systems.
North America Unit Dose Manufacturing Market Segmentation
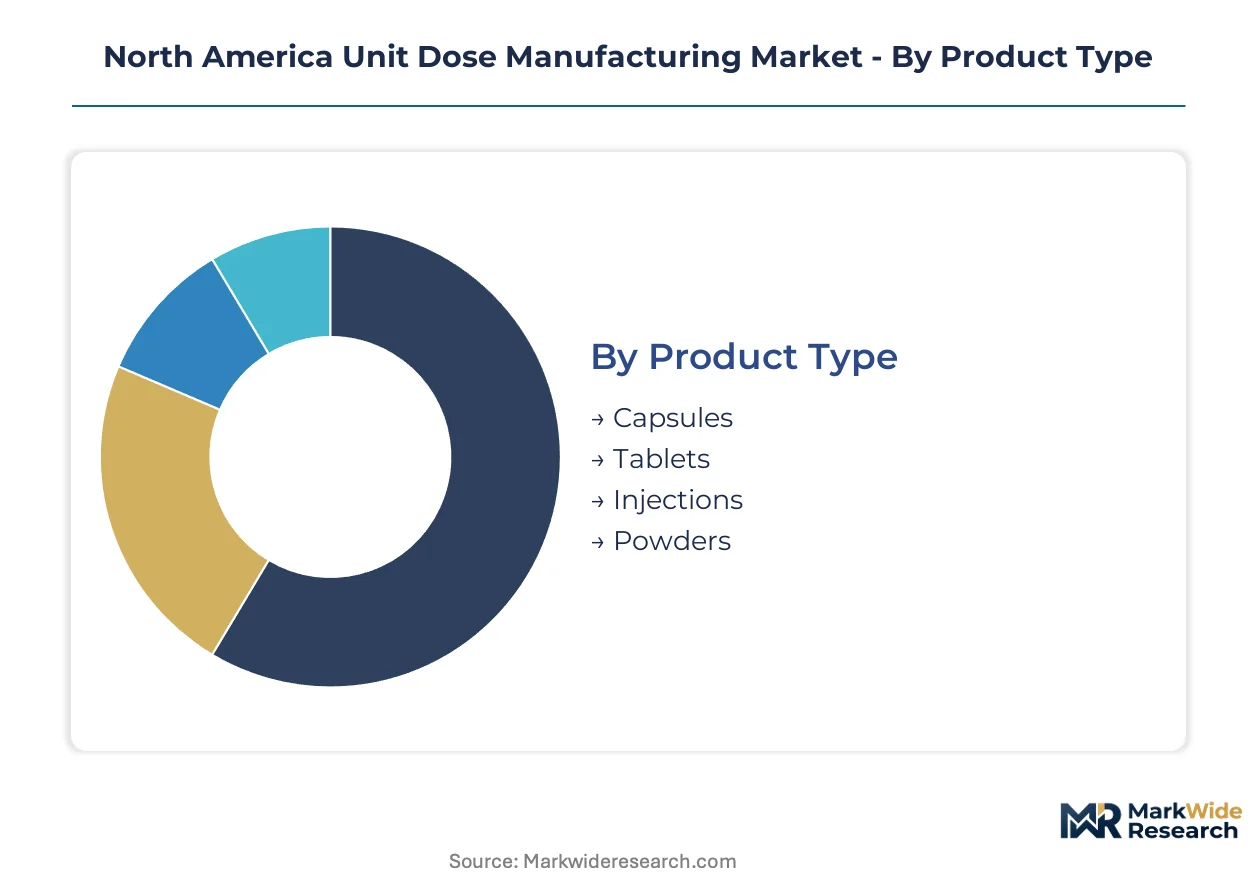
Unit dose manufacturing segments fragment across dosage complexity and sterility requirements. Each dimension carries distinct capital intensity and regulatory burden, shaping facility specialization and customer targeting strategies.
Product Type:
Supply concentration tilts toward sterile formats where isolator infrastructure creates natural barriers to entry.
- Injections:Sterile fill-finish operations demand restricted access barrier systems and continuous environmental monitoring. Demand clusters in the southeastern United States where contract manufacturers serve oncology and immunology portfolios under FDA Current Good Manufacturing Practice oversight.
- Tablets:Compression and coating processes feed high-volume oral solid production with lower capital thresholds. Hospital pharmacies in Florida and Arizona drive blister-pack demand for long-term care medication management programs.
- Capsules:Gelatin and HPMC shells accommodate moisture-sensitive APIs through specialized banding and sealing equipment.
- Powders:Unit dose sachets and stick packs serve pediatric and geriatric populations requiring flexible dosing adjustments.
Injections absorb the bulk of installed capacity; tablets are expanding most quickly.
Delivery Mode:
Cost tier separation emerges between hospital-administered formats and patient-directed applications.
- Injectable:Intramuscular and subcutaneous delivery requires aseptic processing with terminal sterilization or filtration. Prefilled syringe substitution pressures traditional vial formats in biologic therapy segments.
- Intravenous:Large-volume parenterals and piggyback bags demand compounding pharmacy integration with automated verification systems.
- Oral:Swallowable and orodispersible formats dominate outpatient prescribing through pharmacy benefit manager formularies.
- Topical:Transdermal patches and unit dose creams serve pain management and hormone replacement therapies with specialized adhesive and barrier technologies.
Injectable formats command premium pricing; oral delivery maintains volume leadership across retail channels.
End User:
Customer type determines packaging complexity and barcode integration requirements.
- Hospitals:Inpatient pharmacies require bedside-verified unit doses with integrated electronic medication administration records. Texas and California health systems deploy robotic deblistering to extend pharmacist oversight.
- Long-term Care:Nursing facilities need multi-dose blister cards with calendarized packaging for regulatory compliance and medication adherence monitoring.
- Pharmacies:Central fill operations and retail chains demand high-speed packaging lines with serialization for track-and-trace mandates.
- Clinics:Ambulatory settings prioritize pre-filled syringes and single-use vials for point-of-care administration efficiency.
Hospitals absorb the bulk of high-complexity capacity; long-term care is gaining share fastest.
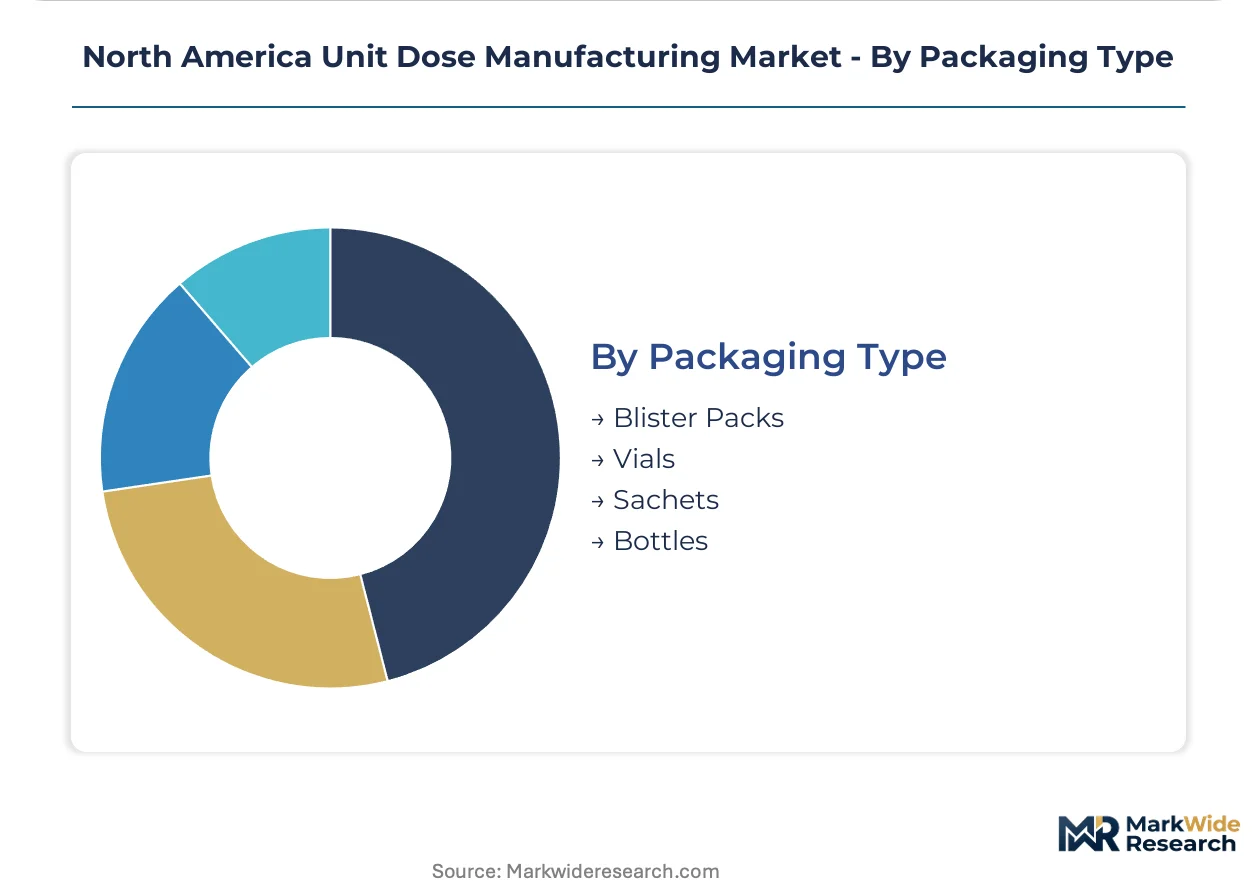
Packaging Type:
Margin structure varies with material science intensity and cold-chain compatibility.
- Blister Packs:Cold-form aluminum laminates and thermoformed PVC provide moisture and light protection for oral solids. Southeast US manufacturers face aluminum laminate supply concentration risks during demand spikes.
- Vials:Glass and polymer containers with elastomeric closures serve sterile injectables requiring lyophilization or liquid stability.
- Sachets:Flexible film pouches accommodate powders and granules with tear-notched convenience for geriatric and pediatric use.
- Bottles:HDPE and PET containers with child-resistant closures retain share in outpatient oral liquid and solid portfolios.
Blister packs absorb the bulk of oral solid capacity; vials are climbing the fastest in value terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Research Triangle Park corridor in North Carolina anchors North American unit dose manufacturing capacity, hosting contract manufacturers serving FDA-regulated sterile fill-finish operations for oncology and immunology portfolios.
United States
Hospital pharmacies in Texas and California deploy robotic deblistering systems to extend pharmacist oversight without proportional headcount expansion. The FDA's serialization mandates and USP <797> sterile compounding standards force upgrades to isolator-based filling lines across southeastern manufacturing clusters. North Carolina's Research Triangle and New Jersey's pharmaceutical corridor concentrate blow-fill-seal automation investments for ophthalmic and respiratory liquid formats.
Canada
Montreal and Toronto biologics clusters lack dedicated high-potency unit dose capacity, creating white space for cross-border contract manufacturers with Health Canada establishment licenses. Health Canada's ICH Q10 pharmaceutical quality system guidelines tighten documentation requirements for multi-site operators running parallel US-Canada production. Ontario-based facilities centralize batch record review functions to manage harmonized deviation investigations across the border.
Southeastern United States
Florida and Arizona aging demographics drive blister-packed oral solid demand for long-term care medication management programs with barcode verification. NHTSA and DOT hazardous materials rules constrain transport packaging for cytotoxic unit dose products moving through regional distribution hubs. Georgia and Tennessee contract manufacturing clusters serve branded pharmaceutical clients under committed capacity contracts with penalty clauses for non-performance.
California
Health systems in the San Francisco Bay Area and Los Angeles metro integrate RFID-enabled blister packs with electronic medication administration records for new pricing tiers. California's Board of Pharmacy enforces stringent sterile compounding oversight that pushes hospital pharmacies toward outsourced unit dose preparation. The state's central fill operations demand high-speed packaging lines with track-and-trace serialization for retail pharmacy chains.
Northeast Corridor
New Jersey and Pennsylvania host legacy oral solid packaging facilities requiring custom engineering for serialization module retrofitting. The FDA's Current Good Manufacturing Practice regulations drive continuous monitoring system investments across Philadelphia-area injectable manufacturing sites. Boston's biotech cluster generates demand for biologic-compatible unit dose formats that bypass traditional vial filling in favor of advanced delivery systems.
North America Unit Dose Manufacturing Market Key Industry Players
Premium-margin players sit above commodity-margin players across sterility complexity and isolator infrastructure investment tiers. The market structures around three distinct player categories: integrated CDMO networks spanning clinical-to-commercial services, specialized high-potency handling facilities commanding pricing premiums, and regional oral solid packagers competing on throughput speed. Consolidation pressures concentrate among mid-scale operators lacking capital reserves for FDA-mandated track-and-trace system upgrades. Dominant competitive moves include multi-year committed capacity contracts with penalty clauses and geographic expansion into underserved Canadian biologics corridors.
Within the integrated network tier, Catalent Inc. and Thermo Fisher Scientific exemplify archetypes combining biologics capabilities with end-to-end service breadth. PCI Pharma Services occupies a position representing specialized high-potency handling differentiation. These three entities anchor competitive positioning across the sterile injectable and oral solid segments without overlapping commodity-packaging territories.
| Leading Market Players |
|---|
| Catalent Inc. |
| Thermo Fisher Scientific |
| Unither Pharmaceuticals |
| PCI Pharma Services |
| Corden Pharma |
| Mikart LLC |
| LTS LOHMANN Therapie-Systeme AG |
| Renaissance Lakewood LLC |
| Medical Packaging Inc. |
| Others |
Cost & Logistics Intelligence
Captive integration of isolator-based filling capacity by Catalent, Thermo Fisher Scientific, and PCI Pharma Services anchors both supply security and premium pricing power for sterile injectable unit doses across the southeastern United States. This vertical control over restricted access barrier systems insulates these operators from aluminum laminate volatility while enabling yield-guaranteed contracting terms that commodity oral solid packagers cannot match.
Pricing Analysis
Yield-based pricing anchors sterile fill-finish contracts, with manufacturers guaranteeing batch success rates above specified thresholds in exchange for per-dose premiums that standard oral solid packaging cannot command. Price differentiation rests on USP <797> certification tier and isolator infrastructure depth, with FDA-validated facilities capturing margins that thermoformed blister operations surrender to throughput competition. Cost compression in standard oral solid segments is intensifying because hospital pharmacy benefit managers are consolidating purchase volumes under committed capacity agreements. Long-term care facilities in Florida and Arizona exhibit the highest price sensitivity, while oncology-focused health systems in Texas and California prioritize sterility assurance over per-unit cost.
Supply Chain Analysis
Cold-chain freight costs for cytotoxic unit doses are constraining distribution radius and reinforcing regional manufacturing clustering around patient population centers. Supply concentration centers on the United States, Canada, and Mexico, with active pharmaceutical ingredients drawing from Indian and Chinese chemical synthesis hubs. Cold-form aluminum laminates, elastomeric closures, and blow-fill-seal polymer resins constitute critical input dependencies. Single-source vulnerability in southeastern aluminum laminate supply exposes manufacturers to allocation constraints during demand spikes. Distribution runs through committed capacity contracts with penalty clauses rather than spot purchasing, locking in multi-year relationships between contract manufacturers and regional health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Isolator technician scarcity and 18-24 month FDA validation timelines for new filling lines are creating structural supply constraints that prop pricing premiums for existing validated capacity. This bottleneck justifies defensive capital allocation toward capacity protection rather than expansion.
For Market Incumbents: Deploy multi-year committed capacity contracts with penalty clauses to lock in hospital pharmacy and long-term care relationships before Canadian biologics corridors attract cross-border investment. Retrofit legacy oral solid lines with serialization modules to defend against mid-scale operator consolidation, while expanding isolator technician training pipelines to mitigate 40% wage premiums that threaten margin sustainability.
For New Entrants and Emerging Players: Launch via Health Canada establishment license acquisition into the Montreal and Toronto biologics corridor, where dedicated high-potency unit dose capacity remains undersupplied. Target long-term care medication management programs in Arizona and Florida with RFID-enabled blister pack integration, leveraging the fastest-growing demand channel outside acute hospital settings.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated CDMO networks seeking isolator infrastructure depth, with financial sponsor rollup of mid-scale oral solid packagers as secondary liquidity route. Acquisition targets should display Health Canada cross-border licenses and established hospital pharmacy relationships. Watch FDA validation timeline compression or Health Canada ICH Q10 enforcement acceleration as inflection signals for capacity value repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Isolator Infrastructure Expansion | FDA-validated restricted access barrier systems command premium pricing in oncology and immunology portfolios. |
| Health Canada License Acquisition | Cross-border establishment licenses unlock underserved Montreal and Toronto biologics manufacturing demand. |
| RFID-Enabled Blister Pack Integration | Electronic medication administration record convergence creates new pricing tiers for hospital pharmacy customers. |
| Serialization Module Retrofitting | FDA track-and-trace mandates force mid-scale operator consolidation among legacy oral solid packagers. |
| Isolator Technician Training Pipeline | Qualified operator scarcity inflates labor costs 40% above conventional cleanroom staff in high-complexity segments. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with contract manufacturing executives, hospital pharmacy directors, long-term care procurement managers, and sterile compounding specialists. FDA 483 inspection observations, Health Canada establishment license databases, and USP <797> compliance audit reports provided facility-level validation. Bottom-up capacity utilization modeling triangulated against top-down health system expenditure tracking.
Granularity-level modeling disaggregated the analysis window by dosage form complexity, sterility requirement, packaging material science intensity, and end-user regulatory environment. CAGRs were derived from installed capacity expansion schedules cross-referenced with patient population growth and formulary adoption curves. Forecast inputs incorporated blow-fill-seal automation penetration rates and prefilled syringe substitution pressures in biologic therapy segments.
Regulatory enforcement acceleration, aluminum laminate supply disruption, and isolator technician wage inflation are the dominant revision risks to capacity expansion assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Pharmacy Automation Market
Pharmaceutical Equipment
Shell Vials Market
Pharmaceutical Equipment
Sterile Vials Market
Pharmaceutical Equipment
Flexible Manufacturing Systems for Pharmaceutical Industry Market
Pharmaceutical Equipment
Pharmaceutical Sterilization Equipment Market
Pharmaceutical Equipment
Pharmaceutical Filtration Market
Pharmaceutical Equipment
Pharmaceutical Continuous Manufacturing Market
Pharmaceutical Equipment
Automated Radiosynthesis Modules Market
Pharmaceutical Equipment
North America and Europe Pharmaceutical Stability & Storage Services Market
Pharmaceutical Equipment
Radiochemical Synthesizers Market
Pharmaceutical Equipment
North America Pharmaceutical Isolator Market
Pharmaceutical Equipment
Pharmaceutical Cleaning Validation Market
Pharmaceutical Equipment
Global Pharmaceutical Isolator Market
Pharmaceutical Equipment
Closed Funnel Ampoules Market
Pharmaceutical Equipment
Pharmaceutical Refrigerators and Freezers Market
Pharmaceutical Equipment
Depyrogenation Oven Market