
 Shell Vials Market | 2026-2036
Shell Vials Market Size, Share, and Industry Trends Forecast 2026-2036
Shell Vials Market Analytics
China is reshaping shell vials manufacturing through expanded borosilicate glass capacity and automated forming lines. Thermo Fisher Scientific leverages integrated life sciences distribution to sustain volume leadership across North American and European diagnostic channels. Agilent Technologies specializes in chromatography-grade vial specifications that dominate high-sensitivity analytical workflows. Waters Corporation anchors premium positioning through mass spectrometry-compatible shell vial geometries with ultra-low extractable profiles.
Shell vials are small-volume cylindrical containers, typically manufactured from borosilicate glass or inert polymers, designed for autosampler compatibility and minimal sample interaction during chromatographic and spectroscopic analysis. Wall thickness tolerances of 1.0–1.3 millimeters and flat-bottom geometries ensure precise needle penetration and reproducible injection volumes in high-throughput laboratory environments. Glass shell vials retain dominance in pharmaceutical quality control due to chemical inertness and thermal stability, while polypropylene variants are gaining share in disposable diagnostic applications where cost-per-test minimization drives procurement decisions. End use concentration in biotechnology reflects expanded monoclonal antibody development pipelines and cell therapy analytical workflows demanding certified low-adsorption vial surfaces.
FDA current Good Manufacturing Practice standards and EU MDR technical documentation requirements govern shell vial biocompatibility, extractable testing, and batch-level traceability for pharmaceutical contact materials. ISO 8362 and USP Type I glass classifications establish dimensional and hydrolytic resistance benchmarks that determine market access for premium analytical and parenteral packaging segments. EPA and OSHA frameworks additionally influence manufacturing facility emissions controls and worker exposure limits in glass melting and plastic molding operations. Stakeholders must monitor evolving pharmacopeial revisions and regional substitution incentives for sustainable materials as determinants of future product mix and geographic sourcing strategy.
Market Dynamics
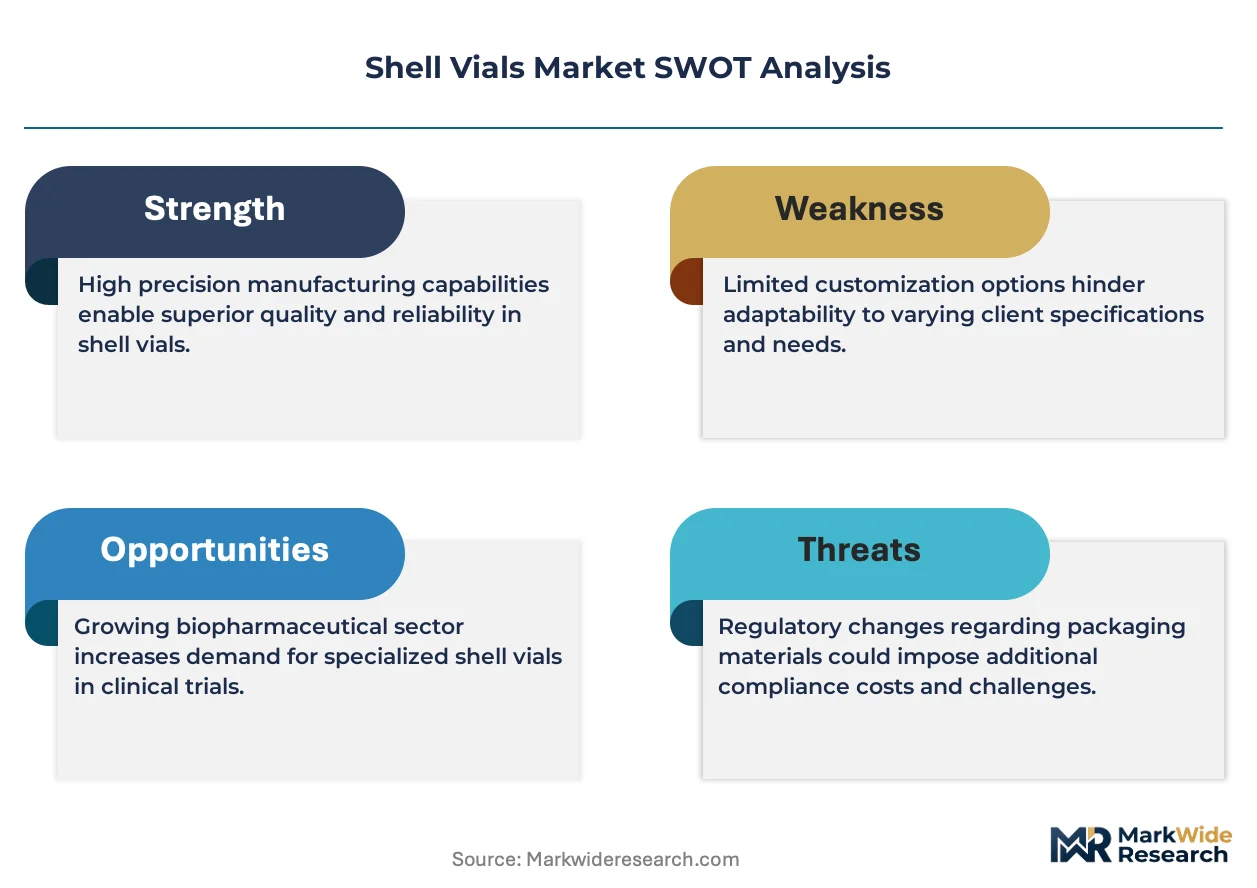
Pharmaceutical serialization mandates and precision glass manufacturing consolidation are compressing supplier margins while elevating certified low-extractable specifications as the primary procurement filter across sterile injectable supply chains.
Growth Catalysts
- EU MDR serialization mandates:Batch-level traceability requirements for pharmaceutical contact materials are forcing packaging upgrades across European biopharma production networks, expanding certified vial demand.
- Monoclonal antibody pipelines:Biotechnology analytical workflows require hydrolytic-resistant borosilicate surfaces for protein stability testing, concentrating procurement among ISO 8362-certified suppliers.
- Automated forming lines:Chinese glass manufacturers are deploying robotic precision molding to reduce dimensional tolerance variance below 0.1 millimeters for autosampler compatibility.
Market Restraints
- Borosilicate raw material volatility:German precision glass clusters face energy-intensive melting cost pressures from natural gas price fluctuations and carbon border adjustments.
- Supply concentration in Central Europe:Three manufacturing clusters control premium borosilicate forming capacity, creating single-source vulnerability for chromatography-grade specifications.
- Polypropylene substitution ceiling:Disposable diagnostic applications cannot achieve USP Type I hydrolytic resistance, limiting polymer vial penetration in parenteral packaging segments.
Strategic Opportunities
- Cell therapy CDMO expansion:Contract development organizations in Singapore and South Korea require certified low-adsorption shell vials for CAR-T analytical workflows, creating premium white space.
- EPA emissions controls:US glass melting facility upgrades under Clean Air Act enforcement are accelerating demand for electric furnace technology partnerships with equipment vendors.
- Direct-to-laboratory e-commerce:Chromatography consumable distributors are building same-day fulfillment networks for high-throughput analytical labs, disintermediating traditional medical supply wholesalers.
Industry Challenges
- Extractables testing talent scarcity:Pharmaceutical quality control departments face recruitment gaps for mass spectrometry specialists capable of validating ultra-low extractable profiles per USP 1664 guidelines.
- Multi-pharmacopeial certification timelines:Simultaneous FDA, EMA, and NMPA filing requirements extend product launch cycles by 18-24 months for new borosilicate formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shell Vials Market |
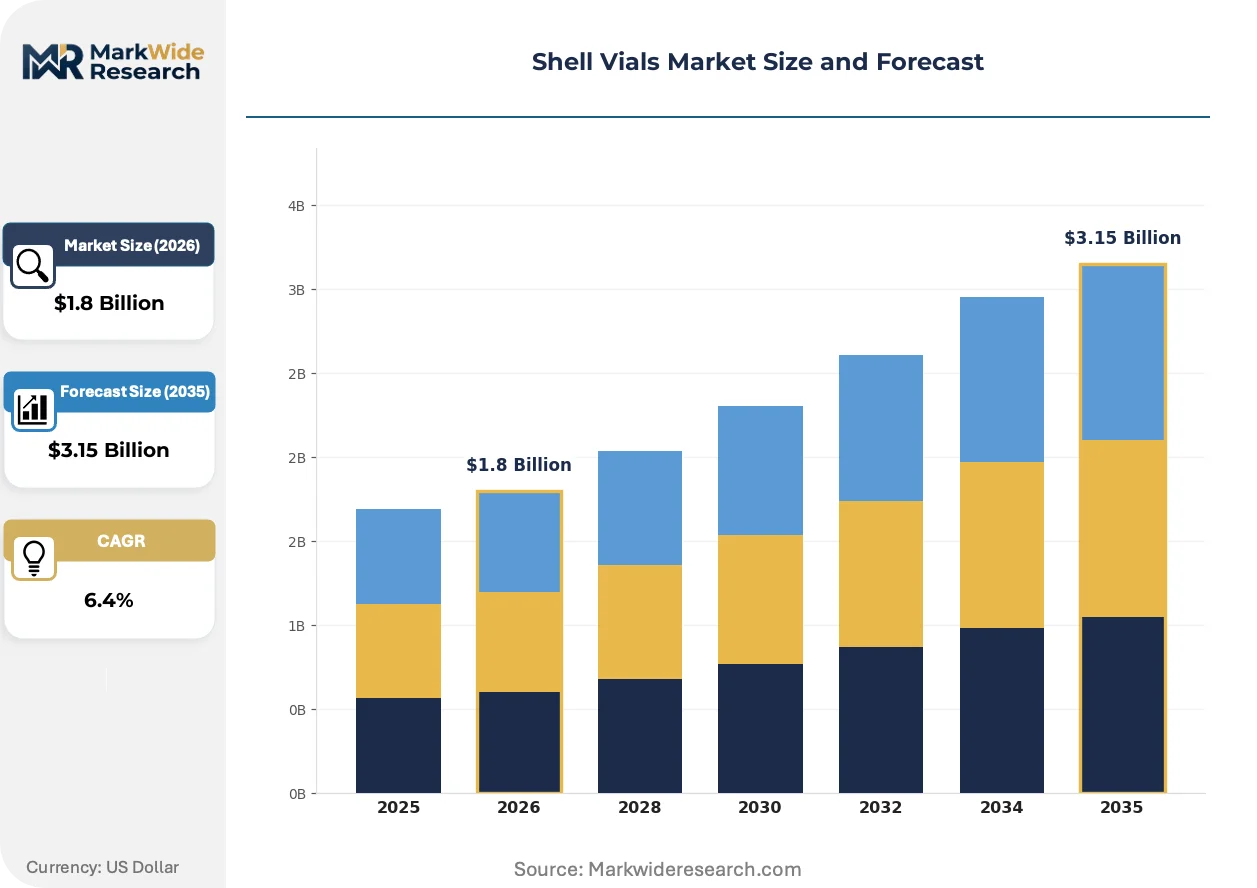
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Glass, Plastic, Polypropylene, Polyethylene Size: 1 mL, 5 mL, 10 mL, 20 mL End Use: Pharmaceutical, Biotechnology, Research Lab, Diagnostic Closure Type: Rubber Stopper, Sealing Cap, Aluminum Cap, Others |
| Companies Covered | Agilent Technologies, Inc., Waters Corporation, Thermo Fisher Scientific Inc., PerkinElmer, Inc., Shimadzu Corporation, Merck KGaA, Chemglass Inc., Gilson, Inc., Restek Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shell Vials Market Evolving Landscape
Digital traceability infrastructure and sustainable material transitions are restructuring how shell vial specifications are validated, procured, and integrated into continuous manufacturing workflows across pharmaceutical quality control.
Laser-etched serialization codes on individual vial surfaces are digitizing batch genealogy tracking from glass forming through final analytical use. Pharmaceutical quality control departments in Germany and Switzerland are mandating machine-readable identifiers for USP 1664 extractable studies. This technology is digitizing compliance documentation, compressing audit preparation timelines from weeks to hours while reducing manual transcription errors in regulated laboratories.
EU Green Deal carbon border adjustment mechanisms are accelerating electric furnace retrofits across borosilicate glass manufacturing. German precision glass clusters face compliance deadlines requiring 40% emissions reduction by 2030, forcing capital reallocation toward renewable-powered melting operations. Premium analytical vial segments are responding with certified low-carbon product lines that command procurement preference among ESG-mandated biotechnology buyers.
Consolidated procurement through group purchasing organizations is compressing supplier negotiation cycles for chromatography consumables. Large contract research organizations in Massachusetts and North Carolina are unbundling after-sales technical support from unit pricing, forcing mid-tier vial manufacturers to build dedicated field application scientist teams. This behavioral shift is most visible in North American biotechnology clusters where CDMO scale concentration enables volume-commitment contracting.
Shell Vials Market Segmentation
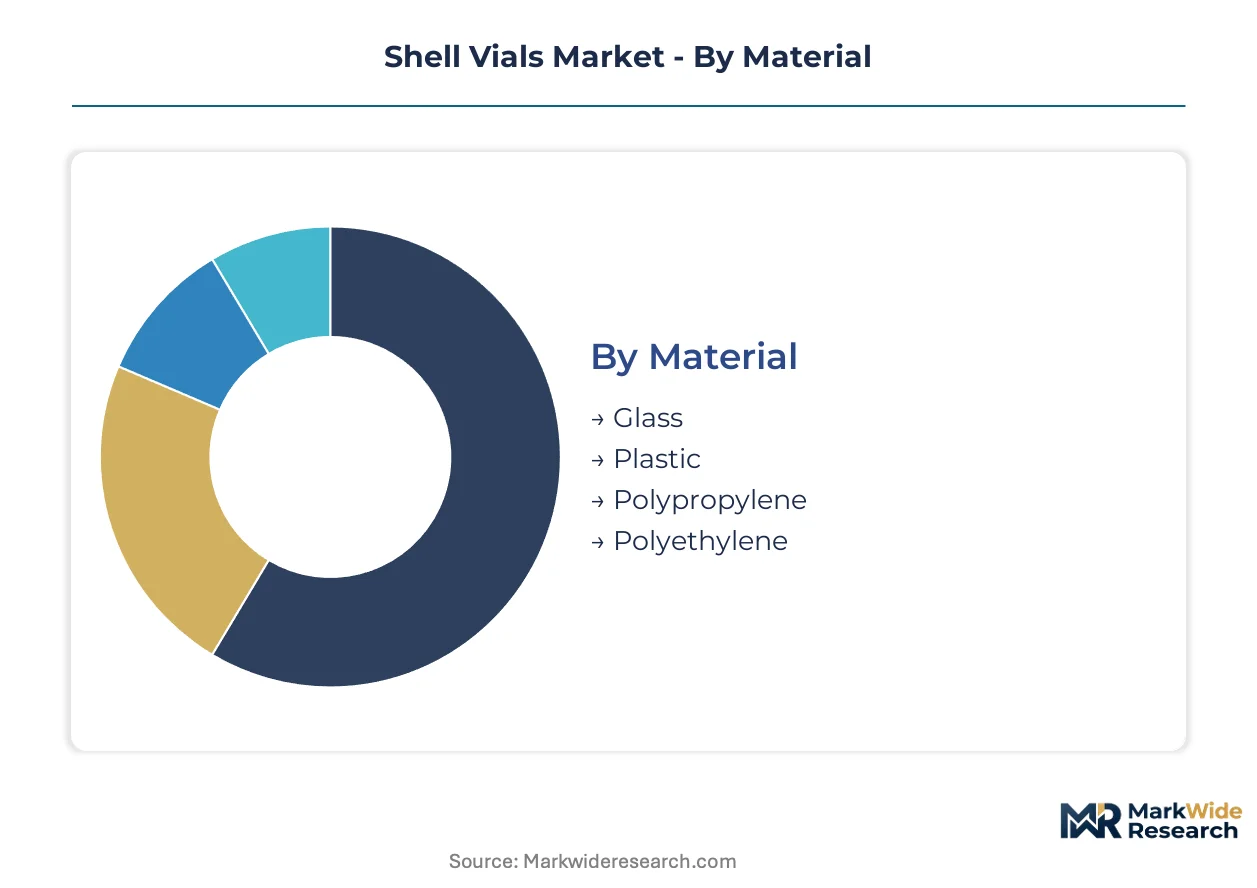
Shell vial procurement decisions cascade through material certification tiers, dimensional precision requirements, and end-use regulatory intensity. Each segmentation dimension carries distinct margin structures and compliance burdens that reshape supplier positioning across pharmaceutical and analytical workflows.
Material:
Cost tier differentiation separates certified pharmaceutical grades from disposable diagnostic alternatives, with raw material chemistry governing extractable profiles and thermal stability thresholds.
- Glass:Borosilicate formulations meeting USP Type I hydrolytic resistance standards dominate parenteral packaging and chromatography applications. German precision glass clusters in Mainz and Jena supply central European biopharma networks facing EU MDR serialization mandates.
- Plastic:Polymer formulations sacrifice thermal stability for cost-per-test minimization in high-throughput diagnostic environments. Demand concentrates in North American clinical laboratory networks where disposability outweighs extractable certification requirements.
- Polypropylene:Inert hydrocarbon chains resist aqueous sample interaction but cannot achieve borosilicate hydrolytic resistance grades. Single-use diagnostic workflows in Massachusetts and North Carolina procurement networks favor this tier for non-parenteral applications.
- Polyethylene:Lower density variants offer marginal cost advantages in non-critical research settings. Academic laboratory procurement in California and Texas represents the primary absorption channel for this specification tier.
Glass commands the established base across pharmaceutical quality control. The steepest expansion runs through polypropylene as diagnostic automation accelerates disposable consumable throughput.
Size:
Volume specifications align with autosampler needle penetration depths and minimum fill requirements across chromatography and spectroscopic instrumentation platforms.
- 1 mL:Micro-volume geometry enables high-sensitivity mass spectrometry workflows with minimal sample depletion. Agilent Technologies and Waters Corporation analytical divisions specify this dimension for proteomics and metabolomics applications requiring ultra-low dead volumes.
- 5 mL:Intermediate capacity balances sample sufficiency with autosampler rack density in pharmaceutical quality control laboratories. FDA-regulated stability testing protocols for monoclonal antibody formulations standardize on this volume for multi-timepoint analysis.
- 10 mL:Expanded capacity serves preparative chromatography and bulk reagent storage in contract manufacturing organizations. Singapore and South Korean cell therapy CDMOs specify this dimension for CAR-T analytical workflow scalability.
- 20 mL:Maximum standard volume supports rare sample archiving and reference standard preparation in regulatory laboratories. Swissmedic-inspected facilities in Basel and Zurich maintain certified low-adsorption inventories at this scale for long-term stability studies.
5 mL specifications anchor routine pharmaceutical quality control. 1 mL dimensions are climbing the fastest as high-sensitivity analytical platforms proliferate across biotechnology research networks.
End Use:
Application intensity determines certification depth, with parenteral contact materials facing multi-pharmacopeial validation timelines that extend procurement cycles.
- Pharmaceutical:Sterile injectable packaging demands USP 1664 extractable validation and batch-level traceability under FDA current Good Manufacturing Practice. Serialization mandates compress supplier qualification timelines while elevating certified low-extractable specifications as primary procurement filters.
- Biotechnology:Monoclonal antibody and cell therapy analytical workflows require hydrolytic-resistant surfaces for protein stability testing. ISO 8362-certified borosilicate specifications from German and Swiss manufacturers concentrate procurement among precision glass specialists.
- Research Lab:Academic and government laboratories prioritize cost efficiency over extractable certification for non-regulated discovery workflows. Chinese e-commerce distributors are disintermediating traditional supply chains through direct-to-laboratory fulfillment networks.
- Diagnostic:Disposable polymer vials in automated clinical analyzers minimize cross-contamination risk through single-use protocols. Thermo Fisher Scientific integrated distribution channels sustain volume leadership across North American hospital laboratory networks.
Pharmaceutical applications retain the revenue base through premium certification requirements. Biotechnology workflows are gaining share fastest as cell therapy pipelines expand analytical consumable intensity.
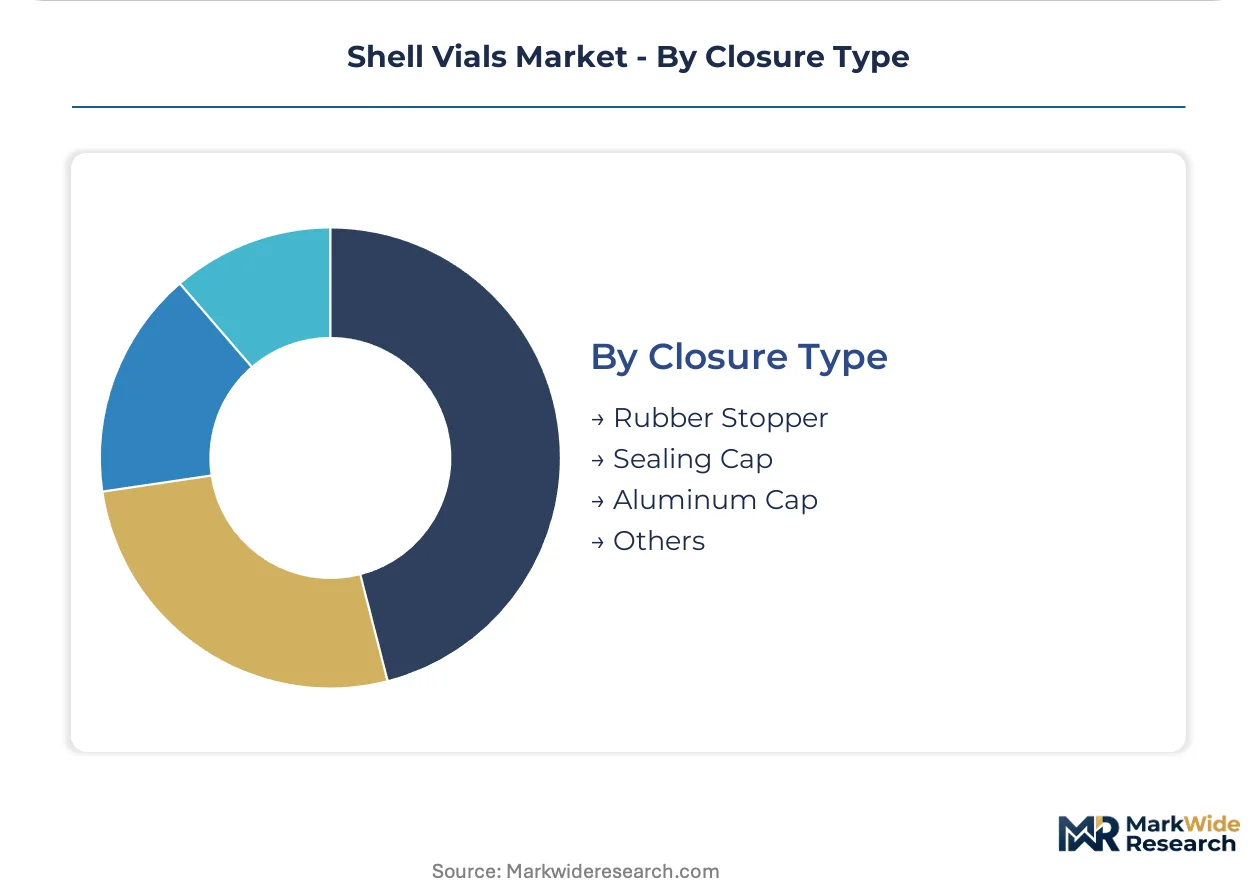
Closure Type:
Sealing mechanism selection governs headspace integrity, needle penetration resistance, and aluminum crimp compatibility across automated capping and decapping equipment.
- Rubber Stopper:Bromobutyl and chlorobutyl elastomer formulations provide resealability for multi-dose parenteral applications. West Pharmaceutical Services and Aptar Group supply integrated vial-closure systems to FDA-regulated sterile fill-finish facilities in New Jersey and Puerto Rico.
- Sealing Cap:Threaded polypropylene closures enable hand-tight sealing in research and diagnostic environments without crimping equipment. Direct-to-laboratory distributors in Massachusetts and California specify this format for same-day fulfillment convenience.
- Aluminum Cap:Crimped metal seals provide tamper-evidence and hermetic integrity for long-term pharmaceutical stability storage. EMA technical documentation requirements for centralized European procedures mandate this closure grade for commercial drug products.
- Others:Specialty formats including snap-fit and magnetic closures serve niche automation platforms and cryogenic storage applications. Cryoport and Brooks Life Sciences integrate these variants into cold chain logistics systems for cell therapy distribution.
Aluminum crimp seals dominate commercial pharmaceutical packaging. Rubber stopper systems are expanding most quickly as integrated vial-closure platforms reduce assembly validation burden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA serialization mandates and EU MDR technical documentation requirements are reshaping procurement patterns across pharmaceutical packaging networks, with certified low-extractable specifications becoming the primary filter for supplier qualification in regulated markets.
United States
Massachusetts and North Carolina biotechnology clusters drive demand for chromatography-grade shell vials in monoclonal antibody analytical workflows. FDA current Good Manufacturing Practice standards govern extractable testing protocols under USP 1664 guidelines. New Jersey sterile fill-finish facilities source integrated vial-closure systems from domestic distributors serving FDA-regulated commercial drug production.
Germany
Mainz and Jena precision glass manufacturing clusters supply central European biopharma networks facing EU MDR batch-level traceability mandates. German glassmakers confront EU Green Deal carbon border adjustments requiring 40% emissions reduction by 2030. Bavarian analytical laboratories specify ISO 8362-certified borosilicate dimensions for high-throughput pharmaceutical quality control.
China
Expanded borosilicate glass capacity and automated robotic forming lines are reducing dimensional tolerance variance below 0.1 millimeters for autosampler compatibility. NMPA filing requirements extend product launch cycles for new pharmaceutical contact materials. Yangtze River Delta manufacturing hubs serve domestic diagnostic automation and export chromatography consumable demand.
Switzerland
Swissmedic-inspected facilities in Basel and Zurich maintain certified low-adsorption shell vial inventories for long-term stability studies and reference standard preparation. EMA centralized procedure technical documentation mandates aluminum crimp seals for commercial pharmaceutical products. Precision glass procurement concentrates among ISO-certified suppliers serving cell therapy analytical workflows.
Singapore
Cell therapy CDMO expansion is creating premium demand for certified low-adsorption shell vials in CAR-T analytical workflows. The national pharmaceutical regulator enforces batch-level traceability standards aligned with international pharmacopeial benchmarks. Biopharma manufacturing clusters specify 10 mL dimensions for scalable analytical processing in contract development operations.
Shell Vials Market Competitive Landscape
Precision glass specialists and integrated life sciences distributors split the market between certified pharmaceutical grades and high-throughput analytical channels. The supplier base concentrates around three manufacturing clusters controlling premium borosilicate forming capacity, creating tiered access based on pharmacopeial certification depth. Two strategic archetypes dominate: precision glass manufacturers with ISO 8362-certified melting operations, and integrated distributors leveraging same-day fulfillment networks for chromatography consumables. Competitive moves center on electric furnace technology partnerships for emissions compliance and dedicated field application scientist teams for technical support unbundling.
Among integrated life sciences distributors, Thermo Fisher Scientific Inc. exemplifies the scale-driven archetype through North American and European diagnostic channel penetration. Precision glass specialists Agilent Technologies, Inc. and Waters Corporation occupy positions within the chromatography-grade tier, with company names signaling analytical instrumentation heritage rather than commodity packaging supply. These three entities represent the dominant competitive anchors across certified low-extractable and high-sensitivity workflow segments.
| Leading Market Players |
|---|
| Agilent Technologies, Inc. |
| Waters Corporation |
| Thermo Fisher Scientific Inc. |
| PerkinElmer, Inc. |
| Shimadzu Corporation |
| Merck KGaA |
| Chemglass Inc. |
| Gilson, Inc. |
| Restek Corporation |
| Others |
Value Network & Pricing Analysis
Mainz and Jena precision glass clusters in Germany anchor premium borosilicate capacity, translating concentrated melting expertise into pricing power over ISO 8362-certified pharmaceutical grades. Cost compression in diagnostic polymer tiers accelerates as Chinese automated forming lines reduce dimensional tolerance variance below 0.1 millimeters, forcing mid-tier suppliers to unbundle technical support from unit pricing or exit.
Pricing Analysis
Geographic price spreads separate German precision glass at premium tiers from Chinese automated output serving diagnostic mass markets. Three-tier pricing structure across premium, standard, and economy levels stratifies by USP Type I hydrolytic resistance certification, with batch-level traceability mandates under EU MDR widening spreads between certified and uncertified grades. Cost compression in polymer diagnostic tiers intensifies as disposability requirements override extractable validation. Academic laboratory procurement in California and Texas exhibits highest price sensitivity, while Swissmedic-inspected facilities in Basel accept premium positioning for long-term stability studies.
Supply Chain Analysis
Export control regimes on precision glass forming technology limit equipment flows to Chinese manufacturers, preserving German and Swiss technical leadership in low-extractable specifications. Supply concentrates in Germany, China, and Switzerland, with borosilicate raw material sourcing drawing from Ukrainian soda ash and Siberian quartz deposits. Single-source vulnerability pervades chromatography-grade forming capacity controlled by three manufacturing clusters. Distribution runs through integrated life sciences distributors in North America and direct-to-laboratory e-commerce networks disintermediating traditional medical supply wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where field application scientist teams and extractables validation support expand faster than commodity vial hardware. Recurring revenue from USP 1664 compliance documentation and batch genealogy tracking services now exceeds unit margin capture in premium segments.
For Market Incumbents: Harden certification depth against polypropylene substitution ceilings by investing in ISO 8362-certified electric furnace capacity ahead of EU Green Deal deadlines. Lock in cell therapy CDMO relationships in Singapore and South Korea through dedicated low-adsorption product lines and embedded field support teams. Defensive consolidation around extractables testing talent scarcity protects margin structure from mid-tier competitors unbundling technical service. For New Entrants and Emerging Players: Build out direct-to-laboratory e-commerce fulfillment networks targeting Massachusetts and North Carolina biotechnology clusters where same-day chromatography consumable delivery remains underserved. Penetrate polypropylene diagnostic tiers in North American clinical laboratory networks where cost-per-test minimization overrides brand loyalty. Anchor go-to-market strategy through group purchasing organization bypass, offering unbundled pricing without after-sales support overhead. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because pharmacopeial certification timelines extend competitive moats beyond manufacturing scale. Precision glass specialists with captive electric furnace technology and ISO 8362 melting operations represent the optimal acquisition archetype. Watch for EPA Clean Air Act enforcement acceleration as the inflection signal forcing capital reallocation toward emissions-compliant capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Furnace Technology Partnership | Enables 40% emissions reduction compliance under EU Green Deal carbon border adjustments. |
| Field Application Scientist Team Buildout | Addresses unbundling pressure from Massachusetts CDMOs demanding embedded technical support. |
| Cell Therapy CDMO Supply Agreement | Captures premium white space in Singapore CAR-T analytical workflow expansion. |
| Laser-Etched Serialization Infrastructure | Compresses USP 1664 audit preparation timelines from weeks to hours for Swissmedic facilities. |
| Direct-to-Laboratory E-Commerce Platform | Disintermediates traditional wholesalers serving high-throughput North American diagnostic labs. |
Research Methodology
A spread of perspectives from pharmaceutical quality control directors, regulatory affairs specialists at sterile fill-finish facilities, chromatography consumable procurement managers, and precision glass manufacturing engineers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation through FDA 483 inspection observations, EMA centralized procedure technical documentation, USP pharmacopeial revision notices, and ISO 8362 certification databases. Bottom-up volume builds from individual facility consumption patterns triangulated against top-down borosilicate glass production capacity assessments across German and Chinese manufacturing clusters.
Demand-supply balance modeling anchored projections across material certification tiers, dimensional precision requirements, and end-use regulatory intensity. Segmentation dimensions spanned glass versus polymer chemistry, 1-20 mL volume specifications, pharmaceutical versus diagnostic application intensity, and closure mechanism compatibility. CAGRs derived from weighted capacity expansion timelines, regulatory mandate enforcement schedules, and substitution elasticity estimates for polymer alternatives in non-parenteral workflows. Industry-specific inputs incorporated monoclonal antibody pipeline advancement rates and cell therapy CDMO facility commissioning announcements.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese automated forming lines or accelerated electric furnace retrofits by German clusters would shift outcomes. Material shifts in FDA serialization mandate enforcement timing, EU MDR carbon border adjustment implementation, or NMPA pharmaceutical contact material approval pathways would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Closed Funnel Ampoules Market
Pharmaceutical Equipment
Global Pharmaceutical Contract Manufacturing and Contract Research Market
Pharmaceutical Equipment
North America Pharmaceutical Isolator Market
Pharmaceutical Equipment
ASEAN Contract Development and Manufacturing Organization (CDMO) Market
Pharmaceutical Equipment
Sterile Fill-Finish Process Simulation and Media Fill Test Equipment Market
Pharmaceutical Equipment
Vials and Ampoules Market
Pharmaceutical Equipment
Radiochemical Synthesizers Market
Pharmaceutical Equipment
Prefilled Formalin Vials Market
Pharmaceutical Equipment
Pharmaceutical Automation Market
Pharmaceutical Equipment
Aseptic Negative Pressure Pharmaceutical Isolators Market
Pharmaceutical Equipment
Inhalation CDMO Market
Pharmaceutical Equipment
Europe Pharmaceutical Vials Market
Pharmaceutical Equipment
US Depyrogenated Sterile Empty Vials Market
Pharmaceutical Equipment
Sterile Vials Market
Pharmaceutical Equipment
Serum Vials Market
Pharmaceutical Equipment
Europe Pharmacy Automation Market