
 Pharmerging Contract Manufacturing Market | 2026-2036
Pharmerging Contract Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmerging Contract Manufacturing Market Analytics
Fill-finish services is consolidating as the highest-margin attachment in biologics outsourcing contracts, transforming standalone API supply into integrated drug-product partnerships. Lonza Group anchors its competitive position through mammalian cell culture scale-up at Swiss and Singapore sites. Catalent, Inc. differentiates via specialized containment infrastructure for potent compounds. WuXi AppTec extends geographic reach through U.S. and European regulatory-grade facilities.
Pharmerging contract manufacturing encompasses outsourced production of pharmaceuticals for emerging markets, spanning active pharmaceutical ingredient synthesis, biologic drug substance manufacture, and finished dosage form processing under GMP conditions with batch release by national regulators. The primary purpose is to enable originator and generic firms to access certified capacity without capital-intensive facility construction. Biologics and biosimilars command premium pricing due to cold-chain complexity and cell-line stewardship requirements, while small molecules remain the volume backbone across Indian and Chinese facilities. Continuous processing technology attracts investment as batch failure rates and facility footprint shrink, though microbial fermentation still dominates antibiotic and vaccine bulk production.
FDA, EMA, and India's CDSCO collectively shape market access through divergent inspection calendars and data integrity expectations that favor multi-site operators with dedicated regulatory affairs teams. China's NMPA now requires local clinical data for imported biologics, pushing multinationals toward domestic CDMO partnerships rather than pure export models. Stakeholders must monitor how CDSCO's revised Schedule M and NMPA's updated GMP annexes for biological products recalibrate acceptable quality agreements between sponsors and contract manufacturers.
Market Dynamics
Fill-finish capacity scarcity in biologics is compressing contract timelines and elevating pricing power for CDMOs with aseptic isolator technology, as originators race to secure slots for biosimilar launches.
Growth Catalysts
- India's PLI scheme for APIs:Domestic manufacturers are expanding fermentation capacity to reduce import dependence on Chinese intermediates, creating captive demand for local contract synthesis.
- Biosimilar pipeline deepening:Southeast Asian and Latin American generic firms now outsource monoclonal antibody production to specialized mammalian cell culture facilities rather than building in-house.
- Dual FDA-EMA certification:Procurement officers at originator firms are mandating dual regulatory audits, redirecting volume toward CDMOs with synchronized compliance infrastructure.
Market Restraints
- Specialized media cost volatility:Serum-free and chemically defined cell culture media prices fluctuate with agricultural commodity cycles, squeezing margin predictability for biologics manufacturers.
- Single-source equipment dependency:Stainless steel bioreactor supply concentrates among German and Swiss fabricators, creating delivery bottlenecks for capacity expansions.
- NMPA local clinical data mandate:China's requirement for domestic trial data before biologic import approval forces multinationals into complex partnership structures rather than pure export arrangements.
Strategic Opportunities
- Brazil's underpenetrated fill-finish market:Domestic formulation capacity cannot absorb accelerating biotech licensing activity, creating white space for imported aseptic processing services.
- Continuous processing convergence:Perfusion cell culture technology is merging with single-use downstream processing to enable smaller-footprint, higher-throughput biologic manufacturing.
- EU MDR sterile injectable requirements:The tightened compliance threshold for barrier technology and environmental monitoring is disqualifying legacy facilities and concentrating volume among upgraded sites.
Industry Challenges
- Qualified aseptic operator scarcity:Fill-finish facilities in India and China face recruitment gaps for personnel capable of isolator-based intervention techniques and viable environmental monitoring.
- Technology transfer timeline compression:Accelerated biosimilar launch schedules compress the validation window for cell line adaptation and process analytical technology implementation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmerging Contract Manufacturing Market |
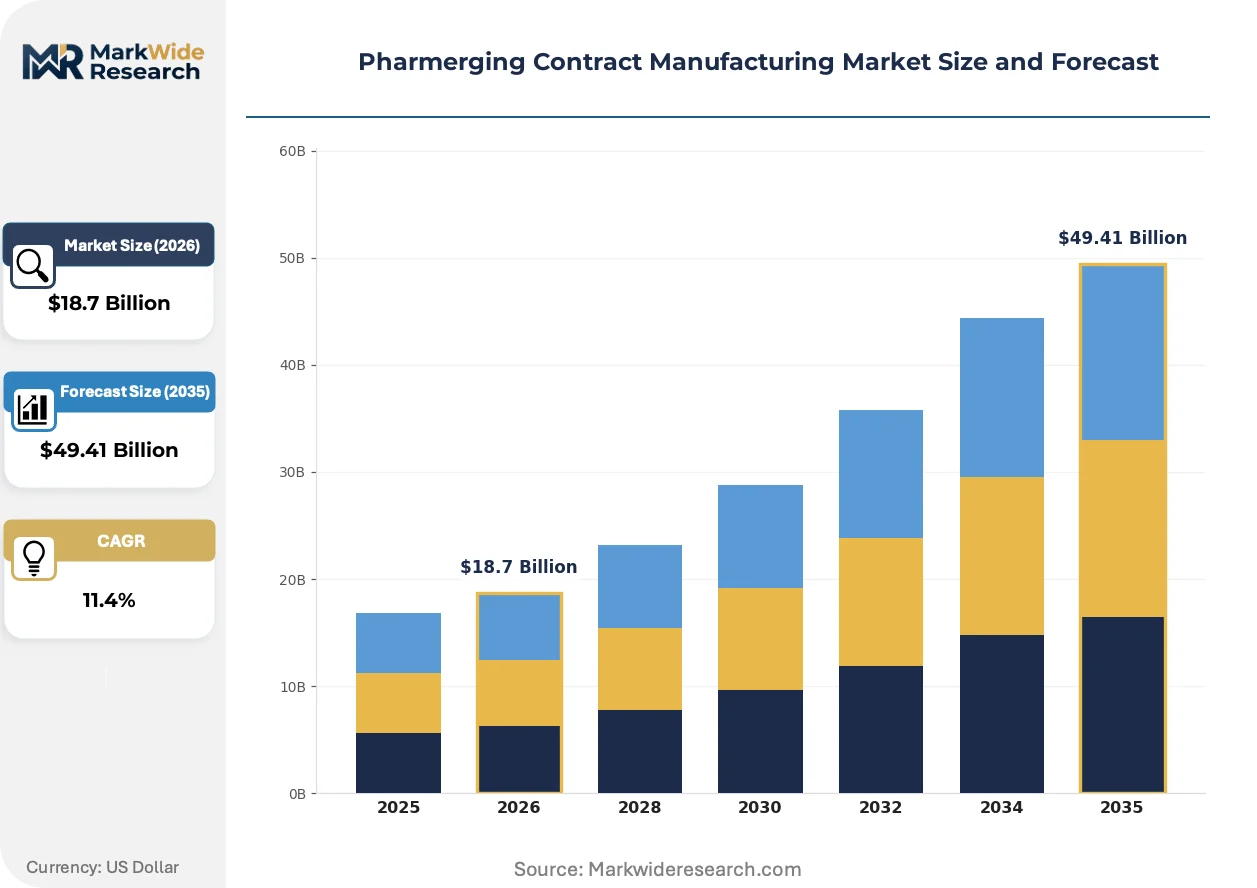
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biologics, Biosimilars, Small Molecules, Injectables Technology: Cell Culture, Microbial Fermentation, Fill-Finish, Continuous Processing End User: Pharmaceutical Companies, Biotech Firms, Academic Institutions, Startups Delivery Mode: Intravenous, Oral, Transdermal, Inhalation |
| Companies Covered | Lonza Group, Catalent, Inc., Thermo Fisher Scientific, WuXi AppTec, Boehringer Ingelheim, Dr. Reddy's Laboratories, Jubilant Life Sciences, Recipharm AB, Evonik Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmerging Contract Manufacturing Market Evolving Landscape
Process intensification and regulatory harmonization pressures are reshaping how CDMOs configure capacity, with technology choices increasingly dictated by audit readiness rather than unit cost alone.
Continuous bioprocessing technology is converging with single-use automation platforms to enable real-time quality release and reduced facility footprints. Mid-scale biologics manufacturers in Singapore and Switzerland are adopting perfusion-fed bioreactors coupled with integrated continuous chromatography. This convergence is compressing the traditional batch-to-batch release cycle from weeks to days, enabling just-in-time inventory models for temperature-sensitive drug substances.
EMA's updated GMP Annex 1 for sterile manufacturing mandates barrier isolation and enhanced environmental monitoring for all new aseptic processing lines. European CDMOs are retrofitting existing suites with restricted access barrier systems and automated viable particle counters. Fill-finish operators serving the EU market are absorbing capital costs of 15-25 million euros per line upgrade, passing selective premiums to sponsors with accelerated approval timelines.
Originator procurement departments are consolidating vendor panels from 15-20 CDMOs to 3-5 strategic partners with integrated drug substance-to-drug product capabilities. Large pharma firms in the United States and Germany now require dedicated capacity reservations and co-investment in facility expansion as conditions of preferred supplier status. This behavioral shift is most visible in oncology biologics, where sponsor firms lock in five-year fill-finish commitments to secure slot availability for pipeline assets.
Pharmerging Contract Manufacturing Market Segmentation
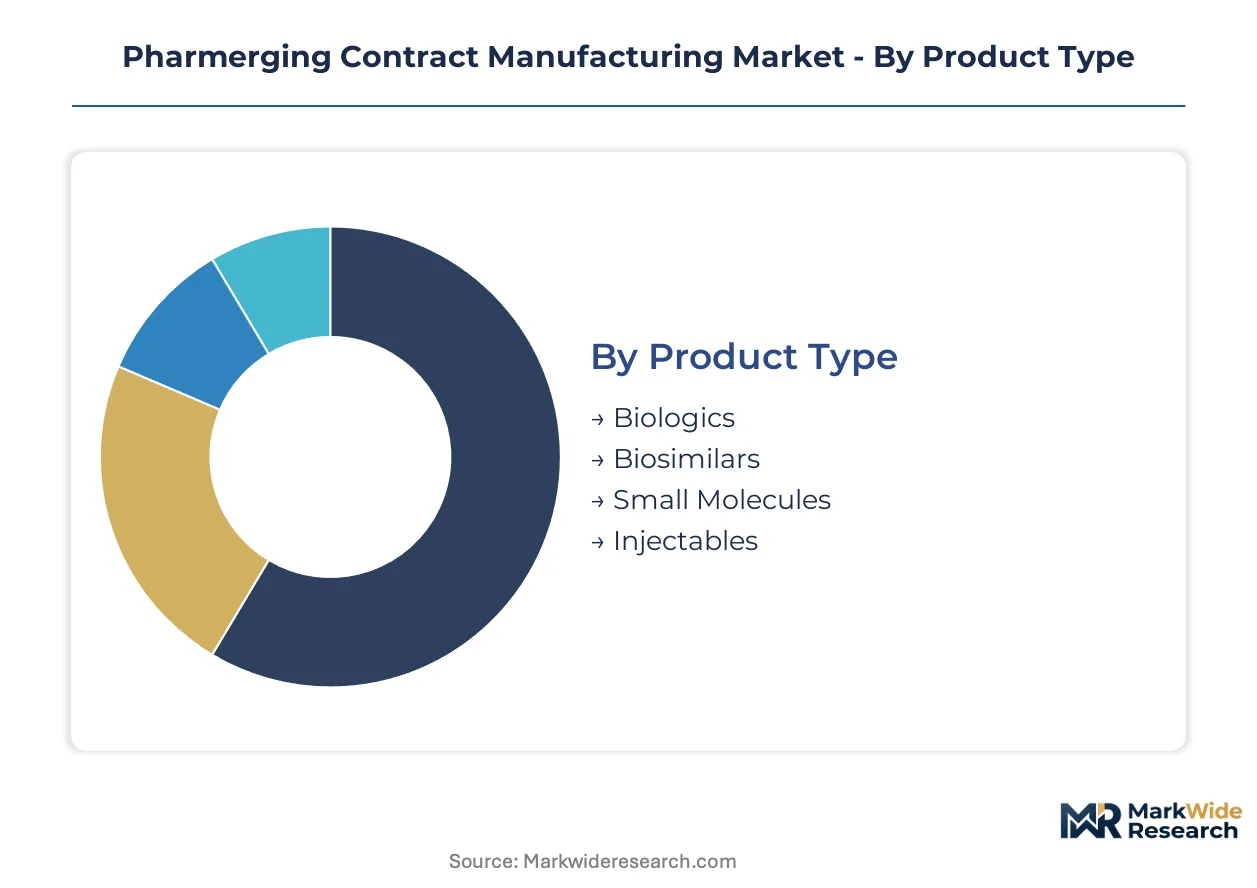
Segmentation in pharmerging contract manufacturing reveals how value migrates across technology tiers and customer types. Contract manufacturers must align facility investments with the specific regulatory and technical demands of each segment to capture premium pricing.
Product Type:
Volume concentration sits with mature small-molecule categories, while margin expansion concentrates in biologics and biosimilars requiring specialized containment and cold-chain infrastructure.
- Biologics:Mammalian cell culture-derived monoclonal antibodies and recombinant proteins demand single-use bioreactor trains and dedicated viral clearance suites. Procurement officers at originator firms in Germany and Switzerland now mandate five-year capacity reservations for oncology biologics fill-finish slots.
- Biosimilars:Follow-on biologics manufactured under abbreviated approval pathways require cell-line stewardship and analytical biosimilarity packages that match reference products. Southeast Asian generic firms outsource biosimilar production to CDMOs with prior FDA pre-approval inspection history rather than building captive mammalian capacity.
- Small Molecules:Synthetic organic chemistry and solid oral dosage forms remain the volume backbone across Indian and Chinese facilities.
- Injectables:Sterile liquid and lyophilized parenterals require aseptic processing lines with isolator barrier technology for EU MDR compliance.
Today's leader: Small Molecules. Tomorrow's challenger: Biosimilars.
Technology:
Process maturity separates commodity fermentation from premium cell culture, with fill-finish commanding the steepest capacity premiums due to qualified operator scarcity.
- Cell Culture:Perfusion-fed bioreactors with integrated continuous chromatography enable real-time quality release and reduced facility footprints. Singapore-based CDMOs deploy this configuration for mid-scale biologics manufacturing serving Asia-Pacific markets.
- Microbial Fermentation:Bacterial and yeast-based expression systems dominate antibiotic and vaccine bulk production with established stainless steel infrastructure. India's PLI scheme for active pharmaceutical ingredients is expanding domestic fermentation capacity to reduce import dependence on Chinese intermediates.
- Fill-Finish:Aseptic isolator technology and automated viable particle counting command 15-25 million euro capital costs per line upgrade.
- Continuous Processing:Integrated upstream-downstream automation compresses batch release cycles from weeks to days.
Technology investment gravity centers on fill-finish isolator upgrades, with continuous processing gaining share fastest among greenfield biologics facilities.
End User:
Customer sophistication determines contract structure complexity, with large pharma demanding integrated partnerships and startups seeking flexible milestone-based arrangements.
- Pharmaceutical Companies:Large originator and generic firms with established regulatory affairs teams drive vendor consolidation from 15-20 CDMOs to 3-5 strategic partners. These customers require dedicated capacity reservations and co-investment in facility expansion as conditions of preferred supplier status.
- Biotech Firms:Venture-backed development-stage companies prioritize speed-to-IND and technology transfer efficiency over unit cost. Biotech procurement patterns favor CDMOs with modular single-use suites that accommodate rapid process changes between pipeline assets.
- Academic Institutions:University research hospitals and technology transfer offices require GMP manufacturing for early-phase clinical materials.
- Startups:Seed-stage companies with limited capital seek fee-for-service models with minimal upfront commitment.
Pharmaceutical Companies anchor current contract value. Biotech Firms represent the steepest expansion trajectory as licensing activity accelerates.
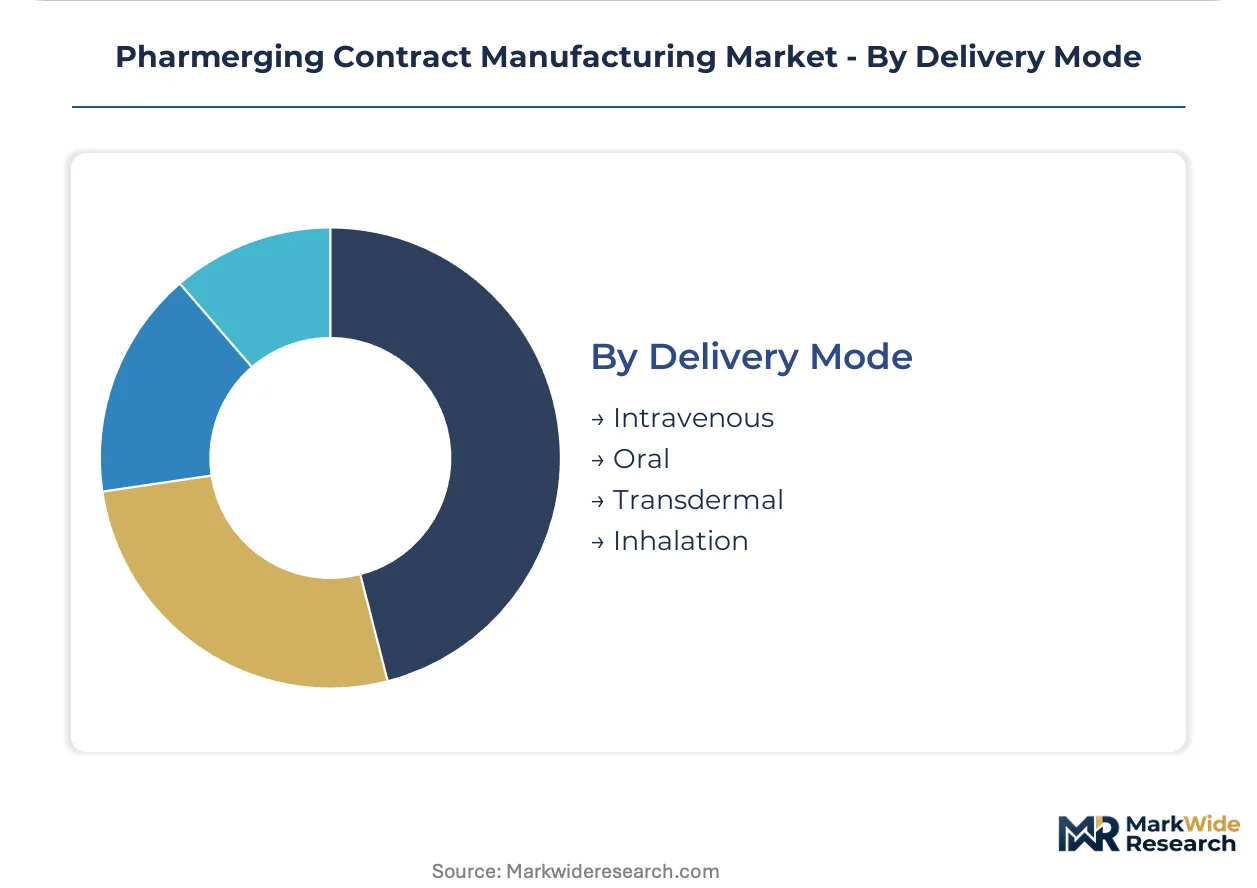
Delivery Mode:
Route of administration dictates facility infrastructure requirements, with parenteral formats requiring the most specialized containment and environmental monitoring systems.
- Intravenous:Sterile injectable solutions and lyophilized powders for infusion require aseptic processing with barrier isolation and continuous environmental monitoring. EMA's updated GMP Annex 1 mandates these upgrades for all new EU-serving lines.
- Oral:Tablets, capsules, and oral liquids utilize conventional solid dosage and liquid manufacturing equipment with lower capital intensity. Brazilian and Indian facilities concentrate oral dosage capacity for domestic and export markets.
- Transdermal:Patches and topical formulations require specialized adhesive coating and skin-permeation testing capabilities.
- Inhalation:Metered-dose and dry-powder inhalers demand particle engineering and cascade impaction testing for aerodynamic performance.
Intravenous formats dominate biologics value. Oral formats retain volume leadership across pharmerging markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting biologics manufacturing toward jurisdictions where FDA-EMA dual certification costs less to maintain. CDMOs in India, China, and Brazil capture volume as originators seek compliant capacity without Swiss or German facility economics.
India
Domestic fermentation capacity is expanding under the PLI scheme for active pharmaceutical ingredients, reducing import dependence on Chinese intermediates. CDSCO's revised Schedule M tightens quality agreements between sponsors and contract manufacturers. Hyderabad and Ahmedabad clusters concentrate mammalian cell culture investments serving biosimilar developers.
China
NMPA's local clinical data mandate for imported biologics forces multinationals into domestic CDMO partnerships rather than pure export models. Dual carbon goals from MEE pressure energy-intensive microbial fermentation sites toward efficiency retrofits. Shanghai and Suzhou biotech corridors anchor perfusion-fed bioreactor deployments for regional biologics supply.
Brazil
Underpenetrated fill-finish capacity cannot absorb accelerating biotech licensing activity from domestic generic firms. ANVISA's alignment with FDA inspection protocols enables export-oriented sterile injectable production. São Paulo state concentrates formulation investments as originators seek Latin American regulatory-grade supply.
Switzerland
Swissmedic's synchronized audit protocols with EMA attract originator procurement mandating dual regulatory coverage. Basel and Zurich sites command premium pricing for oncology biologics fill-finish with dedicated capacity reservations. Mammalian cell culture scale-up investments anchor integrated drug-substance-to-drug-product partnerships.
Singapore
Strategic location between Indian API supply and Asia-Pacific biotech demand positions the city-state as a mid-scale biologics manufacturing hub. EMA-equivalent GMP enforcement from the national pharmaceutical regulator enables EU market access without European facility costs. Tuas Biomedical Park concentrates continuous processing technology adoption for real-time quality release.
Pharmerging Contract Manufacturing Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated drug-substance-to-drug-product providers capturing preferred supplier status from vendor consolidation. The vendor base organizes around three strategic archetypes: Swiss-German precision manufacturers with dual FDA-EMA certifications, Indian-Chinese scale operators with fermentation cost advantages, and mid-tier regional specialists with isolator barrier technology. M&A activity concentrates fill-finish capacity under fewer owners, while greenfield expansion in Brazil and Southeast Asia addresses geographic white space.
Among Swiss-based integrated providers, Lonza Group exemplifies the dual-certified archetype with mammalian cell culture scale-up positioning. Catalent, Inc. represents specialized containment infrastructure for potent compounds. WuXi AppTec anchors geographic reach extension through regulatory-grade facilities in multiple jurisdictions.
| Leading Market Players |
|---|
| Lonza Group |
| Catalent, Inc. |
| Thermo Fisher Scientific |
| WuXi AppTec |
| Boehringer Ingelheim |
| Dr. Reddy's Laboratories |
| Jubilant Life Sciences |
| Recipharm AB |
| Evonik Industries |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up fill-finish specialists now control a disproportionate share of premium aseptic capacity, compressing procurement timelines while extracting capacity reservation fees from originator firms racing biosimilar launch windows. This ownership concentration tightens pricing discipline across Swiss and Singapore facilities where dual FDA-EMA certification commands structural premiums over Indian and Chinese fermentation-heavy sites.
Pricing Analysis
Capacity additions in India and China are reshaping price floors for small-molecule API synthesis, yet biologics fill-finish remains supply-constrained. Three-tier pricing structure across premium dual-certified, standard single-certified, and economy domestic-only levels separates CDMO tiers. Cost compression in standard-tier mammalian cell culture is intensifying because Chinese NMPA local clinical data mandates force partnership complexity. Generic firms in Southeast Asia exhibit highest price sensitivity, while German and Swiss originators prioritize slot availability over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from EMA and FDA now mandate that originator procurement teams qualify at least two fill-finish suppliers per biosimilar program, stretching qualified capacity thin. Supply concentrates in India for API fermentation, Switzerland for mammalian cell culture scale-up, and Singapore for mid-scale biologics finishing. Stainless steel bioreactor fabrication draws from German and Swiss fabricators, while serum-free cell culture media hinges on agricultural commodity cycles. Single-source equipment dependency creates delivery bottlenecks for expansions. Distribution runs through cold-chain logistics networks with regional regulatory release points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pharmerging contract manufacturing market compounds steadily as biologics licensing activity outpaces captive capacity buildout across emerging economies. Biosimilar pipeline deepening creates durable demand for specialized CDMO partnerships without cyclical interruption.
For Market Incumbents: Extend isolator barrier technology footprints into Brazil and Southeast Asia before regional specialists capture ANVISA-aligned fill-finish capacity. Lock in five-year dedicated capacity reservations with oncology biologics sponsors to defend against emerging Singapore-based competitors with EMA-equivalent certification. Prioritize continuous processing retrofits at Swiss and Indian sites to compress batch release cycles. For New Entrants and Emerging Players: Launch via fee-for-service models targeting Brazilian biotech startups seeking ANVISA-grade sterile injectable capacity without São Paulo facility economics. White space concentrates in mid-scale perfusion-fed bioreactor deployments serving Asia-Pacific biosimilar developers. Target CDSCO Schedule M compliance as a differentiated entry credential for Indian generic firms expanding into biologics. For Investors and Strategic Acquirers: Valuations sit cheapest among Indian fermentation-heavy API manufacturers with PLI scheme expansion capacity but limited biologics fill-finish exposure. Acquisition focus centers on regional specialists with isolator barrier technology and prior FDA pre-approval inspection history. Watch NMPA biologic import approval timelines as the signal indicating when Chinese domestic CDMO partnerships shift from mandatory to preferred.| Strategic Initiative | Industry Significance |
|---|---|
| Fill-Finish Capacity Expansion | Isolator line upgrades in Brazil absorb ANVISA-aligned sterile injectable demand from domestic generic firms. |
| Dual Certification Investment | Synchronized FDA-EMA audit protocols at Swiss sites command preferred supplier status from German originators. |
| Continuous Processing Adoption | Perfusion-fed bioreactor deployments in Singapore compress batch release cycles for temperature-sensitive drug substances. |
| Backward Integration into Cell Culture Media | In-house chemically defined media production buffers margin volatility from agricultural commodity price swings. |
| Regional Partnership Structuring | NMPA-mandated local clinical data forces multinationals into Chinese CDMO joint ventures versus pure export models. |
Research Methodology
Bottom-up biologics licensing activity modeling reconciled against top-down CDMO capacity tracking forms the analytical core of this study. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers combined with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and CDSCO Schedule M guidance documents. Triangulation between sponsor-reported pipeline data and contract manufacturer disclosed capacity expansions ensures consistency across volume estimates.
Historical trendline analysis of fill-finish slot utilization rates and API fermentation capacity additions informs the projection framework. Segmentation dimensions span product type, technology tier, end-user sophistication, and delivery mode, with regional regulatory cluster as an additional modeled dimension. CAGRs derive from fitted growth curves adjusted for biosimilar approval pathway acceleration and PLI scheme subsidy impacts. Forecast inputs include CDSCO inspection calendar density and NMPA biologic import approval velocity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt EMA GMP Annex 1 enforcement shifts or Chinese dual carbon goal acceleration. Projections reflect assumptions regarding regulatory harmonization progress and sponsor vendor consolidation behavior. Deviation in FDA-EMA synchronized audit protocol adoption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Vial Adaptors for Reconstitution Drug Market
Pharmaceutical Equipment
Pharmaceutical Automation Market
Pharmaceutical Equipment
Pharmaceutical Processing Equipment Market
Pharmaceutical Equipment
China Pharmaceutical Warehousing Market
Pharmaceutical Equipment
Sterile Injectable Contract Manufacturing Market
Pharmaceutical Equipment
Pharmaceutical Manufacturing Market
Pharmaceutical Equipment
Radiochemical Synthesizers Market
Pharmaceutical Equipment
Medication Dispenser Market
Pharmaceutical Equipment
Global Central Fill Pharmacy Automation Market
Pharmaceutical Equipment
Shell Vials Market
Pharmaceutical Equipment
Pharmaceutical Anti-Counterfeiting Technologies Market
Pharmaceutical Equipment
Depyrogenation Oven Market
Pharmaceutical Equipment
Interlock Vials Market
Pharmaceutical Equipment
Asia-Pacific CDMO Market
Pharmaceutical Equipment
Japan Contract Development and Manufacturing Organization Market
Pharmaceutical Equipment
Pharmaceutical Equipment Market