
 Asia-Pacific Pharmacy Automation Market | 2026-2036
Asia-Pacific Pharmacy Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Pharmacy Automation Market Analysis
Australia's TGA medication safety mandates is rebalancing procurement priorities toward error-reduction technologies. Omnicell Inc anchors its regional position through cloud-enabled inventory platforms. Swisslog Healthcare AG specializes in robotic dispensing architectures for high-volume hospital settings. Becton Dickinson competes via integrated medication management ecosystems spanning storage through administration.
Asia-Pacific pharmacy automation encompasses electromechanical systems, software middleware, and robotic platforms engineered to dispense, store, compound, and track pharmaceuticals with precision measured in single-dose accuracy. These systems eliminate manual transcription errors and accelerate prescription throughput in high-volume clinical environments. Automated dispensing systems dominate current installed bases across hospital pharmacies, while artificial intelligence segments attract disproportionate R&D investment for predictive inventory optimization. Robotics applications in sterile compounding represent the fastest-expanding margin pool as oncology and biologic therapies multiply.
Japan's PMDA enforces strict validation protocols for automated medication devices, elevating compliance costs for market entrants. India's CDSCO and China's NMPA are converging toward international harmonization standards for pharmacy software interoperability, reshaping vendor certification requirements. Stakeholders must monitor regulatory divergence between national pharmacopeia standards and emerging cross-border data governance frameworks.
Market Dynamics
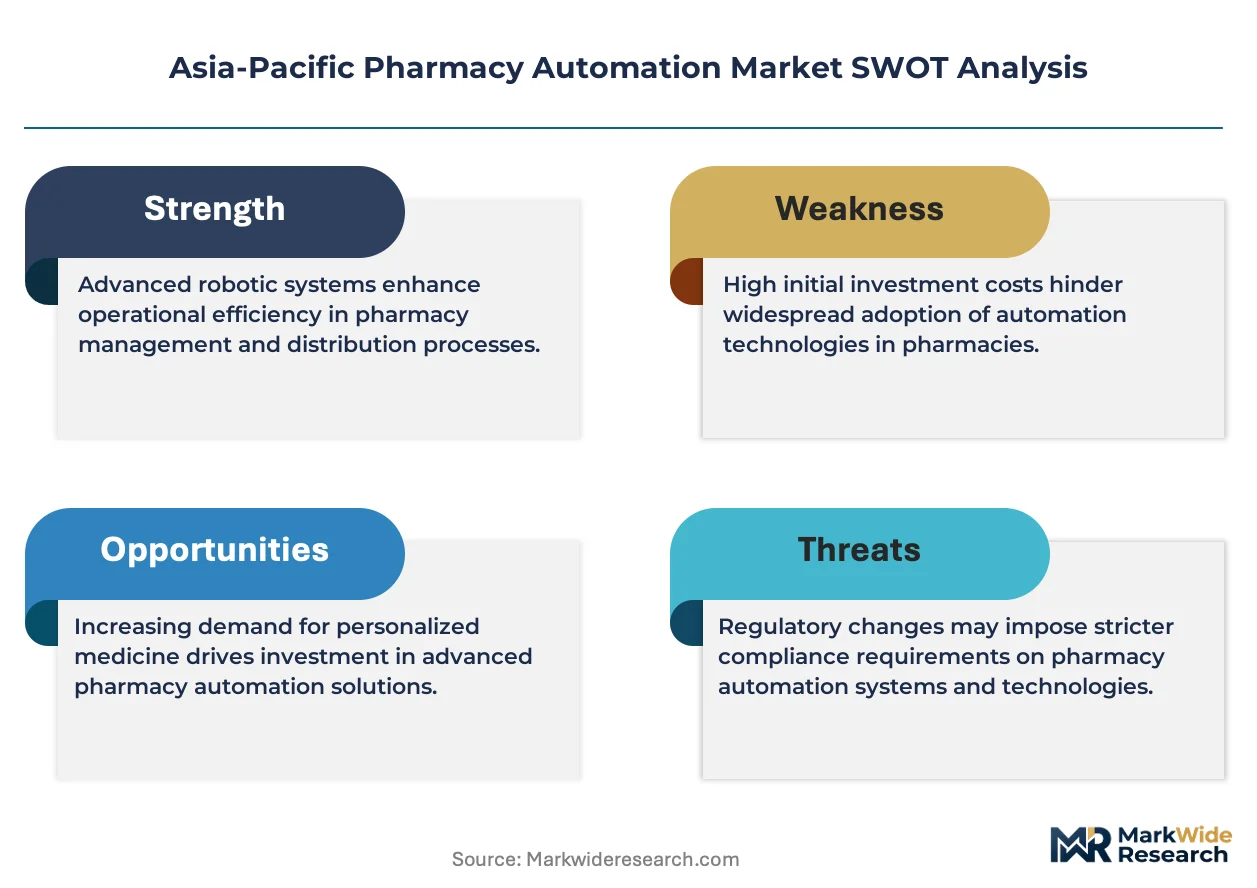
Japan's PMDA validation protocols for automated medication devices are compressing vendor certification timelines while elevating compliance investment thresholds across the Asia-Pacific region.
Growth Catalysts
- Japan's metropolitan hospital networks:Dense patient throughput in Tokyo and Osaka corridors is pulling robotic dispensing installations into 24/7 operational cycles.
- TGA medication safety mandates:Australia's tightened protocols are rebalancing procurement priorities toward error-reduction technologies with audit-trail capabilities.
- Oncology therapy expansion:Biologic and sterile compounding volumes are accelerating demand for isolator-based robotic systems with single-dose precision.
Market Restraints
- Component supply concentration:Servo motors and precision sensors concentrate in Japanese and South Korean manufacturing clusters, exposing lead time volatility.
- PMDA validation costs:Extended clinical evidence requirements for automated devices elevate entry barriers for mid-scale vendors.
- Legacy infrastructure incompatibility:Hospital pharmacies in secondary Indian and Indonesian cities operate manual workflows that resist modular retrofit.
Strategic Opportunities
- Vietnam and Philippines hospital buildouts:Greenfield medical infrastructure in Ho Chi Minh City and Manila bypasses legacy constraints entirely.
- AI-driven predictive inventory:Machine learning modules are converging with cloud-enabled dispensing cabinets to compress stockout incidents.
- CDSCO-NMPA harmonization:India's and China's convergence on software interoperability standards is opening cross-border certification pathways.
Industry Challenges
- Biomedical engineering talent scarcity:Maintenance of robotic dispensing systems requires hybrid skill sets spanning pharmacy operations and mechatronics.
- Integration complexity:Enterprise health record systems in Australian and Japanese hospitals demand custom middleware development for data exchange.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Pharmacy Automation Market |
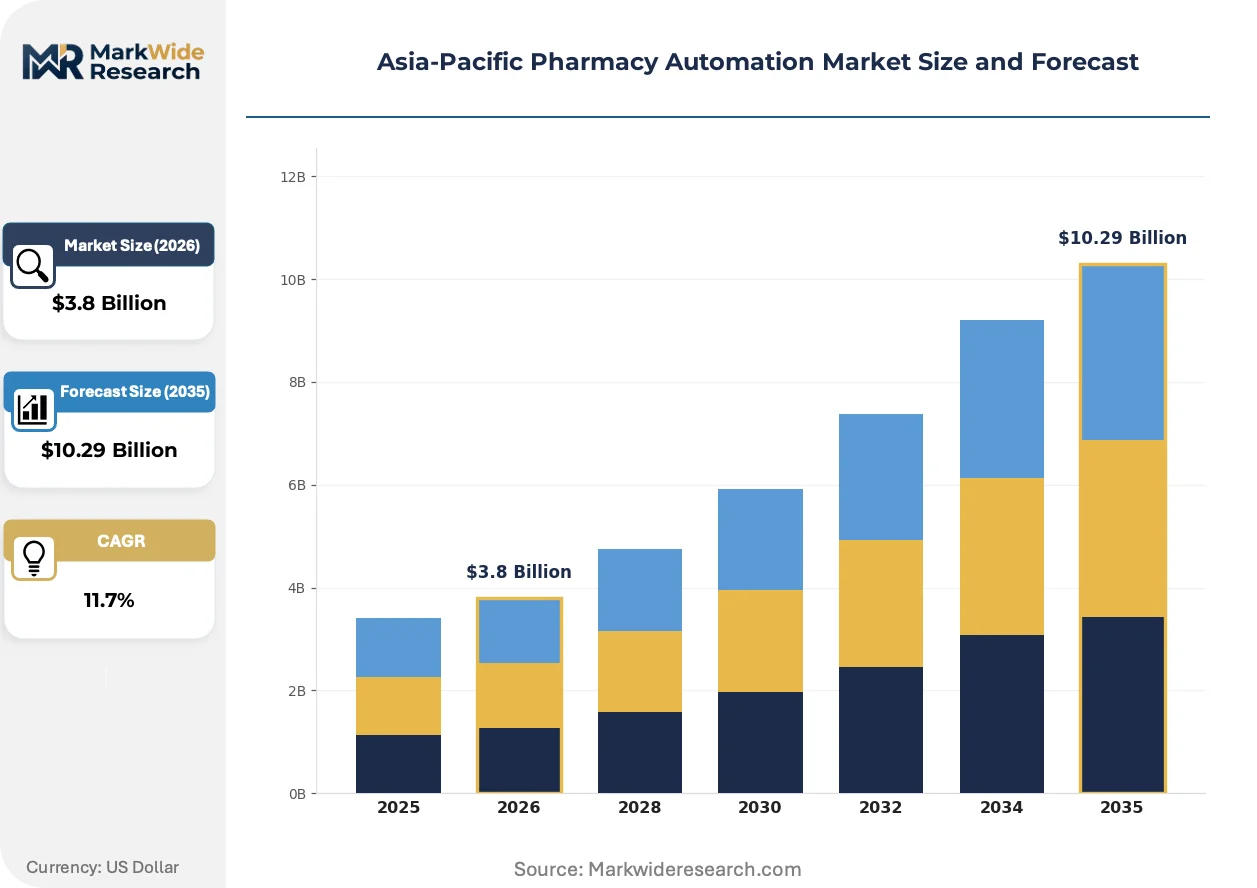
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Dispensing Systems, Automated Storage and Retrieval Systems, Middleware Solutions, Robotics End User: Hospitals, Retail Pharmacies, Long-term Care Facilities, Mail Order Pharmacies Technology: Barcode Verification, RFID Technology, Artificial Intelligence, Machine Learning Application: Inventory Management, Prescription Processing, Drug Compounding, Medication Delivery |
| Companies Covered | Swisslog Healthcare AG, ScriptPro LLC, Omnicell Inc, Parata Systems LLC, Capsa Healthcare, Becton Dickinson, ARxIUM, KUKA AG, McKesson Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Pharmacy Automation Market Emerging Trajectories
Automation architectures across Asia-Pacific pharmacy operations are fragmenting into interoperable subsystems rather than monolithic installations, enabling staged capital deployment and faster technology refresh cycles.
Robotic dispensing cells with standardized mechanical interfaces and swappable gripper assemblies are modularizing hospital pharmacy layouts across Japan and South Korea. Metropolitan medical centers in Seoul and Tokyo are adopting these configurations to reconfigure workflow zones without full system replacement. This modularity is compressing the traditional seven-to-ten-year capital replacement cycle into three-year capability upgrades.
PMDA's 2023 guidance on software-as-a-medical-device validation is forcing vendors to submit algorithmic transparency documentation for AI-enabled inventory prediction tools. Japanese hospital pharmacies must now maintain version-controlled audit trails for any automated dosing recommendation system. The regulation is accelerating demand for explainable AI modules that can output decision rationale in structured formats compatible with electronic health record systems.
Pharmacy directors in Australia's state hospital networks are unbundling after-sales service contracts from initial hardware procurement, selecting specialized third-party maintenance providers on three-year renewable terms. This disintermediation is displacing manufacturer-captive service agreements that previously bundled remote monitoring and on-site repair. Victorian and New South Wales health procurement frameworks now mandate competitive tendering for technical support separately from capital equipment acquisition.
Asia-Pacific Pharmacy Automation Market Segmentation
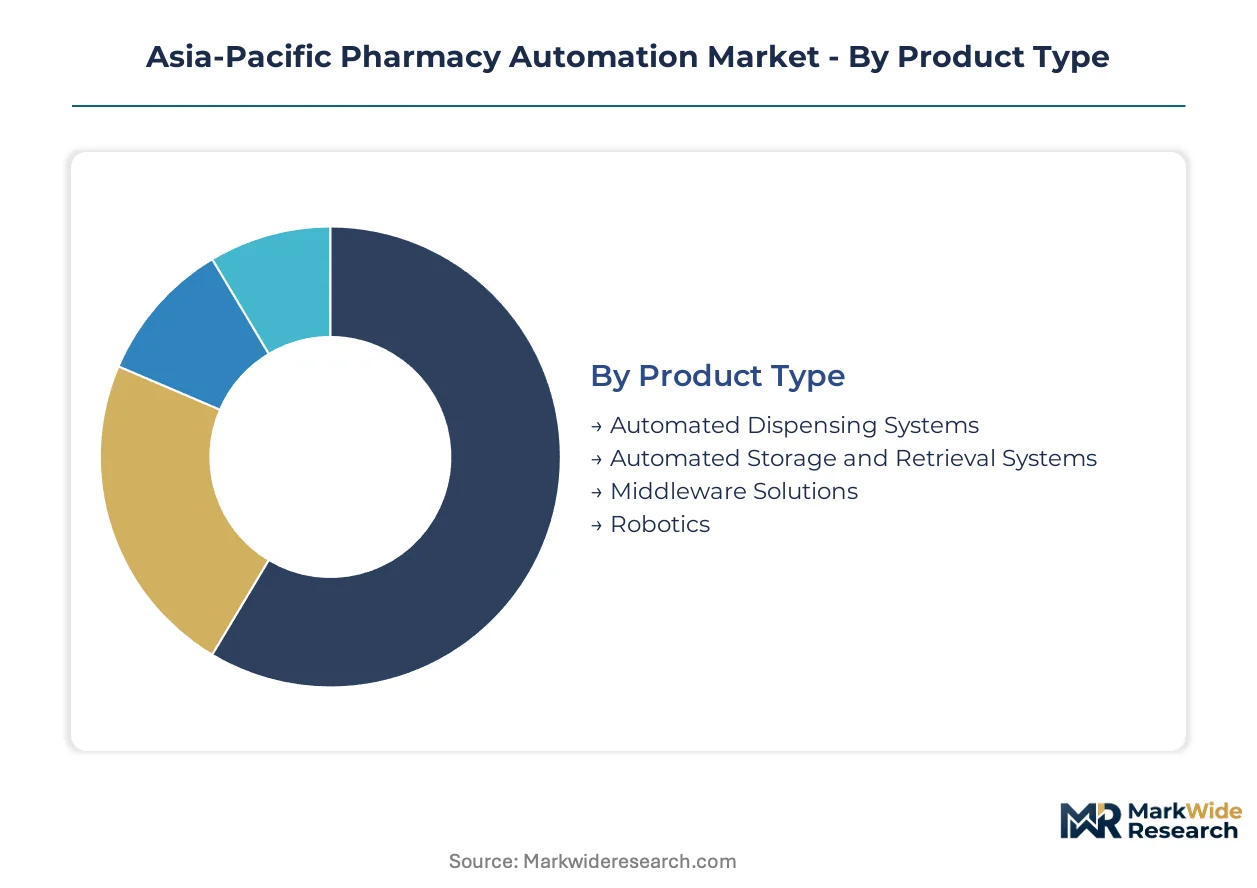
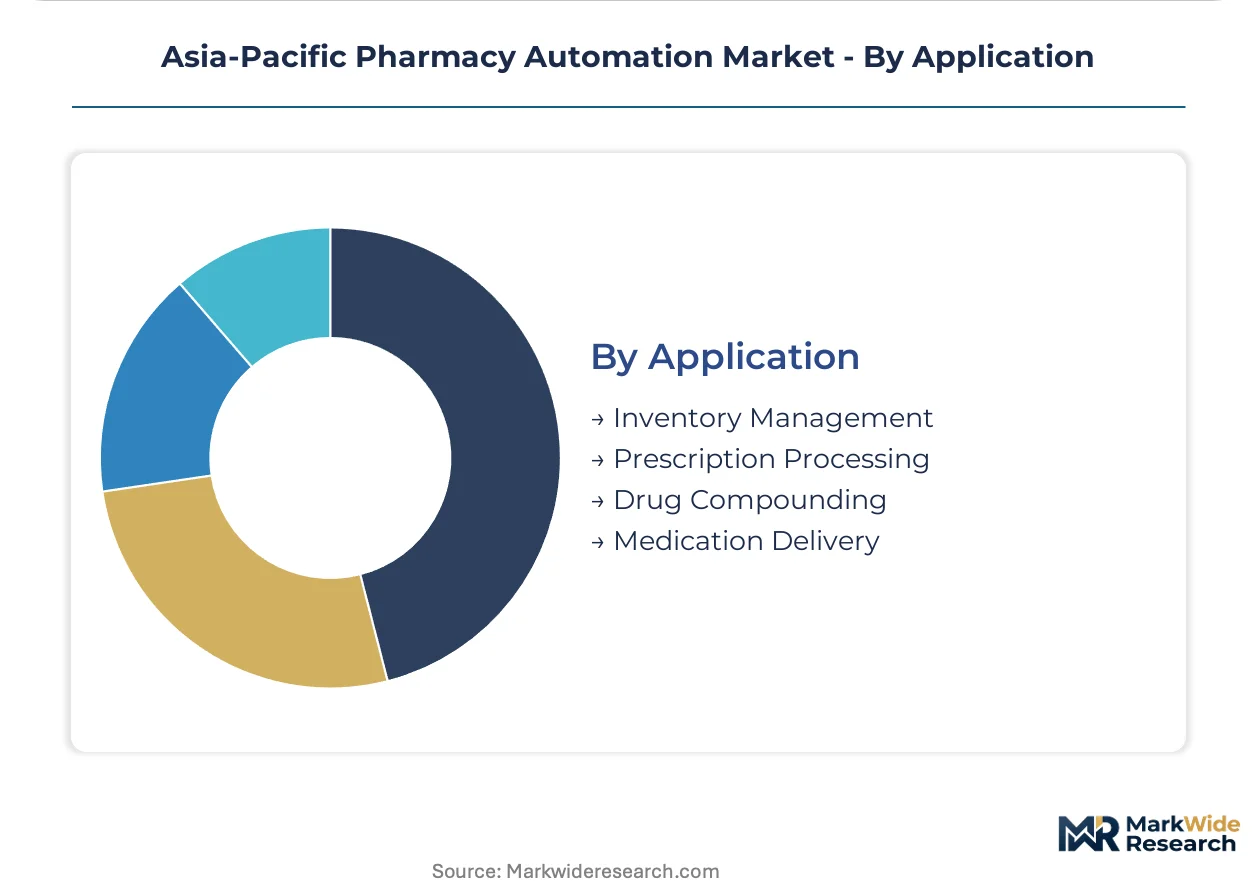
Segmentation reveals how automation investments fragment across hardware platforms, institutional settings, and intelligence layers. Procurement patterns diverge sharply between high-volume hospital networks seeking throughput gains and retail chains prioritizing labor substitution. Technology choices increasingly hinge on regulatory audit requirements rather than pure operational efficiency.
Product Type:
Servo motor and precision sensor supply concentrates in Japanese and South Korean manufacturing clusters, shaping which automation architectures achieve viable unit economics.
- Automated Dispensing Systems:Electromechanical cabinets with single-dose accuracy control medication release through barcode-verified workflows. Tokyo and Osaka metropolitan hospital networks deploy these in 24/7 operational cycles to manage dense patient throughput. PMDA validation protocols elevate compliance investment thresholds for cabinet vendors seeking Japanese market entry.
- Robotics:Robotic dispensing cells with standardized mechanical interfaces and swappable gripper assemblies modularize pharmacy layouts across Seoul and Tokyo medical centers. Isolator-based systems for sterile compounding attract disproportionate capital as oncology and biologic therapy volumes multiply across Asia-Pacific hospital networks.
- Automated Storage and Retrieval Systems:Vertical lift modules and carousel-based architectures optimize floor-to-ceiling pharmaceutical density in space-constrained urban facilities.
- Middleware Solutions:Cloud-enabled inventory platforms bridge enterprise health record systems with dispensing hardware, requiring custom development for Australian and Japanese hospital data exchange protocols.
Automated dispensing systems absorb the bulk of installed capacity; robotics is expanding most quickly.
End User:
Customer procurement authority fragments across public health procurement frameworks, private hospital groups, and retail pharmacy chains with diverging capital cycles.
- Hospitals:Inpatient pharmacy operations demand highest-throughput automation with full audit-trail capabilities for medication safety compliance. Australia's state hospital networks unbundle after-sales service contracts from hardware procurement, mandating competitive tendering for technical support separately from capital equipment acquisition.
- Retail Pharmacies:Community pharmacy chains prioritize compact footprint automation that substitutes for pharmacist labor in prescription verification and labeling workflows.
- Long-term Care Facilities:Medication adherence packaging and multi-dose blister automation address polypharmacy management in aged care settings.
- Mail Order Pharmacies:Centralized fulfillment centers serving regional populations require high-volume sortation and verification systems with postal integration.
Hospitals command the dominant share of automation capital; retail pharmacies are gaining share fastest as labor costs climb.
Technology:
Algorithmic transparency requirements from PMDA's software-as-a-medical-device guidance reshape R&D allocation toward explainable decision systems.
- Artificial Intelligence:Predictive inventory optimization modules compress stockout incidents through demand forecasting algorithms. PMDA's validation protocols force vendors to submit algorithmic transparency documentation, accelerating demand for AI systems that output decision rationale in structured formats compatible with electronic health record systems.
- Machine Learning:Continuous improvement loops refine dispensing accuracy through pattern recognition in medication error datasets.
- Barcode Verification:Linear and 2D symbology scanning remains the foundational medication identification layer across all automation tiers.
- RFID Technology:Item-level pharmaceutical tracking enables real-time inventory visibility without line-of-sight scanning constraints.
Barcode verification underpins the majority of deployed systems; artificial intelligence is climbing the fastest as cloud infrastructure matures.
Application:
Workflow automation priorities diverge between inventory-centric operations and patient-facing medication administration processes.
- Inventory Management:Automated replenishment triggers and par-level optimization reduce pharmacist time spent on stock monitoring. AI-driven modules converging with cloud-enabled dispensing cabinets compress stockout incidents across Australian and Japanese hospital networks.
- Drug Compounding:Robotic sterile compounding addresses hazardous drug preparation with isolator-based precision for oncology and biologic therapies.
- Prescription Processing:Order intake, verification, and label generation automation accelerates throughput in high-volume retail and mail order settings.
- Medication Delivery:Pneumatic tube systems and autonomous mobile robots transport pharmaceuticals from pharmacy to nursing units.
Inventory management captures the largest automation footprint; drug compounding is gaining share fastest as biologic therapy volumes expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Component manufacturing clusters in Japan and South Korea supply precision hardware, while hospital networks in Australia and metropolitan India absorb the bulk of system deployments. This production-consumption split shapes procurement lead times and vendor certification priorities across the region.
Japan
Tokyo and Osaka hospital corridors operate robotic dispensing cells in continuous 24/7 cycles to manage dense inpatient throughput. PMDA validation protocols for automated medication devices compress vendor certification timelines while elevating compliance investment thresholds. Kanto and Kansai medical centers modularize pharmacy layouts with swappable gripper assemblies that enable three-year capability upgrades.
Australia
State hospital networks in Victoria and New South Wales unbundle after-sales service contracts from hardware procurement, mandating competitive tendering for technical support. TGA medication safety mandates rebalance procurement priorities toward error-reduction technologies with audit-trail capabilities. Sydney and Melbourne metropolitan facilities anchor cloud-enabled inventory platform adoption.
China
NMPA convergence toward international software interoperability standards reshapes vendor certification requirements for pharmacy automation systems. Yangtze River Delta hospital networks demand AI-driven predictive inventory modules that compress stockout incidents. Shanghai medical centers pilot explainable AI systems compatible with electronic health record protocols.
India
CDSCO harmonization with international standards opens cross-border certification pathways for middleware and robotic dispensing vendors. Maharashtra and Karnataka hospital buildouts in Mumbai and Bangalore bypass legacy infrastructure constraints through greenfield automation deployment. Secondary cities in Gujarat and Tamil Nadu resist modular retrofit due to entrenched manual workflows.
South Korea
Seoul Capital Area medical centers adopt standardized mechanical interfaces for robotic dispensing cells that reconfigure workflow zones without full system replacement. MFDS validation requirements align with PMDA protocols, streamlining certification for Japanese-origin hardware. Busan-Ulsan manufacturing clusters supply servo motors and precision sensors to regional automation vendors.
Asia-Pacific Pharmacy Automation Market Vendor Landscape
The competitive structure tilts toward integrated medication management ecosystems spanning storage through administration. Vendor positioning fragments across three tiers: cloud-enabled inventory platforms, robotic dispensing architectures for high-volume hospital settings, and modular middleware specialists. Consolidation pressure concentrates among mid-scale vendors facing PMDA validation cost barriers. Dominant competitive moves include strategic partnerships for regulatory certification acceleration and geographic expansion into Vietnam and Philippines greenfield hospital buildouts.
Among Switzerland and Germany-based automation architects, Swisslog Healthcare AG and KUKA AG occupy positions emphasizing robotic dispensing precision for sterile compounding applications. Omnicell Inc anchors the cloud-enabled inventory tier, while Becton Dickinson exemplifies integrated ecosystem providers spanning enterprise medication management. These three represent distinct strategic archetypes: hardware-centric robotics, software-centric inventory optimization, and full-stack integration.
| Leading Market Players |
|---|
| Swisslog Healthcare AG |
| ScriptPro LLC |
| Omnicell Inc |
| Parata Systems LLC |
| Capsa Healthcare |
| Becton Dickinson |
| ARxIUM |
| KUKA AG |
| McKesson Corporation |
| Others |
Supply Flow & Price Mechanics
Neodymium and servo motor price indices cascade through automation hardware tiers, compressing margins for mid-scale cabinet vendors while amplifying pricing power for Japanese and South Korean manufacturers with captive component supply. PMDA validation costs further stratify procurement tiers, separating audit-capable suppliers from price-competitive challengers.
Pricing Analysis
Uptime-guarantee contracts anchor value-based pricing for robotic dispensing cells in Tokyo and Osaka hospital networks, where 24/7 operational continuity commands premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates PMDA-validated systems from CDSCO-registered alternatives and unbundled hardware-only configurations. Pricing pressure stems from Australian state procurement frameworks mandating competitive tendering for technical support separately from capital acquisition. Retail pharmacy chains exhibit highest price sensitivity due to labor-substitution ROI calculations, while metropolitan hospital networks prioritize total cost of ownership over upfront capital outlay.
Supply Chain Analysis
Direct-to-hospital channels handle hyperscale demand from Japan's Kanto and Kansai medical corridors, while distributor networks serve secondary Indian and Indonesian cities with modular retrofit solutions. Component manufacturing concentrates in Japan, South Korea, and China's Yangtze River Delta, with servo motors, precision sensors, and robotic grippers drawing from these clusters. Single-source vulnerability runs through Japanese semiconductor foundries supplying motor control chipsets. Distribution runs through authorized service partners in Australia and specialized biomedical engineering contractors across Southeast Asian greenfield hospital buildouts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-enabled inventory platforms are displacing on-premise dispensing cabinets across Asia-Pacific hospital networks, compressing the technology refresh cycle from seven years to three and redefing vendor competitive moats.
For Market Incumbents: Anticipate margin compression in hardware-only segments as Australian procurement frameworks unbundle service contracts and Chinese NMPA harmonization invites new certification pathways. Defensive consolidation into AI-driven predictive inventory modules and sterile compounding robotics preserves positioning. Backward integration into servo motor supply secures cost advantage against South Korean manufacturing clusters. For New Entrants and Emerging Players: Secondary Indian cities with entrenched manual workflows represent the most penetrable buyer archetype for modular dispensing cabinets with staged capital deployment. Vietnam and Philippines greenfield hospital buildouts bypass legacy infrastructure constraints entirely. CDSCO-NMPA harmonization opens cross-border certification efficiency for middleware specialists targeting multi-hospital network rollouts. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale vendors facing PMDA validation cost barriers in Japan and Australia, where compliance investment thresholds have outrun capital access. Long-term viability hinges on software-as-a-medical-device revenue streams with recurring licensing models. Watch for MFDS-PMDA regulatory alignment as inflection signal for Korean-origin hardware acquisition appetite.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Certification Acceleration | Reduces vendor entry timelines for Tokyo and Osaka metropolitan hospital networks. |
| AI Companion Development | Explainable inventory prediction modules satisfy PMDA algorithmic transparency mandates. |
| Hospital System Partnership | Victorian and New South Wales frameworks mandate competitive tendering for technical support. |
| Backward Integration | Captive servo motor production insulates Japanese vendors from Korean supply volatility. |
| Geographic Expansion | Ho Chi Minh City and Manila greenfield buildouts bypass legacy retrofit constraints. |
Methodological Framework
Multi-period observation of PMDA validation timelines, CDSCO-NMPA harmonization progress, and Australian state procurement framework changes anchored the trend analysis, supplemented by interviews with hospital pharmacy directors, biomedical engineering maintenance contractors, GPO contracts managers, and robotic dispensing system vendors. Secondary validation drew from TGA medication safety guidance documents, PMDA software-as-a-medical-device notifications, MFDS regulatory alignment bulletins, and hospital procurement database disclosures. Bottom-up installation tracking across Tokyo, Osaka, Sydney, Melbourne, Shanghai, Mumbai, and Bangalore facilities triangulated against top-down vendor revenue segmentation.
Input-output matrices mapped hardware unit shipments to software licensing attach rates across automated dispensing systems, robotics, storage and retrieval systems, and middleware solutions. Segmentation dimensions spanned product architecture, end-user institution type, intelligence layer technology, and application workflow. CAGRs were derived from curve-fitting observed adoption velocities against regulatory milestone schedules. Forecast inputs included oncology therapy volume trajectories and biologic compounding demand curves.
Revisions become necessary when PMDA validation protocols tighten algorithmic evidence requirements, when CDSCO-NMPA harmonization stalls, or when servo motor supply clusters face disruption. Forecasts reflect documented assumptions about regulatory convergence timelines and hospital capital cycle phasing. Periodic stress-testing of base assumptions against biomedical engineering talent availability and middleware integration complexity is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Interlock Vials Market
Pharmaceutical Equipment
Global Depyrogenated Sterile Empty Vials Market
Pharmaceutical Equipment
Serum Vials Market
Pharmaceutical Equipment
Drug Infusion System Market
Pharmaceutical Equipment
Depyrogenation Oven Market
Pharmaceutical Equipment
Pharmaceutical Track and Trace Systems Market
Pharmaceutical Equipment
Pharmaceutical Equipment Market
Pharmaceutical Equipment
Middle East and Africa Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Radiochemical Synthesizers Market
Pharmaceutical Equipment
Pharmaceutical Stability and Storage Services Market
Pharmaceutical Equipment
US Depyrogenated Sterile Empty Vials Market
Pharmaceutical Equipment
Pharmaceutical Hot Melt Extrusion Equipment Market
Pharmaceutical Equipment
mRNA Vaccine Formulation Stability and Stress Test Systems Market
Pharmaceutical Equipment
Pharmerging Contract Manufacturing Market
Pharmaceutical Equipment
North America Pharmacy Automation Market
Pharmaceutical Equipment
Pharmaceutical Manufacturing Market