
 Sterile Vials Market | 2026-2036
Sterile Vials Market Size, Share, and Industry Trends Forecast 2026-2036
Sterile Vials Market Analysis
Aftermarket service revenue for sterile vial inspection and qualification is reconfiguring how suppliers capture lifetime value from pharmaceutical customers. SCHOTT AG leverages its borosilicate glass expertise to dominate high-value vaccine vial contracts. Gerresheimer AG sustains competitive position through integrated manufacturing from tubing to finished sterile containers. West Pharmaceutical Services anchors North American supply chains with its proprietary elastomeric closure systems paired with vial platforms.
Sterile vials are sealed, depyrogenated containers manufactured from borosilicate glass or cyclic olefin polymer, designed to maintain sterility and chemical inertness for parenteral drug storage. These containers undergo gamma irradiation or steam sterilization and must demonstrate container closure integrity below 10 micron leak rates to comply with pharmacopeial standards. Glass vials retain the largest volume share due to proven chemical stability, though plastic vials are gaining fastest in biologics applications requiring break resistance. Pre-filled vials command premium positioning as pharmaceutical companies outsource fill-finish complexity to specialized suppliers.
FDA enforces strict container closure integrity testing under USP 1207, while EMA mandates compliance with EU GMP Annex 1 for sterile manufacturing environments. ISO 15378 governs primary packaging materials for medicinal products, creating a harmonized baseline that reduces regulatory friction for multinational suppliers. Stakeholders must monitor how USP and EP revisions on visible particulate limits reshape vial inspection technology investments and supplier qualification timelines.
Market Dynamics
Biopharmaceutical fill-finish outsourcing is compressing supplier qualification timelines while FDA and EMA tighten container closure integrity standards, forcing vial manufacturers to absorb validation costs upstream.
Growth Catalysts
- EMA Annex 1 Revision:The 2022 update to EU GMP Annex 1 mandates stricter sterile manufacturing environments, accelerating pharmaceutical demand for pre-sterilized, ready-to-use vial formats that eliminate in-house depyrogenation.
- Cell and Gene Therapy Expansion:Advanced therapy medicinal products require specialized cyclic olefin polymer vials with break resistance and low extractables, pulling material innovation from glass-dominated portfolios.
- Germany:The country's concentration of mRNA manufacturing facilities creates localized demand spikes for borosilicate glass vials with proven chemical stability in ultra-cold chain storage.
Market Restraints
- Borosilicate Glass Feedstock Concentration:Tubing supply concentrates among three European and Asian suppliers, exposing vial manufacturers to price volatility and allocation constraints during demand surges.
- USP 1207 Validation Burden:FDA enforcement of probabilistic container closure integrity testing methods extends qualification timelines by 8-14 months for new vial formats, delaying revenue recognition.
- Pre-filled Syringe Substitution:Biologics developers increasingly bypass vials entirely for patient-administered therapies, constraining addressable market expansion in chronic disease segments.
Strategic Opportunities
- India:CDSCO's streamlined medical device regulations and domestic PLI scheme incentives create entry pathways for sterile vial suppliers serving the country's expanding biologics manufacturing base.
- Dual-Chamber Vial Convergence:Integration of lyophilized drug and diluent compartments addresses reconstitution complexity, opening premium positioning in emergency medicine and field-deployed therapeutics.
- Aftermarket Inspection Services:Pharmaceutical outsourcing of vial qualification and container closure integrity testing creates recurring revenue streams detached from unit volume cycles.
Industry Challenges
- Visual Inspection Automation Talent Gap:Pharmaceutical manufacturers lack sufficient personnel trained in machine vision algorithm validation for particulate detection, forcing reliance on semi-automated hybrid systems.
- ISO 15378 Certification Timeline:Primary packaging material certification requires 18-24 months of quality system documentation and auditor rotation, blocking market entry for new suppliers.
- Legacy Fill-Finish Integration:Established pharmaceutical facilities operate isolator lines designed for traditional glass vial dimensions, creating retrofit costs for novel polymer formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sterile Vials Market |
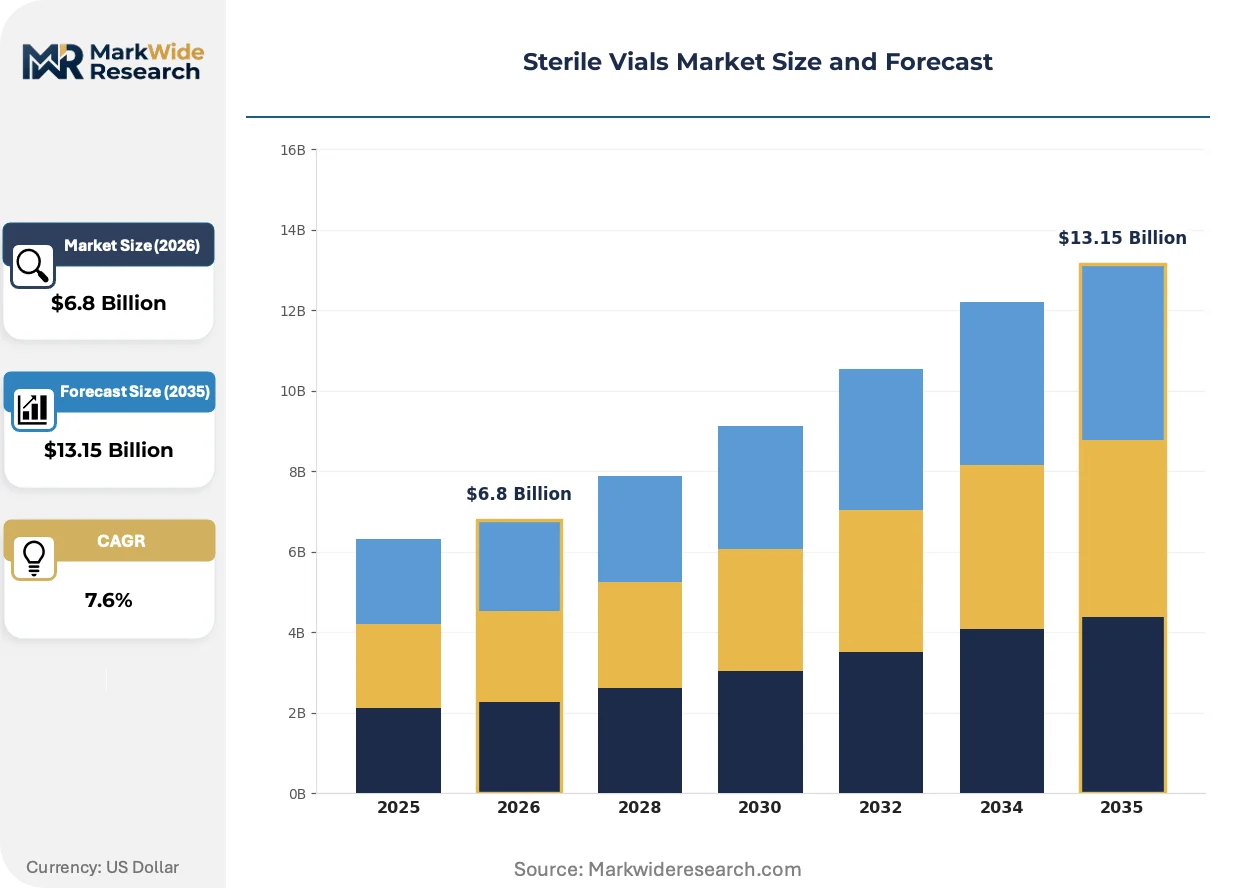
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass Vials, Plastic Vials, Pre-filled Vials, Multi-dose Vials End User: Pharmaceutical Companies, Hospitals, Research Laboratories, Contract Manufacturing Organizations Application: Vaccines, Injectable Medications, Biologicals, Diagnostics Capacity: 1 mL, 5 mL, 10 mL, 20 mL |
| Companies Covered | Nipro Corporation, SGD Pharma, SCHOTT AG, DWK Life Sciences GmbH, West Pharmaceutical Services, Inc., Gerresheimer AG, Corning Incorporated, Bormioli Pharma S.p.A., Stevanato Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sterile Vials Market Emerging Trajectories
Machine vision and artificial intelligence are compressing inspection cycle times while regulatory convergence on visible particulate standards forces harmonization of quality thresholds across manufacturing geographies.
Spectral imaging combined with deep learning algorithms is digitizing vial defect detection. Contract manufacturing organizations in the United States and Germany are deploying these systems at line speeds exceeding 600 units per minute. The technology is digitizing quality assurance workflows, compressing batch release timelines from days to hours while reducing false rejection rates.
REACH regulation amendments targeting extractables and leachables from pharmaceutical contact materials are reshaping material selection protocols. European vial manufacturers must now submit comprehensive chemical characterization data for cyclic olefin polymers. Biologics applications face the steepest compliance burden, driving substitution toward pre-validated polymer grades with established toxicological profiles.
Pharmaceutical procurement teams are consolidating supplier panels from twelve-plus vendors to three-to-four strategic partners. Large molecule drug developers in China and the United States now require vertically integrated vial-to-closure compatibility guarantees. This concentration is visible most acutely in vaccine manufacturing, where single-source qualification for pandemic response stockpiles has become a contractual requirement.
Sterile Vials Market Segmentation
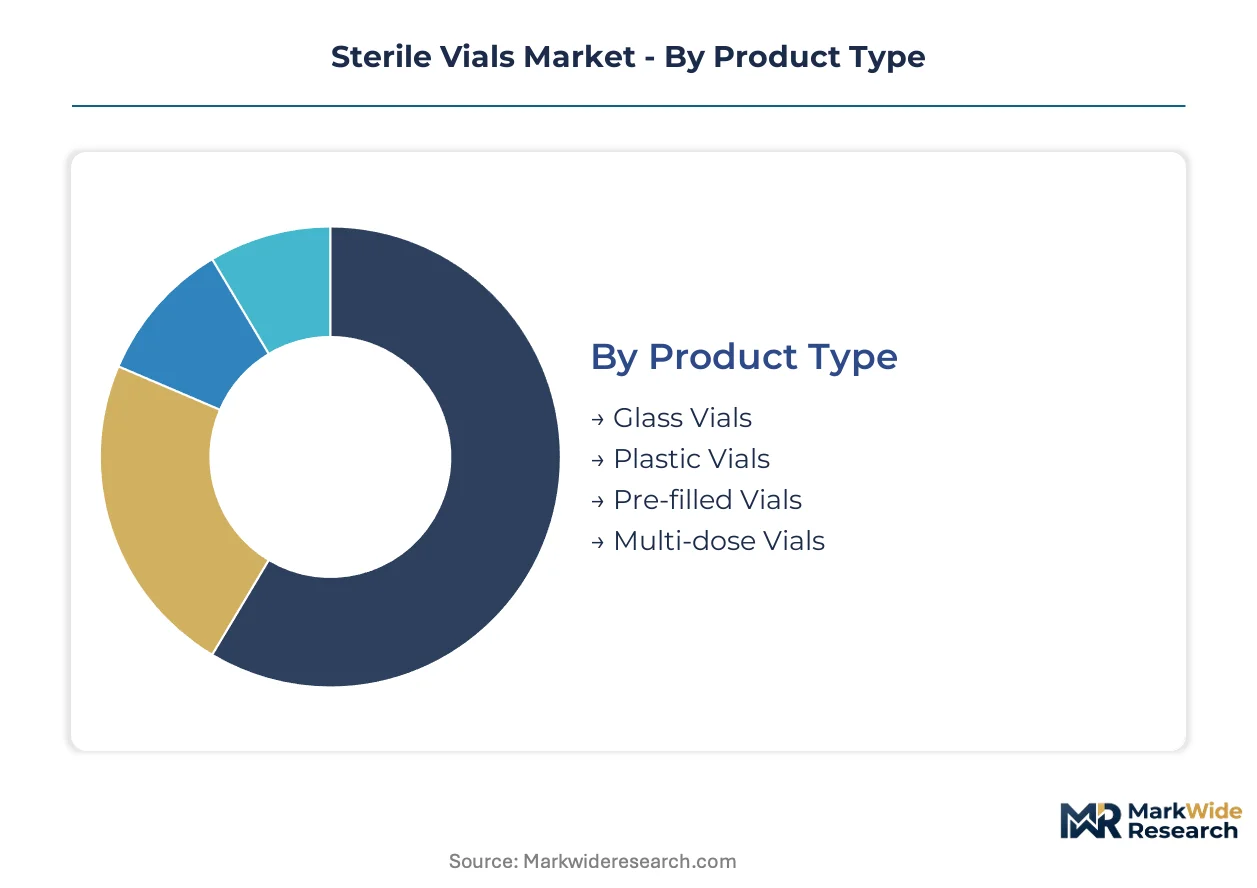
Sterile vial segmentation reveals how material science, end-use requirements, and fill-finish automation are fragmenting supplier portfolios. Pharmaceutical procurement teams now qualify vial formats against specific drug stability profiles and cold chain specifications rather than selecting generic containers.
Product Type:
Material composition dictates chemical compatibility, break resistance, and regulatory validation burden across fill-finish operations.
- Glass Vials:Borosilicate construction delivers proven chemical inertness and thermal shock resistance for parenteral drugs. Demand concentrates in Germany and the United States where mRNA vaccine manufacturing requires ultra-cold chain stability down to minus 80 degrees Celsius.
- Pre-filled Vials:Drug product integration at the point of manufacture eliminates compounding errors and reduces preparation time in clinical settings. Pharmaceutical companies in China are accelerating adoption to compress time-to-market for biosimilar launches.
- Plastic Vials:Cyclic olefin polymer grades offer break resistance for cell and gene therapies requiring flexible supply chains.
- Multi-dose Vials:Preservative-compatible formats reduce per-dose packaging costs for high-volume immunization programs.
Glass vials hold installed capacity. Pre-filled vials are rotating up the share rankings.
End User:
Customer type determines order scale, qualification rigor, and aftermarket service attachment rates.
- Pharmaceutical Companies:Large molecule developers demand vertically integrated vial-to-closure compatibility guarantees and single-source pandemic stockpile contracts. FDA container closure integrity enforcement extends their qualification timelines substantially.
- Contract Manufacturing Organizations:Fill-finish specialists require rapid format switching capabilities to serve multiple drug sponsors from shared isolator lines. CMOs in the United States are deploying spectral imaging inspection systems to compress batch release cycles.
- Hospitals:Health systems prioritize ready-to-use formats that eliminate in-house sterilization infrastructure.
- Research Laboratories:Small-batch requirements favor flexible minimum order quantities and rapid prototyping services.
Pharmaceutical companies command volume concentration. Contract manufacturing organizations are climbing the fastest in procurement influence.
Application:
Therapeutic category shapes material selection, extractables testing depth, and cold chain complexity.
- Vaccines:Temperature-sensitive formulations require borosilicate stability across extended frozen storage periods. German manufacturing clusters anchor demand for pandemic response stockpiles with proven ultra-cold performance.
- Biologicals:Protein-based therapeutics face the steepest ECHA extractables compliance burden under REACH amendments, driving substitution toward pre-validated polymer grades with established toxicological profiles.
- Injectable Medications:Generic sterile drugs compete on unit cost, favoring high-speed glass vial formats.
- Diagnostics:Reagent vials prioritize optical clarity and dimensional precision for automated analyzer compatibility.
Vaccines retain the largest committed capacity. Biologicals are gaining share fastest on cell and gene therapy expansion.
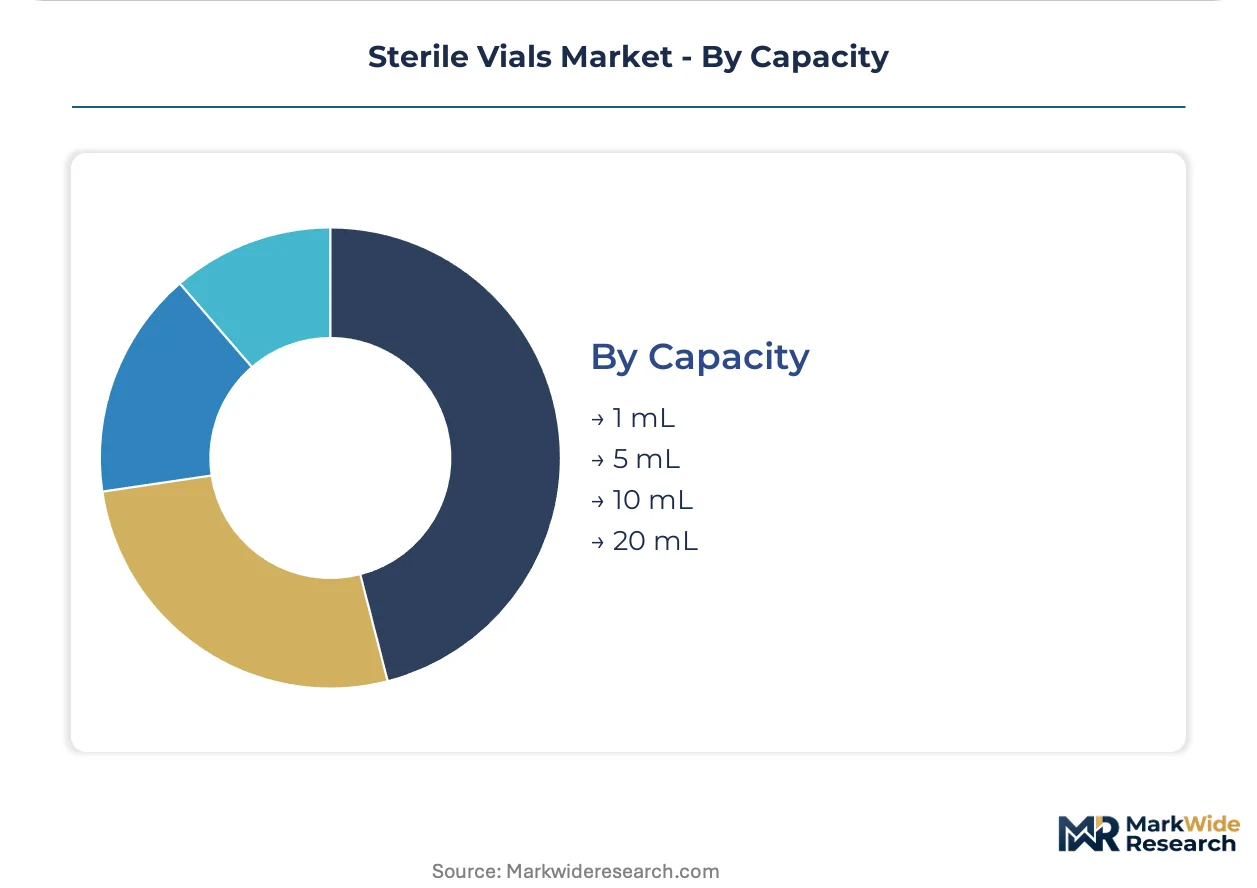
Capacity:
Volume specification determines line speed economics, inspection cycle times, and logistics cube efficiency.
- 10 mL:The workhorse format for biologics and vaccines balances drug product volume with handling ergonomics. Chinese biologics manufacturers are standardizing on this capacity to streamline isolator line configurations.
- 1 mL:Pediatric and precision-dose applications require specialized fill accuracy and minimal dead volume design. Demand is expanding in the United States for ophthalmic and emergency medicine formulations.
- 5 mL:Mid-range capacity serves diagnostic reagents and combination therapies with moderate volume requirements.
- 20 mL:Large-volume parenteral nutrition and contrast media applications require reinforced sidewall construction.
10 mL formats dominate committed manufacturing lines. 1 mL specifications are expanding most quickly on precision therapy trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between mature pharmaceutical manufacturing clusters and emerging biologics hubs. The United States and Germany prioritize ultra-cold chain stability for mRNA applications, while China and India concentrate on cost-optimized formats for biosimilar volume production.
United States
mRNA vaccine manufacturing expansion and cell therapy commercialization drive specialized cyclic olefin polymer demand. FDA enforcement of USP 1207 container closure integrity testing extends supplier qualification timelines. The Boston-Cambridge biotech corridor anchors demand for pre-filled vial formats that eliminate compounding errors in clinical settings.
Germany
Concentrated mRNA production facilities and legacy biologics manufacturing sustain borosilicate glass volume leadership. EMA Annex 1 revision mandates accelerate pharmaceutical migration toward ready-to-use sterile formats. The Rhine-Main region hosts specialized tubing conversion capacity serving pandemic response stockpile contracts.
China
Biosimilar launch acceleration and domestic biologics manufacturing scale-up compress time-to-market requirements. NMPA streamlined medical device registration pathways enable faster sterile vial supplier qualification. The Yangtze River Delta biopharma cluster standardizes on 10 mL formats to streamline isolator line configurations across contract manufacturing organizations.
India
Domestic biologics manufacturing expansion and export-oriented vaccine production create dual demand streams. CDSCO's PLI scheme incentives and streamlined medical device regulations attract sterile vial supplier investment. The Hyderabad-Bengaluru pharmaceutical corridor concentrates fill-finish outsourcing demand from multinational drug sponsors.
Japan
Precision-dose biologics and ophthalmic formulations sustain demand for specialized 1 mL capacity formats. PMDA quality standards for primary packaging materials enforce rigorous extractables testing protocols. The Kansai region maintains specialized glass conversion capacity serving domestic and Asia-Pacific export markets.
Sterile Vials Market Vendor Landscape
Capability concentration sits with integrated glass-to-finish specialists; scale advantage sits with diversified packaging conglomerates. The market structures around three tiers: borosilicate tubing converters with captive pharmaceutical relationships, polymer format innovators serving cell therapy applications, and regional fabricators competing on minimum order flexibility. Dominant competitive moves include backward integration into tubing supply and strategic partnerships with fill-finish contract manufacturing organizations.
Among German-headquartered specialists, SCHOTT AG and Gerresheimer AG occupy positions reflecting deep borosilicate expertise and integrated manufacturing architectures. West Pharmaceutical Services, Inc. anchors North American supply chain security through proprietary closure system integration. These three exemplify divergent strategic postures: tubing-to-vial vertical control, pharmaceutical outsourcing partnership depth, and elastomeric compatibility platform dominance.
| Leading Market Players |
|---|
| Nipro Corporation |
| SGD Pharma |
| SCHOTT AG |
| DWK Life Sciences GmbH |
| West Pharmaceutical Services, Inc. |
| Gerresheimer AG |
| Corning Incorporated |
| Bormioli Pharma S.p.A. |
| Stevanato Group |
| Others |
Supply Flow & Price Mechanics
Single-source borosilicate glass tubing dependency from European and Asian suppliers compresses pricing power for downstream converters while simultaneously forcing tiered spreads between validated pharmaceutical-grade formats and commodity diagnostic containers. This feedstock chokepoint amplifies cost volatility during demand surges and rewards manufacturers with captive supply arrangements or long-term offtake contracts with pandemic stockpile customers.
Pricing Analysis
Long-term offtake agreements with pharmaceutical companies anchor pricing stability for high-volume vaccine contracts, while spot procurement for research-grade batches captures premium spreads. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated formats with full extractables documentation from unvalidated diagnostic grades. Cost compression in standard-tier glass vials is intensifying because Chinese biosimilar manufacturers consolidate supplier panels and demand volume discounts. Contract manufacturing organizations exhibit the sharpest price sensitivity due to margin pressure from drug sponsors, whereas mRNA vaccine developers prioritize supply security over unit cost.
Supply Chain Analysis
Borosilicate glass tubing production draws from Germany, China, and Japan, with specialized conversion capacity concentrated in the Rhine-Main region and the Yangtze River Delta. Raw material dependencies center on high-purity silica sand, boron oxide, and alumina for thermal shock resistance, plus elastomeric compounds for closure systems. Single-source vulnerability in pharmaceutical-grade tubing supply exposes converters to allocation constraints during pandemic demand spikes. Distribution runs through direct pharmaceutical procurement channels for validated formats and medical device distributors for research and diagnostic segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pre-filled syringe substitution in patient-administered biologics threatens vial volume expansion, forcing incumbents to defend position through format innovation and fill-finish outsourcing partnerships that embed containers irreversibly into drug product supply chains.
For Market Incumbents: Build regulatory validation moats by accelerating ISO 15378 certification for polymer formats ahead of REACH extractables enforcement. Backward integration into borosilicate tubing supply secures allocation priority during demand surges. Dual-chamber vial development for lyophilized emergency medicines creates sticky relationships with pharmaceutical customers facing reconstitution complexity.
For New Entrants and Emerging Players: India's CDSCO streamlined pathways and PLI scheme incentives offer the most penetrable entry corridor for sterile vial suppliers serving domestic biologics manufacturing. Cyclic olefin polymer formats for cell and gene therapy applications face less entrenched incumbent control than glass-dominated vaccine segments. Partnership with fill-finish contract manufacturing organizations in Hyderabad-Bengaluru provides rapid qualification acceleration without direct pharmaceutical salesforce investment.
For Investors and Strategic Acquirers: EMA Annex 1 revision reshapes the acquisition landscape by elevating ready-to-use sterile format capabilities above traditional glass conversion assets. Five-to-ten-year viability favors suppliers with polymer innovation pipelines and aftermarket inspection service revenue streams detached from unit volume cycles. Target acquisition profile: mid-cap specialists with captive tubing relationships or validated polymer grades. The signal to watch is FDA enforcement intensity on USP 1207 probabilistic testing methods, which extends qualification timelines and entrenches incumbent positions.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tubing Supply | Captive borosilicate feedstock secures allocation priority during pandemic demand surges against constrained European and Asian suppliers. |
| Polymer Format Innovation | Cyclic olefin polymer vials with low extractables profiles capture cell and gene therapy growth beyond glass-dominated portfolios. |
| Aftermarket Inspection Services | Recurring revenue from container closure integrity testing reduces dependence on cyclical vial unit volume demand. |
| Dual-Chamber Vial Development | Integrated lyophilized drug and diluent compartments address emergency medicine reconstitution complexity for premium positioning. |
| Strategic CMO Partnership | Fill-finish outsourcing alliances embed vial formats irreversibly into drug product supply chains, raising switching costs. |
Methodological Framework
Cross-validation between primary interviews with fill-finish operations directors, regulatory affairs leads at sterile drug manufacturers, pharmaceutical procurement managers, and container closure integrity testing specialists anchors the qualitative findings. Secondary validation draws from FDA 483 inspection observations, EMA GMP inspection reports, ISO 15378 certification databases, and USP revision documentation. Bottom-up demand modeling from drug sponsor vial qualification pipelines and top-down supply assessment from tubing manufacturer capacity disclosures complete the triangulation.
Calibration against historical qualification timeline data and pandemic demand shock responses shapes the analytical framework across the projection horizon. Segmentation dimensions include material composition, therapeutic application, end-user type, and regional regulatory cluster. CAGRs derive from installed fill-finish capacity expansion plans and biologics pipeline conversion rates. Industry-specific forecast inputs incorporate EMA Annex 1 migration timelines and REACH extractables compliance burden trajectories.
Practitioners should monitor USP and EP visible particulate limit revisions, borosilicate tubing allocation announcements, and pre-filled syringe substitution rates in chronic disease segments for early signals. Forecasts reflect assumptions on regulatory enforcement intensity and polymer validation acceleration that could shift materially. Cross-checking against pharmaceutical capital expenditure disclosures and contract manufacturing organization capacity announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Investigational New Drug CDMO Market
Pharmaceutical Equipment
Prefilled Formalin Vials Market
Pharmaceutical Equipment
Pharmaceutical Continuous Manufacturing Market
Pharmaceutical Equipment
Inhalation CDMO Market
Pharmaceutical Equipment
Pharmaceutical Hot Melt Extrusion Equipment Market
Pharmaceutical Equipment
Pharmaceutical Processing Equipment Market
Pharmaceutical Equipment
Pharmaceutical CDMO Market
Pharmaceutical Equipment
India Contract Manufacturing Organization (CMO) Market
Pharmaceutical Equipment
Pharmaceutical Cleaning Validation Market
Pharmaceutical Equipment
Pharmaceutical Anti-Counterfeiting Technologies Market
Pharmaceutical Equipment
Pharmaceutical Incubators Market
Pharmaceutical Equipment
mRNA Vaccine Formulation Stability and Stress Test Systems Market
Pharmaceutical Equipment
Global Rotary Tablet Press Market
Pharmaceutical Equipment
Sterile Fill-Finish Process Simulation and Media Fill Test Equipment Market
Pharmaceutical Equipment
Aseptic Negative Pressure Pharmaceutical Isolators Market
Pharmaceutical Equipment
Interlock Vials Market