
 Global Rotary Tablet Press Market | 2026-2036
Global Rotary Tablet Press Market Size, Share, and Industry Trends Forecast 2026-2036
Global Rotary Tablet Press Market Foresight
The capital-intensity divergence between single-punch legacy operators and high-speed rotary specialists is collapsing as mid-tier manufacturers scale automated tool-changing systems. Fette Compacting GmbH leverages German precision engineering to sustain premium positioning in validated pharmaceutical environments. KORSCH AG anchors European demand through modular tablet press architectures that accommodate rapid product changeovers. Syntegon Technology GmbH competes by integrating real-time release testing with compression workflows.
A rotary tablet press is a mechanical device that uses rotating turrets fitted with multiple punch-and-die sets to compress granular or powder formulations into uniform tablets at speeds reaching thousands of units per minute; its primary purpose is enabling high-volume, consistent solid-dose manufacturing for regulated industries. High-speed rotary configurations dominate capital deployment as oral solid dosage remains the most economical drug delivery format for mass therapies. Electric drive technology is displacing mechanical drive systems where energy efficiency and precise compression force control determine total cost of ownership. Contract manufacturers represent the fastest-growing end user category as pharmaceutical companies outsource capacity to balance variable demand against fixed asset burdens.
FDA validation requirements and EMA GMP Annex 15 guidelines shape equipment qualification protocols, compelling manufacturers to invest in process analytical technology integration for batch release. The EU AI Act and emerging FDA guidance on artificial intelligence in manufacturing are forcing re-evaluation of automated defect detection systems. China's NMPA alignment with ICH Q12 lifecycle management standards is opening pathways for Western equipment suppliers. Stakeholders must monitor regulatory convergence on continuous manufacturing acceptance criteria to time platform upgrade investments.
Market Dynamics
Electric drive technology is decomposing mechanical compression architectures across pharmaceutical manufacturing, forcing incumbent suppliers to reengineer torque transmission systems for precision force modulation and energy recovery.
Growth Catalysts
- FDA Process Analytical Technology mandates:Continuous manufacturing validation protocols compel equipment upgrades with integrated real-time release testing capabilities.
- Contract manufacturing expansion:Pharmaceutical outsourcing concentrates procurement volume among high-speed rotary specialists serving variable batch demand.
- EMA GMP Annex 15 alignment:European lifecycle management standards accelerate replacement cycles for legacy single-punch installations.
Market Restraints
- Tooling steel supply concentration:Premium tungsten carbide die sets depend on concentrated German and Austrian metallurgical suppliers.
- Validation cost escalation:FDA 21 CFR Part 11 compliance documentation requirements extend qualification timelines for new installations.
- Continuous processing substitution:Fluid bed granulation and hot-melt extrusion lines compete for solid-dose capital allocation.
Strategic Opportunities
- India PLI scheme alignment:Domestic pharmaceutical production incentives create localized equipment demand for import substitution.
- EU AI Act integration:Automated defect detection systems qualify for regulatory preference in validated manufacturing environments.
- Modular architecture convergence:Rapid product changeover capabilities combine with single-use containment technologies for multi-product facilities.
Industry Challenges
- Mechatronics talent scarcity:Servo drive calibration and compression force algorithm development require specialized cross-functional engineering teams.
- Legacy system integration friction:Electric drive retrofits face mechanical turret incompatibility with existing punch-and-die inventories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Rotary Tablet Press Market |
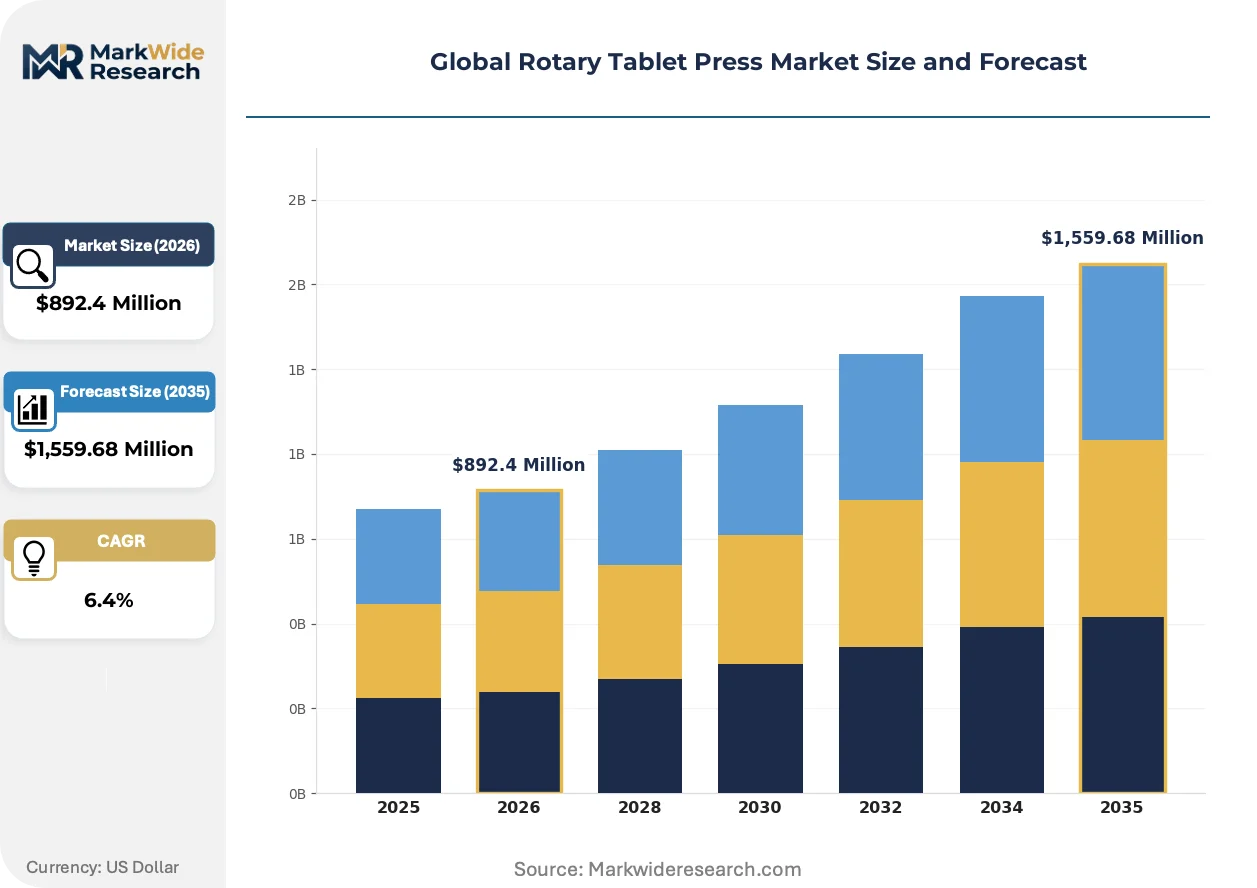
| Market Size in 2026 | $892.4 Million |
| Market Size in 2035 | $1,559.68 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Rotary, Multi Rotary, Double Rotary, High-Speed Rotary Technology: Hydraulic Compression, Pneumatic Compression, Electric Drive, Mechanical Drive Application: Pharmaceutical Manufacturing, Nutritional Supplement Production, Chemical Compounding, Veterinary Medicine End User: Contract Manufacturers, Research Laboratories, Bulk Producers, Specialized Pharmacies |
| Companies Covered | IMA S.p.A, Elizabeth Companies, KORSCH AG, Syntegon Technology GmbH, Cadmach Machinery Company Pvt., GEA Group Aktiengesellschaft, Romaco GmbH, Manesty (Bosch), Fette Compacting GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Rotary Tablet Press Market Shifts & Advancements
Real-time process control architectures are displacing batch-based quality verification, compressing release timelines from days to minutes while demanding new sensor integration competencies from equipment suppliers.
Servo-electric compression systems is decomposing mechanical cam-driven force profiles into digitally programmable waveforms. Mid-tier contract manufacturers in Germany and India are adopting these configurations for multi-product flexibility. The technology is decomposing the traditional trade-off between throughput and tablet weight uniformity, enabling high-speed output with reduced rejection rates.
EMA GMP Annex 15 lifecycle management guidelines now mandate ongoing process verification rather than one-time qualification. Pharmaceutical manufacturers must demonstrate continued control through automated data collection. High-volume oral solid dosage facilities in Switzerland and Germany are retrofitting legacy presses with process analytical technology suites to satisfy inspection readiness.
Equipment-as-a-service contracting is replacing outright purchase for capacity expansion decisions. Contract manufacturers in the United States and China now prioritize operational expenditure models that transfer obsolescence risk to suppliers. After-sales revenue streams are concentrating among vendors with captive financing arms and regional spare parts depots.
Global Rotary Tablet Press Market Segmentation
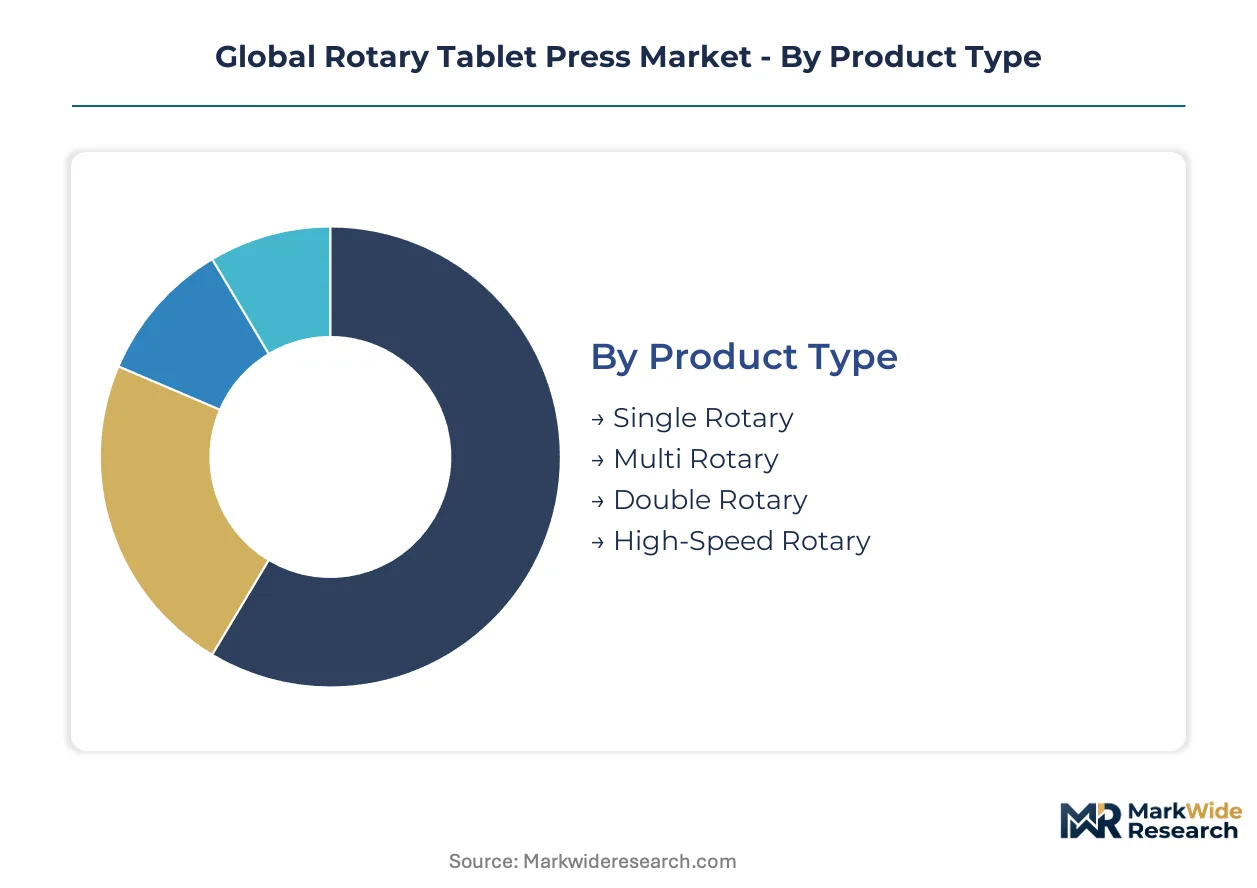
Rotary tablet press segmentation reveals how capital deployment priorities diverge between validated pharmaceutical environments and cost-sensitive supplement operations. Equipment specifications, drive architectures, and end-user procurement models each create distinct margin pools that suppliers must navigate.
Product Type:
Margin pools concentrate in high-speed configurations where pharmaceutical validation requirements sustain premium pricing, while single-rotary legacy systems face commoditization pressure from Asian suppliers.
- High-Speed Rotary:Turret configurations exceeding 100 stations deliver throughput above 1 million tablets per hour with real-time weight monitoring. Demand clusters at contract manufacturers in Germany, India, and the United States serving Big Pharma outsourcing contracts where FDA validation timelines compress equipment selection windows.
- Double Rotary:Dual-turret architectures enable continuous production with alternating compression cycles for extended runtime. Procurement concentrates among Indian bulk producers leveraging PLI scheme incentives to scale export capacity for regulated markets.
- Multi Rotary:Intermediate station counts balance throughput against changeover flexibility for multi-product facilities.
- Single Rotary:Entry-level configurations serve research scale-up and veterinary compounders with limited batch volumes.
High-speed rotary holds installed capacity across major pharmaceutical clusters. Double rotary is rotating up the share rankings as Indian manufacturers expand validated export capacity.
Technology:
Cost tier stratification separates precision servo-electric systems from legacy mechanical architectures, with pneumatic and hydraulic alternatives occupying intermediate positions in specialty applications.
- Electric Drive:Servo motor arrays replace mechanical cams with programmable force profiles and energy recovery systems. German and Swiss pharmaceutical manufacturers specify these configurations for EMA GMP Annex 15 compliance, where compression force traceability supports continuous process verification.
- Mechanical Drive:Cam-driven systems retain share in emerging markets where capital constraints outweigh efficiency considerations. Indian nutritional supplement producers favor these units for high-volume, low-variability formulations where energy costs represent smaller total cost of ownership components.
- Hydraulic Compression:Fluid power systems deliver sustained force for high-diameter tablets and layered formulations in chemical compounding.
- Pneumatic Compression:Compressed air actuation serves specialized coating and core-shell applications with gentler compression profiles.
Mechanical drive retains legacy installed base across price-sensitive segments. Electric drive is climbing the fastest as energy efficiency mandates tighten in European manufacturing.
Application:
Volume concentration in pharmaceutical manufacturing creates procurement scale that drives supplier R&D priorities, while adjacent applications demand adapted specifications at reduced price points.
- Pharmaceutical Manufacturing:Validated environments require 21 CFR Part 11 compliant data integrity, automated tool recognition, and isolator integration for potent compound handling. FDA process analytical technology mandates are accelerating replacement of legacy presses at facilities in the United States, Germany, and Switzerland.
- Nutritional Supplement Production:Probiotic, protein, and botanical formulations demand modified feed frame designs for poor-flowing powders. Contract manufacturers in China and India specify these configurations for export to North American and European wellness markets with escalating quality expectations.
- Chemical Compounding:Industrial catalyst and detergent tablet production prioritizes corrosion-resistant contact parts over precision dosing.
- Veterinary Medicine:Palatable large-diameter tablets for livestock require extended dwell time modifications to standard compression kinematics.
Pharmaceutical manufacturing commands premium specification concentration. Nutritional supplement production is gaining share fastest as wellness market outsourcing expands.
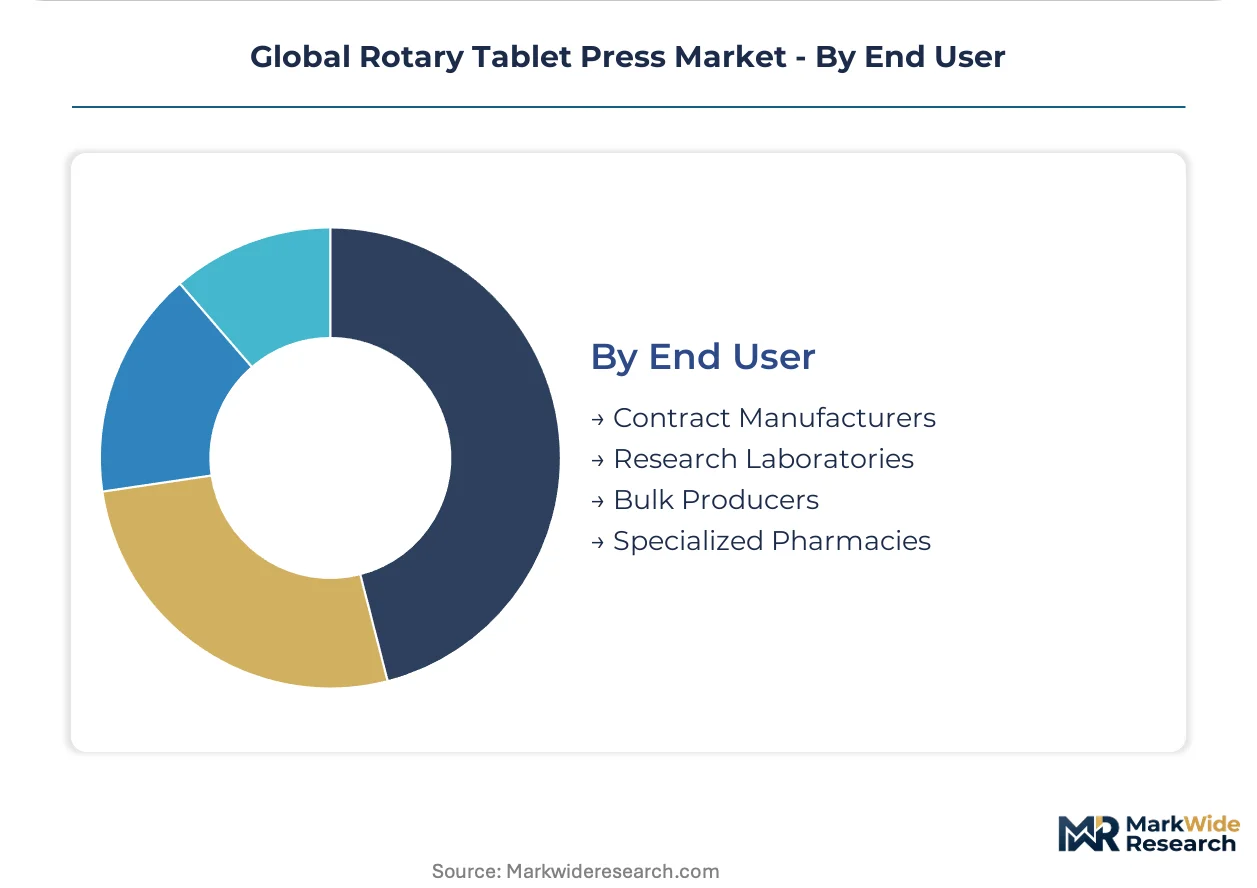
End User:
Customer type determines procurement model selection between capital purchase, equipment-as-a-service, and lease arrangements, with financing capability becoming a competitive differentiator.
- Contract Manufacturers:Variable batch demand and multi-product portfolios drive requirements for rapid tool changeover and automated recipe management. United States and Chinese facilities increasingly prefer operational expenditure models that transfer obsolescence risk to equipment suppliers with captive financing arms.
- Bulk Producers:Dedicated high-volume facilities for single products maximize uptime through predictive maintenance and redundant press configurations. Indian pharmaceutical exporters under PLI scheme coverage are expanding capacity with standardized high-speed lines for generic solid dosage.
- Research Laboratories:Clinical trial material production demands flexibility for small batches with full batch documentation.
- Specialized Pharmacies:Compounding operations require portable units for patient-specific formulations with minimal validation overhead.
Bulk producers anchor equipment utilization rates across major manufacturing clusters. Contract manufacturers are expanding most quickly as pharmaceutical outsourcing accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Swiss precision engineering clusters while Indian manufacturers compete on capital efficiency for mid-tier contract manufacturing contracts.
United States
Contract manufacturing organizations in New Jersey and North Carolina drive high-speed rotary press procurement for FDA-validated oral solid dosage production. FDA process analytical technology mandates compress equipment qualification timelines. Boston-area biopharma clusters are retrofitting legacy installations with real-time release testing capabilities.
Germany
EMA GMP Annex 15 lifecycle management standards accelerate replacement cycles at pharmaceutical facilities in Baden-Württemberg and Bavaria. Electric drive technology dominates new capital deployment for energy efficiency compliance. Fette Compacting GmbH and KORSCH AG anchor premium equipment supply from Stuttgart and Berlin manufacturing bases.
India
PLI scheme incentives for domestic pharmaceutical production are scaling export-oriented capacity in Gujarat and Maharashtra. CDSCO alignment with ICH Q12 standards enables Western market access for contract manufacturers. Ahmedabad and Mumbai clusters are standardizing on high-speed rotary configurations for generic solid dosage exports.
China
NMPA convergence with international GMP standards is opening pathways for Western equipment suppliers in Jiangsu and Zhejiang provinces. Contract manufacturers in Shanghai and Suzhou are adopting automated tool-changing systems for multi-product flexibility. Domestic producers are displacing mechanical drive imports with localized electric press assembly.
Switzerland
Swissmedic inspection protocols demand continuous process verification capabilities at Basel-area pharmaceutical manufacturing sites. High-value solid dosage facilities are integrating process analytical technology suites into existing press lines. Precision engineering subcontractors in the Jura region supply validated compression tooling for global pharmaceutical customers.
Global Rotary Tablet Press Market Competitive Landscape
Concentration sits with German precision engineering specialists and diversified European industrial conglomerates serving validated pharmaceutical environments. The vendor base stratifies across premium-tier validated equipment suppliers, mid-tier contract manufacturing specialists, and emerging Asian fabricators competing on capital efficiency. Strategic archetypes include precision engineering heritage firms, diversified packaging technology conglomerates, and regional contract manufacturing equipment suppliers. Competitive moves center on modular architecture development for rapid product changeover and equipment-as-a-service financing models that transfer obsolescence risk.
Among German-based precision engineering firms, Fette Compacting GmbH and KORSCH AG exemplify heritage positioning in EMA-validated environments, while Syntegon Technology GmbH represents diversified packaging technology integration. These entities anchor premium-tier supply relationships with contract manufacturers requiring FDA and EMA compliant documentation packages.
| Leading Market Players |
|---|
| IMA S.p.A |
| Elizabeth Companies |
| KORSCH AG |
| Syntegon Technology GmbH |
| Cadmach Machinery Company Pvt. |
| GEA Group Aktiengesellschaft |
| Romaco GmbH |
| Manesty (Bosch) |
| Fette Compacting GmbH |
| Others |
Supply & Pricing Matrix
Forty-five-day tooling lead times from German and Austrian metallurgical suppliers compress procurement windows for high-speed rotary configurations, concentrating pricing power with precision engineering specialists while forcing mid-tier buyers into longer inventory commitments or premium expedite fees.
Pricing Analysis
The customization-premium spread between configured-to-order and standard catalog pricing widens as FDA validation documentation requirements escalate. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales service bundling. Cost compression in mechanical drive segments intensifies because Indian and Chinese fabricators scale standardized exports. Contract manufacturers exhibit highest price sensitivity due to equipment-as-a-service preference, while bulk producers under PLI scheme coverage absorb premium electric drive specifications with lower negotiating leverage.
Supply Chain Analysis
Strategic stockpile preferences dominate tungsten carbide die procurement as single-source concentration in German and Austrian metallurgical centers exposes buyers to allocation risk during capacity constraints. Premium tooling steel draws from Germany, Austria, and select Japanese specialty foundries. Compression force sensors and servo motor arrays rest on Taiwanese and South Korean electronics supply chains. Tariff exposure on precision-machined turrets shipped from European Union origins into Indian and Chinese assembly plants represents the primary structural vulnerability. Distribution runs through captive regional spare parts depots maintained by premium-tier vendors, with secondary channels serving aftermarket tooling demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous processing technologies including fluid bed granulation and hot-melt extrusion lines threaten solid-dose capital allocation, compelling rotary press incumbents to defend substitution risk through integrated workflow positioning.
For Market Incumbents: Shield validated installed base relationships by embedding process analytical technology suites that lock in EMA GMP Annex 15 compliance workflows. Deepen backward integration into precision tooling manufacturing to secure tungsten carbide supply against German-Austrian allocation constraints. Counter emerging Asian electric drive competitors through captive financing arms that absorb obsolescence risk for contract manufacturers.
For New Entrants and Emerging Players: Anchor in Indian pharmaceutical clusters where PLI scheme incentives concentrate export-oriented capacity expansion and Western validation standards create equipment upgrade demand. Target mid-tier contract manufacturers in Gujarat and Maharashtra with modular architectures supporting rapid product changeover. Penetrate through equipment-as-a-service contracting that transfers qualification timeline risk from capital-constrained buyers.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because FDA and EMA validation protocols create structural barriers against commoditization. Acquire precision engineering specialists with captive metallurgical supply relationships and documented FDA 21 CFR Part 11 compliance packages. Watch for inflection when NMPA alignment with ICH Q12 standards accelerates Western equipment penetration into Chinese contract manufacturing facilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Process Analytical Technology Integration | FDA mandates for real-time release testing compress qualification timelines for equipment suppliers. |
| Electric Drive Platform Development | Servo-electric architectures displace mechanical cams in EMA GMP Annex 15 validated environments. |
| Captive Tooling Manufacturing | Backward integration into tungsten carbide die production secures supply against German-Austrian concentration. |
| Equipment-as-a-Service Expansion | Operational expenditure models transfer obsolescence risk and lock in aftermarket revenue streams. |
| Modular Architecture Convergence | Rapid product changeover capabilities align with multi-product contract manufacturing demand. |
Research Methodology
Operator-level perspectives from pharmaceutical manufacturing engineers, contract manufacturing procurement leads, aftermarket service heads, and regulatory affairs specialists anchored the qualitative base. These primary insights combined with secondary validation from FDA 510(k) filings, EMA inspection reports, CDSCO registration databases, and pharmaceutical customs trade records. Bottom-up equipment shipment analysis and top-down pharmaceutical capital expenditure triangulation established volume and value estimates.
Sensitivity analysis around electric drive adoption rates and PLI scheme capacity expansion timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, drive technology, application, and end-user procurement model, with regional regulatory cluster as an additional pharmaceutical-specific dimension. CAGRs derived from equipment replacement cycle analysis and continuous manufacturing validation protocol diffusion curves. Forecast inputs incorporated EMA GMP Annex 15 inspection readiness requirements and NMPA ICH Q12 alignment progress.
Decision-makers should treat outputs as directional under assumptions of sustained FDA process analytical technology mandate enforcement and stable German-Austrian tooling steel supply; material deviation would warrant model refresh. Forecasts reflect documented base-case assumptions regarding contract manufacturing outsourcing velocity and electric drive cost parity achievement. Revision becomes warranted when continuous processing substitution rates or tariff exposure on precision-machined components cross thresholds that alter capital allocation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Sterile Vials Market
Pharmaceutical Equipment
Interlock Vials Market
Pharmaceutical Equipment
Pharmaceutical Cleaning Validation Market
Pharmaceutical Equipment
Pharmaceutical Continuous Manufacturing Market
Pharmaceutical Equipment
Latin America Pharmaceutical Glass Packaging Market
Pharmaceutical Equipment
Global Pharmaceutical Granulation Equipment Market
Pharmaceutical Equipment
North America Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Global Pharmaceutical Membrane Filtration Market
Pharmaceutical Equipment
Global Depyrogenated Sterile Empty Vials Market
Pharmaceutical Equipment
Serum Vials Market
Pharmaceutical Equipment
Global Pharmaceutical Contract Manufacturing and Contract Research Market
Pharmaceutical Equipment
Europe Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Vial Adaptors for Reconstitution Drug Market
Pharmaceutical Equipment
Shell Vials Market
Pharmaceutical Equipment
Sterile Fill-Finish Process Simulation and Media Fill Test Equipment Market
Pharmaceutical Equipment
US and Europe Pharmaceutical Manufacturing Market