
 Sterile Injectable Contract Manufacturing Market | 2026-2036
Sterile Injectable Contract Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Sterile Injectable Contract Manufacturing Market Analytics
India is tilting toward large-scale sterile injectable capacity as Western sponsors seek geographic diversification beyond traditional North American and European supply bases. Catalent leverages integrated biologics fill-finish networks across multiple continents to sustain sponsor relationships. Baxter anchors hospital-channel demand through its parenteral nutrition and generic injectables specialization. Vetter Pharma differentiates via prefilled syringe and cartridge expertise for high-potency biologics.
Sterile injectable contract manufacturing encompasses the outsourced production of drug products administered directly into body tissues or circulatory systems under strict aseptic or terminal sterilization conditions, requiring ISO 5 cleanroom environments, validated isolator or RABS technology, and endotoxin limits typically below 0.25 EU/mL. Biologics command premium capacity allocation due to cold-chain sensitivity and complex protein stability requirements. Small molecules retain volume leadership in generic injectables where cost compression dominates procurement. Filling and packaging services capture disproportionate margin pools relative to upstream drug substance manufacture.
FDA aseptic processing guidance, EMA GMP Annex 1 revisions, and WHO TRS 961 standards collectively elevate barrier technology and continuous monitoring requirements for contract facilities. These frameworks increase capital intensity for new market entrants while creating compliance-based switching costs for incumbent-sponsor relationships. Stakeholders must weigh facility qualification timelines against pipeline commercialization clocks when selecting or expanding CDMO partnerships.
Market Dynamics
Barrier technology mandates from the FDA, EMA, and WHO are compressing facility qualification timelines while oncology biologics developers race to lock in aseptic fill-finish capacity ahead of commercialization deadlines. This regulatory acceleration is forcing sponsors to pre-qualify CDMO partnerships years before anticipated launch.
Growth Catalysts
- EMA GMP Annex 1 revisions:The updated sterile manufacturing standards mandate isolator or RABS deployment, creating upgrade cycles that expand total addressable capacity for compliant contract manufacturers.
- Oncology pipeline density:Biologics developers facing cold-chain complexity and protein stability requirements are outsourcing fill-finish operations to access validated isolator infrastructure they cannot economically replicate in-house.
- India:Western sponsors are qualifying large-scale sterile injectable facilities on the subcontinent to diversify supply chains beyond traditional North American and European manufacturing bases.
Market Restraints
- Capital intensity:ISO 5 cleanroom construction, isolator validation, and continuous monitoring systems require capital deployment that excludes mid-scale entrants from aseptic biologics segments.
- Single-source dependency:Limited qualified suppliers of pharmaceutical-grade rubber stoppers and pre-sterilized container closure systems create input bottlenecks for high-volume parenteral production.
- Endotoxin testing limitations:Limulus amebocyte lysate supply constraints and alternative recombinant factor C validation gaps restrict batch release velocity for sterile injectable lots.
Strategic Opportunities
- Prefilled syringe convergence:Integration of ready-to-use delivery formats with high-potency biologics is opening capacity niches for CDMOs with validated cartridge and auto-injector assembly lines.
- Continuous manufacturing:Adoption of isolator-integrated filling lines with in-line weight checking and 100% inspection is collapsing batch failure rates and enabling real-time release paradigms.
- Integrated CDMO models:Sponsors are consolidating drug substance and drug product manufacture with single providers to compress tech transfer timelines and reduce supply chain handoff risks.
Industry Challenges
- Aseptic operator certification:FDA and EMA inspectorates are intensifying personnel qualification scrutiny, extending training timelines and constraining workforce scalability for multi-shift operations.
- Legacy equipment integration:Retrofitting existing fill-finish suites with isolator technology while maintaining commercial production creates validation complexity and temporary capacity loss.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sterile Injectable Contract Manufacturing Market |
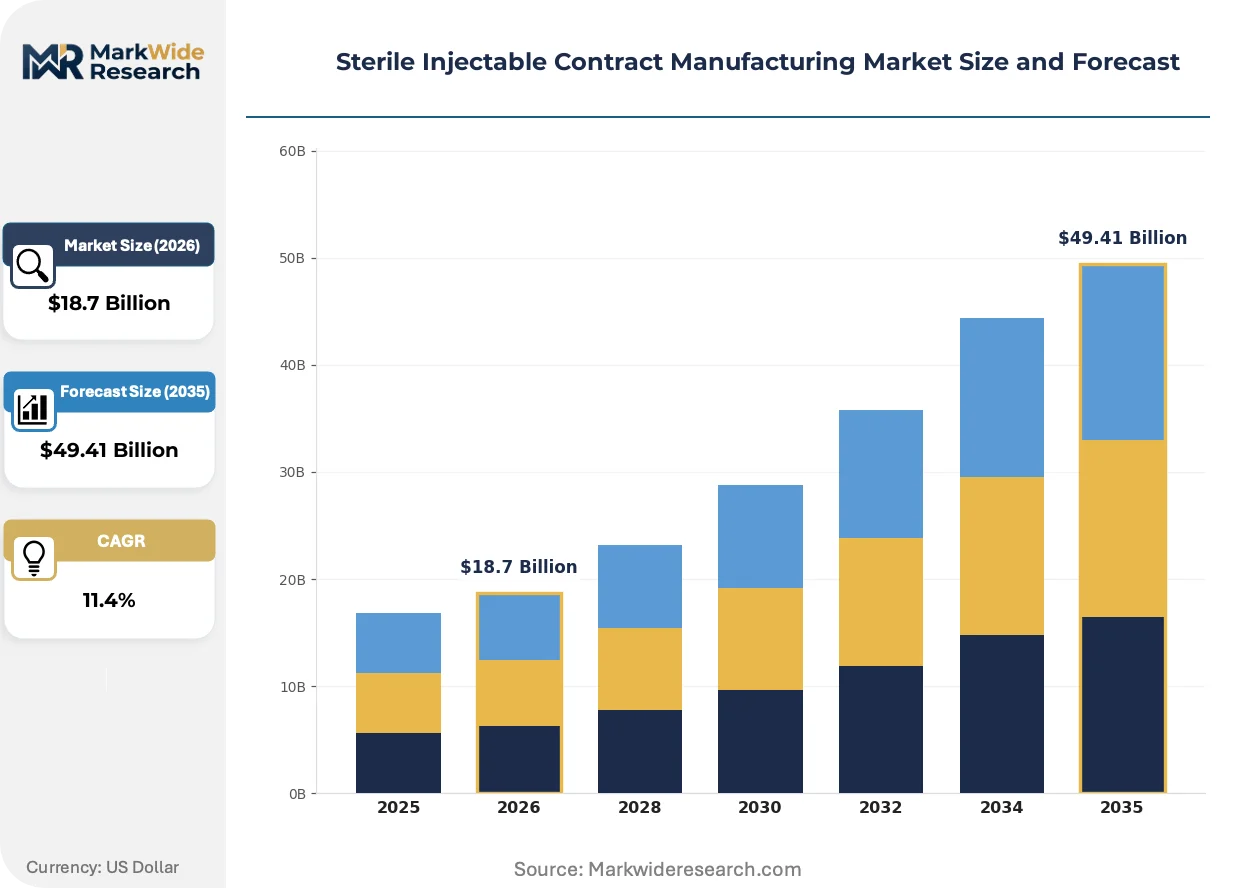
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biologics, Vaccines, Small Molecules, Peptides End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutions, Contract Research Organizations Delivery Mode: Intravenous, Intramuscular, Subcutaneous, Intra-articular Service Type: Formulation Development, Filling & Packaging, Quality Control, Regulatory Compliance |
| Companies Covered | Catalent, Baxter, Vetter Pharma, Recipharm, Aenova Group, Fresenius Kabi, Unither Pharmaceuticals, Famar, Cipla, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sterile Injectable Contract Manufacturing Market Evolving Landscape
Isolator technology and continuous process verification are compressing the traditional boundaries between batch manufacturing and real-time release, while regulatory convergence across FDA, EMA, and WHO standards is harmonizing compliance architectures.
Closed Restricted Access Barrier Systems (cRABS) and isolator-based filling lines are collapsing contamination risk profiles for high-potency biologics. Oncology and autoimmune therapeutic developers are specifying isolator technology in CDMO qualification protocols regardless of compound hazard classification. This technology compression is eliminating the historical gap between aseptic processing and terminal sterilization capability requirements.
WHO TRS 961 standards on pharmaceutical quality systems are elevating environmental monitoring and data integrity requirements for sterile manufacturing facilities. Contract manufacturers serving emerging market registrations must demonstrate equivalent barrier technology and continuous viable particle monitoring to maintain supply access. African and Latin American national regulators are adopting these standards as import preconditions, affecting sponsor site selection criteria.
Biologics sponsors are consolidating vendor relationships around integrated drug substance-to-drug product CDMOs with validated cold-chain distribution networks. This concentration is displacing fragmented procurement models where sponsors managed separate API, fill-finish, and logistics contracts. United States-based developers with pipeline assets approaching Phase III are prioritizing domestic or near-shore capacity to minimize tech transfer distance and regulatory inspection coordination complexity.
Sterile Injectable Contract Manufacturing Market Segmentation
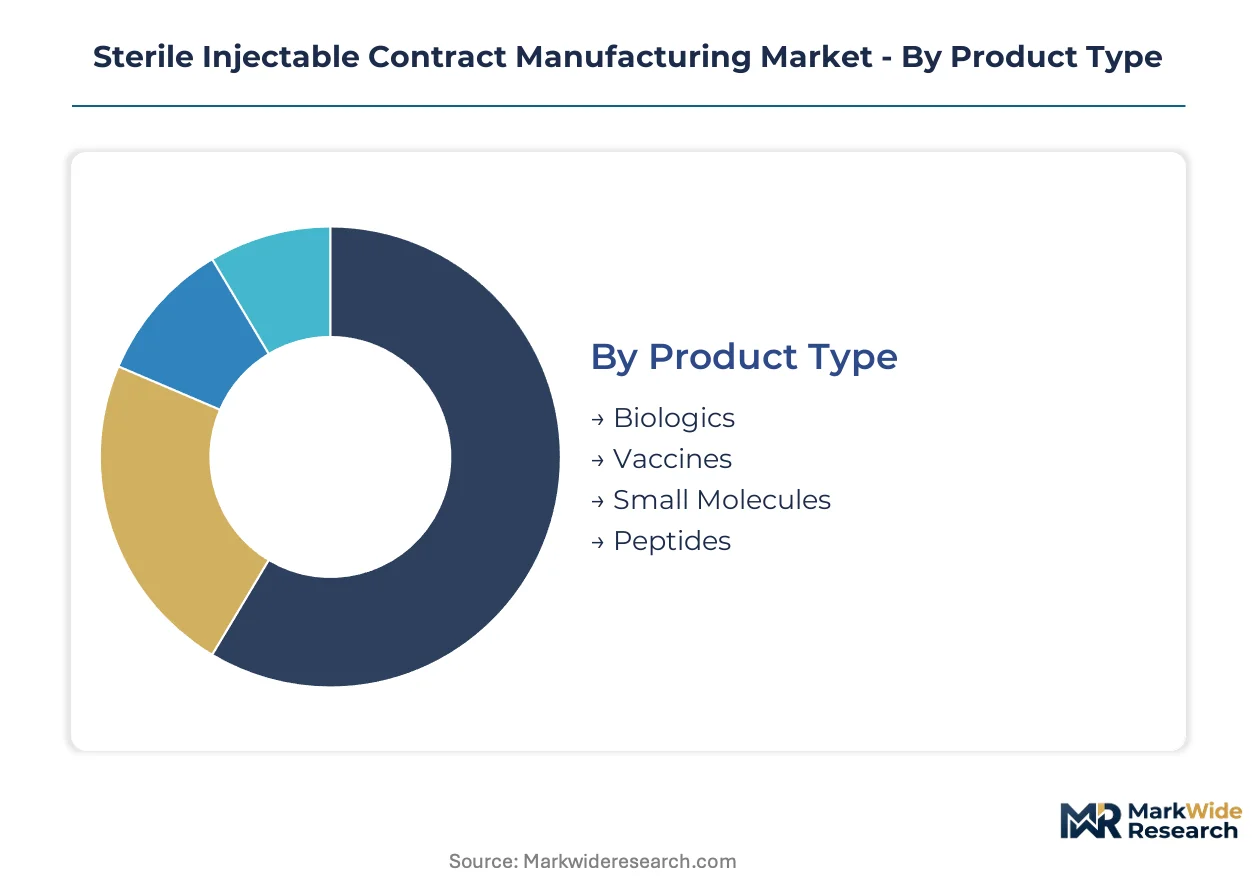
Sterile injectable contract manufacturing segments along four critical dimensions that determine facility design, regulatory pathway, and margin structure. Each segmentation axis reveals distinct capacity allocation patterns and sponsor qualification criteria that shape partnership decisions.
Product Type:
Mature small molecule capacity coexists with emerging biologics infrastructure as sponsors balance volume against complexity premiums.
- Biologics:Complex protein therapeutics requiring validated isolator technology, continuous cold-chain maintenance, and endotoxin limits below 0.25 EU/mL. Demand concentrates in United States-based CDMOs serving Phase III oncology pipelines where FDA aseptic guidance mandates barrier technology deployment.
- Small Molecules:Generic injectable antibiotics, analgesics, and anesthesia agents produced through terminal sterilization or aseptic processing. Volume leadership persists in hospital-channel parenteral nutrition and generic anti-infectives where cost compression dominates procurement decisions.
- Vaccines:Adjuvanted and mRNA formulations requiring dedicated viral clearance validation and specialized containment infrastructure.
- Peptides:Synthetic oligopeptide therapeutics bridging small molecule and biologics regulatory frameworks with unique stability challenges.
Small molecules handles the majority of throughput; biologics is expanding most quickly on share.
End User:
Customer type determines contract structure complexity, with integrated developers seeking single-source accountability versus fragmented procurement by research-stage sponsors.
- Pharmaceutical Companies:Large-cap sponsors consolidating drug substance and drug product manufacture with integrated CDMOs to compress tech transfer timelines and reduce supply chain handoff risks across multi-product portfolios.
- Biotechnology Firms:Venture-backed developers outsourcing fill-finish operations to access validated isolator infrastructure they cannot economically replicate in-house, particularly for high-potency oncology biologics.
- Research Institutions:Academic medical centers requiring small-batch GMP manufacturing for investigator-initiated trials and early-phase clinical materials.
- Contract Research Organizations:Clinical service providers extending vertically into manufacturing to capture sponsor relationships across the development continuum.
Pharmaceutical companies dominate committed capacity; biotechnology firms are climbing the fastest on contract volume.
Delivery Mode:
Route of administration dictates container closure system specifications and drives differentiation in fill-finish line configuration.
- Intravenous:Large-volume parenterals and lyophilized vials requiring automated filling lines with in-line weight checking and 100% inspection capabilities for hospital infusion.
- Subcutaneous:Prefilled syringes and auto-injector cartridges for self-administered biologics, opening capacity niches for CDMOs with validated assembly lines and combination product expertise.
- Intramuscular:Vaccine and long-acting antipsychotic formulations in single-dose vials and prefilled syringes with specific viscosity handling requirements.
- Intra-articular:Hyaluronic acid and corticosteroid injections for orthopedic applications with specialized particulate control and syringe lubrication specifications.
Intravenous commands the largest installed base; subcutaneous is gaining share fastest through prefilled format convergence.
Service Type:
Margin pools concentrate downstream in drug product operations, with formulation and regulatory services anchoring long-term sponsor retention.
- Filling & Packaging:Aseptic fill-finish, lyophilization, and container closure processing capturing disproportionate margin pools relative to upstream drug substance manufacture through ISO 5 cleanroom execution.
- Formulation Development:Stability-indicating method development, forced degradation studies, and compatibility testing for biologics with complex protein stability requirements.
- Quality Control:Release testing, environmental monitoring, and endotoxin validation with Limulus amebocyte lysate supply constraints restricting batch release velocity.
- Regulatory Compliance:CMC documentation, FDA pre-approval inspection preparation, and EMA GMP Annex 1 gap remediation for barrier technology qualification.
Filling & packaging anchors revenue concentration; formulation development shows the steepest expansion trajectory as sponsors front-load CDMO engagement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA aseptic processing guidance anchors capacity concentration in the United States, while EMA GMP Annex 1 revisions and WHO TRS 961 standards reshape qualification requirements across Germany and India. Sponsors now pre-qualify CDMO partnerships years before commercialization deadlines.
United States
Biologics pipeline density drives demand concentration, with oncology developers locking in isolator-equipped fill-finish capacity ahead of Phase III transitions. FDA updated guidance on sterile drug products manufactured aseptically tightens compliance thresholds for barrier technology deployment. The Greater Boston and San Francisco Bay Area clusters anchor sponsor R&D proximity preferences, pulling integrated CDMO services toward these coastal hubs.
Germany
EMA GMP Annex 1 revisions mandate isolator or RABS deployment, creating upgrade cycles that expand compliant contract manufacturing capacity. The country's national pharmaceutical regulator enforces continuous viable particle monitoring standards that align with WHO TRS 961 frameworks. The Rhine-Main and Baden-Württemberg industrial corridors concentrate prefilled syringe and cartridge expertise for high-potency biologics exports.
India
Western sponsors qualify large-scale sterile injectable facilities to diversify supply chains beyond traditional North American and European manufacturing bases. CDSCO oversight harmonizes with FDA inspection protocols for facilities serving US-bound drug products. The Hyderabad and Ahmedabad pharmaceutical clusters are adding isolator-integrated filling lines to capture biologics outsourcing contracts from mid-cap biotechnology firms.
Switzerland
High-potency biologics specialization attracts sponsor investment, with Swissmedic maintaining alignment with EMA standards for aseptic processing validation. The country's national pharmaceutical regulator emphasizes data integrity and environmental monitoring for sterile manufacturing site approvals. The Basel metropolitan area anchors integrated drug substance-to-drug product CDMO networks serving European biotechnology sponsors.
Japan
PMDA inspection rigor for aseptic operator certification extends training timelines, constraining workforce scalability for multi-shift fill-finish operations. METI industrial policy supports domestic biologics manufacturing capacity to reduce import dependency for critical injectable therapies. The Kanto region around Tokyo concentrates legacy pharmaceutical infrastructure undergoing isolator retrofitting to meet revised international standards.
Sterile Injectable Contract Manufacturing Market Competitive Landscape
Capability concentration sits with integrated biologics specialists; scale advantage sits with hospital-channel generic injectables producers. The market structure tiers across three archetypes: multi-continent integrated CDMOs with validated cold-chain networks, regional fill-finish specialists with prefilled format expertise, and diversified pharmaceutical manufacturers leveraging captive capacity for contract revenue. Dominant competitive moves include barrier technology upgrades to secure oncology biologics contracts and backward integration into drug substance manufacture to compress tech transfer timelines.
Within the integrated CDMO tier, Catalent exemplifies multi-continent biologics fill-finish network deployment. Among hospital-channel specialists, Baxter occupies a position anchored in parenteral nutrition and generic injectables scale. Vetter Pharma represents the prefilled syringe and cartridge differentiation archetype for high-potency biologics applications.
| Leading Market Players |
|---|
| Catalent |
| Baxter |
| Vetter Pharma |
| Recipharm |
| Aenova Group |
| Fresenius Kabi |
| Unither Pharmaceuticals |
| Famar |
| Cipla |
| Others |
Value Network & Pricing Analysis
Pharma-grade cold-chain corridors between Frankfurt and Mumbai carry cost premiums that concentrate pricing power with isolator-equipped CDMOs while compressing margins for generic injectable producers. These freight dynamics amplify price spreads between biologics fill-finish and small-molecule terminal sterilization tiers.
Pricing Analysis
Geographic price spreads between United States and Indian contract manufacturing facilities exceed threefold for equivalent biologics capacity. Three-tier pricing structure across premium isolator-validated, standard RABS-equipped, and economy terminal-sterilization levels anchors the market. Cost compression in generic hospital-channel injectables is intensifying because of formulary consolidation at GPOs. Small-molecule generic sponsors exhibit highest price sensitivity; oncology biologics developers prioritize barrier technology certification over unit cost.
Supply Chain Analysis
Tariff exposure between United States and China dominates supply chain risk calculations for pharmaceutical-grade rubber stoppers and borosilicate glass vials. Manufacturing concentration centers on Germany, India, and the United States for sterile fill-finish capacity. Isolator-grade HEPA filtration media, pre-sterilized container closure systems, and validated cold-chain packaging constitute critical input dependencies. Single-source vulnerability for Limulus amebocyte lysate constrains batch release velocity. Distribution runs through integrated CDMO networks with validated temperature-controlled logistics rather than fragmented third-party channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Validated isolator infrastructure scarcity is constraining oncology pipeline commercialization timelines, creating asymmetric returns for facility owners versus capacity-constrained sponsors. This capability gap justifies preemptive capacity commitments years ahead of regulatory submission.
For Market Incumbents: Pre-empt biosimilar developers and mid-cap biotechnology firms by accelerating isolator retrofitting at legacy facilities before EMA GMP Annex 1 enforcement deadlines. Backward integration into drug substance manufacture compresses tech transfer timelines and defends against integrated CDMO competitors capturing sponsor relationships. Barrier technology certification investments anchor long-term contract renewals.
For New Entrants and Emerging Players: Southeast Asian sterile injectable capacity remains underpenetrated by Western-qualified CDMOs despite rising sponsor interest in geographic diversification. Target prefilled syringe assembly for high-potency biologics as the most penetrable niche, leveraging lower capital intensity than full isolator fill-finish. Pursue partnership-first go-to-market positioning with established regional distributors to bypass multi-year facility qualification barriers.
For Investors and Strategic Acquirers: Regional fill-finish specialists with validated prefilled format expertise represent the highest-conviction acquisition archetype for portfolio consolidation. Long-term viability across the analysis window hinges on isolator technology deployment and cold-chain distribution network density. Watch FDA warning letter issuance rates for aseptic processing violations as the inflection indicator for competitive capacity rationalization.
| Strategic Initiative | Industry Significance |
|---|---|
| Isolator Technology Deployment | EMA GMP Annex 1 compliance mandates barrier systems for oncology biologics contracts. |
| Backward Integration into Drug Substance | Integrated CDMO models reduce tech transfer risk for Phase III pipeline sponsors. |
| Prefilled Syringe Capacity Expansion | Self-administered biologics convergence creates margin-rich assembly line opportunities. |
| Indian Facility Qualification | CDSCO-FDA harmonization enables geographic diversification for Western sponsors. |
| Cold-Chain Distribution Network Buildout | Validated temperature-controlled logistics anchor long-term sponsor retention. |
Research Methodology
Operator-level perspectives from aseptic processing technicians, regulatory affairs directors, CDMO commercial leads, and hospital pharmacy procurement managers anchored the qualitative base. Primary interview insights combined with secondary validation from FDA Form 483 observations, EMA inspection databases, WHO TRS 961 implementation reports, and pharmaceutical trade customs records. Bottom-up facility capacity modeling and top-down sponsor outsourcing spend estimates were triangulated to constrain output ranges.
Scenario-bracketing framed analytical outputs across the projection horizon, with regulatory acceleration and supply chain disruption as boundary conditions. Segmentation dimensions included product type complexity tier, delivery mode specifications, service type margin structure, and regional regulatory cluster alignment. CAGRs were derived from capacity expansion announcements cross-referenced against sponsor pipeline transition probabilities and isolator qualification timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by private-equity-backed CDMO rollups or sovereign wealth fund facility investments would shift outcomes. Regulatory inspection backlog resolution and Limulus amebocyte lysate supply normalization constitute specific revision triggers. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Investigational New Drug CDMO Market
Pharmaceutical Equipment
Latin America Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
China Pharmaceutical Warehousing Market
Pharmaceutical Equipment
Pharmaceutical Equipment Market
Pharmaceutical Equipment
Latin America Pharmaceutical Glass Packaging Market
Pharmaceutical Equipment
Vial Adaptors for Reconstitution Drug Market
Pharmaceutical Equipment
Automated Radiosynthesis Modules Market
Pharmaceutical Equipment
Pharmaceutical Storage and Material Handling Equipment Market
Pharmaceutical Equipment
Aseptic Negative Pressure Pharmaceutical Isolators Market
Pharmaceutical Equipment
Pharmaceutical Equipment Testing Market
Pharmaceutical Equipment
Radiopharmaceutical Synthesizer Market
Pharmaceutical Equipment
Pharmaceutical Glass Ampoules Market
Pharmaceutical Equipment
Pharmaceutical Cleaning Validation Market
Pharmaceutical Equipment
Global Depyrogenated Sterile Empty Vials Market
Pharmaceutical Equipment
Middle East and Africa Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Pharmaceutical Sterilization Equipment Market