
 Global Pharmacy Automation Systems Market | 2026-2036
Global Pharmacy Automation Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pharmacy Automation Systems Market Outlook
The capital-intensity divergence between large-scale platform vendors and point-solution specialists is collapsing as mid-tier buyers demand integrated medication management stacks. McKesson Corporation leverages its distribution infrastructure to bundle automation hardware with enterprise software contracts. Omnicell sustains R&D intensity across closed-loop inventory platforms that anchor hospital pharmacy workflows. Swisslog Healthcare competes through robotic dispensing cells that occupy central-fill and mail-order facilities in North America and Europe.
Pharmacy automation systems encompass electromechanical and software-controlled devices that store, dispense, track, and package medications with specifications including dispensing accuracy rates exceeding 99.9% and throughput capacities of 300-plus prescriptions per hour in high-volume configurations. Their primary commercial purpose is to eliminate human error in medication handling while compressing labor cost per script across retail, hospital, and long-term care settings. Automated dispensing units dominate installed base value, though cloud-based solutions represent the fastest-expanding margin pool as pharmacy chains prioritize remote fleet management and predictive maintenance over capital-heavy on-premise deployments. Artificial Intelligence applications in prescription verification and inventory forecasting are attracting venture-stage investment despite limited regulatory clarity on algorithmic validation standards.
The FDA enforces Drug Supply Chain Security Act serialization requirements that shape demand for track-and-trace-capable automation, while the EMA's Falsified Medicines Directive mandates similar authentication infrastructure across European dispensaries. Japan's PMDA imposes distinct software validation protocols on medication management systems that create market access friction for non-domestic vendors. Stakeholders must monitor how evolving AI/ML regulatory frameworks in the United States and European Union reshape product development roadmaps and compliance cost structures for next-generation platforms.
Market Dynamics
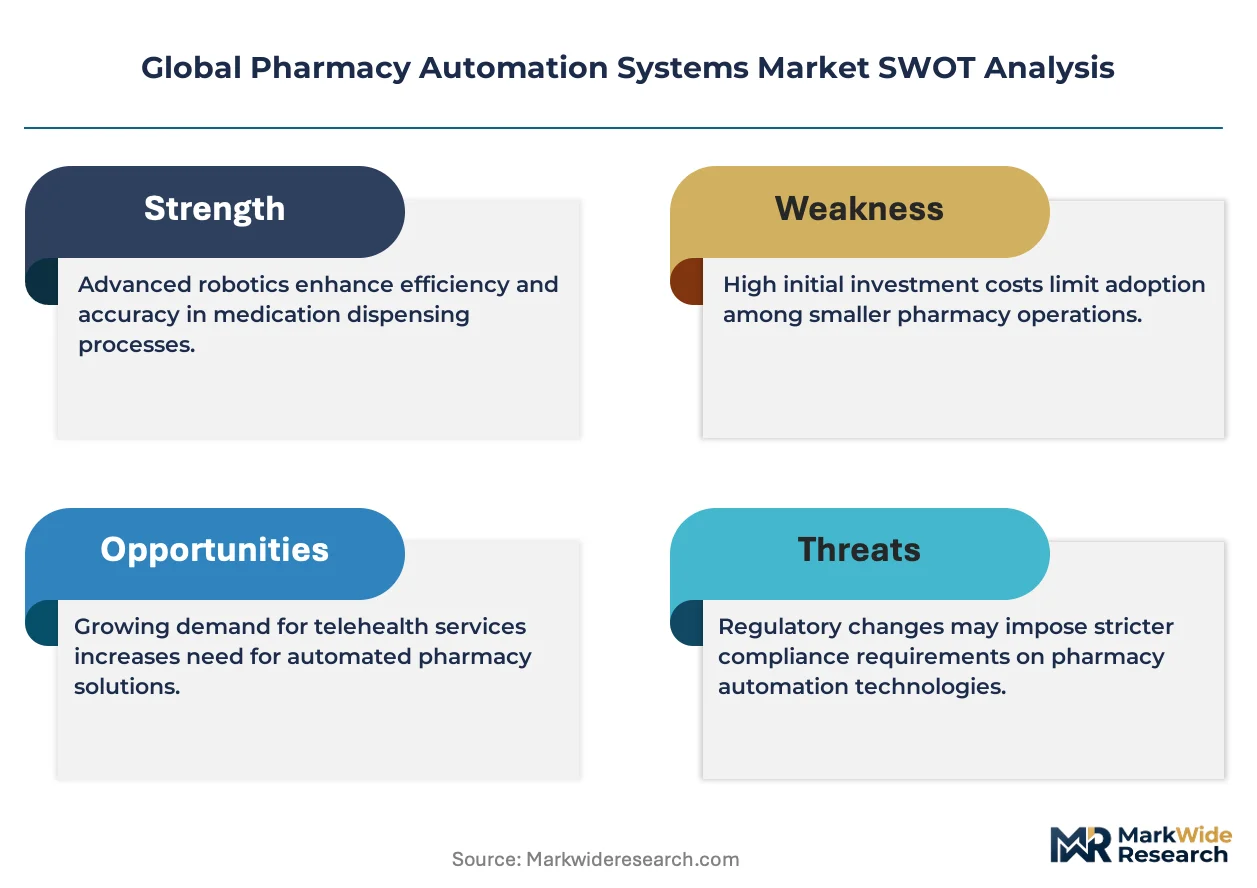
Hospital pharmacy consolidation is compressing vendor margins as integrated delivery networks demand enterprise-wide automation contracts rather than point solutions for individual facilities. This buyer-side concentration forces automation suppliers to bundle hardware, software, and service components into multi-year agreements that lock out specialized competitors lacking distribution scale.
Growth Catalysts
- Drug Supply Chain Security Act:FDA serialization mandates compel pharmaceutical distributors to deploy track-and-trace automation infrastructure, creating replacement demand across retail and hospital dispensaries in the United States.
- Japan's aging pharmacist workforce:Labor shortages in hospital and community pharmacy operations accelerate robotic dispensing adoption as METI promotes productivity-focused healthcare investment incentives.
- Closed-loop inventory management:Real-time medication tracking integration between automated dispensing cabinets and electronic health records reduces diversion risk and compliance audit failures.
Market Restraints
- Stainless steel and precision servo motor costs:Input price volatility for robotic dispensing hardware compresses gross margins for equipment manufacturers without captive component sourcing.
- PMDA software validation protocols:Japan's distinct medication management system certification requirements create market access friction and extend product launch timelines for non-domestic automation vendors.
- Manual pharmacy workflows in emerging markets:Low labor costs and limited capital availability in India and Southeast Asia sustain substitution pressure against high-throughput automation investments.
Strategic Opportunities
- German hospital digitization:The EU Medical Device Regulation and national Hospital Future Act funding create procurement windows for AI-enabled verification systems in centralized pharmacy operations.
- Cloud-based fleet management:Remote monitoring and predictive maintenance platforms enable recurring revenue streams that offset cyclical hardware sales dependence.
- Long-term care integration:Medication adherence packaging automation for skilled nursing facilities addresses labor scarcity and regulatory audit intensity in the United States and Japan.
Industry Challenges
- Mechatronics engineering scarcity:Specialized talent combining pharmaceutical workflow knowledge with robotics integration expertise constrains deployment velocity for complex central-fill installations.
- Legacy health record interoperability:Proprietary data formats in incumbent hospital information systems force costly custom interface development for automated dispensing cabinet deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pharmacy Automation Systems Market |
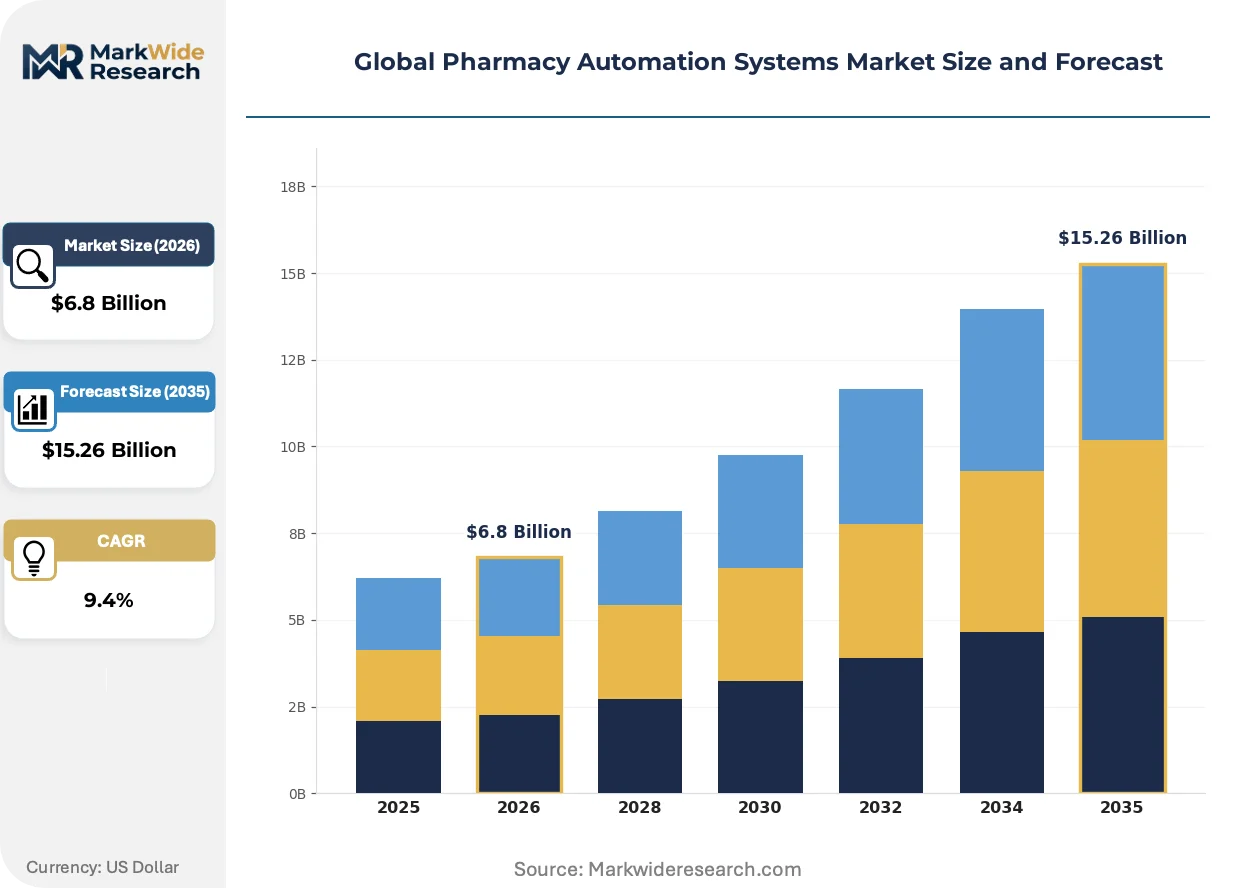
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Dispensing Units, Robotic Prescription Dispensing, Pharma Packaging Systems, Medication Management Systems Technology: Barcode Technology, RFID Systems, Cloud-Based Solutions, Artificial Intelligence End User: Hospital Pharmacies, Retail Pharmacies, Long-Term Care Facilities, Compounding Pharmacies Application: Inventory Management, Prescription Filling, Patient Safety, Workflow Efficiency |
| Companies Covered | ScriptPro, McKesson Corporation, Omnicell, Swisslog Healthcare, Becton, Dickinson and Company, Capsa Healthcare, ARxIUM, RxSafe, Parata Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pharmacy Automation Systems Market Strategic Shifts
Artificial intelligence applications are penetrating prescription verification and inventory forecasting functions, though regulatory uncertainty around algorithmic validation standards constrains deployment velocity. Cloud-native architectures are displacing on-premise infrastructure as pharmacy chains prioritize operational flexibility over capital ownership.
Computer vision systems for pill identification and counting are decomposing traditional manual verification workflows in high-volume mail-order and central-fill environments. CVS Health and Express Scripts operations in the United States deploy these systems to compress labor per script while maintaining accuracy thresholds. The technology is decomposing the historical trade-off between throughput speed and error reduction, enabling single-pass processing for complex multi-medication orders.
The EU AI Act's risk classification framework for medical device software is reshaping product development roadmaps for European automation vendors. Systems incorporating machine learning for dose verification or adverse interaction detection face heightened conformity assessment requirements. German and French hospital pharmacy buyers now prioritize suppliers with documented post-market surveillance protocols and algorithmic transparency documentation.
Subscription-based service models are displacing perpetual license structures in pharmacy automation procurement. Hospital systems in the United States and United Kingdom favor operational expenditure treatment for software and remote monitoring components, transferring obsolescence risk to vendors. This preference shift concentrates contract awards with suppliers possessing balance sheet capacity to finance hardware deployment against multi-year service commitments.
Global Pharmacy Automation Systems Market Segmentation
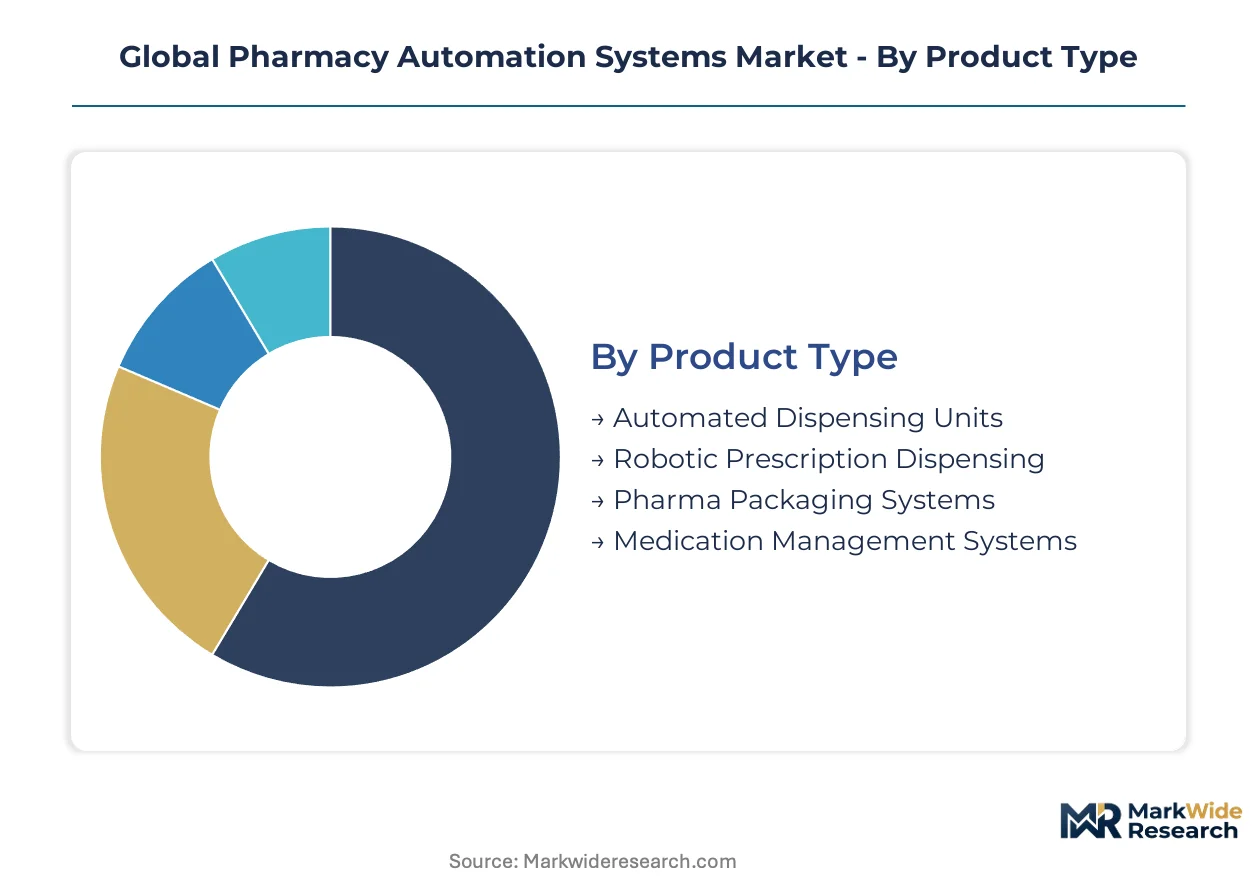
Pharmacy automation systems fragment across hardware, software, and service layers that face distinct regulatory scrutiny and capital deployment cycles. Buyers prioritize integrated stacks over point solutions as FDA serialization mandates and EMA authentication requirements reshape procurement specifications.
Product Type:
FDA Drug Supply Chain Security Act enforcement and EMA Falsified Medicines Directive compliance timelines differentiate capital allocation across hardware categories.
- Automated Dispensing Units:Electromechanical cabinets with 99.9% dispensing accuracy specifications and 300-plus prescriptions per hour throughput anchor hospital pharmacy workflows. United States integrated delivery networks bundle these with enterprise software contracts to satisfy Joint Commission medication management standards.
- Robotic Prescription Dispensing:Multi-axis robotic cells with precision servo motors occupy central-fill and mail-order facilities in North America and Europe. Germany's Hospital Future Act funding accelerates procurement for AI-enabled verification integration.
- Pharma Packaging Systems:Unit-dose and multi-dose adherence packaging equipment addresses labor scarcity in United States and Japanese long-term care settings.
- Medication Management Systems:Cloud-native software platforms enable remote fleet management and predictive maintenance for pharmacy chains prioritizing operational expenditure treatment.
Automated Dispensing Units handle the majority of throughput; Medication Management Systems is the fastest mover on share.
Technology:
Cost tier differentiation separates legacy barcode infrastructure from emerging AI and cloud-native architectures requiring distinct validation protocols.
- Barcode Technology:Linear and 2D symbology scanning systems dominate installed base value for prescription verification and inventory tracking. United States retail pharmacies deploy these for FDA track-and-trace compliance without the capital intensity of RFID infrastructure.
- Cloud-Based Solutions:Remote monitoring platforms with predictive maintenance algorithms enable recurring revenue streams that offset cyclical hardware sales. United Kingdom hospital systems favor operational expenditure treatment for these components.
- RFID Systems:Ultra-high frequency tags and readers support real-time medication tracking between automated dispensing cabinets and electronic health records.
- Artificial Intelligence:Machine learning algorithms for dose verification and adverse interaction detection face heightened EU AI Act conformity assessment requirements.
Barcode Technology carries the largest installed base; Cloud-Based Solutions are climbing the fastest on commercial traction.
End User:
Customer type concentration reflects labor cost structures and regulatory audit intensity across acute, ambulatory, and post-acute settings.
- Hospital Pharmacies:Centralized pharmacy operations in integrated delivery networks demand enterprise-wide automation contracts with closed-loop inventory management. Japan's aging pharmacist workforce accelerates robotic dispensing adoption as METI promotes productivity-focused healthcare investment.
- Retail Pharmacies:High-volume chains deploy computer vision systems for pill identification to compress labor per script while maintaining accuracy thresholds. CVS Health and Express Scripts operations in the United States lead central-fill automation deployment.
- Long-Term Care Facilities:Skilled nursing facilities in the United States and Japan invest in medication adherence packaging automation to address regulatory audit intensity.
- Compounding Pharmacies:Sterile and non-sterile compounding operations face distinct USP 797 and USP 800 engineering controls that limit automation penetration.
Hospital Pharmacies command the largest capital deployment; Long-Term Care Facilities are gaining share fastest on labor scarcity pressures.
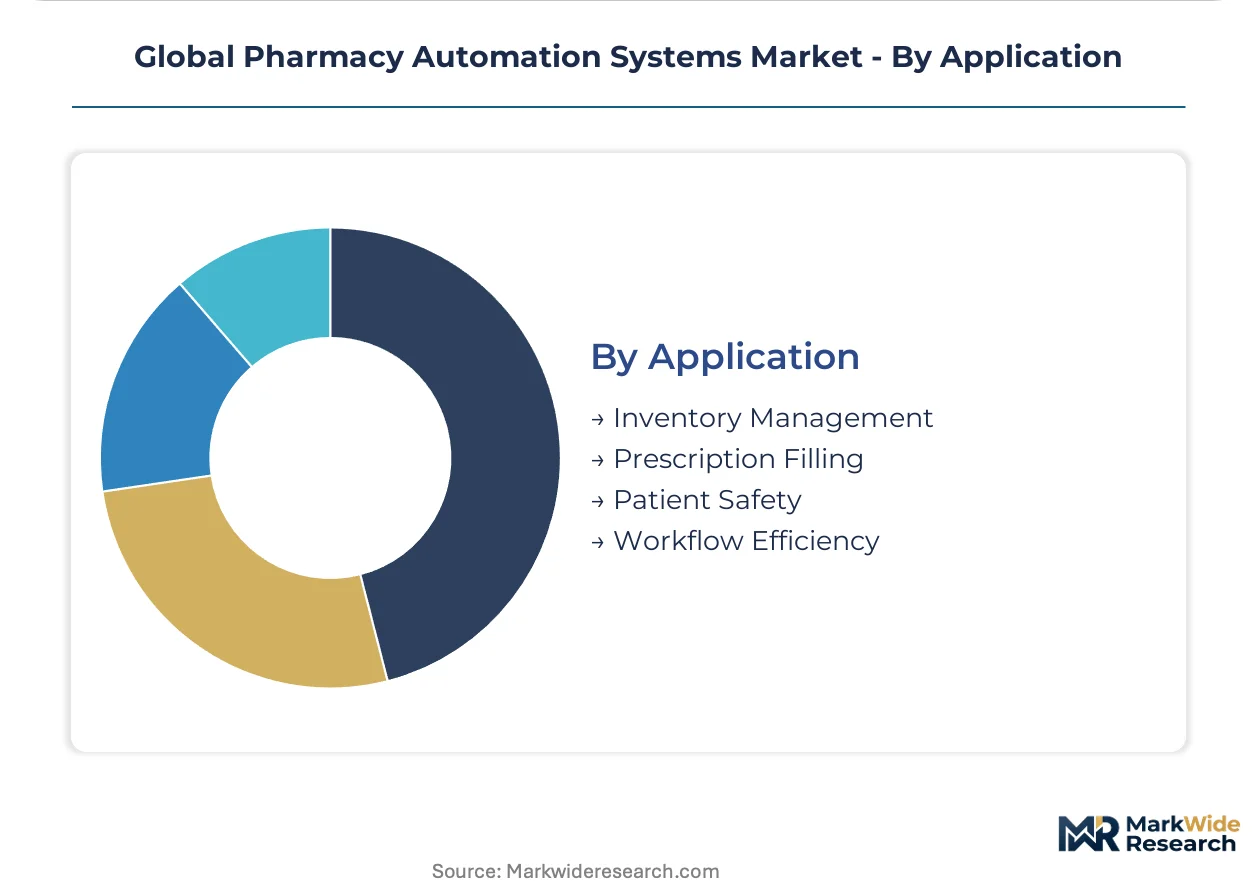
Application:
Maturity curves separate established inventory management automation from emerging patient safety and workflow efficiency platforms.
- Inventory Management:Real-time medication tracking integration between automated dispensing cabinets and electronic health records reduces diversion risk. EMA Falsified Medicines Directive mandates drive authentication infrastructure upgrades across European dispensaries.
- Prescription Filling:Robotic dispensing cells with throughput capacities exceeding 300 prescriptions per hour decompose manual verification workflows in mail-order environments.
- Patient Safety:AI-enabled dose verification systems face regulatory uncertainty around algorithmic validation standards that constrains deployment velocity.
- Workflow Efficiency:Cloud-native fleet management platforms transfer obsolescence risk to vendors through multi-year service commitments.
Inventory Management absorbs the majority of automation spend; Workflow Efficiency is expanding most quickly on subscription model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity diverges sharply across geographies. Hospital systems in the United States and Germany absorb premium automation costs to satisfy regulatory audit intensity, while retail chains in India and Southeast Asia defer capital deployment where labor arbitrage remains viable.
United States
Integrated delivery networks consolidate procurement around enterprise-wide automation contracts that bundle hardware, software, and multi-year service commitments. The FDA's Drug Supply Chain Security Act serialization mandates compel pharmaceutical distributors to upgrade track-and-trace infrastructure across retail and hospital dispensaries. The Research Triangle Park cluster in North Carolina anchors development of cloud-native medication management platforms serving national pharmacy chains.
Germany
The Hospital Future Act channels federal funding toward centralized pharmacy digitization, accelerating procurement for AI-enabled verification systems in academic medical centers. The EU Medical Device Regulation imposes conformity assessment requirements that favor established vendors with documented post-market surveillance protocols. The Baden-Württemberg industrial corridor around Stuttgart concentrates precision mechatronics engineering talent for robotic dispensing cell manufacturing.
Japan
METI productivity-focused healthcare investment incentives offset capital constraints as hospital pharmacies confront an aging pharmacist workforce approaching mass retirement. The PMDA imposes distinct software validation protocols that extend product launch timelines for non-domestic automation vendors. The Kansai region surrounding Osaka hosts concentrated demand from university hospitals upgrading to closed-loop inventory management systems.
United Kingdom
National Health Service trusts favor operational expenditure treatment for pharmacy automation, transferring obsolescence risk to vendors through subscription-based service models. The Medicines and Healthcare products Regulatory Agency aligns with EMA authentication requirements while maintaining distinct procurement frameworks for hospital pharmacy infrastructure. The Greater Manchester health innovation cluster pilots predictive maintenance platforms for automated dispensing cabinet fleets.
India
Manual pharmacy workflows persist across community retail and hospital settings where pharmacist labor costs remain low relative to capital-intensive automation investments. The Central Drugs Standard Control Organization advances track-and-trace regulations for pharmaceutical supply chains without mandating specific automation technologies. The Hyderabad-Visakhapatnam pharmaceutical manufacturing corridor generates ancillary demand for packaging automation serving export-oriented formulation facilities.
Global Pharmacy Automation Systems Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating tiered competitive dynamics. The vendor base stratifies around three strategic positions: distribution-integrated platform vendors bundling hardware with enterprise software contracts, robotics specialists occupying high-throughput central-fill installations, and cloud-native software providers capturing recurring revenue through remote fleet management services. Dominant competitive moves include strategic partnerships between automation hardware manufacturers and electronic health record vendors, plus geographic expansion through localized service subsidiaries to satisfy regional regulatory validation requirements.
Within the distribution-integrated tier, McKesson Corporation leverages captive pharmaceutical supply chain infrastructure to anchor enterprise automation contracts. Among robotics specialists, Swisslog Healthcare occupies positions in North American and European central-fill facilities. On the software-centric vector, Omnicell exemplifies the shift toward cloud-native architectures and predictive maintenance platforms that transfer capital risk from hospital buyers to vendors.
| Leading Market Players |
|---|
| ScriptPro |
| McKesson Corporation |
| Omnicell |
| Swisslog Healthcare |
| Becton, Dickinson and Company |
| Capsa Healthcare |
| ARxIUM |
| RxSafe |
| Parata Systems |
| Others |
Value Chain & Pricing Dynamics
Multi-year service contracts with embedded hardware financing lock in supply access for hospital pharmacy automation buyers while compressing vendor margins through operational expenditure treatment. United States integrated delivery networks and United Kingdom NHS trusts favor these structures to transfer obsolescence risk to suppliers while securing predictable lifecycle costs for robotic dispensing infrastructure.
Pricing Analysis
After-sales service and predictive maintenance subscriptions now drive lifetime value for pharmacy automation vendors, displacing perpetual license structures. Three-tier pricing structure across premium, standard, and economy levels separates AI-enabled verification platforms from legacy barcode systems and refurbished hardware tiers. Cost compression in robotic dispensing hardware is intensifying because stainless steel and precision servo motor input volatility squeezes equipment manufacturers without captive component sourcing. Retail pharmacy chains in India and Southeast Asia exhibit the highest price sensitivity, while German hospital systems under Hospital Future Act funding absorb premium costs for centralized pharmacy digitization.
Supply Chain Analysis
Precision servo motor fabrication in Germany, Japan, and Taiwan anchors throughput capacity for robotic dispensing cells deployed across North American and European central-fill facilities. Supply chains for pharmacy automation hardware draw from specialized mechatronics engineering clusters in Baden-Württemberg and Osaka-Kansai, with cloud-native software development concentrating in North Carolina's Research Triangle Park. Single-source vulnerability in precision motion control components creates procurement risk for vendors lacking backward integration into motor manufacturing. Distribution runs through pharmaceutical supply chain intermediaries that bundle automation hardware with enterprise software and multi-year service commitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pharmacy automation market sits in a post-pandemic capital replacement cycle as hospital pharmacy consolidation and FDA serialization mandates force infrastructure upgrades. This cyclical recovery favors vendors with balance sheet capacity to finance hardware deployment against recurring service revenue streams.
For Market Incumbents: Fortify enterprise contract positions by embedding predictive maintenance platforms into multi-year hospital pharmacy automation agreements. Cloud-native software specialists threaten hardware-centric vendors through operational expenditure treatment preferences; counter by deepening backward integration into precision mechatronics components and securing Joint Commission-compliant certification tiers that lock out non-validated competitors. For New Entrants and Emerging Players: Differentiate on AI-enabled prescription verification systems that satisfy EU AI Act conformity assessment requirements with documented algorithmic transparency. Long-term care facilities in Japan and the United States represent the most penetrable segment on labor scarcity pressures; pursue direct partnerships with skilled nursing facility operators bypassing incumbent hospital-focused distribution channels. For Investors and Strategic Acquirers: The market sits at a vendor consolidation phase that favors platform-integrated automation suppliers with recurring revenue foundations. Five-to-ten-year viability hinges on cloud-native architecture adoption and regulatory validation depth rather than hardware throughput specifications alone. Acquisition targets should demonstrate FDA track-and-trace compliance roadmaps and post-market surveillance protocols for machine learning components. Watch PMDA software validation protocol harmonization efforts as the inflection signal for Japanese market access expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Enables recurring revenue streams that offset cyclical hardware sales dependence for pharmacy chains. |
| AI Verification System Certification | Satisfies EU AI Act conformity assessment requirements that German hospital buyers now prioritize. |
| Backward Integration into Servo Motors | Reduces input cost volatility exposure for robotic dispensing hardware manufacturers. |
| Long-Term Care Partnership Development | Captures medication adherence packaging demand from skilled nursing facilities in Japan and the United States. |
| PMDA Validation Protocol Investment | Accelerates product launch timelines for non-domestic vendors targeting Japanese hospital pharmacies. |
Study Parameters
Operator-level perspectives from hospital pharmacy directors, biomedical engineers, GPO contracts managers, and pharmaceutical supply chain executives anchored the qualitative base for this analysis. Primary interviews combined with secondary validation from FDA Drug Supply Chain Security Act enforcement documentation, EMA Falsified Medicines Directive compliance timelines, and hospital procurement database records. SEC 10-K filings from publicly traded automation vendors and METI healthcare investment incentive disclosures provided financial and strategic context. Bottom-up installation base modeling and top-down market sizing triangulated volume and value estimates.
Sensitivity analysis across deployment scale, regulatory compliance tier, and service contract structure tested forecast robustness over the projection horizon. Segmentation dimensions modeled include product type, technology architecture, end-user setting, and application function, with regional regulatory cluster as an additional pharmacy-specific dimension. CAGRs derived from installed base replacement cycles, greenfield adoption curves, and technology substitution rates. Forecast inputs incorporated PMDA software validation timeline assumptions and EU AI Act risk classification implementation pace.
Material uncertainties — regulatory clarity on algorithmic validation standards, precision component input cost trajectories, and hospital pharmacy consolidation velocity — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding FDA serialization mandate enforcement timing and METI incentive program continuity. Revision becomes warranted when AI/ML regulatory framework harmonization crosses implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Global Contract Development and Manufacturing Organization (CDMO) Outsourcing Market
Pharmaceutical Equipment
Malaysia Pharmacy Automation Market
Pharmaceutical Equipment
Interlock Vials Market
Pharmaceutical Equipment
Global Pharmaceutical Cartridges Market
Pharmaceutical Equipment
Asia-Pacific CDMO Market
Pharmaceutical Equipment
Vials and Ampoules Market
Pharmaceutical Equipment
China Pharmaceutical Warehousing Market
Pharmaceutical Equipment
Serum Vials Market
Pharmaceutical Equipment
Pharmaceutical Glass Ampoules Market
Pharmaceutical Equipment
Middle East and Africa Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
North America Unit Dose Manufacturing Market
Pharmaceutical Equipment
Pharmacy Automation Market
Pharmaceutical Equipment
Global Fill Finish Manufacturing Market
Pharmaceutical Equipment
Pharmaceutical Sterilization Equipment Market
Pharmaceutical Equipment
Global Pharmaceutical Isolator Market
Pharmaceutical Equipment
Aseptic Negative Pressure Pharmaceutical Isolators Market