
 Europe Pharmacy Automation Market | 2026-2036
Europe Pharmacy Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Pharmacy Automation Market Foresight
Buyer concentration among hospital pharmacy groups is broadening across Europe as national health systems consolidate procurement under centralized tenders. Omnicell Inc. leverages its installed base of automated dispensing cabinets to secure multi-year service contracts with regional hospital networks. McKesson Corporation anchors its position through distribution infrastructure that bundles automation hardware with pharmaceutical supply agreements. Swisslog Healthcare AG specializes in robotic material handling systems tailored to European hospital layouts and regulatory requirements.
Europe pharmacy automation encompasses electromechanical systems, software platforms, and sensor networks engineered to dispense, verify, track, and manage pharmaceutical inventories with minimal human intervention; these systems typically integrate barcode scanners, weight verification modules, and robotic pick-and-place mechanisms operating at throughputs exceeding 200 prescriptions per hour. Automated dispensing systems dominate current installed capacity across hospital pharmacies, while AI-driven analytics represents the fastest-expanding technology layer as pharmacies seek predictive inventory optimization. Retail pharmacies retain the largest end-user share by volume, though compounding pharmacies command superior margins due to stringent sterility and traceability requirements.
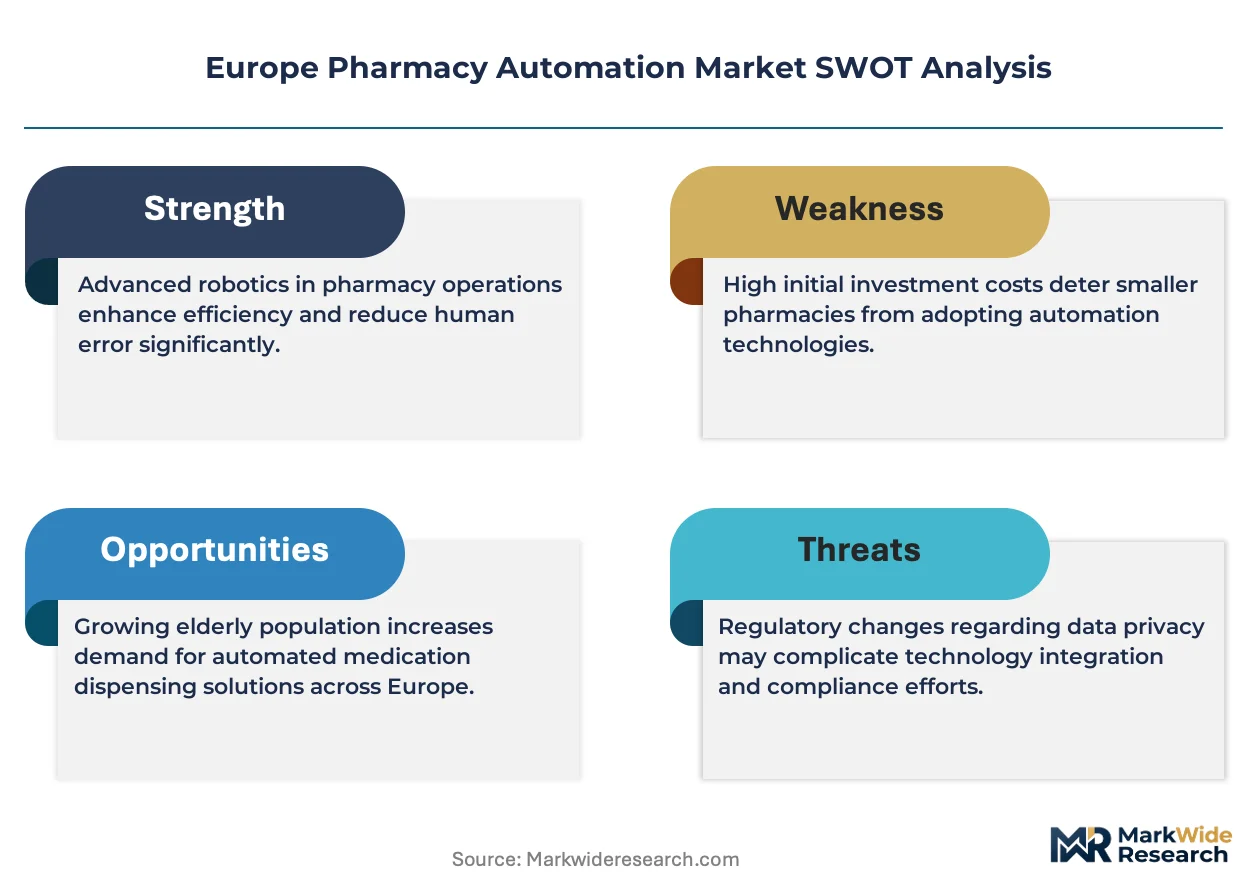
The EU Medical Device Regulation and CE marking framework govern hardware certification, while the Falsified Medicines Directive mandates serialization and verification infrastructure that directly drives barcode and RFID technology adoption. National regulators including Germany's BfArM and France's ANSM enforce pharmacy practice standards that increasingly specify automation for high-risk medication processes. Stakeholders must monitor how the EU AI Act's risk classification rules will reshape algorithmic prescription validation and clinical decision-support tools.
Market Dynamics
Hospital pharmacy consolidation across Germany, France, and the United Kingdom is compressing vendor margins while amplifying contract scale requirements. Centralized procurement frameworks now bundle automation hardware with decade-long service commitments.
Growth Catalysts
- EU Medical Device Regulation:MDR compliance deadlines are compelling hospital pharmacies to replace legacy dispensing equipment with certified automated systems before 2027 enforcement windows.
- Robotic dispensing cabinets:German hospital networks are accelerating deployment of these systems to address persistent pharmacist staffing shortages in acute care settings.
- Falsified Medicines Directive:Serialization mandates across EU member states are driving barcode and RFID infrastructure investments into retail and hospital pharmacies alike.
Market Restraints
- Capital intensity:Automated dispensing systems require upfront investment exceeding €500,000 per installation, freezing out independent community pharmacies.
- Component concentration:Precision servo motors and optical sensors depend heavily on East Asian suppliers, exposing lead times to geopolitical friction.
- Interoperability gaps:Legacy hospital information systems in France and Italy lack standardized APIs, forcing costly middleware development.
Strategic Opportunities
- Nordic pharmacy chains:Sweden and Denmark's digitally integrated retail networks remain underpenetrated by robotic dispensing relative to hospital saturation.
- AI-driven inventory optimization:Machine learning modules layered atop dispensing hardware enable predictive stock management in high-volume hospital settings.
- Compounding pharmacy automation:Sterile preparation robotics address EU GMP Annex 1 requirements for cytotoxic and biologic medication handling.
Industry Challenges
- Clinical informatics expertise:Pharmacy automation deployment requires hybrid professionals fluent in both pharmaceutical workflows and systems integration.
- CE marking timeline:MDR technical documentation review periods now stretch 18-24 months, delaying product launches.
- Legacy system entrenchment:Proprietary data formats in incumbent dispensing cabinets complicate competitive displacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Pharmacy Automation Market |
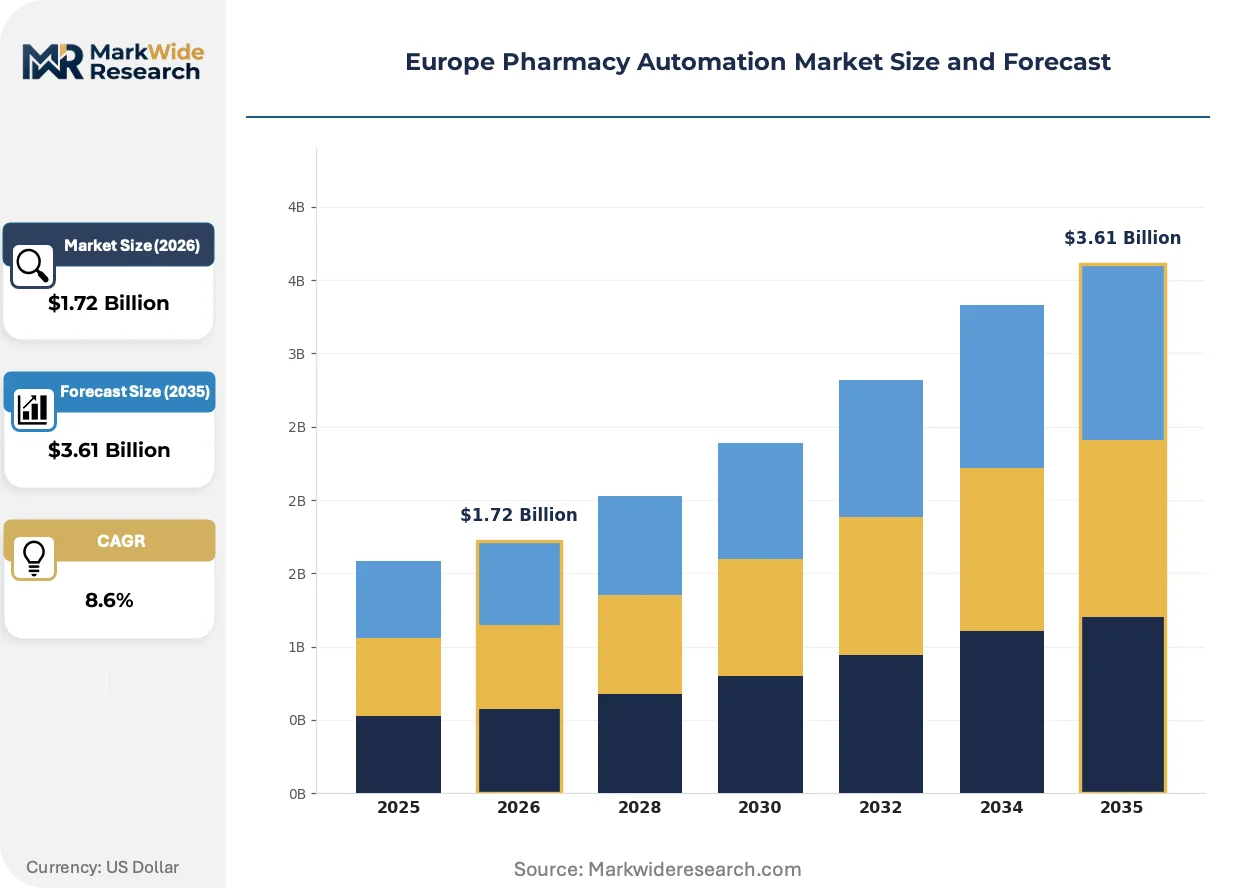
| Market Size in 2026 | $1.72 Billion |
| Market Size in 2035 | $3.61 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Dispensing Systems, Smart Medication Management, Robotic Prescription Filling, Inventory Management Solutions End User: Retail Pharmacies, Hospital Pharmacies, Long-term Care Facilities, Compounding Pharmacies Technology: Barcode Verification, RFID Tracking, Cloud-based Solutions, AI-driven Analytics Application: Prescription Management, Inventory Control, Workflow Optimization, Patient Safety Enhancement |
| Companies Covered | OMNICELL INC., McKesson Corporation, Capsa Healthcare, ScriptPro LLC, BD, Swisslog Healthcare AG, Deenova S.r.l., Willach Group, Cerner Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Pharmacy Automation Market Shifts & Advancements
Artificial intelligence and machine vision are penetrating prescription verification workflows, reducing human oversight requirements while tightening error detection. Hardware vendors now compete on software sophistication rather than mechanical throughput alone.
Machine vision systems equipped with deep learning algorithms are automating pill identification and counting in high-volume dispensing operations. Hospital pharmacies in Germany and the Netherlands are adopting these systems fastest, driven by labor cost pressures. The technology is automating quality control steps that previously required dual pharmacist verification, compressing staffing models.
The EU AI Act's risk classification framework is reshaping algorithmic prescription validation tools as high-risk medical devices. Developers must now implement post-market surveillance and human oversight protocols for clinical decision-support functions. French and German hospital pharmacies are delaying procurement of AI-enabled verification modules pending notified body guidance.
Consolidated procurement through regional hospital networks is displacing single-site purchasing autonomy across Continental Europe. Tender specifications now mandate interoperability with existing electronic health record infrastructure and multi-year total cost of ownership guarantees. This pattern concentrates most visibly in the United Kingdom's NHS Integrated Care Systems and Spain's autonomous community health services.
Europe Pharmacy Automation Market Segmentation
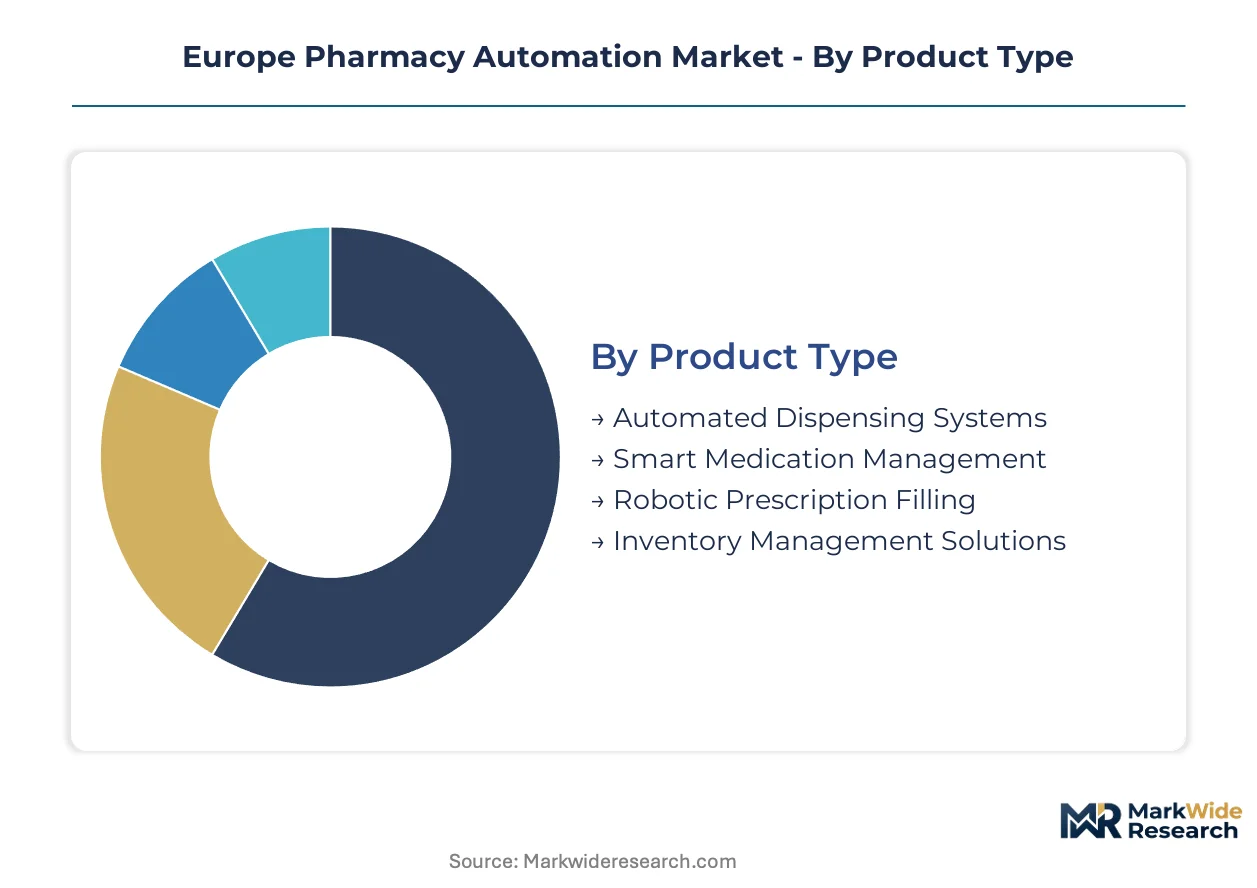
Pharmacy automation procurement patterns diverge sharply across hardware categories, end-user settings, and technology layers. Understanding these segment boundaries reveals where vendor margins concentrate and which integration pathways hospitals prioritize.
Product Type:
Electromechanical sophistication and throughput capacity differentiate hardware tiers across European hospital networks.
- Automated Dispensing Systems:Robotic cabinets with multi-cell storage and pick-and-place mechanisms dominate acute care installations. German hospital networks deploy these systems most aggressively to address pharmacist staffing gaps in Berlin and Munich metropolitan clusters.
- Smart Medication Management:Software-integrated platforms connecting dispensing hardware to electronic health records enable real-time inventory visibility. France's ANSM guidelines increasingly specify these systems for high-risk medication workflows in university hospitals.
- Robotic Prescription Filling:High-throughput systems processing 200+ prescriptions hourly utilize machine vision for pill verification. Nordic retail chains adopt these for centralized fulfillment.
- Inventory Management Solutions:Sensor networks and weight-based tracking modules reduce stockout incidents. These systems gain traction in UK hospital trusts pursuing NHS efficiency targets.
Mature deployment sits with automated dispensing cabinets in German acute care. Newer deployment is concentrated in cloud-integrated inventory management across Nordic retail networks.
End User:
Procurement scale and regulatory stringency create four distinct customer archetypes with diverging automation roadmaps.
- Retail Pharmacies:High-volume dispensing chains in Sweden and Denmark drive demand for compact robotic systems. Labor cost pressures and 24-hour service mandates accelerate replacement of manual workflows.
- Hospital Pharmacies:Consolidated procurement through regional networks in the United Kingdom and Spain bundles automation hardware with decade-long service contracts. These buyers command superior vendor attention and pricing leverage.
- Long-term Care Facilities:Medication adherence packaging and blister card automation address polypharmacy management. Deployment concentrates in Benelux countries with aged care infrastructure investments.
- Compounding Pharmacies:Sterile preparation robotics for cytotoxic and biologic medications command premium pricing. EU GMP Annex 1 compliance requirements in France and Germany drive specialized system adoption.
Revenue concentration favors hospital pharmacy networks. Margin expansion is steepest in compounding pharmacy robotics.
Technology:
Verification and tracking modalities layer atop mechanical hardware to create differentiated value propositions.
- Barcode Verification:Linear and 2D symbology scanning satisfies Falsified Medicines Directive serialization mandates. This infrastructure now saturates retail pharmacies across EU member states.
- RFID Tracking:Item-level tagging enables real-time location systems for high-value biologics. Hospital pharmacies in the Netherlands deploy these for cold chain integrity monitoring.
- Cloud-based Solutions:Remote monitoring and predictive maintenance platforms reduce on-site technical staffing. UK NHS Integrated Care Systems favor these for multi-site pharmacy oversight.
- AI-driven Analytics:Machine learning modules optimize par levels and expiration management. German hospital pharmacies pilot these systems fastest, though EU AI Act risk classification delays broader procurement.
Barcode verification represents baseline infrastructure. AI-driven analytics is climbing the fastest as pharmacies seek predictive inventory capabilities.
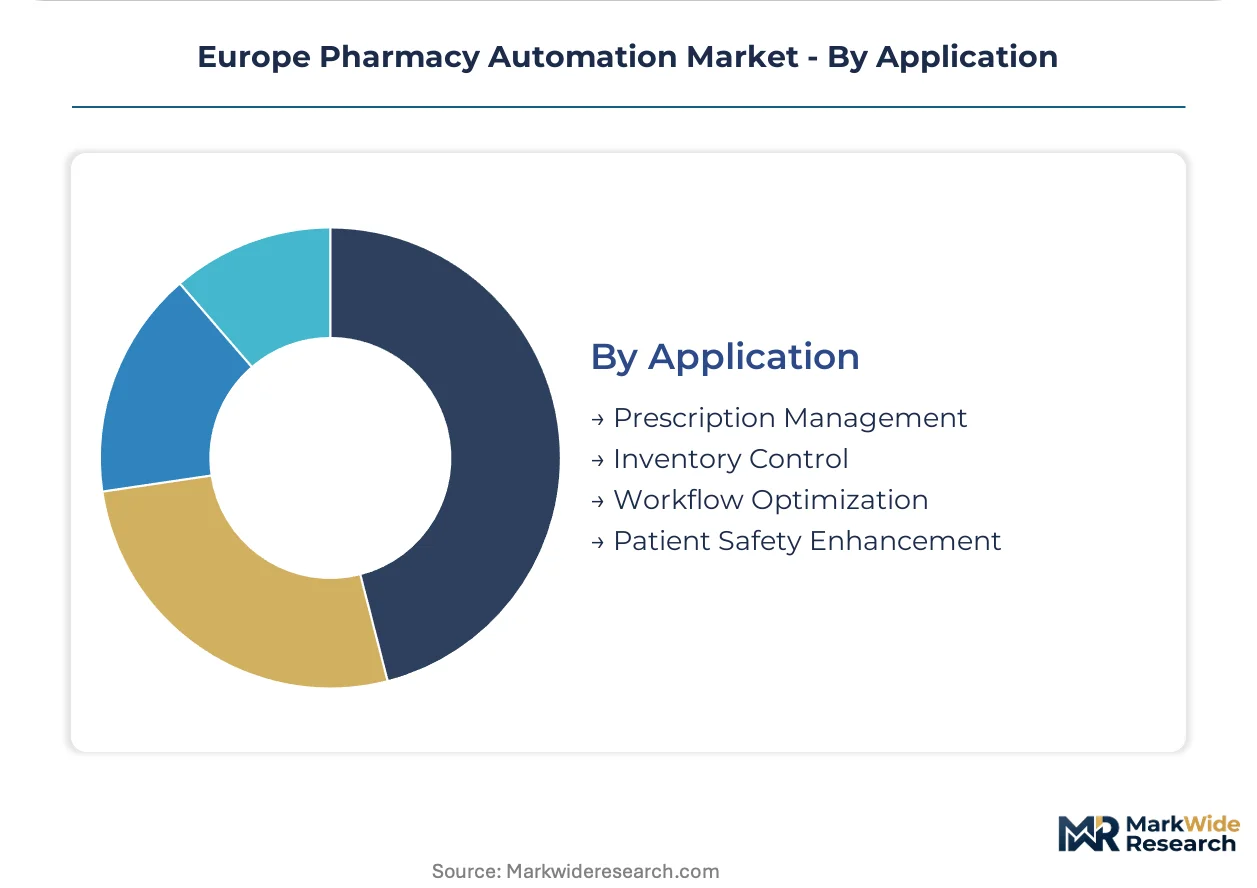
Application:
Functional use cases determine integration complexity and return-on-investment timelines for automation investments.
- Prescription Management:End-to-end automation from order intake through patient counseling documentation. French hospital pharmacies prioritize these workflows for error reduction.
- Inventory Control:Automated replenishment and expiry date tracking reduce carrying costs. German regional pharmacy networks achieve measurable working capital improvements.
- Workflow Optimization:Task sequencing and staff routing algorithms compress prescription turnaround times. These applications gain traction in UK community pharmacy chains.
- Patient Safety Enhancement:Double-verification robotics and allergy alert integration address liability concerns. Scandinavian hospital systems mandate these capabilities for high-alert medications.
Workflow optimization commands investment in retail settings. Patient safety enhancement dominates hospital pharmacy procurement specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision servo motor supply chains from Bavaria and Baden-Württemberg anchor hardware manufacturing for European pharmacy automation. Component fabrication clusters in southern Germany feed assembly lines serving hospital networks across the continent.
Germany
Hospital pharmacy consolidation in Berlin and Munich metropolitan clusters drives robotic dispensing cabinet procurement. BfArM enforcement of EU MDR compliance deadlines accelerates replacement of legacy equipment in acute care settings. The Rhine-Ruhr corridor hosts dense networks of university hospitals deploying automated inventory management systems.
United Kingdom
NHS Integrated Care Systems bundle decade-long automation service contracts with regional procurement frameworks. The Falsified Medicines Directive serialization mandates push barcode verification infrastructure into community pharmacy chains. London and Southeast England concentrate pilot deployments of AI-driven prescription validation tools pending regulatory clarity.
France
ANSM guidelines increasingly specify automation for high-risk medication workflows in university hospitals. The EU AI Act risk classification framework delays procurement of algorithmic verification modules as notified bodies issue guidance. The Île-de-France region anchors sterile compounding robotics adoption for cytotoxic preparation under EU GMP Annex 1.
Sweden
Digitally integrated retail pharmacy chains drive demand for compact robotic dispensing systems addressing 24-hour service mandates. Labor cost pressures in Stockholm and Gothenburg accelerate replacement of manual prescription workflows. The country's centralized health data infrastructure enables cloud-integrated inventory management across pharmacy networks.
Netherlands
Hospital pharmacies deploy RFID tracking systems for cold chain integrity monitoring of high-value biologics. The country's dense hospital network in the Randstad region prioritizes interoperability with electronic health record infrastructure. Dutch regulators enforce stringent pharmacy practice standards that specify automation for medication error reduction.
Europe Pharmacy Automation Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue AI-driven analytics and cloud-native inventory platforms. The vendor base stratifies across three tiers: multinational healthcare technology conglomerates with installed base leverage, regional specialists in robotic material handling, and software-first entrants targeting predictive maintenance. Consolidation pressure from hospital procurement centralization favors scale players with service infrastructure. Competitive moves concentrate on multi-year service contract capture and middleware development for legacy system integration.
Within the installed-base tier, Omnicell Inc. and McKesson Corporation exemplify vendors leveraging hardware-service bundling to secure regional hospital network relationships. Swisslog Healthcare AG occupies a position among European specialists tailoring robotic systems to local regulatory requirements and hospital layout constraints. These three anchors represent divergent strategic postures: North American conglomerate scale, distribution-integrated automation, and European engineering specialization.
| Leading Market Players |
|---|
| OMNICELL INC. |
| McKesson Corporation |
| Capsa Healthcare |
| ScriptPro LLC |
| BD |
| Swisslog Healthcare AG |
| Deenova S.r.l. |
| Willach Group |
| Cerner Corporation |
| Others |
Supply & Pricing Matrix
Centralized tender frameworks across NHS Integrated Care Systems and German regional hospital networks now mandate decade-long service bundling with automation hardware, compelling vendors to absorb upfront capital costs into recurring revenue models and compressing margins on unbundled equipment sales.
Pricing Analysis
Extended warranty and predictive maintenance clauses now anchor contract negotiations rather than hardware unit costs. Three-tier pricing structure across premium, standard, and economy levels separates CE-MDR certified systems with AI validation modules from basic barcode-enabled cabinets and refurbished legacy units. Price differentiation rests on software integration depth and multi-site service coverage radius. Cost compression in the standard tier is intensifying because Nordic retail chains are consolidating procurement through centralized pharmacy cooperatives. Independent community pharmacies exhibit highest price sensitivity, while university hospital networks in France and Germany prioritize total cost of ownership guarantees over acquisition price.
Supply Chain Analysis
Refurbishment flows for robotic dispensing cabinets now cycle through Swisslog Healthcare AG's Baden-Württemberg service centers and Omnicell Inc.'s Netherlands redistribution hubs, extending asset lifecycles and dampening new equipment demand. Precision servo motor fabrication concentrates in Germany, Switzerland, and Japan, while optical sensor modules draw from South Korean and Taiwanese semiconductor foundries. Single-source vulnerability sits with rare-earth magnet suppliers for high-torque dispensing actuators. Distribution runs through regional hospital procurement consortia and GPO-affiliated pharmacy networks rather than direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Component lead times for precision motion control systems now stretch eighteen months, propping pricing power for vendors with captive inventory positions and service infrastructure already deployed across buyer networks.
For Market Incumbents: Anchor defensive positioning through backward integration into sensor module calibration capabilities and predictive maintenance software stacks. Consolidate service infrastructure across Benelux and Nordic regions before emerging cloud-native entrants achieve interoperability certifications. The threat of AI-first software vendors unbundling analytics from hardware hardware demands preemptive API standardization investment. For New Entrants and Emerging Players: Begin with sterile compounding robotics for cytotoxic preparation workflows in French and German hospital pharmacies, where EU GMP Annex 1 compliance requirements create certification barriers that slow incumbent response. Nordic retail pharmacy chains present the most penetrable geography due to digitized procurement platforms and 24-hour service mandates. A software-first go-to-market angle emphasizing cloud-integrated inventory optimization bypasses capital-intensive hardware manufacturing. For Investors and Strategic Acquirers: The window for entry favors mid-cap specialists with established CE marking dossiers and installed bases in secondary European markets. Long-term viability hinges on regulatory navigation capabilities rather than mechanical engineering differentiation alone. The signal to watch is EU AI Act notified body guidance on algorithmic prescription validation risk classification, which will determine whether AI-enabled modules command premium pricing or face procurement delays.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR technical documentation review periods now stretch 18-24 months, delaying competitive launches. |
| Hospital System Partnership | NHS Integrated Care Systems bundle decade-long service contracts with regional procurement frameworks. |
| Software Companion Development | Machine learning modules for predictive inventory optimization command fastest-expanding technology layer demand. |
| Reimbursement Strategy | National health system efficiency targets in Germany and UK convert automation savings into contract renewal leverage. |
| Strategic Partnership | Interoperability middleware development with legacy hospital information system vendors unlocks French and Italian procurement. |
Research Methodology
Multi-period observation of robotic dispensing cabinet deployment rates, pharmacist staffing ratios, and MDR compliance substitution patterns anchored the trend analysis, supplemented by interviews with hospital pharmacy directors, GPO contracts managers, biomedical engineers, and regulatory affairs leads at automation vendors. Secondary validation drew from EMA medical device databases, BfArM and ANSM enforcement notices, NHS procurement disclosure registers, and hospital capital expenditure filings. Bottom-up installation tracking across German university hospital networks and top-down market sizing through pharmaceutical distribution channel analysis enabled triangulation.
Segment-weighting applied differential growth assumptions across hardware categories, end-user settings, and technology layers with hospital pharmacy consolidation velocity and retail chain digitization maturity as cross-cutting modifiers. CAGRs were derived from installed base expansion curves and replacement cycle compression in acute care settings. Modeled inputs included EU AI Act implementation timelines, Falsified Medicines Directive serialization compliance deadlines, and regional labor cost trajectories affecting automation payback calculations.
Regulatory enforcement delays, component supply disruptions, and hospital budget freeze decisions are the dominant revision risks to projection assumptions. Forecasts reflect documented baseline scenarios with explicit sensitivity ranges around MDR transition timing and AI risk classification outcomes. Practitioners should monitor notified body guidance publication schedules and East Asian semiconductor export control developments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Pharmaceutical Manufacturing Market
Pharmaceutical Equipment
Global Contract Development and Manufacturing Organization (CDMO) Outsourcing Market
Pharmaceutical Equipment
Vial Adaptors for Reconstitution Drug Market
Pharmaceutical Equipment
Cryogenic Ampoules Market
Pharmaceutical Equipment
Pharmaceutical Anti-Counterfeiting Technologies Market
Pharmaceutical Equipment
Latin America Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Tablet Press Market
Pharmaceutical Equipment
ASEAN Contract Development and Manufacturing Organization (CDMO) Market
Pharmaceutical Equipment
Pharmaceutical Continuous Manufacturing Market
Pharmaceutical Equipment
Closed Funnel Ampoules Market
Pharmaceutical Equipment
Pharmaceutical Incubators Market
Pharmaceutical Equipment
Global Pharmaceutical Contract Manufacturing and Contract Research Market
Pharmaceutical Equipment
Lyophilization Equipment Market
Pharmaceutical Equipment
Medication Dispenser Market
Pharmaceutical Equipment
Asia-Pacific Pharmaceutical Isolator Market
Pharmaceutical Equipment
Pharmaceutical Track and Trace Systems Market