
 Pharmaceutical Equipment Market | 2026-2036
Pharmaceutical Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Equipment Market Outlook
Direct-to-biotech distribution channels is reconfiguring how pharmaceutical equipment reaches end users, bypassing traditional multi-tier distributors in favor of embedded service contracts. GEA Group leverages its integrated process technology portfolio to anchor long-term partnerships with monoclonal antibody producers. Sartorius AG specializes in single-use systems that reduce cross-contamination risk in multi-product facilities. ACG Worldwide competes on cost-engineered fill-finish lines tailored for emerging-market generic manufacturers.
Pharmaceutical equipment encompasses machinery designed for drug formulation, processing, packaging, and quality control, typically constructed from 316L stainless steel with surface finishes below 0.8 micrometers Ra to meet cleanroom standards and prevent microbial adhesion. Its primary purpose is to ensure batch consistency, sterility assurance, and regulatory compliance across small-molecule and biologic manufacturing. Fill-finish equipment captures the deepest margin pools as aseptic processing complexity rises with biologics growth. Integrated systems are displacing standalone units as manufacturers pursue continuous processing and real-time release testing. Solid dosage machinery remains mature, with replacement cycles driving revenue rather than capacity expansion.
FDA enforcement of updated Annex 1 sterile manufacturing standards is accelerating capital expenditure on isolator-based filling lines and closed-system processing equipment. EMA's Medical Device Regulation and ISO 14644 cleanroom classifications further constrain supplier qualification, favoring vendors with established regulatory dossiers. The EU AI Act introduces documentation requirements for automated visual inspection systems that use machine learning algorithms. Stakeholders must monitor how FDA draft guidance on continuous manufacturing equipment validation reshapes supplier-customer contracting models and service revenue attachment rates.
Market Dynamics
Biologics manufacturing is forcing capital reallocation toward aseptic fill-finish systems as monoclonal antibody pipelines expand and FDA Annex 1 compliance deadlines tighten across installed equipment bases.
Growth Catalysts
- FDA Annex 1 Enforcement:Mandatory isolator upgrades and closed-system processing investments are pulling forward replacement cycles for legacy open-filling lines in sterile injectable facilities.
- Single-Use Technology Adoption:Biologics manufacturers are deploying disposable bioreactor and fluid pathway systems to eliminate cross-contamination risk in multi-product CDMO operations.
- German Precision Engineering Cluster:Concentrated supplier capabilities around Stuttgart and Karlsruhe are shortening equipment qualification timelines for global pharma clients requiring rapid capacity scaling.
Market Restraints
- 316L Stainless Steel Price Volatility:Electropolished vessel and piping raw material costs fluctuate with nickel and molybdenum commodity markets, compressing fabrication margins on fixed-price contracts.
- Specialized Welding Labor Scarcity:ASME Section IX-certified orbital welders for high-purity pharmaceutical piping remain concentrated in Central European and North American labor pools with limited expansion capacity.
- Legacy Equipment Stranding:Depreciated but functional stainless steel tank farms and open-filling lines face accelerated obsolescence under revised sterility assurance expectations without salvage value recovery.
Strategic Opportunities
- Indian Generic API-to-Finished-Dose Integration:Domestic manufacturers are backward-integrating into formulation equipment to capture margin from CDMO outsourcing trends in oral solid dosage.
- Continuous Manufacturing Equipment Validation:FDA draft guidance on real-time release testing is creating first-mover advantage for suppliers offering integrated powder-to-tablet processing lines with embedded PAT sensors.
- EU AI Act Documentation Requirements:Automated visual inspection systems using machine learning algorithms require requalification support services, opening recurring revenue streams for equipment vendors with regulatory dossier capabilities.
Industry Challenges
- ASME BPE and ISO 14644 Certification Bottlenecks:Third-party cleanroom and surface finish validation timelines extend equipment delivery schedules by four to eight months, straining project cash flow.
- Legacy DCS Integration Complexity:Brownfield facilities running proprietary distributed control systems face protocol mismatches when connecting new skids for continuous processing upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Equipment Market |
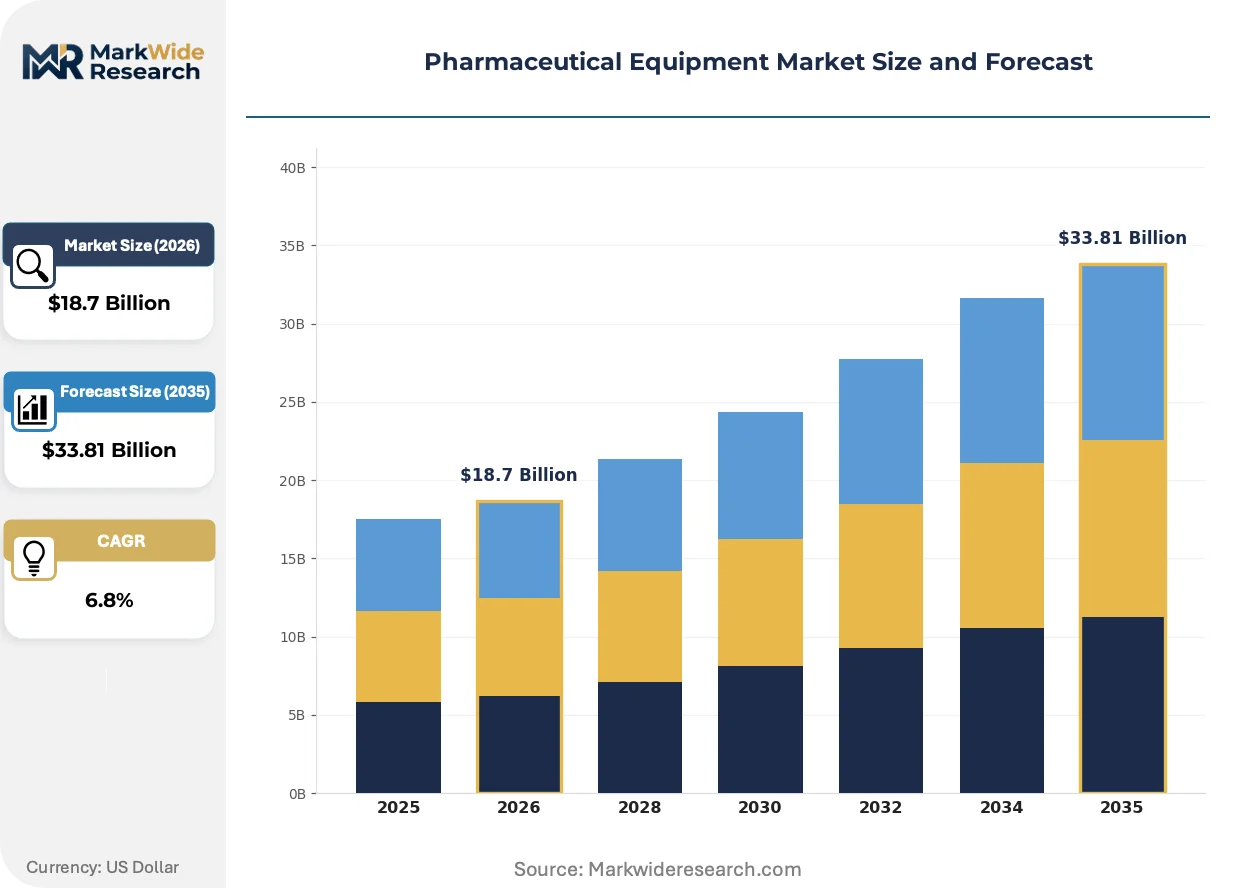
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fill-Finish Equipment, Packaging Machines, Labeling Machines, Lyophilizers Technology: Automatic, Semi-Automatic, Manual, Integrated Systems End User: Pharmaceutical Manufacturers, Contract Manufacturing Organizations, Research Laboratories, Biotechnology Companies Application: Solid Dosage, Liquid Dosage, Sterile Products, Biologics |
| Companies Covered | GEA Group, Syntegon Technology, IMA Group, Sartorius AG, Fette Compacting, Bausch+Ströbel, ACG Worldwide, Glatt, Romaco Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Equipment Market Strategic Shifts
Equipment architectures are converging around modularity and data integration as manufacturers abandon fixed stainless steel trains in favor of flexible, reconfigurable production platforms.
Isolator-based filling technology is rendering obsolete open Restricted Access Barrier Systems in aseptic processing. Contract development and manufacturing organizations are specifying integrated isolator lines for new biologics capacity. This technology is rendering obsolete the three-year validation cycles associated with conventional cleanroom-based filling operations.
EMA's Medical Device Regulation and updated ISO 14644 cleanroom classifications are tightening supplier qualification requirements. Equipment vendors must maintain current technical documentation and quality management system certifications to remain on approved vendor lists. Aseptic filling line manufacturers serving European markets are absorbing compliance costs through extended service contract pricing.
Biologics producers are unbundling equipment procurement from multi-year service agreements. CDMOs are negotiating separate performance-based maintenance contracts with specialized third-party service providers. This pattern is most visible in German and Swiss manufacturing clusters where equipment utilization rates drive total cost-of-ownership calculations.
Pharmaceutical Equipment Market Segmentation
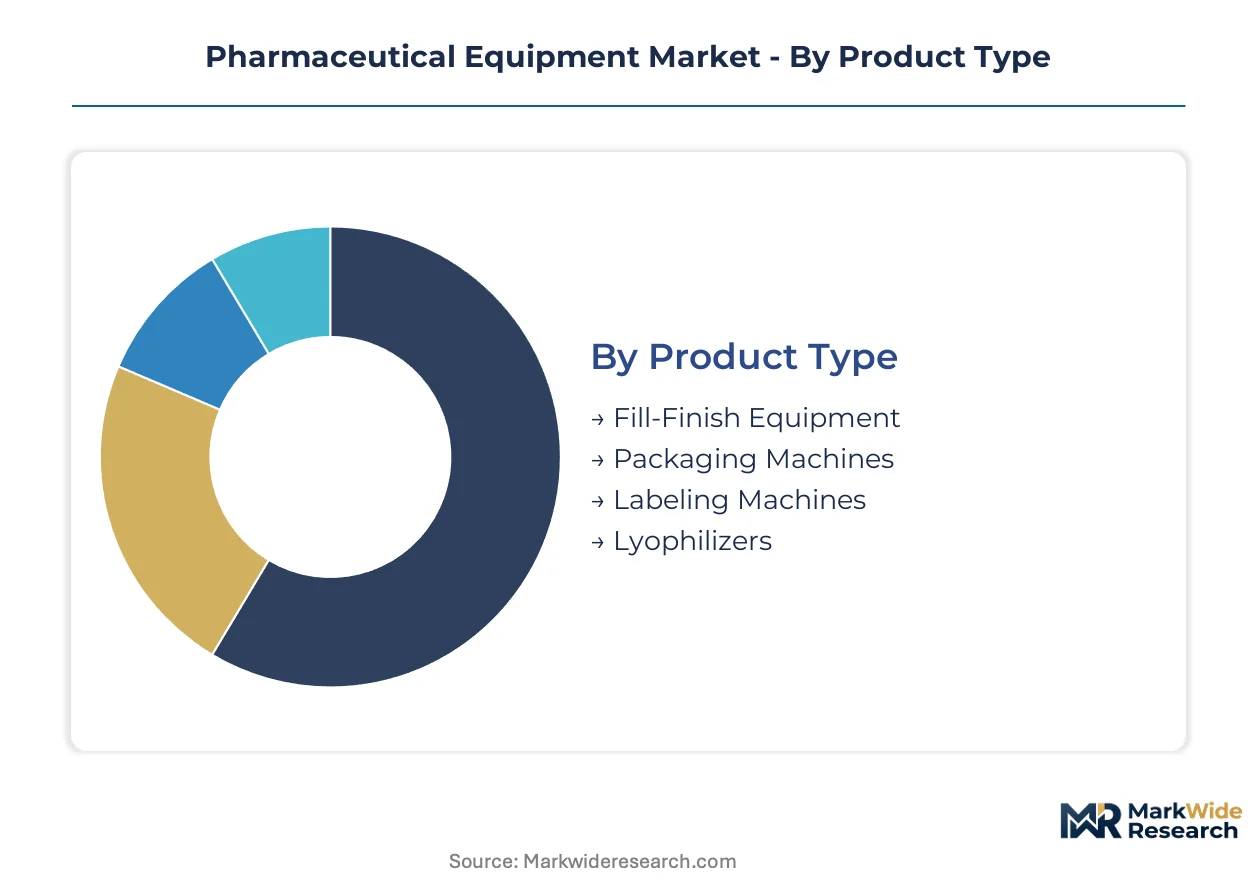
Equipment segmentation reveals how capital allocation priorities diverge between biologics capacity expansion and generic solid-dose replacement cycles. Technology tiers and end-user procurement patterns determine margin capture and service attachment rates across supplier portfolios.
Product Type:
Cost tier segmentation separates high-complexity aseptic systems from standardized packaging machinery with divergent qualification timelines and aftermarket revenue profiles.
- Fill-Finish Equipment:Isolator-based filling lines and closed-system processing skids constructed from electropolished 316L stainless steel with surface finishes below 0.4 micrometers Ra. Demand concentrates in German and Swiss manufacturing clusters serving monoclonal antibody producers facing FDA Annex 1 compliance deadlines.
- Packaging Machines:Blister packaging, bottle filling, and cartoning systems with serialization capabilities for track-and-trace compliance. Contract manufacturing organizations in India and Ireland are expanding secondary packaging capacity to capture biopharma outsourcing flows.
- Labeling Machines:Pressure-sensitive and shrink-sleeve applicators with vision inspection for label verification.
- Lyophilizers:Freeze-drying systems for thermally sensitive biologics and parenteral formulations.
Fill-Finish Equipment holds installed capacity. Packaging Machines is rotating up the share rankings.
Technology:
Automation intensity determines labor qualification requirements, batch record integrity, and integration complexity with manufacturing execution systems.
- Automatic:Fully automated processing lines with programmable logic controllers and distributed control system integration for continuous operation. Biotechnology companies in Massachusetts and California are specifying automatic systems to minimize human intervention in aseptic processing.
- Integrated Systems:Skid-mounted units combining multiple unit operations with embedded process analytical technology sensors. FDA draft guidance on real-time release testing is accelerating procurement of integrated powder-to-tablet lines by oral solid dosage manufacturers.
- Semi-Automatic:Equipment requiring operator intervention for material loading or batch changeover.
- Manual:Bench-scale or development-stage systems for clinical trial material production.
Automatic systems dominate current procurement volumes. Integrated Systems is climbing the fastest as continuous manufacturing adoption accelerates.
End User:
Customer type segmentation captures divergent total cost-of-ownership calculations between capital-constrained generic manufacturers and yield-focused biologics producers.
- Pharmaceutical Manufacturers:Integrated Big Pharma and mid-cap generic companies with captive production networks. Indian domestic manufacturers are backward-integrating into formulation equipment to capture margin from CDMO outsourcing trends in oral solid dosage.
- Contract Manufacturing Organizations:Third-party operators serving multiple clients with multi-product flexibility requirements. CDMOs in Germany and Switzerland are unbundling equipment procurement from multi-year service agreements to optimize utilization-based cost calculations.
- Research Laboratories:Academic and government facilities with small-batch, high-variety production needs.
- Biotechnology Companies:Emerging and established biotech firms with pipeline-dependent capacity scaling requirements.
Pharmaceutical Manufacturers retain the largest installed base. Contract Manufacturing Organizations is gaining share fastest as outsourcing concentration intensifies.
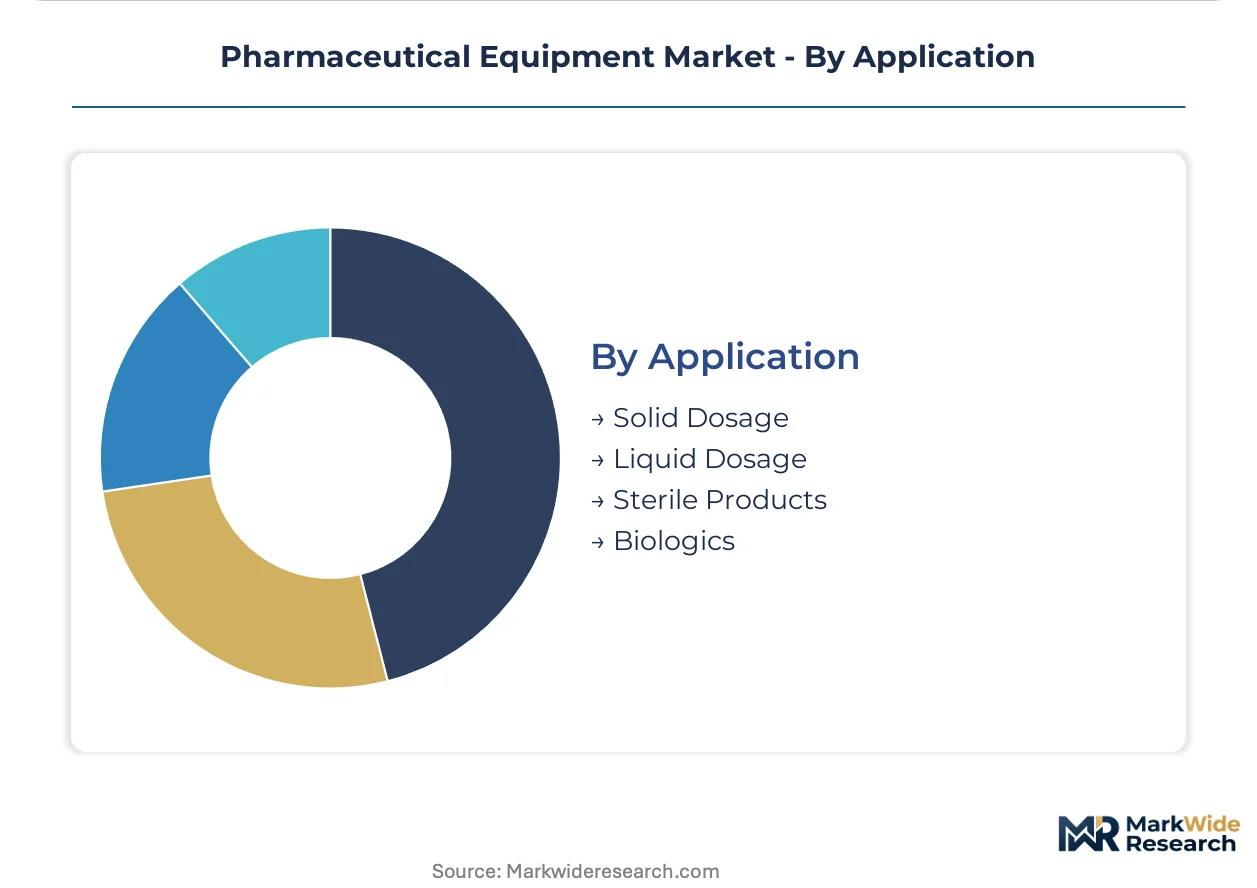
Application:
Application segmentation tracks how biologics growth is reallocating capital from mature solid-dose replacement toward aseptic processing complexity.
- Biologics:Monoclonal antibody, vaccine, and cell therapy manufacturing requiring isolator-based filling and single-use fluid pathways. German precision engineering clusters around Stuttgart are shortening qualification timelines for global pharma clients requiring rapid monoclonal antibody capacity scaling.
- Sterile Products:Parenteral formulations including injectables and ophthalmics with terminal sterilization or aseptic processing requirements. FDA enforcement of updated Annex 1 standards is accelerating capital expenditure on isolator-based filling lines across North American sterile injectable facilities.
- Solid Dosage:Tablet compression, coating, and capsule filling for oral administration.
- Liquid Dosage:Solution and suspension manufacturing for oral or topical delivery.
Solid Dosage holds depreciated but functional installed capacity. Biologics is expanding most quickly as pipeline concentrations shift toward large-molecule therapeutics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Swiss precision engineering clusters while Indian fabricators compete on cost-engineered delivery timelines. This asymmetry shapes procurement patterns across biologics capacity expansion and generic solid-dose replacement cycles.
United States
FDA Annex 1 enforcement is accelerating isolator-based filling line procurement across Massachusetts and California biotechnology corridors. The agency's sterile manufacturing guidance mandates closed-system processing upgrades with compliance deadlines tightening through 2027. Boston-Cambridge biotech clusters are specifying automatic aseptic systems to minimize human intervention in monoclonal antibody production.
Germany
Stuttgart and Karlsruhe engineering clusters anchor global supply for electropolished 316L stainless steel processing equipment with surface finishes below 0.4 micrometers Ra. EMA's Medical Device Regulation and updated ISO 14644 cleanroom classifications constrain supplier qualification timelines. German precision fabricators are shortening equipment validation schedules for rapid monoclonal antibody capacity scaling by global pharma clients.
India
Domestic manufacturers are backward-integrating into formulation equipment to capture margin from CDMO outsourcing trends in oral solid dosage. CDSCO's quality enforcement and the PLI scheme for pharmaceuticals are accelerating technology upgrades across Maharashtra and Gujarat manufacturing belts. Mumbai-Pune and Ahmedabad-Vadodara industrial corridors are expanding secondary packaging capacity for biopharma export flows.
Switzerland
Swissmedic's stringent device and sterile processing standards favor vendors with established regulatory dossiers and quality management system certifications. Basel and Zurich manufacturing clusters serve as qualification hubs for global biologics producers requiring rapid capacity deployment. Swiss CDMOs are unbundling equipment procurement from multi-year service agreements to optimize utilization-based total cost-of-ownership calculations.
China
NMPA's alignment with international ICH guidelines is reshaping equipment qualification requirements for domestic biologics manufacturers in Shanghai and Suzhou biotech parks. The Yangtze River Delta concentration of monoclonal antibody producers is driving demand for single-use fluid pathway systems. Chinese fabricators are expanding isolator-based filling capacity to meet both domestic pipeline growth and export certification standards.
Pharmaceutical Equipment Market Competitive Environment
Integrated process technology specialists and single-use system fabricators split the market between long-term partnership models and disposable technology adoption. The vendor base concentrates around German precision engineering clusters and Swiss regulatory-qualified fabricators, with Indian cost-engineered specialists capturing emerging-market generic demand. Three archetypes dominate: precision engineering houses with full validation capabilities, single-use technology specialists reducing cross-contamination risk, and cost-optimized fabricators serving price-sensitive oral solid dosage markets. Competitive moves center on geographic expansion into Indian and Chinese manufacturing corridors and technology licensing partnerships for continuous processing equipment.
Among German-based precision engineering houses, GEA Group and Sartorius AG occupy distinct positioning vectors. GEA Group represents the integrated process technology archetype anchoring long-term service partnerships with biologics manufacturers. Sartorius AG exemplifies the single-use technology specialist model serving multi-product CDMO operations. Syntegon Technology sits within the precision automation tier, reflecting Stuttgart-Karlsruhe engineering cluster capabilities.
| Leading Market Players |
|---|
| GEA Group |
| Syntegon Technology |
| IMA Group |
| Sartorius AG |
| Fette Compacting |
| Bausch+Ströbel |
| ACG Worldwide |
| Glatt |
| Romaco Group |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in German precision engineering clusters is compressing equipment delivery timelines and amplifying pricing power for electropolished 316L stainless steel fabricators serving FDA Annex 1 compliance-driven buyers. This utilization squeeze rewards suppliers with validated regulatory dossiers while forcing cost-sensitive generic manufacturers toward Indian cost-engineered alternatives.
Pricing Analysis
Configured-to-order pricing for isolator-based filling lines commands substantial premiums over standardized packaging machinery due to ASME BPE certification requirements and embedded process analytical technology integration. Three-tier pricing structure across premium, standard, and economy levels separates German precision fabricators from Swiss regulatory-qualified specialists and Indian cost-optimized suppliers. Price differentiation hinges on surface finish grade below 0.4 micrometers Ra and qualification timeline guarantees. Cost compression in economy-tier oral solid dosage equipment is intensifying because Indian domestic manufacturers are backward-integrating into captive fabrication. Contract manufacturing organizations in Germany and Switzerland exhibit lowest price sensitivity due to utilization-based total cost-of-ownership calculations, while emerging-market generic producers in India and China face acute budget constraints.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are becoming standard contracting features as equipment vendors absorb working capital strain from elongated ASME Section IX certification timelines. Geographic supply concentration centers on Germany, Switzerland, and India, with Stuttgart-Karlsruhe clusters anchoring high-precision fabrication and Mumbai-Pune corridors serving cost-engineered demand. Raw material dependencies draw from nickel and molybdenum commodity markets for 316L stainless steel, specialized electropolishing chemicals, and ASME-certified orbital welding consumables. Single-source vulnerability persists for ASME Section IX-certified welders concentrated in Central European labor pools. Distribution runs through direct-to-biotech channels bypassing traditional multi-tier distributors in favor of embedded long-term service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as biologics growth splinters demand between isolator-based aseptic systems and cost-optimized solid-dose replacement, creating distinct competitive arenas with divergent margin and service attachment profiles.
For Market Incumbents: Pre-empt displacement by single-use technology specialists through captive supply of disposable fluid pathway components and isolator-integrated service contracts. Anchor long-term partnerships with monoclonal antibody producers facing FDA Annex 1 compliance deadlines by embedding multi-year performance-based maintenance agreements. Consolidate position in German precision engineering clusters through capacity addition in Karlsruhe-Stuttgart corridor to shorten qualification timelines for global pharma clients. For New Entrants and Emerging Players: Indian generic API-to-finished-dose integration represents the most penetrable entry point for cost-engineered fill-finish lines tailored to CDMO outsourcing trends in oral solid dosage. Secondary packaging capacity expansion in Maharashtra and Gujarat industrial corridors offers white-space capture as biopharma export flows intensify. Go-to-market angle should emphasize rapid delivery timelines and flexible financing structures against established European incumbents. For Investors and Strategic Acquirers: Capital is best deployed toward precision automation specialists with established EMA Medical Device Regulation dossiers and ISO 14644 cleanroom certification capabilities serving biologics capacity scaling. Long-term viability over the projection horizon rests on regulatory qualification moats rather than commodity fabrication scale. Signal to watch: FDA draft guidance finalization on continuous manufacturing equipment validation reshaping supplier-customer contracting models and service revenue attachment rates.| Strategic Initiative | Industry Significance |
|---|---|
| Isolator Technology Integration | Closed-system processing upgrades accelerate replacement cycles for legacy open-filling lines under FDA Annex 1 enforcement. |
| Single-Use Technology Licensing | Disposable bioreactor systems eliminate cross-contamination risk in multi-product CDMO operations serving monoclonal antibody pipelines. |
| Continuous Manufacturing Validation | Integrated powder-to-tablet lines with embedded PAT sensors capture first-mover advantage from FDA real-time release testing guidance. |
| Regulatory Dossier Expansion | EU AI Act documentation capabilities for automated visual inspection systems open recurring requalification service revenue streams. |
| Indian Manufacturing Footprint | Cost-engineered fill-finish capacity in Maharashtra-Gujarat corridors captures margin from generic manufacturer backward integration. |
Study Parameters
Initial hypotheses were tested against primary input from biologics manufacturing executives, regulatory affairs leads at sterile injectable facilities, equipment procurement managers at contract development organizations, and aftermarket service heads at precision engineering firms and refined through secondary validation. FDA filings, EMA Medical Device Regulation submissions, ISO 14644 cleanroom certification databases, and ASME BPE technical documentation provided foundational data layers. Bottom-up equipment shipment analysis and top-down pharmaceutical capital expenditure tracking were triangulated to establish market sizing.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include equipment product type, automation technology tier, end-user archetype, and application area alongside regional regulatory cluster differentiation. CAGRs were derived from installed base growth rates, replacement cycle acceleration factors, and compliance-driven upgrade intensity. Forecast inputs incorporated monoclonal antibody pipeline concentrations, FDA Annex 1 compliance deadline schedules, and single-use technology adoption curves.
Practitioners should monitor FDA draft guidance finalization, nickel and molybdenum commodity price volatility, and ASME Section IX welder labor pool expansion for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Shell Vials Market
Pharmaceutical Equipment
US Pharmaceutical Isolators Market
Pharmaceutical Equipment
Middle East and Africa Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Flip Top Vials Market
Pharmaceutical Equipment
Pharmaceutical Continuous Manufacturing Market
Pharmaceutical Equipment
Pharmaceutical Equipment Testing Market
Pharmaceutical Equipment
Europe Pharmaceutical Vials Market
Pharmaceutical Equipment
Drug Infusion System Market
Pharmaceutical Equipment
Pharmaceutical Anti-Counterfeiting Technologies Market
Pharmaceutical Equipment
Europe Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Vial Adaptors for Reconstitution Drug Market
Pharmaceutical Equipment
Lyophilization Equipment and Services Market
Pharmaceutical Equipment
Cryogenic Ampoules Market
Pharmaceutical Equipment
Inhalation CDMO Market
Pharmaceutical Equipment
Pharmaceutical Automation Market
Pharmaceutical Equipment
Global Pharmaceutical Isolator Market