
 Pharmaceutical Sterilization Equipment Market | 2026-2036
Pharmaceutical Sterilization Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Sterilization Equipment Market Outlook
Buyer concentration among contract manufacturing organizations is recalibrating procurement patterns across the sterilization equipment landscape. STERIS plc leverages its installed base of ethylene oxide systems to sustain long-term service contracts with multi-site pharmaceutical operators. Getinge AB anchors European demand through specialized isolator-integrated sterilization lines for aseptic processing. 3M Company competes in hydrogen peroxide vapor segments where low-temperature requirements dominate biologics manufacturing workflows.
Pharmaceutical sterilization equipment encompasses engineered systems that eliminate viable microorganisms from drug products, packaging materials, and production surfaces through validated thermal, chemical, or radiation processes, typically achieving sterility assurance levels of 10^-6. Steam sterilizers dominate capital expenditure budgets due to proven compatibility with aqueous parenteral formulations, while hydrogen peroxide sterilizers capture fastest-growing share as temperature-sensitive biologics expand. Contract Manufacturing Organizations represent the most concentrated end-user segment, with equipment specifications tightening around automated batch documentation and real-time biological indicator monitoring.
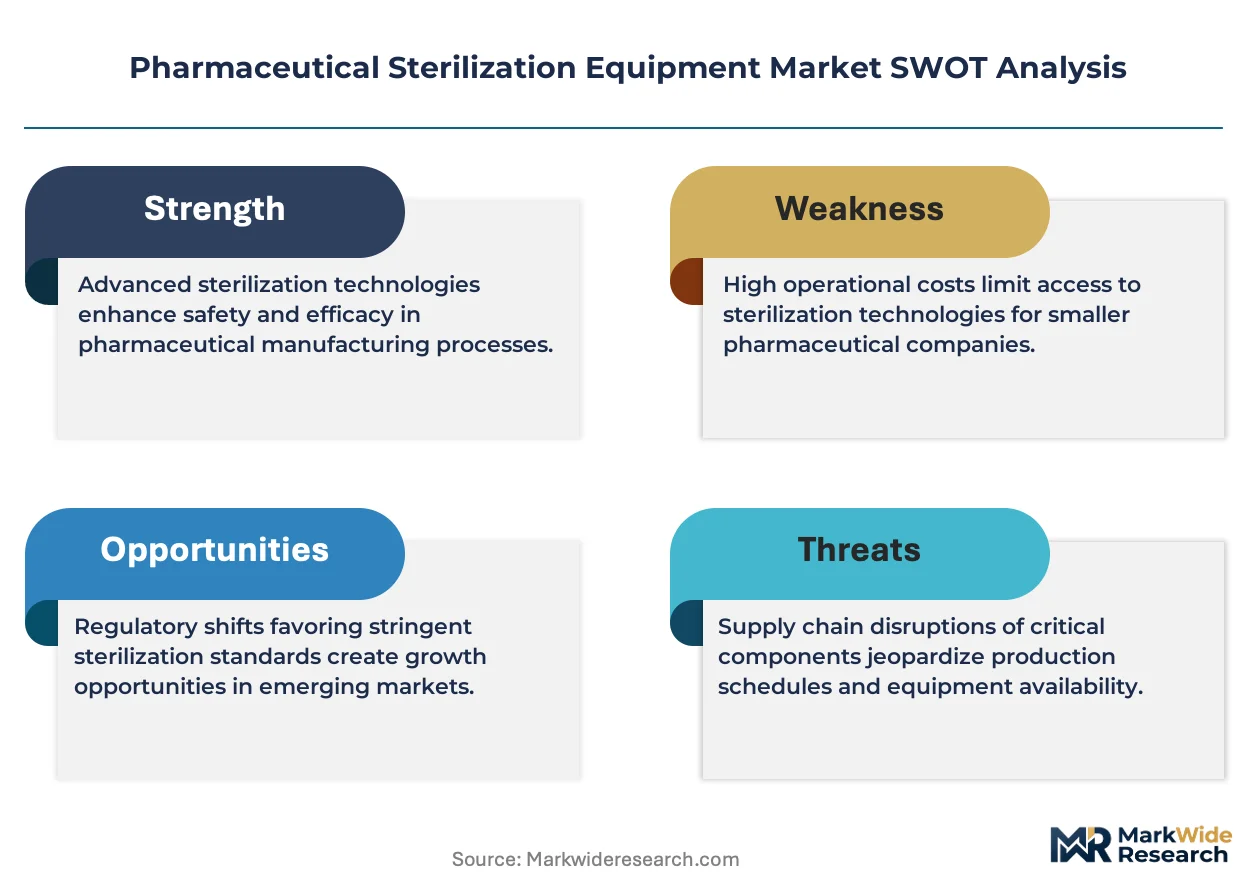
FDA sterilization guidance, EU GMP Annex 1 revision, and ISO 17665 steam sterilization standards collectively elevate validation documentation requirements for equipment suppliers. The EPA's evolving emissions rules for ethylene oxide are forcing facility engineers to evaluate alternative modalities or install advanced abatement systems. Stakeholders must monitor regulatory divergence between FDA terminal sterilization expectations and EMA emphasis on barrier isolation technology when allocating R&D budgets across product development pipelines.
Market Dynamics
Contract Manufacturing Organizations are consolidating sterilization procurement around multi-site service agreements, compressing vendor counts and elevating equipment specifications toward continuous processing platforms with integrated validation documentation.
Growth Catalysts
- FDA Terminal Sterilization Guidance:Updated validation requirements are accelerating replacement cycles for batch-mode steam sterilizers across parenteral drug manufacturing facilities in the United States.
- Cell and Gene Therapy Biologics:Temperature-sensitive manufacturing workflows are pulling hydrogen peroxide vapor systems into new facility builds faster than legacy modalities.
- German CDMO Clustering:Concentrated contract manufacturing capacity around Frankfurt and Munich is generating synchronized equipment refresh demand from sterilization infrastructure nearing end-of-life.
Market Restraints
- Ethylene Oxide Emissions Compliance:EPA evolving abatement rules are forcing facility engineers to install costly catalytic oxidation systems or abandon established EtO sterilization lines entirely.
- Stainless Steel Input Volatility:Grade 316L chamber fabrication costs fluctuate with nickel pricing, compressing margins for autoclave manufacturers with fixed-price contract exposure.
- Specialized Skill Scarcity:Validation engineers with combined thermal processing and GMP documentation expertise command premium compensation, extending commissioning timelines.
Strategic Opportunities
- India Biologics Manufacturing:CDSCO production-linked incentive schemes for active pharmaceutical ingredients are attracting greenfield sterile injectable facilities requiring full sterilization infrastructure.
- Isolator-Integrated Sterilization:Convergence of hydrogen peroxide vapor generators with restricted access barrier systems opens modular cleanroom configurations for flexible aseptic processing.
- EU GMP Annex 1 Revision:Contamination control strategy mandates are creating replacement demand for legacy steam sterilizers lacking real-time biological indicator monitoring capabilities.
Industry Challenges
- Legacy System Integration:New continuous processing sterilizers must interface with existing batch documentation software, requiring costly custom middleware development.
- Commissioning Timeline Compression:IQ/OQ/PQ validation protocols for combined sterilization-isolator systems now extend 18-24 months, delaying revenue recognition for equipment suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Sterilization Equipment Market |
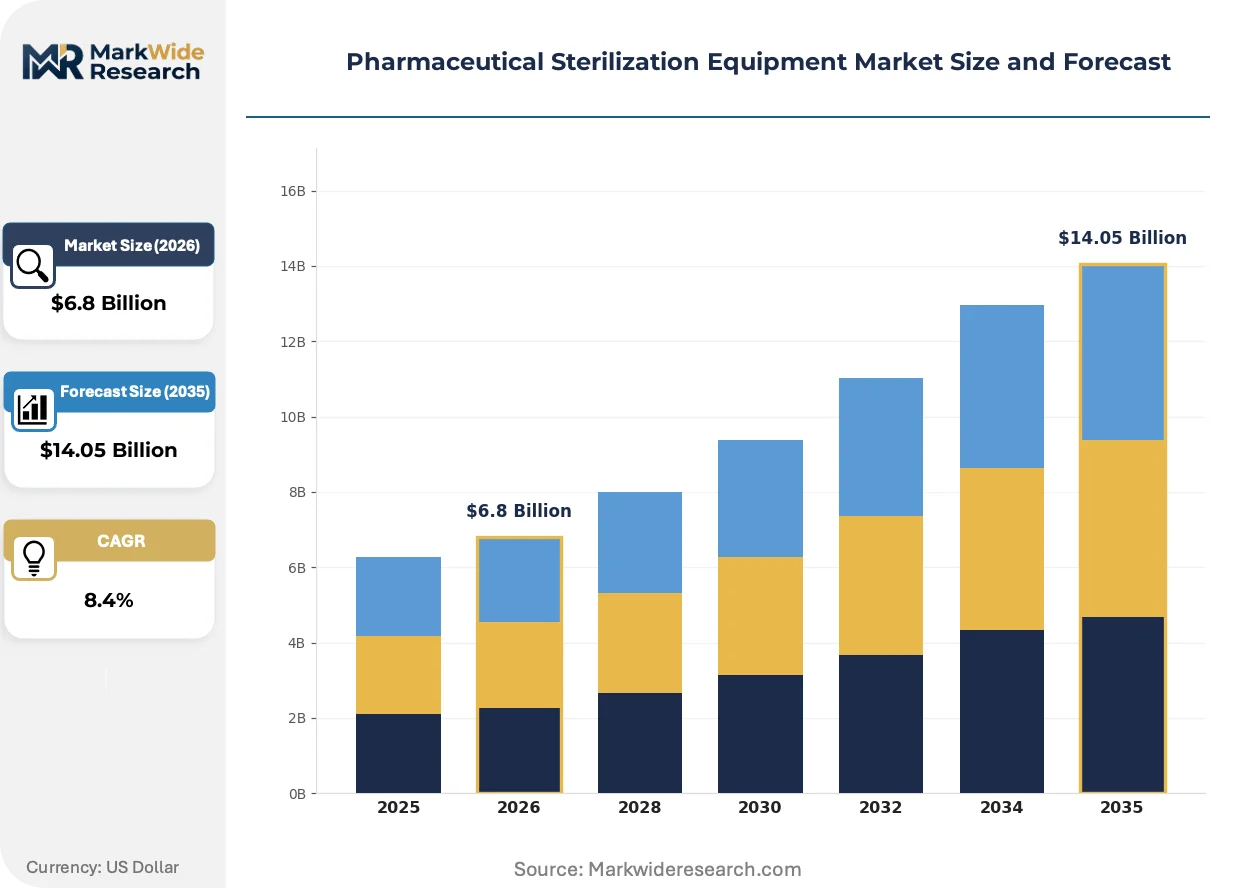
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steam Sterilizers, Ethylene Oxide Sterilizers, Hydrogen Peroxide Sterilizers, Radiation Sterilizers Application: Injectables, Surgical Instruments, Laboratory Equipment, Biotechnology Products End User: Pharmaceutical Companies, Contract Manufacturing Organizations, Research Laboratories, Hospitals Technology: Filtration, Heat, Chemical, Ionizing Radiation |
| Companies Covered | STERIS plc, Getinge AB, 3M Company, Advanced Sterilization Products, Belimed AG, Cardinal Health, Fortive Corporation, MMM Group, Antonio Matachana, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Sterilization Equipment Market Strategic Shifts
Equipment architecture is pivoting from standalone batch units toward integrated processing lines where sterilization modules communicate directly with fill-finish isolators, compressing contamination risk windows and documentation burden.
Electron beam sterilization is converging with pharmaceutical packaging workflows as dose-mapping software enables precise surface treatment without thermal degradation. Medical device and drug combination product manufacturers are piloting in-line e-beam systems at commercial scale. This modality is converging with high-speed form-fill-seal operations, collapsing traditional sterilization logistics into single-pass manufacturing.
EMA's emphasis on barrier isolation technology in its 2022 GMP revision is elevating isolator-integrated sterilizer specifications above standalone autoclave purchases. Pharmaceutical manufacturers must now demonstrate physical separation between operators and sterile product zones. Aseptic processing facilities in Ireland and Switzerland are retrofitting existing cleanrooms with hydrogen peroxide vapor generators integrated into isolator walls.
After-sales service unbundling is fragmenting traditional equipment procurement as CDMOs separate capital purchase from validation support and maintenance contracts. Third-party service providers now compete directly with original equipment manufacturers for biological indicator testing and annual requalification. This shift is most pronounced in Germany, where multi-site operators standardize service procurement across heterogeneous installed bases.
Pharmaceutical Sterilization Equipment Market Segmentation
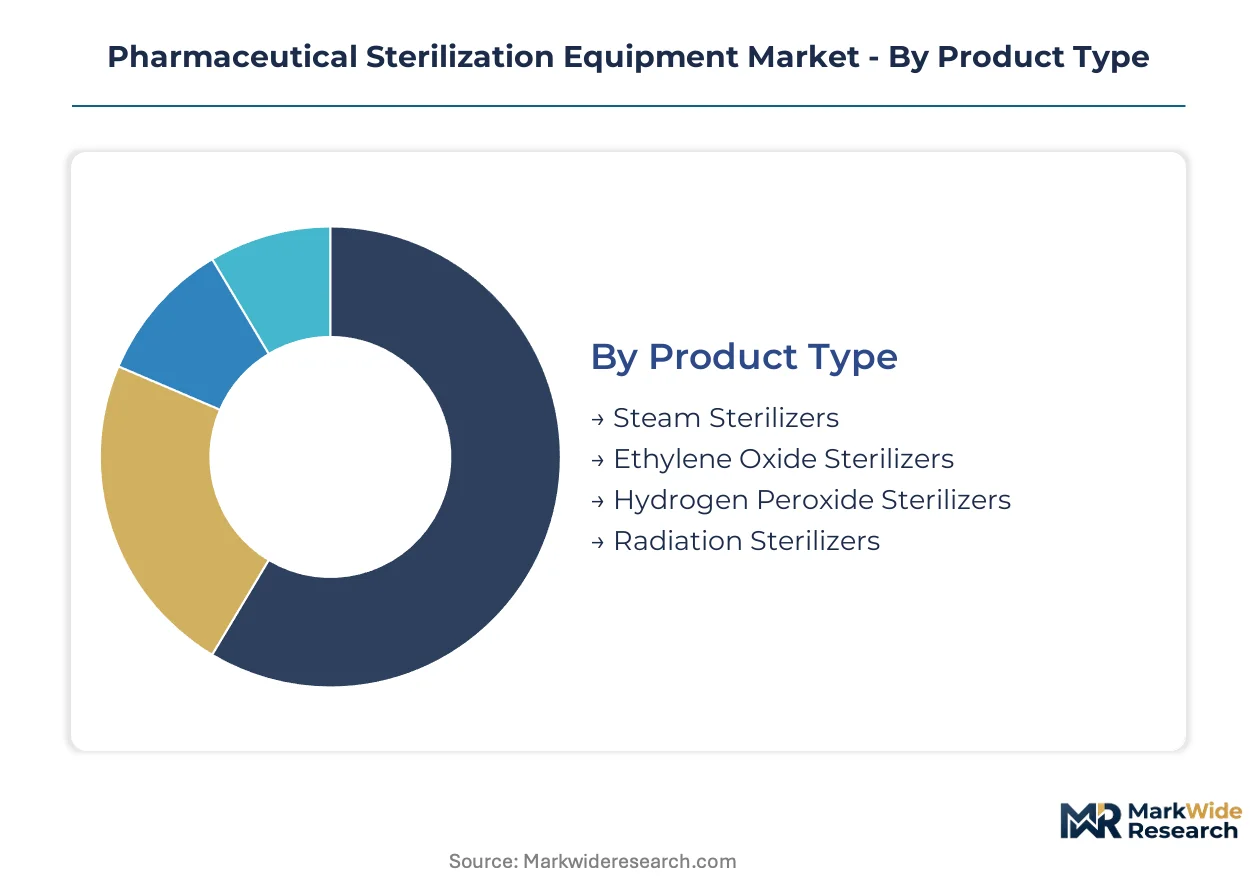
Equipment selection in pharmaceutical sterilization hinges on thermal tolerance of drug products, regulatory validation pathways, and integration complexity with existing manufacturing lines. Segmentation reveals how modality preferences split between mature steam infrastructure and emerging low-temperature alternatives.
Product Type:
Capital allocation patterns diverge sharply based on facility age and biologics exposure in the manufacturing portfolio.
- Steam Sterilizers:Saturated steam autoclaves operating at 121°C or 134°C remain the default for aqueous parenteral formulations. German CDMO clusters around Frankfurt and Munich are driving replacement cycles as legacy systems approach end-of-life validation limits.
- Hydrogen Peroxide Sterilizers:Vapor-phase hydrogen peroxide systems operate below 60°C, preserving protein integrity in cell and gene therapy manufacturing. Demand is concentrating in new biologics facilities where FDA terminal sterilization guidance favors continuous processing compatibility.
- Ethylene Oxide Sterilizers:Gas-phase sterilization persists for heat-sensitive packaging and combination products despite EPA emissions compliance pressures forcing costly abatement retrofits.
- Radiation Sterilizers:Gamma and electron beam systems serve terminal sterilization of prefilled syringes and sealed drug-device combinations where moisture exclusion is critical.
Steam sterilizers lead volumes today; hydrogen peroxide sterilizers are gaining share fastest.
Application:
Regulatory scrutiny intensity and contamination risk profiles reshape equipment specifications across therapeutic categories.
- Injectables:Parenteral drug sterilization demands validated steam cycles with SAL 10^-6 assurance. EU GMP Annex 1 revision mandates real-time biological indicator monitoring for terminally sterilized products.
- Surgical Instruments:Reusable device sterilization in hospital settings favors gravity-displacement autoclaves with shorter cycle times than pharmaceutical-grade prevacuum systems.
- Laboratory Equipment:Research-scale sterilization requires flexible chamber configurations accommodating irregular glassware loads without production-line throughput constraints.
- Biotechnology Products:Temperature-sensitive biologics manufacturing pulls hydrogen peroxide vapor and filtration-based modalities into upstream cell culture and downstream purification workflows.
Injectables dominate current installed base; biotechnology products show steepest expansion trajectory.
End User:
Procurement scale and validation expertise availability separate institutional buyers into distinct negotiating positions.
- Pharmaceutical Companies:Multi-site operators standardize on single-vendor platforms to compress spare parts inventory and training overhead across global manufacturing networks.
- Contract Manufacturing Organizations:CDMOs concentrate demand through multi-site service agreements, elevating specifications toward automated batch documentation and continuous processing platforms.
- Research Laboratories:Academic and government labs prioritize capital cost containment over validation throughput, extending replacement cycles beyond commercial manufacturing standards.
- Hospitals:Healthcare institutions operate sterilization infrastructure for surgical instruments and compounded pharmaceuticals under Joint Commission accreditation rather than FDA drug GMP.
Contract Manufacturing Organizations command the largest aggregate procurement volumes; research laboratories lag in equipment refresh frequency.
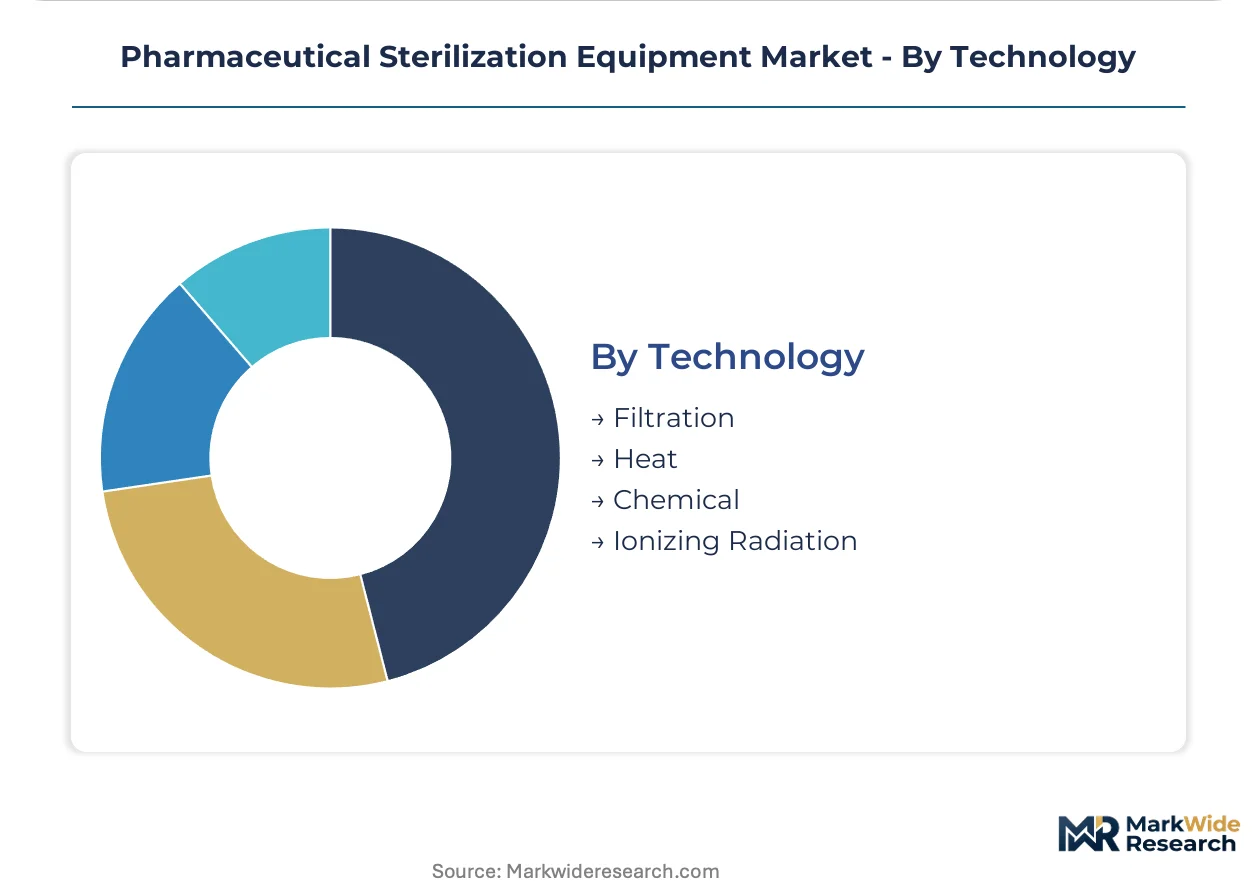
Technology:
Physical mechanism of microbial inactivation determines compatibility with drug product stability requirements and facility infrastructure constraints.
- Filtration:Membrane-based sterilization of heat-labile solutions through 0.22µm rated filters preserves protein activity in biologics fill-finish operations.
- Heat:Thermal sterilization via saturated steam or dry heat delivers proven SAL attainment for stable small-molecule parenterals and glassware depyrogenation.
- Chemical:Gaseous and vapor-phase biocides including ethylene oxide, hydrogen peroxide, and peracetic acid penetrate packaging barriers without thermal degradation.
- Ionizing Radiation:Gamma and electron beam modalities achieve terminal sterilization of sealed final containers, collapsing traditional aseptic processing logistics into single-pass manufacturing.
Heat-based systems anchor current infrastructure; ionizing radiation is climbing the fastest as dose-mapping software enables precise surface treatment integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates replacement demand for legacy steam sterilizers while the United States drives adoption of continuous processing platforms under updated FDA guidance. Country-level procurement patterns diverge sharply based on regulatory timelines and biologics manufacturing exposure.
United States
FDA terminal sterilization validation requirements are accelerating equipment refresh cycles across parenteral drug facilities. The EPA's evolving ethylene oxide emissions rules force facility engineers toward costly abatement retrofits or alternative modalities. Massachusetts and North Carolina biomanufacturing clusters are prioritizing hydrogen peroxide vapor systems for cell therapy production.
Germany
CDMO concentration around Frankfurt and Munich generates synchronized demand for isolator-integrated sterilization lines. EU GMP Annex 1 revision mandates real-time biological indicator monitoring, disqualifying legacy batch-mode autoclaves. Baden-Württemberg pharmaceutical fabricators are consolidating procurement through multi-site service agreements with automated documentation requirements.
India
CDSCO production-linked incentive schemes for active pharmaceutical ingredients attract greenfield sterile injectable facilities requiring full sterilization infrastructure. Temperature-sensitive biologics manufacturing is pulling low-temperature modalities into new facility builds. Maharashtra and Gujarat pharmaceutical corridors are standardizing on continuous processing platforms to meet export validation standards.
Switzerland
Swissmedic emphasis on barrier isolation technology elevates specifications for hydrogen peroxide vapor generators integrated into restricted access systems. Basel-region biologics manufacturers are retrofitting existing cleanrooms with modular isolator configurations. The country's precision engineering base supports domestic fabrication of specialized sterilization chambers for aseptic processing.
Japan
PMDA alignment with FDA terminal sterilization expectations drives adoption of continuous processing equipment with integrated validation documentation. Osaka and Kanto pharmaceutical manufacturing belts are replacing end-of-life steam sterilizers ahead of regulatory deadlines. Domestic equipment suppliers face pressure from European and American competitors on automation specifications.
Pharmaceutical Sterilization Equipment Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across sterilization modality segments. The vendor base organizes around three strategic archetypes: full-line sterilization platform providers, isolator-integrated system specialists, and low-temperature modality pure-plays. Consolidation pressure intensifies as CDMO procurement concentrates through multi-site agreements, compressing vendor counts and elevating equipment specifications. Dominant competitive moves include geographic expansion into emerging biologics manufacturing corridors and technology licensing for continuous processing validation software.
Among full-line platform providers, STERIS plc and Getinge AB exemplify the diversified equipment-and-service model. STERIS plc leverages its installed base of ethylene oxide systems to sustain long-term service relationships with multi-site pharmaceutical operators. Getinge AB anchors European demand through specialized isolator-integrated sterilization lines for aseptic processing. 3M Company occupies a position within the low-temperature modality tier, competing in hydrogen peroxide vapor segments where temperature-sensitive biologics manufacturing workflows dominate equipment selection.
| Leading Market Players |
|---|
| STERIS plc |
| Getinge AB |
| 3M Company |
| Advanced Sterilization Products |
| Belimed AG |
| Cardinal Health |
| Fortive Corporation |
| MMM Group |
| Antonio Matachana |
| Others |
Value Chain & Pricing Dynamics
Validation engineer concentration in Germany's Rhine-Main and Upper Bavaria regions feeds labor-cost differentials into pricing-tier spreads, compressing margins for equipment suppliers with fixed-price exposure to 316L stainless steel volatility.
Pricing Analysis
Capacity additions in India are reshaping price floors for standard steam autoclaves, while European isolator-integrated systems command premium positioning. Three-tier pricing structure across premium isolator-integrated, standard batch-mode, and economy laboratory-grade levels separates CDMO multi-site operators from single-facility research labs. Pricing pressure stems from EPA ethylene oxide abatement mandates forcing costly retrofit decisions. Research laboratories exhibit highest price sensitivity; CDMOs with multi-site standardization contracts show lowest.
Supply Chain Analysis
Dual-sourcing requirements from FDA-regulated pharmaceutical operators mandate multi-supplier qualification for biological indicator consumables and chamber fabrication components. Supply concentrates in Germany for precision isolator engineering, Italy for stainless steel chamber fabrication, and the United States for control system software. Raw material dependencies include Grade 316L stainless steel, nickel alloys, and specialized seal polymers. Single-source vulnerability around European precision machining capacity for isolator-grade components poses structural risk. Distribution runs through direct OEM channels for large CDMO accounts and regional distributors for mid-tier pharmaceutical manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with EU GMP Annex 1 revision mandating real-time biological indicator monitoring as the definitive demand catalyst across European sterilization infrastructure replacement cycles.
For Market Incumbents: Anchor service revenue through unbundled validation support contracts that outlast equipment depreciation cycles, insulating against hydrogen peroxide vapor pure-plays displacing steam autoclave incumbents. Deepen backward integration into biological indicator manufacturing to capture recurring consumable streams from installed base expansion. For New Entrants and Emerging Players: Electron beam dose-mapping software presents a technology-first wedge for combination product manufacturers seeking single-pass sterilization-packaging integration. Target Swiss and Irish biologics facilities retrofitting existing cleanrooms with modular isolator configurations as the most penetrable white-space. Lead with continuous processing validation software licensing rather than capital equipment sales to compress customer acquisition friction. For Investors and Strategic Acquirers: Valuations sit cheapest among regional steam autoclave fabricators lacking isolator integration capabilities, creating roll-up opportunities ahead of EU GMP Annex 1 enforcement windows. Long-term viability favors platforms with recurring service revenue exceeding 40 percent of total mix. Watch FDA terminal sterilization guidance expansion to Asia-Pacific as the inflection signal for geographic reallocation.| Strategic Initiative | Industry Significance |
|---|---|
| Isolator Integration Partnership | Combines hydrogen peroxide vapor generators with restricted access barrier systems for modular cleanroom deployment. |
| Biological Indicator Consumable Verticalization | Captures recurring revenue streams from installed base expansion through in-house indicator manufacturing. |
| Continuous Processing Validation Software Licensing | Decouples revenue from capital equipment cycles through SaaS-tiered documentation platforms. |
| India Greenfield Facility Partnership | Positions equipment suppliers for CDSCO production-linked incentive scheme capacity builds. |
| EtO Abatement Technology Acquisition | Addresses EPA compliance pressure through catalytic oxidation system integration capabilities. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with sterilization equipment procurement directors, validation engineering leads, CDMO facility managers, and regulatory affairs specialists at FDA and EMA. Secondary validation draws from FDA 483 inspection observations, EMA GMP inspection reports, ISO 17665 revision drafts, and SEC equipment supplier filings. Bottom-up demand modeling triangulates against top-down market sizing across modality segments.
Rate-of-change decomposition isolates volume expansion from price-mix effects across the projection horizon. Segmentation dimensions include equipment modality, application type, end-user category, and regional regulatory cluster complexity. CAGRs derive from installed base replacement velocity analysis and greenfield facility commissioning timelines. Industry-specific forecast inputs incorporate biological indicator testing frequency standards and cleanroom isolator retrofit penetration curves.
The model holds under steady regulatory enforcement timelines; deviation in EPA ethylene oxide rule acceleration or EMA barrier isolation mandate delays would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
US Depyrogenated Sterile Empty Vials Market
Pharmaceutical Equipment
Sterile Vials Market
Pharmaceutical Equipment
North America Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Radiosynthesis Equipment Market
Pharmaceutical Equipment
Automated Radiosynthesis Modules Market
Pharmaceutical Equipment
Pharmerging Contract Manufacturing Market
Pharmaceutical Equipment
Sterile Injectable Contract Manufacturing Market
Pharmaceutical Equipment
Asia-Pacific Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Malaysia Pharmacy Automation Market
Pharmaceutical Equipment
Pharmaceutical Incubators Market
Pharmaceutical Equipment
Aseptic Negative Pressure Pharmaceutical Isolators Market
Pharmaceutical Equipment
Japan Contract Development and Manufacturing Organization Market
Pharmaceutical Equipment
Radiopharmaceutical Synthesizer Market
Pharmaceutical Equipment
Pharmaceutical Equipment Market
Pharmaceutical Equipment
Lyophilization Equipment and Services Market
Pharmaceutical Equipment
Radiochemical Synthesizers Market