
 Automated Radiosynthesis Modules Market | 2026-2036
Automated Radiosynthesis Modules Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Radiosynthesis Modules Market Analysis
Fluorine-18 precursors are replacing carbon-11 in routine clinical workflows, rebalancing cost structures for module manufacturers. GE Healthcare leverages its cyclotron network to sustain geographic dominance in North American installations. Siemens Healthineers anchors its position through deep integration with PET scanner ecosystems. Trasis S.A competes on modular architecture that allows site-specific reconfiguration without hardware replacement.
Automated radiosynthesis modules are enclosed, shielded systems that execute multi-step radiochemical reactions under automated control, typically handling Curie-scale activities of short-lived isotopes such as fluorine-18 and gallium-68 with half-lives under two hours. These systems perform synthesis, purification, formulation, and sterile filtration to produce patient-injectable radiopharmaceuticals for molecular imaging. Modular Systems dominate current installations due to their upgrade flexibility and lower capital barriers for mid-sized nuclear medicine centers. Pharmaceutical Production applications represent the fastest-expanding segment as contract manufacturing organizations scale tracer output for therapeutic radiopharmaceutical pipelines. Remote-Controlled Units command premium positioning where operator radiation exposure limits drive regulatory compliance costs.
The FDA's current good manufacturing practice requirements for PET drugs mandate process validation and batch records that directly shape module software architecture and sensor arrays. EMA's Annex 1 revisions on sterile manufacturing extend these requirements across European installations, while REACH obligations govern precursor chemical handling protocols. Japan's PMDA enforces additional shielding and containment standards that differentiate product specifications for that market. Stakeholders must monitor evolving isotope supply chain resilience and therapeutic radiopharmaceutical scale-up requirements when planning module procurement and facility design.
Market Dynamics
The FDA's current good manufacturing practice requirements for PET drugs are compressing equipment replacement cycles as nuclear medicine departments retrofit existing installations to meet batch record and process validation mandates.
Growth Catalysts
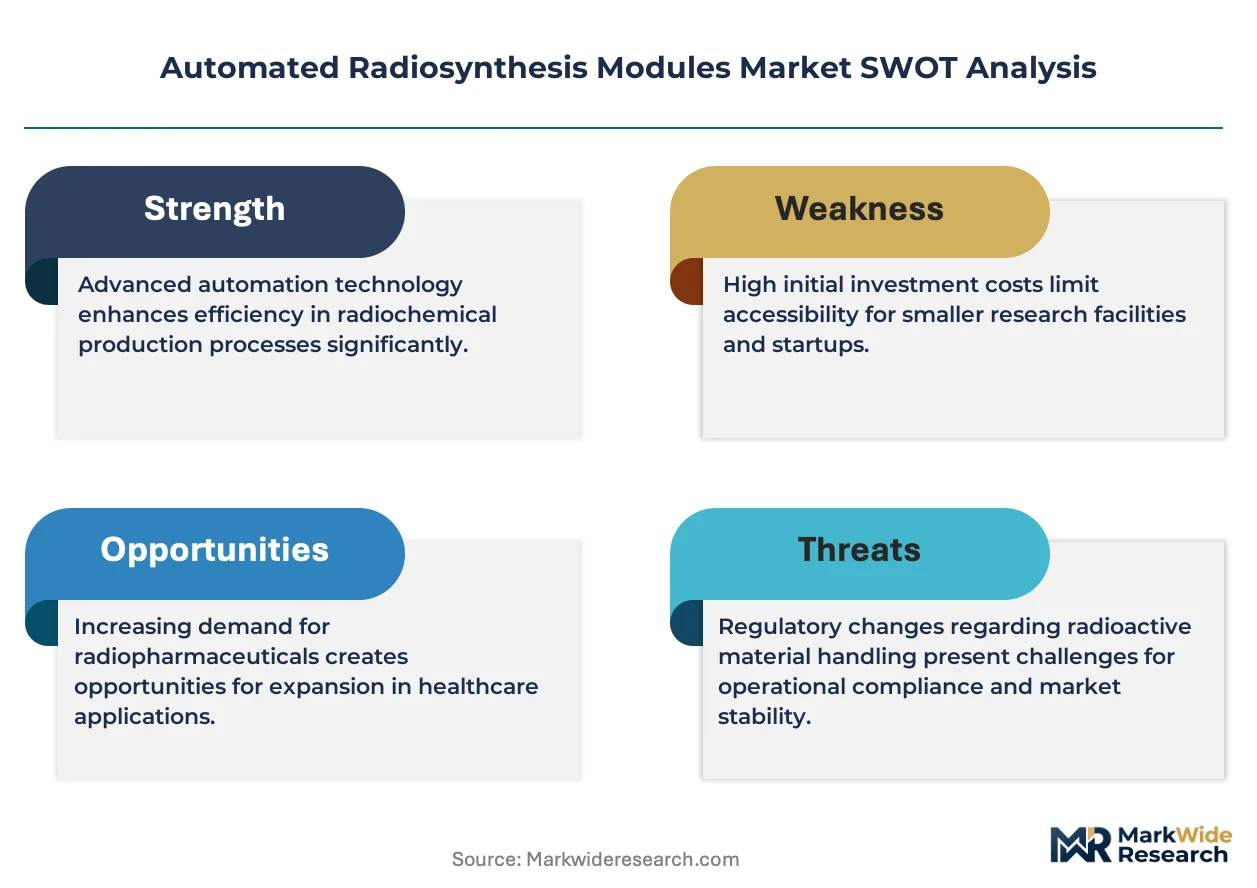
- EMA Annex 1 Revisions:Sterile manufacturing updates across European installations are mandating sensor array upgrades and automated environmental monitoring systems in module architecture.
- Fluorine-18 Precursor Standardization:Clinical workflow migration toward fluorine-18 labeled tracers is expanding addressable module demand in hospital nuclear medicine departments.
- Germany Production Clustering:Concentrated manufacturing capabilities around Berlin and Munich are reducing lead times for module delivery and service support across Central European markets.
Market Restraints
- Cyclotron Isotope Supply Concentration:Dependence on centralized production facilities for fluorine-18 and gallium-68 creates vulnerability to single-site operational disruptions.
- Capital Intensity Barriers:Shielded enclosure requirements and Curie-scale handling specifications elevate baseline procurement costs for mid-sized nuclear medicine centers.
- Short Half-Life Logistics:Isotope decay constraints below two hours compress synthesis windows and limit geographic radius for centralized production models.
Strategic Opportunities
- Therapeutic Radiopharmaceutical Pipeline Scale-Up:Contract manufacturing organizations are expanding module capacity to serve alpha-emitter and beta-emitter therapeutic tracer production.
- Remote-Controlled Unit Premiumization:Operator radiation exposure limits under ALARA principles are creating compliance-driven demand for fully enclosed, distantly operated synthesis systems.
- Modular Architecture Reconfiguration:Site-specific hardware adaptation without full replacement enables upgrade revenue streams and extends customer lifecycle value.
Industry Challenges
- Radiochemist Talent Scarcity:Specialized expertise in automated synthesis optimization and quality control remains concentrated in academic medical centers and limits operational scaling.
- Legacy System Integration Friction:Existing PET scanner ecosystems and hospital information systems require customized software bridges that extend deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Radiosynthesis Modules Market |
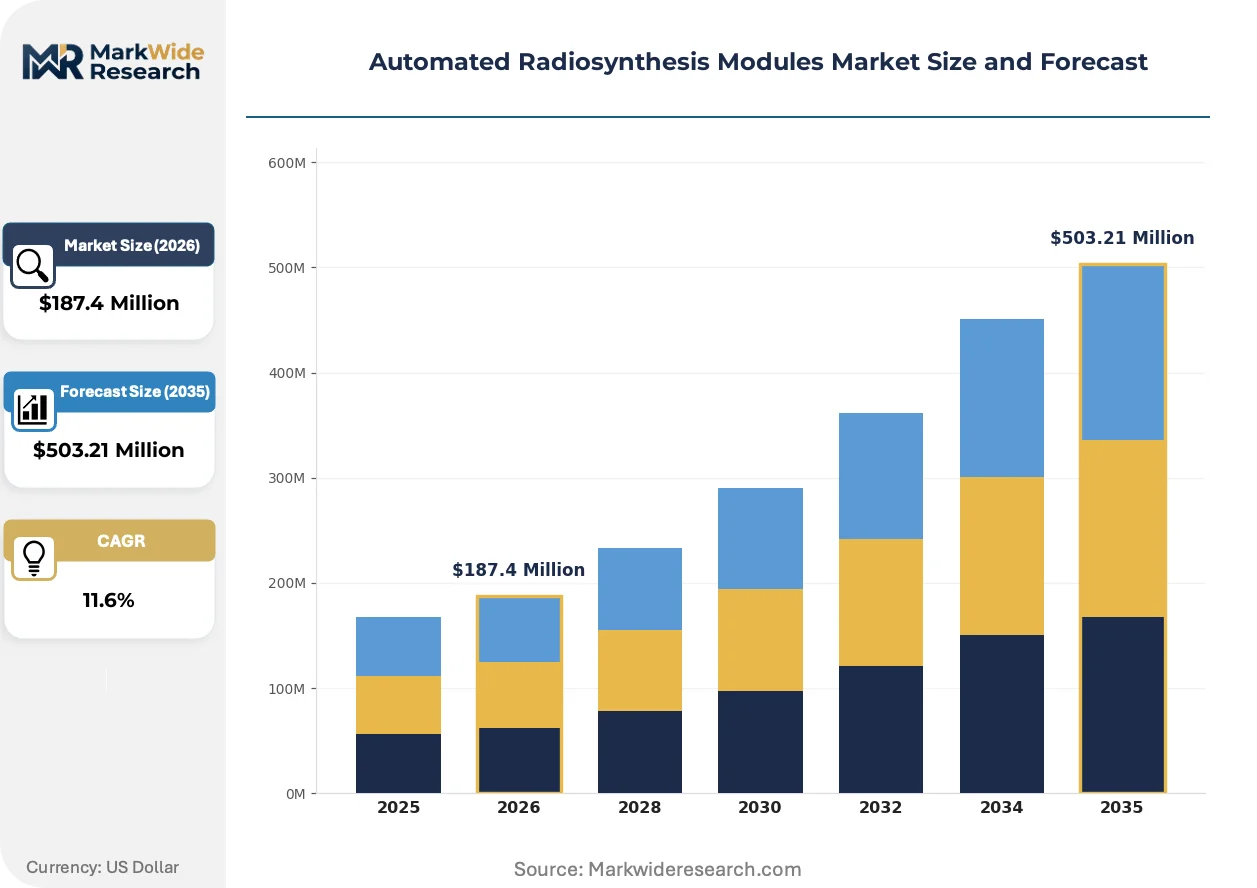
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Systems, Single-Source Units, Multipurpose Platforms, Remote-Controlled Units Application: Research Laboratories, Clinical Settings, Pharmaceutical Production, Academic Institutions Technology: Radiochemistry, Automated Dispensing, PET Imaging, Radioisotope Production End User: Biotechnology Companies, Research Institutions, Hospitals, Pharmaceuticals |
| Companies Covered | GE Healthcare, Siemens Healthineers, IBA Radiopharma Solutions, Eckert & Ziegler, Synthra GmbH, Trasis S.A, Scintomics GmbH, Sofie Biosciences, Optimized Radiochemical Applications, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Radiosynthesis Modules Market Emerging Trajectories
Module architecture is absorbing pressure from dual-use therapeutic applications while software layers face escalating validation requirements from pharmaceutical-grade manufacturing standards.
Microfluidic reaction chambers are absorbing conventional macro-scale synthesis workflows in next-generation module designs. Academic medical centers in the United States are piloting these systems for reduced precursor consumption and improved radiochemical yield consistency. The technology is absorbing cost structures previously allocated to bulk reagent handling infrastructure.
REACH obligations governing precursor chemical handling are extending documentation requirements across European module installations. Manufacturers must now incorporate automated tracking for acetonitrile and other solvent classifications in their control software. German and French nuclear medicine departments are prioritizing modules with pre-integrated compliance logging to preempt regulatory audit friction.
Service unbundling is separating hardware procurement from synthesis protocol licensing and ongoing technical support. Hospital buyers in Japan are negotiating standalone maintenance contracts and per-synthesis technical assistance rather than bundled multi-year agreements. This pattern is most visible in metropolitan Tokyo and Osaka markets where PMDA inspection frequency elevates operational risk sensitivity.
Automated Radiosynthesis Modules Market Segmentation
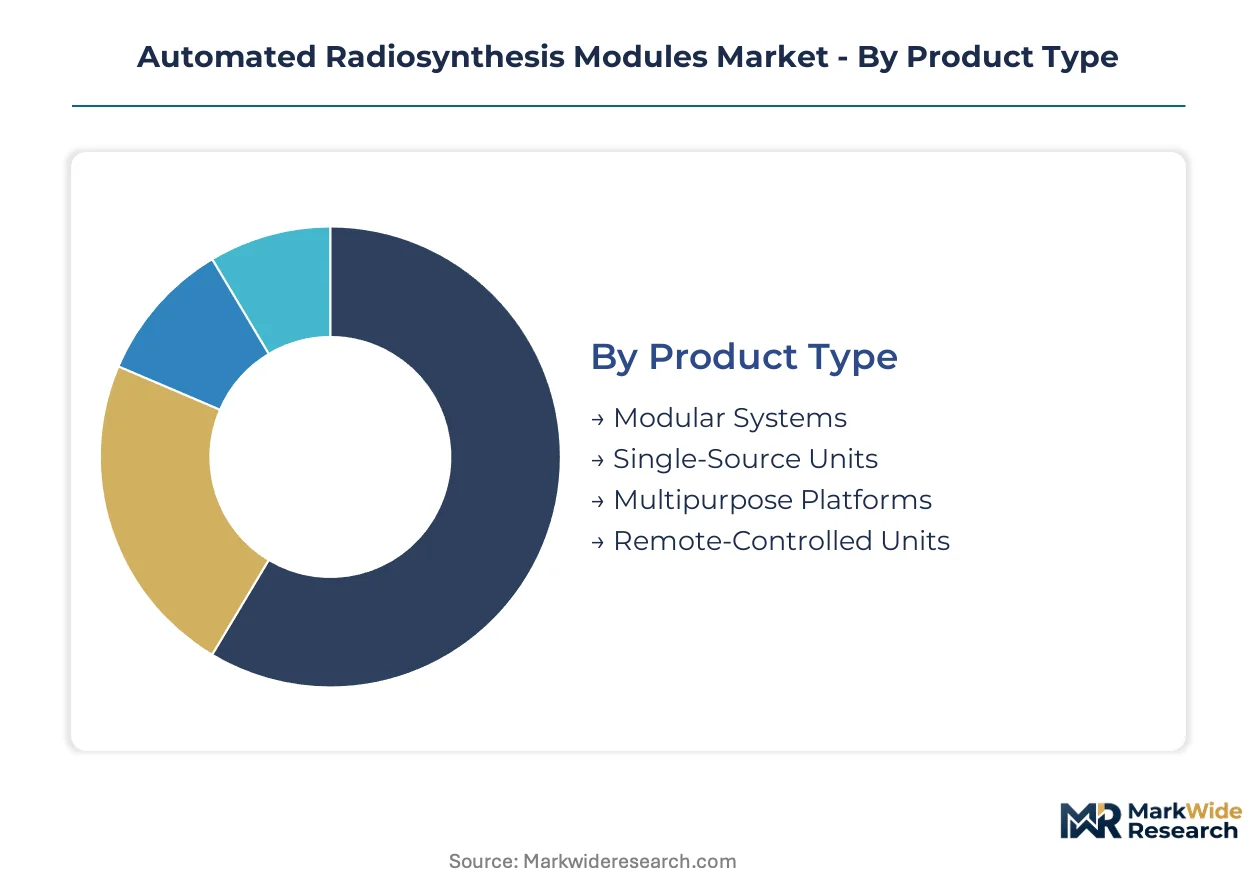
Automated radiosynthesis modules serve heterogeneous buyer profiles with divergent capital constraints, regulatory exposure, and throughput requirements. Segmentation reveals how equipment specifications bifurcate between high-volume pharmaceutical manufacturing and lower-throughput clinical or research environments.
Product Type:
Capital deployment thresholds and upgrade flexibility separate buyers across this category.
- Modular Systems:Reconfigurable architectures permit field upgrades without hardware replacement, reducing lifecycle costs for mid-sized nuclear medicine departments. Demand concentrates in German hospital clusters where Eckert & Ziegler and Synthra GmbH anchor regional service networks.
- Remote-Controlled Units:Fully enclosed synthesis environments with distant operator interfaces address ALARA compliance mandates for radiation exposure limits. Japanese nuclear medicine centers under PMDA inspection regimes drive premium positioning for these systems.
- Single-Source Units:Fixed-configuration systems for dedicated fluorine-18 or gallium-68 production occupy entry-tier procurement budgets.
- Multipurpose Platforms:Hybrid architectures accommodate both diagnostic and emerging therapeutic isotope synthesis protocols.
Modular Systems lead volumes today; Remote-Controlled Units are climbing the fastest as regulatory pressure intensifies.
Application:
Regulatory stringency and batch scale requirements fragment demand across use cases.
- Pharmaceutical Production:Contract manufacturing organizations scale tracer output for therapeutic radiopharmaceutical pipelines under FDA current good manufacturing practice mandates. EMA Annex 1 sterile manufacturing revisions in Europe are accelerating sensor array upgrades in these installations.
- Clinical Settings:Hospital nuclear medicine departments execute patient-specific synthesis with compressed turnaround windows dictated by isotope half-lives under two hours. Fluorine-18 precursor standardization is rebalancing equipment specifications toward this segment.
- Research Laboratories:Academic medical centers pilot microfluidic reaction chambers for reduced precursor consumption and yield consistency improvements.
- Academic Institutions:Training and protocol development environments prioritize reconfigurable systems for multi-isotope experimentation.
Clinical Settings dominate installed base; Pharmaceutical Production shows the steepest expansion trajectory as therapeutic pipelines mature.
Technology:
Core process capabilities determine integration complexity with existing cyclotron and imaging infrastructure.
- Radiochemistry:Multi-step automated synthesis, purification, and sterile filtration for Curie-scale isotope handling represents the foundational capability layer. REACH obligations governing precursor chemical handling in Europe are extending automated solvent tracking requirements into control software architectures.
- PET Imaging:Tracer production integration with scanner ecosystems drives deep hardware-software coupling, particularly in Siemens Healthineers and GE Healthcare installations.
- Automated Dispensing:Dose calibration and patient-specific formulation modules address final-stage quality control requirements.
- Radioisotope Production:Cyclotron interface systems for target irradiation and initial isotope extraction anchor upstream process chains.
Radiochemistry anchors current procurement volumes; PET Imaging integration capabilities are expanding most quickly as scanner ecosystem consolidation advances.
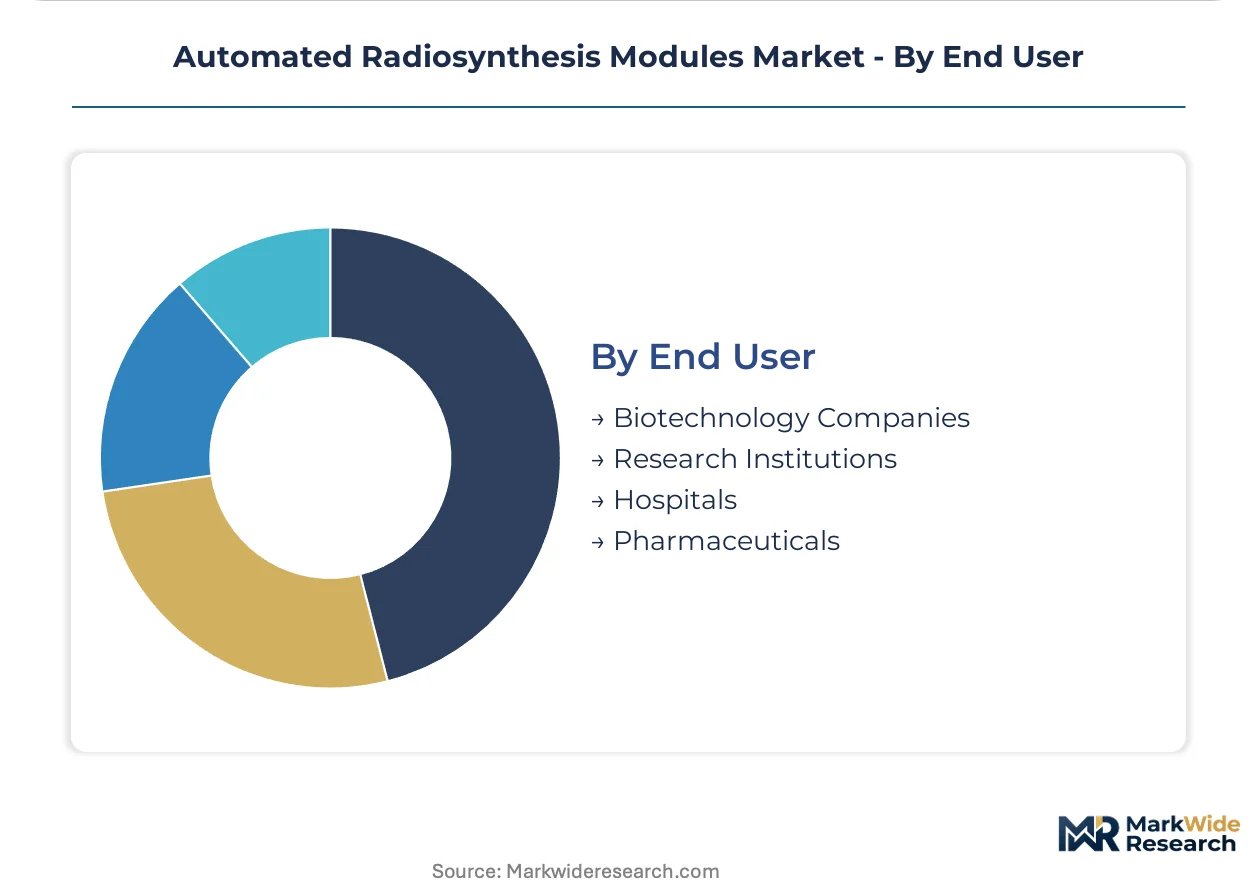
End User:
Operational scale and in-house versus outsourced production strategies differentiate buyer economics.
- Hospitals:Nuclear medicine departments with captive cyclotron facilities or regional isotope supply contracts represent the core installed base. FDA batch record mandates are compressing replacement cycles for legacy installations.
- Pharmaceuticals:Integrated radiopharmaceutical divisions and contract manufacturers scale therapeutic tracer production with pharmaceutical-grade validation requirements.
- Biotechnology Companies:Emerging therapeutic developers outsource synthesis or acquire modular capacity for pipeline-specific tracer programs.
- Research Institutions:Academic medical centers and national laboratories advance protocol development with flexible, multi-isotope capable systems.
Hospitals retain the largest installed base; Pharmaceuticals are gaining share fastest as therapeutic radiopharmaceutical manufacturing scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Berlin-Munich corridor anchors European production density for automated radiosynthesis modules, with concentrated manufacturing capabilities reducing lead times across Central European markets. FDA batch record mandates in the United States are compressing replacement cycles for legacy hospital installations. Japanese PMDA shielding standards differentiate product specifications for East Asian procurement.
United States
Hospital nuclear medicine departments drive module demand as PET tracer volumes climb for oncology and neurology diagnostics. FDA current good manufacturing practice requirements for positron emission tomography drugs mandate process validation architectures that reshape equipment specifications. The Greater Boston and Houston medical center clusters concentrate cyclotron facilities and module installations for regional isotope distribution networks.
Germany
Eckert & Ziegler and Synthra GmbH anchor production clusters around Berlin and Munich, serving Central European hospital networks with reduced service response times. EMA Annex 1 revisions on sterile manufacturing extend sensor array and environmental monitoring requirements across module installations. The Bavarian nuclear medicine corridor concentrates both manufacturing headquarters and reference clinical sites for protocol validation.
Japan
PMDA enforcement of additional shielding and containment standards creates market-specific product differentiation for automated synthesis systems. Operator radiation exposure limits under ALARA principles elevate demand for remote-controlled unit configurations. The Tokyo-Osaka metropolitan corridor concentrates nuclear medicine departments with captive cyclotron facilities and high inspection frequency sensitivity.
United Kingdom
Academic medical centers in London, Oxford, and Cambridge pilot microfluidic reaction chambers for reduced precursor consumption and yield consistency improvements. MHRA alignment with EMA sterile manufacturing standards shapes procurement specifications for hospital installations. The Southeast England research corridor concentrates protocol development activity that transfers to commercial module configurations.
India
CDSCO regulatory frameworks for radiopharmaceutical manufacturing are maturing as hospital networks expand PET-CT infrastructure into tier-2 cities. Import dependence for fluorine-18 and gallium-68 isotopes creates vulnerability to supply disruptions that module procurement strategies must address. The Delhi-Mumbai medical corridor concentrates early adopter installations with cyclotron facilities at AIIMS and Tata Memorial Centre reference sites.
Automated Radiosynthesis Modules Market Vendor Landscape
Global majors compete with regional champions across cyclotron network integration and scanner ecosystem coupling. The vendor base stratifies between diversified imaging conglomerates, specialized radiochemistry module fabricators, and emerging therapeutic-focused equipment developers. Three archetypes dominate: cyclotron-integrated system providers, modular architecture specialists, and pharmaceutical-grade validation enablers. Capacity expansion in therapeutic radiopharmaceutical production and technology licensing for microfluidic reaction chambers represent the dominant competitive vectors.
Among diversified imaging conglomerates, GE Healthcare and Siemens Healthineers exemplify cyclotron-network and scanner-ecosystem integration archetypes. Trasis S.A occupies a position within the modular architecture specialist tier, with reconfigurable systems that permit site-specific adaptation without hardware replacement. These three companies represent distinct strategic postures: network scale, ecosystem lock-in, and upgrade flexibility.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| IBA Radiopharma Solutions |
| Eckert & Ziegler |
| Synthra GmbH |
| Trasis S.A |
| Scintomics GmbH |
| Sofie Biosciences |
| Optimized Radiochemical Applications |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up radiochemistry specialists have consolidated module servicing networks across Germany and the United States, tightening pricing discipline while compressing aftermarket margins for independent service providers. This ownership concentration feeds directly into supply chain behavior, as consolidated buyers negotiate volume-based precursor procurement contracts that smaller nuclear medicine centers cannot replicate.
Pricing Analysis
Input-cost pass-through from fluorine-18 and gallium-68 isotope supply contracts dominates module pricing dynamics, with cyclotron network operators capturing margin through bundled isotope-plus-hardware agreements. Three-tier pricing structure across premium, standard, and economy levels separates remote-controlled units with full ALARA compliance from modular systems and entry-tier single-source configurations. Pricing pressure stems from EMA Annex 1 validation requirements that force sensor array upgrades in legacy installations. Hospital nuclear medicine departments exhibit highest price sensitivity due to capital budget constraints, while pharmaceutical contract manufacturers accept premium positioning for pharmaceutical-grade validation capabilities.
Supply Chain Analysis
Logistics and freight costs for Curie-scale isotope transport compress effective supply radius to under 200 kilometers from cyclotron facilities, anchoring module demand patterns to regional production clusters. Manufacturing concentrates in Germany, the United States, and Belgium, with Eckert & Ziegler and IBA Radiopharma Solutions anchoring European supply. Key component dependencies include lead shielding enclosures, automated valve manifolds, and sterile filtration assemblies sourced from specialized radiochemistry equipment fabricators. Single-source vulnerability in fluorine-18 target material supply creates disruption risk from geopolitical trade restrictions. Distribution runs through direct hospital procurement in mature markets and distributor-mediated sales in emerging nuclear medicine infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automated radiosynthesis modules market functions as a regulatory compounder, where each successive FDA current good manufacturing practice revision and EMA Annex 1 update forces equipment refresh cycles that expand addressable demand beyond organic PET tracer volume growth.
For Market Incumbents: Deepen cyclotron network integration to lock in captive isotope-plus-module bundled contracts before microfluidic reaction chamber technology matures to commercial scale. Prioritize backward integration into fluorine-18 precursor manufacturing to defend margin position against isotope supply cost volatility. Expand sensor array and environmental monitoring capabilities to preempt EMA Annex 1 compliance retrofit demand in European hospital installations. For New Entrants and Emerging Players: Microfluidic reaction chamber platforms offer a technology-first wedge into academic medical center procurement budgets where reduced precursor consumption justifies premium positioning despite unproven scale. Target India's tier-2 city hospital expansion as the most penetrable geography, where CDSCO regulatory maturation lags equipment installation timelines and creates first-mover positioning. Pursue per-synthesis technical assistance licensing rather than bundled hardware-service contracts to mirror Japan's unbundling pattern. For Investors and Strategic Acquirers: Cyclotron network operators and PET scanner ecosystem consolidators represent the most active acquirer categories in this space, driven by vertical integration imperatives to capture isotope-to-imaging value chains. Long-term viability hinges on therapeutic radiopharmaceutical pipeline scale-up sustaining module demand beyond diagnostic tracer saturation. Monitor alpha-emitter and beta-emitter therapeutic tracer FDA approval velocity as the critical inflection signal for capacity expansion investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA cGMP Compliance Pathway | Process validation architectures reshape module software specifications for pharmaceutical-grade manufacturing. |
| Microfluidic Platform Development | Reduced precursor consumption and yield consistency improvements attract academic medical center pilot budgets. |
| Cyclotron Network Expansion | Regional isotope production density directly determines module installation addressable market radius. |
| Remote-Controlled Unit Certification | ALARA compliance mandates under PMDA and EMA drive premium positioning for enclosed synthesis systems. |
| Therapeutic Tracer Manufacturing Scale-Up | Alpha-emitter and beta-emitter production pipelines expand module capacity requirements beyond diagnostic applications. |
Methodological Framework
Bottom-up hospital nuclear medicine department modeling reconciled against top-down cyclotron facility and PET scanner installation tracking forms the analytical core of this study. Primary interviews with radiochemistry module procurement officers, biomedical engineers, GPO contracts managers, and regulatory affairs specialists at FDA-registered PET drug manufacturers combined with secondary validation against FDA 510(k) filings, EMA medical device registrations, and hospital capital expenditure disclosures. Trade data from German and Belgian radiochemistry equipment exporters supplemented regional demand calibration.
Historical trendline analysis of module replacement cycles, isotope production capacity expansion, and PET tracer volume growth established baseline trajectory parameters across the projection horizon. Segmentation modeling incorporated product type tier, application setting, technology integration depth, and end-user operational scale dimensions. CAGRs derived from regression analysis of installed base evolution and average selling price movements, with therapeutic radiopharmaceutical pipeline maturation and regulatory compliance refresh cycles as industry-specific forecast inputs.
The model holds under stable isotope supply chain conditions and continued regulatory enforcement of current good manufacturing practice standards; deviation in cyclotron facility operational disruptions or accelerated microfluidic technology commercialization would shift replacement cycle assumptions and module specification demand. Forecasts reflect documented analytical parameters and stakeholder-derived operational constraints. Stakeholders should weight assumptions against their own facility upgrade timelines and regional regulatory inspection frequency patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Pharmaceutical Continuous Manufacturing Market
Pharmaceutical Equipment
Lyophilization Equipment Market
Pharmaceutical Equipment
Flip Top Vials Market
Pharmaceutical Equipment
Pharmaceutical Manufacturing Market
Pharmaceutical Equipment
Lyophilization Equipment and Services Market
Pharmaceutical Equipment
North America Pharmacy Automation Market
Pharmaceutical Equipment
Pharmaceutical Glass Ampoules Market
Pharmaceutical Equipment
Pharmaceutical Coating Equipment Market
Pharmaceutical Equipment
Sterile Fill-Finish Process Simulation and Media Fill Test Equipment Market
Pharmaceutical Equipment
Europe Pharmaceutical Isolator Market
Pharmaceutical Equipment
Global Pharmaceutical Cartridges Market
Pharmaceutical Equipment
Pharmaceutical Sterilization Equipment Market
Pharmaceutical Equipment
Global Contract Development and Manufacturing Organization (CDMO) Outsourcing Market
Pharmaceutical Equipment
North America and Europe Pharmaceutical Stability & Storage Services Market
Pharmaceutical Equipment
Asia-Pacific Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Pharmaceutical Storage and Material Handling Equipment Market