
 Lyophilization Equipment and Services Market | 2026-2036
Lyophilization Equipment and Services Market Size, Share, and Industry Trends Forecast 2026-2036
Lyophilization Equipment and Services Market Outlook
Buyer concentration among large biopharmaceutical contract manufacturers is pivoting toward integrated CDMOs that internalize lyophilization capacity rather than outsource to fragmented equipment vendors. Thermo Fisher Scientific Inc. leverages its laboratory-to-production equipment portfolio to anchor relationships across development scales. GEA Group competes through industrial-scale freeze dryer installations that dominate commercial biologics manufacturing facilities. Millrock Technology, Inc. specializes in precision laboratory systems that sustain R&D partnerships with emerging biotech firms.
Lyophilization equipment and services encompass vacuum-based sublimation systems that remove water from heat-sensitive biological materials at temperatures typically below −40°C and pressures under 0.1 mbar, preserving structural integrity for long-term storage and reconstitution. The primary commercial purpose centers on stabilizing parenteral biologics, vaccines, and cell therapies where thermal degradation would destroy therapeutic efficacy. Industrial freeze dryers occupy the largest installed base among product type segments due to biologics batch scaling requirements, while spray freeze drying represents the fastest-growing technology variant for nanoparticle and inhalable formulation applications. Maintenance services command durable revenue streams as regulatory validation cycles mandate periodic equipment qualification and re-qualification.
FDA cGMP guidelines and EMA Annex 1 revisions on sterile manufacturing impose stringent lyophilization cycle validation, driving replacement demand for equipment with enhanced process analytical technology capabilities. ISO 13485 and WHO TRS 961 standards further shape market access by requiring documented equipment qualification protocols for pharmaceutical exports. Stakeholders must monitor evolving regulatory expectations for continuous process verification and decide between capital-intensive in-house lyophilization investments versus strategic outsourcing to specialized CDMO networks.
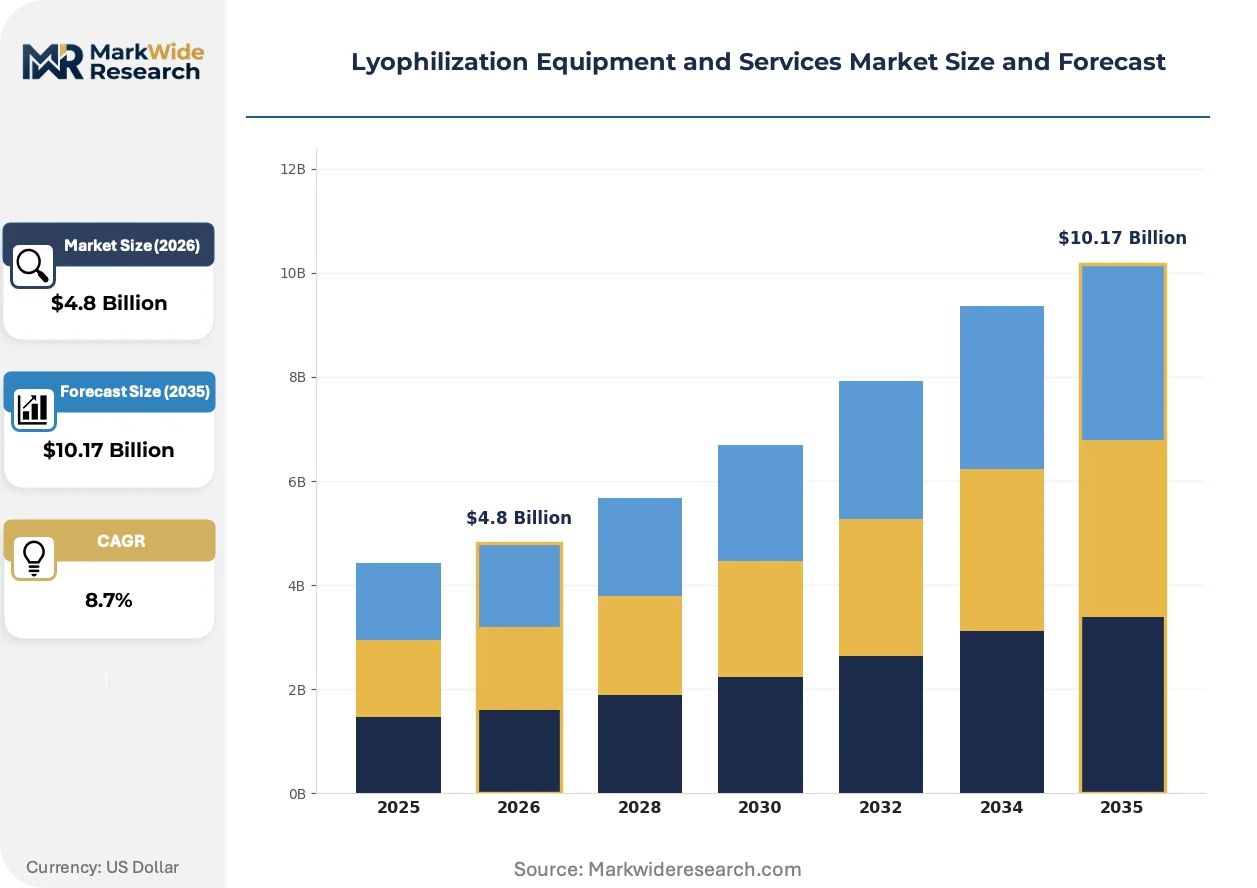
Market Dynamics
Biopharmaceutical contract manufacturers are consolidating lyophilization capacity internally, compressing demand for standalone equipment vendors while elevating process analytical technology requirements across all supplier tiers.
Growth Catalysts
- FDA cGMP sterile manufacturing mandates:Tightened container closure integrity rules are forcing facility upgrades and validation investments across parenteral drug producers.
- Cell therapy commercialization:Autologous and allogeneic cell products require ultra-low temperature stabilization protocols that standard biologics manufacturing cannot accommodate.
- China biologics manufacturing expansion:NMPA regulatory harmonization with ICH guidelines is accelerating domestic freeze-dryer procurement for export-capable facilities.
Market Restraints
- Stainless steel and vacuum pump supply concentration:German and Japanese precision component suppliers command extended lead times for industrial-scale chamber fabrication.
- Cycle development cost escalation:PAT-enabled equipment requires 40-60% longer validation timelines versus conventional systems, delaying revenue recognition.
- Thermal stabilization alternatives:Spray-drying and deep-cold chain logistics are capturing niche applications in vaccine distribution where portability outweighs shelf-life extension.
Strategic Opportunities
- Continuous manufacturing integration:FDA's Quality by Design initiative rewards real-time release testing capabilities that link lyophilization directly to upstream bioreactor operations.
- India CDMO capacity buildout:PLI scheme incentives for active pharmaceutical ingredients are extending into biologics infrastructure, creating demand for mid-scale freeze-dryer installations.
- Personalized medicine micro-batches:Precision dosing requirements for rare disease therapies favor smaller, flexible lyophilization units over traditional batch-scale systems.
Industry Challenges
- Process analytical technology engineering scarcity:Qualified professionals capable of integrating PAT sensors with legacy SCADA systems command premium compensation and extended recruitment cycles.
- IQ/OQ/PQ documentation burden:EMA Annex 1 revisions require re-qualification of existing installations, consuming technical resources that would otherwise support new capacity deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lyophilization Equipment and Services Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Freeze Dryers, Tray Dryers, Laboratory Freeze Dryers, Industrial Freeze Dryers End User: Pharmaceutical Companies, Biotechnology Firms, Research Laboratories, Food Processing Units Technology: Vacuum Technology, Hybrid Technology, Manifold Freeze Drying, Spray Freeze Drying Service Type: Maintenance Services, Calibration Services, Customization Services, Consulting Services |
| Companies Covered | Martin Christ Freeze-Drying Systems GmbH, Thermo Fisher Scientific Inc., GEA Group, Millrock Technology, Inc., IMA S.p.A., SP Industries, Labconco Corporation, Azbil Corporation, Tofflon Science and Technology Group Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lyophilization Equipment and Services Market Strategic Shifts
Equipment architecture and service delivery models are diverging as biopharmaceutical manufacturers prioritize operational flexibility over maximum throughput in facility design decisions.
Single-use containment systems for freeze-dryer loading and unloading are modularizing cleanroom configurations, allowing multi-product facilities to reconfigure barrier isolators between campaigns without structural renovation. Mid-scale CDMOs in Germany and Massachusetts are adopting these systems to accommodate both clinical and commercial batches within shared suites. This modularity is compressing facility commissioning timelines and reducing cross-contamination validation overhead for contract manufacturers serving multiple sponsors.
EMA's Annex 1 revision on sterile manufacturing mandates continuous environmental monitoring and automated contamination control strategies for lyophilization operations. The regulation requires real-time viable and non-viable particle detection integrated directly into freeze-dryer isolators. Commercial biologics facilities across the European Union are retrofitting existing chambers with enhanced sensor arrays or specifying these capabilities in new capital procurement, driving equipment differentiation toward compliance-enabled architectures.
After-sales service contracts are unbundling from equipment sales as biopharmaceutical buyers seek specialized validation and re-qualification providers independent of original manufacturers. Large molecule producers in the United States are segmenting maintenance procurement between mechanical service (retained with OEMs) and regulatory documentation (awarded to third-party qualification specialists). This bifurcation is most pronounced among multi-site operators seeking standardized validation protocols across geographically dispersed freeze-dryer fleets.
Lyophilization Equipment and Services Market Segmentation
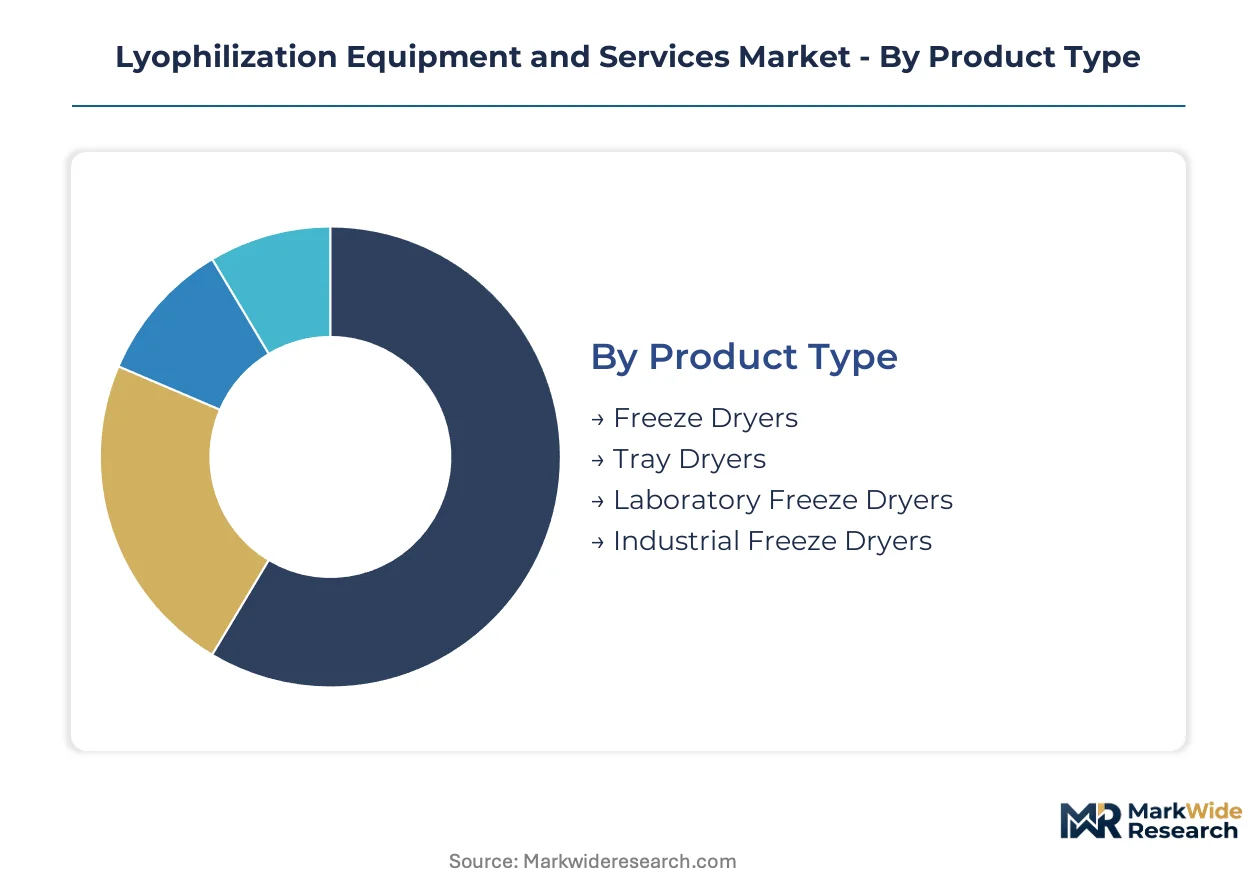
Segmentation in lyophilization equipment and services reveals how supply-side specialization aligns with distinct biopharmaceutical manufacturing requirements. Equipment vendors and service providers configure their offerings around batch scale, regulatory complexity, and integration depth demanded by specific end-use applications.
Product Type:
Supply concentration in precision vacuum chamber fabrication favors vendors with captive stainless steel processing capabilities and established pharmaceutical industry relationships.
- Industrial Freeze Dryers:These systems feature shelf areas exceeding 10 square meters and automated loading mechanisms designed for commercial biologics batch production. German and United States-based contract manufacturers absorb the majority of new installations as they expand capacity for monoclonal antibodies and complex injectables. FDA cGMP validation requirements for container closure integrity drive specification toward equipment with integrated process analytical technology.
- Laboratory Freeze Dryers:Compact units with shelf areas under 1 square meter support formulation development and cycle optimization prior to scale-up. Emerging biotechnology firms in Massachusetts and Bavaria concentrate demand here, prioritizing flexibility for small-batch clinical material production. These systems require less extensive IQ/OQ/PQ documentation, compressing procurement timelines compared to commercial-scale alternatives.
- Tray Dryers:Convective drying systems serve applications where vacuum sublimation is unnecessary or cost-prohibitive. Food processing facilities and certain active pharmaceutical ingredient producers deploy these for intermediate drying steps.
- Freeze Dryers:General-purpose systems span laboratory through pilot-scale configurations, offering modular shelf arrangements and interchangeable condenser capacities. Academic research institutions and smaller contract development organizations represent the core customer base.
Industrial freeze dryers absorb the bulk of installed capacity; laboratory freeze dryers are expanding most quickly as development pipelines thicken.
End User:
Cost tier differentiation separates capital-intensive in-house installations from outsourced processing arrangements across customer categories.
- Pharmaceutical Companies:Large molecule producers with established parenteral portfolios internalize lyophilization capacity to protect proprietary formulation knowledge and ensure supply chain control. These buyers specify equipment with continuous manufacturing compatibility and real-time release testing capabilities. EMA Annex 1 compliance requirements dominate European procurement specifications.
- Biotechnology Firms:Cell therapy developers and gene therapy specialists require ultra-low temperature protocols that exceed standard biologics processing parameters. These firms concentrate in Cambridge, Massachusetts and Basel, Switzerland, where specialized CDMO partnerships supplement limited internal manufacturing infrastructure.
- Research Laboratories:Academic and government institutions prioritize equipment versatility over throughput, supporting multi-disciplinary applications from vaccine development to materials science. Funding constraints favor mid-scale systems with shared service arrangements.
- Food Processing Units:Nutraceutical and specialty food producers employ lyophilization for premium product categories where texture preservation justifies processing costs. These applications face less stringent regulatory documentation requirements than pharmaceutical uses.
Pharmaceutical companies deploy the largest cumulative investment; biotechnology firms are climbing the fastest as novel modality pipelines mature.
Technology:
Application-specific performance requirements determine technology selection, with nanoparticle and inhalable formulation demands pushing innovation boundaries.
- Spray Freeze Drying:Atomization of liquid feedstock into cryogenic media followed by vacuum sublimation produces porous particles optimized for pulmonary delivery and rapid reconstitution. This technology is gaining adoption among formulation specialists developing inhalable biologics and vaccine adjuvants where particle morphology directly impacts efficacy.
- Vacuum Technology:Conventional sublimation systems operating below 0.1 mbar pressure remain the dominant architecture for commercial biologics stabilization. These systems balance throughput, reliability, and regulatory qualification precedent that alternative technologies have not yet matched.
- Manifold Freeze Drying:Flask-based systems accommodate small volumes and diverse container formats during early-stage development. Research laboratories and clinical manufacturing suites deploy these for flexibility in handling experimental formulations.
- Hybrid Technology:Combined drying approaches integrate vacuum sublimation with alternative dehydration methods for specific substrate requirements. Niche applications in botanical extracts and certain diagnostic reagents utilize these configurations.
Vacuum technology retains the dominant installed base; spray freeze drying is gaining share fastest as pulmonary delivery applications expand.
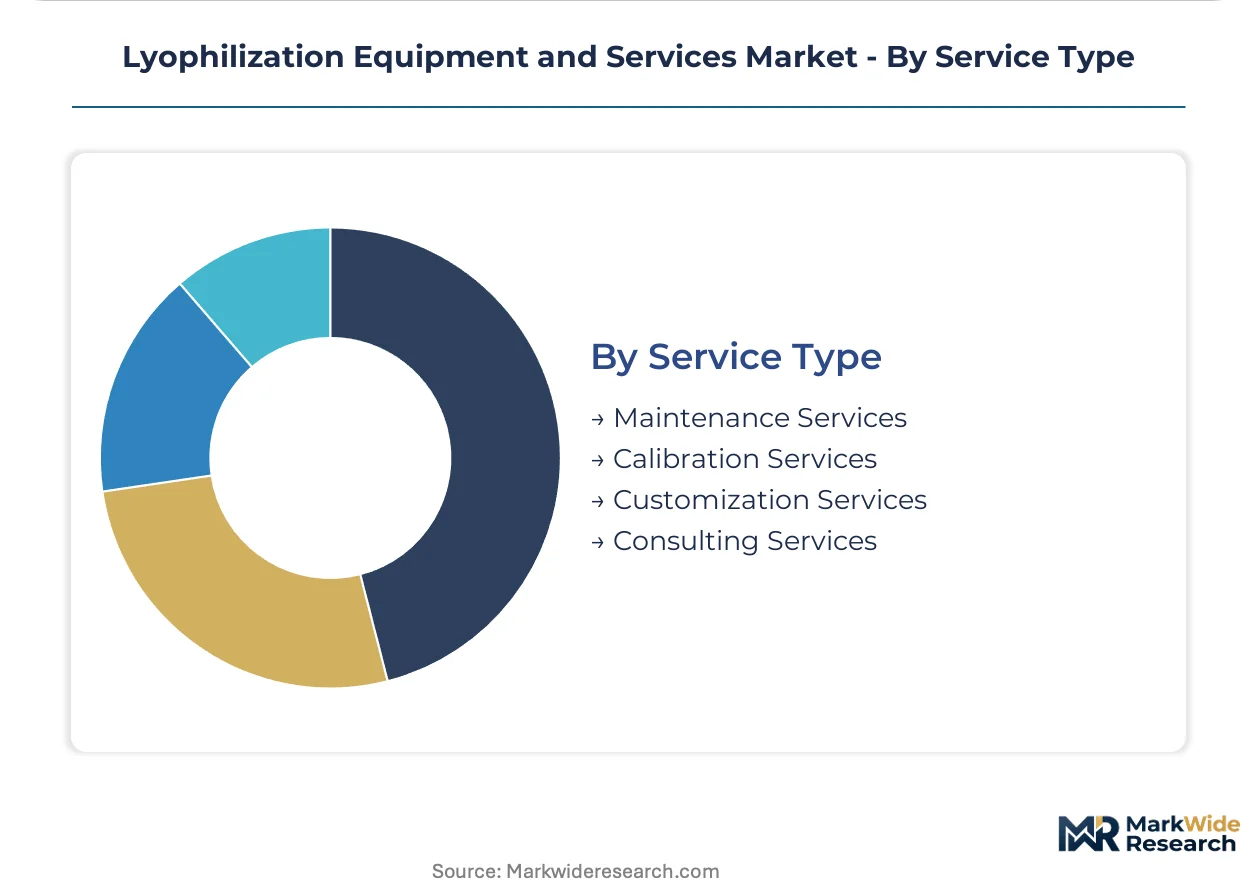
Service Type:
Customer type fragmentation between multi-site operators and single-facility producers shapes procurement patterns for post-sale support.
- Maintenance Services:Preventive and corrective maintenance contracts cover vacuum pump refurbishment, refrigeration system servicing, and chamber integrity verification. These services generate recurring revenue streams tied to equipment operating life, with regulatory re-qualification requirements extending contract durations beyond mechanical necessity alone.
- Calibration Services:Temperature mapping, pressure sensor verification, and shelf uniformity studies support ongoing compliance with FDA process validation guidance. Third-party metrology specialists are capturing share from original equipment manufacturers as buyers seek independent documentation.
- Customization Services:Chamber modifications, control system upgrades, and isolator integration adapt existing equipment to evolving product portfolios. CDMOs with multi-sponsor obligations rely on these services to reconfigure facilities between campaigns.
- Consulting Services:Cycle development, technology transfer, and regulatory strategy support assist manufacturers optimizing lyophilization processes for new molecular entities. These engagements typically precede capital equipment procurement or facility design decisions.
Maintenance services command the largest ongoing revenue commitment; calibration services are expanding most quickly as EMA Annex 1 and FDA guidance tighten documentation requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biopharmaceutical manufacturing clusters in Germany, the United States, China, India, and Switzerland absorb the majority of lyophilization equipment procurement. FDA and EMA regulatory tightening on sterile manufacturing drives replacement cycles across these jurisdictions.
United States
Cell therapy commercialization and mRNA vaccine manufacturing sustain demand for ultra-low temperature stabilization systems. FDA cGMP sterile manufacturing mandates force facility upgrades across parenteral drug producers. Greater Boston and San Francisco Bay Area biotech clusters concentrate procurement of laboratory-scale freeze dryers for early-stage development.
Germany
Industrial-scale biologics manufacturing and contract development operations anchor equipment demand. EMA Annex 1 revisions on sterile manufacturing impose continuous environmental monitoring requirements. Bavarian pharmaceutical corridors retrofit existing chambers with enhanced sensor arrays to meet compliance deadlines.
China
Domestic biologics manufacturing expansion accelerates freeze-dryer procurement for export-capable facilities. NMPA regulatory harmonization with ICH guidelines elevates validation standards. Yangtze River Delta pharmaceutical zones concentrate new capital investments in integrated lyophilization suites.
India
CDMO capacity buildout for biologics infrastructure creates demand for mid-scale freeze-dryer installations. PLI scheme incentives for active pharmaceutical ingredients extend into downstream processing equipment. Maharashtra and Gujarat pharmaceutical manufacturing belts attract equipment vendors establishing local service networks.
Switzerland
Specialized biologics formulation and precision manufacturing sustain premium equipment demand. Swissmedic guidelines on container closure integrity align with EMA standards. Basel biotech corridors maintain concentrated procurement of process analytical technology-enabled systems.
Lyophilization Equipment and Services Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue modular and single-use configurations to bypass incumbent validation advantages. The vendor landscape consolidates around three archetypes: diversified laboratory-to-production equipment conglomerates, precision vacuum chamber specialists with captive fabrication capabilities, and regional system integrators serving cost-sensitive markets. Competitive positioning hardens through M&A activity targeting PAT engineering talent and strategic partnerships linking equipment supply with CDMO facility construction.
Among diversified equipment conglomerates, Thermo Fisher Scientific Inc. anchors relationships across development scales through portfolio breadth. German precision fabricators Martin Christ Freeze-Drying Systems GmbH and GEA Group exemplify the industrial-scale chamber specialization archetype, leveraging captive stainless steel processing capabilities. Tofflon Science and Technology Group Co., Ltd. represents regional system integrators expanding service networks into emerging biologics manufacturing zones.
| Leading Market Players |
|---|
| Martin Christ Freeze-Drying Systems GmbH |
| Thermo Fisher Scientific Inc. |
| GEA Group |
| Millrock Technology, Inc. |
| IMA S.p.A. |
| SP Industries |
| Labconco Corporation |
| Azbil Corporation |
| Tofflon Science and Technology Group Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Equipment certification tiers separate FDA-validated industrial systems from laboratory-scale units without pharmaceutical-grade documentation, creating a bifurcation where premium pricing aligns with German and Japanese stainless steel fabrication capabilities while cost-sensitive buyers turn to regional integrators in China and India for mid-scale alternatives. This tier divergence manifests in procurement patterns: large biopharmaceutical contract manufacturers absorb extended lead times and higher capital outlays for EMA Annex 1-compliant architectures, whereas emerging biotechnology firms prioritize flexible laboratory systems with compressed validation timelines and lower upfront commitments.
Pricing Analysis
High-volume commercial biologics manufacturers trade margin for throughput certainty, while precision laboratory equipment vendors capture premium returns on smaller batch configurations. Three-tier pricing structure across premium, standard, and economy levels reflects validation depth, with FDA cGMP-qualified industrial freeze dryers commanding substantial premiums over research-grade alternatives. Cost compression in mid-scale equipment is intensifying because Chinese and Indian system integrators are expanding service networks and localizing component sourcing. Biotechnology firms with limited manufacturing infrastructure exhibit highest price sensitivity, whereas integrated CDMOs prioritize total cost of ownership over initial capital expenditure.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and Switzerland anchor hub-and-spoke patterns for precision vacuum chamber components, with satellite facilities in India and China serving cost-optimized mid-scale markets. Supply concentration rests on German and Japanese precision component suppliers for industrial-scale chamber fabrication, Chinese electrical and control system manufacturing, and Swiss sensor and instrumentation specialists. Single-source vulnerability runs through specialized stainless steel processing capabilities concentrated among Bavarian fabricators. Distribution runs through direct OEM relationships for large pharmaceutical manufacturers and regional distributor networks for smaller biotechnology and research laboratory customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EMA Annex 1 revisions on sterile manufacturing erect substantial compliance barriers that favor established equipment vendors with documented qualification protocols and captive validation engineering teams, effectively moating compliant incumbents from price-competitive challengers lacking regulatory precedent.
For Market Incumbents: Deepen captive stainless steel processing capabilities to insulate against German and Japanese supplier lead time volatility, while expanding process analytical technology engineering benches to address qualified professional scarcity. Patent-protected isolator integration architectures and continuous manufacturing compatibility specifications defend against modular single-use entrants. Capacity addition in Yangtze River Delta and Maharashtra pharmaceutical corridors captures China and India biologics expansion. For New Entrants and Emerging Players: FDA cGMP sterile manufacturing mandates in the United States open a window for specialized validation and re-qualification service providers independent of original equipment manufacturers. Mid-scale CDMOs in Greater Boston and Bavaria represent the most penetrable customer segment, as these operators seek standardized protocols across geographically dispersed freeze-dryer fleets. A go-to-market angle anchored on unbundled regulatory documentation services—separating mechanical maintenance from compliance qualification—addresses procurement bifurcation trends among multi-site operators. For Investors and Strategic Acquirers: Re-rating potential sits with precision vacuum chamber specialists possessing captive fabrication capabilities and established pharmaceutical industry relationships, given EMA and FDA regulatory tightening that privileges vendors with proven validation track records. The five-to-ten-year viability window favors equipment providers with backward integration into stainless steel processing and forward integration into PAT-enabled service contracts. The signal to watch is CDMO consolidation patterns: accelerating internalization of lyophilization capacity suggests equipment vendor margin compression, whereas sustained multi-sponsor outsourcing favors specialized service providers.| Strategic Initiative | Industry Significance |
|---|---|
| Process Analytical Technology Integration | FDA Quality by Design initiative rewards real-time release testing capabilities linking lyophilization to upstream bioreactor operations. |
| Single-Use Containment System Deployment | Modular cleanroom configurations allow Massachusetts and Bavarian CDMOs to reconfigure barrier isolators between campaigns without structural renovation. |
| Regional Service Network Expansion | Local validation and re-qualification capabilities in Maharashtra and Gujarat pharmaceutical belts address PLI scheme-driven biologics infrastructure growth. |
| Continuous Manufacturing Compatibility Investment | Equipment architectures supporting direct upstream integration capture replacement demand from facilities upgrading for EMA Annex 1 compliance. |
| PAT Engineering Talent Acquisition | Qualified professionals capable of integrating sensors with legacy SCADA systems command premium compensation, creating defensive moats through human capital. |
Study Parameters
FDA 483 inspection observations, EMA GMP inspection deficiency data, and ISO 13485 certification registries formed the secondary backbone, supplemented by trade flow records for freeze-dryer component imports and pharmaceutical capital expenditure disclosures. Primary interviews with biopharmaceutical manufacturing executives, regulatory affairs directors, CDMO procurement leads, and aftermarket service heads validated equipment procurement timelines and validation burden estimates. Bottom-up segmentation modeling triangulated against top-down market sizing derived from installed base analysis and replacement cycle assumptions.
Historical trendline analysis of biologics manufacturing capacity expansion and regulatory inspection enforcement patterns informed projection frameworks across the analysis window. Segmentation dimensions encompassed product scale tier, end-user category, technology architecture, and service type intensity. CAGRs emerged from curve-fitting approaches applied to validated data points rather than single-source extrapolation. Industry-specific forecast inputs included cell therapy pipeline maturation rates and NMPA regulatory harmonization milestones affecting China biologics export facility investments.
The model assumes a particular technology adoption path; alternative pathways for spray freeze drying in pulmonary delivery applications would alter the outlook if inhalable biologics development accelerates beyond current clinical trial trajectories. Forecasts reflect documented assumptions regarding regulatory enforcement consistency, stainless steel supply availability, and qualified engineering labor pool expansion. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Sterile Fill-Finish Process Simulation and Media Fill Test Equipment Market
Pharmaceutical Equipment
Medication Dispenser Market
Pharmaceutical Equipment
Pharmaceutical CDMO Market
Pharmaceutical Equipment
Europe Formulation Development Outsourcing Market
Pharmaceutical Equipment
Pharmaceutical Equipment Market
Pharmaceutical Equipment
Pharmaceutical Manufacturing Market
Pharmaceutical Equipment
Global Rotary Tablet Press Market
Pharmaceutical Equipment
Asia-Pacific CDMO Market
Pharmaceutical Equipment
Vials and Ampoules Market
Pharmaceutical Equipment
Pharmaceutical Hot Melt Extrusion Equipment Market
Pharmaceutical Equipment
Flip Top Vials Market
Pharmaceutical Equipment
Pharmaceutical Cleaning Validation Market
Pharmaceutical Equipment
Vial Adaptors for Reconstitution Drug Market
Pharmaceutical Equipment
Lyophilization Equipment Market
Pharmaceutical Equipment
US and Europe Pharmaceutical Manufacturing Market
Pharmaceutical Equipment
Sterile Injectable Contract Manufacturing Market