
 US Peripheral Vascular Devices and Accessories Market | 2026-2036
US Peripheral Vascular Devices and Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
US Peripheral Vascular Devices and Accessories Market Intelligence
Minnesota's medical technology corridor is rewriting supply chain dynamics for vascular intervention platforms. Medtronic leverages its deep manufacturing infrastructure in the state to sustain catheter and guidewire leadership. Boston Scientific Corporation anchors East Coast production capacity while Abbott competes through diversified stent and balloon portfolios across the South and Southwest.
Peripheral vascular devices and accessories encompass stents, catheters, guidewires, and balloons engineered from metal alloys, polymers, and biodegradable substrates to restore or maintain blood flow in vessels outside the coronary and cerebral circulations. These instruments deploy through minimally invasive access sites, typically requiring 5-8 French sheath compatibility and fluoroscopic guidance for precise lesion crossing. The stent category dominates revenue contribution due to recurring restenosis interventions, while biodegradable materials represent the fastest-growing material dimension as clinicians pursue reduced long-term inflammation profiles. Ambulatory surgical centers are capturing disproportionate procedural volume growth, shifting the end-user margin pool away from traditional inpatient settings.
FDA premarket notification and premarket approval pathways govern device commercialization, with the agency's Breakthrough Devices Program accelerating access for novel thrombectomy platforms. NHTSA transport regulations and OSHA bloodborne pathogen standards shape accessory sterilization and handling protocols across manufacturing and clinical environments. Stakeholders must monitor CMS reimbursement calibration for peripheral interventions as site-of-service differentials between hospitals and ambulatory centers reshape procurement economics.
Market Dynamics
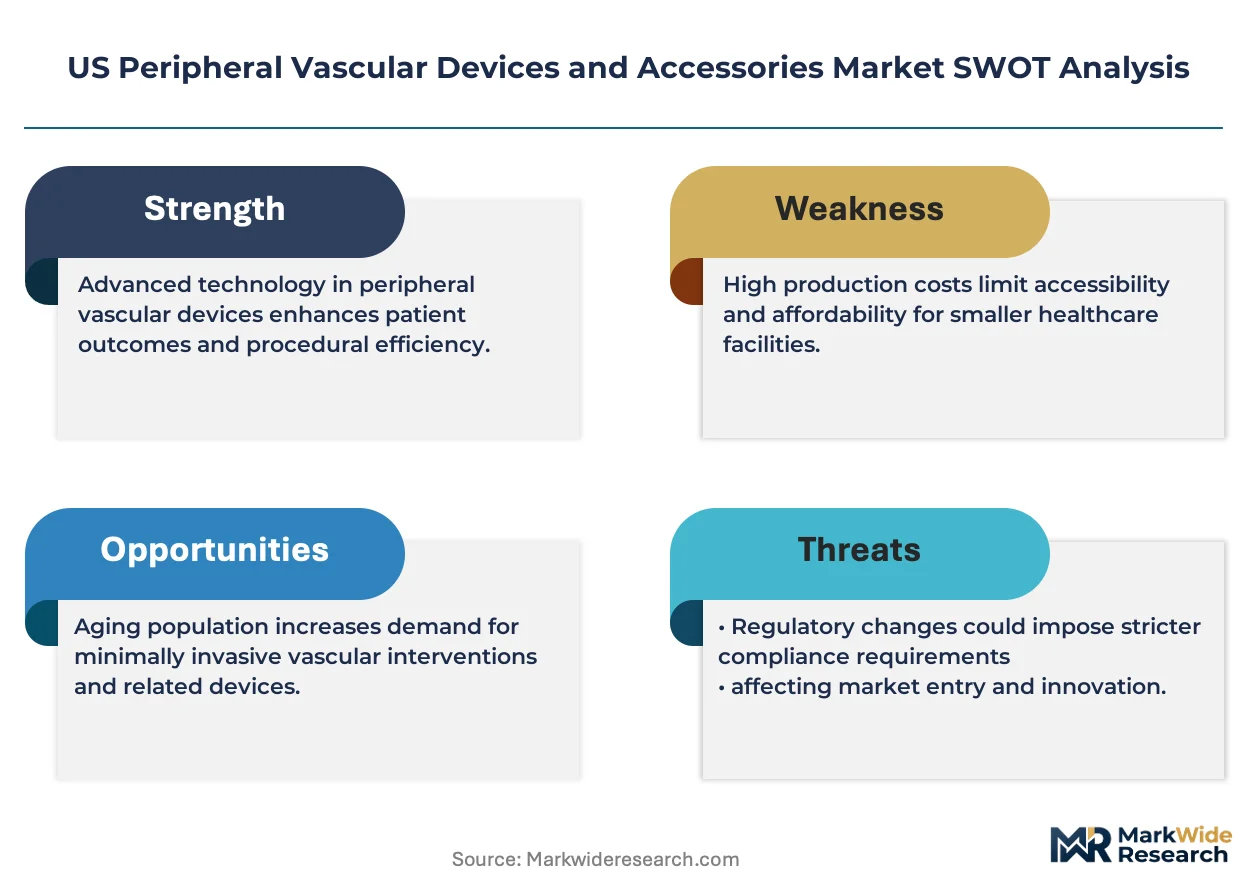
Ambulatory surgical centers are capturing procedural volume from inpatient settings, compressing reimbursement differentials and forcing manufacturers to reconfigure distribution economics around lower-acuity sites.
Growth Catalysts
- Site-of-service expansion:Ambulatory surgical centers in the Southeast and Midwest corridors are adding interventional suites, creating concentrated demand pockets for catheter and guidewire platforms.
- Biodegradable material innovation:Polymer and magnesium alloy stents reduce long-term inflammation profiles, pulling adoption from permanent metal implants in restenosis-prone lesions.
- Breakthrough Devices Program:FDA's accelerated pathway compresses commercialization timelines for novel thrombectomy systems, rewarding first-mover clinical data packages.
Market Restraints
- Nitinol supply concentration:Shape-memory alloy sourcing clusters with a limited supplier base, exposing stent and guidewire manufacturers to price volatility and allocation risk.
- Premarket approval friction:FDA's PMA pathway for novel stent designs demands extensive clinical trials, extending capital lockup periods and deterring mid-tier entrants.
- Balloon catheter commoditization:Standard angioplasty platforms face pricing pressure from private-label alternatives, compressing margin pools in the high-volume segment.
Strategic Opportunities
- Rural hospital penetration:Underserved markets in the Mountain West and Great Plains present white space for teleproctoring-supported intervention programs.
- Drug-coated balloon convergence:Paclitaxel-eluting platforms paired with bioresorbable scaffolds create combination therapy categories outside stent-dominant revenue models.
- CMS reimbursement calibration:Site-neutral payment policies incentivize manufacturers to bundle device and service offerings for ambulatory center procurement committees.
Industry Challenges
- Interventional cardiologist pipeline constraints:Fellowship program output lags procedural volume growth, creating staffing bottlenecks for expanded site networks.
- Quality management system recertification:ISO 13485 surveillance audits demand sustained documentation overhead across multi-site manufacturing footprints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Peripheral Vascular Devices and Accessories Market |
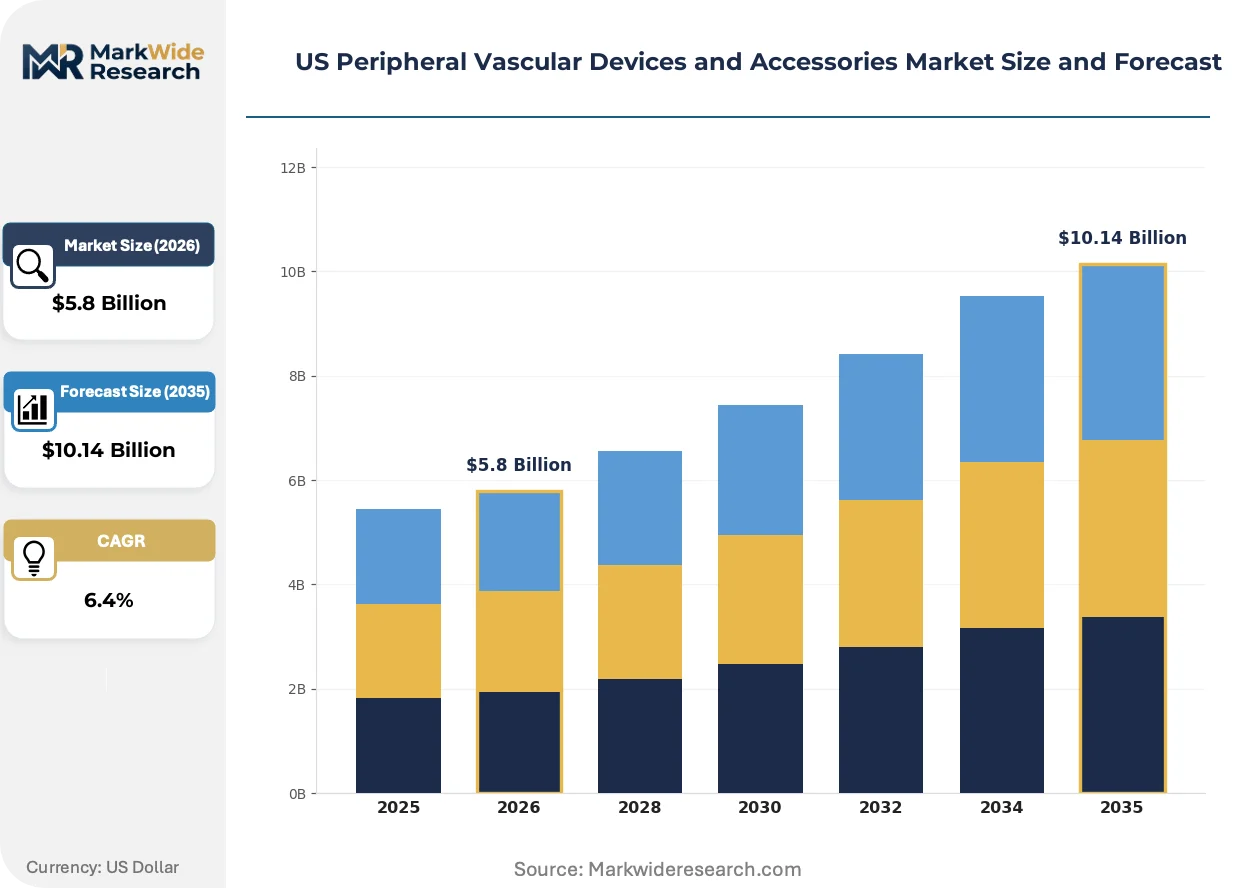
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Stents, Catheters, Guidewires, Balloons Material: Metal, Polymer, Coated, Biodegradable End User: Hospitals, Clinics, Ambulatory Surgical Centers, Specialty Centers Application: Angioplasty, Thrombectomy, Aneurysm Repair, Bypass Surgery |
| Companies Covered | Medtronic, Boston Scientific Corporation, Abbott, Terumo Corporation, BD, Koninklijke Philips N.V., Cook Group, W. L. Gore & Associates, BIOTRONIK SE & Co. KG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Peripheral Vascular Devices and Accessories Market Strategic Shifts & Innovations
Material science advances and regulatory pathway optimization are compressing product lifecycles while shifting competitive advantage toward integrated clinical evidence generation.
Bioresorbable vascular scaffolds are migrating from coronary to peripheral applications as magnesium and polymer formulations demonstrate comparable mechanical performance with reduced late thrombotic risk. Large academic medical centers in the Northeast and California are piloting these platforms in below-the-knee lesions. The technology is migrating from niche salvage procedures toward first-line de novo lesion treatment, expanding addressable procedure volumes.
OSHA bloodborne pathogen standards are tightening sterilization validation requirements for accessory manufacturers, mandating documented pathogen inactivation across reprocessing cycles. Reusable catheter and sheath suppliers face elevated compliance costs and extended validation timelines. The sterilization services segment is consolidating around third-party providers with dedicated vascular device expertise.
Hospital procurement committees are unbundling device selection from physician preference item contracts, creating direct commercial relationships between manufacturers and supply chain executives. Traditional distributor margins are compressing as consignment and vendor-managed inventory models displace stock-and-ship arrangements. The shift is most visible in integrated delivery networks across Texas and Florida, where centralized contracting authority has consolidated purchasing decisions.
US Peripheral Vascular Devices and Accessories Market Segmentation
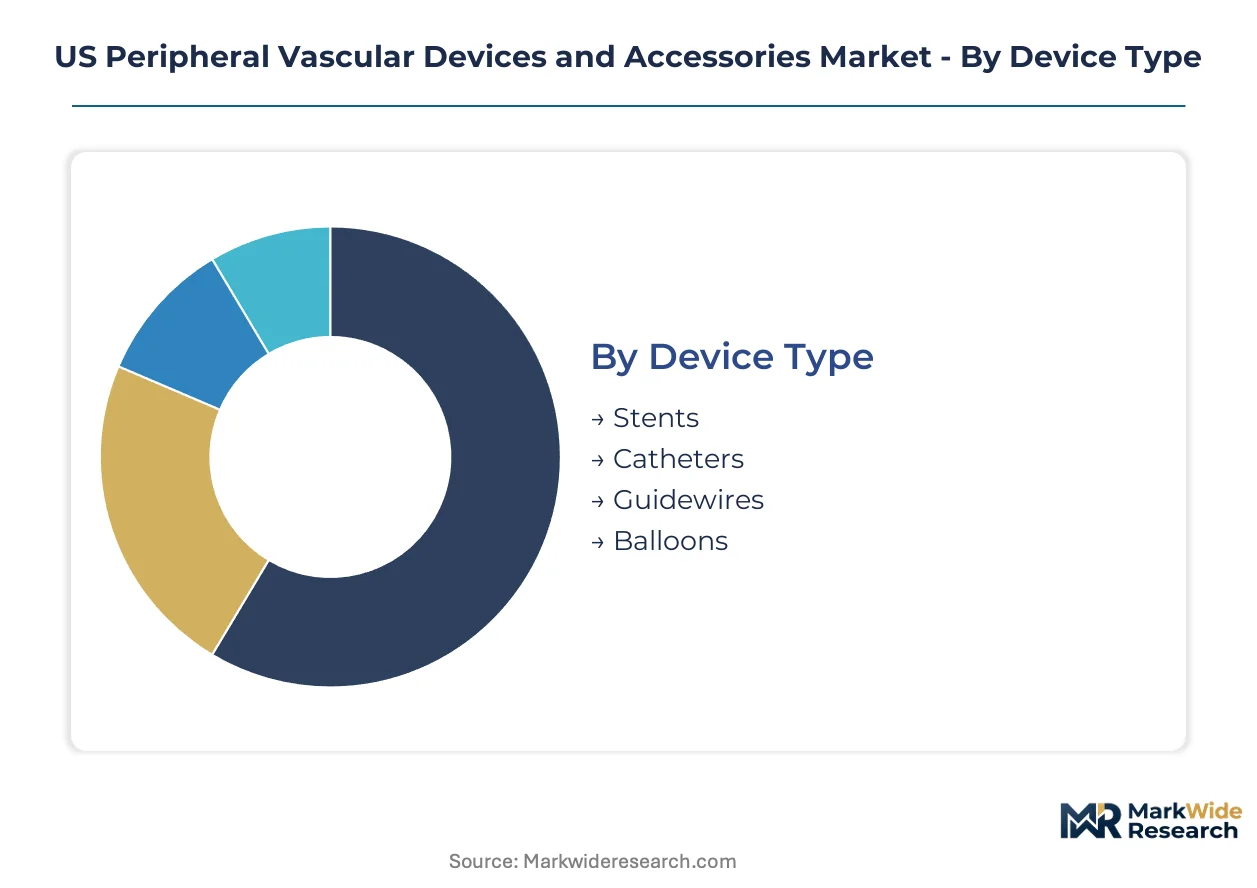
Segmentation in peripheral vascular devices reveals how procurement cycles, reimbursement pathways, and clinical workflows fragment demand across incompatible use cases. Manufacturers must align product portfolios to distinct velocity profiles—some segments turn inventory quarterly, others annually—while navigating divergent regulatory and sterilization requirements.
Device Type:
Catheter platforms rotate through clinical inventory fastest due to single-use protocols and high procedural throughput, while stent systems lock capital longest through consignment models and restenosis-driven replacement cycles.
- Stents:Self-expanding nitinol and balloon-expandable platforms address iliac, femoropopliteal, and infrapopliteal lesions. Demand clusters in Southeast hospital systems where diabetes prevalence drives repeat intervention volumes. Recurring restenosis creates predictable replacement revenue but demands sustained clinical evidence for CMS coverage.
- Catheters:Diagnostic and interventional catheters in 4-7 French configurations enable lesion crossing and therapeutic delivery. Ambulatory surgical centers in the Midwest corridor consume disproportionate volumes as site-of-service migration accelerates. FDA 510(k) clearance pathways compress commercialization timelines relative to PMA-track devices.
- Guidewires:Hydrophilic and hydrophobic wire platforms in 0.014-0.035 inch diameters support access and lesion navigation.
- Balloons:Standard and high-pressure angioplasty platforms face commoditization pressure from private-label alternatives.
Catheters anchor the volume base while biodegradable-eligible stent platforms gain share at the steepest rate.
Material:
Cost tiers stratify sharply—permanent metal alloys dominate high-volume, price-sensitive procedures while premium biodegradable substrates command markup in restenosis-prone anatomies.
- Metal:Nitinol and cobalt-chromium alloys deliver shape memory and radial force for self-expanding stent applications. Supply concentrates with limited specialty foundries, exposing manufacturers to allocation risk during raw material volatility.
- Biodegradable:Magnesium alloy and polymer formulations—polylactic acid, polycaprolactone—degrade to restore native vessel physiology. Academic medical centers in California and Massachusetts pilot below-the-knee applications where permanent implants historically failed.
- Polymer:Durable thermoplastics and elastomers form catheter bodies, sheaths, and delivery system components.
- Coated:Drug-eluting and passive surface modifications reduce thrombogenicity and smooth muscle proliferation.
Metal substrates anchor the volume base while biodegradable materials climb the fastest as clinical data accumulates.
End User:
Customer type determines purchasing authority structure—hospitals retain committee-based decision-making while ambulatory centers enable direct manufacturer relationships.
- Hospitals:Inpatient and outpatient departments within integrated delivery networks maintain capital equipment and inventory through distributor relationships. Texas and Florida health systems consolidate procurement authority at network level, compressing vendor margins.
- Ambulatory Surgical Centers:Freestanding interventional suites in the Southeast and Midwest capture migrating procedural volume from hospital campuses. Direct consignment arrangements with manufacturers displace traditional distributor intermediaries.
- Clinics:Office-based labs and vascular access centers perform diagnostic and limited therapeutic procedures.
- Specialty Centers:Dedicated vein clinics and wound care facilities address chronic venous insufficiency and limb salvage.
Hospitals anchor the volume base while ambulatory surgical centers expand most quickly as site-neutral reimbursement takes hold.
Application:
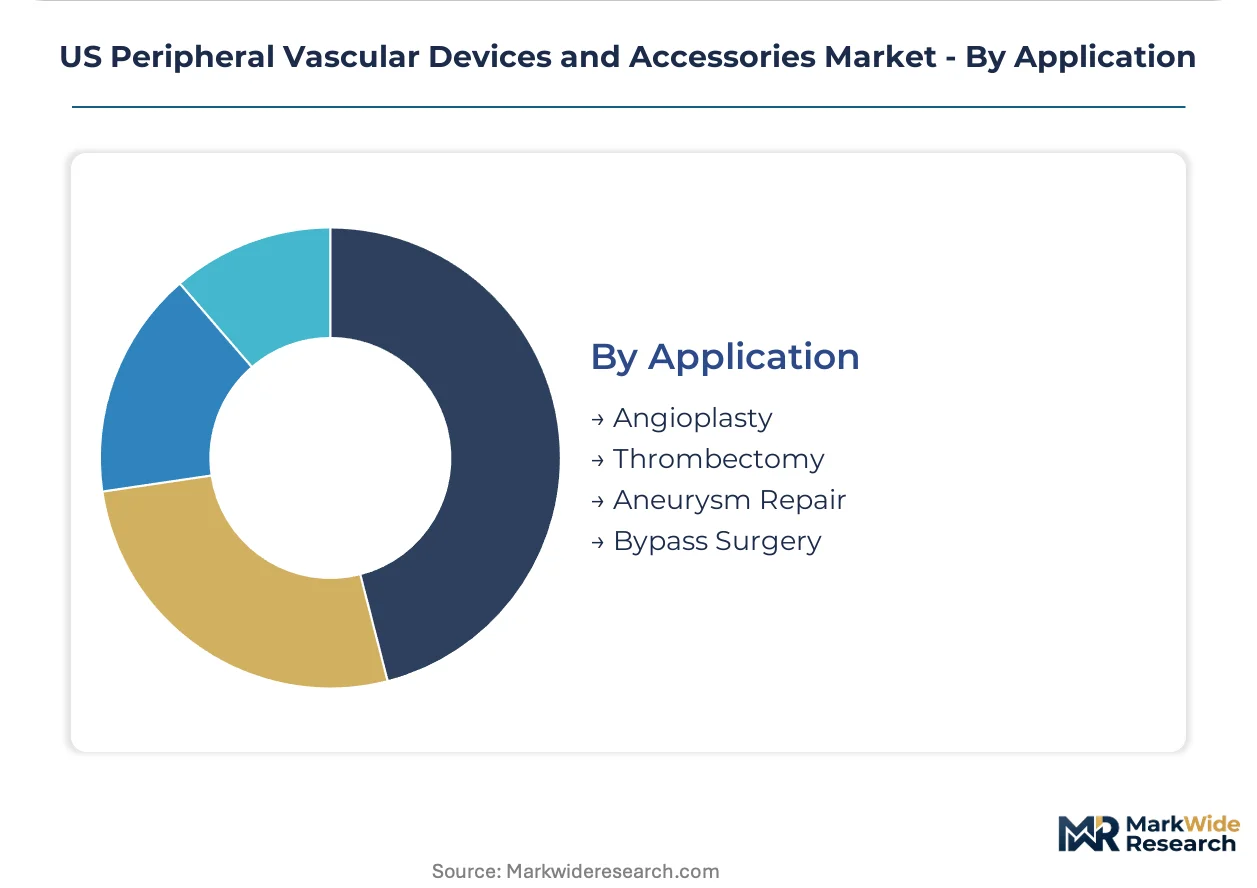
Procedure maturity fragments margin profiles—angioplasty platforms face reimbursement compression while thrombectomy systems command premium through breakthrough technology designation.
- Angioplasty:Balloon dilation remains the foundational peripheral intervention across femoropopliteal and infrapopliteal territories. Standard platforms face pricing pressure; drug-coated balloon variants sustain margin through outcomes-based contracting.
- Thrombectomy:Mechanical and aspiration systems address acute limb ischemia and venous thromboembolism. FDA Breakthrough Devices Program accelerates market access for novel platforms with demonstrable clot burden reduction.
- Aneurysm Repair:Endovascular sealing and stent-graft deployment address abdominal and peripheral aneurysmal disease.
- Bypass Surgery:Open surgical revascularization with synthetic or autologous conduit persists in complex multilevel disease.
Angioplasty anchors the volume base while thrombectomy applications gain share at the steepest rate through regulatory acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty foundries and precision manufacturing clusters concentrate nitinol and polymer supply chains in discrete geographic corridors. FDA regulatory oversight and CMS reimbursement calibration create divergent commercialization timelines across hospital and ambulatory networks.
Southeast
Florida and Georgia health systems drive stent demand through elevated diabetes-related restenosis interventions. CMS site-neutral payment policies compress reimbursement differentials between hospital and ambulatory settings. Tampa and Atlanta corridors anchor integrated delivery network procurement consolidation.
Midwest
Minnesota's medical technology corridor sustains catheter and guidewire manufacturing through deep supplier ecosystems. OSHA bloodborne pathogen standards tighten sterilization validation requirements for regional reprocessing facilities. Minneapolis-St. Paul anchors captive production capacity for shape-memory alloy components.
Northeast
Massachusetts and New York academic medical centers pilot bioresorbable scaffold applications in below-the-knee lesions. FDA Breakthrough Devices Program accelerates thrombectomy platform access through Boston and New York clinical trial networks. Greater Boston concentrates venture-backed device development.
Southwest
Texas integrated delivery networks consolidate catheter procurement authority at network level, compressing vendor margins. NHTSA transport regulations govern accessory sterilization logistics across El Paso and Houston distribution hubs. Dallas-Fort Worth anchors ambulatory surgical center expansion.
Mountain West
Underserved rural markets in Colorado and Utah present white space for teleproctoring-supported intervention programs. Rural hospital networks face interventional cardiologist pipeline constraints. Denver and Salt Lake City corridors anchor regional distribution for lower-acuity sites.
US Peripheral Vascular Devices and Accessories Market Key Industry Players
Diversified conglomerates and specialized device fabricators split the market through divergent capital allocation strategies. Tier-one manufacturers leverage integrated clinical evidence generation to sustain premium positioning. Mid-tier specialists concentrate on catheter commoditization defense through private-label partnerships. Dominant competitive moves include consignment model expansion and biodegradable material platform licensing.
Within the diversified medical technology tier, Medtronic, Boston Scientific Corporation, and Abbott occupy positions defined by manufacturing infrastructure depth and portfolio breadth. Medtronic exemplifies the captive supply archetype through Minnesota-based production ecosystems. Boston Scientific Corporation anchors East Coast clinical trial and regulatory submission capacity. Abbott represents the diversified stent-balloon portfolio model across South and Southwest corridors.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific Corporation |
| Abbott |
| Terumo Corporation |
| BD |
| Koninklijke Philips N.V. |
| Cook Group |
| W. L. Gore & Associates |
| BIOTRONIK SE & Co. KG |
| Others |
Cost & Logistics Intelligence
Overcapacity in standard balloon catheter manufacturing across the US Midwest is forcing suppliers to absorb margin compression while premium biodegradable stent platforms retain pricing power through clinical differentiation. This utilization divergence shapes procurement negotiations, with hospital GPOs extracting concessions in commoditized segments while ambulatory surgical centers pay premiums for novel material platforms.
Pricing Analysis
FDA premarket approval pathway dictates the pricing tier structure across peripheral vascular devices, with PMA-track stent systems commanding premium positioning against 510(k)-cleared catheter platforms. Price differentiation rests on clinical evidence depth and CMS coverage determination, with Southeast hospital systems showing highest sensitivity to standard balloon pricing due to volume procurement consolidation. Cost compression in angioplasty platforms is intensifying because private-label alternatives displace branded inventory in Midwest ambulatory centers, while biodegradable-eligible stent tiers sustain margin through restenosis outcomes data.
Supply Chain Analysis
Tariff exposure between the United States and China dominates raw material risk planning for nitinol and polymer substrate sourcing. Specialty foundries in Germany and Japan anchor shape-memory alloy supply for self-expanding stent platforms, while domestic polymer compounding in Minnesota and Massachusetts feeds catheter body production. Single-source vulnerability concentrates in electrolytic polishing services for nitinol surface finishing. Distribution runs through consignment models at integrated delivery networks and direct manufacturer arrangements with freestanding ambulatory surgical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of interventional cardiologists trained in below-the-knee procedures constrains market expansion regardless of device availability, making physician education infrastructure the binding capability gap for stakeholders.
For Market Incumbents: Build captive nitinol supply moats through backward integration into shape-memory alloy foundry capacity or long-term offtake agreements with German and Japanese specialty metal suppliers. Defend against biodegradable platform disruption by accelerating clinical trial enrollment in infrapopliteal applications before mid-tier entrants secure FDA Breakthrough Devices designation. Channel control through vendor-managed inventory at Texas and Florida IDNs preserves pricing power against distributor disintermediation.
For New Entrants and Emerging Players: Pursue teleproctoring-enabled penetration of Mountain West rural hospitals where interventional cardiologist shortages create procedural access gaps. Target drug-coated balloon combination therapies as the most penetrable segment outside stent-dominant revenue models, leveraging outcomes-based contracting with ambulatory surgical center procurement committees as the primary go-to-market angle.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among catheter platform manufacturers with consignment models at expanding ambulatory surgical center networks. Long-term viability over the next decade hinges on biodegradable material platform licensing portfolios and FDA Breakthrough Devices Program queue position. Acquisition targets with magnesium alloy scaffold clinical data in below-the-knee lesions signal inflection potential as restenosis-driven replacement cycles shift toward bioresorbable alternatives.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Devices Submission | Accelerated market access for novel thrombectomy platforms compresses commercialization timelines against PMA-track competitors. |
| Hospital System Partnership | Direct consignment arrangements with Texas and Florida IDNs displace distributor intermediaries and preserve margin. |
| Biodegradable Material Licensing | Magnesium alloy and polymer formulation access enables migration from permanent metal implants toward physiologic restoration. |
| Software Companion Development | Fluoroscopic guidance integration and procedural workflow optimization differentiate platform ecosystems for ambulatory adoption. |
| Reimbursement Strategy | CMS site-neutral payment calibration shapes bundled device-and-service offerings for ASC procurement committee decisions. |
Research Approach
Desk research of FDA 510(k) and PMA filing databases, hospital procurement contract repositories, and CMS Medicare reimbursement schedules preceded structured interviews with interventional cardiologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers. Secondary validation drew from SEC 10-K disclosures of publicly traded device manufacturers, trade customs data for nitinol and polymer imports, and OSHA bloodborne pathogen compliance records. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue attribution across the analysis window.
Assumptions around site-of-service migration velocity, biodegradable material adoption curves, and interventional cardiologist fellowship output were held fixed at baseline scenarios while reimbursement policy shifts and raw material allocation shocks were stress-tested. Segmentation dimensions modeled include device type, material substrate, end-user facility category, and application procedure class. CAGRs were derived from polynomial trend fitting to historical procedural volume data, adjusted for FDA regulatory pathway timelines and CMS coverage determination patterns specific to peripheral vascular interventions.
Sensitivities concentrate around FDA premarket approval timeline extensions, nitinol supply allocation disruptions, and CMS reimbursement rate recalibration for hospital-versus-ambulatory site differentials. Forecasts reflect documented assumptions regarding procedural volume migration and material substitution elasticities. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Pacemaker Devices Market
Medical Devices
Thoracic Surgery Devices Market
Medical Devices
MRI Guided Drug Delivery Market
Medical Devices
Micro Syringes Market
Medical Devices
North America Oxygen Concentrators Market
Medical Devices
Argentina Aesthetic Devices Market
Medical Devices
Middle East and Africa Hip and Knee Reconstruction Devices Market
Medical Devices
Middle-East and Africa Cardiac Arrhythmia Monitoring Devices Market
Medical Devices
Global Electrotherapy Devices Market
Medical Devices
Global Interspinous Spacers Market
Medical Devices
Permanent Artificial Skin Market
Medical Devices
Endocavity Transducer Market
Medical Devices
Elbow Fixators Market
Medical Devices
Global Implantable Loop Recorder Market
Medical Devices
Acute External Ventricular Drain Market
Medical Devices
Membrane Oxygenators Market