
 Venous Thromboembolism Treatment Market | 2026-2036
Venous Thromboembolism Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Venous Thromboembolism Treatment Market Analysis
Hospital procurement committees are rotating toward integrated VTE prophylaxis bundles that combine pharmacological and mechanical interventions. Pfizer Inc. leverages its anticoagulant manufacturing scale to anchor hospital formulary contracts across North American and European markets. Bristol Myers Squibb competes through specialized hematology sales forces that navigate complex payer landscapes for novel oral anticoagulant positioning. Medtronic plc extends its interventional portfolio into inferior vena cava filter placement and retrieval systems, occupying the procedural device segment alongside pharmaceutical counterparts.
Venous thromboembolism treatment encompasses pharmacological agents, interventional devices, and mechanical prophylaxis systems designed to prevent, dissolve, or mechanically intercept blood clots within the venous system; direct oral anticoagulants function through selective factor Xa or thrombin inhibition with fixed dosing regimens that eliminate routine coagulation monitoring requirements. Anticoagulants dominate prescription volume and revenue pools, while thrombolytics capture acute pulmonary embolism intervention scenarios where rapid clot dissolution determines mortality outcomes. Compression devices sustain steady demand in post-surgical and immobilized patient populations, with home care settings representing an expanding delivery channel as ambulatory reimbursement frameworks mature.
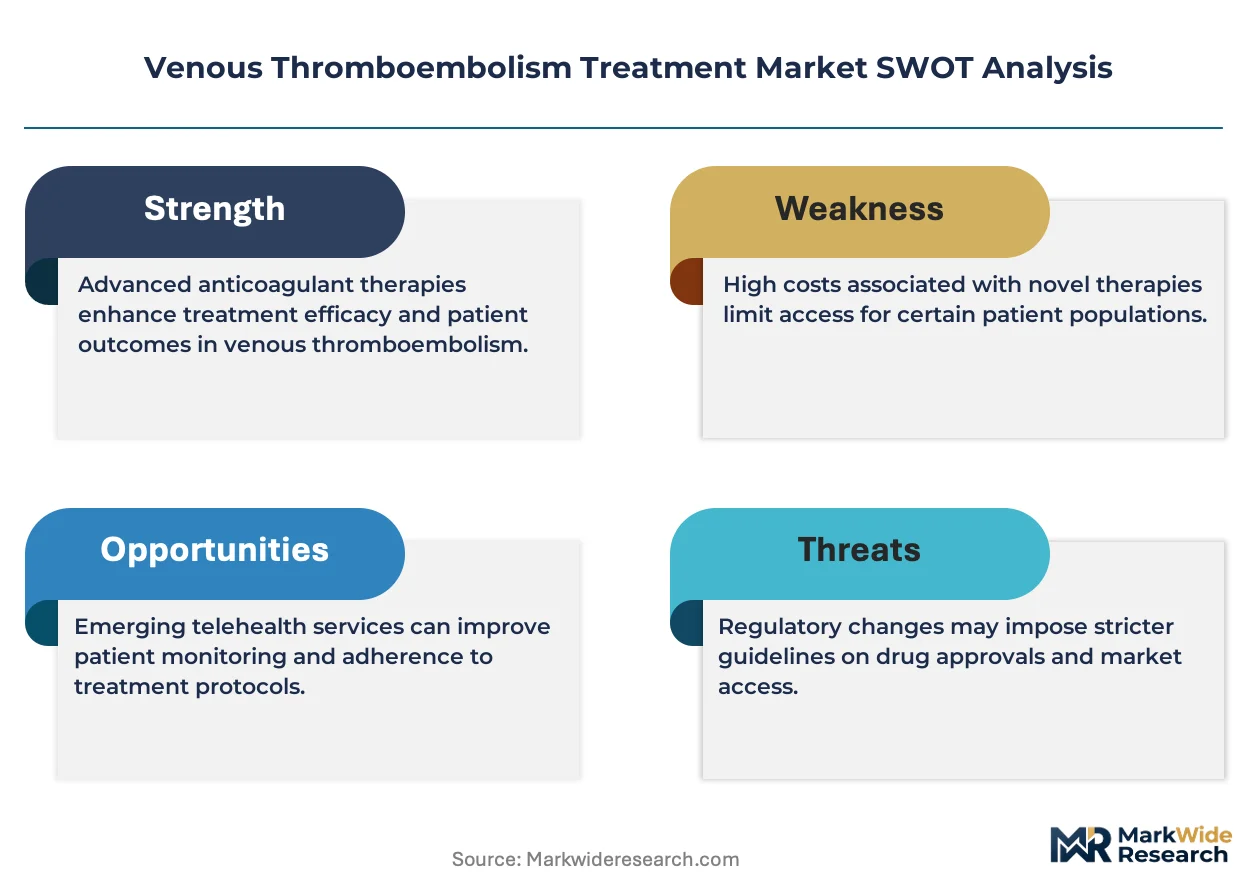
The FDA maintains stringent efficacy and bleeding-risk thresholds for novel anticoagulant approvals, while the EMA's pharmacovigilance frameworks mandate post-market surveillance that shapes product labeling and physician confidence. Health technology assessment bodies in Germany and France apply incremental cost-effectiveness ratios that filter market access for premium-priced oral anticoagulants against established vitamin K antagonist benchmarks. Stakeholders must monitor evolving real-world evidence requirements from payers and the trajectory of biosimilar heparin competition that could compress margin pools across the anticoagulant segment.
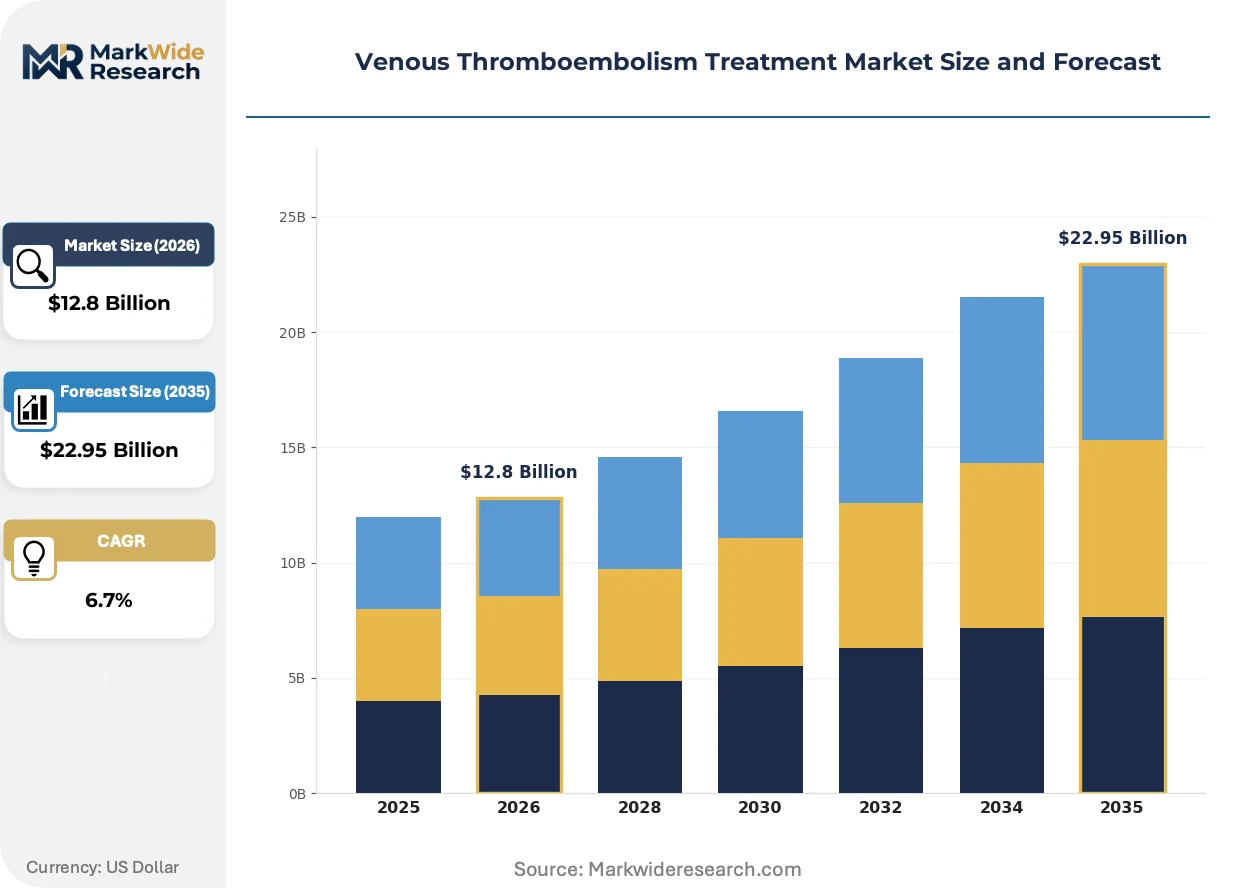
Market Dynamics
Hospital formulary committees are consolidating purchasing power around integrated VTE prophylaxis bundles, compressing standalone anticoagulant margins while elevating vendors with mechanical-pharmacological combination portfolios. This procurement centralization is redrawing competitive boundaries between pharmaceutical manufacturers and interventional device suppliers.
Growth Catalysts
- Surgical volume expansion:Rising orthopedic and oncology procedure rates in aging populations sustain anticoagulant consumption. Hospital systems embed mandatory VTE risk assessment protocols into electronic health records.
- EMA pharmacovigilance frameworks:Post-market surveillance mandates for novel oral anticoagulants generate real-world evidence that reinforces physician confidence and supports premium positioning against vitamin K antagonists.
- Factor Xa inhibitor innovation:Fixed-dosing regimens without routine coagulation monitoring eliminate laboratory infrastructure requirements, expanding addressable markets to ambulatory and home care settings.
Market Restraints
- Heparin raw material concentration:Porcine mucosa supply chains concentrate in China and select Southeast Asian processing facilities, exposing manufacturers to zoonotic disease disruptions and export policy volatility.
- Bleeding risk thresholds:FDA efficacy-safety balance requirements for novel anticoagulant approvals demand extensive Phase III programs that extend development timelines and elevate capital requirements.
- Mechanical prophylaxis substitution:Pneumatic compression devices and early ambulation protocols reduce pharmacological dependency in select surgical populations, capping anticoagulant penetration in post-operative care.
Strategic Opportunities
- Home care channel expansion:Ambulatory reimbursement frameworks in Germany and France mature, enabling compression device and self-injectable anticoagulant delivery outside institutional settings.
- IVC filter retrieval systems:Interventional suites prioritize retrieval-capable filter designs over permanent implants, creating device refresh cycles and recurring procedure revenue streams.
- PLI scheme alignment:India's production-linked incentive schemes for medical devices attract contract manufacturing investment for mechanical prophylaxis systems serving emerging markets.
Industry Challenges
- Hematology specialist scarcity:Complex oral anticoagulant positioning requires specialized sales forces capable of navigating payer pharmacy-benefit-manager landscapes, constraining vendor scaling velocity.
- Legacy anticoagulant switching inertia:Warfarin monitoring infrastructure and established reversal protocols create clinical habit persistence that slows novel agent uptake in conservative prescriber segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Venous Thromboembolism Treatment Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anticoagulants, Thrombolytics, Compression Devices, Filters Delivery Mode: Intravenous, Oral, Subcutaneous, Transdermal End User: Hospitals, Clinics, Home Care, Long-term Care Facilities Therapy Area: Cardiology, Pulmonology, Hematology, Vascular Surgery |
| Companies Covered | Pfizer Inc., Bayer AG, Bristol Myers Squibb, Johnson & Johnson, Medtronic plc, Boston Scientific Corporation, AngioDynamics, Inc., Stryker Corporation, Cardinal Health, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Venous Thromboembolism Treatment Market Emerging Trajectories
Anticoagulant development trajectories are fragmenting across precision-dosing biomarkers, interventional device miniaturization, and ambulatory care model restructuring. These concurrent shifts are compressing traditional hospital-centric revenue pools while opening alternative site-of-care channels.
Direct oral anticoagulant development is decomposing the traditional vitamin K antagonist market by eliminating dietary interaction constraints and coagulation monitoring requirements. Cardiology and hematology practices in the United States and Western Europe adopt these agents as first-line therapy for non-valvular atrial fibrillation. The technology is decomposing laboratory-dependent care models and enabling decentralized prescription management.
REACH registration requirements and EMA post-authorization safety studies are elevating real-world evidence standards for novel anticoagulant market access. Manufacturers must maintain pharmacovigilance infrastructure that captures bleeding events across distributed patient populations. European health technology assessment bodies in Germany, France, and England apply incremental cost-effectiveness thresholds that filter premium-priced agent reimbursement against warfarin benchmarks.
Hospital procurement committees are consolidating mechanical and pharmacological VTE prophylaxis into single-source contracts with penalty clauses for protocol non-compliance. Device vendors and pharmaceutical suppliers compete as bundled service providers rather than standalone product categories. This concentration is most visible in United States integrated delivery networks and NHS England trust procurement frameworks.
Venous Thromboembolism Treatment Market Segmentation
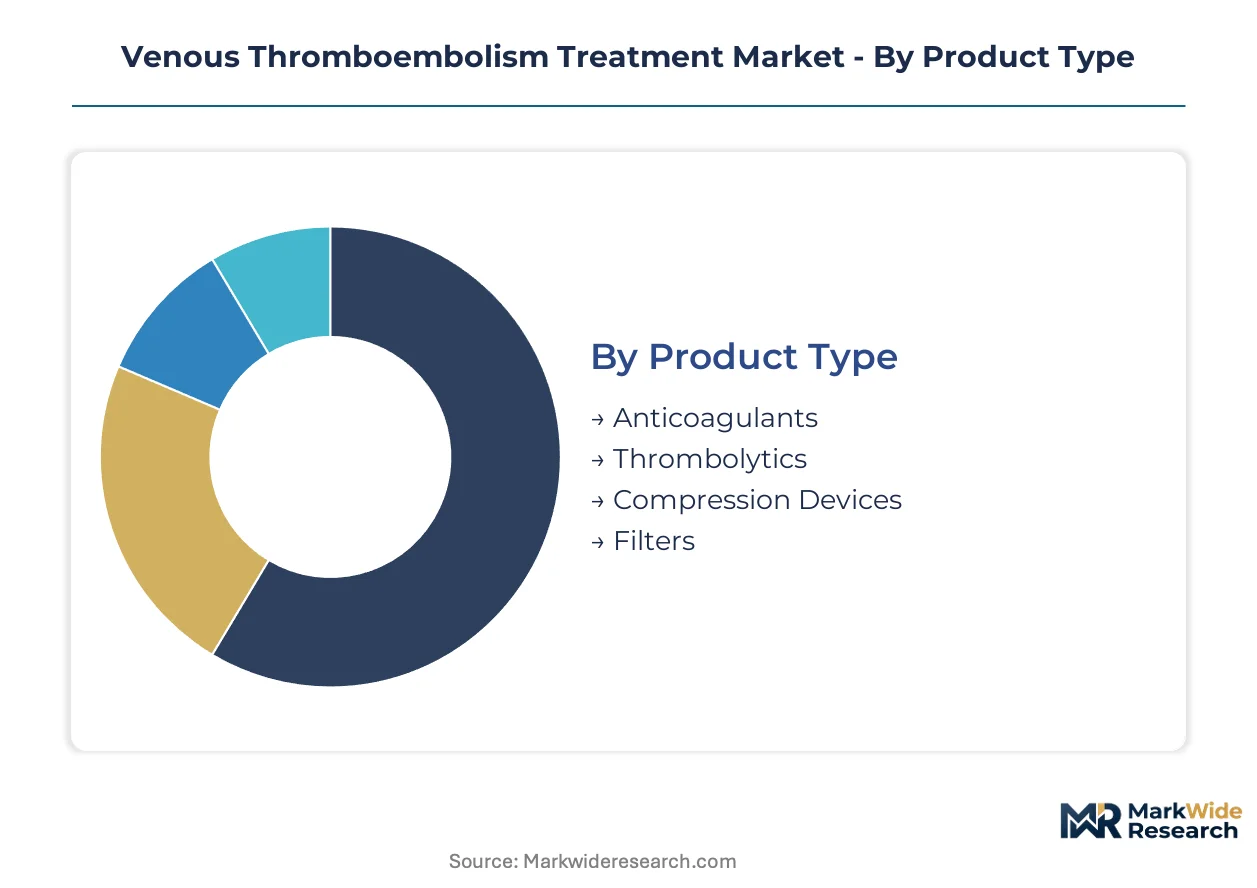
Venous thromboembolism treatment segments flow through distinct procurement and reimbursement channels that shape competitive positioning. Pharmaceutical agents navigate pharmacy-benefit-manager formularies while mechanical prophylaxis systems contract through hospital supply chain committees. Understanding these channel dynamics reveals where margin pools concentrate and where substitution threats emerge.
Product Type:
Channel mix varies sharply across product categories, with anticoagulants flowing through retail and specialty pharmacy networks while interventional devices route through hospital cath lab and surgical supply chains.
- Anticoagulants:Direct oral anticoagulants and heparin derivatives constitute the revenue core, with fixed-dose factor Xa inhibitors displacing vitamin K antagonists in ambulatory settings. United States demand concentrates in cardiology practices managing non-valvular atrial fibrillation, where elimination of INR monitoring drives prescriber preference.
- Thrombolytics:Systemic and catheter-directed clot-dissolving agents command premium pricing in acute pulmonary embolism intervention where mortality reduction justifies bleeding risk. Pulmonology and critical care units in tertiary hospitals generate concentrated demand during hemodynamically unstable presentations.
- Compression Devices:Intermittent pneumatic compression systems and graduated compression stockings serve post-surgical prophylaxis protocols. Home medical equipment dealers and hospital discharge planning coordinate delivery for immobilized patients.
- Filters:Inferior vena cava filters for mechanical clot interception deploy through interventional radiology suites, with retrieval-capable designs displacing permanent implants to reduce long-term complications.
Anticoagulants dominate installed prescription volume. Filters and compression systems are where ambulatory channel expansion concentrates.
Delivery Mode:
Cost tier stratification separates acute inpatient administration from chronic outpatient self-management, with oral agents capturing the largest addressable patient population.
- Intravenous:Unfractionated heparin and thrombolytic infusion in intensive care and perioperative settings requires nursing supervision and coagulation monitoring infrastructure. Tertiary medical centers in Germany and France maintain the highest utilization density.
- Oral:Direct oral anticoagulants with fixed dosing eliminate dietary restrictions and laboratory monitoring, enabling primary care prescription authority. United States Medicare Part D formularies drive substantial volume through preferred tier placement.
- Subcutaneous:Low-molecular-weight heparin and fondaparinux serve bridging protocols and post-surgical prophylaxis in hospitalized populations. Home health nursing facilitates transition-to-home administration for selected patients.
- Transdermal:Heparin gel formulations and experimental anticoagulant patches occupy niche applications where injection avoidance carries compliance value. Dermatology and pediatric segments generate exploratory demand.
Oral delivery commands the largest patient-month volume. Subcutaneous administration is gaining share fastest in home care transition protocols.
End User:
Customer type determines reimbursement pathway complexity, with institutional purchasers leveraging formulary control against fragmented home care reimbursement.
- Hospitals:Integrated delivery networks consolidate anticoagulant purchasing through pharmacy and therapeutics committees, while surgical services procure mechanical prophylaxis bundles. NHS England trust frameworks and United States IDN contracts concentrate procurement power.
- Clinics:Outpatient anticoagulation clinics and hematology practices manage warfarin-to-DOAC transitions and peri-procedural bridging. Cardiology specialty clinics in Japan and South Korea drive novel agent adoption.
- Home Care:Durable medical equipment suppliers and home infusion services deliver compression devices and subcutaneous anticoagulants to post-acute patients. German ambulatory care reimbursement reforms accelerate channel development.
- Long-term Care Facilities:Nursing homes and skilled nursing facilities administer prophylaxis to immobile elderly populations with elevated VTE risk. CMS quality metrics in the United States mandate risk assessment documentation.
Hospitals retain the highest acute intervention volume. Home care is where patient-day expansion concentrates as length-of-stay compression continues.
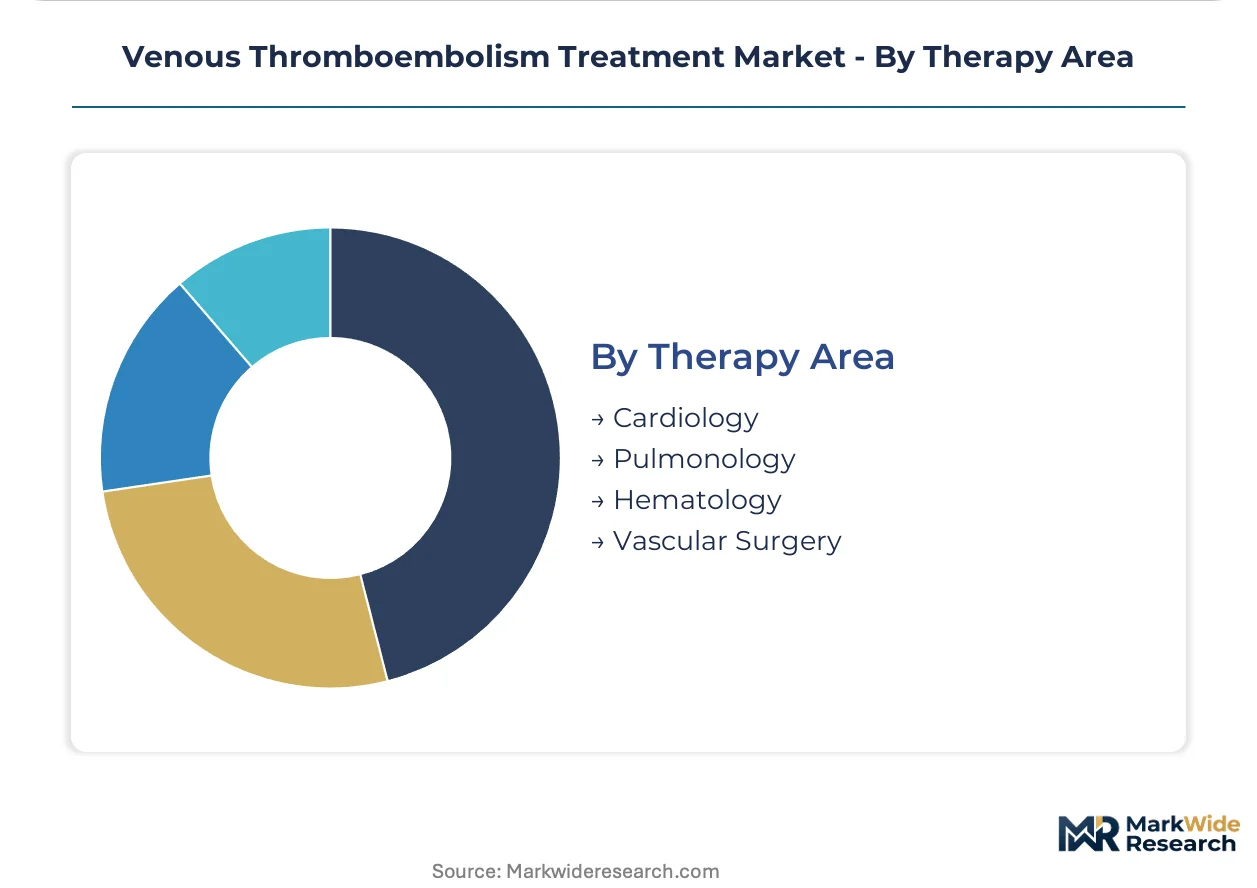
Therapy Area:
Application-specific clinical evidence requirements and specialist referral patterns segment demand across medical and surgical disciplines.
- Cardiology:Atrial fibrillation stroke prevention generates the largest eligible population for oral anticoagulation, with electrophysiology practices driving DOAC selection. United States cardiology societies publish guideline-directed therapy recommendations.
- Pulmonology:Acute pulmonary embolism management requires rapid risk stratification and thrombolytic decision-making in emergency and critical care settings. Pulmonary embolism response teams in major academic centers coordinate multidisciplinary care.
- Hematology:Thrombophilia evaluation and cancer-associated thrombosis management demand specialized coagulation expertise. Comprehensive cancer centers maintain dedicated thrombosis services.
- Vascular Surgery:Deep vein thrombosis intervention, IVC filter placement, and chronic venous insufficiency procedures generate device and pharmaceutical demand. Vascular surgery practices in France and Germany combine open and endovascular techniques.
Cardiology anchors chronic anticoagulant utilization. Pulmonology is where acute intervention technology adoption concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German anticoagulant manufacturers export direct oral anticoagulant formulations to hospital systems across France, Italy, and the Netherlands. This trade corridor reflects EMA-aligned regulatory standards and centralized procurement frameworks that facilitate cross-border pharmaceutical distribution.
United States
Medicare Part D formularies drive substantial anticoagulant volume through preferred tier placement for factor Xa inhibitors. FDA guidance on DOAC reversal agents shapes hospital pharmacy committee purchasing criteria. The Cleveland Clinic and Mayo Clinic anchor cardiovascular research clusters that generate real-world evidence supporting novel agent adoption.
Germany
Aging demographics sustain orthopedic procedure volumes that trigger mandatory VTE prophylaxis protocols under hospital reimbursement frameworks. The G-BA applies incremental cost-effectiveness ratios that filter premium-priced oral anticoagulants against warfarin benchmarks. Berlin and Munich host thrombosis research consortia that coordinate multicenter post-authorization safety studies.
France
HAS health technology assessments determine reimbursement eligibility for novel oral anticoagulants in non-valvular atrial fibrillation indications. ANSM pharmacovigilance mandates require manufacturers to maintain bleeding event registries across distributed patient populations. The Paris-Saclay medical cluster coordinates pulmonary embolism response team training for acute intervention standardization.
Japan
PMDA approval pathways for novel anticoagulants emphasize ethnic-specific dosing validation and bleeding risk stratification. METI reimbursement reforms accelerate home care channel development for compression device delivery. Tokyo and Osaka academic medical centers anchor electrophysiology practices that drive DOAC selection for atrial fibrillation stroke prevention.
India
CDSCO regulatory harmonization with ICH guidelines streamlines clinical trial protocols for biosimilar heparin development. The PLI scheme for medical devices attracts contract manufacturing investment for mechanical prophylaxis systems. Hyderabad and Ahmedabad host active pharmaceutical ingredient clusters that supply heparin derivatives to domestic formulation manufacturers.
Venous Thromboembolism Treatment Market Vendor Landscape
Player mix skews toward integrated pharmaceutical-device conglomerates with hospital formulary anchoring capabilities. Market structure concentrates around three strategic tiers: multinational anticoagulant developers with cardiovascular specialty sales forces, interventional device manufacturers with cath lab penetration, and diversified health systems suppliers with supply chain integration. Dominant competitive moves include portfolio bundling of pharmacological and mechanical prophylaxis systems and geographic expansion through health technology assessment alignment in European markets.
Within the pharmaceutical archetype, Pfizer Inc. and Bristol Myers Squibb occupy positions defined by anticoagulant manufacturing scale and hematology sales force specialization. Medtronic plc exemplifies the interventional device vector through inferior vena cava filter placement and retrieval system portfolios. These three entities represent distinct competitive approaches: manufacturing scale anchoring, specialized therapeutic area focus, and procedural device integration.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Bayer AG |
| Bristol Myers Squibb |
| Johnson & Johnson |
| Medtronic plc |
| Boston Scientific Corporation |
| AngioDynamics, Inc. |
| Stryker Corporation |
| Cardinal Health, Inc. |
| Others |
Supply Flow & Price Mechanics
Anticoagulant manufacturing scale at Pfizer and Bristol Myers Squibb anchors price floors through captive heparin sourcing and fixed-cost absorption, while smaller formulation competitors face margin compression from biosimilar heparin entry and raw material volatility. This concentration dynamic shapes tiered procurement negotiations where integrated delivery networks extract volume discounts that standalone device vendors cannot match.
Pricing Analysis
Factor Xa inhibitor pricing stratifies across premium, standard, and economy tiers, with fixed-dose oral agents commanding premium positioning against vitamin K antagonist benchmarks in United States Medicare Part D formularies. Price differentiation hinges on FDA approval tier and hospital formulary placement, with cardiology specialty clinics showing lowest price sensitivity due to clinical outcome focus. Pricing pressure intensifies in mechanical prophylaxis segments where pneumatic compression device commoditization accelerates; post-acute care facilities exhibit highest price sensitivity due to CMS reimbursement compression.
Supply Chain Analysis
Inventory lead times for porcine mucosa-derived heparin extend to 180 days due to concentrated processing in China and Southeast Asian facilities, exposing manufacturers to zoonotic disease disruptions and export policy shifts. Active pharmaceutical ingredient production draws from Indian and Chinese chemical synthesis clusters, while finished formulation capacity concentrates in Germany and United States pharmaceutical plants. Single-source vulnerability in porcine-derived raw materials represents the dominant structural risk. Distribution runs through hospital supply chain committees for mechanical devices and pharmacy-benefit-manager networks for anticoagulants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Venous Thromboembolism Treatment Market exhibits cyclical recovery characteristics as surgical volume normalization and aging demographic expansion restore anticoagulant consumption patterns disrupted by pandemic-era procedure deferrals.
For Market Incumbents: Consolidate manufacturing scale advantages through backward integration into heparin raw material sourcing, securing captive supply from Indian and Chinese API clusters against biosimilar competition. Anchor hospital formulary contracts with integrated VTE prophylaxis bundles that combine pharmacological and mechanical interventions, creating switching costs that defend margin position against emerging device-pharma hybrid competitors. For New Entrants and Emerging Players: Home care service infrastructure represents the most penetrable white space, where incumbent pharmaceutical manufacturers under-serve compression device delivery and patient education needs outside institutional settings. Target German and French ambulatory reimbursement expansion corridors with self-injectable anticoagulant and pneumatic compression system offerings. Pursue direct-to-patient subscription models that bypass hospital procurement concentration. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors interventional device manufacturers with retrieval-capable IVC filter platforms and software-integrated mechanical prophylaxis systems over pure-play pharmaceutical developers facing biosimilar compression. Long-term viability over the next decade hinges on ambulatory channel capture and real-world evidence generation capabilities. Monitor EMA pharmacovigilance framework tightening as the inflection signal for regulatory compliance cost escalation that favors scaled players.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated VTE Prophylaxis Bundle Development | Hospital formulary committees consolidate purchasing around combined pharmacological-mechanical protocols that reduce standalone vendor margins. |
| Retrieval-Capable IVC Filter Platform Launch | Interventional radiology suites prioritize removable designs over permanent implants, creating recurring procedure revenue streams. |
| Home Care Channel Partnership Expansion | German ambulatory reimbursement reforms enable compression device and self-injectable anticoagulant delivery outside institutional settings. |
| Real-World Evidence Infrastructure Investment | EMA post-authorization safety study requirements and HAS health technology assessments demand bleeding event registries across distributed populations. |
| Biosimilar Heparin Manufacturing Scale-Up | CDSCO regulatory harmonization and PLI scheme alignment attract contract manufacturing investment serving emerging market price points. |
Methodological Framework
Initial hypotheses were tested against primary input from hospital pharmacy directors, interventional radiologists, hematology specialists, and GPO contract managers, then refined through secondary validation against FDA filings, EMA submission databases, ClinicalTrials.gov records, and CMS Medicare Part D formulary data. Bottom-up prescription volume modeling and top-down market sizing triangulated around manufacturer-reported shipment data and hospital procurement database extracts.
Variance decomposition across product type, delivery mode, end user, and therapy area segmentation dimensions structured the analytical framework over the projection horizon. CAGRs derived from surgical volume elasticity models, demographic aging curves, and DOAC substitution rate trajectories informed value outputs. Forecast inputs incorporated orthopedic procedure expansion rates, anticoagulant reversal agent approval timelines, and mechanical prophylaxis device refresh cycles.
Forecasts assume regulatory continuity in FDA, EMA, and PMDA approval pathways; material policy shifts such as novel bleeding-risk thresholds or reversal agent mandates would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Atherosclerosis Market
Cardiovascular
Endocarditis Therapeutics Market
Cardiovascular
Chronic Heart Failure Market
Cardiovascular
Cardiometabolic Disease Market
Cardiovascular
Chronic Pulmonary Hypertension Treatment Market
Cardiovascular
Pericarditis Treatment Market
Cardiovascular
Ticagrelor Market
Cardiovascular
Stable Angina Management Market
Cardiovascular
Global Hypotension Treatment Market
Cardiovascular
Eisenmenger Syndrome Treatment Market
Cardiovascular
Global Cardiac Tamponade Market
Cardiovascular
Angina Pectoris Treatment Market
Cardiovascular
Global Advanced Cardiovascular Life Support Market
Cardiovascular
Ischemia Market
Cardiovascular
Acute Coronary Syndrome (ACS) Market
Cardiovascular
Global Pericarditis Market